
 Enhanced Efficiency Fertilizer Market | 2026-2036
Enhanced Efficiency Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Enhanced Efficiency Fertilizer Market Insights
Specialty crop growers is collapsing the historical dominance of broad-acre commodity farmers in enhanced efficiency fertilizer procurement. Nutrien Limited leverages its integrated retail network to lock in greenhouse and high-value vegetable accounts across North America. Yara International ASA anchors its position through deep ammonia backward integration and precision agriculture digital platforms. Koch Agronomic Services differentiates via polymer-coated urea technology leadership and direct-to-farm distribution control.
Enhanced efficiency fertilizers incorporate stabilizers, coatings, or controlled-release matrices to synchronize nutrient availability with crop uptake patterns, typically achieving nitrogen use efficiency improvements of 20-40% over conventional urea. These formulations serve commercial agriculture by reducing volatilization losses, cutting application frequency, and protecting watersheds from nitrate loading. Controlled-release and coated fertilizers command the deepest margin pools where polymer technology barriers limit new entrants, while slow-release variants sustain volume leadership in price-sensitive broad-acre segments. Water-soluble fertilizers represent the fastest-expanding category as greenhouse and hydroponic operators demand exact nutrient dosing.
The EPA regulates nitrogen runoff under the Clean Water Act, compelling growers in Chesapeake Bay and Mississippi River watersheds to adopt loss-reduction products. The EU Green Deal and national nitrate directives in Germany, Denmark, and the Netherlands mandate step-downs in fertilizer application rates, directly accelerating coated and stabilized product demand. China's MEE enforces groundwater quality thresholds in the North China Plain that penalize conventional urea over-application. Stakeholders must monitor how carbon border adjustment mechanisms and farm-level emissions accounting reshape product certification requirements and procurement criteria.
Market Dynamics
EU F-Gas Regulation and national nitrate reduction mandates in Germany, France, and the Netherlands are compressing leaching standards and forcing rapid formulation upgrades across the value chain. Specialty crop growers now dictate procurement patterns that commodity farmers once dominated.
Growth Catalysts
- EU Green Deal nitrogen directives:Germany, Denmark, and the Netherlands mandate step-downs in fertilizer application rates, directly accelerating coated and stabilized product demand.
- North China Plain groundwater thresholds:China's MEE enforces binding water quality targets that penalize conventional urea over-application among winter wheat growers.
- Controlled-release polymer matrices:Synchronized nutrient availability with crop uptake patterns achieves nitrogen use efficiency improvements of 20-40% over conventional urea.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings directly compress margins for ammonia-integrated producers, particularly in European manufacturing clusters.
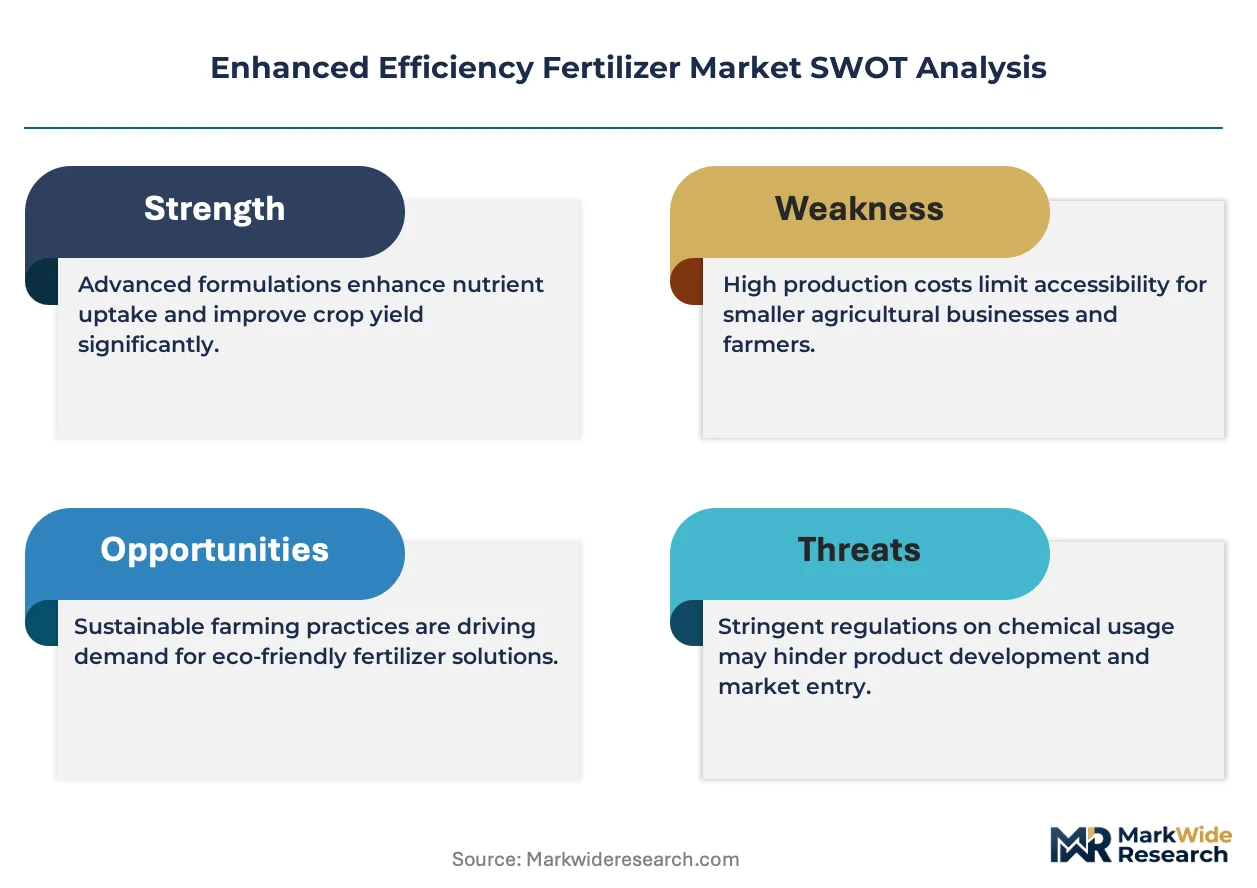
- Polymer coating cost premiums:Advanced polymer technology barriers limit new entrants and sustain elevated price points that exclude price-sensitive broad-acre segments.
- Conventional urea substitution threat:Unsubsidized smallholder farmers in developing agricultural economies continue defaulting to low-cost conventional formulations.
Strategic Opportunities
- Hydroponic and greenhouse expansion:Water-soluble fertilizers capture fastest-expanding category status as controlled-environment agriculture operators demand exact nutrient dosing.
- Carbon border adjustment mechanisms:Emerging farm-level emissions accounting standards reshape product certification requirements and create premium positioning for verified low-emission formulations.
- Direct-to-farm distribution channels:Bypassing traditional wholesale cooperatives allows margin capture and grower relationship control in high-value vegetable production zones.
Industry Challenges
- Polymer R&D talent scarcity:Formulation chemists with controlled-release matrix expertise command premium compensation and limited geographic mobility.
- Legacy equipment incompatibility:Existing spreader fleets at broad-acre operations require retrofitting or replacement to handle coated product physical properties.
- Multi-jurisdiction certification timelines:Separate approval pathways for EU REACH, US EPA, and China MEE registrations extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enhanced Efficiency Fertilizer Market |
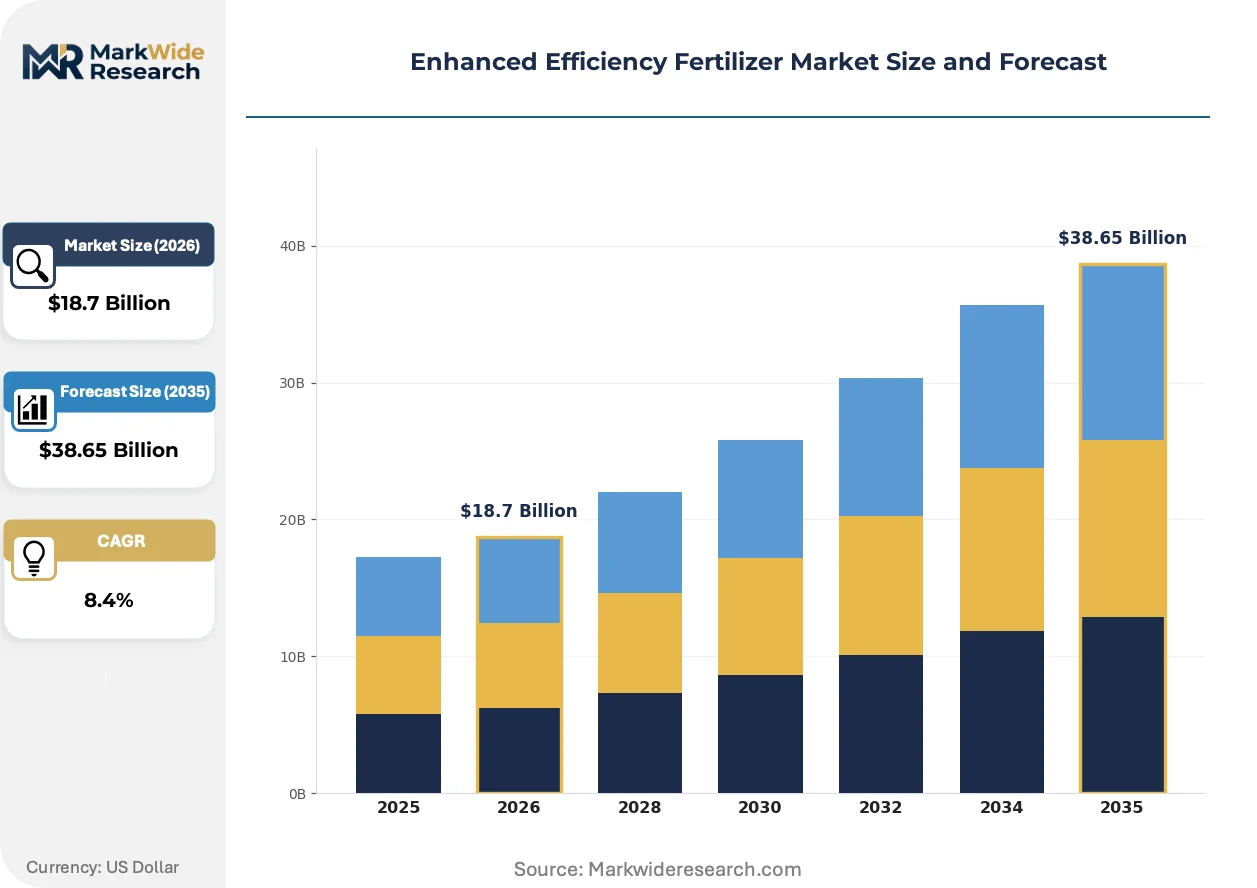
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controlled Release, Slow Release, Coated Fertilizers, Water-Soluble Fertilizers Application: Agricultural Fields, Greenhouses, Turf & Ornamentals, Hydroponics Distribution Channel: Direct Sales, Online Retail, Agrochemical Dealers, Wholesale End User: Farmers, Landscaping Companies, Nurseries, Research Institutions |
| Companies Covered | KAO Corporation, Nutrien Limited, Corteva Agriscience, ICL Group, Yara International ASA, BASF SE, Clariant International Ltd, Koch Agronomic Services, Arkema (ArrMaz), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enhanced Efficiency Fertilizer Market Trends and Innovations
Polymer-coated urea formulations are displacing conventional stabilized products as the dominant technology platform. Precision agriculture integration and regulatory tightening are compressing the viable product development cycle.
Biodegradable polymer coatings derived from plant-based feedstocks are displacing synthetic resin matrices in premium formulations. Greenhouse operators in the Netherlands and Belgium specify these coatings to meet retailer sustainability procurement standards. The technology is displacing first-generation sulfur-coated urea in high-value vegetable segments where application precision determines contract eligibility.
REACH authorization requirements for persistent organic pollutants are tightening coating additive specifications across European manufacturing. Formulators must reformulate stabilizer packages to maintain efficacy while eliminating restricted substances. Specialty crop growers in Germany and France face compressed compliance timelines as national nitrate directives accelerate enforcement.
Outcome-based agronomic service contracts are replacing transactional bulk purchases among large-scale specialty crop operations. Agronomists bundle fertilizer recommendations with application timing protocols and yield guarantees. This model concentrates in California's Central Valley and Spain's Almería greenhouse cluster where input costs represent decisive margin variables.
Enhanced Efficiency Fertilizer Market Segmentation
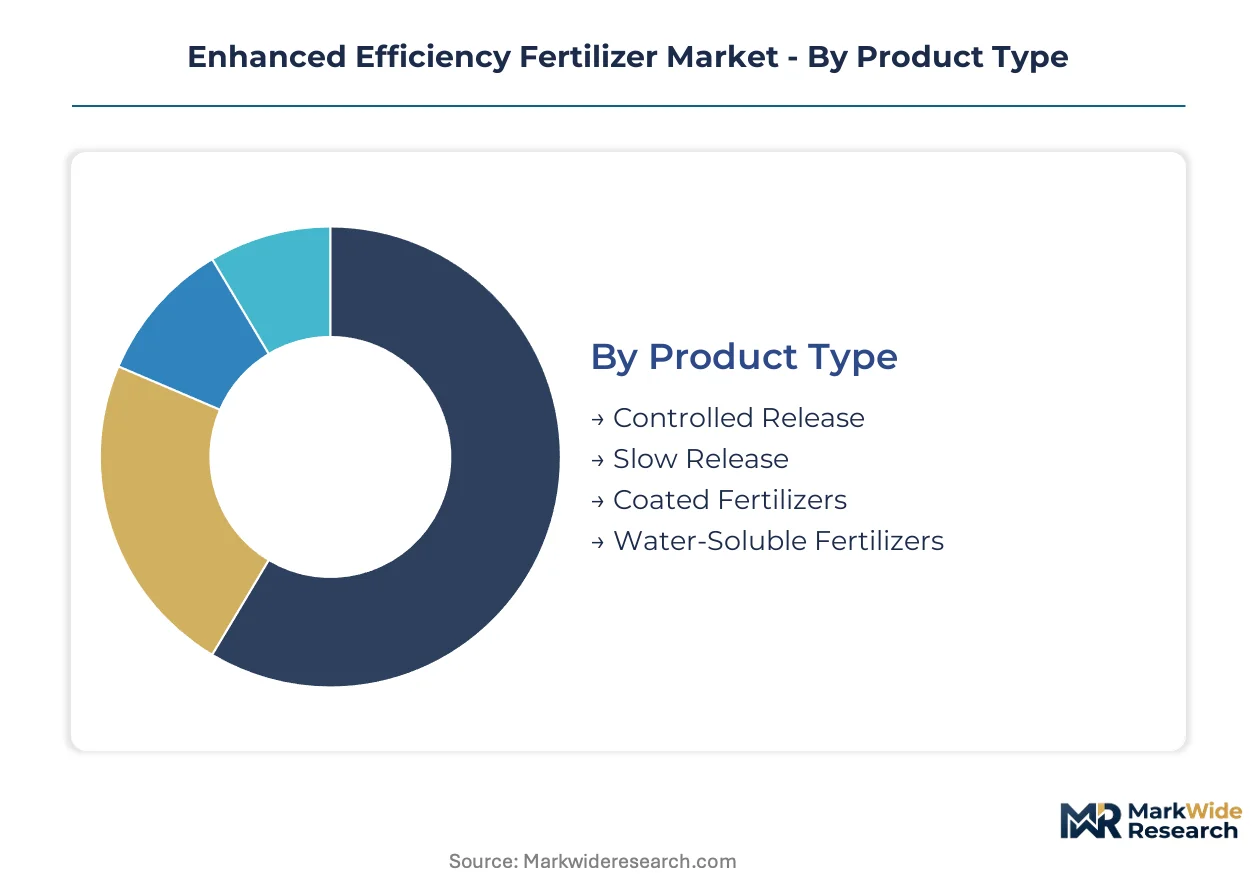
Segmentation in enhanced efficiency fertilizers reveals how technology tiers, application environments, and procurement channels create distinct margin pools and competitive dynamics. Product chemistry and release-mechanism specifications determine which customer types dominate demand within each segment.
Product Type:
Controlled-release and coated formulations flow through agronomist-led direct sales channels to high-value specialty operations, while slow-release variants move via wholesale cooperatives into broad-acre commodity production.
- Controlled Release:Polymer matrix technologies synchronize nitrogen availability with crop uptake curves, achieving 20-40% efficiency gains over conventional urea. Demand concentrates in California's Central Valley specialty vegetable operations where application timing precision determines contract eligibility with retail produce buyers.
- Coated Fertilizers:Sulfur and polymer coatings create diffusion barriers that extend nutrient release across 30-120 day windows. Greenhouse operators in the Netherlands and Belgium specify biodegradable plant-based coatings to meet retailer sustainability procurement standards enforced under EU Green Deal nitrogen directives.
- Slow Release:Chemical stabilizers delay nitrification through urease or nitrification inhibitors rather than physical barriers. Broad-acre corn and wheat producers in the US Corn Belt purchase through legacy wholesale cooperatives.
- Water-Soluble Fertilizers:Complete nutrient solutions dissolve instantly for drip irrigation and foliar feeding systems. Hydroponic lettuce and tomato operations in Spain's Almería cluster represent the steepest expansion trajectory as controlled-environment agriculture scales.
Controlled-release formulations dominate installed base revenue. Water-soluble fertilizers are where expansion concentrates.
Application:
Application environment dictates product specification requirements, with protected cultivation demanding exact nutrient dosing and open-field operations prioritizing leaching reduction.
- Agricultural Fields:Open-field row crops require formulations that withstand rainfall and temperature variability while minimizing groundwater contamination. Winter wheat growers on China's North China Plain face binding MEE groundwater quality thresholds that penalize conventional urea over-application.
- Greenhouses:Controlled-environment agriculture demands water-soluble and precision-coated products compatible with automated fertigation systems. Dutch tomato and pepper producers operate under national nitrate directives that mandate step-downs in fertilizer application rates.
- Turf & Ornamentals:Golf courses and municipal landscapes prioritize uniform greening without surge growth or burn risk. German landscaping contractors source through specialized dealers with application equipment bundling.
- Hydroponics:Soilless cultivation systems require ultra-pure nutrient solutions free of precipitating compounds or clogging residues. Research institutions in Denmark trial novel formulations under EU F-Gas Regulation compliance frameworks.
Agricultural fields retain the largest volume footprint. Hydroponics is climbing the fastest as vertical farming investments accelerate.
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with direct relationships capturing margin in high-value segments and wholesale maintaining commodity throughput.
- Direct Sales:Manufacturer agronomists embed with large specialty crop operations to design season-long fertility programs. California Central Valley almond and pistachio growers purchase through outcome-based service contracts bundling fertilizer with yield guarantees.
- Agrochemical Dealers:Independent retailers provide localized agronomic advice and application equipment access. French vegetable cooperatives in Brittany source coated products through dealer networks with EU REACH compliance documentation.
- Wholesale:Volume distributors serve price-sensitive broad-acre operations with limited technical support. US Corn Belt corn-soy rotations move through legacy cooperative wholesale channels.
- Online Retail:E-commerce platforms capture small-scale greenhouse operators and landscaping contractors seeking convenient reordering. Urban farming startups in Germany purchase water-soluble formulations through digital channels.
Agrochemical dealers anchor volume throughput. Direct sales is gaining share fastest as outcome-based contracting proliferates.
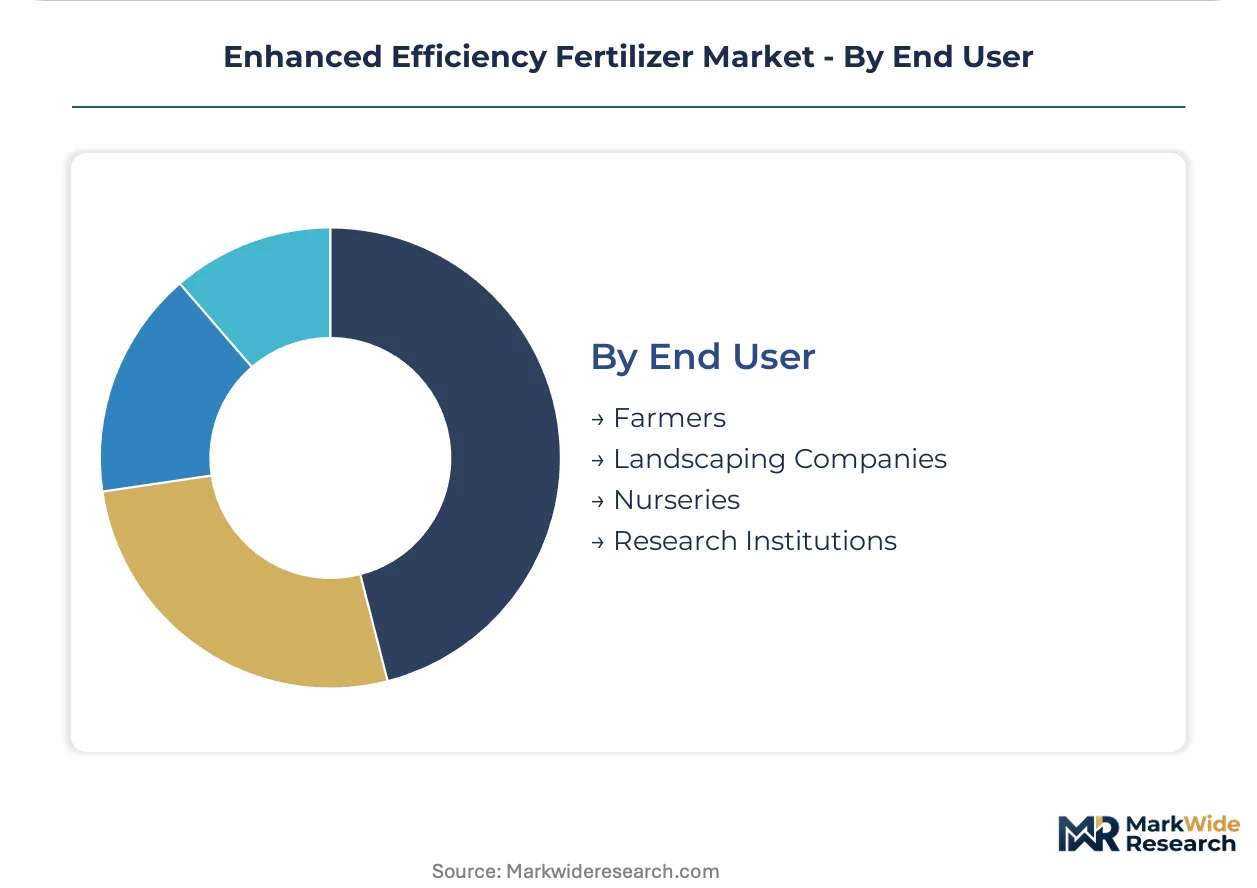
End User:
End-user sophistication determines willingness to pay for premium formulations and associated agronomic services.
- Farmers:Commercial growers range from price-driven commodity producers to technology-adopting specialty operators. Chinese winter wheat growers face MEE enforcement of groundwater quality thresholds.
- Landscaping Companies:Professional turf managers prioritize visual consistency and regulatory compliance over input cost minimization. German municipal contractors specify low-leaching formulations under national nitrate reduction mandates.
- Nurseries:Containerized plant producers require precise nutrient control to manage inventory holding periods. Dutch ornamental nurseries source biodegradable coated products to meet retailer sustainability standards.
- Research Institutions:Agricultural universities and government experiment stations trial novel formulations and document efficacy data. Denmark's agricultural research centers evaluate stabilizer packages under EU Green Deal nitrogen directive protocols.
Farmers represent the dominant installed base. Landscaping companies are where premium pricing expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ammonia production clusters in China, the United States, and Germany anchor supply-side capacity for enhanced efficiency fertilizer manufacturing. Regulatory divergence across major agricultural economies is fragmenting product registration pathways and accelerating regional formulation specialization.
United States
Corn Belt growers and California specialty vegetable operators drive differentiated demand patterns. The EPA enforces nitrogen runoff limits under the Clean Water Act across Chesapeake Bay and Mississippi River watersheds. Iowa and Illinois broad-acre operations source slow-release stabilizers through legacy wholesale cooperatives.
Germany
Winter wheat producers and ornamental nurseries face compressed compliance timelines under national nitrate reduction mandates. The EU F-Gas Regulation and REACH authorization requirements tighten coating additive specifications for persistent organic pollutants. Bavarian potato growers and Lower Saxony livestock operations procure biodegradable coated products through specialized dealer networks.
China
Winter wheat cultivation on the North China Plain confronts binding groundwater quality thresholds enforced by the MEE. The country's dual carbon goals accelerate displacement of conventional urea in high-intensity agricultural zones. Shandong Peninsula fertilizer manufacturers retrofit polymer coating lines to meet domestic efficiency standards.
Netherlands
Greenhouse tomato and pepper producers operate under national nitrate directives mandating step-downs in fertilizer application rates. The EU Green Deal nitrogen directives drive specification of plant-based biodegradable coatings among Dutch growers. Westland municipality horticulture clusters source water-soluble formulations through direct manufacturer relationships.
Brazil
Soybean and corn producers in the Cerrado and southern states confront emerging watershed protection regulations. The country's national agricultural regulator evaluates stabilizer package efficacy data for tropical soil conditions. Mato Grosso broad-acre operations trial controlled-release formulations to reduce application frequency across vast production zones.
Enhanced Efficiency Fertilizer Market Competitive Landscape
Concentration sits with integrated ammonia producers and specialty coating technology developers. The vendor base stratifies across three tiers: multinational agrochemical conglomerates with backward integration into ammonia feedstocks, mid-scale polymer specialists with regional formulation expertise, and emerging biodegradable coating innovators serving sustainability-certified supply chains. Dominant competitive moves include direct-to-farm distribution channel construction and precision agriculture digital platform integration.
Among integrated ammonia producers, Nutrien Limited and Yara International ASA exemplify the scale-driven archetype with captive nitrogen manufacturing and retail network control. Koch Agronomic Services occupies a position within the polymer technology specialist tier. These three anchors demonstrate how backward integration into ammonia and forward integration into agronomic services reshape margin capture across the value chain.
| Leading Market Players |
|---|
| KAO Corporation |
| Nutrien Limited |
| Corteva Agriscience |
| ICL Group |
| Yara International ASA |
| BASF SE |
| Clariant International Ltd |
| Koch Agronomic Services |
| Arkema (ArrMaz) |
| Others |
Pricing and Supply Chain Analysis
Biodegradable polymer feedstocks displacing synthetic resin matrices simultaneously relocate coating production toward EU Green Deal compliance zones and compress margin structures for first-generation sulfur-coated urea manufacturers. This substitution dynamic redistributes supply geography toward Netherlands and Belgium sustainability-certified clusters while pricing economics bifurcate between premium plant-based formulations and commodity sulfur-coated tiers.
Pricing Analysis
Volume-discount tiering structures separate greenhouse operators purchasing direct-to-farm contracts from broad-acre wheat growers sourcing through wholesale cooperatives. Price differentiation rests on polymer technology grade and EU REACH certification status, with biodegradable coatings commanding substantial premiums over conventional sulfur matrices. Pricing pressure intensifies in the slow-release stabilizer tier as unsubsidized smallholders in developing agricultural economies default to low-cost conventional urea. Specialty vegetable producers in California's Central Valley exhibit lowest price sensitivity due to contract eligibility requirements with retail produce buyers.
Supply Chain Analysis
Inbound logistics costs from Middle Eastern ammonia feedstock suppliers through Rotterdam and Houston ports constrain margin flexibility for European and North American formulators. Manufacturing concentrates in China, the United States, and Germany where ammonia production clusters anchor coating and compounding operations. Raw material dependencies include natural gas for ammonia synthesis, polymer resins for controlled-release matrices, and sulfur for conventional coating substrates. Supply chain risk centers on single-source vulnerability for advanced polymer formulation chemists with controlled-release expertise. Distribution runs through agronomist-led direct sales for specialty crop accounts and legacy wholesale cooperatives for commodity broad-acre segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by natural gas price normalization restoring ammonia production economics. The recovery phase favors integrated producers with captive feedstock positions.
For Market Incumbents: Shield margin pools in controlled-release polymer technology by deepening backward integration into ammonia and accelerating R&D investment in biodegradable coating matrices. Lock in greenhouse operator accounts through outcome-based service contracts bundling fertilizer recommendations with yield guarantees. The priority defensive lever is channel control against emerging biodegradable coating specialists. For New Entrants and Emerging Players: Anchor in hydroponic and vertical farming water-soluble formulations where demand expansion outpaces established supply capacity. Spain's Almería cluster and German urban farming startups represent the most penetrable white-space segments. Pursue digital-first distribution through e-commerce platforms capturing small-scale greenhouse operators seeking convenient reordering. For Investors and Strategic Acquirers: The market sits at an early-recovery phase that favors acquisition of mid-scale polymer specialists with regional formulation expertise and EU REACH registration assets. Long-term viability over the next decade hinges on carbon border adjustment mechanism positioning and farm-level emissions accounting compliance. The signal to watch is MEE enforcement intensity on China's North China Plain groundwater quality thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia | Captive natural gas feedstock access insulates margin compression from European energy volatility. |
| Biodegradable Coating R&D Program | Plant-based polymer matrices satisfy Netherlands retailer sustainability procurement standards. |
| Direct-to-Farm Channel Buildout | Bypassing wholesale cooperatives captures margin and grower relationship control in California specialty vegetable zones. |
| Precision Agriculture Platform Integration | Digital fertility protocols lock in greenhouse operator loyalty through application timing optimization. |
| EU REACH Registration Acceleration | Expedited authorization pathways for stabilizer packages eliminate persistent organic pollutant compliance gaps. |
Research Methodology
Cross-validation between primary interviews with coating formulation chemists, agronomists at specialty crop operations, procurement leads at wholesale cooperatives, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from China MEE groundwater quality enforcement disclosures, EU F-Gas Regulation implementation timelines, US EPA Clean Water Act nitrogen runoff monitoring data, and ammonia production capacity filings. Bottom-up demand modeling triangulates against top-down macroeconomic agriculture input expenditure trends.
Sensitivity analysis across natural gas price scenarios, regulatory enforcement intensity variations, and polymer feedstock availability constraints shapes the analytical framework. Segmentation dimensions modeled include product chemistry tier, application environment, distribution channel structure, and end-user sophistication level. CAGRs derive from trend extrapolation moderated by adoption curve analysis for controlled-release technology penetration. Industry-specific forecast inputs incorporate EU Green Deal nitrogen directive implementation schedules and China's dual carbon policy trajectory.
Material uncertainties — abrupt natural gas price spikes, accelerated EU REACH substance restrictions, and MEE enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory continuity and feedstock cost normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
North America Fertilizers Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Diammonium Phosphate (DAP) Market