
 Asia Pacific Controlled Release Fertilizers Market | 2026-2036
Asia Pacific Controlled Release Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Controlled Release Fertilizers Market Outlook
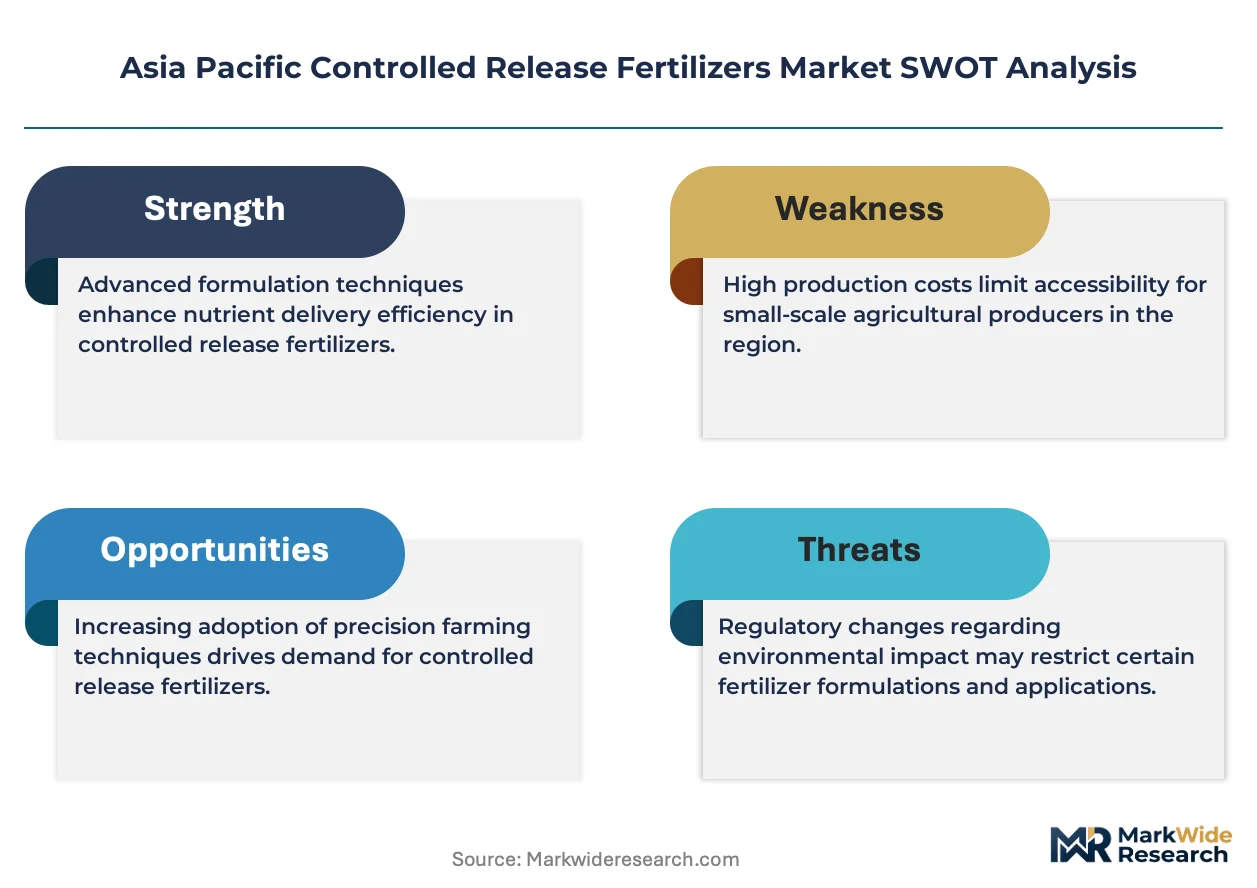
Capital-intensity divergence between integrated polymer-coating facilities and commodity blending operations is bifurcating competitive returns across the Asia Pacific Controlled Release Fertilizers Market. ICL Group Ltd leverages captive phosphate reserves and coating technology leadership to sustain margin structures that commodity blenders cannot replicate. Kingenta International anchors its position through deep distribution networks across China's provincial agricultural cooperatives. Yara International competes on precision-agriculture digital bundling rather than manufacturing scale alone.
Asia Pacific controlled release fertilizers encompass polymer-coated, sulfur-coated, and chemically stabilized formulations that meter nutrient availability across 30- to 180-day crop cycles, reducing leaching losses in monsoon-intensive cultivation systems. Their primary commercial purpose centers on aligning nitrogen release curves with crop phenology to improve nitrogen-use efficiency and limit environmental runoff. Coated variants command the dominant value share as polymer and sulfur encapsulation technologies mature, while liquid controlled-release formulations represent the fastest-growing product type due to compatibility with drip-fertigation systems in greenhouse-intensive regions. Among end users, greenhouse operators generate the highest per-hectare application rates and the most price-inelastic procurement patterns.
China's SAMR enforces GB standards for coated fertilizer quality thresholds, while India's FSSAI-aligned state agricultural departments regulate micronutrient claims under the CEA's fertilizer control order. Australia's TGA-equivalent agricultural chemical regulator, together with Japan's METI JIS standards for controlled-release specifications, creates a fragmented compliance landscape that favors multi-country registrants. Stakeholders must monitor polymer raw-material cost volatility and evolving coating-efficiency benchmarks as the primary determinants of manufacturing competitiveness and product substitution risk.
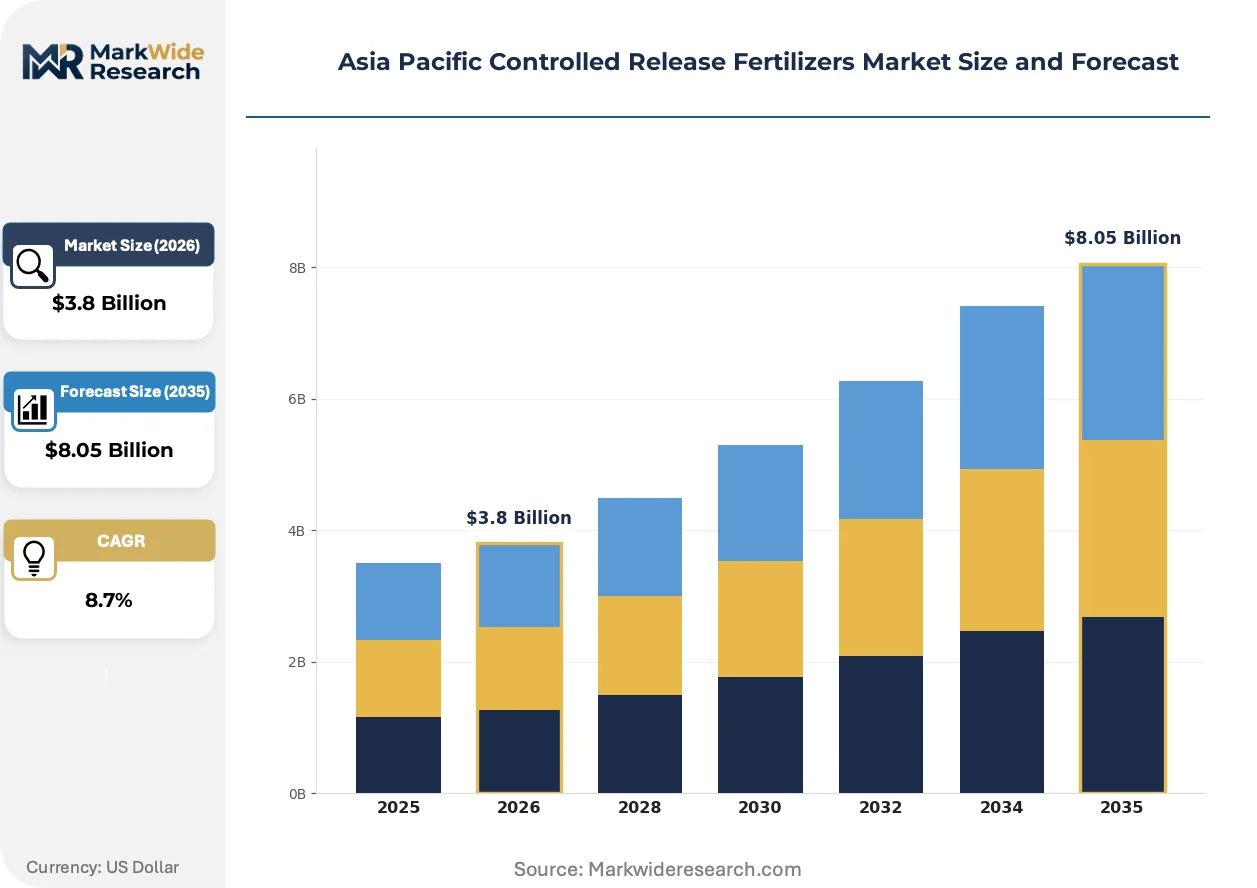
Market Dynamics
China's GB standards for polymer-coated urea quality thresholds are reshaping product registration pathways across the Asia Pacific Controlled Release Fertilizers Market, forcing manufacturers to recalibrate coating efficiency benchmarks and raw-material sourcing strategies.
Growth Catalysts
- Groundwater conservation mandates:India's CEA fertilizer control order in Punjab and Haryana states accelerates slow-release adoption as agricultural departments enforce nitrogen-use efficiency targets for water-intensive rice cultivation.
- Polymer coating maturation:Encapsulation technologies for 90- to 180-day nutrient release curves now align precisely with monsoon-driven crop phenology, reducing leaching losses in Vietnam and Indonesia's paddy systems.
- Drip-fertigation compatibility:Liquid controlled-release formulations penetrate greenhouse-intensive regions of Japan and South Korea, enabling precise nutrient timing in protected cultivation environments.
Market Restraints
- Polymer raw-material cost volatility:Petrochemical-derived coating substrates expose manufacturers to naphtha and propylene price swings that compress margin structures during energy market dislocations.
- Fragmented compliance landscape:Divergent quality thresholds between China's SAMR GB standards, Japan's METI JIS specifications, and India's FSSAI-aligned state regulations create multi-jurisdiction registration burdens for regional suppliers.
- Commodity urea substitution:Unsubsidized coated products face price resistance from conventional nitrogen sources in price-sensitive smallholder segments across Southeast Asian markets.
Strategic Opportunities
- Underpenetrated Indonesian smallholder sector:Kalimantan and Sulawesi rice cooperatives present white-space demand for sulfur-coated formulations suited to acidic soil conditions and irregular irrigation access.
- Digital agriculture bundling:Integration of controlled-release prescriptions with soil-sensor networks and variable-rate application platforms creates stickiness among Australian broadacre operators and Chinese provincial cooperatives.
- Japan's carbon-neutrality roadmap:METI incentives for reduced-input cultivation systems favor premium polymer-coated products that demonstrate measurable nitrogen-use efficiency gains in vegetable and fruit production.
Industry Challenges
- Coating technician skill scarcity:Polymer encapsulation process optimization requires specialized expertise in film-thickness control and release-kinetics calibration that outpaces vocational training pipelines in Vietnam and Indonesia.
- Integrated facility capex intensity:Captive polymer synthesis and coating operations demand capital commitments that exclude mid-scale blenders from margin structures achievable by phosphate-integrated manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Controlled Release Fertilizers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Coated, Slow-Release, Liquid Application: Agriculture, Horticulture, Turf, Landscaping End User: Farmers, Greenhouses, Landscape Contractors, Retailers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | ICL Group Ltd, Hebei Sanyuanjiuqi Fertilizer Co., Ltd., Grupa Azoty S.A. (Compo Expert), National Fertilizers Ltd, New Mountain Capital (Florikan), Yara International, Kingenta International, Hangfeng Evergreen, Nutrien Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Controlled Release Fertilizers Market Strategic Shifts
Coating technology trajectories and regulatory stringency are compressing competitive differentiation windows across the Asia Pacific Controlled Release Fertilizers Market, forcing simultaneous investment in formulation precision and compliance infrastructure.
Biodegradable polymer coatings derived from starch-blend and polylactic acid substrates are bifurcating the product landscape between premium environmental-credentials segments and cost-optimized conventional encapsulation. Japanese greenhouse operators and Australian organic-certified horticulture producers absorb these materials at 40-60% price premiums, while Southeast Asian rice sectors resist the cost transfer. The structural consequence is a two-tier supply base where coating-technology leadership determines accessible customer segments.
China's NMPA-aligned GB standards for coated fertilizer quality thresholds now mandate minimum nutrient-release predictability metrics and polymer-film integrity specifications that exceed prior industry norms. Manufacturers must submit extended field-trial data packages to SAMR provincial branches, extending registration timelines by 8-14 months for new product introductions. Polymer-coated urea categories face the steepest compliance escalation, while sulfur-coated variants navigate lighter technical documentation burdens.
State agricultural cooperatives in China and India are consolidating procurement authority away from fragmented village-level input retailers, concentrating annual contract volumes with manufacturers demonstrating coating-consistency certification and digital traceability systems. This channel compression disadvantages small blenders lacking laboratory quality-assurance infrastructure. The shift is most visible in Shandong Province and Maharashtra State, where cooperative federations now specify release-curve tolerance bands in tender documentation.
Asia Pacific Controlled Release Fertilizers Market Segmentation
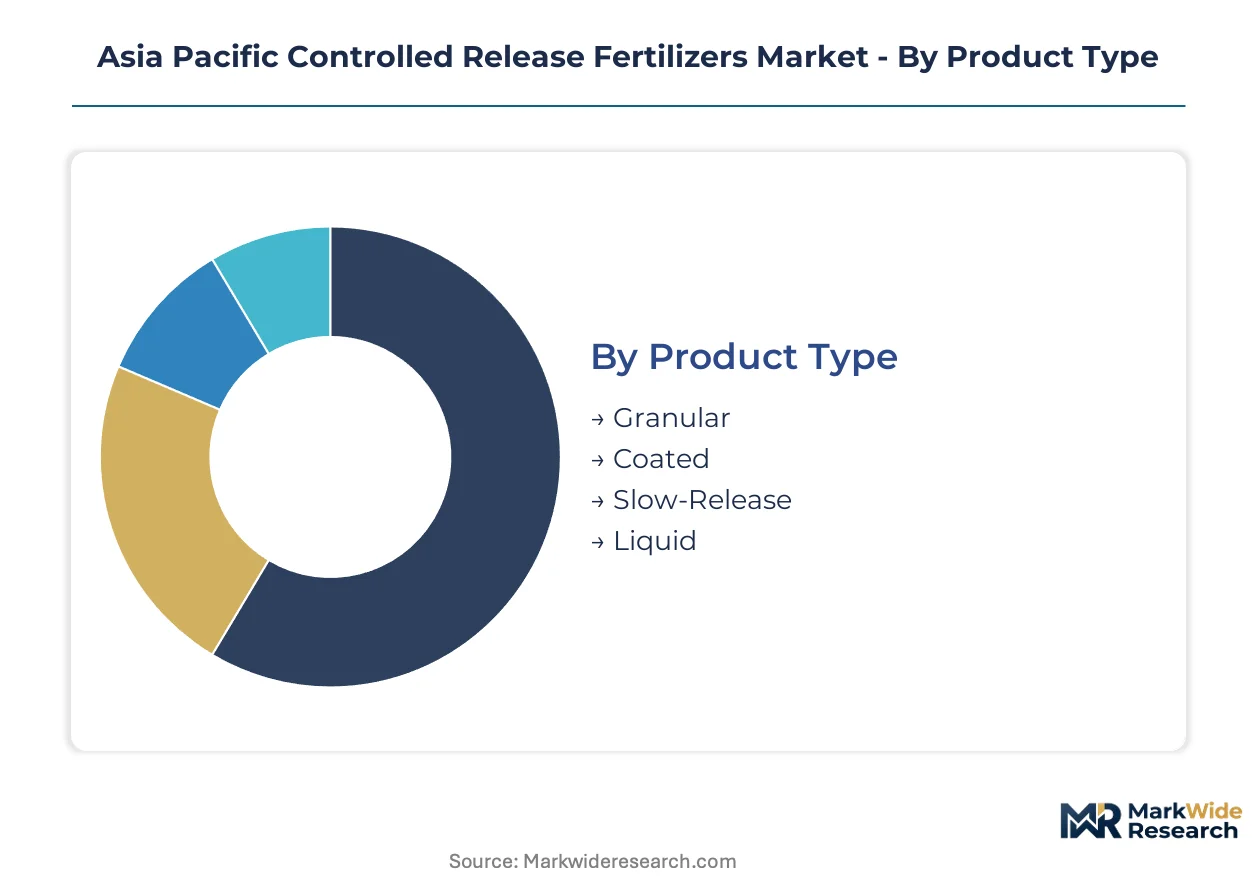
Segmentation in the Asia Pacific Controlled Release Fertilizers Market reveals how coating chemistry, application environment, and procurement authority reshape competitive access. Manufacturers must align formulation portfolios with divergent regulatory thresholds and channel consolidation patterns across rice-dominant and greenhouse-intensive cultivation systems.
Product Type:
China's SAMR GB standards for polymer-coated urea enforce distinct quality thresholds that separate registration pathways by encapsulation chemistry and release-curve predictability.
- Granular:Unencapsulated compressed formulations deliver baseline nutrient release for price-sensitive smallholder rice cultivation in Vietnam and Indonesia. Punjab agricultural departments restrict procurement to coated alternatives under CEA fertilizer control order mandates.
- Coated:Polymer and sulfur encapsulation technologies meter nitrogen across 90- to 180-day crop cycles, aligning release curves with monsoon-driven phenology in Indonesia's paddy systems. China's NMPA-aligned GB standards mandate minimum film-integrity specifications that extend SAMR registration timelines.
- Slow-Release:Chemically stabilized formulations inhibit urea hydrolysis through nitrification inhibitors, suited to acidic soil conditions in Kalimantan cooperatives with irregular irrigation access.
- Liquid:Controlled-release formulations compatible with drip-fertigation systems penetrate greenhouse-intensive regions of Japan and South Korea. These products enable precise nutrient timing in protected cultivation environments.
Established volume favors Coated; emerging adoption favors Liquid.
Application:
Water intensity and cultivation protection level determine which controlled-release formulations command price-inelastic procurement across the region's divergent agricultural systems.
- Agriculture:Rice cultivation in Vietnam and Indonesia drives coated fertilizer uptake as water-intensive cropping demands precise nutrient timing aligned with monsoon patterns. India's CEA mandates in Punjab and Haryana accelerate slow-release adoption for groundwater conservation.
- Horticulture:Vegetable and fruit production in Japan absorbs premium polymer-coated products demonstrating measurable nitrogen-use efficiency gains under METI carbon-neutrality incentives.
- Turf:Sports field and golf course maintenance in Australia's urban centers requires consistent greening without leaching runoff into sensitive watersheds.
- Landscaping:Municipal and commercial green space management in South Korean metropolitan regions prioritizes labor-reducing extended-release formulations.
Agriculture concentrates procurement volume; horticulture commands the steepest price premiums.
End User:
Procurement authority consolidation toward cooperative federations and away from village-level retailers restructures accessible customer segments by scale and technical sophistication.
- Farmers:Smallholder rice producers across Southeast Asia face commodity urea substitution pressure where unsubsidized coated products encounter price resistance.
- Greenhouses:Protected cultivation operators in Japan and South Korea generate the highest per-hectare application rates and most price-inelastic procurement patterns due to fertigation system compatibility requirements.
- Landscape Contractors:Commercial maintenance firms in Australian broadacre operations seek bundled prescriptions with soil-sensor networks and variable-rate application platforms.
- Retailers:Consolidating state agricultural cooperatives in Shandong Province and Maharashtra State now specify release-curve tolerance bands in tender documentation, excluding small blenders lacking laboratory quality-assurance infrastructure.
Greenhouses sustain margin structures; cooperative procurement concentration favors integrated manufacturers.
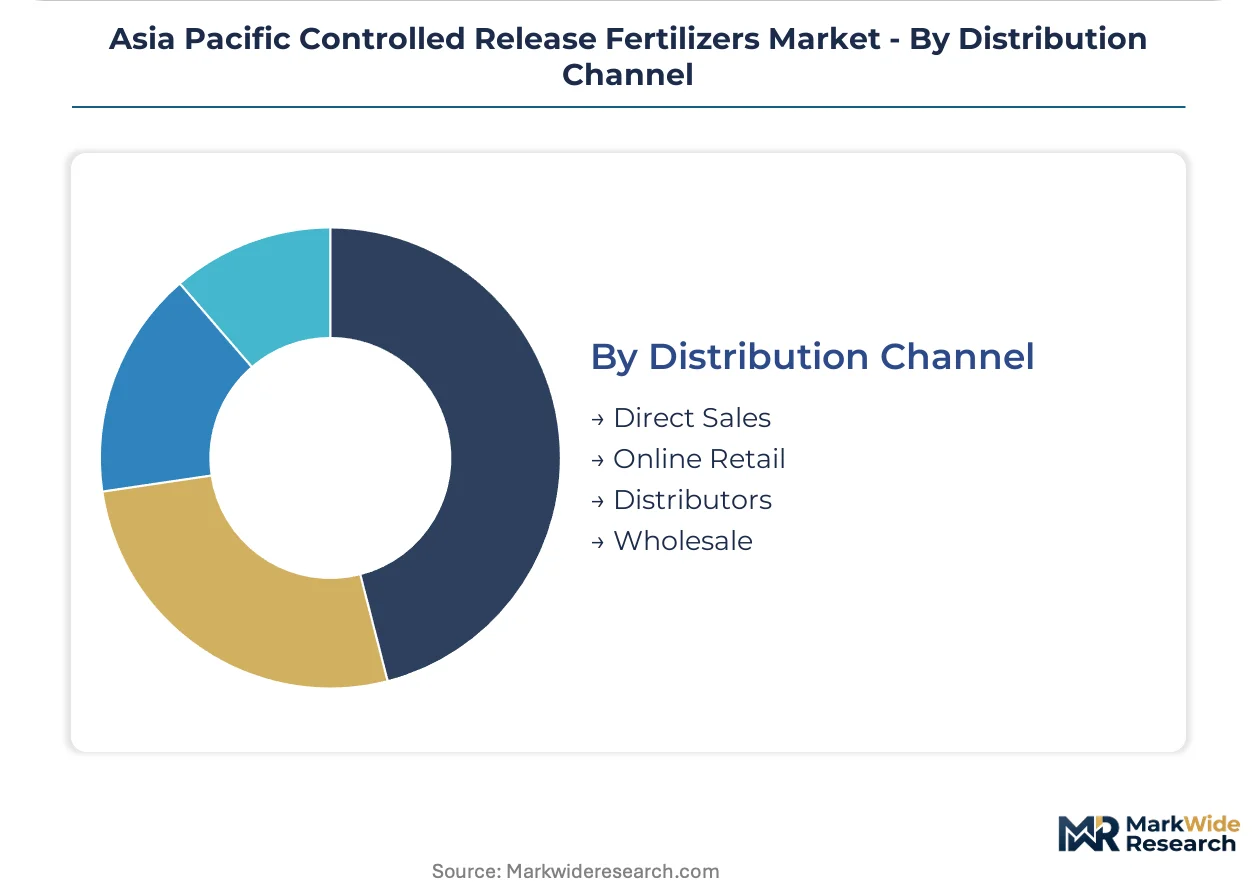
Distribution Channel:
Channel selection determines compliance burden exposure and customer relationship stickiness across fragmented regulatory jurisdictions.
- Direct Sales:Manufacturer relationships with provincial agricultural cooperatives in China and India concentrate annual contract volumes and require coating-consistency certification.
- Online Retail:E-commerce penetration remains limited for controlled-release formulations requiring technical consultation on release-curve matching to crop phenology.
- Distributors:Regional intermediaries navigate multi-jurisdiction registration burdens between China's SAMR, Japan's METI JIS specifications, and India's FSSAI-aligned state regulations.
- Wholesale:Volume aggregation through agricultural input wholesalers serves commodity blending operations excluded from integrated polymer-coating facility margin structures.
Direct sales capture cooperative consolidation; distributor networks manage regulatory fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in controlled release fertilizers tilt toward domestic production across Northeast Asia, while Southeast Asian markets absorb coated product inflows from regional manufacturing hubs. China's polymer-coating capacity expansion is displacing former import dependence for sulfur-coated variants.
China
Rice cultivation in the Yangtze River Delta and Shandong Peninsula drives polymer-coated urea consumption as water-intensive cropping demands precise nutrient timing. SAMR enforces GB standards for film-integrity specifications that extend registration timelines for new market entrants. Provincial agricultural cooperatives in Shandong now consolidate procurement authority, concentrating annual contract volumes with certified manufacturers.
India
Groundwater depletion in Punjab and Haryana states accelerates slow-release adoption as the CEA fertilizer control order mandates nitrogen-use efficiency targets for paddy cultivation. State agricultural departments align micronutrient claims with FSSAI standards under evolving fertilizer control frameworks. Cooperative federations in Maharashtra specify release-curve tolerance bands in tender documentation, excluding small blenders lacking laboratory infrastructure.
Japan
Greenhouse vegetable and fruit production in the Kanto region absorbs premium polymer-coated products demonstrating measurable efficiency gains. METI carbon-neutrality incentives favor reduced-input cultivation systems with documented nitrogen-use performance. Protected cultivation operators in Chubu and Kyushu generate the highest per-hectare application rates due to fertigation compatibility requirements.
Vietnam
Mekong Delta rice systems drive coated fertilizer uptake as monsoon-driven phenology demands nutrient release curves spanning 90- to 180-day cycles. The country's agricultural extension services promote encapsulation technologies to reduce leaching losses in water-intensive paddy cultivation. Provincial input distributors in the Red River Delta navigate technical consultation requirements for release-curve matching.
Australia
Broadacre operators in New South Wales and Victoria seek bundled prescriptions integrating controlled-release formulations with soil-sensor networks and variable-rate platforms. The national agricultural chemical regulator enforces quality thresholds for coated products entering watershed-sensitive catchments. Landscape contractors in metropolitan centers prioritize extended-release formulations for labor-reducing maintenance of sports fields and commercial green space.
Asia Pacific Controlled Release Fertilizers Market Competitive Environment
Concentration sits with integrated phosphate-captive manufacturers possessing in-house coating technology and laboratory certification infrastructure. Mid-scale blenders face exclusion from cooperative procurement channels as registration burdens and quality-assurance requirements escalate. Two strategic archetypes dominate: phosphate-integrated coating specialists leveraging captive raw material supply, and precision-agriculture bundlers competing through digital platform integration. Dominant competitive moves include backward integration into polymer synthesis operations and geographic expansion through provincial cooperative federation contracts.
Within the integrated manufacturing tier, ICL Group Ltd and Kingenta International exemplify divergent geographic anchoring strategies. Yara International occupies a position emphasizing precision-agriculture digital bundling over manufacturing scale alone. Nutrien Ltd and Hangfeng Evergreen represent North American and Chinese capital structures respectively, each navigating the fragmented compliance landscape spanning SAMR, METI JIS, and India's FSSAI-aligned state regulations. Hebei Sanyuanjiuqi Fertilizer Co., Ltd. and National Fertilizers Ltd illustrate state-linked and provincial cooperative distribution penetration models.
| Leading Market Players |
|---|
| ICL Group Ltd |
| Hebei Sanyuanjiuqi Fertilizer Co., Ltd. |
| Grupa Azoty S.A. (Compo Expert) |
| National Fertilizers Ltd |
| New Mountain Capital (Florikan) |
| Yara International |
| Kingenta International |
| Hangfeng Evergreen |
| Nutrien Ltd. |
| Others |
Value Chain & Pricing Dynamics
China's SAMR GB standards for polymer-coated urea quality thresholds gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb extended registration costs that separate certified producers from commodity blenders unable to meet film-integrity specifications. This regulatory filter concentrates pricing power with integrated phosphate-captive manufacturers while excluding mid-scale operations from cooperative procurement channels.
Pricing Analysis
Configured-to-order pricing for custom release-curve formulations commands substantial premiums over standard polymer-coated urea grades, with coating-thickness precision and nutrient-release predictability driving differentiation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with greenhouse operators in Japan and South Korea showing least price sensitivity due to fertigation compatibility requirements. Cost compression in economy-tier sulfur-coated variants is intensifying because of naphtha and propylene volatility, while smallholder rice producers across Southeast Asia exhibit highest price resistance to unsubsidized coated products.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo port corridors fluctuate with container availability and intra-Asia trade lane congestion, compressing margins for polymer raw-material importers. Manufacturing concentrates in China, India, and Japan, with captive phosphate reserves in Israel and Morocco feeding coating operations. The supply chain rests on petrochemical-derived substrates and sulfur feedstock dependencies, with single-source vulnerability in specialized polymer synthesis equipment. Distribution runs through consolidating state agricultural cooperatives in Shandong Province and Maharashtra State that now mandate laboratory quality-assurance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where digital agriculture bundling and soil-sensor integration expand faster than standalone fertilizer manufacturing, creating recurring-revenue layers through precision-agriculture subscriptions.
For Market Incumbents: Compound coating-technology leadership through backward integration into polymer synthesis operations and captive phosphate supply, defending against commodity urea substitution pressure by embedding release-curve optimization services. Prioritize certification investment for China's SAMR GB standards and India's FSSAI-aligned state registrations to maintain cooperative procurement access.
For New Entrants and Emerging Players: Lead with biodegradable polymer coatings targeting Japan's METI carbon-neutrality incentives and Australian organic-certified horticulture producers willing to absorb environmental-credential premiums. Target Indonesia's Kalimantan and Sulawesi rice cooperatives with sulfur-coated formulations suited to acidic soil conditions, deploying technical consultation services for release-curve matching as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-agriculture platforms possessing digital bundling capabilities but lacking captive manufacturing infrastructure. Long-term viability across the analysis window favors acquisition targets with laboratory quality-assurance certification and provincial cooperative federation contracts. Watch for inflection signals in China's SAMR registration timeline compression as a leading indicator of competitive access tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captive substrate supply insulates margin structures from naphtha volatility in coating operations. |
| Digital Agriculture Bundling | Soil-sensor integration with controlled-release prescriptions creates stickiness among Australian broadacre operators. |
| Biodegradable Coating Development | Starch-blend and polylactic acid substrates access Japan's METI carbon-neutrality incentive programs. |
| Provincial Cooperative Federation Contracts | Shandong and Maharashtra procurement consolidation concentrates annual volumes with certified manufacturers. |
| Extended Registration Data Packages | Field-trial documentation for China's SAMR GB standards extends competitive moats against unqualified entrants. |
Study Parameters
Desk research of customs and trade data, agricultural chemical registration databases, and SEC filings preceded structured interviews with polymer-coating plant managers, procurement leads at downstream greenhouse operators, distribution channel partners, and technical R&D directors at integrated manufacturers. Primary fieldwork combined with secondary validation from SAMR provincial branch documentation and METI JIS specification releases enabled bottom-up and top-down triangulation across product type, application environment, and end-user procurement authority segments.
Variance-decomposition across the modeling period isolates volume drivers by coating chemistry, cultivation protection level, and regulatory compliance tier, with CAGRs derived from segmented growth trajectory analysis. The analytical framework incorporates nutrient-release predictability benchmarks, polymer raw-material cost indices, and cooperative procurement consolidation patterns as industry-specific forecast inputs alongside standard demographic and macroeconomic variables.
The analysis sits within stated boundaries; outcomes outside sustained regulatory stringency in China and India or abrupt polymer feedstock price dislocation would require recalibration. Forecasts reflect assumptions regarding SAMR registration timeline stability and METI incentive program continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
United States Organic Fertilizers Market