
 Crop Micronutrients Market | 2026-2036
Crop Micronutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Micronutrients Market Intelligence
The gap between premium chelated micronutrient formulations and commodity-grade bulk powders is rebalancing as commercial growers demand water-soluble precision products while smallholder segments remain price-sensitive. Nutrien Ltd. leverages its retail agronomy network to push high-margin liquid micronutrient programs directly to farm gate customers. Yara International ASA anchors its position through backward integration into mining and acid production for boron and zinc intermediates. BASF SE differentiates via patented chelation chemistry that improves nutrient uptake efficiency in alkaline soils.
Crop micronutrients encompass essential mineral elements—iron, zinc, manganese, copper, boron, and molybdenum—required in trace quantities for plant metabolic functions, typically supplied at concentrations below one part per million in plant tissue, with chelation technologies using EDTA, DTPA, or natural lignosulfonate ligands to maintain solubility across varying pH conditions. Their primary purpose is correcting deficiency-induced yield losses in intensive cropping systems where soil depletion outpaces natural replenishment. Zinc and boron formulations dominate volume flows due to widespread deficiency in cereal-growing regions, while chelated iron products command premium positioning in horticultural segments where chlorosis control determines crop value. Liquid applications are displacing granular methods in drip-irrigated specialty crop systems, though powder and pellet forms retain cost advantages in broad-acre broadcasting operations across developing agricultural economies.
The EU Fertilizing Products Regulation and REACH compliance requirements are reshaping import specifications for micronutrient blends entering European markets, while India's BIS certification and CDSCO oversight of micronutrient mixtures as agricultural inputs create parallel compliance pathways. The EPA and state-level fertilizer regulatory frameworks in the United States impose labeling and heavy-metal limits that filter which products reach commercial distribution channels. Stakeholders must monitor divergence between regional micronutrient labeling standards and emerging carbon-accounting requirements for fertilizer production, as these will increasingly determine market access and margin sustainability.
Market Dynamics
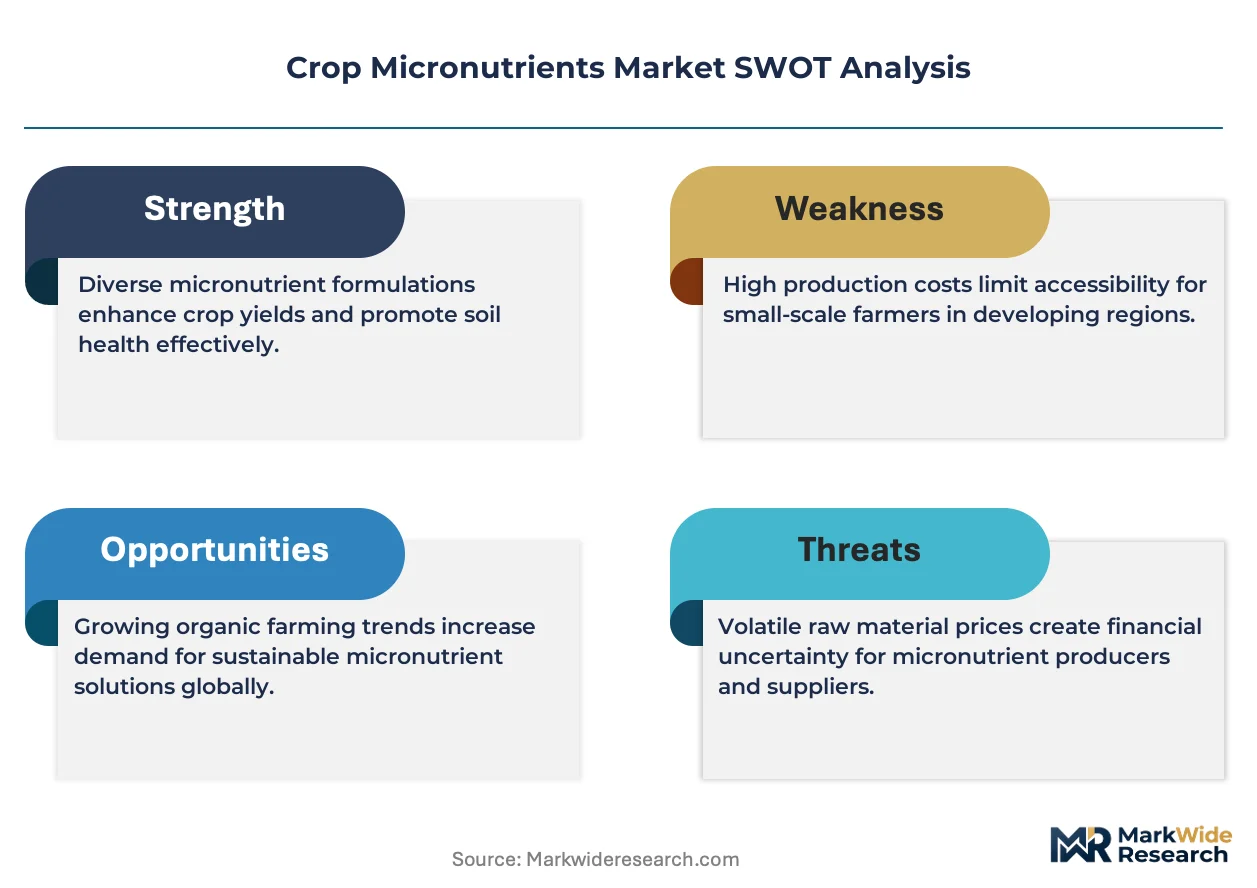
The EU Fertilizing Products Regulation is compressing formulation standards across borders, forcing blenders to abandon commodity sulfates for certified chelates while India's PLI scheme redirects procurement toward domestic manufacturing of precision-grade inputs.
Growth Catalysts
- EU Fertilizing Products Regulation:Mandatory CE marking for micronutrient blends entering European markets is accelerating chelation technology upgrades among exporters targeting controlled-environment agriculture operations.
- Controlled-environment agriculture:Specialty vegetable growers operating hydroponic and greenhouse systems now specify water-soluble precision formulations that command premium positioning over bulk powders.
- India's PLI scheme:Production-linked incentives for agrochemical manufacturing are redirecting domestic procurement toward certified chelated formulations produced in Maharashtra and Gujarat clusters.
Market Restraints
- Sulfuric acid price volatility:Fluctuations in sulfur-derived intermediate costs compress margins for sulfate-based micronutrient producers serving price-sensitive smallholder segments.
- EDTA supply concentration:Chelating agent production clusters in China create input dependency risks for European and North American blenders formulating premium products.
- REACH registration thresholds:The European Chemicals Agency's data requirements for novel chelating ligands extend commercialization timelines by 18-24 months for innovative formulations.
Strategic Opportunities
- Sub-Saharan Africa soil mapping:National agricultural research institutes in Ethiopia and Nigeria are identifying zinc and boron deficiency zones, creating first-mover openings for certified blend suppliers.
- Biostimulant-micronutrient convergence:Formulators combining lignosulfonate-chelated minerals with seaweed extracts can access dual-use product registrations under evolving EU fertilizer categories.
- Distributor agronomy services:Farm-gate technical support bundled with liquid micronutrient programs is capturing grower loyalty in Brazil's citrus and coffee belts.
Industry Challenges
- Chelate stability testing capacity:Analytical laboratories capable of validating DTPA and EDDHA chelation integrity under variable pH conditions remain scarce outside Western Europe and North America.
- Legacy equipment incompatibility:Broad-acre operations in developing agricultural economies face capital barriers when retrofitting granular spreaders for liquid application systems.
- Heavy-metal contamination verification:Cadmium and arsenic testing protocols required by EPA state-level frameworks add 6-8 weeks to batch release schedules for imported blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Micronutrients Market |
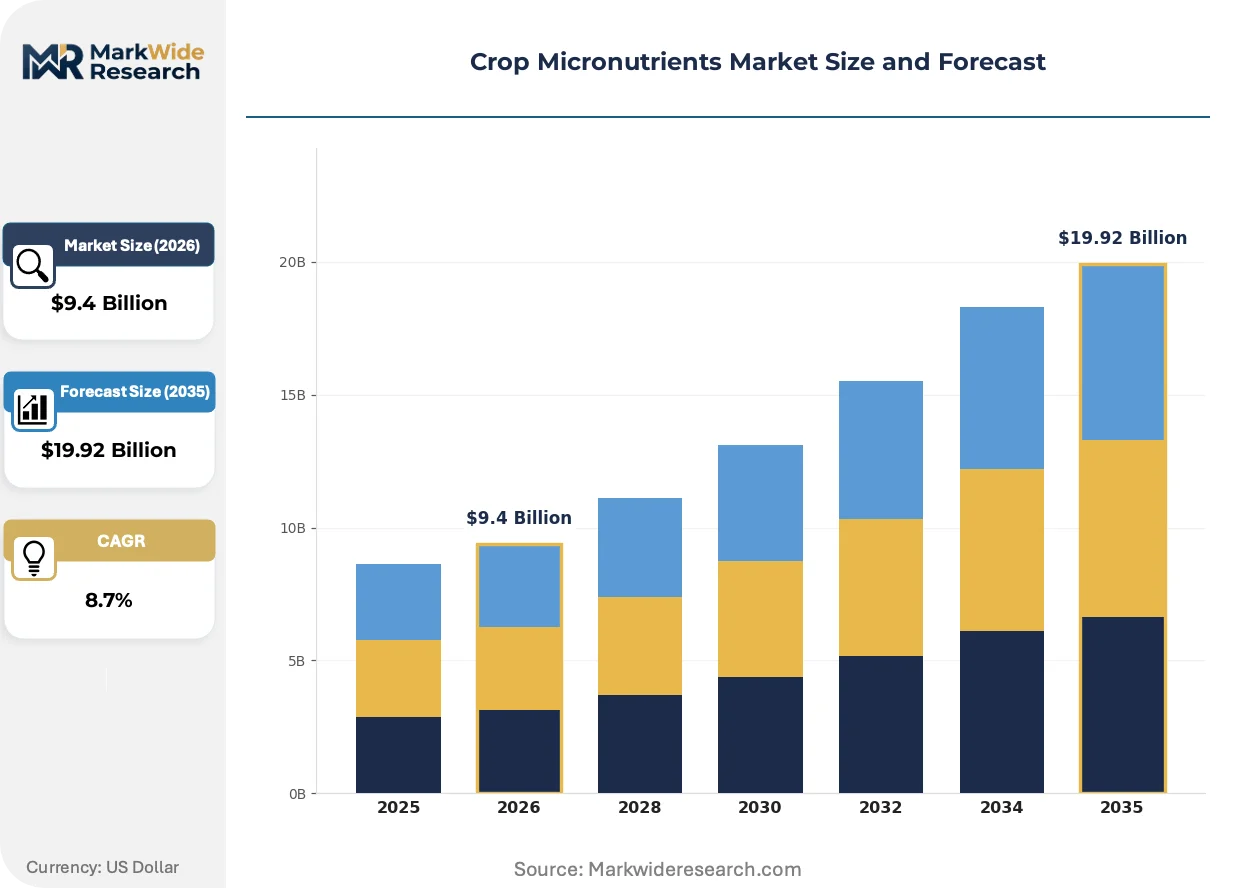
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron, Zinc, Manganese, Copper, Boron, Molybdenum Form: Liquid, Powder, Granular, Chelates, Pellets Application: Cereal Crops, Oilseeds, Pulses, Fruits, Vegetables, Plantation Crops End User: Smallholder Farmers, Commercial Growers, Agrochemical Companies, Horticulturists |
| Companies Covered | Nutrien Ltd., Yara International ASA, The Mosaic Company, BASF SE, ICL Group Ltd., Nouryon, Haifa Group, Valagro S.p.A, Coromandel International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Micronutrients Market Strategic Shifts & Innovations
Precision delivery systems and biological chelation alternatives are compressing the performance gap between synthetic and natural formulations while regulatory data requirements reshape competitive entry barriers.
Sensor-guided variable-rate application technology is automating micronutrient distribution in drip-irrigated specialty crop systems. Large-scale tomato and pepper operations in California's Central Valley deploy soil-mounted ion-selective electrodes that trigger foliar feed cycles based on real-time tissue analysis. This automation is compressing labor inputs while reducing over-application penalties in water-quality constrained watersheds.
REACH Annex XVII amendments restricting persistent organic pollutants in fertilizer matrices are forcing reformulation of boron carriers containing legacy contaminants. The European Chemicals Agency's 2024 guidance on micronutrient additive safety data sheets now requires chronic ecotoxicity endpoints previously exempt for trace mineral products. Horticultural exporters to Northern European markets face the steepest compliance costs as supermarket chains mandate third-party verification of chelate biodegradability.
Specialty crop buyers now specify performance guarantees tied to tissue-test outcomes rather than input volumes. Distributor agronomists in India's Punjab and Haryana states bundle zinc application programs with post-harvest deficiency verification, replacing transactional powder sales with season-long technical contracts. This service integration is most visible where government soil health card schemes have established baseline micronutrient status databases at the village level.
Crop Micronutrients Market Segmentation
Crop micronutrient purchasing decisions hinge on soil chemistry compatibility, application infrastructure, and crop value density. Buyers segment themselves across these dimensions, creating distinct margin pools that favor precision formulations in high-value horticulture and commodity powders in broad-acre cereals.
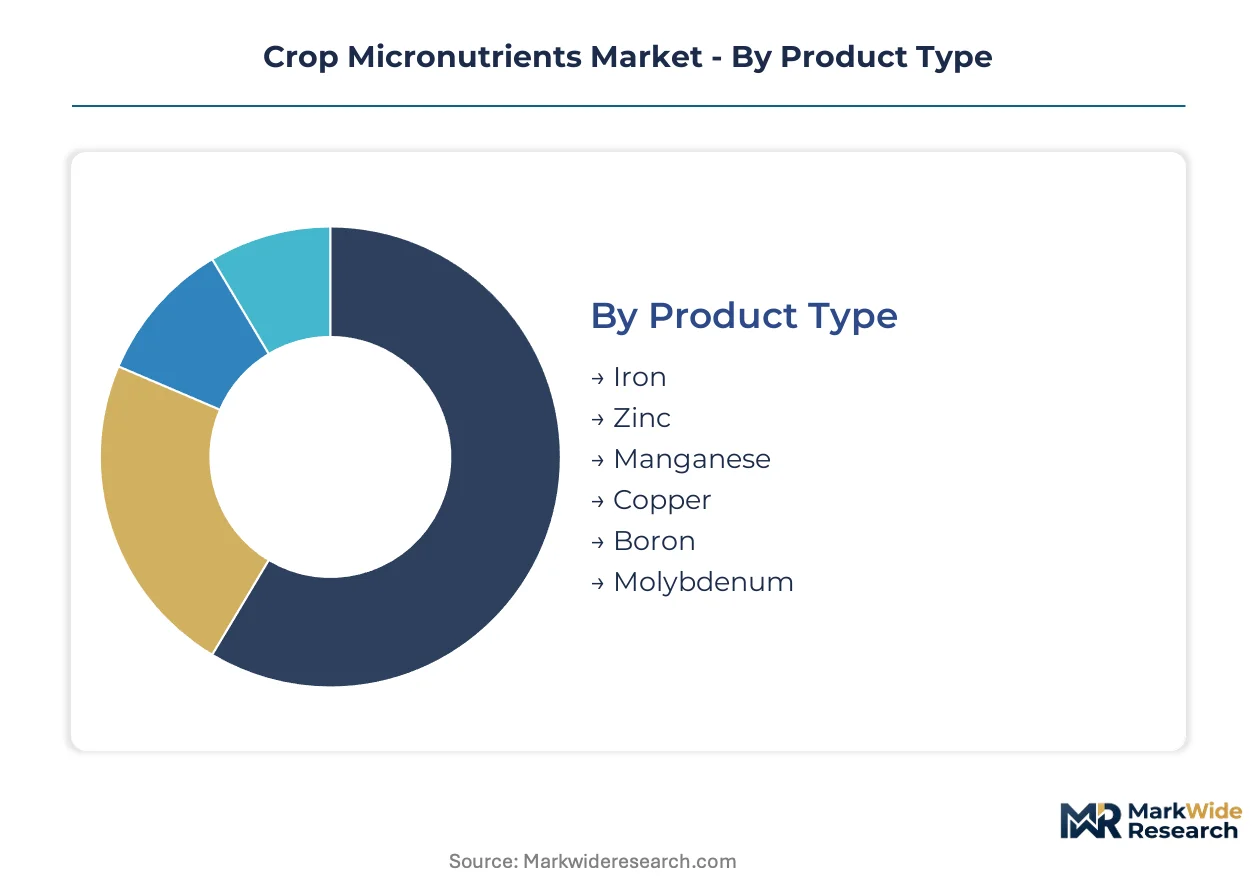
Product Type:
Buyers prioritize deficiency prevalence in their regional soils and the agronomic return per dollar spent on correction.
- Zinc:Sulfate and oxide forms dominate volume flows across cereal-growing regions of India and Ethiopia where calcareous soils lock up native zinc. State agricultural extension programs in Maharashtra distribute certified zinc formulations through subsidized input channels.
- Boron:Solubility requirements in alkaline conditions drive specification of refined borates over raw mineral sources. California almond and pistachio growers mandate water-soluble boron for fertigation systems during critical flowering windows.
- Iron:Chelated ferrous forms using EDDHA ligands command premium positioning in drip-irrigated greenhouse operations where chlorosis control determines harvest quality.
- Manganese:EDTA-chelated products serve specialty crop segments in Florida's citrus belt where soil pH extremes induce deficiency despite adequate total soil manganese.
- Copper:Sulfate-based powders retain cost advantage in wheat systems of the Indo-Gangetic Plain where deficiency correction requires broadcast scale rather than precision placement.
- Molybdenum:Ammonium molybdate concentrates address nodulation failure in pulse crops across Saskatchewan and Australian lentil-growing regions where soil molybdenum availability limits nitrogen fixation.
Zinc leads on scale; boron leads on momentum.
Form:
Application equipment compatibility and labor cost structures determine form selection across farm size tiers.
- Liquid:Ready-to-use concentrates eliminate dissolution steps and enable injection into pressurized irrigation networks. Nutrien's retail agronomists in Brazil's citrus belt bundle technical support with liquid micronutrient programs that displace granular alternatives.
- Chelates:Synthetic and natural ligand formulations maintain nutrient solubility across pH extremes that precipitate unprotected mineral salts. BASF's patented chelation chemistry captures premium positioning in alkaline soil zones of Spain's greenhouse vegetable sector.
- Powder:Dry crystalline products retain transport cost advantages and extended shelf stability for smallholder procurement through cooperative distribution channels.
- Granular:Blended fertilizer carriers enable single-pass application in mechanized broad-acre operations across the US Corn Belt and Ukrainian wheat systems.
- Pellets:Compressed formulations reduce dust exposure during handling and enable controlled-release characteristics in perennial plantation crops.
Powder leads on scale; liquid leads on momentum.
Application:
Crop value per hectare and harvest quality sensitivity drive micronutrient investment intensity.
- Vegetables:Controlled-environment tomato and pepper operations in the Netherlands and Mexico specify water-soluble precision formulations tied to tissue-test monitoring protocols. Sensor-guided variable-rate systems automate foliar feed cycles based on real-time ion-selective electrode readings.
- Fruits:Permanent crop systems in California's Central Valley and Chile's Central Valley deploy fertigation-compatible chelates during phenological stages where micronutrient stress compromises pack-out grades.
- Cereal Crops:Wheat and rice systems across India's Punjab and Haryana states apply zinc through government-subsidized powder programs linked to soil health card databases.
- Oilseeds:Canola and sunflower operations in Ukraine and Argentina address boron deficiency during reproductive growth stages through foliar application timing.
- Pulses:Lentil and chickpea growers in Ethiopia's highlands apply molybdenum seed treatments to ensure nodulation establishment in acidic, low-molybdenum soils.
- Plantation Crops:Coffee and tea estates in Karnataka and Kerala states of India integrate micronutrient programs with shade management and pruning cycles.
Cereal crops lead on scale; vegetables lead on momentum.
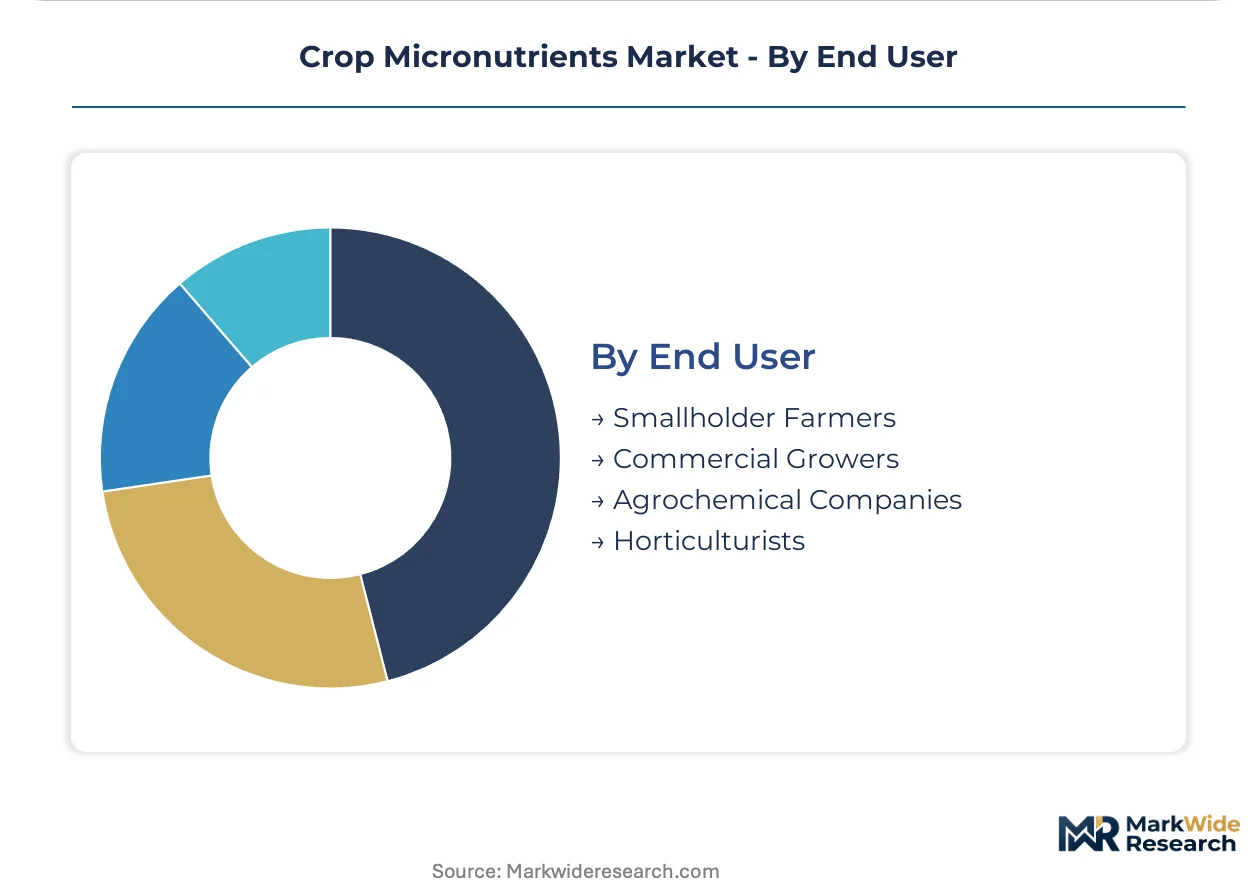
End User:
Technical capability and capital access separate price-sensitive volume buyers from service-attached premium segments.
- Commercial Growers:Large-scale specialty crop operations in California, Spain, and Mexico specify performance guarantees tied to tissue-test outcomes rather than input volumes. Distributor agronomists bundle season-long technical contracts with liquid micronutrient programs.
- Smallholder Farmers:India's 120 million smallholders access subsidized zinc and boron powders through state agricultural extension networks linked to soil health card schemes. Price sensitivity limits uptake of chelated formulations despite demonstrated agronomic superiority.
- Agrochemical Companies:Formulation specialists in Gujarat and Maharashtra clusters blend micronutrient premixes for resale under private labels, sourcing chelating agents from concentrated Chinese production centers.
- Horticulturists:Protected cultivation operators in the Netherlands and Belgium demand third-party verification of chelate biodegradability under supermarket chain sustainability protocols.
Smallholder farmers lead on scale; commercial growers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomists and soil scientists concentrate in India, the Netherlands, and California's Central Valley, anchoring technical demand for precision micronutrient formulations. Their expertise shapes procurement specifications across controlled-environment agriculture and broad-acre cereal systems.
India
Maharashtra and Gujarat clusters manufacture certified chelated formulations under the government's PLI scheme for agrochemical production. CDSCO oversight of micronutrient mixtures as agricultural inputs creates compliance pathways for domestic blenders. State agricultural extension programs in Punjab distribute subsidized zinc powders through soil health card databases.
United States
California's Central Valley tomato and pepper operations deploy sensor-guided variable-rate application systems automating foliar feed cycles. EPA and state-level fertilizer frameworks impose labeling and heavy-metal limits filtering products reaching commercial channels. Nutrien's retail agronomists bundle liquid micronutrient programs directly to specialty crop growers.
Germany
BASF anchors premium positioning through patented chelation chemistry improving nutrient uptake in alkaline soils. REACH registration thresholds at the European Chemicals Agency extend commercialization timelines for novel ligands by 18-24 months. The EU Fertilizing Products Regulation mandates CE marking compressing formulation standards for exporters.
Brazil
Distributor agronomy services capture grower loyalty in citrus and coffee belts through farm-gate technical support bundled with liquid programs. Sulfuric acid price volatility compresses margins for sulfate-based producers serving price-sensitive smallholder segments. State agricultural research institutes identify deficiency zones creating openings for certified blend suppliers.
Netherlands
Greenhouse vegetable growers in Westland and North Brabant specify water-soluble precision formulations tied to tissue-test monitoring protocols. Supermarket chains mandate third-party verification of chelate biodegradability under sustainability protocols. REACH Annex XVII amendments restricting persistent organic pollutants force reformulation of legacy boron carriers.
Crop Micronutrients Market Key Industry Players
Top-tier vendors anchor premium chelation technology, while regional blenders and commodity sulfate producers occupy volume tiers. The vendor base stratifies across three archetypes: integrated mining-to-retail conglomerates controlling upstream boron and zinc intermediates; specialty chelation houses patenting ligand chemistry for alkaline soil performance; and formulation blenders sourcing Chinese EDTA concentrates for private-label resale. Dominant competitive moves include backward integration into acid and mining operations, plus agronomy service bundling displacing transactional input sales.
Within the integrated mining-to-retail tier, Nutrien Ltd. and Yara International ASA exemplify archetypes combining upstream mineral control with farm-gate distribution networks. BASF SE occupies a position representing specialty chelation chemistry, while Coromandel International Ltd. anchors the regional formulation blender segment. These three company structures illustrate how competitive positioning separates captive supply advantages from technology differentiation and geographic density.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Yara International ASA |
| The Mosaic Company |
| BASF SE |
| ICL Group Ltd. |
| Nouryon |
| Haifa Group |
| Valagro S.p.A |
| Coromandel International Ltd |
| Others |
Cost & Logistics Intelligence
Formulation chemists concentrated in Gujarat and Maharashtra clusters anchor labor-cost differentials that widen pricing-tier spreads between certified chelates and commodity sulfates. Their technical expertise enables domestic manufacturers to undercut European blenders on precision-grade production while maintaining REACH-equivalent quality benchmarks.
Pricing Analysis
Bundled agronomy services versus unbundled commodity sales split the pricing architecture across buyer tiers. Three-tier pricing structure across premium, standard, and economy levels captures service-attached commercial growers, certified-chelate mid-market buyers, and price-sensitive smallholder segments respectively. Price differentiation rests on chelation certification grade and bundled technical support intensity. Cost compression in commodity sulfate tiers is intensifying because sulfuric acid feedstock volatility transmits directly to margin structures. Smallholder farmers in India's cooperative procurement channels exhibit highest price sensitivity; commercial greenhouse operators in California and the Netherlands show least.
Supply Chain Analysis
Certification and qualification gating through BIS, CDSCO, and REACH frameworks filter which formulations enter priority markets. Manufacturing concentrates in India, China, and Germany, with formulation blending clustered in Gujarat and acid production anchored in German industrial corridors. Raw material dependencies center on sulfur-derived intermediates, Chinese EDTA concentrates, and mined boron from Turkish and South American deposits. Single-source vulnerability around EDTA chelating agents creates structural risk for European and North American blenders. Distribution runs through agronomy-retail networks in mature markets and state-subsidized extension channels in developing agricultural economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as commercial growers shift procurement specifications toward tissue-test-verified outcomes rather than input volumes. Premium chelation technologies capture expanding margin pools while commodity sulfates face structural compression.
For Market Incumbents: Lock in backward integration into acid and mining operations to secure captive supply of boron and zinc intermediates against sulfur price volatility. Deepen certification investments for EU Fertilizing Products Regulation compliance to defend margin position against emerging regional blenders. Prioritize channel control through retail agronomy networks that bundle technical services with liquid formulation programs.
For New Entrants and Emerging Players: India's PLI scheme for agrochemical manufacturing opens a window for domestic production of certified chelated formulations serving Maharashtra and Gujarat industrial clusters. Target Sub-Saharan Africa soil mapping initiatives in Ethiopia and Nigeria as the most penetrable geography for first-mover certified blend supply. Pursue biostimulant-micronutrient convergence under evolving EU fertilizer categories as the go-to-market angle for dual-use product registrations.
For Investors and Strategic Acquirers: Integrated mining-to-retail conglomerates are the most active acquirer in this space, seeking captive mineral supply and farm-gate distribution density. Long-term viability over a multi-year horizon favors specialty chelation houses with patented ligand chemistry and regional formulation blenders with geographic concentration in high-growth agricultural corridors. Watch for divergence between regional micronutrient labeling standards and emerging carbon-accounting requirements as the inflection signal for margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Operations | Yara International ASA secures captive boron supply from upstream mineral assets. |
| Certification Investment for REACH Compliance | BASF SE extends commercialization timelines but locks out commodity competitors. |
| Agronomy Service Bundling | Nutrien Ltd. captures grower loyalty through farm-gate technical support programs. |
| Biostimulant-Micronutrient Convergence | Valagro S.p.A accesses dual-use registrations under EU Fertilizing Products Regulation. |
| Regional Manufacturing Cluster Expansion | Coromandel International Ltd. leverages PLI incentives in Gujarat production hubs. |
Research Approach
Bottom-up crop modeling reconciled against top-down chelating agent production tracking forms the analytical core of this study. Primary interviews with formulation chemists, retail agronomists, state agricultural extension officers, and procurement leads at commercial growing operations combined with secondary validation from customs records, CDSCO registration databases, EU Fertilizing Products Regulation certification listings, and SEC filings of listed agrochemical manufacturers. Triangulation across stakeholder inputs and documentary sources ensures coverage of both demand-side specification shifts and supply-side capacity dynamics.
Historical trendline analysis of zinc and boron formulation volumes, chelation technology adoption curves, and regional procurement pattern shifts informed the projection framework. Segmentation dimensions modeled include micronutrient type, chelation chemistry grade, application form, crop category, and end-user technical capability tier. CAGRs derived from fitted growth curves applied to baseline volume estimates, with cross-checks against sulfuric acid price elasticity and subsidy program budget trajectories in priority markets.
Revisions become necessary when sulfur-derived intermediate cost shocks, regulatory reclassification of chelating agents, or subsidy program suspensions materialize. Forecasts reflect assumptions regarding continuation of current certification pathways and trade flow patterns. A model refresh is warranted upon material change in EU-India regulatory alignment or carbon-accounting integration into fertilizer procurement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Nitrogen Nutrients Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Africa Fertilizers Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market