
 Italy Foliar Fertilizer Market | 2026-2036
Italy Foliar Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Foliar Fertilizer Market Intelligence
The gap between premium chelated micronutrient formulations and commodity NPK foliar sprays is realigning procurement patterns across Italian agriculture. ICL leverages its integrated phosphate mining and specialty nutrient manufacturing to dominate the premium chelate segment. Timac Agro anchors its position through deep distribution networks in northern Italy's cooperative farming systems. Valagro differentiates via marine biostimulant extraction technology that commands higher margins in organic-certified operations.
Foliar fertilizers are nutrient solutions applied directly to plant leaves, typically containing soluble nitrogen, phosphorus, potassium, and trace elements in concentrations optimized for rapid stomatal and cuticular absorption, with pH buffering and surfactant adjuvants to maximize foliar uptake efficiency. Their primary purpose is to correct acute nutrient deficiencies during critical growth stages when root uptake cannot meet metabolic demand. Liquid formulations lead the product type landscape due to compatibility with existing spray equipment and uniform droplet distribution, while suspended concentrates capture growing interest for their higher nutrient payload per application. Among crop types, fruits command the densest margin pool as vineyard and orchard operators prioritize precision nutrient timing over per-hectare cost minimization.
Italy's Ministry of Agriculture, Food and Forestry (Ministero delle Politiche Agricole Alimentari e Forestali) enforces the National Fertilizer Registry, which mandates product registration and label compliance for all foliar products sold domestically. The EU Fertilizing Products Regulation extends these requirements by standardizing CE-marked fertilizing products across member states, creating dual compliance obligations for manufacturers. Italy's central bank and agricultural credit institutions shape demand indirectly through preferential lending terms for precision agriculture investments. Stakeholders must monitor how the EU Green Deal's nutrient management targets will tighten allowable cadmium and contaminant thresholds in phosphate-based inputs.
Market Dynamics
The EU Green Deal's nutrient management targets are compressing allowable contaminant thresholds in phosphate-based inputs, forcing Italian formulators to requalify product portfolios ahead of 2030 compliance deadlines.
Growth Catalysts
- EU Fertilizing Products Regulation:Standardized CE-marked products across member states create export-ready manufacturing scale for Italian producers serving adjacent Mediterranean markets.
- Specialty vineyard operators in Tuscany:Precision nutrient timing protocols during veraison and pre-harvest stages drive recurring micronutrient spray programs with higher application frequency than field crops.
- Marine biostimulant extraction:Organic-certified operations in Emilia-Romagna command premium pricing for algae-derived foliar formulations with documented stress-resistance properties.
Market Restraints
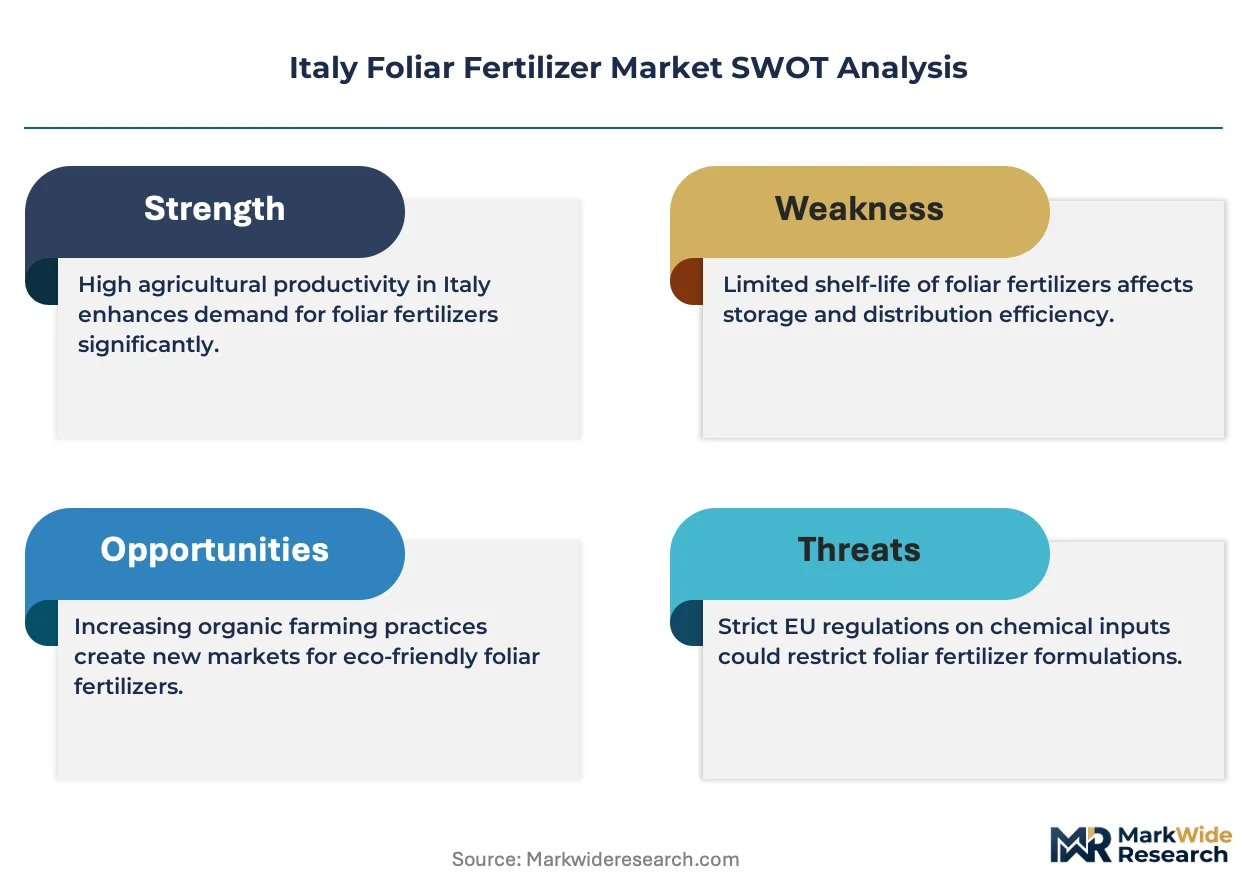
- Phosphate rock import dependency:Italy sources phosphate concentrate from Moroccan and Tunisian suppliers, exposing formulators to shipping cost volatility and geopolitical supply interruptions.
- National Fertilizer Registry compliance:The Ministry of Agriculture's tightened product registration timelines extend market entry delays for novel chelate formulations by 12-18 months.
- Soil-applied controlled-release fertilizers:These substitutes capture investment in permanent orchard systems where root-zone feeding reduces foliar dependency.
Strategic Opportunities
- Underpenetrated southern regions:Puglia and Sicily citrus cooperatives currently underutilize precision foliar programs relative to northern vegetable intensity, representing whitespace for technical sales deployment.
- Drone-based variable-rate application:NDVI-guided spot spraying in Po Valley tomato operations reduces product waste while enabling outcome-based service contracts between input suppliers and grower associations.
- EU Green Deal farm subsidies:Preferential credit terms for precision agriculture investments lower equipment barriers for mid-scale farms adopting sensor-integrated foliar systems.
Industry Challenges
- Formulation chemist scarcity:Italian technical universities produce limited graduates with dual competency in plant physiology and chelation chemistry, constraining R&D pipeline velocity for domestic manufacturers.
- Legacy sprayer incompatibility:Suspended concentrate formulations require nozzle upgrades and tank agitation systems that many Po Valley cooperatives have deferred replacing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Foliar Fertilizer Market |
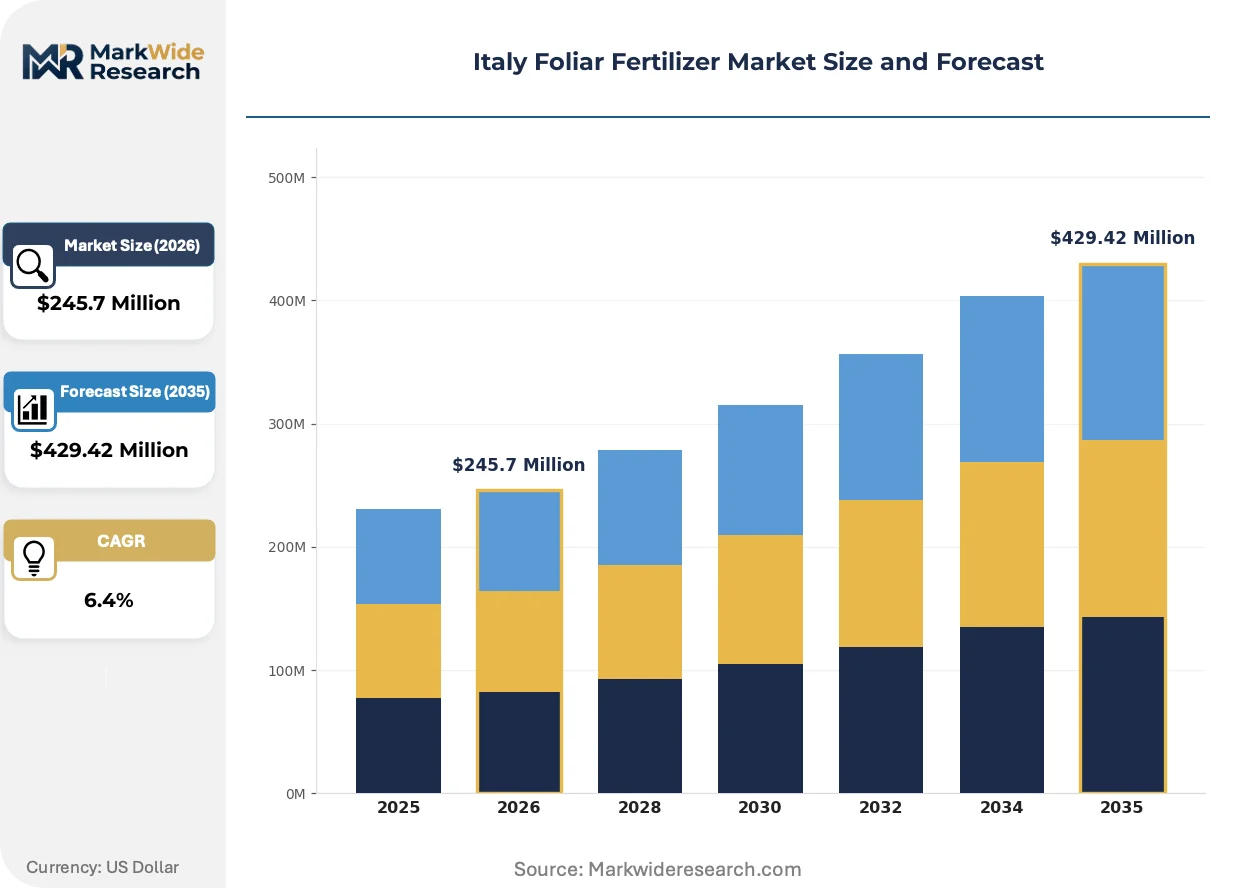
| Market Size in 2026 | $245.7 Million |
| Market Size in 2035 | $429.42 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granular, Powder, Suspended Crop Type: Cereals, Fruits, Vegetables, Oilseeds End Use: Agricultural, Horticultural, Organic, Conventional Distribution Channel: Online, Retail, Distributors, Wholesalers |
| Companies Covered | ICL, Timac Agro, Akzo Nobel N.V., PAVONI & C SPA, Arpa Speciali S.r.l, Sociedad Quimica Y Minera De Chile, Valagro, Trade Corporation International, Biolchim SPA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Foliar Fertilizer Market Strategic Shifts & Innovations
Digital agriculture tools are penetrating Italian foliar application workflows, compressing the gap between laboratory formulation and field execution precision.
Variable-rate spraying technology is automating nutrient deposition decisions based on real-time canopy sensors and GPS-mapped soil variability. Vineyard operators in Chianti Classico zones deploy these systems during critical phenological windows to reduce over-application in low-vigor blocks. The technology is automating what previously required agronomist field walks, compressing labor costs while improving uniformity metrics.
Italy's Ministry of Agriculture enforces cadmium threshold reductions under EU Green Deal implementation timelines. Domestic phosphate-based foliar manufacturers face reformulation mandates to qualify for continued National Fertilizer Registry listing. Specialty chelate producers with pre-qualified low-cadmium raw material sourcing capture accelerated registration pathways.
Cooperative procurement consolidation in Emilia-Romagna's vegetable belt is displacing distributor-centric purchasing. Large tomato and pepper grower associations negotiate direct supply contracts with ICL and Timac Agro, extracting volume pricing and technical advisory bundles previously fragmented across regional dealers. This concentration is most visible in the Po Valley corridor where input purchasing has shifted from thirty-plus independent retailers to five dominant cooperative buying groups.
Italy Foliar Fertilizer Market Segmentation
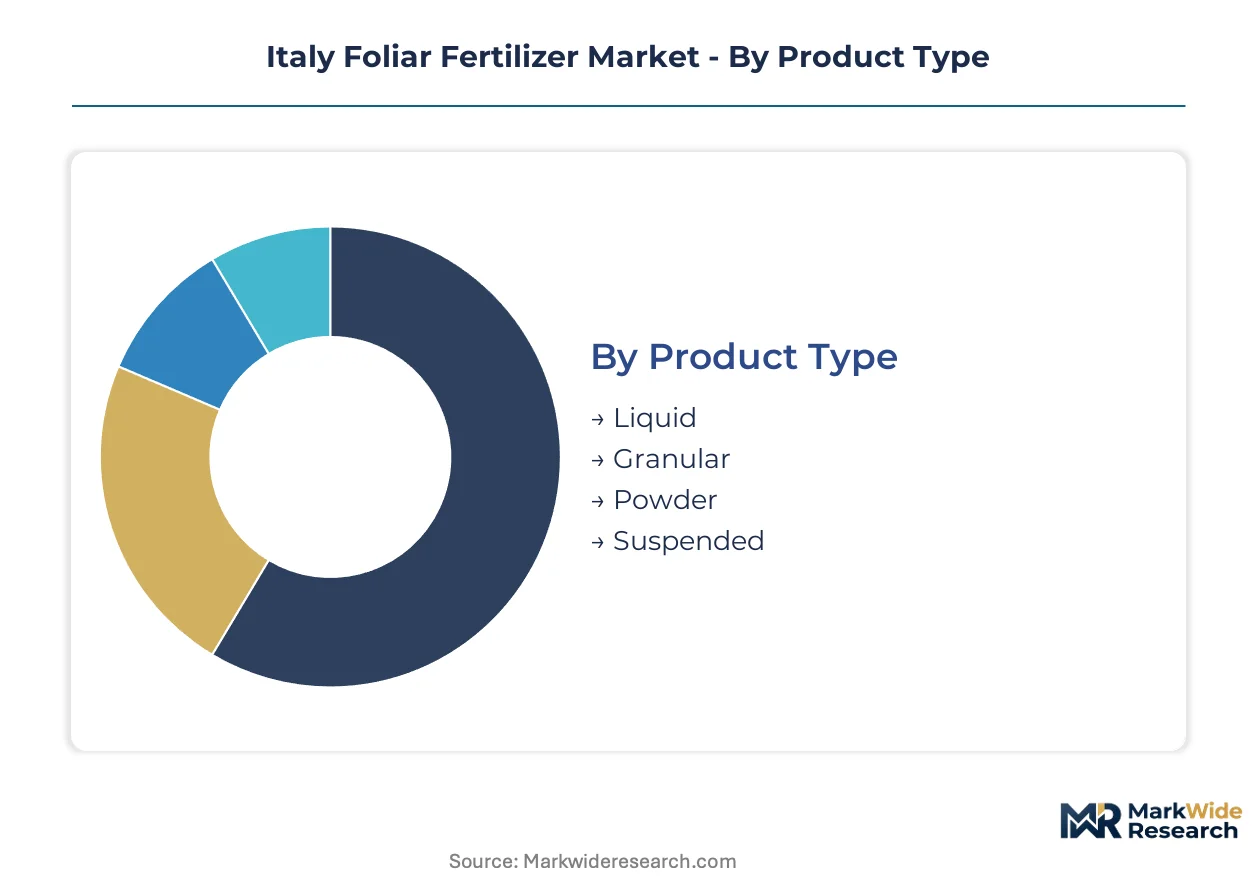
Italian foliar fertilizer procurement patterns diver sharply across product formulations and crop applications. Supply concentration in the Po Valley vegetable belt and Tuscany vineyard clusters creates distinct demand profiles that manufacturers must navigate through tailored distribution strategies.
Product Type:
Supply concentration among northern Italian formulators favors liquid and suspended concentrate production due to integrated phosphate processing capabilities.
- Liquid:Soluble nutrient solutions with optimized pH buffering and surfactant adjuvants for rapid stomatal absorption. Po Valley tomato cooperatives deploy these formulations through existing boom sprayer infrastructure, prioritizing uniform droplet distribution over per-liter cost.
- Suspended:Higher nutrient payload concentrates requiring nozzle upgrades and tank agitation systems. Emilia-Romagna vegetable associations are retrofitting equipment to capture application efficiency gains despite upfront capital requirements.
- Granular:Solid formulations for dissolution prior to foliar application, primarily serving smallholder vineyard operators in southern regions with limited mixing equipment.
- Powder:Dry concentrates for reconstitution, capturing residual demand from legacy procurement contracts in central Italian cereal districts.
Liquid formulations absorb the bulk of installed capacity; suspended concentrates are expanding most quickly.
Crop Type:
Margin capture potential varies dramatically across crop categories, with precision timing protocols in permanent plantings commanding premium pricing over field crop applications.
- Fruits:Vineyard and orchard operators in Chianti Classico and Prosecco zones prioritize micronutrient timing during veraison and pre-harvest windows. These recurring spray programs generate higher application frequency and technical advisory attachment than annual field crops.
- Vegetables:Intensive tomato, pepper, and leafy green production in the Po Valley corridor drives volume concentration. Cooperative procurement consolidation here has shifted purchasing from fragmented retailers to direct manufacturer negotiations.
- Cereals:Wheat and maize operations in the Padan Plain utilize foliar supplements primarily for corrective deficiency treatments rather than programmed nutrition protocols.
- Oilseeds:Sunflower and rapeseed cultivation in Apennine foothill zones represents emerging adoption territory with limited current penetration.
Vegetables absorb the bulk of installed capacity; fruits are climbing the fastest.
End Use:
Certification requirements under Italy's National Fertilizer Registry create divergent compliance pathways for organic versus conventional operations.
- Conventional:Standard agricultural applications utilizing synthetic chelates and mineral salts, dominating volume in Po Valley vegetable systems where yield maximization overrides input sourcing constraints.
- Organic:Certified operations in Emilia-Romagna and Tuscany command algae-derived and plant-extract formulations with documented stress-resistance properties, capturing premium pricing through marine biostimulant technology.
- Agricultural:Broadacre and permanent crop applications encompassing the majority of hectarage under foliar treatment protocols.
- Horticultural:Protected cultivation and nursery operations with specialized equipment requirements for greenhouse humidity management during application.
Conventional applications absorb the bulk of installed capacity; organic certification is gaining share fastest.
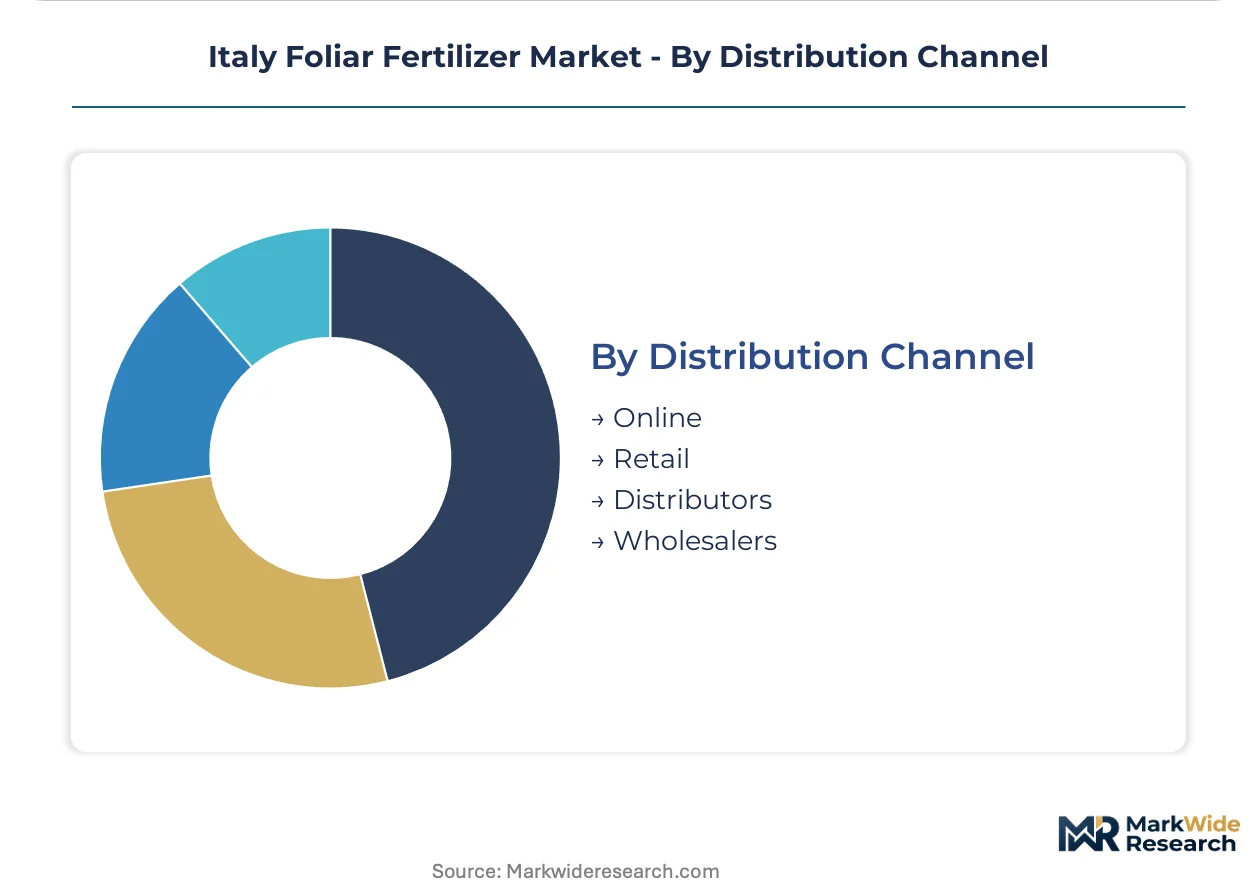
Distribution Channel:
Channel structure is concentrating as cooperative buying groups displace independent retailer networks across northern production zones.
- Distributors:Regional dealers with technical agronomist staff serving vineyard and vegetable operations through field-level prescription services. Timac Agro anchors this channel through deep cooperative relationships.
- Wholesalers:Volume aggregators supplying input retailers across central and southern regions with lower service intensity but broader geographic coverage.
- Retail:Independent farm supply stores facing displacement as Emilia-Romagna tomato associations negotiate direct manufacturer contracts.
- Online:Digital procurement platforms emerging for standardized product replenishment among tech-adopting mid-scale operations.
Distributors absorb the bulk of installed capacity; wholesaler consolidation is accelerating most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Po Valley corridor anchors Italian foliar fertilizer demand through intensive vegetable farming systems stretching from Turin to Ravenna. This concentration shapes regional procurement patterns and distribution infrastructure investments across northern agricultural zones.
Lombardy
Po Valley tomato and pepper cooperatives drive micronutrient spray programs with precision timing protocols. Italy's Ministry of Agriculture enforces National Fertilizer Registry compliance for all products entering this high-volume zone. Milan-based distributors maintain technical agronomist teams serving the densest concentration of protected cultivation in Europe.
Emilia-Romagna
Marine biostimulant extraction facilities supply organic-certified vegetable operations with algae-derived formulations. The EU Fertilizing Products Regulation mandates CE marking for cross-border product movement. Bologna and Modena host cooperative buying groups that have displaced independent retailers through direct manufacturer negotiations.
Tuscany
Specialty vineyard operators in Chianti Classico and Prosecco zones prioritize chelated micronutrient applications during veraison. EU Green Deal cadmium thresholds force phosphate-based input reformulation for continued registry eligibility. Florence and Siena clusters concentrate technical advisory services for precision nutrient timing in permanent plantings.
Veneto
Intensive orchard and vineyard systems generate recurring foliar application demand with higher frequency than annual field crops. Regional agricultural credit institutions shape equipment investment through preferential lending terms for precision agriculture. Verona and Vicenza formulators leverage proximity to Alpine water sources for high-purity solution production.
Puglia
Citrus cooperatives currently underutilize precision foliar programs relative to northern vegetable intensity. The National Fertilizer Registry extends compliance timelines for novel formulations entering this whitespace territory. Bari and Lecce agricultural associations represent expansion targets for technical sales deployment in underpenetrated southern markets.
Italy Foliar Fertilizer Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and certification tiers. The vendor base separates into integrated phosphate processors, specialty chelate formulators, and marine biostimulant extractors. Three strategic archetypes dominate: mining-integrated multinationals with captive raw material supply, regional specialists with deep cooperative relationships, and technology licensors with proprietary extraction patents. Competitive moves center on cooperative procurement consolidation and drone-based application service bundling.
Within the mining-integrated tier, ICL and Sociedad Quimica Y Minera De Chile represent archetypes of upstream-controlled supply chains. Timac Agro exemplifies the cooperative-anchored distribution model through embedded relationships with northern Italian vegetable associations. Valagro occupies a position among biostimulant specialists leveraging marine extraction technology for organic-certified market segments.
| Leading Market Players |
|---|
| ICL |
| Timac Agro |
| Akzo Nobel N.V. |
| PAVONI & C SPA |
| Arpa Speciali S.r.l |
| Sociedad Quimica Y Minera De Chile |
| Valagro |
| Trade Corporation International |
| Biolchim SPA |
| Others |
Cost & Logistics Intelligence
Formulation chemist scarcity in Italy's northern industrial zones widens the labor-cost gap between premium chelate developers and commodity blenders, compressing mid-tier margins while amplifying spreads between certified organic and conventional NPK sprays.
Pricing Analysis
Yield-linked pricing anchors premium tiers, with vineyard operators in Chianti Classico paying per-hectare outcome fees tied to veraison-stage micronutrient response rather than input volume. Three-tier pricing structure across premium, standard, and economy levels separates marine biostimulant formulations from synthetic chelates and basic NPK commodities. Price differentiation hinges on EU Green Deal cadmium certification and cooperative volume scale. Cost compression in commodity NPK blends is intensifying because Moroccan phosphate shipping volatility feeds raw material uncertainty. Vegetable cooperatives in the Po Valley corridor exhibit highest price sensitivity, while organic-certified Tuscan vineyards show least elasticity.
Supply Chain Analysis
CE marking qualification under the EU Fertilizing Products Regulation gates market entry for non-domestic suppliers, extending registration timelines for novel formulations. Manufacturing concentrates in Italy, with phosphate concentrate drawn from Morocco and Tunisia. Raw material inputs center on phosphoric acid, marine algae biomass, and synthetic chelating agents. Single-source vulnerability runs through Moroccan phosphate rock dependency, exposing formulators to Maghreb geopolitical interruptions. Distribution runs through cooperative buying groups that have displaced independent retailers across Emilia-Romagna and Lombardy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU Green Deal cadmium thresholds force sub-scale formulators to exit, unable to fund raw material requalification and extended National Fertilizer Registry timelines.
For Market Incumbents: Deepen backward integration into low-cadmium phosphate sourcing to secure accelerated registration pathways ahead of 2030 compliance deadlines. Anchor cooperative relationships through embedded technical agronomists serving Po Valley vegetable associations, defending against direct manufacturer contracting. Threat substitution from soil-applied controlled-release fertilizers in permanent orchards demands R&D investment in drone-compatible application protocols. For New Entrants and Emerging Players: Drone-based variable-rate spraying technology offers a technology-first wedge into underpenetrated Puglia citrus cooperatives where precision foliar programs remain nascent. Target Sicily almond and olive operations with sensor-integrated service bundles, bypassing legacy distributor networks entirely. Go-to-market angle: outcome-based contracts with grower associations that shift input risk from farmer to supplier. For Investors and Strategic Acquirers: Re-rating potential sits with marine biostimulant specialists given EU Green Deal farm subsidies accelerating organic certification adoption across Mediterranean markets. Long-term viability favors formulators with captive algae extraction capacity and pre-qualified low-cadmium supply chains. Signal to watch: cooperative procurement consolidation velocity in southern regions as a proxy for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Sourcing | Captive low-cadmium supply secures EU Green Deal compliance and accelerates National Fertilizer Registry approvals. |
| Drone-Based Application Service Bundling | NDVI-guided spot spraying in Po Valley tomato operations enables outcome-based contracts with grower associations. |
| Marine Biostimulant Extraction Scale-Up | Algae-derived formulations command premium pricing in organic-certified Emilia-Romagna vegetable operations. |
| Cooperative Technical Agronomist Embedding | Direct manufacturer relationships with Lombardy pepper associations displace independent retailer intermediation. |
| Southern Region Technical Sales Deployment | Puglia and Sicily citrus cooperatives represent whitespace for precision foliar program adoption. |
Research Approach
Independent corroboration across formulation chemists at Italian technical universities, procurement leads at Emilia-Romagna vegetable cooperatives, and regulatory affairs officers familiar with National Fertilizer Registry protocols underwrites the qualitative findings. Primary interviews with vineyard operators in Chianti Classico, distribution channel partners serving the Po Valley corridor, and R&D directors at phosphate processing facilities combined with secondary validation from EU Fertilizing Products Regulation filings, Italian Ministry of Agriculture registry databases, and customs trade data. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume estimates.
Historical reference periods spanning pre- and post-EU Green Deal announcement established baseline growth trajectories across the projection horizon. The analytical framework modeled product type, crop application, and certification tier segmentation dimensions throughout the forecast period. CAGRs derived from weighted average growth contributions across these segments, incorporating phosphate import dependency ratios and cooperative consolidation velocity as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt Moroccan phosphate export restrictions, accelerated EU cadmium threshold tightening, and breakthrough soil-applied fertilizer technologies displacing foliar dependency. Forecasts reflect documented assumptions on registration timeline stability and cooperative procurement behavior continuity. A model refresh is warranted upon material change in EU Green Deal implementation pacing or southern region cooperative formation rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
United States Fertilizers Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Brazil Fertilizers Market