
 Russia Specialty Fertilizer Market | 2026-2036
Russia Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Specialty Fertilizer Market Analytics
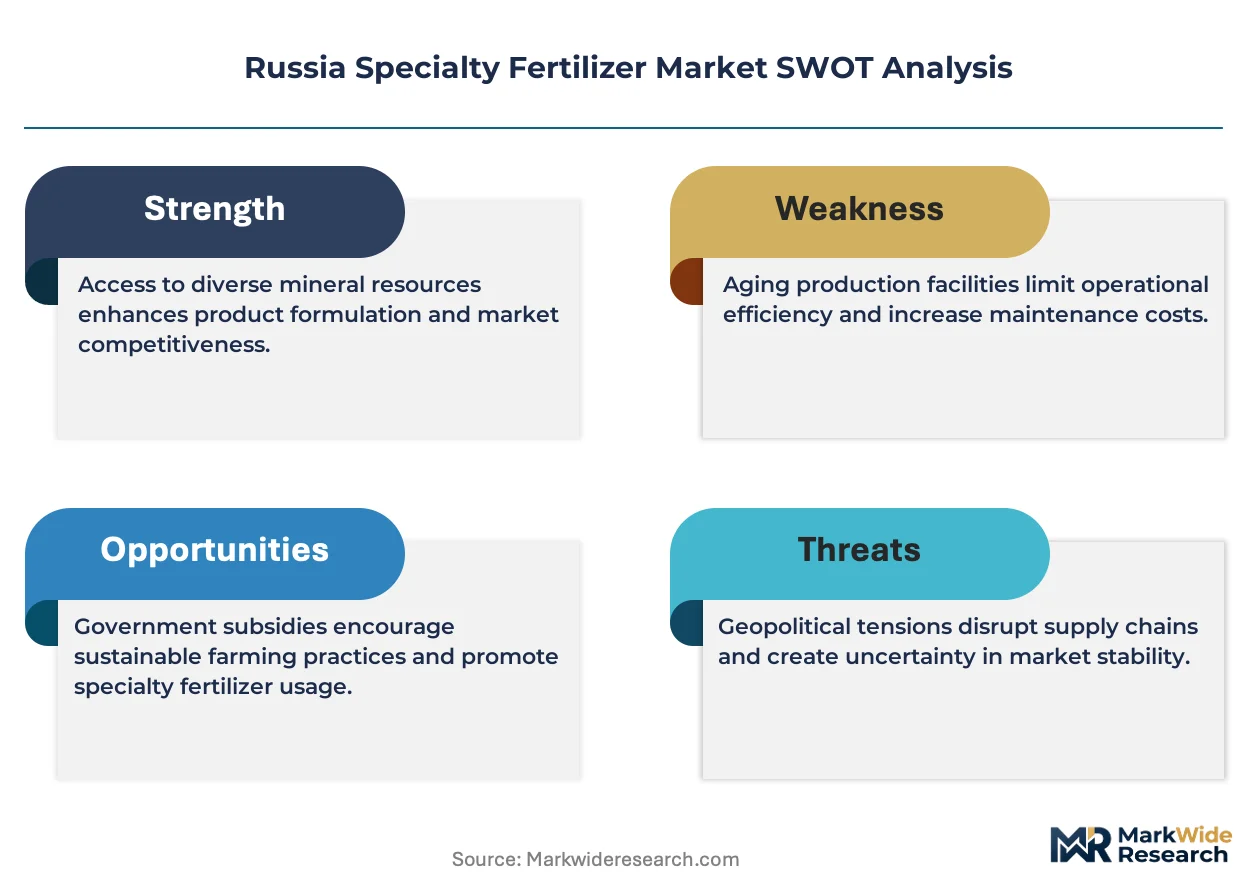
Russia's Volga-Ural manufacturing corridor is reconfiguring domestic nitrogen and potash downstream capabilities. EuroChem Group leverages captive phosphate rock and ammonia integration to sustain cost leadership in water-soluble NPK blends. PhosAgro Group anchors premium phosphate-based microfertilizer supply through its Cherepovets complex. Uralkali competes on muriate of potash purity grades tailored to export-competitive Russian wheat operations.
Specialty fertilizers are chemically enhanced or physically modified nutrient formulations delivering controlled release, targeted placement, or micronutrient enrichment beyond conventional NPK bulk products; they typically incorporate polymer coatings, chelated trace elements, or stabilizing inhibitors to synchronize nutrient availability with crop phenological stages. Controlled-release fertilizers command premium positioning due to their polymer-encapsulated nitrogen efficiency in Russia's short growing-season environments. Liquid formulations lead adoption in fertigation systems across Krasnodar Krai vegetable operations, while granular microfertilizers occupy established soil-application channels for cereals. Organic fertilizers remain nascent but gain traction where export-oriented producers seek residue-compliant certification for EU-bound oilseeds.
Russia's Ministry of Agriculture fertilizer subsidy framework, administered through regional agricultural departments, shapes procurement volumes and approved product registries for domestic manufacturers. BIS-equivalent GOST standards and the national technical regulation on fertilizer safety enforce labeling, heavy-metal limits, and efficacy claims verification. The EAEU's harmonized customs union technical regulations further condition cross-border formulation trade with Kazakhstan and Belarus. Stakeholders must monitor subsidy allocation shifts between commodity and enhanced-efficiency grades, as well as evolving GOST testing protocols for novel biostimulant-adjuvant combinations.
Market Dynamics
Russia's specialty fertilizer sector is being fundamentally restructured by the Ministry of Agriculture's subsidy reallocation toward enhanced-efficiency formulations, which forces manufacturers to reconfigure product portfolios while wheat cooperatives in the Black Earth region consolidate procurement power.
Growth Catalysts
- National Soil Fertility Program:This framework mandates enhanced-efficiency formulations for subsidized distribution, compelling regional agricultural departments to prioritize controlled-release and stabilized nitrogen products in procurement registries.
- Precision Agriculture Adoption:Large-scale wheat and barley producers in the Black Earth region are deploying variable-rate application technologies that require water-soluble NPK blends and micronutrient-enriched formulations.
- EAEU Harmonization:The customs union's technical regulations are conditioning cross-border formulation trade with Kazakhstan and Belarus, creating standardized product pathways for Russian manufacturers.
Market Restraints
- Captive Phosphate Rock Concentration:EuroChem Group's dominance over domestic phosphate rock and ammonia integration limits independent blender access to cost-competitive raw material inputs.
- Short Growing Season Constraints:Russia's compressed agricultural calendar reduces the effective application window for slow-release polymer coatings, compressing demand seasonality.
- GOST Testing Protocol Friction:BIS-equivalent standards and evolving efficacy verification requirements for novel biostimulant-adjuvant combinations delay product registration timelines.
Strategic Opportunities
- Krasnodar Krai Vegetable Operations:Fertigation system expansion in this southern region creates demand for liquid specialty formulations that synchronize with drip irrigation infrastructure.
- EU-Bound Oilseed Certification:Export-oriented producers seeking residue-compliant certification for oilseeds are adopting organic fertilizer adjuvants despite nascent domestic supply chains.
- Cherepovets Complex Downstream:PhosAgro Group's premium phosphate-based microfertilizer capacity offers white space for chelated trace element blends targeting high-value crop segments.
Industry Challenges
- Polymer Coating Technical Talent:Formulation chemists capable of engineering controlled-release nitrogen encapsulation for short-season environments remain concentrated at established research institutes.
- Legacy Soil-Application Channel Integration:Granular microfertilizer distributors face complexity embedding liquid fertigation products into established cereal procurement relationships.
- Heavy-Metal Compliance Verification:GOST-mandated testing for cadmium, lead, and arsenic limits in phosphate-based products requires capital-intensive laboratory infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Specialty Fertilizer Market |
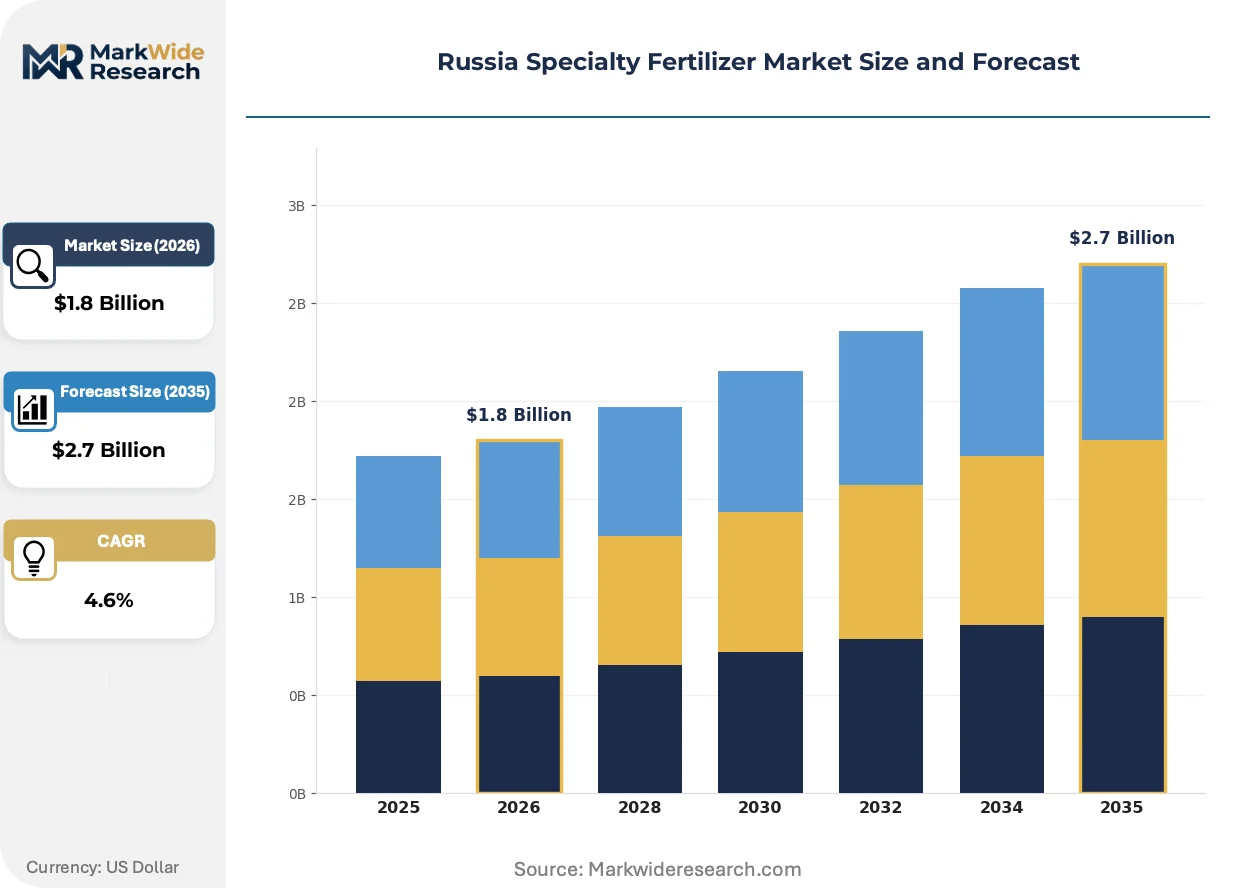
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfertilizers, NPK Fertilizers, Organic Fertilizers, Controlled-Release Fertilizers Formulation: Liquid, Granular, Powder, Soluble Application Method: Soil Application, Foliar Application, Fertigation, Seed Treatment Crop Type: Cereals, Vegetables, Fruits, Oilseeds |
| Companies Covered | KuibyshevAzot, Uralkali, EuroChem Group, Acron Group, Uralchem, PhosAgro Group, Biolchim SPA, MINUDOBRENIYA JSC, ICL Group Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Specialty Fertilizer Market Evolving Landscape
Digital soil mapping and variable-rate application technologies are compressing traditional fertilizer distribution hierarchies, while regulatory pressure on nutrient runoff accelerates formulation innovation across Russia's major agricultural clusters.
Polymer-encapsulated nitrogen formulations with biodegradable coating chemistries are virtualizing the traditional bulk-blend supply chain by enabling direct-to-farm customization. Large-scale cooperatives in the Central Federal District are adopting these technologies at accelerating rates. This virtualization is compressing regional distributor margins while shifting formulation control toward precision agriculture service providers.
Russia's national technical regulation on fertilizer safety is tightening heavy-metal limit enforcement and expanding efficacy claims verification requirements. The Ministry of Agriculture is administering these standards through regional agricultural departments with increasing rigor. Subsidy-eligible product registries are contracting as novel biostimulant-adjuvant combinations face extended GOST testing timelines.
Commercial farming cooperatives around Moscow are consolidating procurement volumes and demanding outcome-based nutrient management contracts from suppliers. Traditional distributor networks are being displaced by direct manufacturer-cooperative relationships with performance guarantees. This concentration is most visible in the Central Federal District where wheat and barley operations exceed ten thousand hectares.
Russia Specialty Fertilizer Market Segmentation
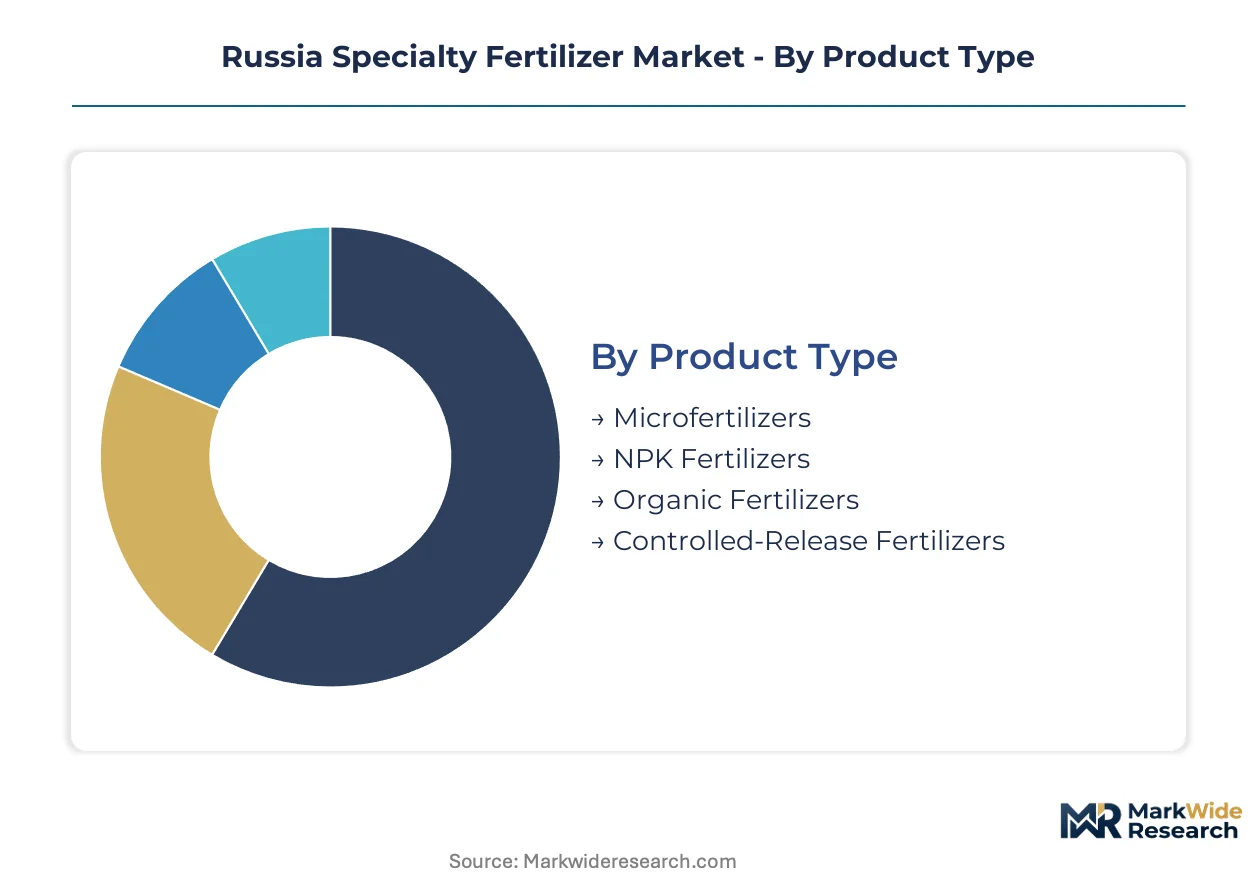
Specialty fertilizer procurement in Russia stratifies across product chemistry, physical form, delivery mechanism, and crop-specific nutrient protocols. Each segmentation dimension carries distinct regulatory, logistical, and agronomic constraints that shape manufacturer positioning and distributor economics.
Product Type:
Use-case spectrum spans micronutrient correction, complete macronutrient delivery, organic certification compliance, and precision nitrogen management.
- Controlled-Release Fertilizers:Polymer-encapsulated nitrogen formulations synchronize nutrient availability with wheat and barley phenological stages in the Black Earth region. The Ministry of Agriculture's subsidy reallocation toward enhanced-efficiency formulations concentrates procurement through regional agricultural department registries.
- Microfertilizers:Chelated trace element blends address zinc, boron, and manganese deficiencies in high-value vegetable operations. PhosAgro Group's Cherepovets complex anchors domestic supply for premium phosphate-based variants targeting export-competitive oilseed producers.
- NPK Fertilizers:Water-soluble complete nutrient formulations serve variable-rate application systems deployed by large-scale cooperatives.
- Organic Fertilizers:Residue-compliant biostimulant-adjuvant combinations gain traction where EU-bound oilseed certification requirements mandate reduced synthetic inputs.
Established volume favors NPK Fertilizers; emerging adoption favors Controlled-Release Fertilizers.
Formulation:
Physical state determines equipment compatibility, storage economics, and integration with existing distribution infrastructure.
- Liquid:Fertigation-compatible concentrates integrate with drip irrigation systems across Krasnodar Krai vegetable operations. The format's direct-injection compatibility accelerates adoption in precision agriculture service provider networks.
- Granular:Slow-release coated prills dominate soil-application channels for cereals, leveraging established blender infrastructure and mechanical spreader compatibility.
- Soluble:Rapid-dissolution crystalline products serve foliar spray and hydroponic systems requiring immediate nutrient availability.
- Powder:Fine-particulate formulations occupy niche seed treatment and greenhouse substrate amendment applications.
Granular formulations retain procurement dominance; liquid formulations expand most quickly in southern agricultural clusters.
Application Method:
Delivery mechanism selection correlates with farm scale, equipment sophistication, and crop-specific nutrient timing requirements.
- Fertigation:Drip-irrigation-synchronized liquid delivery enables precise nutrient dosing in Krasnodar Krai vegetable operations. The method's water-use efficiency aligns with regional water scarcity constraints and export quality requirements.
- Soil Application:Broadcast and banded granular placement remains standard for wheat and barley in the Central Federal District, supported by conventional spreader fleets and cooperative procurement patterns.
- Foliar Application:Micronutrient spray protocols address acute deficiency correction during critical growth stages in high-value fruit operations.
- Seed Treatment:Microfertilizer coatings provide early-stage phosphorus and zinc availability for oilseed establishment in variable Black Earth conditions.
Soil Application commands procurement volume; Fertigation gains share fastest in irrigated southern districts.
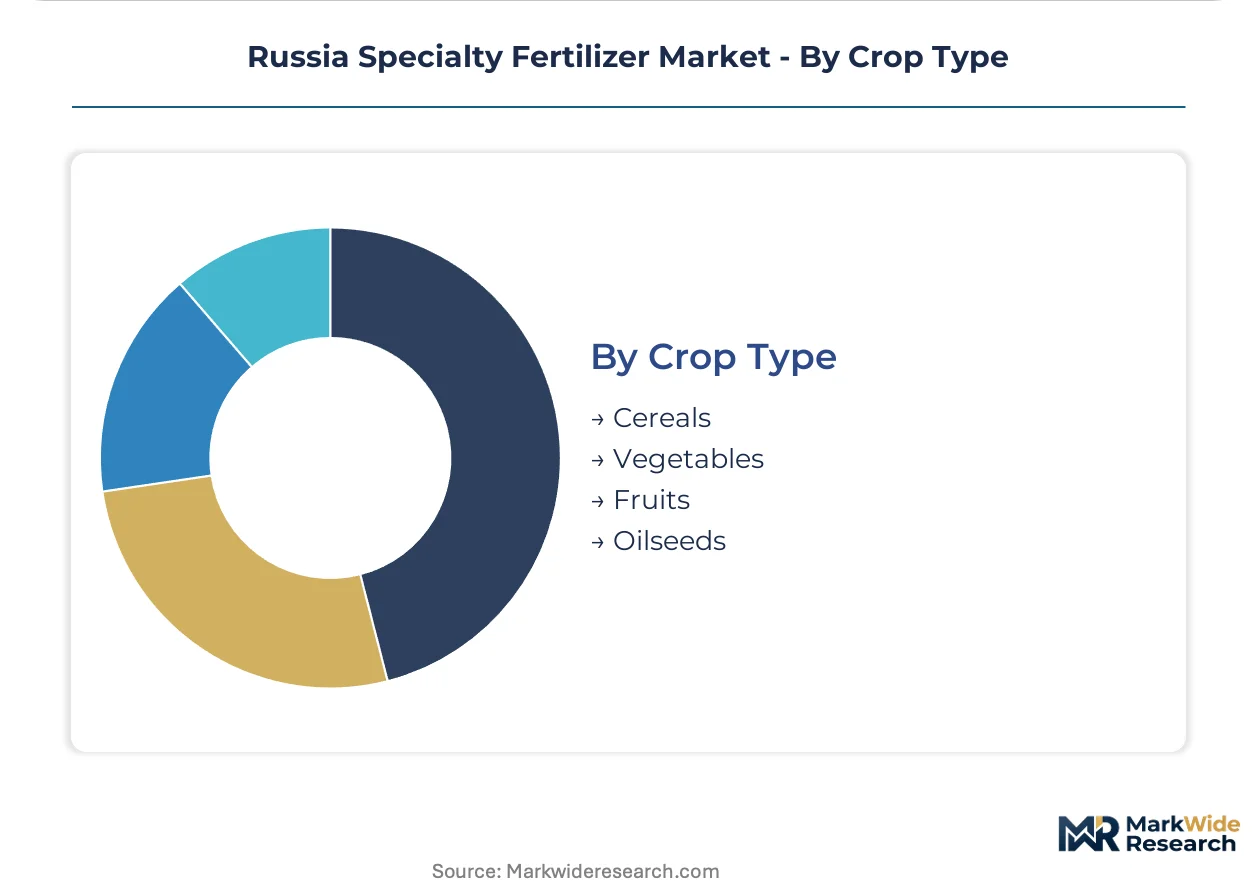
Crop Type:
Nutrient intensity and formulation sophistication vary sharply between commodity grain systems and high-value horticultural operations.
- Cereals:Wheat and barley operations in the Black Earth region drive controlled-release nitrogen and water-soluble NPK demand. Large-scale cooperatives consolidate procurement through outcome-based nutrient management contracts.
- Vegetables:Krasnodar Krai greenhouse and open-field operations require liquid fertigation formulations with precise micronutrient ratios for export quality compliance.
- Oilseeds:Sunflower and rapeseed producers adopt organic fertilizer adjuvants where EU residue limits constrain synthetic input use.
- Fruits:Southern orchard operations deploy foliar microfertilizer programs targeting premium domestic and export market grades.
Cereals anchor procurement scale; Vegetables drive formulation premiumization and technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's Ministry of Agriculture anchors demand concentration through its national soil fertility program, which mandates enhanced-efficiency formulations for subsidized distribution across federal districts. Procurement gravity centers on the Central Federal District and Black Earth region, where large-scale cooperatives consolidate volumes.
Central Federal District
Commercial farming cooperatives around Moscow exceed ten thousand hectares and deploy variable-rate application technologies requiring water-soluble NPK blends. The Ministry of Agriculture administers subsidy registries through regional agricultural departments with increasing rigor. Direct manufacturer-cooperative relationships are displacing traditional distributor networks in this cluster.
Black Earth Region
Large-scale wheat and barley producers drive controlled-release nitrogen demand to synchronize nutrient availability with compressed growing seasons. The national soil fertility program prioritizes this region for enhanced-efficiency formulation subsidies. Precision agriculture service providers embed polymer-encapsulated products into outcome-based nutrient management contracts.
Krasnodar Krai
Vegetable operations across this southern territory expand drip irrigation infrastructure and adopt liquid fertigation-compatible concentrates. Water scarcity constraints and export quality requirements accelerate formulation premiumization. Greenhouse and open-field producers demand precise micronutrient ratios for EU-bound shipments.
Volga Federal District
The Volga-Ural manufacturing corridor reconfigures domestic nitrogen and potash downstream capabilities to serve subsidized procurement channels. Regional agricultural departments enforce GOST standards for heavy-metal limits and efficacy claims verification. Captive phosphate rock and ammonia integration sustains cost leadership for local blenders.
Northwestern Federal District
PhosAgro Group's Cherepovets complex anchors premium phosphate-based microfertilizer supply for high-value crop segments. The EAEU's harmonized customs union technical regulations condition cross-border formulation trade with Belarus. Chelated trace element blends target export-competitive oilseed producers seeking residue-compliant certification.
Russia Specialty Fertilizer Market Competitive Landscape
Capability concentration sits with integrated resource holders; scale advantage sits with subsidized procurement registries. The sector structures around three tiers: captive mineral processors with backward integration into phosphate rock and potash, regional blenders dependent on traded ammonia and sulfur inputs, and precision agriculture service providers virtualizing distribution through direct-to-farm customization. Dominant competitive moves include portfolio reconfiguration toward enhanced-efficiency grades and direct relationship-building with consolidating cooperatives.
Among integrated mineral processors, EuroChem Group, Uralkali, and PhosAgro Group occupy positions that exemplify divergent resource-based strategies. EuroChem Group represents captive phosphate rock and ammonia integration sustaining cost leadership in water-soluble NPK blends. Uralkali anchors muriate of potash purity grades tailored to export-competitive wheat operations. PhosAgro Group sits within premium phosphate-based microfertilizer supply through its Cherepovets complex, targeting chelated trace element formulations for high-value segments.
| Leading Market Players |
|---|
| KuibyshevAzot |
| Uralkali |
| EuroChem Group |
| Acron Group |
| Uralchem |
| PhosAgro Group |
| Biolchim SPA |
| MINUDOBRENIYA JSC |
| ICL Group Ltd |
| Others |
Value Network & Pricing Analysis
Single-source dependency on EuroChem Group's captive phosphate rock and ammonia integration determines both pricing tier spreads and supply chain shape across Russia's specialty fertilizer sector. The Ministry of Agriculture's subsidy reallocation toward enhanced-efficiency formulations compresses margins for non-integrated blenders while concentrating procurement power among subsidized registry participants.
Pricing Analysis
Geographic price spreads widen significantly between the Central Federal District and southern agricultural clusters, with Moscow-proximate cooperatives absorbing premium positioning for water-soluble NPK blends. Pricing stratifies across premium controlled-release formulations, standard granular microfertilizers, and economy-grade bulk NPK products. Cost compression in standard tiers intensifies because regional agricultural departments enforce increasingly rigid GOST efficacy verification. Large-scale wheat cooperatives in the Black Earth region exhibit lowest price sensitivity due to outcome-based contract structures, while independent vegetable operators in Krasnodar Krai face acute margin pressure from irrigation infrastructure costs.
Supply Chain Analysis
Extended payment terms from regional agricultural departments strain working capital for non-integrated blenders, forcing supply-chain finance facility dependence. Manufacturing concentrates in Russia's Volga-Ural corridor, with captive mineral processing anchored at Cherepovets and Kovdor, while Kazakhstan and Belarus provide cross-border ammonia and sulfur inputs. Raw material dependencies rest on phosphate rock from Kovdor, potash from Solikamsk, and imported sulfur for acidulation. Single-source vulnerability permeates polymer coating chemistry supply, where formulation expertise concentrates at legacy research institutes. Distribution runs through regional agricultural department procurement registries that consolidate cooperative volumes into direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's specialty fertilizer market sits at a technology-driven inflection where precision agriculture adoption and subsidy reallocation are restructuring competitive boundaries. The Ministry of Agriculture's enhanced-efficiency mandate creates asymmetric opportunity for formulation capabilities that synchronize with variable-rate application infrastructure.
For Market Incumbents: Harden subsidy registry positioning by accelerating controlled-release nitrogen registration through GOST efficacy verification pipelines. Prioritize backward integration into biodegradable polymer coating chemistry to reduce dependence on legacy research institute licensing. Defensive consolidation should target precision agriculture service providers in the Central Federal District to preempt direct-to-farm virtualization by competitors. For New Entrants and Emerging Players: Krasnodar Krai's fertigation infrastructure expansion represents the most penetrable white space for liquid formulation specialists lacking granular distribution legacy. Organic fertilizer adjuvants for EU-bound oilseed certification offer second-entry positioning where domestic supply chains remain nascent. A cooperative-partnership go-to-market model bypasses entrenched distributor relationships in cereal-dominated regions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision agriculture technology integrators over commodity blenders. Acquisition target archetypes include regional blenders with GOST-registered enhanced-efficiency portfolios and precision agriculture service providers with established cooperative relationships. The signal to watch is Ministry of Agriculture testing protocol acceleration for novel biostimulant-adjuvant combinations, which would validate premium formulation R&D bets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Coating Chemistry | Captive supply of biodegradable encapsulation materials reduces licensing costs from Russian Academy of Agricultural Sciences institutes. |
| Precision Agriculture Service Provider Acquisition | Direct cooperative relationships in the Central Federal District displace traditional distributor intermediaries. |
| GOST Registration Acceleration for Biostimulant Combinations | Early-mover advantage in subsidy-eligible product registries as testing protocols evolve. |
| Krasnodar Krai Fertigation Infrastructure Partnership | Liquid formulation volume anchors through drip irrigation system deployment in vegetable operations. |
| EU Certification-Compliant Organic Adjuvant Development | Residue-compliant positioning captures oilseed export premiums to European markets. |
Research Methodology
Initial hypotheses were tested against primary input from agronomic research directors at Black Earth region cooperatives, procurement leads at Central Federal District farming associations, technical R&D managers at integrated mineral processors, and regional agricultural department subsidy administrators, then refined against secondary validation. Bottom-up and top-down triangulation combined customs and trade data from EAEU member states, Ministry of Agriculture subsidy registry disclosures, GOST standard documentation, and PhosAgro Group and EuroChem Group operational filings. The analysis cross-referenced fertilizer application rate surveys with precision agriculture technology deployment metrics across federal districts.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product chemistry tiers, physical formulation states, application method infrastructure requirements, and crop-specific nutrient protocols. CAGRs were derived from volume trajectory analysis calibrated to subsidy allocation shifts and cooperative consolidation patterns. Industry-specific forecast inputs incorporated polymer coating technology adoption curves and GOST testing protocol timeline assumptions for novel formulation categories.
Macroeconomic conditions sit as an overlay; deviation in ruble-denominated input costs, EAEU cross-border tariff structures, or Ministry of Agriculture subsidy budget allocations would shift the trajectory. Forecasts reflect assumptions about precision agriculture technology penetration rates and GOST regulatory evolution that continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
China Fertilizers Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market
Fertilizers
India Fertilizers Market