
 Planting and Fertilizing Machinery Market | 2026-2036
Planting and Fertilizing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Planting and Fertilizing Machinery Market Analytics
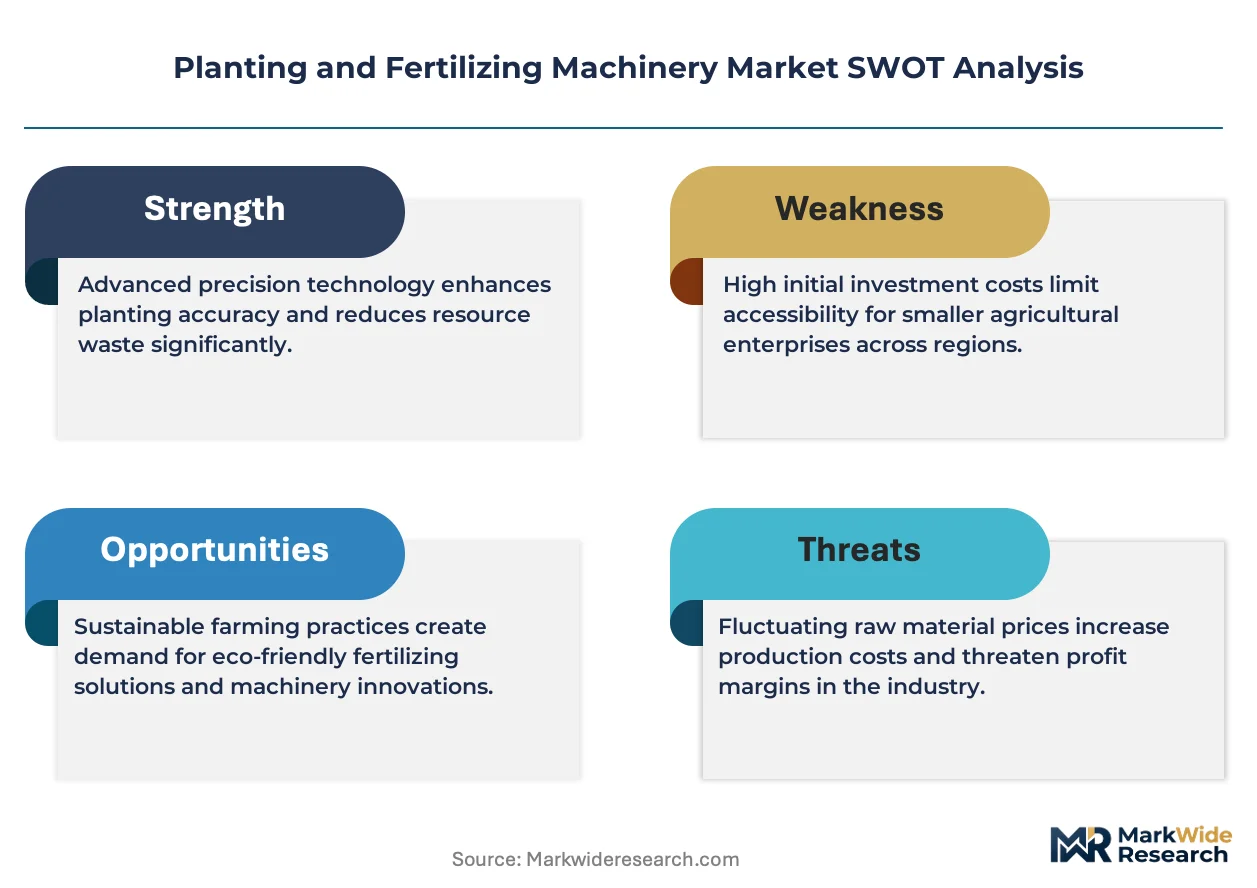
Precision agriculture integration with GPS-guided auto-steer and variable-rate application is tilting the technology stack toward sensor-rich, software-defined machines. Deere & Company leverages its integrated operations platform to lock in fleet renewal cycles among enterprise farms. AGCO Corporation anchors its competitive position through Fendt-branded high-horsepower planters with independent row control. Kubota Corporation specializes in compact precision seeders tailored to Asian paddy-field geometries and European vegetable operations.
Planting and fertilizing machinery encompasses mechanized equipment designed to deposit seeds, seedlings, or nutrient formulations at controlled depths, spacing, and rates, typically operating at working widths from 3 to 36 meters and row spacings calibrated to crop species. These machines serve the primary commercial purpose of establishing crop stands while optimizing input placement to maximize yield potential and minimize waste. Pneumatic seed metering dominates high-value row-crop applications where singulation accuracy directly affects germination uniformity and final yield. Mechanical systems retain cost advantages in small-grain and forage operations across developing agricultural economies. Electric drive technology is capturing margin pools in premium planter segments where individual row control enables real-time population adjustments.
The EPA regulates off-road diesel emissions under Tier 4 Final standards, compelling engine redesigns and after-treatment integration that add cost but bar non-compliant imports from US market entry. ISO 7256 and OECD Codes govern seeding performance testing protocols, creating de facto technical barriers for equipment lacking certified laboratory validation. The EU Machinery Directive and CE marking requirements enforce safety interlocks and electromagnetic compatibility standards that shape product development priorities for European-bound manufacturers. Stakeholders must monitor how emerging battery-electric powertrains and autonomous field operation protocols reshape capital allocation between incremental fleet upgrades and transformative platform bets.
Market Dynamics
Electric drive row units are compressing the technology adoption curve across precision planting fleets, forcing simultaneous investment in sensor hardware and software subscription architectures that lock in multi-year fleet renewal commitments.
Growth Catalysts
- Variable-rate application mandates:The EU F-Gas Regulation is accelerating replacement of hydraulic drive systems with electric alternatives in European-bound equipment, creating compliance-driven upgrade cycles among German and French farm cooperatives.
- Soybean yield optimization:Large-scale commercial growers in Brazil are expanding precision planting fleets to maximize per-hectare productivity, concentrating demand for 24-row and 36-meter working-width planters with pneumatic seed metering.
- Consolidation-driven replacement:Farm consolidation across the North American Corn Belt is shortening equipment replacement cycles as enterprise operations standardize on unified fleet management platforms.
Market Restraints
- After-treatment cost burden:EPA Tier 4 Final diesel emissions standards have added substantial cost to engine redesigns, pricing smaller manufacturers out of US market entry and compressing margin pools for mid-tier equipment.
- Steel and aluminum input volatility:Fluctuating commodity prices for frame materials and precision-machined components are destabilizing production cost forecasts for pneumatic metering systems and toolbar assemblies.
- Certification bottlenecks:ISO 7256 and OECD seeding performance testing protocols create de facto technical barriers for equipment lacking certified laboratory validation, particularly affecting entrants from developing manufacturing bases.
Strategic Opportunities
- Autonomous field protocols:Integration of GPS-guided auto-steer with real-time kinematic correction is creating white space for fully autonomous planting operations in Australian broadacre wheat systems and Canadian prairie grain farms.
- Battery-electric powertrains:Emerging battery-electric architectures for sub-150 horsepower tractors are enabling new planter tow-vehicle configurations that eliminate hydraulic complexity and reduce maintenance intervals.
- Asian paddy-field specialization:Compact precision seeders calibrated to wet-field geometries represent underpenetrated demand in Southeast Asian rice production systems, particularly Vietnam and Thailand transplanting operations.
Industry Challenges
- Software-hardware integration complexity:Legacy mechanical planters require extensive retrofitting to accommodate ISOBUS-compatible control systems and variable-rate prescription maps, extending deployment timelines and service technician training requirements.
- Electromagnetic compatibility certification:CE marking requirements for safety interlocks and electromagnetic immunity testing are lengthening product development cycles for European market entry, particularly for sensor-dense electric drive units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Planting and Fertilizing Machinery Market |
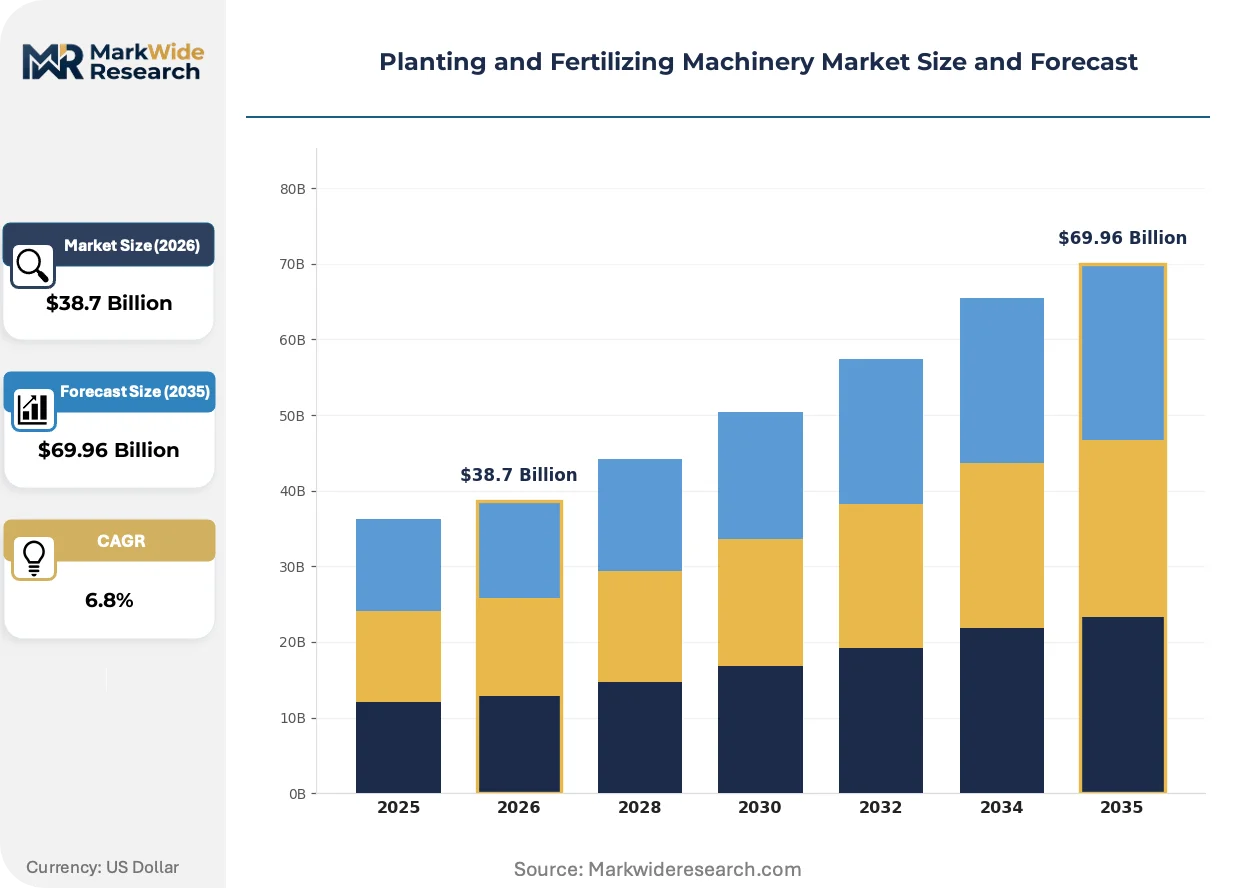
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeders, Planters, Fertilizer Spreaders, Transplanters Technology: Mechanical, Pneumatic, Hydraulic, Electric End User: Farmers, Agricultural Contractors, Commercial Growers, Agricultural Cooperatives Application: Crops, Vegetables, Flowers, Grass |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Kubota Corporation, Mahindra & Mahindra, KUHN Group, CLAAS, Yanmar Holdings, HORSCH Maschinen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Planting and Fertilizing Machinery Market Evolving Landscape
Precision agriculture is converging three distinct technology streams—satellite positioning, real-time soil sensing, and cloud-based prescription mapping—into unified planting and fertilizing platforms that redefine equipment value propositions.
Electric drive technology is hybridizing pneumatic and mechanical seed metering architectures into unified row-unit designs that enable individual population control. Large enterprise farms in the US Corn Belt and Brazilian Cerrado are adopting these systems at accelerated replacement cycles. This convergence is compressing the addressable market for pure mechanical metering while expanding service revenue pools from software-defined population management.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in mobile air conditioning and auxiliary systems, indirectly pressuring hydraulic component suppliers to accelerate electric alternatives. European manufacturers are redesigning planter lift and fold systems around electromechanical actuators to eliminate refrigerant-dependent hydraulics. Premium Fendt-branded equipment in Germany and high-horsepower units bound for French cooperatives are experiencing the most acute compliance-driven redesign cycles.
After-sales service unbundling is fragmenting traditional dealer revenue models as farm enterprises negotiate direct software subscriptions with manufacturers. Equipment dealers in Iowa and Illinois are losing exclusive access to precision agriculture support contracts as Deere and AGCO build direct customer relationships. This disintermediation is most visible in North American row-crop operations where fleet telematics enable remote diagnostics and predictive maintenance scheduling without dealer intermediation.
Planting and Fertilizing Machinery Market Segmentation
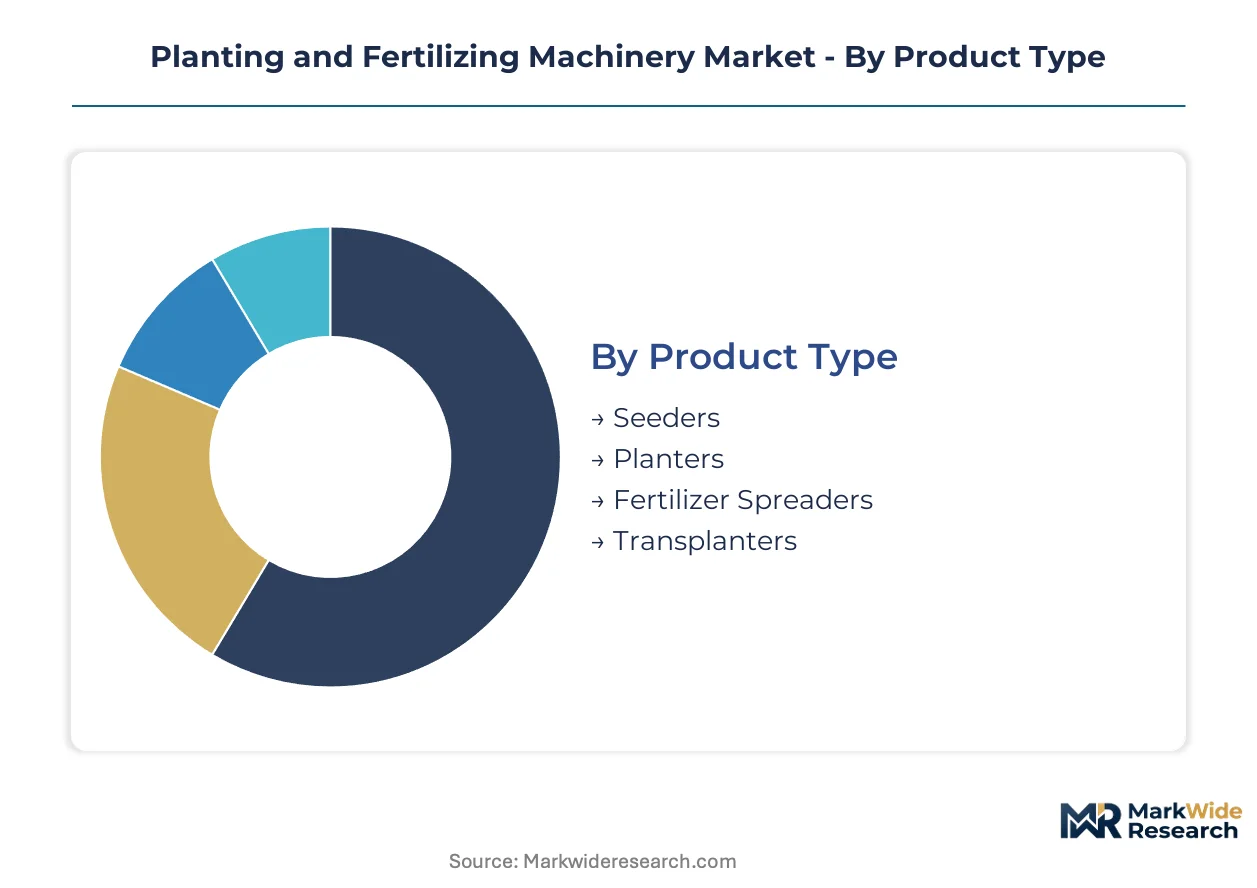
Segmentation in planting and fertilizing machinery reveals how technology tiers, operational scale, and crop-specific requirements fragment equipment specifications across divergent buyer budgets. Understanding these divisions exposes where margin pools concentrate and where retrofit opportunities persist for legacy fleet operators.
Product Type:
Equipment categories align with crop establishment methods, from broadcast seeding through precision singulation to transplanting operations.
- Seeders:Mechanical and pneumatic mechanisms distribute small grains and forage crops across working widths from 3 to 12 meters. Demand concentrates in Australian wheat belts and Canadian prairie provinces where broadacre operations prioritize throughput over individual seed placement.
- Planters:Precision row units with pneumatic metering achieve singulation accuracy critical for maize and soybean germination uniformity. Brazilian Cerrado commercial growers and US Corn Belt enterprises drive specification toward 24-row and 36-meter configurations with GPS-guided auto-steer integration.
- Fertilizer Spreaders:Broadcast and variable-rate applicators distribute granular or liquid nutrient formulations.
- Transplanters:Automated seedling placement systems serve vegetable and rice paddy operations in Vietnam and Thailand transplanting workflows.
Planters hold installed capacity. Transplanters is rotating up the share rankings.
Technology:
Drive architectures differentiate equipment cost tiers and determine compatibility with precision agriculture platforms.
- Pneumatic:Vacuum or positive-pressure seed metering dominates high-value row-crop applications where population control directly affects yield potential. German and French farm cooperatives are accelerating replacement under EU F-Gas Regulation pressure to eliminate hydraulic dependencies.
- Electric:Individual row-unit motors enable real-time population adjustments and eliminate hydraulic complexity. North American enterprise farms are adopting these systems fastest, accepting multi-year software subscription commitments for prescription mapping integration.
- Mechanical:Fluted-wheel and finger-pickup mechanisms retain cost advantages in small-grain operations across developing agricultural economies.
- Hydraulic:Traditional lift, fold, and drive systems face phase-out pressure from emissions regulations.
Pneumatic systems command the largest installed base. Electric drive configurations are climbing the fastest among premium equipment specifications.
End User:
Customer type determines fleet scale, financing capacity, and sensitivity to total cost of ownership versus upfront capital expenditure.
- Commercial Growers:Large-scale operations in Brazil and the US Midwest standardize on unified fleet management platforms and negotiate direct manufacturer relationships for precision agriculture subscriptions. Their replacement cycles compress as consolidation accelerates.
- Agricultural Cooperatives:German and French shared-equipment pools balance member access costs with compliance requirements under EU Machinery Directive and CE marking standards.
- Farmers:Owner-operators in developing markets prioritize mechanical reliability and parts availability over technology integration.
- Agricultural Contractors:Custom service providers require rapid field efficiency and transportability between dispersed customer operations.
Commercial growers anchor equipment volume. Agricultural cooperatives are expanding their share of precision technology procurement.
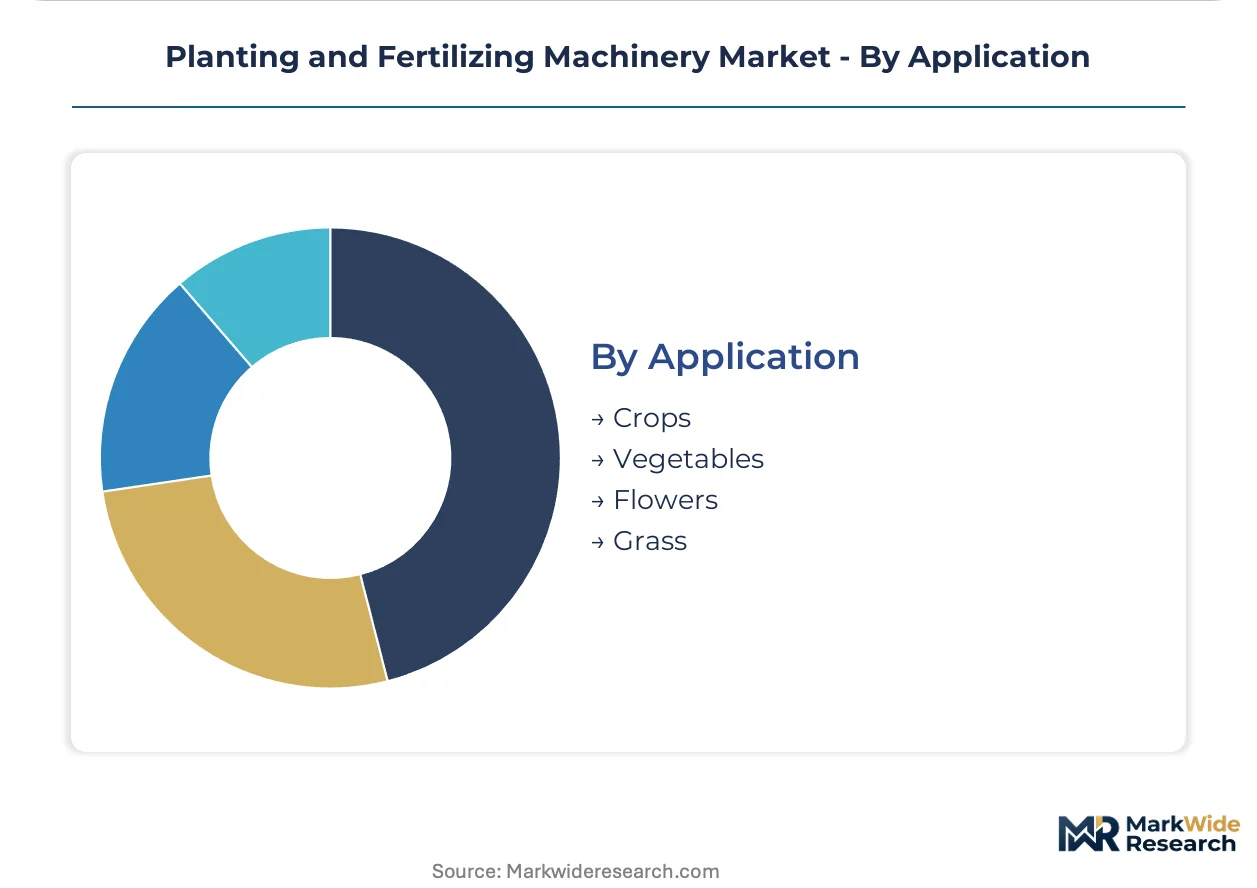
Application:
Crop biology dictates row spacing, depth control, and timing requirements that shape equipment specification.
- Crops:Maize, soybean, wheat, and rice establishment drives the largest equipment volumes, with precision requirements varying from broadcast small-grain seeding to singulated row-crop planting.
- Vegetables:Specialized seeders and transplanters calibrated to narrow row spacings and shallow planting depths serve European market gardening and Asian protected cultivation systems.
- Flowers:High-value ornamental production requires gentle handling mechanisms and precise depth control for delicate seed structures.
- Grass:Pasture renovation and turf establishment utilize broadcast seeders with minimal soil disturbance features.
Crop applications dominate installed capacity. Vegetable specialization is gaining share fastest as protected cultivation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise-scale commercial growers in Brazil, the United States, and Germany concentrate procurement volume for precision planting fleets, while regulatory pressure across multiple jurisdictions accelerates equipment replacement cycles toward electric-drive architectures.
Brazil
Large-scale soybean producers in the Cerrado and Mato Grosso regions drive specification toward 36-meter working-width planters with pneumatic seed metering. ANVISA oversees agricultural chemical application standards that influence fertilizing equipment calibration requirements. São Paulo-based equipment pools serve as distribution nodes for precision technology adoption across southern agricultural belts.
United States
Farm consolidation across Iowa, Illinois, and Indiana compresses replacement cycles as enterprise operations standardize on unified fleet management platforms. EPA Tier 4 Final emissions standards bar non-compliant engine imports from market entry. The Corn Belt manufacturing corridor stretching through Moline, Illinois, anchors domestic production capacity for high-horsepower row-crop equipment.
Germany
Farm cooperatives in Bavaria and Lower Saxony balance member access costs with EU F-Gas Regulation compliance mandates for electric drive alternatives. CE marking requirements under the EU Machinery Directive enforce safety interlocks and electromagnetic compatibility testing. Stuttgart-area industrial clusters concentrate precision component fabrication for European-bound planter specifications.
China
State-backed agricultural modernization programs in Heilongjiang and Henan provinces subsidize mechanization upgrades for wheat and maize establishment. MIIT sets equipment performance standards through GB certification protocols that shape domestic manufacturer design priorities. The Yangtze River Delta manufacturing base supplies compact seeders calibrated to regional paddy-field geometries.
Australia
Broadacre wheat operations in New South Wales and Western Australia adopt GPS-guided auto-steer systems for autonomous planting protocols across expansive dryland holdings. The national Department of Agriculture, Fisheries and Forestry administers import quarantine regulations affecting equipment transit timelines. Perth-based service networks support rapid field efficiency requirements for dispersed grain production systems.
Planting and Fertilizing Machinery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered technology segments, creating a consolidated structure where integrated operations platforms lock in multi-year fleet commitments. Premium equipment manufacturers anchor high-margin positions through software-defined population management, while mid-tier fabricators compete on mechanical reliability and parts availability. Three archetypes dominate: full-line integrators with subscription-based precision platforms, regional specialists in compact geometries, and component suppliers capturing margin pools from electric drive retrofits. Competitive moves concentrate on strategic partnerships for sensor hardware integration and geographic expansion into underpenetrated Asian rice systems.
Within the integrated operations tier, Deere & Company and AGCO Corporation exemplify platform-centric positioning through direct customer relationships that disintermediate traditional dealer networks. Kubota Corporation occupies a distinct specialization vector for compact precision seeders. Among German fabricators, HORSCH Maschinen GmbH and CLAAS represent precision-focused engineering origins. Japanese manufacturers including Yanmar Holdings and Kubota Corporation anchor Asian market development. The competitive map reveals concentration among North American and European headquarters, with emerging representation from Indian and Chinese equipment builders.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Kubota Corporation |
| Mahindra & Mahindra |
| KUHN Group |
| CLAAS |
| Yanmar Holdings |
| HORSCH Maschinen GmbH |
| Others |
Value Network & Pricing Analysis
Moline, Illinois anchors North American manufacturing capacity for high-horsepower row-crop equipment, concentrating production economics that downstream buyers in Iowa and Illinois negotiate against. This geographic concentration of toolbar fabrication and pneumatic metering assembly creates asymmetric pricing power for integrated manufacturers serving enterprise farm consolidations.
Pricing Analysis
Steel and aluminum cost-plus contracts with London Metal Exchange indexation dominate frame and toolbar procurement, passing commodity volatility through to equipment list prices. Three-tier pricing structure across premium electric-drive, standard pneumatic, and economy mechanical configurations segments buyer budgets, with EPA Tier 4 Final after-treatment costs compressing margins most acutely in mid-tier diesel-powered units. Commercial growers in Brazil demonstrate lowest price sensitivity due to yield-optimization returns, while owner-operators in developing markets resist technology premiums.
Supply Chain Analysis
Supplier-financing facilities extended by German precision-component fabricators to Stuttgart-area industrial clusters stabilize electromechanical actuator availability for EU F-Gas Regulation compliance redesigns. China, Germany, and the United States concentrate supply of precision-machined metering components, high-strength steel forgings, and GPS guidance hardware respectively. Distribution runs through manufacturer-direct subscription platforms disintermediating traditional Iowa and Illinois dealer networks, with single-source vulnerability in electric drive motor controllers representing acute concentration risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric drive row-unit adoption constitutes a high-growth disruption, with EU F-Gas Regulation mandates forcing simultaneous hardware and software subscription investments that lock in multi-year fleet commitments.
For Market Incumbents: Pre-empt margin erosion from battery-electric tractor entrants by accelerating in-house production of electromechanical lift and fold systems, eliminating hydraulic complexity. Secure ISO 7256 certification capacity to create technical barriers against developing-market equipment builders seeking US Corn Belt entry. For New Entrants and Emerging Players: Southeast Asian paddy-field geometries in Vietnam and Thailand represent underpenetrated demand for compact precision seeders, with transplanting workflows underserved by existing broadcast-mechanical equipment. Partner with Yangtze River Delta manufacturing bases for cost-compact electric drive architectures calibrated to wet-field operations. For Investors and Strategic Acquirers: Long-term, this sits as a precision-agriculture platform play because software-defined population management subscriptions are displacing transactional equipment sales as the primary value capture mechanism. Target component suppliers with electric drive retrofit capabilities for Brazilian Cerrado fleet upgrades. Watch battery-electric tractor powertrain maturation as the inflection signal for planter tow-vehicle configuration disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive Retrofit Program | Captures EU F-Gas Regulation compliance-driven replacement cycles among German cooperatives. |
| Direct Subscription Platform Launch | Disintermediates Iowa and Illinois dealer networks for precision agriculture revenue pools. |
| Asian Paddy-Field Specialization | Addresses Vietnam and Thailand transplanting workflows with compact wet-field geometries. |
| ISO 7256 Certification Investment | Creates laboratory validation barriers against developing-market equipment entrants. |
| Battery-Electric Tow-Vehicle Partnership | Aligns planter configurations with emerging sub-150 horsepower tractor architectures. |
Research Methodology
The analysis maps pneumatic metering systems, electric drive row units, mechanical seeders, and fertilizer spreader categories, each validated through equipment procurement directors at Brazilian commercial growers, precision agriculture specialists at German cooperatives, aftermarket service heads at North American dealer networks, and plant engineers at Yangtze River Delta manufacturing bases. Primary interview findings triangulate against customs trade data, OECD seeding performance test protocols, SEC equipment manufacturer filings, and ANVISA agricultural chemical application standards. Bottom-up unit shipment estimates and top-down value aggregation converge across product type, technology tier, and end-user segmentation.
Assumptions held fixed include continued EPA Tier 4 Final enforcement barring non-compliant diesel imports, sustained EU F-Gas Regulation phase-down timelines, and observed farm consolidation rates across the North American Corn Belt. Variables tested include battery-electric tractor adoption velocity, autonomous planting protocol regulatory clearance timelines, and steel-aluminum commodity price trajectories. CAGRs derive from segmented unit economics modeling across working-width configurations, technology tiers, and regional replacement cycles, with software subscription attach rates and precision agriculture penetration curves as critical industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive direct-to-farmer subscription pricing by integrated operations platforms would shift equipment procurement timelines and margin distribution. Macroeconomic deterioration in Brazilian soybean export economics, acceleration of Chinese domestic equipment subsidy programs, or breakthrough solid-state battery commercialization for agricultural powertrains would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market