
 Brazil Fertilizers Market | 2026-2036
Brazil Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Fertilizers Market Outlook
Project finance structures tied to port terminal expansions and warehouse leasing is reshaping competitive entry in Brazilian fertilizer distribution. Mosaic leverages its vertical integration from phosphate mining to blending facilities in Minas Gerais to sustain cost advantages against importers. Verde Agritech anchors its position through domestic potash production in Minas Gerais, reducing foreign exchange exposure that competitors navigate. Atlas Agro differentiates by developing green ammonia projects in Brazil, positioning for low-carbon nitrogenous supply.
Fertilizers are nutrient-dense chemical or organic compounds formulated with specified N-P-K ratios, micronutrient blends, or controlled-release coatings to replenish soil fertility and maximize crop yield. Manufacturing involves ammonia synthesis via Haber-Bosch, phosphate rock acidulation, or potash evaporation and granulation to produce water-soluble or slow-release granules for commercial agriculture. Nitrogenous fertilizers dominate volume due to soy-corn rotation intensity, though specialty fertilizers capture expanding margin pools from precision agriculture and fertigation systems. Oilseeds application, particularly soybeans, leads absolute consumption, while fruits and vegetables drive fastest growth in water-soluble and foliar product categories.
ANVISA regulates maximum contaminant levels in fertilizer imports, while MAPA oversees product registration and quality certification under Brazilian agricultural standards. The Central Bank of Brazil's foreign exchange policies directly shape import cost structures for phosphate and potash derivatives sourced from Morocco, Russia, and Canada. Stakeholders must monitor domestic green ammonia project timelines and port infrastructure bottlenecks at Santos and Paranaguá to secure supply chain positioning.
Market Dynamics
Precision agriculture adoption across Mato Grosso's soy-corn belt is compressing application windows and demanding specialty fertilizer formulations with micronutrient precision and controlled-release coatings. This technology shift is forcing distributors to reconfigure blending capabilities and logistics networks around variable-rate application data.
Growth Catalysts
- Cerrado Expansion:Large-scale commercial operations in Brazil's agricultural frontier are converting degraded pasture to intensive row-crop production, creating step-function demand for phosphate and potash inputs.
- ANVISA Contaminant Standards:Tighter maximum residue limits on imported fertilizer products are accelerating domestic blending facility investments and quality certification upgrades.
- Soy-Corn Rotation Intensity:Double-cropping systems across Paraná and Rio Grande do Sul extract soil nutrients at rates requiring supplemental nitrogenous and phosphatic replenishment beyond natural regeneration.
Market Restraints
- Foreign Exchange Exposure:Brazilian Real volatility against the US dollar directly inflates landed costs for Moroccan phosphate rock and Canadian potash concentrate.
- Port Infrastructure Bottlenecks:Terminal capacity constraints at Santos and Paranaguá create vessel queuing delays during peak planting-season import windows.
- Domestic Ammonia Supply Deficit:Brazil's limited natural gas feedstock availability forces reliance on imported urea and ammonia, exposing nitrogenous fertilizer pricing to international energy market swings.
Strategic Opportunities
- Green Ammonia Production:Electrolysis-based nitrogenous fertilizer manufacturing using Brazil's renewable electricity surplus offers carbon-intensity advantages for EU-bound agricultural exports.
- Precision Fertigation Systems:Water-soluble fertilizer integration with center-pivot and drip irrigation infrastructure in São Paulo's fruit and vegetable zones enables micronutrient delivery at vegetative growth stages.
- MAPA Simplified Registration:Streamlined product approval pathways for controlled-release and stabilized fertilizer formulations reduce time-to-market for specialty product launches.
Industry Challenges
- Agronomic Technical Support Gap:Variable-rate application expertise and soil sampling interpretation skills lag equipment deployment rates across mid-scale operations in Goiás and Bahia.
- Blending Facility Capex Requirements:Automated bulk blending plants with contamination controls and real-time N-P-K adjustment capabilities demand capital commitments exceeding smaller distributor balance sheet capacity.
- Import License Processing Delays:MAPA and ANVISA documentation requirements for first-time product registrations extend commercialization timelines for international suppliers entering Brazilian distribution.
Report Scope
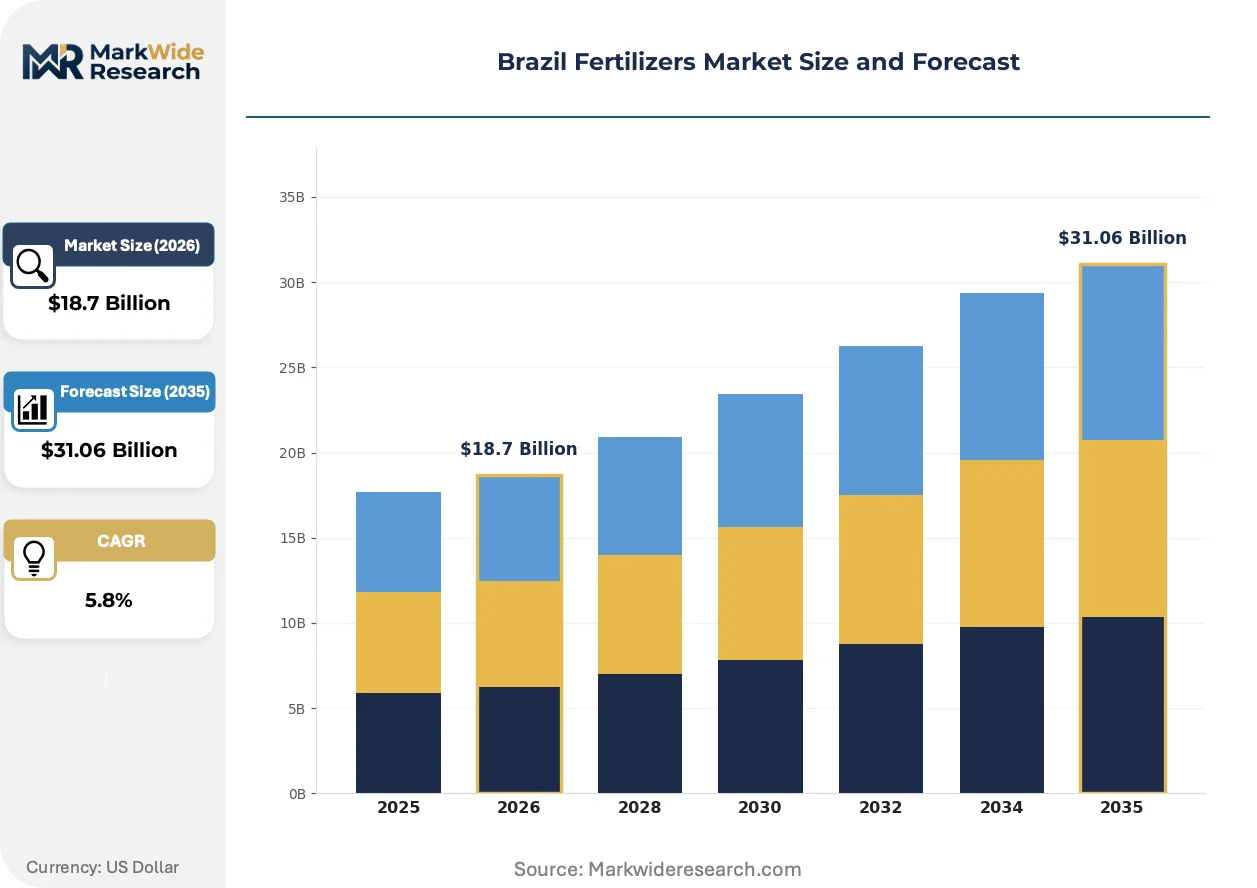
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Fertilizers Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphate, Potash, Specialty Fertilizers Application: Cereal Crops, Pulses, Oilseeds, Fruits & Vegetables End User: Agricultural Farms, Commercial Growers, Research Institutes, Greenhouses Distribution Channel: Retail Stores, Online Sales, Distribution Hubs, Direct Sales |
| Companies Covered | Yara International, Mosaic, Nutrien, ICL Group, EuroChem, Verde Agritech, Atlas Agro, Nortox, Haifa Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Fertilizers Market Strategic Shifts
Digital soil mapping and prescription agriculture platforms are collapsing the information asymmetry between fertilizer suppliers and growers. This convergence is redistributing margin capture toward data-integrated distributors and away from commodity traders.
Variable-rate application technology using GPS-guided spreaders and drone-mounted sensors is virtualizing the traditional uniform-field fertilization model. Large-scale operations in Mato Grosso are deploying these systems across soybean hectares to match nutrient delivery with productivity zones identified through electromagnetic conductivity mapping. The technology is virtualizing inventory planning by enabling just-in-time blending based on real-time yield potential rather than historical averages.
ANVISA's progressive tightening of cadmium and arsenic maximum limits in phosphate fertilizer imports is forcing supplier qualification restructuring. Domestic blenders must now maintain dual sourcing strategies and enhanced laboratory testing protocols to ensure compliance across shipment lots. Specialty fertilizer categories with certified low-contaminant profiles command positioning advantages in export-oriented soy supply chains serving European food processors.
Collective procurement cooperatives among mid-scale growers are consolidating purchase volumes and negotiating direct manufacturer relationships. These associations in Paraná and Rio Grande do Sul are displacing traditional distributor intermediaries for base fertilizer products while retaining technical advisory services. The behavior is most pronounced in regions with established cooperative infrastructure and homogeneous crop profiles enabling standardized formulation procurement.
Brazil Fertilizers Market Segmentation
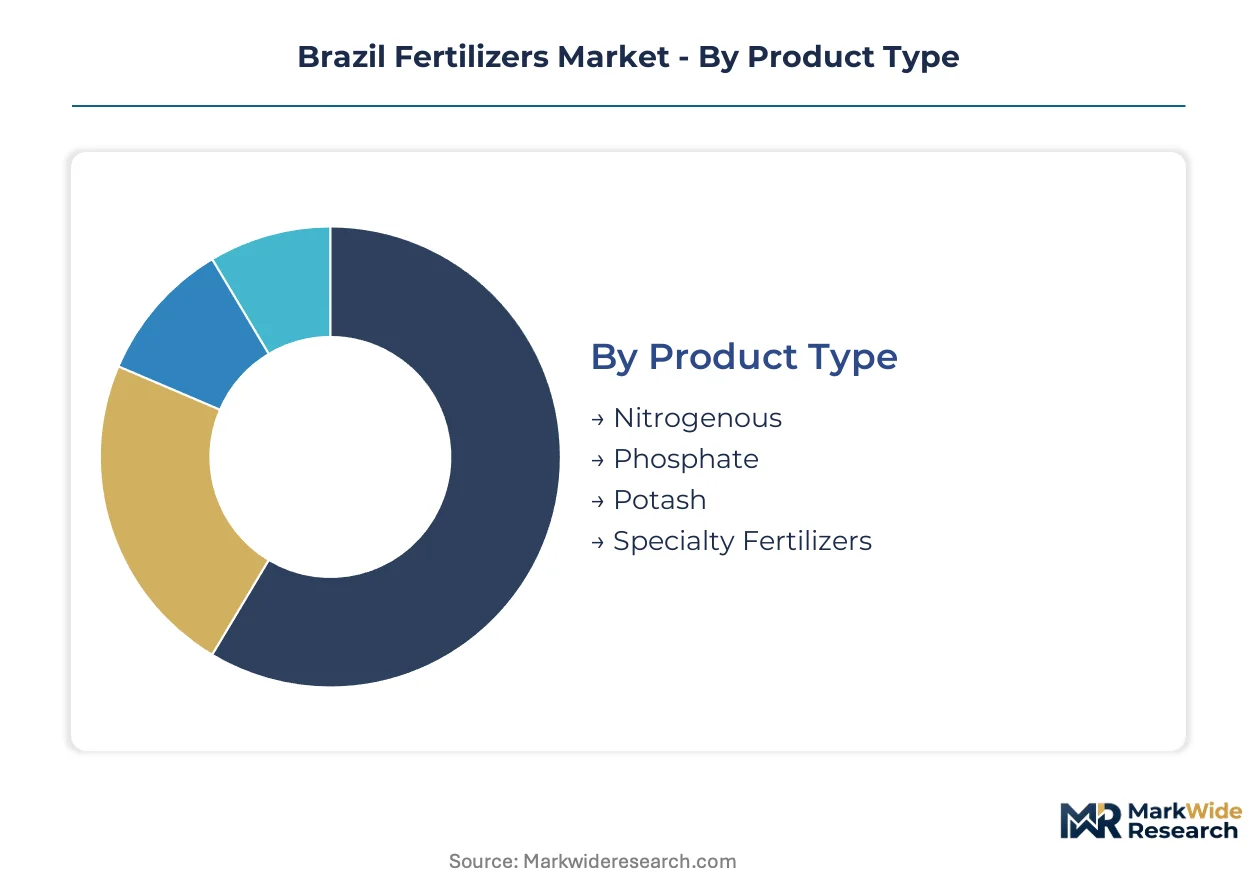
Brazil's fertilizer segmentation reflects divergent maturity profiles across product chemistry and application intensity. Precision agriculture adoption and ANVISA contaminant standards are fragmenting traditional commodity categories while concentrating margin capture in specialized formulations.
Product Type:
Mature commodity chemistries dominate absolute volume, while emerging specialty formulations capture expanding margin pools from precision application systems.
- Nitrogenous:Urea and ammonia-based formulations supply the N component in N-P-K blends through Haber-Bosch synthesis or direct import. Soy-corn rotation intensity across Mato Grosso and Paraná drives consumption volumes exceeding soil natural regeneration rates.
- Phosphate:Single and triple superphosphate products derive from acidulated phosphate rock, with ANVISA cadmium limits forcing supplier qualification restructuring. Domestic blending facilities in Minas Gerais are upgrading laboratory testing protocols to ensure shipment lot compliance.
- Potash:Muriate of potash dominates potassium delivery, sourced primarily from Canadian concentrate imports. Verde Agritech's domestic production in Minas Gerais offers foreign exchange hedging unavailable to pure importers.
- Specialty Fertilizers:Controlled-release coatings, micronutrient blends, and water-soluble formulations target precision agriculture adoption. Fertigation integration in São Paulo's fruit zones enables vegetative-stage nutrient delivery.
Nitrogenous fertilizers handle the majority of throughput; specialty fertilizers are expanding most quickly on share.
Application:
Application segmentation tracks crop-specific nutrient extraction rates and commercial farming intensity across Brazil's agricultural frontier.
- Cereal Crops:Corn and rice production in Rio Grande do Sul and Santa Catarina demands seasonal nitrogen top-dressing aligned with rainfall patterns. Double-cropping systems compress application windows and strain logistics networks.
- Pulses:Dry bean cultivation in Goiás and Bahia requires phosphorus-heavy starter fertilizers to support nitrogen fixation symbiosis. Cooperative procurement associations are consolidating purchase volumes for standardized formulations.
- Oilseeds:Soybean hectares across the Cerrado dominate absolute fertilizer consumption, with precision agriculture adoption driving variable-rate application. Electromagnetic conductivity mapping enables productivity-zone-specific nutrient delivery.
- Fruits & Vegetables:High-value production in São Paulo's citrus belt and Minas Gerais' coffee zones demands water-soluble and foliar formulations. Fertigation infrastructure enables micronutrient precision unavailable in bulk broadcasting systems.
Oilseeds handle the majority of throughput; fruits and vegetables are gaining share fastest.
End User:
End user segmentation reflects operational scale differentiation and technical advisory requirements across Brazil's farming structure.
- Agricultural Farms:Family and mid-scale operations in Paraná rely on cooperative procurement for base fertilizers while retaining distributor advisory services. Variable-rate application expertise lags equipment deployment rates in Goiás and Bahia.
- Commercial Growers:Large-scale operations in Mato Grosso deploy GPS-guided spreaders and drone-mounted sensors for prescription agriculture. Real-time yield potential data virtualizes inventory planning toward just-in-time blending.
- Research Institutes:EMBRAPA and state agricultural universities conduct field trials for controlled-release formulation validation. MAPA simplified registration pathways accelerate commercialization timelines for validated products.
- Greenhouses:Protected cultivation in São Paulo's peri-urban zones demands complete nutrient solution control through hydroponic and substrate systems. Water-soluble fertilizer integration enables precise EC and pH management.
Agricultural farms handle the majority of throughput; commercial growers are climbing the fastest on share.
Distribution Channel:
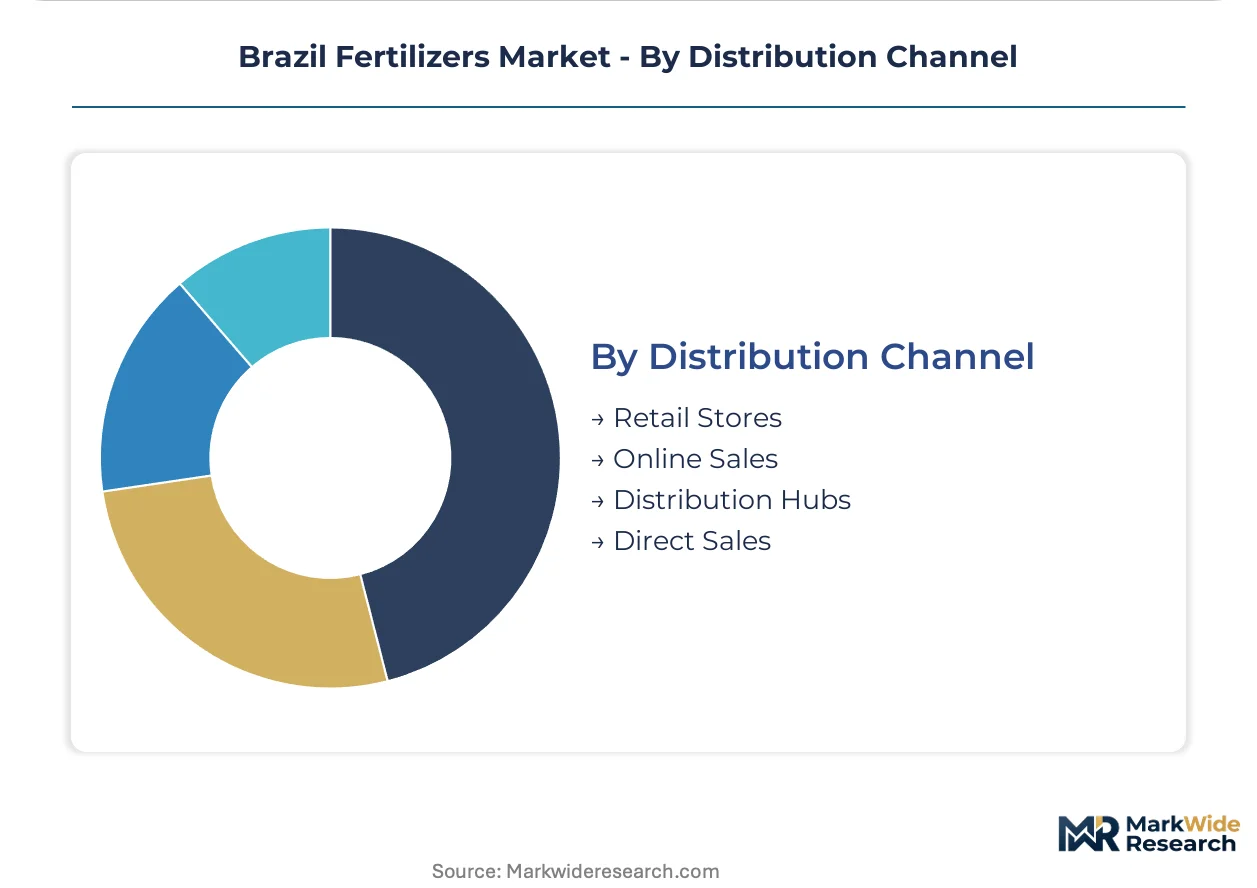
Channel segmentation tracks the disintermediation pressure from collective procurement and digital platform emergence.
- Retail Stores:Traditional rural supply stores in Rio Grande do Sul maintain farmer relationships through credit extension and technical advisory. Automated bulk blending plant investments exceed smaller distributor balance sheet capacity.
- Online Sales:Digital platforms are collapsing information asymmetry between suppliers and growers, redistributing margin capture toward data-integrated distributors. Prescription agriculture platforms enable direct manufacturer relationships.
- Distribution Hubs:Port-adjacent terminals at Santos and Paranaguá face vessel queuing delays during peak planting-season import windows. Project finance structures tied to warehouse leasing reshape competitive entry.
- Direct Sales:Collective procurement cooperatives in Paraná and Rio Grande do Sul negotiate direct manufacturer relationships for base fertilizer products. Homogeneous crop profiles enable standardized formulation procurement at volume discounts.
Retail stores handle the majority of throughput; online sales show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MAPA's streamlined registration pathways and ANVISA contaminant standards are redirecting investment toward domestic blending capacity across Brazil's agricultural states. Regional differentiation reflects soil chemistry variation, crop mix intensity, and port access economics.
Mato Grosso
Soy-corn rotation intensity across the Cerrado frontier extracts soil nutrients at rates requiring intensive phosphate and potash replenishment. ANVISA cadmium limits on imported phosphate rock are forcing local blenders to upgrade laboratory testing protocols. Large-scale commercial operations around Sorriso and Lucas do Rio Verde deploy GPS-guided variable-rate spreaders matched to electromagnetic conductivity mapping zones.
Paraná
Collective procurement cooperatives consolidate purchase volumes for standardized N-P-K formulations serving homogeneous soybean profiles. MAPA quality certification requirements shape distributor relationships with international suppliers. The Cascavel and Toledo corridors anchor blending facility investments targeting just-in-time delivery compression during compressed planting windows.
São Paulo
High-value fruit and vegetable production in the citrus belt and peri-urban zones demands water-soluble and foliar formulations for fertigation integration. ANVISA maximum residue limits on imported products accelerate domestic formulation investments. Piracicaba and Limeira clusters concentrate precision agriculture advisory services linking soil sampling to prescription nutrient delivery.
Minas Gerais
Phosphate mining and domestic potash production anchor upstream supply security unavailable to pure importers. Verde Agritech's operations near São Gotardo reduce foreign exchange exposure for regional distributors. Uberaba and Patos de Minas serve as blending hubs for the Triângulo Mineiro soybean corridor with contamination-controlled laboratory infrastructure.
Rio Grande do Sul
Double-cropping wheat-soybean systems compress application logistics and strain port terminal capacity during peak import windows. Cooperative procurement associations in Passo Fundo and Erechim negotiate direct manufacturer relationships for base fertilizers. Traditional rural supply stores maintain farmer loyalty through credit extension and technical advisory despite disintermediation pressure.
Brazil Fertilizers Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structured around import dependency and domestic production scarcity. Consolidation pressures concentrate among distributors with port terminal access and automated blending capabilities, while fragmentation persists among regional advisory-focused retailers. Three archetypes dominate: vertically integrated miners with captive phosphate supply, pure-play importers managing foreign exchange exposure, and domestic specialty formulators targeting precision agriculture niches. Competitive moves center on backward integration into green ammonia production and warehouse leasing structures securing Santos and Paranaguá throughput priority.
Among the integrated mining tier, Mosaic exemplifies upstream control over phosphate rock through Minas Gerais acidulation facilities. Nutrien and Yara International occupy positions as import-dependent nitrogenous suppliers navigating Central Bank foreign exchange volatility. Verde Agritech anchors the domestic production archetype with potash mining operations reducing currency risk for regional distributors. Atlas Agro represents the emerging green ammonia category targeting carbon-intensity advantages for export-oriented supply chains.
| Leading Market Players |
|---|
| Yara International |
| Mosaic |
| Nutrien |
| ICL Group |
| EuroChem |
| Verde Agritech |
| Atlas Agro |
| Nortox |
| Haifa Group |
| Others |
Value Chain & Pricing Dynamics
Canadian potash concentrate and Moroccan phosphate rock concentration upstream anchors margin capture at port-adjacent blending terminals and automated distribution hubs downstream. ANVISA contaminant certification tiers stratify pricing spreads between import-dependent commodity traders and domestic quality-certified formulators.
Pricing Analysis
Certification level under ANVISA cadmium and arsenic maximum limits creates the primary spread between premium low-contaminant phosphate products and standard-grade imports. Three-tier pricing structure across certified-premium, standard-import, and economy-blend levels tracks laboratory testing investment and dual-sourcing qualification costs. Cost compression in nitrogenous tiers is intensifying because Central Bank foreign exchange volatility inflates urea and ammonia landed costs. Mid-scale cooperative buyers in Paraná and Rio Grande do Sul exhibit highest price sensitivity through collective procurement leverage, while Mato Grosso commercial growers prioritize application precision over unit cost.
Supply Chain Analysis
Export licensing restrictions on Russian potash and Belarusian fertilizer products under international sanctions regimes constrain alternative sourcing for Brazilian importers. Geographic supply concentration centers on Canada for muriate of potash, Morocco for phosphate rock, and Trinidad and Tobago for ammonia feedstock. Raw material dependencies rest on sulfur for acidulation, natural gas for Haber-Bosch synthesis, and specialized coatings for controlled-release formulations. Single-source vulnerability runs through Santos and Paranaguá terminal capacity during October-March peak import windows. Distribution feeds from port-adjacent warehouses through regional blending hubs to cooperative procurement associations and commercial grower direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's fertilizer market structure rewards defensive positioning through regulatory entrenchment around ANVISA certification and MAPA registration pathways that embed switching costs for qualified suppliers.
For Market Incumbents: Harden port terminal lease structures and automated blending capacity at Santos and Paranaguá against emerging green ammonia domestic production threats. Deepen backward integration into phosphate acidulation or potash mining to offset foreign exchange exposure that pure importers navigate. Prioritize laboratory certification investments that lock in premium tier positioning as ANVISA tightens cadmium limits. For New Entrants and Emerging Players: Goiás and Bahia's mid-scale farm segments offer underpenetrated variable-rate application advisory services where technical expertise lags equipment deployment. Target precision agriculture data integration partnerships with existing cooperatives rather than competing on base fertilizer volume. Enter through water-soluble and foliar formulation niches serving São Paulo's fruit and vegetable zones where fertigation infrastructure enables premium positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding port-adjacent warehouse leases and established MAPA registration portfolios. Five-to-ten year viability hinges on positioning for green ammonia project offtake agreements and carbon-intensity certification for EU-bound agricultural export supply chains. Watch Atlas Agro and domestic electrolysis-based nitrogenous project timelines as inflection signals for import displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Green Ammonia Production | Electrolysis-based nitrogenous manufacturing leverages Brazil's renewable electricity surplus for carbon-intensity advantages. |
| Port Terminal Capacity Expansion | Project finance structures at Santos and Paranaguá secure throughput priority during compressed planting-season import windows. |
| ANVISA Certification Laboratory Investment | Dual-sourcing qualification and enhanced testing protocols ensure compliance across cadmium-limited phosphate shipment lots. |
| Precision Agriculture Data Platform Integration | Prescription agriculture partnerships with Mato Grosso commercial growers redistribute margin capture toward data-integrated distributors. |
| Cooperative Procurement Direct Relationship | Volume consolidation with Paraná and Rio Grande do Sul associations displaces traditional distributor intermediaries for base products. |
Study Parameters
Desk research of customs trade records, MAPA registration databases, and ANVISA contaminant standard filings preceded structured interviews with blending facility operations managers, cooperative procurement directors, and port terminal logistics coordinators. Primary fieldwork with commercial growers in Mato Grosso and Paraná validated precision agriculture adoption rates and variable-rate application equipment deployment. Secondary validation drew from Central Bank foreign exchange policy documents and EMBRAPA agronomic trial publications. Bottom-up volume estimates from crop-specific nutrient extraction rates triangulated against top-down import value flows through Santos and Paranaguá customs data.
Forecast assumptions held Brazilian Real volatility within historical bands against the US dollar, ANVISA regulatory timelines within documented processing windows, and green ammonia project development within announced construction schedules. The analytical framework modeled product type segmentation across nitrogenous, phosphate, potash, and specialty formulations; application intensity across oilseeds, cereals, and high-value crops; and distribution channel evolution across retail, direct procurement, and digital platforms. CAGRs derived from trend extrapolation of precision agriculture penetration rates and Cerrado land conversion trajectories, cross-referenced against nutrient balance modeling for soy-corn rotation systems.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed international suppliers or accelerated green ammonia commissioning would shift outcomes. Material shifts in Central Bank foreign exchange intervention policy, ANVISA maximum residue limit revisions, or port infrastructure privatization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Mixtures Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Russia Fertilizers Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Global Starter Fertilizers Market