
 Nitro Compound Fertilizers Market | 2026-2036
Nitro Compound Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Nitro Compound Fertilizers Market Analysis
Blended nutrient bundling is restructuring how growers evaluate nitrogen efficiency against phosphorus and potassium integration. Yara International leverages its integrated ammonia-to-nitrate supply chain to sustain premium positioning in stabilized formulations. EuroChem Group anchors its competitiveness through captive phosphate and potash assets that reduce raw material cost volatility. CF Industries Holdings, Inc. differentiates via large-scale U.S. ammonia production and pipeline-connected distribution density.
Nitro compound fertilizers combine nitrogen with secondary or micronutrients in single-granule or homogeneous formulations, typically manufactured through ammoniation-granulation or melt-spraying processes to achieve controlled nutrient release profiles. These products serve commercial agriculture by reducing application passes and improving nutrient use efficiency versus straight nitrogen sources. Granular formulations occupy the dominant volume position due to mechanical spreading compatibility and storage stability, while liquid suspensions represent the fastest-expanding configuration where fertigation and precision application infrastructure penetrate. Agricultural crops command the largest application share, though horticulture generates disproportionate margin pools through specialty micronutrient inclusion and technical support requirements.
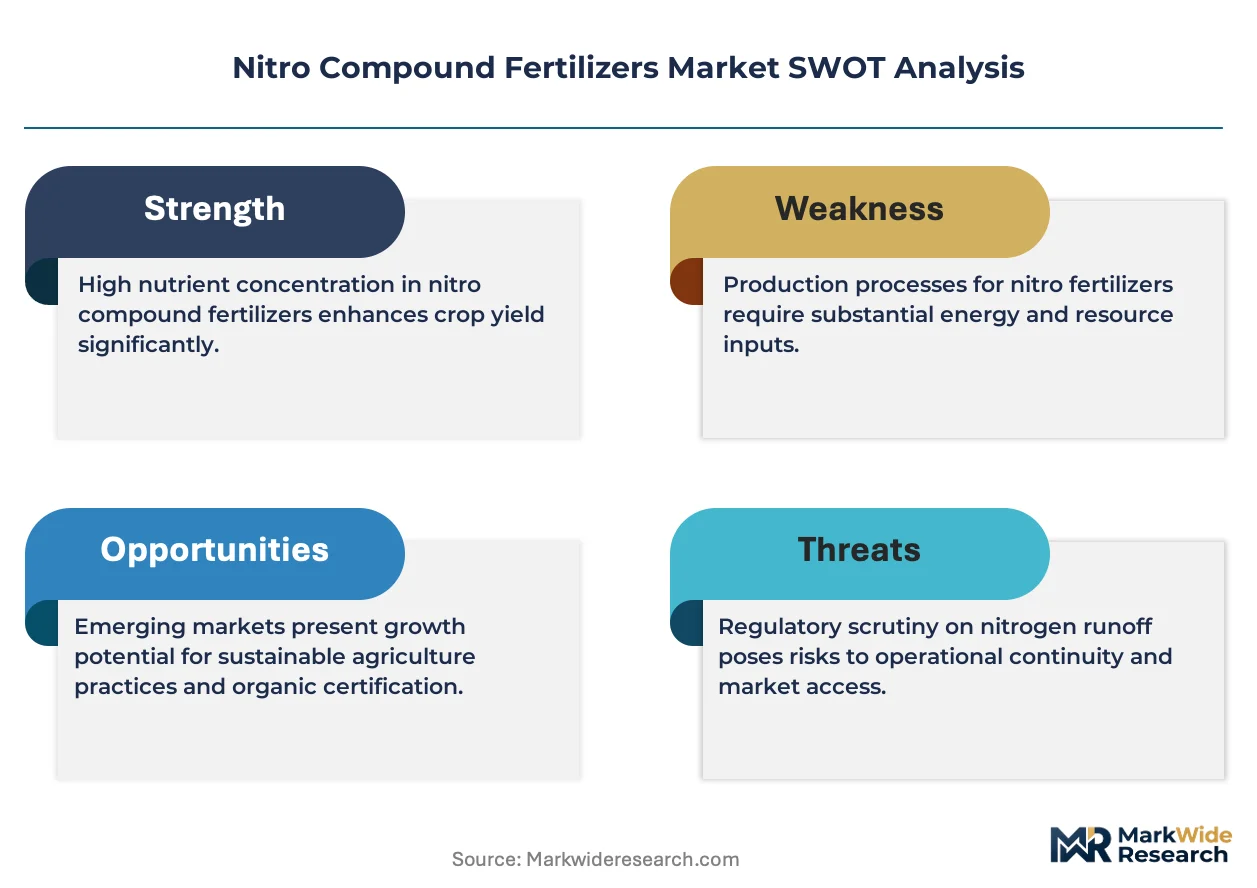
The U.S. EPA regulates ammonia and nitrous oxide emissions from fertilizer production facilities, compelling manufacturers to adopt Best Available Control Technology or face operating permit restrictions. China's MEE enforces nitrogen runoff limits in major watersheds, redirecting formulation demand toward polymer-coated and nitrification-inhibitor-enhanced products. The EU F-Gas Regulation and Farm-to-Fork Strategy constrain conventional nitrogen application rates, creating compliance-driven substitution toward enhanced-efficiency compounds. Stakeholders must monitor evolving carbon border adjustment mechanisms and watershed-level nutrient trading schemes that will reshape cost structures and regional competitive advantage without warning.
Market Dynamics
China's dual carbon goals and nitrogen emission caps are forcing reformulation toward stabilized and controlled-release products, restructuring competitive advantage around environmental compliance rather than raw scale.
Growth Catalysts
- Precision Agriculture Expansion:Specialty crop producers in Brazil's Cerrado zone are intensifying soybean-corn rotation systems that compound fertilizer uptake.
- Watershed Protection Mandates:China's MEE enforces nitrogen runoff limits in major watersheds, redirecting formulation demand toward polymer-coated and inhibitor-enhanced products.
- EU Green Deal Alignment:The EU F-Gas Regulation and Farm-to-Fork Strategy constrain conventional nitrogen application rates, creating compliance-driven substitution toward enhanced-efficiency compounds.
Market Restraints
- Natural Gas Feedstock Volatility:Ammonia production costs swing with Henry Hub and TTF pricing, compressing margins for non-integrated manufacturers.
- Phosphate Supply Concentration:Captive phosphate and potash assets cluster in Morocco, Russia, and Belarus, exposing buyers to geopolitical disruption risk.
- Technical Limitation in Liquid Stability:Suspension fertilizers face seasonal storage degradation that granular formulations avoid, limiting adoption in temperate climates.
Strategic Opportunities
- Carbon Border Adjustment Leverage:The EU's CBAM mechanism rewards low-carbon ammonia sourcing, creating premium positioning for producers with renewable hydrogen integration.
- Fertigation Infrastructure Penetration:Liquid suspensions capture share where drip irrigation and center-pivot systems expand in India's Gujarat and Maharashtra states.
- Nutrient Trading Schemes:Watershed-level credit markets in the Chesapeake Bay and Mississippi River basins monetize runoff reduction, incentivizing stabilized product adoption.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Polymer-coating and nitrification inhibitor expertise concentrates at legacy research centers, constraining rapid product pipeline expansion.
- Capex Intensity in Emissions Abatement:Best Available Control Technology upgrades for ammonia and nitrous oxide compliance demand nine-figure investments per facility.
- Legacy Equipment Integration Friction:Controlled-release granules require recalibrated spreader settings that agronomist networks must retrain across dealer channels.
Report Scope
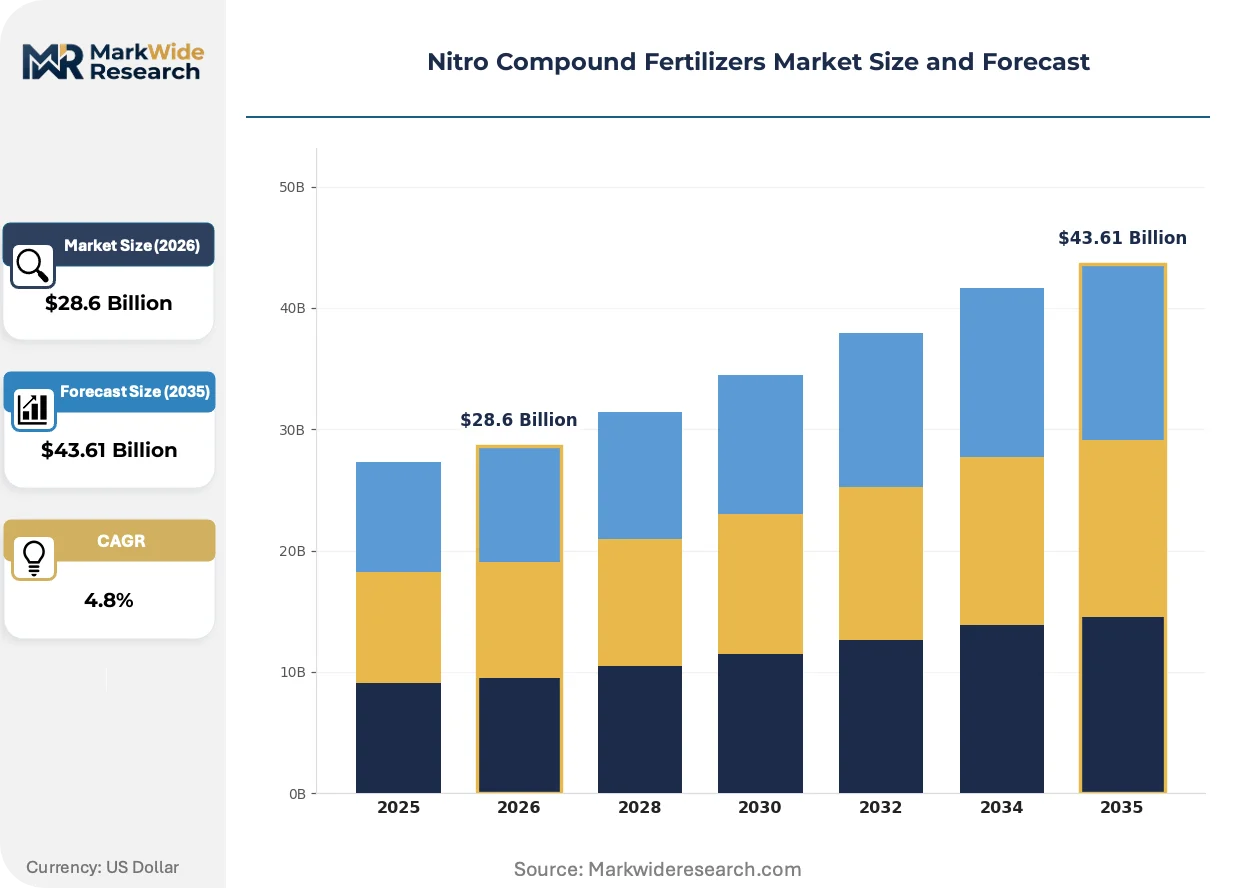
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitro Compound Fertilizers Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Suspensions Application: Agricultural Crops, Horticulture, Landscaping, Turf End User: Farmers, Distributors, Retailers, Agricultural Cooperatives Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Yara International, CF Industries Holdings, Inc., EuroChem Group, Nutrien, BASF, Sinochem, Kingenta Ecological Engineering Group Co., Ltd, Sichuan Ruixiang Agricultural Science and Technology Development Co., Ltd., Haifa Negev technologies LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitro Compound Fertilizers Market Emerging Trajectories
Formulation science and application infrastructure are converging to reduce nutrient loss while tightening the link between input cost and yield response.
Controlled-release polymer coatings are unifying nitrogen, phosphorus, and potassium into single-granule formulations with synchronized nutrient availability curves. Large-scale corn operations in the U.S. Corn Belt are adopting these products at accelerating rates to reduce split-application labor costs. This unifying technology compresses the addressable market for straight nitrogen sources while elevating technical support requirements as a competitive differentiator.
The U.S. EPA regulates ammonia and nitrous oxide emissions from fertilizer production facilities, compelling manufacturers to adopt Best Available Control Technology or face operating permit restrictions. Facilities without abatement infrastructure face production curtailments during ozone season. Nitrogen producers with pipeline-connected distribution density are responding by front-loading capital into emissions capture systems ahead of permit renewal cycles.
Buyers in Brazil's agricultural belt are consolidating procurement through cooperative purchasing pools that negotiate volume-tiered contracts directly with manufacturers. Traditional distributor networks face margin compression as these pools disintermediate regional dealers. This behavioral shift concentrates price-setting power among a smaller number of decision-makers in Mato Grosso and Goiás states.
Nitro Compound Fertilizers Market Segmentation
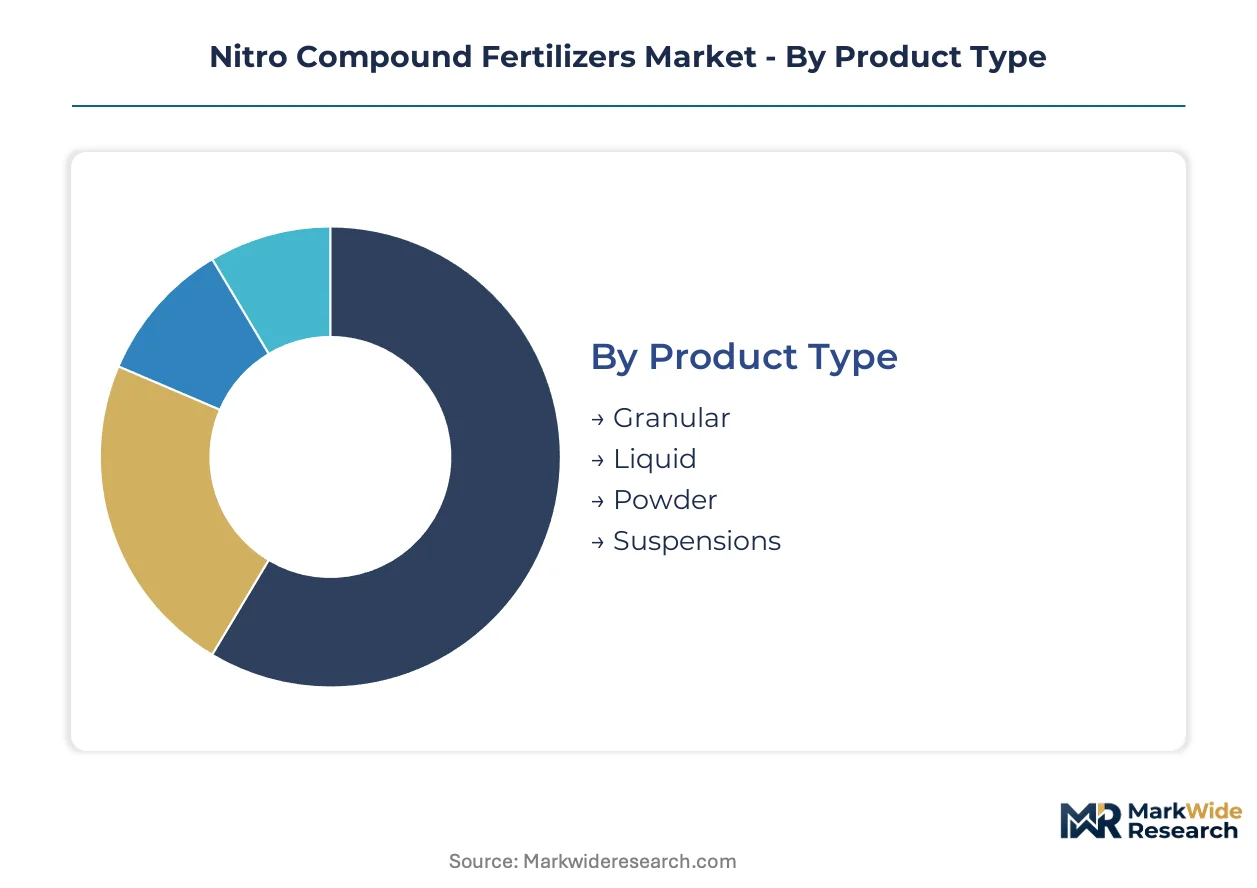
Segmentation in nitro compound fertilizers reveals how formulation chemistry, application infrastructure, and procurement behavior split the addressable market into distinct competitive arenas. Each dimension carries different margin structures and technical barriers that reshape vendor positioning.
Product Type:
Farmers choose formulations based on equipment compatibility, storage constraints, and labor cost tradeoffs across their operations.
- Granular:Spherical particles manufactured through ammoniation-granulation deliver mechanical spreading compatibility and extended storage stability. U.S. Corn Belt operations favor these formulations to reduce split-application labor costs during narrow planting windows.
- Liquid:Homogeneous solutions or suspensions enable fertigation integration and precision variable-rate application. Brazil's Cerrado expansion zone drives demand where center-pivot irrigation infrastructure penetrates soybean-corn rotation systems.
- Powder:Fine particulate formulations suit specialty blending operations and micronutrient inclusion for horticultural producers.
- Suspensions:Concentrated liquid mixtures with suspended solids bridge granular and liquid properties for custom blending flexibility.
Volume sits with Granular; growth tilts toward Liquid.
Application:
End-use economics determine formulation complexity and technical support intensity required from suppliers.
- Agricultural Crops:Broad-acre cereals, oilseeds, and fiber crops consume standardized NPK compounds at scale. China's MEE nitrogen runoff limits in major watersheds redirect demand toward polymer-coated and inhibitor-enhanced products for rice and wheat systems.
- Horticulture:Specialty fruits, vegetables, and ornamentals require micronutrient-inclusive formulations with precise release curves. Greenhouse operations in the Netherlands generate disproportionate margin pools through technical support and prescription blending services.
- Landscaping:Turf establishment and maintenance applications prioritize visual uniformity and rapid greening response over sustained release.
- Turf:Golf courses and sports fields demand homogeneous granule distribution and controlled release to manage clipping rates and playing surface consistency.
Revenue concentrates in Agricultural Crops; margin expansion favors Horticulture.
End User:
Procurement scale and technical sophistication fragment the customer base into distinct negotiation power tiers.
- Farmers:Individual growers select products based on yield response history and equipment compatibility. Mato Grosso and Goiás states in Brazil are consolidating procurement through cooperative purchasing pools that negotiate volume-tiered contracts directly with manufacturers.
- Distributors:Regional logistics networks manage inventory positioning and agronomist-led technical support for dealer channels.
- Retailers:Farm supply stores and garden centers serve smaller-scale operators with bagged and private-label offerings.
- Agricultural Cooperatives:Member-owned entities aggregate demand across thousands of farms to secure manufacturer-direct pricing and custom formulation access.
Transaction volume flows through Distributors; pricing power accumulates at Agricultural Cooperatives.
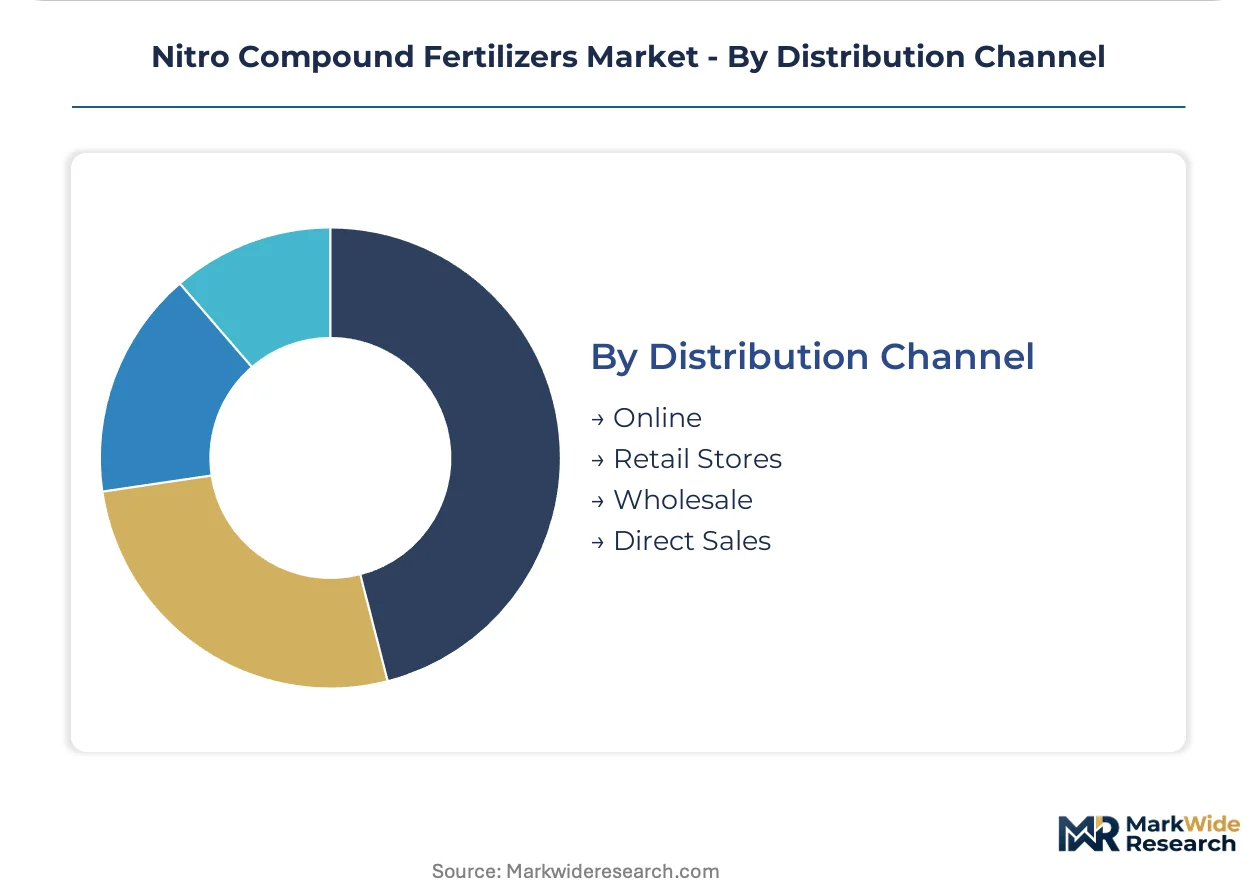
Distribution Channel:
Channel selection reflects buyer scale, urgency requirements, and technical consultation needs.
- Online:Digital platforms enable price transparency and bulk ordering for established growers with formulation familiarity. India's Gujarat and Maharashtra states show expanding adoption where mobile connectivity penetrates rural procurement.
- Retail Stores:Physical locations provide immediate availability and seasonal promotional bundling for smaller operations.
- Wholesale:Volume-tiered pricing and direct-to-farm delivery serve large-scale commercial agriculture with predictable demand patterns.
- Direct Sales:Manufacturer agronomists prescribe customized blends and manage long-term yield response relationships with key accounts.
Wholesale handles the tonnage; Direct Sales captures the premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's MATOPIBA agricultural frontier operates as a special economic zone for agribusiness expansion, concentrating nitro compound fertilizer demand through soybean-corn rotation intensification and infrastructure tax incentives that accelerate input procurement consolidation.
United States
Corn Belt operations in Iowa and Illinois drive granular formulation uptake to compress narrow planting windows. The EPA enforces Best Available Control Technology mandates on ammonia and nitrous oxide emissions, compelling facility upgrades ahead of permit renewals. Pipeline-connected distribution clusters in Louisiana and Oklahoma anchor manufacturer logistics density.
Brazil
Mato Grosso and Goiás cooperative purchasing pools disintermediate traditional distributors through volume-tiered manufacturer contracts. ANVISA and environmental agencies coordinate watershed protection protocols that redirect demand toward stabilized formulations. The Cerrado expansion zone concentrates center-pivot infrastructure investment that accelerates liquid suspension adoption.
China
Yangtze River Delta fertilizer manufacturers reformulate production lines toward polymer-coated products under MEE nitrogen runoff caps. Dual carbon goals force ammonia plant decarbonization investments that restructure cost competitiveness. Shandong Peninsula clusters specialize in controlled-release granule exports to Southeast Asian rice systems.
India
Gujarat and Maharashtra states expand fertigation infrastructure that captures liquid suspension share among cotton and sugarcane operators. The PLI scheme and nutrient-based subsidy reforms incentivize customized blend adoption. Dealer networks in Punjab and Haryana face procurement consolidation as state cooperative federations aggregate demand.
Germany
Rhineland-Palatinate chemical complexes integrate emissions capture systems to comply with EU F-Gas Regulation and Farm-to-Fork nitrogen application constraints. The EU Green Deal's carbon border adjustment mechanism rewards low-carbon ammonia sourcing from renewable hydrogen pilots. Bavarian precision farming cooperatives test variable-rate application protocols that elevate technical support requirements.
Nitro Compound Fertilizers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated ammonia-to-nitrate producers with captive feedstock, regional compounders with formulation flexibility, and technology licensors with polymer-coating intellectual property. Capacity expansion and strategic partnerships dominate competitive moves as emissions compliance costs reshape scale economics.
Among integrated producers, Yara International and CF Industries Holdings, Inc. occupy positions that exemplify feedstock-backward and distribution-density archetypes respectively. EuroChem Group represents the captive-mineral-asset model that insulates margin volatility. Kingenta Ecological Engineering Group Co., Ltd. and Sichuan Ruixiang Agricultural Science and Technology Development Co., Ltd. anchor Chinese domestic supply consolidation. Haifa Negev technologies LTD exemplifies specialty micronutrient positioning that captures horticulture margin pools.
| Leading Market Players |
|---|
| Yara International |
| CF Industries Holdings, Inc. |
| EuroChem Group |
| Nutrien |
| BASF |
| Sinochem |
| Kingenta Ecological Engineering Group Co., Ltd |
| Sichuan Ruixiang Agricultural Science and Technology Development Co., Ltd. |
| Haifa Negev technologies LTD |
| Others |
Supply Flow & Price Mechanics
Premium stabilized formulations command substantial markups over commodity nitrate compounds, with the certification ladder for polymer-coating and nitrification-inhibitor technologies creating parallel supply chains that source ammonia from distinct feedstock tiers and route through separate logistics networks.
Pricing Analysis
Short lead-time premiums reward manufacturers with pipeline-connected distribution density, while spot inventory liquidations in oversupplied quarters compress margins for non-integrated compounders. Contract-based long-term offtake dominates Brazilian cooperative purchasing pools, with price differentiation driven by volume scale and environmental compliance certification. Pricing pressure stems from Henry Hub and TTF natural gas volatility that squeezes ammonia production economics. Large-scale agricultural cooperatives exhibit highest price sensitivity, while horticulture specialists accept premium positioning for micronutrient-inclusive technical support.
Supply Chain Analysis
ISO and REACH certification gating restricts polymer-coating technology licensing to established research centers, filtering supplier qualification. Ammonia production concentrates in the United States, China, and Russia, with phosphate rock dependencies drawing from Morocco and captive potash assets in Belarus. Single-source vulnerability runs through Russian ammonia pipeline disruptions that reroute European sourcing. Distribution runs through manufacturer-direct agronomist networks for premium formulations, while wholesale channels handle commodity granular tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive feedstock control and emissions-abatement infrastructure determine survival, with upstream ammonia production and downstream prescription agronomy services representing the critical levers players are consolidating.
For Market Incumbents: Deepen backward integration into low-carbon ammonia production through renewable hydrogen pilot integration, securing EU carbon border adjustment mechanism compliance ahead of permit renewal cycles. Expand technical agronomist headcount in Brazil's Mato Grosso cooperative purchasing zones to defend margin position against direct manufacturer contracting. Prioritize polymer-coating R&D licensing to constrain formulation chemistry talent scarcity among emerging competitors. For New Entrants and Emerging Players: China's MEE nitrogen runoff limits open a window for polymer-coated and inhibitor-enhanced product specialization targeting Yangtze River Delta rice systems. Target India's Gujarat and Maharashtra liquid suspension segments where fertigation infrastructure penetration outpaces established granular distribution networks. Pursue joint-venture manufacturing with state cooperative federations to bypass entrenched dealer channel control. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-licensing specialists with polymer-coating intellectual property and regional compounders with formulation flexibility in high-growth agricultural frontiers. Long-term viability hinges on emissions compliance infrastructure and captive mineral asset positions that insulate margin volatility. Monitor watershed-level nutrient trading scheme activation in the Chesapeake Bay and Mississippi River basins as inflection indicators for stabilized product demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Ammonia | EU CBAM mechanism rewards renewable hydrogen sourcing from Rhineland-Palatinate pilots. |
| Polymer-Coating Technology Licensing | Controlled-release granule patents constrain rapid pipeline expansion among competitors. |
| Cooperative Purchasing Pool Penetration | Volume-tiered contracts in Mato Grosso disintermediate traditional distributor networks. |
| Fertigation Infrastructure Partnership | Center-pivot system expansion in Brazil's Cerrado accelerates liquid suspension adoption. |
| Emissions Capture System Deployment | Best Available Control Technology upgrades secure EPA operating permits ahead of ozone season. |
Methodological Framework
Multi-period observation of ammonia feedstock pricing, polymer-coating patent filings, and watershed nutrient trading scheme development anchored the trend analysis, supplemented by interviews with plant managers at integrated fertilizer complexes, procurement leads at Brazilian agricultural cooperatives, distribution channel partners in India's dealer networks, and technical R&D directors specializing in controlled-release formulations. Secondary validation drew from customs and trade data, SEC 10-K filings of listed nitrogen producers, EPA emissions compliance disclosures, and MEE watershed protection enforcement records. Bottom-up granular demand modeling and top-down macroeconomic scenario triangulation ensured cross-verification.
Segment-weighting across product type, application intensity, and end-user procurement scale drove the analytical framework over the projection horizon. Formulation chemistry tier, equipment compatibility requirements, and regional regulatory cluster density represented the core segmentation dimensions modeled. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for policy intervention impacts. Industry-specific forecast inputs included natural gas price scenario bands and cooperative purchasing pool consolidation rates.
The model assumes a particular technology adoption path for controlled-release granules; alternative pathways for liquid suspension fertigation integration would alter the outlook. Forecasts reflect assumptions regarding MEE enforcement intensity and EU carbon border adjustment mechanism implementation pacing. A model refresh is warranted upon material change in watershed-level nutrient trading scheme liquidity or renewable hydrogen ammonia cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market