
 Vietnam Specialty Fertilizer Market | 2026-2036
Vietnam Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Specialty Fertilizer Market Analytics
Vietnam's Decree 108/2021/ND-CP on fertilizer management is consolidating the cost-of-entry calculus for both domestic manufacturers and importers. Baconco leverages its integrated distribution network across southern provinces to sustain market presence. Yara International ASA anchors premium micronutrient portfolios through technical agronomy services. PetroVietnam Ca Mau Fertilizer competes on manufacturing scale with its urea-ammonia complex supplying feedstock for downstream specialty blending.
Vietnam specialty fertilizers are formulated products containing specific nutrient ratios, often with added micronutrients or controlled-release coatings, designed for targeted crop nutrition rather than broad-spectrum soil amendment. These formulations typically incorporate chelated trace elements, polymer-coated granules, or microbial inoculants to optimize nutrient use efficiency in tropical acid soils. Organic fertilizers command widening shelf space as retail channels respond to farmer preference for residue-free export crops. Controlled-release fertilizers occupy the fastest-expanding margin pool in horticultural applications, particularly for dragon fruit and pepper plantations where labor savings from reduced application frequency justify price premiums. Liquid formulations lead in the Mekong Delta's intensive vegetable systems where fertigation infrastructure is densest.
BIS-equivalent standards administered by the Vietnam Directorate for Standards, Metrology and Quality, alongside MARD's fertilizer registration protocols, shape product formulation requirements and import clearance timelines. The country's national agricultural regulator enforces heavy metal limits and labeling disclosures that filter out low-grade competitors. Stakeholders must monitor how MARD's pending circular on bio-fertilizer efficacy testing will redistribute competitive advantage between microbial inoculant developers and conventional compounders.
Market Dynamics
MARD's tightened quality certification requirements are consolidating product registration pathways and raising the cost-of-entry calculus for both domestic manufacturers and importers, reshaping competitive positioning across the Mekong Delta and Central Highlands.
Growth Catalysts
- Decree 108/2021/ND-CP:The Ministry of Agriculture and Rural Development's unified fertilizer management framework is streamlining compliance for registered operators while filtering out low-grade competitors through heavy metal limits and labeling disclosures.
- Dragon fruit and pepper plantations:Controlled-release formulations are displacing conventional compounds in horticultural applications where labor savings from reduced application frequency justify price premiums.
- Mekong Delta vegetable systems:Dense fertigation infrastructure is accelerating uptake of liquid specialty formulations among intensive commercial growers seeking precise nutrient delivery.
Market Restraints
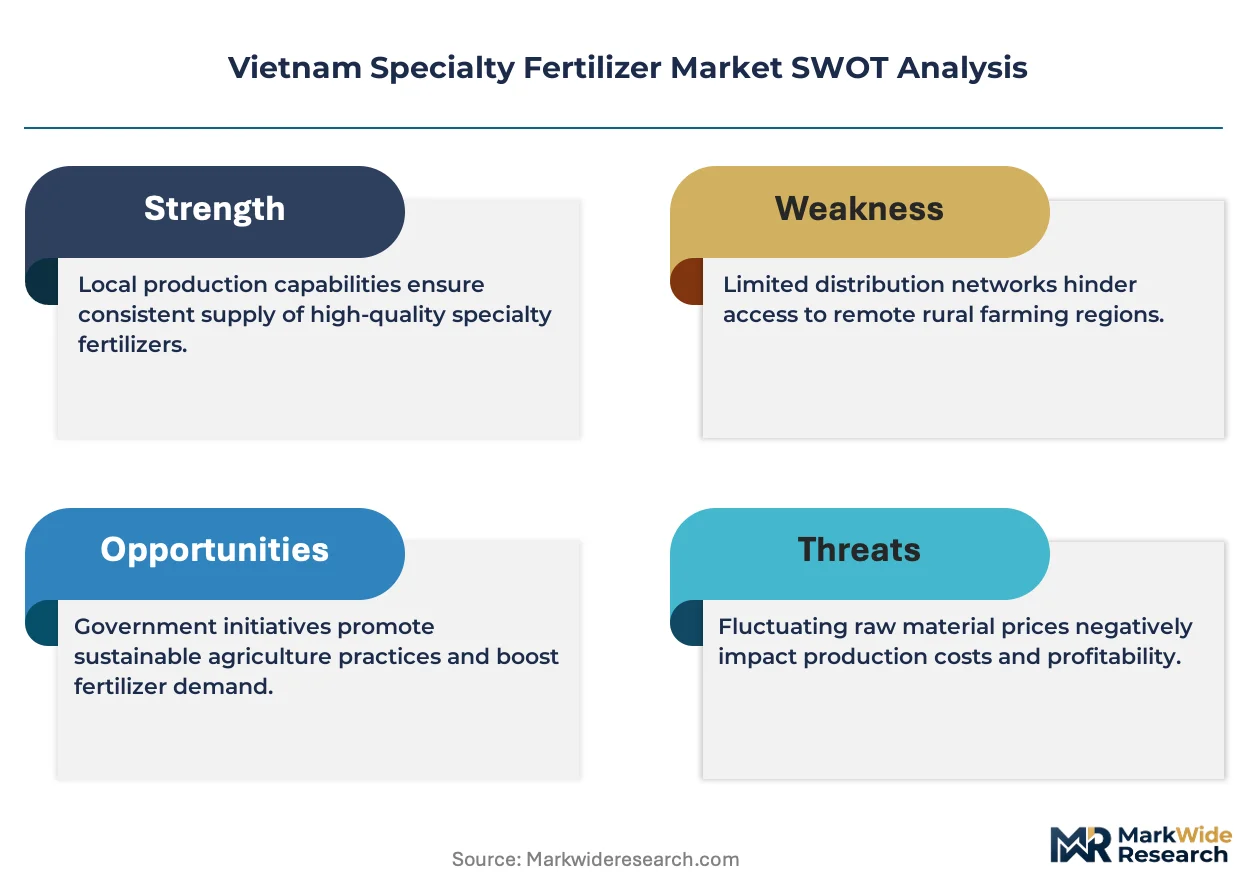
- Import feedstock volatility:PetroVietnam Ca Mau's urea-ammonia complex supplies domestic blending operations, but international ammonia price swings compress margin predictability for downstream compounders.
- Registration timeline friction:BIS-equivalent standards administered by the Vietnam Directorate for Standards, Metrology and Quality extend product clearance timelines, freezing working capital for 12-18 months.
- Organic substitute encroachment:Residue-free export crop requirements are widening shelf space for organic fertilizers in retail channels, pressuring synthetic specialty share in certain vegetable segments.
Strategic Opportunities
- Central Highlands coffee belt:Micronutrient-deficient soils in Dak Lak and Lam Dong provinces require targeted nutrient delivery systems where technical agronomy services can anchor premium positioning.
- Bio-fertilizer efficacy testing circular:MARD's pending protocol will redistribute competitive advantage between microbial inoculant developers and conventional compounders, creating first-mover windows for validated biological products.
- Integrated distribution networks:Southern province coverage gaps present consolidation targets for operators able to merge warehousing, technical service, and credit extension capabilities.
Industry Challenges
- Agronomist talent scarcity:Technical sales and field advisory functions require personnel capable of diagnosing micronutrient deficiencies in tropical acid soils, a skill set concentrated among legacy state-enterprise veterans.
- Coating technology capex:Polymer-controlled-release manufacturing demands specialized granulation and coating equipment that domestic blenders must import or license, raising scale thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Specialty Fertilizer Market |
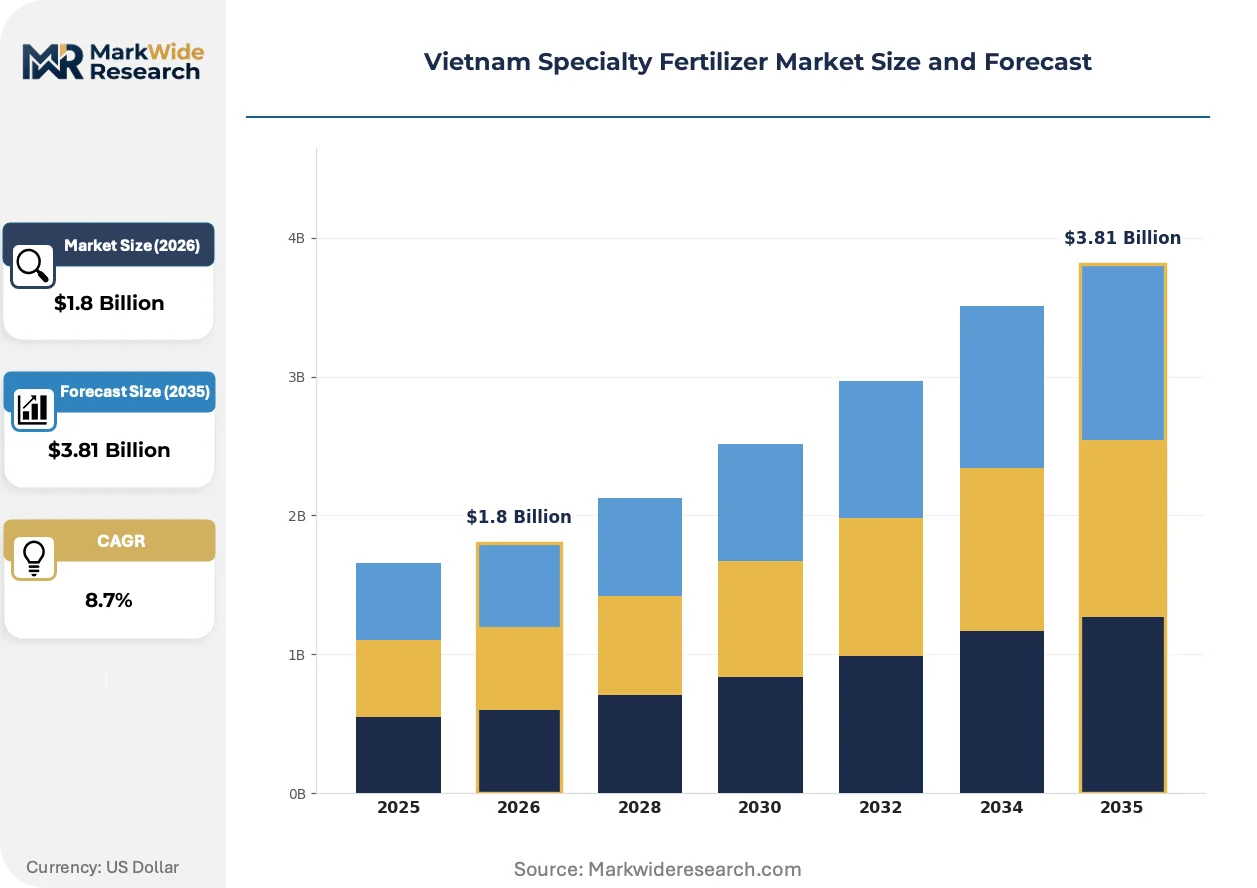
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fertilizers, Inorganic Fertilizers, Bio-Fertilizers, Controlled-Release Fertilizers Application: Agricultural Crops, Horticultural Crops, Turf and Ornamentals, Landscaping Form: Granular, Liquid, Powder, Pelletized Delivery Mode: Soil Application, Foliar Application, Fertigation, Seed Treatment |
| Companies Covered | Baconco, Haifa Group, Yara International ASA, Binh Dien Fertilizer, Hebei Sanyuanjiuqi Fertilizer Co. Ltd., ICL Group Ltd, Duc Giang Chemicals Group, PetroVietnam Ca Mau Fertilizer, Grupa Azoty S.A. (Compo Expert), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Specialty Fertilizer Market Evolving Landscape
Formulation science and regulatory precision are converging to displace commodity fertilization practices across Vietnam's export-oriented crop sectors, with technology adoption pacing diverging sharply between Mekong Delta intensive systems and Central Highlands perennial plantations.
Polymer-coated controlled-release granules are rewriting nutrient management economics in dragon fruit and pepper operations. Large horticultural estates in Binh Thuan and Gia Lai are retrofitting application equipment to accommodate these formulations. The technology is compressing seasonal labor demand and reducing leaching losses in high-rainfall tropical conditions.
Decree 108/2021/ND-CP's implementation is forcing product reformulation across the registration pipeline. Heavy metal limit compliance and Vietnamese-language labeling disclosures are disqualifying legacy import portfolios. Domestic manufacturers with captive laboratory testing capacity are accelerating registration cycles relative to import-dependent competitors.
Farmer buying committees in the Mekong Delta are consolidating procurement through district-level cooperatives that negotiate volume pricing and technical service bundles. Independent retail channels in An Giang and Can Tho are losing share to these consolidated purchasing entities. Vegetable export cooperatives in these provinces are driving the fastest adoption of liquid fertigation-compatible formulations.
Vietnam Specialty Fertilizer Market Segmentation
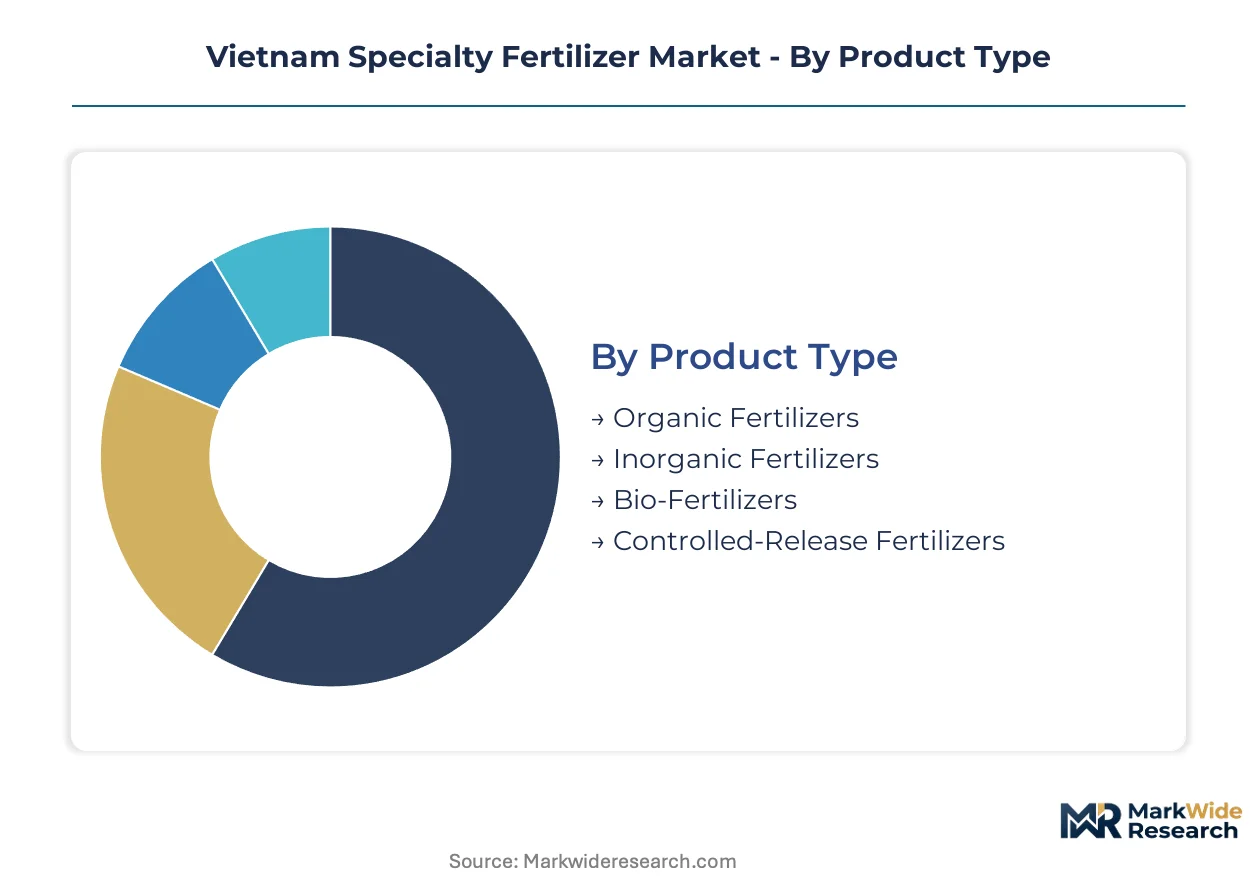
Vietnam's specialty fertilizer market fragments across four structural dimensions that determine margin capture, technical service intensity, and registration pathway complexity. Product type governs raw material sourcing and MARD compliance burden. Application and form dictate distribution channel selection and farmer advisory requirements.
Product Type:
The customization-standardization spectrum runs widest here, from commodity-scale inorganic compounds to bespoke bio-fertilizer formulations requiring strain validation.
- Controlled-Release Fertilizers:Polymer-coated or sulfur-coated granules that meter nutrient release against soil temperature and moisture. Dragon fruit estates in Binh Thuan and pepper plantations in Gia Lai are retrofitting equipment for these formulations where labor savings and leaching reduction justify 40-60% price premiums over conventional compounds.
- Bio-Fertilizers:Microbial inoculants containing nitrogen-fixing bacteria, phosphate-solubilizing fungi, or plant growth-promoting rhizobacteria. MARD's pending efficacy testing circular is freezing registration pipelines for unvalidated strains while creating first-mover windows for developers with captive laboratory capacity in Ho Chi Minh City.
- Organic Fertilizers:Composted agricultural residues, vermicompost, or processed manure meeting residue-free export standards. Retail channels in the Mekong Delta are widening shelf space as vegetable cooperatives seek EU and US market access.
- Inorganic Fertilizers:Chelated micronutrient compounds and water-soluble NPK formulations for targeted deficiency correction. PetroVietnam Ca Mau's urea-ammonia complex supplies domestic blenders with feedstock for downstream specialty compounding.
Most installed capacity flows through Inorganic Fertilizers. Expansion is steepest in Controlled-Release Fertilizers.
Application:
Cost tier separation is pronounced, with export-oriented horticultural operations absorbing premium formulations while subsistence rice cultivation relies on subsidized commodity inputs.
- Horticultural Crops:Intensive systems producing dragon fruit, pepper, coffee, and vegetables for export markets. The Central Highlands coffee belt and Mekong Delta vegetable zones concentrate demand for micronutrient-targeted delivery systems where technical agronomy services anchor supplier selection.
- Agricultural Crops:Commercial rice cultivation in the Mekong Delta and maize production in northern provinces. Baconco's integrated southern distribution network dominates volume supply through district-level cooperative procurement committees.
- Turf and Ornamentals:Golf course maintenance and nursery stock production around Ho Chi Minh City and Hanoi. Controlled-release formulations reduce seasonal labor peaks in high-amenity settings.
- Landscaping:Municipal parks, highway verges, and commercial property maintenance. Price sensitivity limits specialty penetration relative to horticultural applications.
Revenue concentration sits with Horticultural Crops. Volume scale favors Agricultural Crops.
Form:
Supply concentration patterns diverge sharply, with liquid formulations requiring dedicated blending infrastructure and granular products leveraging existing compounder assets.
- Liquid:Fully soluble concentrates and suspensions for fertigation systems. Mekong Delta vegetable operations with dense drip irrigation infrastructure are accelerating uptake where precise nutrient delivery matches intensive production schedules.
- Granular:Standard prilled or compacted products for broadcast or banded application. Domestic manufacturers with rotary drum granulation lines supply the bulk of rice cultivation demand.
- Powder:Fine-ground formulations for foliar spraying or suspension in irrigation water. Limited shelf stability constrains distribution radius.
- Pelletized:Densified products for precision placement or controlled-release coatings. Coating technology capex requirements restrict domestic production to licensed or imported equipment.
Manufacturing asset utilization runs highest for Granular. Technical service margins peak with Liquid.
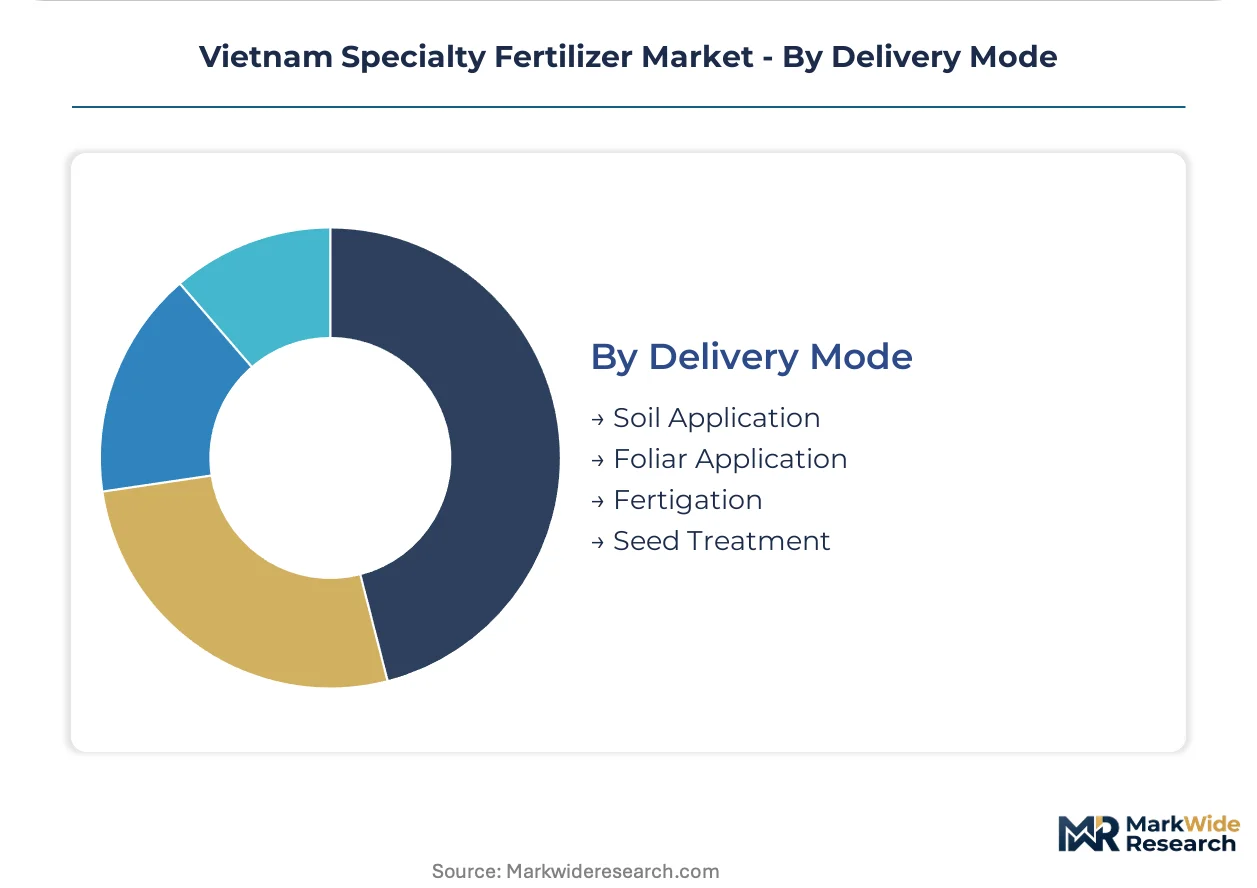
Delivery Mode:
Customer sophistication thresholds determine adoption sequencing, with fertigation requiring capital investment and soil application remaining accessible to smallholders.
- Fertigation:Nutrient delivery through irrigation water in pressurized systems. An Giang and Can Tho vegetable export cooperatives are driving fastest adoption where infrastructure density supports precision agriculture economics.
- Soil Application:Broadcast, banding, or placement of solid or liquid products at root zone. Dominates rice cultivation where flood irrigation precludes fertigation.
- Foliar Application:Micronutrient sprays for rapid deficiency correction in high-value crops. Timing-critical applications require technical advisory support.
- Seed Treatment:Microbial inoculants or micronutrient coatings applied pre-planting. Limited penetration outside commercial maize and vegetable seed markets.
Transaction volume concentrates in Soil Application. Value capture rates are climbing fastest in Fertigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomist talent scarcity concentrates in legacy state-enterprise veterans across southern provinces, anchoring technical service capabilities in the Mekong Delta and Central Highlands corridors.
Mekong Delta
Commercial rice growers and intensive vegetable systems drive specialty fertilizer uptake through district-level cooperative procurement committees. MARD's Decree 108/2021/ND-CP streamlines compliance for registered operators while filtering low-grade competitors via heavy metal limits. An Giang and Can Tho vegetable export cooperatives accelerate liquid fertigation-compatible formulation adoption where infrastructure density supports precision agriculture.
Central Highlands
Coffee belt operations in Dak Lak and Lam Dong provinces require targeted nutrient delivery systems for micronutrient-deficient tropical acid soils. BIS-equivalent standards administered by the Vietnam Directorate for Standards, Metrology and Quality extend product clearance timelines for import-dependent blenders. Gia Lai pepper plantations retrofit application equipment for controlled-release granules where labor savings justify price premiums.
Southeast Region
Dragon fruit estates in Binh Thuan province displace conventional compounds with polymer-coated formulations that compress seasonal labor demand. The Ministry of Agriculture and Rural Development's pending bio-fertilizer efficacy testing circular redistributes competitive advantage between microbial inoculant developers. Ho Chi Minh City anchors captive laboratory capacity for strain validation and accelerated registration cycles.
Red River Delta
Maize production and peri-urban vegetable cultivation concentrate demand for chelated micronutrient compounds. National fertilizer registration protocols enforce Vietnamese-language labeling disclosures that disqualify legacy import portfolios. Hanoi-area retailers widen organic fertilizer shelf space as residue-free export requirements reshape farmer procurement patterns.
South Central Coast
Horticultural diversification into high-value crops drives technical advisory service requirements. PetroVietnam Ca Mau's urea-ammonia complex supplies domestic blenders with feedstock for downstream specialty compounding. Phu Yen and Khanh Hoa provinces present consolidation targets for operators merging warehousing, technical service, and credit extension capabilities.
Vietnam Specialty Fertilizer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Vietnam's specialty fertilizer landscape. State-linked petrochemical groups leverage captive feedstock supply while international agronomy service providers anchor premium micronutrient portfolios. Three archetypes dominate: integrated domestic manufacturers with distribution networks, import-dependent technical service specialists, and microbial inoculant developers awaiting regulatory clarity. Competitive moves concentrate on registration cycle acceleration and southern province distribution consolidation.
Among integrated domestic operators, Baconco and PetroVietnam Ca Mau Fertilizer exemplify the manufacturing-scale archetype with southern province coverage. Yara International ASA occupies a position representing the premium technical service tier. These three entities anchor distinct competitive vectors within a market reshaped by MARD's tightened quality certification requirements.
| Leading Market Players |
|---|
| Baconco |
| Haifa Group |
| Yara International ASA |
| Binh Dien Fertilizer |
| Hebei Sanyuanjiuqi Fertilizer Co. Ltd. |
| ICL Group Ltd |
| Duc Giang Chemicals Group |
| PetroVietnam Ca Mau Fertilizer |
| Grupa Azoty S.A. (Compo Expert) |
| Others |
Value Network & Pricing Analysis
Ammonia feedstock costs from PetroVietnam Ca Mau's urea-ammonia complex cascade through three distinct pricing tiers, with polymer-coated controlled-release granules commanding 40-60% premiums over conventional compounds while uncoated inorganic fertilizers compete on thin margins in rice procurement committees.
Pricing Analysis
Technical service bundling separates premium micronutrient portfolios from commodity-grade alternatives. Price differentiation rests on MARD certification grade and after-sales agronomy support intensity. Pricing pressure intensifies in standard-tier inorganic compounds as import-dependent blenders absorb BIS-equivalent testing costs. District-level cooperatives in the Mekong Delta exhibit highest price sensitivity, while Central Highlands coffee estates prioritize performance over unit economics.
Supply Chain Analysis
Decree 108/2021/ND-CP's heavy metal limits and Vietnamese-language labeling requirements gatekeep import clearance, favoring domestic manufacturers with captive laboratory capacity. Raw material sourcing draws from China's sulfur and polymer coating inputs, Australia's chelated micronutrient compounds, and domestic ammonia from Ca Mau. Single-source vulnerability concentrates in specialized coating equipment imports. Distribution runs through Baconco's integrated southern network and Yara's technical service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's specialty fertilizer market has entered a late-cycle quality phase where Decree 108/2021/ND-CP's tightened certification requirements favor operators with validated product portfolios and captive testing infrastructure over import-dependent competitors.
For Market Incumbents: To counter registration timeline friction from BIS-equivalent standards, accelerate captive laboratory investment in Ho Chi Minh City and secure backward integration into polymer coating technology. Anchor premium positioning through technical agronomy talent retention, as agronomist scarcity concentrates among legacy state-enterprise veterans.
For New Entrants and Emerging Players: The 40-60% price gap between controlled-release premium tiers and economy-grade inorganic compounds opens entry paths through mid-tier bio-fertilizer formulations awaiting MARD's pending efficacy testing circular. Target Gia Lai pepper plantations and An Giang vegetable cooperatives with liquid fertigation-compatible products. Lead with district-level cooperative procurement relationships rather than retail channel displacement.
For Investors and Strategic Acquirers: Consolidation pressure builds where southern province distribution networks remain fragmented and technical service capabilities are concentrated among aging personnel. Five-to-ten year viability favors operators merging warehousing, credit extension, and field advisory functions. Monitor MARD's bio-fertilizer efficacy testing circular as the signal for microbial inoculant developer valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Technology | Captive polymer granulation capacity reduces import equipment dependency and accelerates controlled-release product cycles. |
| Captive Laboratory Investment | Ho Chi Minh City testing facilities compress MARD registration timelines relative to import-dependent competitors. |
| Technical Agronomy Service Expansion | Field advisory capabilities anchor premium positioning in Central Highlands coffee belt micronutrient-deficient soils. |
| District Cooperative Procurement Partnerships | Consolidated buying committees in An Giang and Can Tho displace independent retail channel share. |
| Bio-Fertilizer Strain Validation | Pending MARD efficacy testing circular creates first-mover windows for validated microbial inoculant portfolios. |
Research Methodology
Direct dialogue with MARD registration officials, agronomists at state-enterprise veterans, district cooperative procurement managers, and downstream blending plant operators grounded qualitative findings in operational reality. Secondary validation drew from Decree 108/2021/ND-CP regulatory filings, Vietnam Directorate for Standards, Metrology and Quality certification records, customs trade data on coating polymer imports, and PetroVietnam Ca Mau feedstock supply disclosures. Bottom-up and top-down triangulation cross-checked volume estimates against regional cultivation area data and input intensity benchmarks.
Bottom-up modeling built product-level forecasts across controlled-release, bio-fertilizer, organic, and inorganic categories, then aggregated through application intensity coefficients for horticultural versus agricultural crop segments. Top-down verification anchored aggregate market size against national fertilizer consumption statistics and specialty product penetration rates. CAGRs were derived from regression analysis of historical uptake curves in Mekong Delta vegetable systems and Central Highlands coffee belt expansion. Key inputs included fertigation infrastructure deployment rates and MARD registration pipeline velocity.
Caveats apply where international ammonia price volatility, delays in MARD's bio-fertilizer efficacy testing circular, or shifts in EU residue-free export requirements could materially shift the outlook. A model refresh is warranted upon material change in Decree 108/2021/ND-CP implementation enforcement or PetroVietnam Ca Mau's feedstock pricing policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South Africa Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Polymer Coated Fertilizer Market