
 Brazil Micronutrient Fertilizer Market | 2026-2036
Brazil Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Micronutrient Fertilizer Market Outlook
Specialty-grade chelated micronutrient formulations is redrawing competitive boundaries in Brazil's fertilizer sector. ICL Group Ltd leverages its global micronutrient technology portfolio to anchor premium positioning among large-scale soybean and corn operations. Yara International AS sustains extensive distribution reach through its Brazilian subsidiary network, while Haifa Group specializes in water-soluble and foliar-applied micronutrient systems for high-value fruit and vegetable segments.
Brazil micronutrient fertilizers are inorganic or organically complexed mineral compounds containing essential trace elements such as iron, zinc, manganese, and copper, typically applied at rates of 0.5 to 5 kg per hectare to correct plant physiological disorders and optimize enzymatic functions. Their primary commercial purpose centers on remedying widespread soil deficiencies in tropical and subtropical agricultural zones where intensive cultivation has depleted native micronutrient reserves. Zinc-based products occupy the largest volume share given endemic deficiency across Brazil's Cerrado and Atlantic Forest biome farmlands, while liquid formulations represent the fastest-expanding form category as growers retrofit existing sprayer fleets for in-season micronutrient topdressing. Cereals dominate application volumes due to massive soybean and corn planted areas, though fruits command superior per-hectare micronutrient spending intensity.
ANVISA regulates fertilizer product registration and safety standards under Brazil's national chemical substance framework, while MAPA enforces agronomic efficacy claims and quality specifications for domestic and imported micronutrient products. The Central Bank of Brazil and BNDES influence sector liquidity through rural credit allocation policies that subsidize precision agriculture input purchases. Stakeholders must monitor pending regulatory harmonization between Mercosur member states, as divergent micronutrient labeling and concentration standards threaten to fragment cross-border supply chains and complicate manufacturer compliance portfolios.
Market Dynamics
Precision agriculture retrofitting across Brazil's Center-West is compressing application windows and forcing micronutrient suppliers to integrate with existing sprayer fleets. This hardware-software convergence is restructuring how growers procure, time, and verify micronutrient efficacy.
Growth Catalysts
- ANVISA Registration Harmonization:Tighter quality protocols under Brazil's national chemical substance framework are filtering out substandard imports and elevating certified domestic manufacturers.
- Soybean Yield Correction:Intensive cultivation across Mato Grosso has depleted native zinc and manganese reserves, compelling growers to adopt systematic micronutrient topdressing protocols.
- Liquid Formulation Compatibility:Water-soluble chelates integrate directly with existing aerial and ground-based sprayer infrastructure, eliminating capital expenditure barriers to adoption.
Market Restraints
- Import Dependency Concentration:Specialty-grade chelated intermediates concentrate in Chinese and Israeli manufacturing clusters, exposing Brazilian blenders to currency volatility and shipping disruptions.
- Phosphate Rock Cost Pass-Through:Micronutrient carriers and complexing agents track phosphate fertilizer input costs, compressing margin stability during commodity spikes.
- Soil Test Interpretation Variability:Inconsistent laboratory calibration across Brazil's agricultural extension network generates uncertainty in prescription rates and delays purchase decisions.
Strategic Opportunities
- BNDES Precision Agriculture Credit Lines:Subsidized rural financing for retrofitting sprayers with variable-rate technology creates pull-through demand for compatible liquid micronutrient systems.
- Integrated Fruit and Vegetable Segments:High-value produce operations in São Paulo's interior and Bahia's São Francisco Valley generate per-hectare spending multiples above commodity crops.
- Mercosur Regulatory Convergence:Pending harmonization of micronutrient labeling standards across Argentina, Paraguay, and Uruguay opens cross-border formulation standardization for regional suppliers.
Industry Challenges
- Agronomic Prescription Expertise Gap:Field-level capacity to interpret tissue tests and calibrate variable-rate application remains scarce outside Brazil's southern research corridor.
- ANVISA-MAPA Dual Registration Timelines:Sequential safety and agronomic efficacy approvals extend product commercialization cycles and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Micronutrient Fertilizer Market |
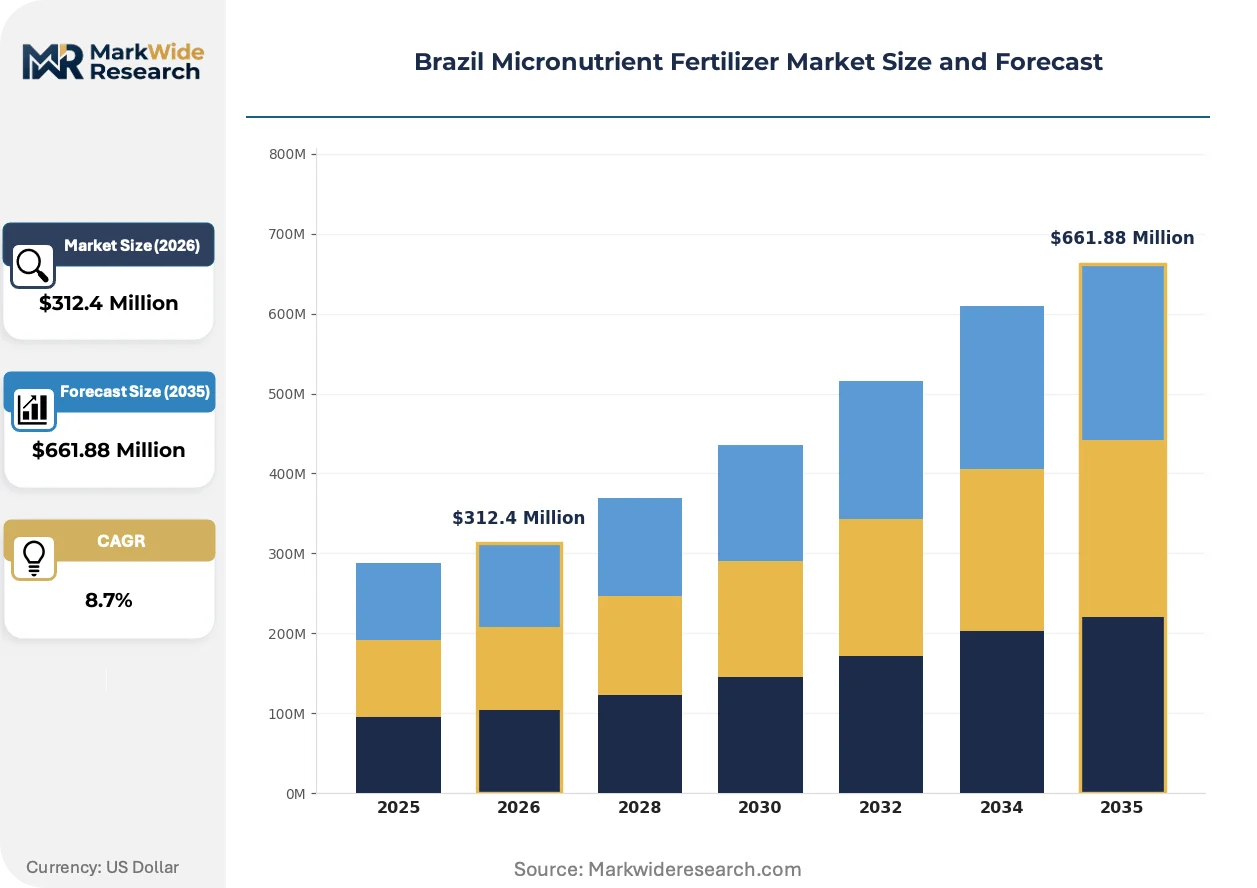
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
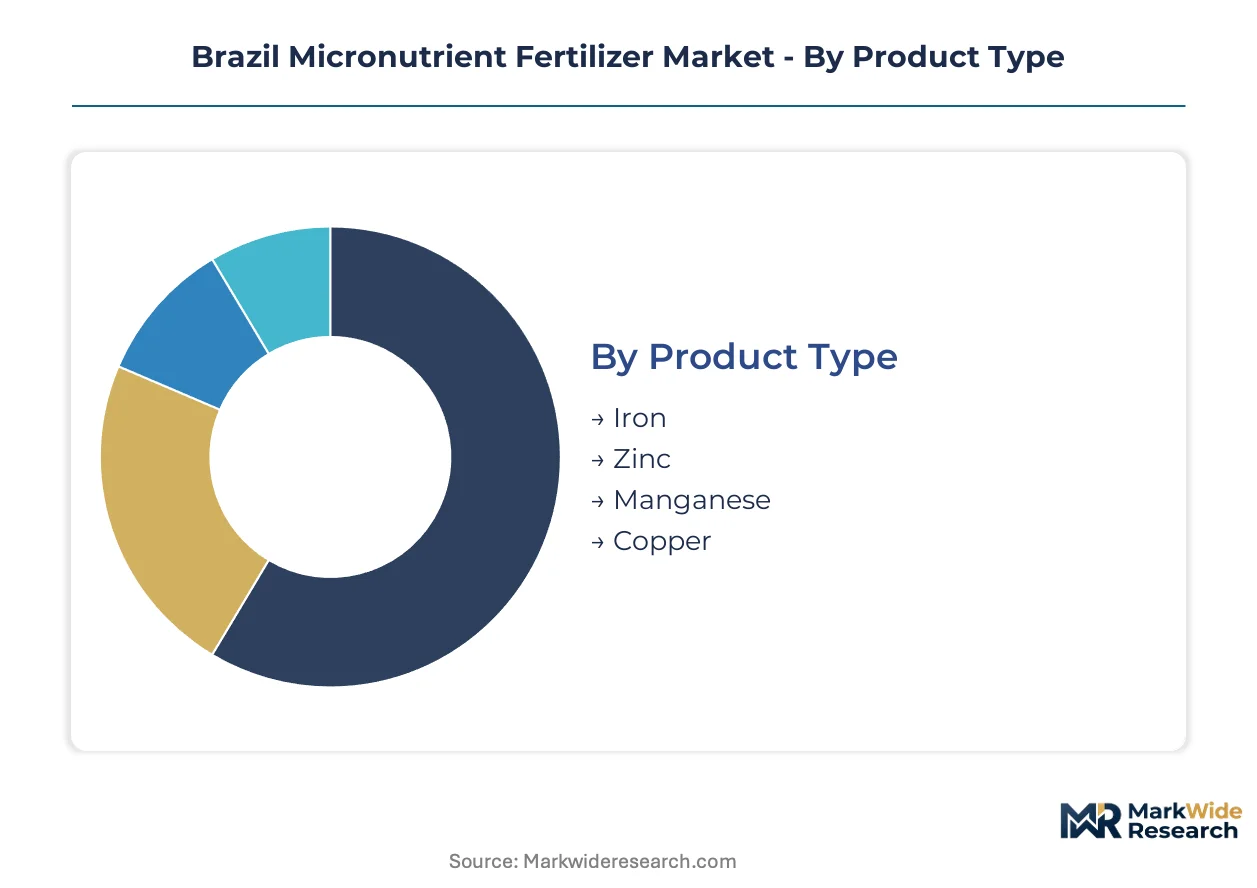
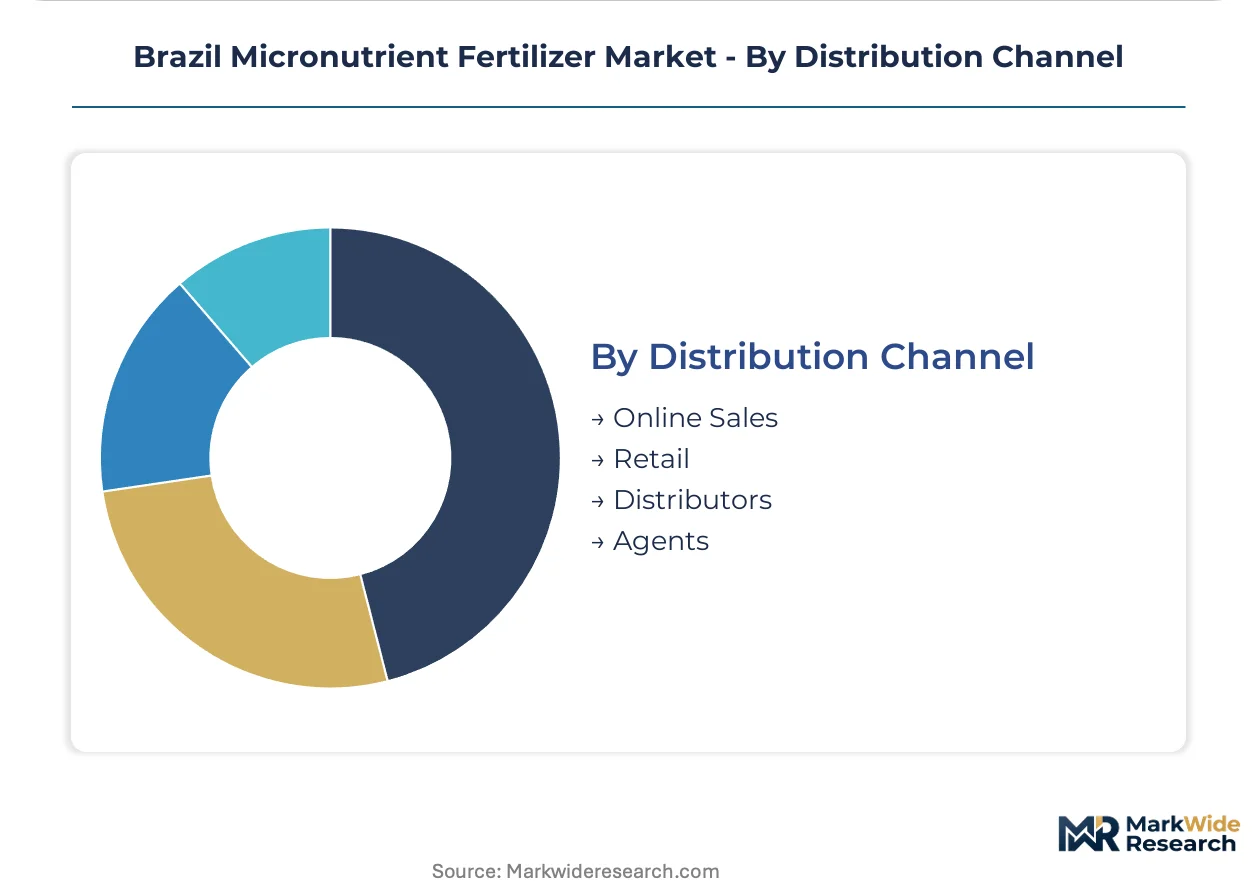
| Segmentation | Product Type: Iron, Zinc, Manganese, Copper Application: Cereals, Fruits, Vegetables, Oilseeds Form: Granular, Liquid, Powder, Suspension Distribution Channel: Online Sales, Retail, Distributors, Agents |
| Companies Covered | K+S Aktiengesellschaft, ICL Group Ltd, Nortox, Grupa Azoty S A (Compo Expert), Haifa Group, The Mosaic Company, Yara International AS, Inquima LTDA, EuroChem Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Micronutrient Fertilizer Market Strategic Shifts
Formulation chemistry and application hardware are converging to enable in-season micronutrient intervention at scale. This integration is compressing the traditional pre-plant fertility window and enabling responsive plant nutrition.
Chelated zinc and manganese complexes utilizing EDTA and EDDHA ligands are supplanting inorganic sulfate salts in high-pH Cerrado soils. Large-scale soybean and corn operations in Mato Grosso and Goiás are adopting these formulations at accelerating rates. The technology is supplanting reactive broadcast applications with targeted, pH-stable delivery that maintains nutrient availability through the critical reproductive growth stages.
ANVISA's evolving fertilizer registration protocols under Brazil's national chemical substance framework are tightening heavy metal limits and mandating batch traceability. Domestic manufacturers and importers must now maintain chain-of-custody documentation from raw material sourcing through final blending. Specialty-grade product categories face the steepest compliance burden, accelerating consolidation among suppliers with dedicated regulatory affairs capabilities.
Service-oriented agronomic support is displacing transactional input sales in Brazil's most sophisticated growing regions. Distributors in Paraná and Rio Grande do Sul are bundling tissue testing, prescription algorithms, and application verification into annual service contracts. This shift concentrates purchasing authority with technical agronomists rather than traditional commodity buyers, rewarding suppliers with integrated decision-support platforms.
Brazil Micronutrient Fertilizer Market Segmentation
Micronutrient fertilizer purchasing in Brazil splits across agronomic requirements, application infrastructure, and channel access. Each segmentation axis reveals distinct margin profiles and competitive dynamics for suppliers navigating the country's diverse agricultural zones.
Product Type:
Zinc and manganese formulations face intensifying substitution pressure from compound NPK blends that incorporate trace elements, forcing standalone micronutrient suppliers to differentiate through chelation technology and application timing precision.
- Zinc:Sulfate and oxide compounds dominate correction protocols for Cerrado soybean operations with endemic deficiency. Mato Grosso growers apply zinc systematically at planting and reproductive stages to prevent yield penalties from hidden hunger.
- Manganese:Chelated EDDHA and EDTA complexes address high-pH soil lockup in Brazil's western agricultural frontier. Goiás corn producers prioritize manganese topdressing during the V4-V6 growth window when enzymatic demand peaks.
- Iron:Ferrous sulfate and chelated formulations correct chlorosis in high-pH irrigated systems. São Paulo citrus orchards represent the concentrated demand node for foliar iron intervention.
- Copper:Sulfate salts and organic complexes remedy deficiency in sandy coastal plain soils. Bahia cocoa and coconut plantations drive specialized copper application protocols.
Zinc anchors the volume base while manganese gains share at the steepest rate.
Application:
Cost tier differentiation separates commodity crop micronutrient spending from high-value produce intensity, with per-hectare outlays varying by an order of magnitude across these segments.
- Cereals:Soybean and corn operations in Mato Grosso, Paraná, and Rio Grande do Sul generate massive absolute tonnage demand. Systematic soil correction programs now embed micronutrients into standard fertility packages for farms exceeding 1,000 hectares.
- Fruits:São Paulo citrus, Bahia mango, and Pernambuco grape operations command premium pricing for water-soluble and foliar-grade formulations. Tissue-test-driven prescription models dominate procurement in this segment.
- Vegetables:Minas Gerais tomato and pepper greenhouses, plus Paraná potato fields, require micronutrient integration with drip irrigation systems. Soluble powder and liquid concentrates predominate given fertigation compatibility requirements.
- Oilseeds:Cotton and sunflower expansion in Bahia's western region creates emerging demand for boron and zinc co-application. Smaller average farm sizes in this segment delay adoption of precision application technology.
Cereals generate the dominant tonnage while fruits exhibit the highest per-hectare spending intensity.
Form:
Application hardware compatibility constraints are reshaping form factor preferences as Brazilian growers retrofit sprayer fleets for in-season intervention.
- Liquid:Water-soluble chelates and true solutions integrate seamlessly with existing aerial and ground-based spray equipment. Center-West soybean operations are converting to liquid systems to enable V4-R2 reproductive stage topdressing without cultivation damage.
- Granular:Coated and compacted granules remain standard for pre-plant incorporation in conventional tillage systems. Southern Brazil's wheat-soybean double-crop rotation sustains granular demand for broadcast application at planting.
- Powder:Crystalline water-soluble grades serve greenhouse and fertigation segments requiring tank-mix precision. São Paulo protected vegetable operations specify powder formulations for automated dosing systems.
- Suspension:High-concentration flowable products bridge granular and liquid categories for specialty topdressing. Paraná corn producers are testing suspension concentrates for late-season foliar manganese delivery.
Granular forms retain the installed base while liquid options are climbing the fastest.
Distribution Channel:
Customer type stratification concentrates technical purchasing authority with agronomists in consolidated retail networks while fragmenting transactional sales through legacy agent structures.
- Distributors:Regional cooperatives and independent input distributors in Mato Grosso and Paraná maintain field agronomist networks that prescribe micronutrient protocols. These intermediaries bundle soil testing, product recommendation, and application services into annual contracts.
- Retail:Company-owned stores and franchise networks of multinational suppliers dominate southern Brazil's more concentrated farm structure. Rio Grande do Sul's smallholder dairy and crop operations rely on retail counter sales with limited technical support.
- Agents:Commission-based independent representatives serve remote expansion zones in Maranhão, Tocantins, and Piauí with sparse physical infrastructure. Credit extension and relationship-based selling predominate in this channel tier.
- Online Sales:E-commerce platforms and direct manufacturer portals are penetrating price-transparent commodity segments. Younger farm managers in São Paulo's interior increasingly comparison-shop standard zinc sulfate grades through digital channels.
Distributor networks capture the volume core while online channels are expanding most quickly in standard product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty-grade chelated intermediates concentrate in Chinese and Israeli manufacturing clusters, yet Brazilian blenders and formulators maintain critical downstream value-add operations across the country's agricultural heartland. ANVISA's tightening registration protocols and BNDES rural credit allocation are reshaping where domestic production capacity expands.
Mato Grosso
Soybean yield correction protocols drive systematic zinc and manganese topdressing across farms exceeding 1,000 hectares. MAPA enforces agronomic efficacy claims for all imported micronutrient products entering through Cuiabá and Rondonópolis distribution corridors. The Sorriso-Sinop agricultural cluster anchors liquid formulation adoption as growers retrofit sprayer fleets for in-season V4-R2 reproductive stage intervention.
São Paulo
Citrus orchards and protected vegetable operations command premium per-hectare spending intensity for water-soluble and foliar-grade formulations. ANVISA's heavy metal limits and batch traceability mandates impose steepest compliance burdens on specialty-grade categories. The São José do Rio Preto citrus belt and Campinas greenhouse cluster concentrate tissue-test-driven prescription procurement models.
Paraná
Wheat-soybean double-crop rotation sustains granular micronutrient demand for broadcast application at planting. Regional cooperatives bundle soil testing, product recommendation, and application services into annual contracts with embedded technical agronomist support. The Cascavel-Toledo corridor exemplifies distributor network consolidation around service-oriented agronomic support displacing transactional input sales.
Bahia
Cotton and sunflower expansion in the western region creates emerging demand for boron and zinc co-application protocols. Smaller average farm sizes delay precision application technology adoption compared to Center-West benchmarks. The São Francisco Valley mango and grape operations generate premium pricing for fertigation-compatible soluble powder formulations.
Rio Grande do Sul
Smallholder dairy and crop operations rely on retail counter sales with limited technical support, fragmenting purchasing authority across legacy agent structures. Company-owned stores and franchise networks dominate the more concentrated southern farm structure. The Passo Fundo agricultural machinery cluster supports gradual precision agriculture retrofitting among mid-scale grain producers.
Brazil Micronutrient Fertilizer Market Competitive Environment
Concentration sits with multinational suppliers possessing dedicated regulatory affairs capabilities and integrated decision-support platforms. Domestic blenders occupy mid-tier positions serving commodity crop volume demand, while specialized importers focus on chelated intermediate distribution. Three archetypes dominate: global technology licensors with premium positioning, regional cooperatives with bundled service contracts, and independent formulators with flexible sourcing. Competitive moves center on ANVISA-MAPA dual registration navigation and BNDES credit-linked precision agriculture partnerships.
Within the global technology tier, ICL Group Ltd and Yara International AS exemplify multinational positioning anchored by extensive distribution infrastructure and micronutrient formulation portfolios. Haifa Group occupies a specialist position representing water-soluble and foliar-applied system providers targeting high-value produce segments. These three entities collectively illustrate how regulatory compliance scale and agronomic service integration separate premium-tier suppliers from commodity blenders in Brazil's evolving micronutrient fertilizer sector.
| Leading Market Players |
|---|
| K+S Aktiengesellschaft |
| ICL Group Ltd |
| Nortox |
| Grupa Azoty S A (Compo Expert) |
| Haifa Group |
| The Mosaic Company |
| Yara International AS |
| Inquima LTDA |
| EuroChem Group |
| Others |
Value Chain & Pricing Dynamics
ANVISA's batch traceability and heavy metal certification protocols simultaneously gate supply qualification and stratify price tiers across Brazil's micronutrient fertilizer sector. Manufacturers must absorb compliance documentation costs from raw material sourcing through final blending, creating automatic price separation between certified domestic producers and uncertified import alternatives.
Pricing Analysis
ANVISA-MAPA dual registration timelines dictate the pricing tier structure across Brazil's micronutrient market. Three-tier pricing structure across premium, standard, and economy levels separates chelated EDDHA complexes from basic sulfate salts and uncertified bulk imports. Price differentiation rests on certification grade and agronomic service bundling rather than raw material costs alone. Cost compression in economy-grade zinc sulfate is intensifying because Chinese import volumes and currency volatility squeeze blender margins. Smallholder operations in Rio Grande do Sul exhibit highest price sensitivity, while São Paulo citrus growers accept premium foliar-grade pricing for tissue-test-validated efficacy.
Supply Chain Analysis
Israeli and Chinese manufacturing clusters for EDTA and EDDHA chelating agents create a chokepoint that Brazilian formulators cannot bypass. Specialty-grade intermediates draw from Haifa, Israel and select coastal Chinese provinces, while phosphate rock carriers hinge on Moroccan and Russian supply. Single-source vulnerability concentrates in Israeli chelate production during regional security disruptions. Distribution runs through Mato Grosso-based cooperatives and Paraná distributor networks that bundle technical agronomy with product delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's micronutrient fertilizer market sits in early-cycle expansion as precision agriculture retrofitting accelerates liquid formulation penetration beyond the Center-West soybean belt. Systematic yield correction protocols now embed micronutrients into standard fertility packages, creating durable adoption tailwinds for suppliers with compatible application technology.
For Market Incumbents: Secure ANVISA regulatory affairs capabilities as a defensive moat against sequential safety and agronomic efficacy approval delays that tie up competitor working capital. Anchor backward integration into chelated intermediate sourcing to reduce exposure to Israeli and Chinese supply concentration. Prioritize BNDES credit-linked precision agriculture partnerships that pull through liquid formulation demand among large-scale Mato Grosso operations. For New Entrants and Emerging Players: ANVISA fast-track registration for water-soluble powder formulations opens immediate white-space access in São Paulo protected vegetable and greenhouse segments. Target Bahia's São Francisco Valley mango and grape operations where fertigation-compatible soluble grades command premium pricing with limited incumbent technical service presence. Pursue digital-first go-to-market positioning through e-commerce platforms that younger farm managers in São Paulo's interior increasingly favor for standard zinc sulfate procurement. For Investors and Strategic Acquirers: Pending Mercosur regulatory harmonization reshapes the acquisition landscape by enabling cross-border formulation standardization for regional suppliers with compliant manufacturing footprints. Long-term viability centers on suppliers with dedicated regulatory affairs capabilities and integrated decision-support platforms rather than commodity blending assets. Monitor ANVISA-MAPA approval timeline compression as the critical inflection signal for working capital efficiency and commercialization speed advantages.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA-MAPA Dual Registration Navigation | Accelerates product commercialization cycles and releases tied-up working capital for faster market entry. |
| Backward Integration into Chelated Intermediates | Reduces currency volatility exposure and Israeli supply concentration risk for Brazilian formulators. |
| BNDES Credit-Linked Precision Agriculture Partnership | Creates pull-through demand for liquid micronutrient systems compatible with variable-rate sprayer retrofits. |
| Digital Channel Development for Standard Grades | Captures price-transparent commodity segments where younger farm managers comparison-shop online. |
| Mercosur Regulatory Convergence Positioning | Enables cross-border formulation standardization across Argentina, Paraguay, and Uruguay for regional scale. |
Study Parameters
Initial hypotheses were tested against primary input from agronomic directors at Mato Grosso cooperatives, ANVISA regulatory affairs specialists, BNDES rural credit officers, and precision agriculture equipment distributors, then refined through secondary validation. Trade data from Brazil's Secretariat of Foreign Trade, MAPA fertilizer registration databases, ANVISA chemical substance filings, and BNDES rural credit disbursement records anchored quantitative sizing. Bottom-up farm-level adoption modeling and top-down sector revenue triangulation converged on segment-level estimates.
Variance decomposition across product type, application crop, formulation chemistry, and distribution channel dimensions structured the analytical framework. CAGRs were derived from fitted adoption curves reflecting sprayer fleet retrofit rates and soil correction protocol penetration. Chelated versus inorganic formulation substitution elasticity and BNDES credit allocation shifts served as industry-specific forecast inputs across the projection horizon.
Decision-makers should treat outputs as directional under assumptions of continued ANVISA enforcement intensity and BNDES precision agriculture credit availability; material deviation in regulatory timelines or rural credit subsidy levels would warrant model refresh. Practitioners should keep alternative scenarios live as Mercosur harmonization negotiations and Israeli supply security conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
South America Fertilizers Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
China Fertilizers Market
Fertilizers
North America Fertilizers Market
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Asia-Pacific Fertilizers Market