
 Blue-Green Algae Fertilizer Market | 2026-2036
Blue-Green Algae Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Blue-Green Algae Fertilizer Market Insights
Modular packaging formats is repositioning buyer choice in the blue-green algae fertilizer space, shifting procurement from bulk sacks toward smaller calibrated units. AlgaEnergy leverages its European biotech infrastructure to sustain premium positioning in liquid concentrate formulations. Coromandel International Limited anchors its South Asian presence through deep distribution networks reaching tier-three farming districts. California Organic Fertilizers, Inc. differentiates via USDA Organic certification and direct-to-grower channel control.
Blue-green algae fertilizer comprises nitrogen-fixing cyanobacterial biomass, typically processed through spray-drying or cold-press extraction to preserve polysaccharide bioactivity, and serves as a slow-release organic nutrient source enhancing soil microbial diversity. Liquid formulations command the widest farmer acceptance due to compatibility with existing drip and foliar application equipment, while granular types retain stronger margins among landscape professionals seeking broadcast-spread compatibility. The horticulture application segment shows the steepest volume trajectory as greenhouse operators replace synthetic feeds with residue-free alternatives ahead of export certification deadlines.
The USDA National Organic Program and the EU Fertilizing Products Regulation jointly constrain permissible input compositions, forcing reformulation of non-compliant preservative additives and driving R&D toward native strain selection. India's FSSAI and BIS standards for organic agricultural inputs create parallel compliance tracks for exporters and domestic suppliers. Stakeholders must monitor evolving strain-registration requirements and build dual-certification capabilities before regulatory divergence hardens into market-access barriers.
Market Dynamics
Modular packaging formats are compressing minimum order sizes and fragmenting procurement authority away from centralized agricultural cooperatives toward individual farm managers.
Growth Catalysts
- EU Fertilizing Products Regulation:Harmonized bio-based nutrient standards across member states reduce cross-border compliance costs for cyanobacterial formulation exporters.
- Rice cultivation intensification:Indian smallholder cooperatives bulk-order microbial formulations to replace synthetic urea in flooded paddy systems.
- Spray-drying process refinement:Cold-press extraction methods now preserve polysaccharide bioactivity at commercial scale.
Market Restraints
- Strain registration bottlenecks:India's FSSAI and BIS parallel compliance tracks create dual-certification burdens for domestic suppliers and exporters.
- Liquid concentrate spoilage:Non-compliant preservative additives force costly reformulation cycles under USDA National Organic Program constraints.
- Synthetic nitrogen substitution:Urea price volatility and subsidized availability in key markets compress organic premium capture.
Strategic Opportunities
- Greenhouse horticulture expansion:Residue-free alternatives displace synthetic feeds ahead of export certification deadlines in protected cropping systems.
- Drip irrigation convergence:Liquid formulation compatibility with existing fertigation infrastructure opens retrofit markets without equipment replacement.
- USDA Organic certification arbitrage:Direct-to-grower channel control bypasses distributor markup layers in specialty crop segments.
Industry Challenges
- Native strain selection timelines:R&D cycles for regulatory-compliant cyanobacterial variants extend product development pipelines.
- Soil microbiome integration complexity:Slow-release nutrient synchronization with existing crop rotation schedules requires agronomic advisory investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue-Green Algae Fertilizer Market |
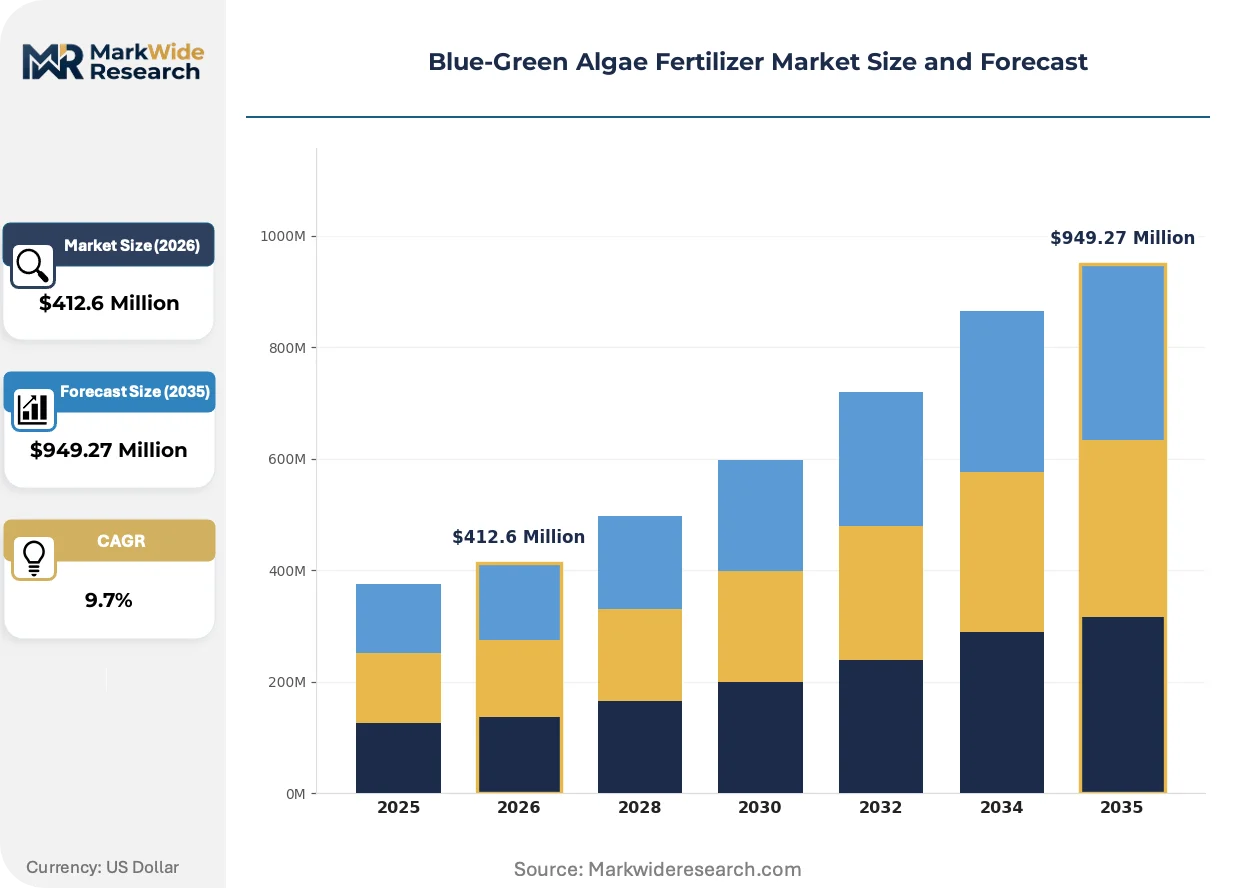
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Tablets Application: Agricultural Crops, Horticulture, Turf, Home Gardens Packaging Type: Bags, Bottles, Drums, Sacks End User: Farmers, Commercial Growers, Homeowners, Landscape Professionals |
| Companies Covered | AlgaEnergy, Algenol, Coromandel International Limited, LidoChem, Inc., Grace Breeding Ltd, The Fertilisers And Chemicals Travancore Limited, MADRAS FERTILIZERS LIMITED, California Organic Fertilizers, Inc., ALGAE Biotecnologia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue-Green Algae Fertilizer Market Trends and Innovations
Bioprocessing advances and regulatory harmonization are compressing time-to-market for certified organic inputs while fragmenting traditional bulk procurement patterns.
Lyophilization technology is integrating into commercial-scale biomass preservation workflows. Premium greenhouse operators in the Netherlands and Spain adopt freeze-dried concentrates for precision dosing in closed hydroponic systems. This preservation method is integrating high-value horticulture segments with pharmaceutical-grade supply chain disciplines.
REACH-compliant strain documentation requirements now mandate full toxicological dossiers for cyanobacterial products entering European distribution. Formulators must maintain living cell banks with traceable genetic provenance. Liquid concentrate exporters to Germany and France face the steepest compliance ramps.
Cooperative buying patterns are fragmenting as California specialty crop producers bypass agricultural supply retailers through direct manufacturer relationships. Tier-three farming districts in India retain cooperative structures, creating divergent channel architectures. Certification-driven preference shifts are most visible in export-oriented vegetable clusters facing residue testing protocols.
Blue-Green Algae Fertilizer Market Segmentation
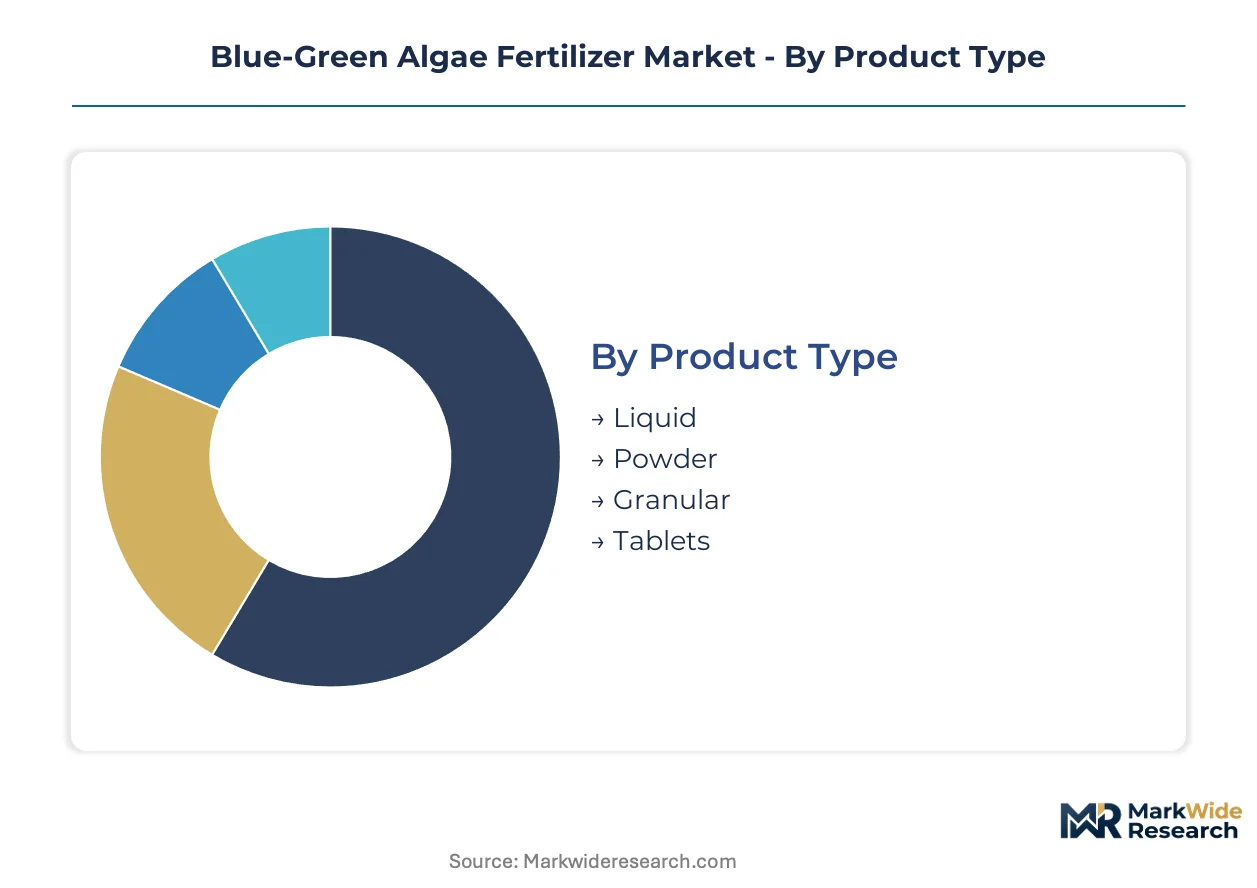
Blue-green algae fertilizer markets fragment across formulation physics, application intensity, and procurement scale. Each segment carries distinct certification burdens and channel economics that reshape competitive positioning.
Product Type:
USDA National Organic Program and EU Fertilizing Products Regulation impose divergent preservative constraints on each formulation state, with liquid concentrates facing the steepest additive scrutiny.
- Liquid:Cold-press extracted concentrates compatible with drip and foliar application equipment. Demand concentrates among California specialty crop producers replacing synthetic feeds ahead of export certification deadlines, though non-compliant preservative additives force costly reformulation cycles.
- Powder:Spray-dried cyanobacterial biomass processed to preserve polysaccharide bioactivity. Indian smallholder cooperatives bulk-order powder formulations for flooded paddy systems where synthetic urea substitution drives procurement.
- Granular:Compressed biomass suited to broadcast-spread compatibility. Landscape professionals seeking mechanical application efficiency anchor this segment's margin structure.
- Tablets:Precision-dosed units for home garden and small-scale horticulture. Netherlands and Spain greenhouse operators adopt freeze-dried tablet variants for closed hydroponic systems.
Leading the category by volume: Liquid. Growing fastest: Powder.
Application:
End-use intensity determines margin capture, with residue-testing protocols in export corridors creating premium pricing tiers for certified organic inputs.
- Agricultural Crops:Rice cultivation intensification in India drives bulk microbial formulation orders for flooded paddy systems. Smallholder cooperatives negotiate volume discounts that compress per-unit margins.
- Horticulture:Greenhouse operators in protected cropping systems face the steepest residue-free substitution pressure. Export certification deadlines accelerate synthetic feed displacement.
- Turf:Sports field and golf course maintenance contracts specify broadcast-spread compatible inputs. Landscape professionals retain stronger pricing power in this segment.
- Home Gardens:Modular packaging formats fragment procurement authority toward individual consumers. Direct-to-grower channel control bypasses distributor markup layers.
Volume concentration: Agricultural Crops. Margin expansion: Horticulture.
Packaging Type:
Container economics and handling infrastructure shape regional preference, with bulk formats dominating cooperative procurement and calibrated units penetrating direct sales.
- Bags:Flexible packaging for powder and granular formulations. Tier-three farming districts in India retain cooperative structures favoring bulk bag procurement.
- Bottles:Liquid concentrate containment for retail and direct channels. California specialty crop producers bypass agricultural supply retailers through bottle-format manufacturer relationships.
- Drums:Intermediate bulk containers for commercial growers. REACH-compliant strain documentation requirements add compliance overhead to drum shipments entering European distribution.
- Sacks:Woven polypropylene for large-volume agricultural supply. Minimum order sizes compress as modular formats fragment procurement authority.
Cooperative procurement anchor: Sacks. Channel shift target: Bottles.
End User:
Customer scale determines advisory intensity and certification complexity, with commercial operations demanding dual-certification capabilities and homeowners prioritizing ease-of-use.
- Farmers:Smallholder cooperatives in India bulk-order microbial formulations. India's FSSAI and BIS parallel compliance tracks create dual-certification burdens for suppliers serving this segment.
- Commercial Growers:Greenhouse operators and export-oriented vegetable clusters face residue testing protocols. USDA Organic certification arbitrage opportunities concentrate here.
- Homeowners:Modular packaging and precision-dosed formats dominate. Channel control shifts toward direct manufacturer relationships as retail intermediaries lose share.
- Landscape Professionals:Broadcast-spread compatibility requirements favor granular and powder formulations. This segment retains stronger margins through equipment integration and recurring maintenance contracts.
Fastest volume expansion: Commercial Growers. Margin protection: Landscape Professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in South Asia and Southern Europe while consumption concentrates in export-oriented agricultural zones. Processing infrastructure for cyanobacterial biomass operates at scale in India and Spain, with formulation and distribution networks extending toward premium horticulture markets.
United States
California specialty crop producers drive liquid concentrate procurement for drip irrigation systems. USDA National Organic Program certification requirements constrain preservative additive formulations. The Central Valley vegetable clusters displace synthetic feeds ahead of export residue-testing protocols.
India
Smallholder cooperatives in rice-growing states bulk-order powder formulations for flooded paddy cultivation. FSSAI and BIS parallel compliance tracks create dual-certification burdens for domestic suppliers and exporters. Tamil Nadu and Andhra Pradesh farming districts anchor cooperative procurement structures.
Spain
Greenhouse operators in Almería and Murcia adopt freeze-dried concentrates for closed hydroponic systems. REACH-compliant strain documentation mandates full toxicological dossiers for cyanobacterial products. Protected cropping systems face residue-free substitution pressure ahead of EU export deadlines.
Netherlands
Precision horticulture in Westland and Aalsmeer drives pharmaceutical-grade supply chain adoption for lyophilized biomass. EU Fertilizing Products Regulation harmonizes bio-based nutrient standards across member state distribution. High-value greenhouse clusters integrate freeze-dried tablet variants.
Germany
Organic farming associations in Bavaria and Lower Saxony source certified inputs for cereal and vegetable rotations. ECHA documentation requirements impose steepest compliance ramps for liquid concentrate exporters. Living cell banks with traceable genetic provenance anchor formulation quality assurance.
Blue-Green Algae Fertilizer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation physics and certification tiers. Market structure shows moderate concentration with regional champions anchored in distinct agricultural zones. Three archetypes dominate: integrated agrochemical conglomerates with biotech divisions, dedicated cyanobacterial biotechnology firms, and regional organic input specialists with direct-to-grower channel control. Capacity expansion and regulatory compliance investments represent the dominant competitive moves.
Among biotechnology-focused specialists, AlgaEnergy and Algenol exemplify the premium liquid concentrate archetype with European and North American infrastructure positioning. Coromandel International Limited anchors the South Asian integrated conglomerate tier with deep distribution networks. California Organic Fertilizers, Inc. occupies the regional specialist position with USDA Organic certification and direct channel control in specialty crop segments.
| Leading Market Players |
|---|
| AlgaEnergy |
| Algenol |
| Coromandel International Limited |
| LidoChem, Inc. |
| Grace Breeding Ltd |
| The Fertilisers And Chemicals Travancore Limited |
| MADRAS FERTILIZERS LIMITED |
| California Organic Fertilizers, Inc. |
| ALGAE Biotecnologia |
| Others |
Pricing and Supply Chain Analysis
EU Fertilizing Products Regulation harmonization gates qualified supply access and premium-tier pricing power for cyanobacterial formulation exporters entering member state distribution. REACH-compliant strain documentation mandates compress eligible supplier pools while liquid concentrate spoilage risks force costly reformulation cycles that reshape tier economics.
Pricing Analysis
Margin tightening in liquid concentrates reflects USDA National Organic Program preservative constraints and synthetic urea price volatility in Indian rice-growing states. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy bulk powder formulations separates certification-grade horticulture inputs from commodity agricultural applications. Cost-down pressure on standard-tier products accelerates because smallholder cooperatives negotiate volume discounts that compress per-unit returns. Home garden segments show lowest price sensitivity while Indian paddy system buyers anchor economy-tier procurement.
Supply Chain Analysis
Living cyanobacterial cell banks rest on Indian bioprocessing infrastructure in Tamil Nadu and Andhra Pradesh, Spanish greenhouse formulation capacity in Almería and Murcia, and Dutch precision horticulture supply chains in Westland. Raw material dependencies span certified organic substrate sourcing, pharmaceutical-grade lyophilization equipment, and REACH-compliant toxicological dossier preparation. Single-source vulnerability concentrates in living strain repositories with traceable genetic provenance requirements. Distribution runs through agricultural supply retailers in tier-three Indian districts, direct manufacturer relationships in California specialty crop zones, and cooperative procurement structures in European protected cropping systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into living cell banking and cold-press extraction capacity anchors competitive position in this vertical-integration race. Players pursuing upstream control over native strain selection compress R&D timelines while downstream channel control captures margin from distributor displacement.
For Market Incumbents: Anchor regulatory compliance capabilities through dual-certification investments spanning USDA National Organic Program and EU Fertilizing Products Regulation standards. Defend against modular packaging format fragmentation by deepening direct-to-grower channel relationships in California specialty crop segments. Capacity addition in South Asian bioprocessing infrastructure protects volume exposure to Indian smallholder cooperative procurement consolidation. For New Entrants and Emerging Players: Enter via home garden precision-dosed tablet formats where incumbent distribution presence remains thin and certification burdens moderate. White-space concentrates in freeze-dried concentrate supply for Netherlands and Spain greenhouse operators adopting pharmaceutical-grade supply chain disciplines. Go-to-market leverage rests on modular packaging partnerships with direct e-commerce channels bypassing agricultural supply retailer intermediaries. For Investors and Strategic Acquirers: REACH-compliant strain documentation mandate acceleration is the leading indicator that regulatory compliance capabilities will consolidate toward integrated biotechnology specialists with living cell bank infrastructure. Long-term viability favors acquisition targets possessing dual-certification track records across USDA and EU frameworks, native strain libraries with traceable provenance, and established relationships with export-oriented vegetable clusters facing residue testing protocols. Watch for tier-three farming district cooperative procurement volume shifts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Banking | Living cell repositories with genetic provenance documentation satisfy ECHA toxicological dossier mandates. |
| Dual-Certification Investment | Parallel USDA Organic and EU Fertilizing Products Regulation compliance opens California and European premium horticulture segments. |
| Direct-to-Grower Channel Expansion | Manufacturer relationships with California specialty crop producers bypass distributor markup compression. |
| Lyophilization Capacity Buildout | Freeze-dried concentrate production serves Netherlands and Spain greenhouse precision dosing requirements. |
| Modular Packaging Partnership | Calibrated unit formats fragment procurement authority toward individual farm managers and home garden consumers. |
Research Methodology
Independent corroboration across agricultural cooperative procurement managers, greenhouse operations directors, bioprocessing plant engineers, and regulatory affairs specialists at cyanobacterial formulation suppliers underwrites the qualitative findings. Secondary validation draws from EU Fertilizing Products Regulation implementation guidance, USDA National Organic Program certification databases, FSSAI organic input standards documentation, customs trade data for cyanobacterial biomass movements, and SEC filings of publicly traded agrochemical conglomerates. Bottom-up volume estimates from application segment procurement patterns reconcile with top-down market sizing through iterative triangulation.
Historical reference periods anchor the projection horizon through calibrated base-year consumption patterns across formulation physics, application intensity, and procurement scale dimensions. Segmentation modeling incorporates product type dynamics, end-use certification requirements, packaging format channel economics, and customer scale advisory intensity. CAGRs derive from regression-adjusted growth rate convergence across segment trajectories, with industry-specific inputs including rice cultivation intensification rates in Indian paddy systems, greenhouse protected cropping expansion in Mediterranean export zones, and synthetic nitrogen substitution elasticities under urea price volatility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence between USDA and EU preservative additive standards, strain registration bottleneck escalation in Indian dual-track compliance, and lyophilization equipment supply constraints affecting premium-tier capacity expansion. A small set of named triggers warrants ongoing watch: REACH documentation requirement phase-in timelines, FSSAI enforcement intensity in Tamil Nadu and Andhra Pradesh cooperative procurement zones, and California export residue-testing protocol adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Nano Fertilizer Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
India Urea Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
India Specialty Fertilizer Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market