
 South America Micronutrient Fertilizer Market | 2026-2036
South America Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
South America Micronutrient Fertilizer Market Analytics
Buyer concentration among large-scale soybean and corn operations across Brazil's Mato Grosso and Goias states is consolidating procurement power toward fewer agronomic service providers. Nutrien Ltd leverages its retail distribution network to anchor volume in these consolidated channels. Yara International ASA competes through precision agriculture digital platforms bundled with micronutrient recommendations. Sociedad Quimica y Minera de Chile SA dominates lithium-derived specialty nutrient supply from its Andean extraction base.
South America micronutrient fertilizers are formulated compounds containing essential trace elements—zinc, manganese, iron, copper—typically applied at rates of 0.5 to 5 kilograms per hectare to correct soil deficiencies and optimize enzymatic plant functions. Manufacturing involves sulfate or oxide base materials, with chelation using EDTA or lignosulfonate to enhance bioavailability in alkaline soils. Zinc formulations lead product type demand due to widespread deficiency across Brazilian oxisols, while hydroponics application expands fastest among vegetable producers in Colombia's Sabana de Bogota. Wholesale distribution channels capture the dominant margin pool through volume contracts with cooperatives, though e-commerce penetration accelerates among mid-sized farms seeking direct pricing transparency.
Brazil's Ministry of Agriculture and Livestock fertilizer registration requirements, alongside ANVISA residue monitoring protocols, shape product formulation standards and market access timelines for imported formulations. Argentina's Senasa phytosanitary oversight and Chile's SAG quality certification create additional compliance layers for cross-border suppliers. Stakeholders must monitor evolving chelate approval lists and biofertilizer classification debates that could reclassify competitive positioning across the continent.
Market Dynamics
Consolidation among Brazil's soybean cooperatives is compressing supplier margins and forcing micronutrient formulators toward direct-to-farm digital channels. This buyer-side concentration is restructuring how zinc, manganese, and chelated iron products reach Mato Grosso's large-scale operations.
Growth Catalysts
- Deficiency mapping via satellite imagery:Brazil's agricultural research corporation Embrapa deploys remote sensing to identify zinc-depleted oxisols, triggering precision application mandates across the Cerrado.
- ANVISA residue protocols:Stricter maximum residue limits for food-grade soy exports are compelling farmers toward certified chelate formulations that guarantee compliance with EU import standards.
- Hydroponics expansion in Colombia:Vegetable producers around Bogota are adopting complete micronutrient solutions for greenhouse operations, creating new formulation demand outside traditional row-crop markets.
Market Restraints
- Lithium supply concentration:Specialty lithium-derived nutrients depend on Chilean Atacama extraction, exposing formulators to single-source geopolitical and pricing volatility.
- Sulfate input cost swings:Zinc sulfate and manganese sulfate prices track London Metal Exchange volatility, compressing blender margins during commodity spikes.
- Substitution by foliar biostimulants:Argentine wheat farmers in Buenos Aires province are testing microbial inoculants as partial replacements for chelated iron applications.
Strategic Opportunities
- Underpenetrated Paraguayan soy belt:Eastern Paraguay's expanding cultivation lacks established micronutrient distribution, offering first-mover positioning for direct technical sales teams.
- Uruguay's grassland restoration programs:Government-funded pasture improvement initiatives are specifying copper and zinc formulations for beef productivity gains.
- E-commerce platform integration:Mid-sized Brazilian farms in Goias are bypassing cooperative procurement through ag-tech marketplaces that bundle soil testing with product recommendations.
Industry Challenges
- Chelate registration timelines:Brazil's Ministry of Agriculture and Livestock requires 18-24 month efficacy trials for new EDTA formulations, delaying product launches.
- Soil testing capacity gaps:Agronomic laboratories in Argentina's interior provinces lack equipment to diagnose micronutrient deficiencies, limiting prescription accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Micronutrient Fertilizer Market |
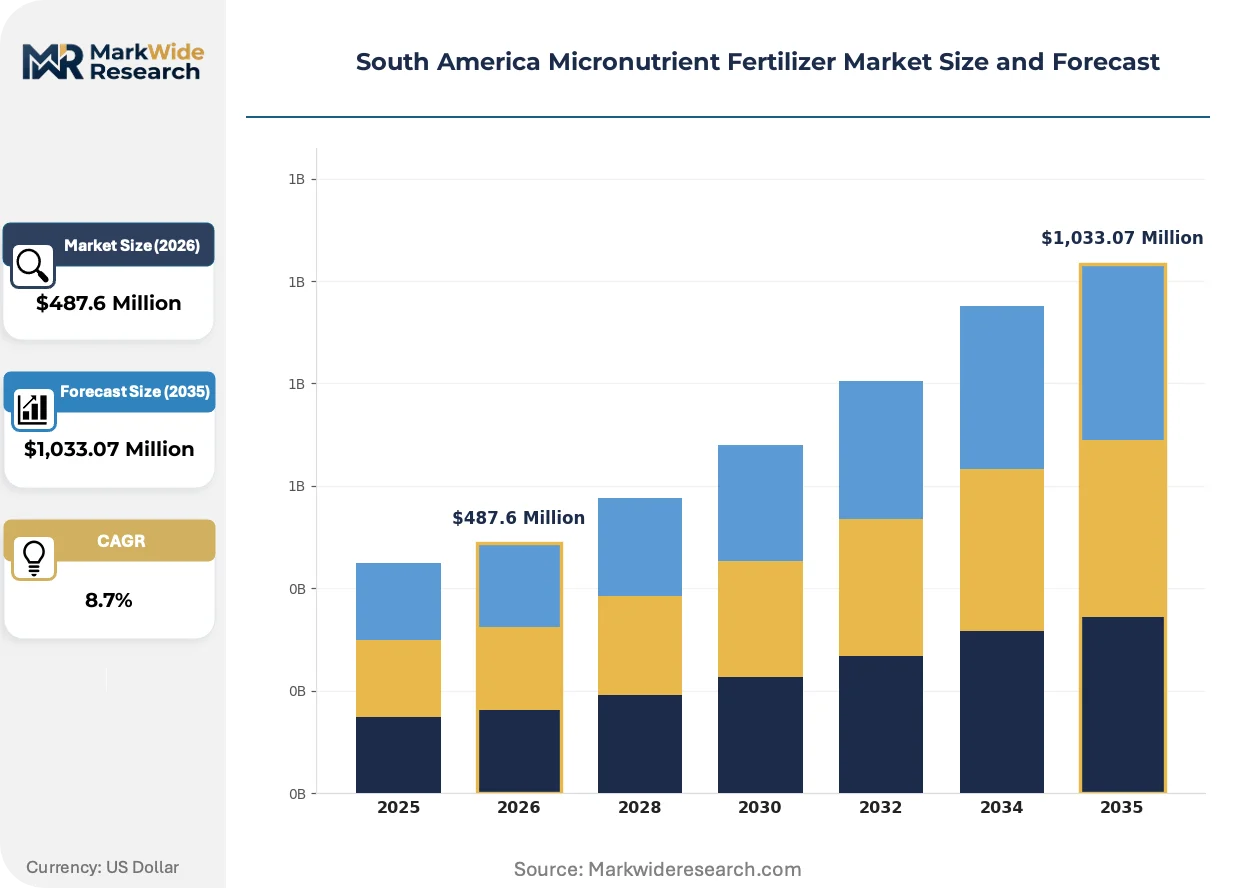
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc, Manganese, Iron, Copper Application: Crops, Turf, Hydroponics, Greenhouses End User: Agriculture, Horticulture, Viticulture, Floriculture Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales |
| Companies Covered | ICL Group Ltd, Sociedad Quimica y Minera de Chile SA, The Mosaic Company, EuroChem Group, Haifa Group, Yara International ASA, K+S Aktiengesellschaft, Nutrien Ltd, Nortox, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Micronutrient Fertilizer Market Evolving Landscape
Digital soil mapping and variable-rate application technologies are compressing the traditional one-size-fits-all approach to micronutrient distribution. Formulators must now integrate hardware partnerships and data services to retain farmer relationships.
Chelated nutrient delivery systems are modularizing around drone-mounted application platforms. Brazil's cotton producers in Mato Grosso are adopting UAV-sprayed zinc formulations at rates below 1 kilogram per hectare. This precision hardware is modularizing service bundles that previously required ground rig deployment, collapsing logistics costs for irregular field geometries.
Argentina's Senasa phytosanitary oversight is tightening documentation requirements for imported micronutrient concentrates. The regulation now mandates batch-level traceability certificates for all cross-border fertilizer shipments. Argentine wheat exporters are responding by specifying domestically blended formulations to avoid customs delays during harvest windows.
Cooperative procurement committees across Brazil's Mato Grosso are unbundling agronomic advisory from product supply. Large soy operations now hire independent soil consultants who specify micronutrient brands through competitive tender rather than accepting bundled cooperative recommendations. This disintermediation is most visible among farms exceeding 5,000 hectares that maintain in-house agronomy teams.
South America Micronutrient Fertilizer Market Segmentation
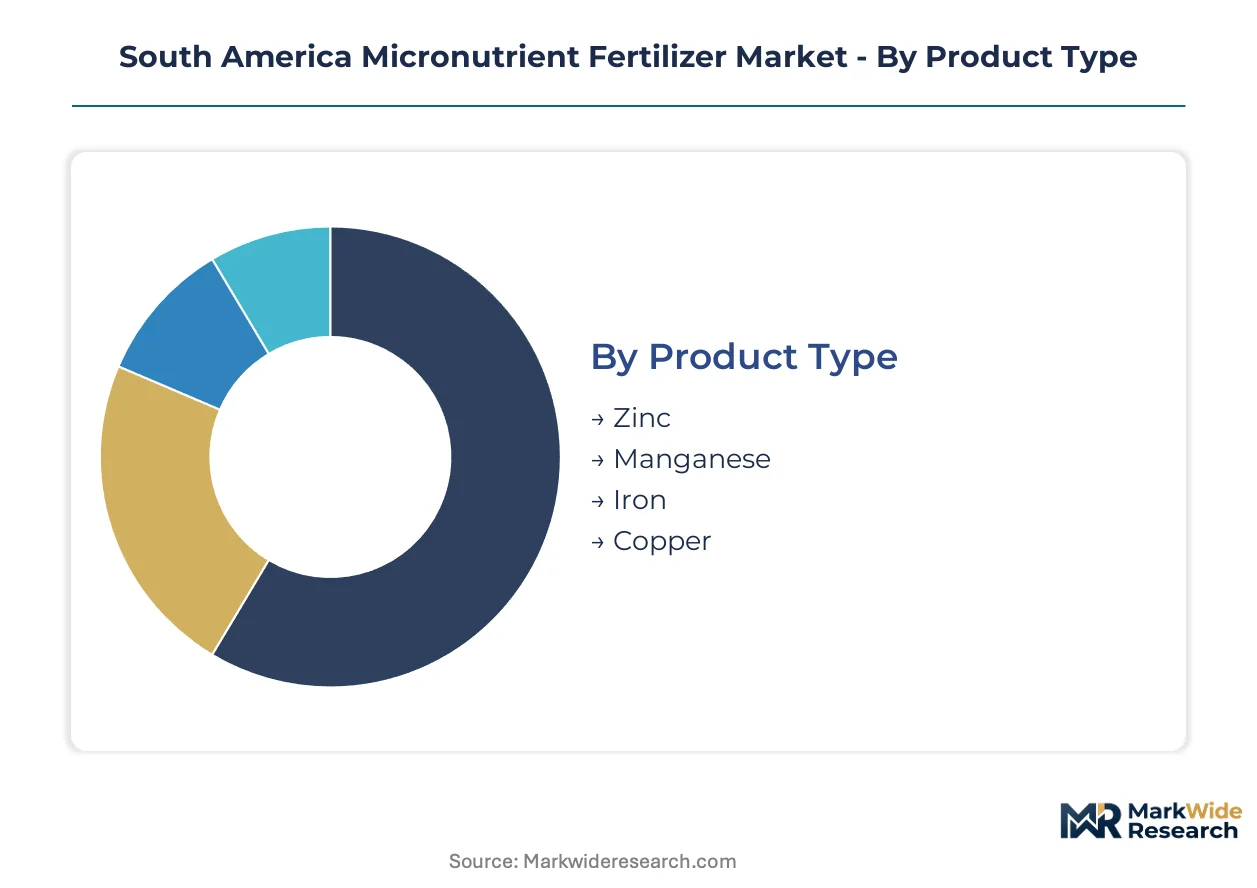
Micronutrient fertilizer segmentation across South America reflects divergent soil chemistries, crop specialization, and procurement channel evolution. Understanding these splits enables suppliers to align formulation investments with where farmer willingness-to-pay is concentrating.
Product Type:
Zinc formulations command the volume tier while copper products capture premium pricing per kilogram applied.
- Zinc:Sulfate and oxide base materials dominate, with EDTA chelation penetrating alkaline oxisols across Brazil's Cerrado. Mato Grosso soybean operations specify zinc at 0.5-2 kg/hectare rates based on Embrapa deficiency mapping.
- Manganese:Demand concentrates in Goias state corn rotations where soil pH above 6.0 locks native manganese. Chelated formulations from lignosulfonate carriers are displacing sulfates where residual sulfate toxicity concerns arise.
- Iron:Chelated iron (EDDHA, EDTA) addresses calcareous soils in Buenos Aires wheat belts; Argentine farmers prioritize yield consistency for export-grade production.
- Copper:Uruguay's grassland restoration programs specify copper for beef productivity; lower volume, higher margin positioning relative to zinc.
Today's leader: Zinc. Tomorrow's challenger: Chelated iron as precision agriculture expands prescription accuracy.
Application:
Crops absorb the tonnage while hydroponics commands formulation complexity premiums.
- Crops:Soybean, corn, and wheat across Brazil and Argentina drive bulk zinc and manganese consumption. Soil-applied formulations at planting dominate, with foliar rescue treatments gaining share in variable-rate zones.
- Hydroponics:Complete micronutrient solutions for greenhouse vegetables in Colombia's Sabana de Bogota require precise ionic balance. Formulators supply concentrated stock solutions calibrated for NFT and drip systems.
- Turf:Sports field and golf course maintenance in Chile's Santiago metro area specifies iron for color response; seasonal application windows limit revenue concentration.
- Greenhouses:Protected cultivation in Ecuador's flower export corridors (roses, carnations) demands manganese and boron co-formulations for continuous flowering cycles.
Crops anchor current procurement volumes. Hydroponics climbs fastest as protected vegetable acreage expands around Andean population centers.
End User:
Agriculture moves the mass tonnage while viticulture and floriculture extract premium per-hectare expenditure.
- Agriculture:Broadacre row-crop operations across Brazil's Mato Grosso and Goias states purchase zinc and manganese through cooperative volume contracts. Price sensitivity is acute; specifications follow commodity crop export requirements.
- Horticulture:Vegetable producers in Colombia and Peru's coastal valleys adopt fertigation-compatible chelates. Smaller average farm sizes drive demand for packaged, ready-to-apply formulations.
- Viticulture:Chile's Central Valley wine regions specify iron and zinc for canopy health; organic and biodynamic certifications constrain chelate selection to approved lists.
- Floriculture:Ecuadorian rose exporters and Colombian chrysanthemum growers require micronutrient programs integrated with pest management protocols for phytosanitary certification.
Agriculture dominates current offtake. Horticulture gains share fastest as urban-proximate greenhouse investment accelerates.
Distribution Channel:
Wholesale captures cooperative volume while e-commerce disintermediates mid-scale independent farms.
- Wholesale:Volume contracts with Brazil's soybean cooperatives and Argentina's grain handling networks structure annual procurement cycles. Blenders and formulators compete on technical service bundling.
- E-commerce:Ag-tech marketplaces in Goias and Mato Grosso bypass cooperative procurement for farms of 500-2,000 hectares. Soil testing integration and transparent pricing are table stakes.
- Retail:Branded micronutrient portfolios through dealer networks serve smaller horticulture and turf accounts; agronomic advice remains the loyalty mechanism.
- Direct Sales:Specialty lithium-derived nutrients and custom chelate formulations move through technical sales teams to large-scale operations with in-house agronomy capacity.
Wholesale structures today's margin pool. E-commerce represents the steepest expansion trajectory as digital adoption penetrates Brazil's interior states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's micronutrient consumption dwarfs Argentine offtake by roughly four-to-one, yet Chile's lithium-derived specialty nutrients command disproportionate pricing power across the continent.
Brazil
Mato Grosso and Goias soybean operations drive zinc and manganese demand through cooperative volume contracts. The Ministry of Agriculture and Livestock enforces 18-24 month registration timelines for new chelate formulations. Embrapa's satellite deficiency mapping across the Cerrado triggers precision application mandates that favor certified product specifications.
Argentina
Buenos Aires wheat farmers specify chelated iron for export-grade yield consistency, particularly in calcareous soils. Senasa phytosanitary oversight mandates batch-level traceability certificates for all imported concentrates. Domestic blending operations in Rosario are expanding to bypass customs delays during narrow harvest windows.
Chile
Specialty lithium-derived nutrients from Atacama extraction supply formulators continent-wide. SAG quality certification creates compliance layers for cross-border shipments. Central Valley viticulture clusters specify iron and zinc for canopy health, with organic certification constraints limiting approved chelate lists.
Colombia
Sabana de Bogota greenhouse vegetable producers adopt complete hydroponic micronutrient solutions requiring precise ionic balance. The country's agricultural modernization programs subsidize protected cultivation infrastructure. Flower export corridors around Facatativá demand manganese-boron co-formulations for continuous flowering cycles.
Uruguay
Government-funded grassland restoration programs specify copper and zinc formulations for beef productivity gains. The national livestock board's pasture improvement mandates create institutional procurement channels. Coastal ranching districts in Rocha and Lavalleja are converting degraded ranges through mineral supplementation protocols.
South America Micronutrient Fertilizer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South America's micronutrient fertilizer market. Tier-one agricultural input majors leverage retail distribution networks and digital agronomy platforms to anchor volume in consolidated cooperative channels. Mid-tier regional blenders compete on technical service bundling and faster regulatory approval navigation. The dominant competitive moves are direct-to-farm digital channel expansion and precision agriculture platform integration.
Among the diversified majors, Nutrien Ltd and Yara International ASA occupy positions exemplifying scale-driven retail anchoring and digital platform bundling respectively. Sociedad Quimica y Minera de Chile SA represents the specialty extraction archetype, supplying lithium-derived nutrient precursors from its Andean base. These three entities illustrate the structural split between distribution-integrated conglomerates and upstream-controlled specialty suppliers.
| Leading Market Players |
|---|
| ICL Group Ltd |
| Sociedad Quimica y Minera de Chile SA |
| The Mosaic Company |
| EuroChem Group |
| Haifa Group |
| Yara International ASA |
| K+S Aktiengesellschaft |
| Nutrien Ltd |
| Nortox |
| Others |
Value Network & Pricing Analysis
Chelated formulation manufacturing in Brazil's São Paulo industrial corridor is compressing unit economics while concentrating supply leverage among sulfate and oxide base material processors. This production-method transition simultaneously elevates quality thresholds for export-grade soybean certification and reshapes margin distribution between domestic blenders and imported concentrate suppliers.
Pricing Analysis
Capacity additions in Brazil's interior states are reshaping price floors for zinc sulfate and manganese oxide base materials. Three-tier pricing structure across certified chelate, standard sulfate, and economy oxide levels segments buyer willingness-to-pay by residue compliance requirements. Cost compression in standard sulfate tiers is intensifying because cooperative procurement committees unbundle technical advisory from product supply. Large-scale Mato Grosso operations with in-house agronomy teams exhibit lowest price sensitivity; mid-sized Goias farms purchasing through ag-tech marketplaces show highest elasticity.
Supply Chain Analysis
Certification gating through Brazil's Ministry of Agriculture and Livestock registration timelines creates supply bottlenecks that favor incumbent formulators with established efficacy dossiers. Geographic concentration centers on Chile for lithium-derived specialty nutrients, Brazil for sulfate processing and blending capacity, and China for EDTA chelating agent precursors. Raw material dependencies rest on Atacama lithium brine extraction, London Metal Exchange-tracked zinc and manganese metal feedstocks, and lignosulfonate carriers from pulp processing. Single-source vulnerability from Chilean lithium supply exposes formulators to geopolitical disruption. Distribution runs through cooperative volume contracts anchoring wholesale channels, with e-commerce penetration accelerating among mid-scale independent farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by Argentine wheat exporters' shift toward certified chelated iron formulations that guarantee EU residue compliance. Premium specification demand now separates viable suppliers from commodity blenders.
For Market Incumbents: To counter disintermediation by independent soil consultants, anchor cooperative relationships through bundled satellite deficiency mapping services and expedite chelate registration investments to maintain 18-24 month approval timelines as a competitive moat. Backward integration into lignosulfonate carrier supply secures formulation cost control against pulp processing volatility. For New Entrants and Emerging Players: Begin with Paraguay's eastern soy belt where established distribution infrastructure remains absent and technical sales teams can capture first-mover positioning through direct farm relationships. Uruguay's government-funded grassland restoration programs offer institutional procurement channels with lower competitive intensity than Brazil's consolidated cooperative landscape. Target e-commerce platform partnerships in Goias that integrate soil testing with transparent pricing to bypass incumbent cooperative gatekeepers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional blenders lacking chelate registration capabilities but possessing established relationships with Brazil's interior cooperatives. Long-term viability over the next decade hinges on precision agriculture platform integration and digital channel control. The signal to watch is Embrapa satellite deficiency mapping adoption rates triggering mandatory certified product specifications across the Cerrado.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Farm Digital Channel Expansion | Bypasses cooperative procurement consolidation in Mato Grosso and Goias through ag-tech marketplace integration. |
| Chelate Registration Investment | Secures 18-24 month Ministry of Agriculture and Livestock approval timelines as competitive moat against imports. |
| Precision Agriculture Platform Partnership | Embeds micronutrient recommendations within variable-rate application hardware sold to large-scale operations. |
| Backward Integration into Carrier Supply | Captures lignosulfonate production from pulp processing to stabilize formulation input costs. |
| Geographic Expansion into Paraguay | Exploits underpenetrated eastern soy belt through technical sales teams ahead of incumbent distributor establishment. |
Research Methodology
Multiple input streams — primary interviews with cooperative procurement managers, formulator technical directors, and agronomic service providers; secondary validation through ANVISA registration databases, Ministry of Agriculture and Livestock approval records, and Embrapa satellite imagery publications; plus customs trade data on sulfate and oxide concentrate imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across supply-side capacity assessments and demand-side adoption curves generated volume and value outputs over the projection horizon. Segmentation dimensions modeled include product type tier, application method, end-user crop specialization, and distribution channel structure. CAGRs were derived from growth rate reconciliation between historical consumption patterns and forward-looking precision agriculture adoption curves, with specific inputs from chelate registration pipeline tracking and cooperative procurement committee unbundling trends.
Several conditions sit outside the modeled scope, including potential reclassification of biofertilizer categories under evolving regulatory debate and abrupt lithium supply disruption from Atacama extraction constraints. Forecasts reflect documented assumptions on farmer digital adoption rates and cooperative consolidation trajectories. A model refresh is warranted upon material change in ANVISA residue protocol stringency or Embrapa precision application mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Diammonium Hydrogen Phosphate (DAP) Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Potassium Thiosulfate Fertilizer Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Fertilizer Mixtures Market