
 EMEA Secondary Macronutrients Market | 2026-2036
EMEA Secondary Macronutrients Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Secondary Macronutrients Market Foresight
The gap between premium micronutrient blends and commodity sulfur sources is rebalancing as fertilizer manufacturers reformulate for differentiated crop outcomes. Yara International ASA leverages its integrated ammonia network to secure downstream sulfur availability, while K+S Aktiengesellschaft anchors Central European supply through its domestic potash and magnesium salt deposits. Eurochem Group AG competes on phosphate-sulfur combination products that address multiple deficiency profiles in single applications.
Secondary macronutrients encompass calcium, magnesium, and sulfur compounds that supplement primary NPK fertilization, typically applied at 20-100 kg per hectare depending on soil test values and crop removal rates. These elements regulate enzyme activation, protein synthesis, and cell wall integrity in plants, making them essential for yield stability and produce quality. Calcium dominates product type value pools due to its role in greenhouse vegetable production and post-harvest durability, while sulfur is accelerating fastest as atmospheric deposition declines across former industrial regions. Agricultural applications occupy the largest share of end-user offtake, though horticulture commands superior margins through customized fertigation formulations.
The EU Green Deal and REACH frameworks govern fertilizer product registration and environmental release thresholds across the EMEA region, with EFSA establishing maximum residue and soil accumulation benchmarks that shape formulation standards. National regulators in Germany and France enforce nitrate directive compliance that indirectly constrains sulfur and magnesium application timing and rates. Stakeholders must monitor evolving carbon border adjustment mechanisms and nutrient recovery mandates that could redirect secondary macronutrient sourcing toward recycled and organic-origin materials.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing application windows and mandating precision nutrient placement, forcing fertilizer formulators to rebuild product portfolios around lower-release, higher-efficiency compounds.
Growth Catalysts
- Declining Atmospheric Sulfur Deposition:Industrial emission reductions across Germany's Ruhr Valley and Poland's Silesian Basin eliminate free sulfur inputs, compelling wheat growers to purchase supplemental sulfate fertilizers.
- REACH Fertilizer Product Registration:Streamlined EU-wide approval pathways for novel calcium-magnesium blends accelerate commercialization timelines for greenhouse vegetable producers in the Netherlands.
- Controlled-Release Coating Technology:Polymer-sulfur encapsulation systems enable single-application programs in France's intensive arable belt, reducing labor costs and environmental runoff.
Market Restraints
- Natural Gas Price Volatility:Ammonia synthesis costs for sulfur-derived ammonium sulfate fluctuate with TTF hub pricing, squeezing margin stability for nitrogen-sulfur compound manufacturers.
- Phosphate Rock Import Concentration:Moroccan and Russian supply dominance for phosphate-sulfur combination products creates geopolitical exposure for Central European blenders.
- Soil Test Interpretation Variability:Inconsistent calcium-magnesium ratio thresholds across national agricultural extension services in Italy and Spain delay adoption decisions by risk-averse growers.
Strategic Opportunities
- Recovered Nutrient Mandates:The EU's proposed circular economy action plan incentivizes struvite-derived magnesium and calcium from wastewater treatment plants, opening secondary raw material channels.
- Sub-Saharan Africa Export Corridor:Ethiopian and Kenyan horticulture sectors seek EMEA-registered calcium chloride and magnesium sulfate for rose and vegetable export quality.
- Fertigation-Compatible Sulfate Liquids:Drip irrigation expansion in Morocco's Souss-Massa region creates demand for high-purity liquid magnesium sulfate bypassing solid fertilizer handling.
Industry Challenges
- Precision Agriculture Technician Shortage:Variable-rate application equipment operation and soil sensor calibration expertise remains scarce in Portugal's Alentejo cereal region.
- EFSA Residue Database Gaps:Incomplete maximum residue level harmonization for calcium nitrate in leafy greens delays product label extensions across member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Secondary Macronutrients Market |
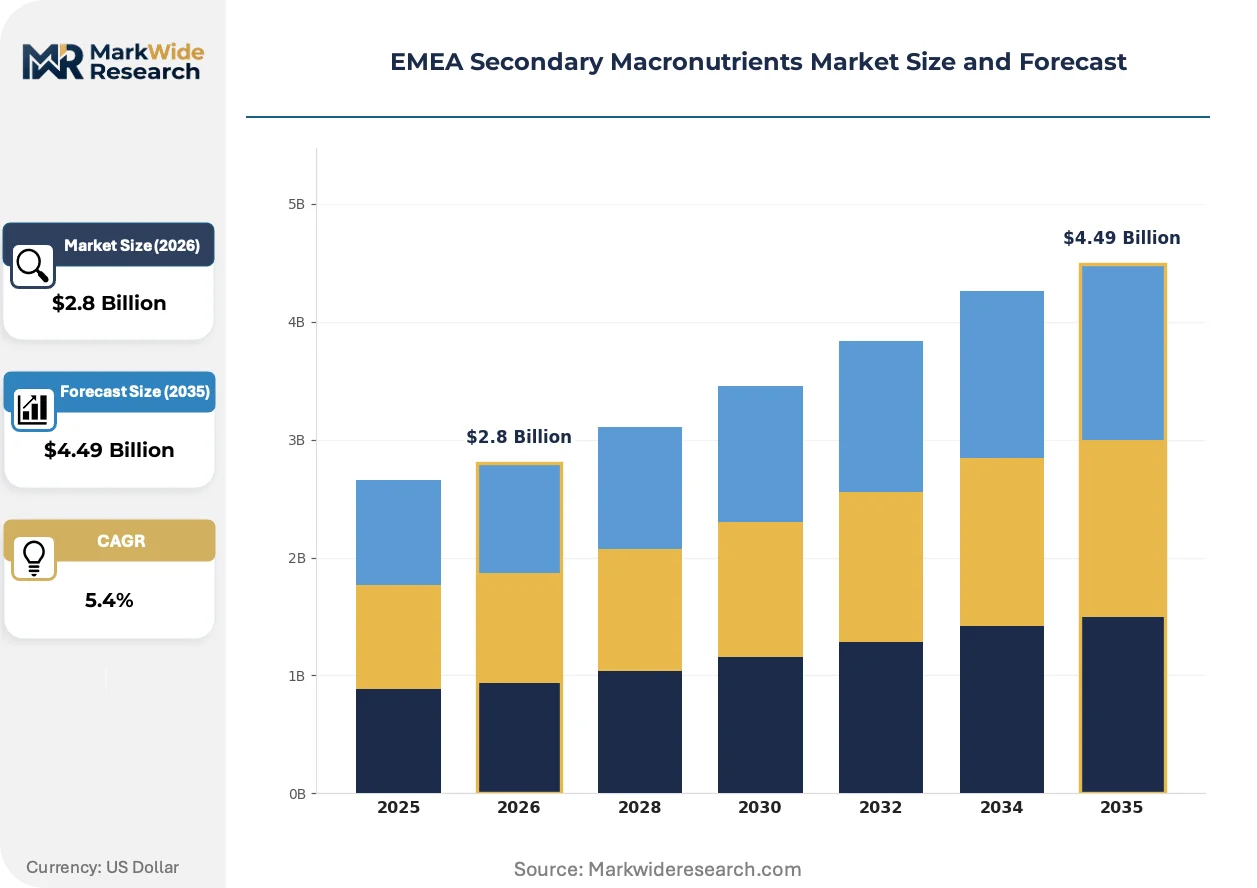
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium, Magnesium, Sulfur, Micronutrient Blends Application: Agriculture, Horticulture, Landscaping, Turf Management End User: Farmers, Fertilizer Manufacturers, Retailers, Agricultural Cooperatives Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Yara International ASA, K+S Aktiengesellschaft, Israel Chemicals Ltd, The Mosaic Company, Nutrien Ltd, Eurochem Group AG, Haifa Group, Rovensa, Van Iperen International, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Secondary Macronutrients Market Shifts & Advancements
Digital soil mapping and variable-rate application hardware are collapsing the information gap between blanket fertilization and site-specific nutrient management across Mediterranean horticulture zones.
Calcium nitrate foliar sprays are expanding into table grape and cherry orchards in Spain's Murcia region and Italy's Apulia. Growers apply these compounds during fruit expansion phases to reduce splitting and extend cold chain tolerance. The technology is expanding into premium export segments where shelf-life premiums justify input cost premiums over ground-applied limestone.
REACH fertilizer regulation amendments now require full lifecycle carbon footprint disclosure for products sold into the EU single market. Manufacturers must quantify emissions from phosphate rock mining through to field application. This pressure most acutely affects sulfur-containing ammonium phosphate producers sourcing rock from North African deposits, who are investing in transport emission offset programs.
Buyer consolidation among French cooperative purchasing groups is compressing supplier negotiation cycles from annual to quarterly terms. These cooperatives now demand real-time application guidance bundled with product supply. The shift is most visible in the Paris Basin wheat belt, where sulfur deficiency correction programs are negotiated as season-long agronomic service packages rather than commodity tonnage contracts.
EMEA Secondary Macronutrients Market Segmentation
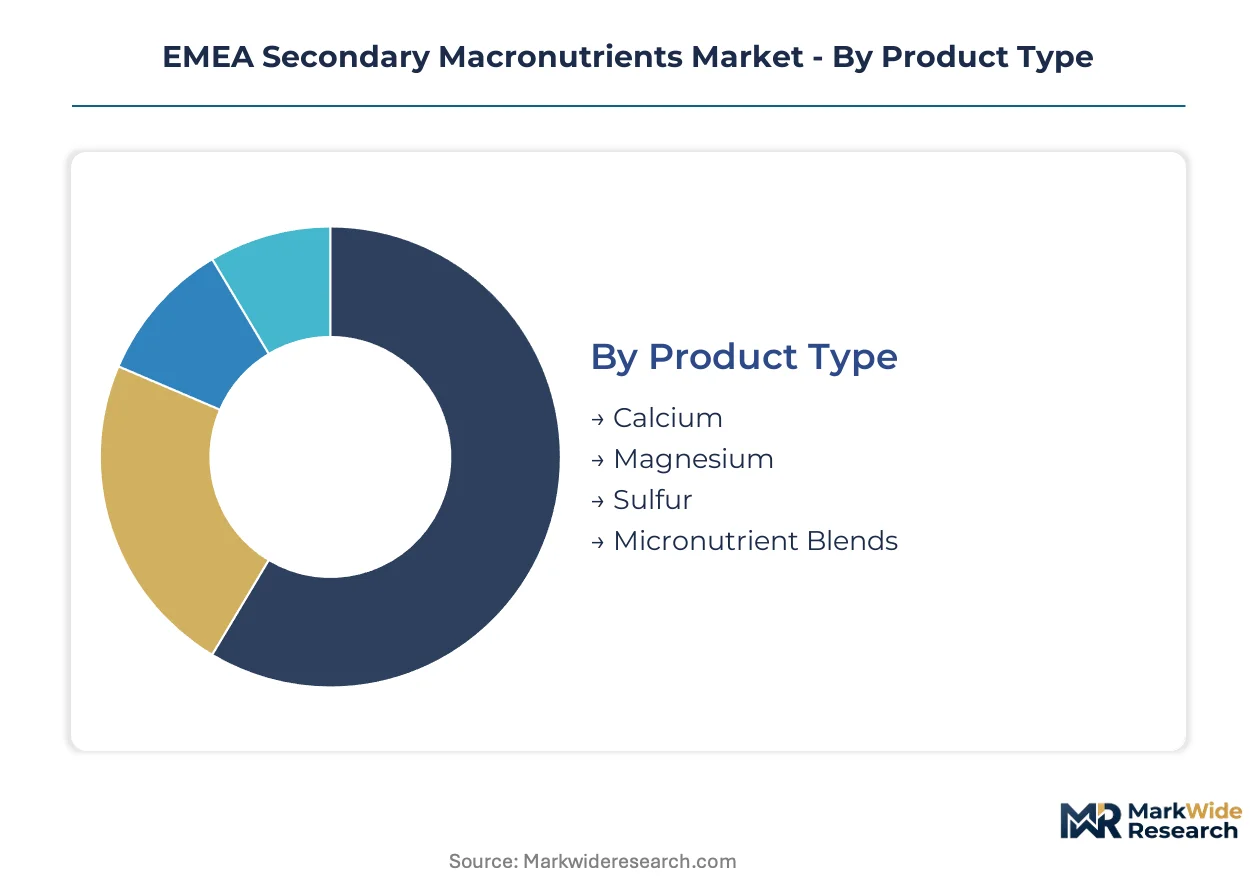
Secondary macronutrient purchasing patterns diverge sharply across crop systems and supply chain tiers. Buyers in intensive arable regions prioritize sulfur replacement programs, while Mediterranean horticulture operators seek calcium formulations for post-harvest quality premiums.
Product Type:
Replacement cycles accelerate where soil test thresholds trigger mandatory correction protocols rather than discretionary maintenance applications.
- Calcium:Calcium nitrate and calcium chloride formulations dominate greenhouse vegetable production in the Netherlands and Spain's Almería province. Dutch tomato growers apply liquid calcium through drip systems to prevent blossom-end rot and extend shelf life for German retail chains.
- Sulfur:Ammonium sulfate and elemental sulfur products address atmospheric deposition deficits across Germany's wheat belt and Poland's cereal regions. Declining industrial emissions eliminate free sulfur inputs, forcing growers into purchased sulfate programs for protein synthesis in bread wheat.
- Magnesium:Kieserite and magnesium sulfate applications concentrate in Central European sugar beet and potato rotations where magnesium removal rates exceed natural replenishment.
- Micronutrient Blends:Custom calcium-magnesium-sulfur combinations serve precision fertigation systems in France's intensive vegetable production zones near Nantes and Tours.
Calcium sits at the top of the volume ranking, with sulfur climbing the fastest as deposition losses compound across former industrial regions.
Application:
Margin structures vary dramatically between bulk commodity sales and customized horticulture formulations.
- Agriculture:Broadacre cereal and oilseed operations in France's Paris Basin and Germany's Lower Saxony apply sulfur and magnesium through solid spreaders. These programs emphasize cost per hectare and compatibility with existing nitrogen application windows.
- Horticulture:Protected vegetable production in Italy's Sicily and Spain's Murcia demands high-purity calcium nitrate for fertigation. Quality premiums for export tomatoes and peppers justify input cost multiples over agricultural-grade products.
- Landscaping:Municipal and commercial turf managers in the UK and Scandinavia apply magnesium sulfate for rapid green-up in cool-season grasses.
- Turf Management:Golf course superintendents in Portugal's Algarve and Spain's Costa del Sol use calcium-magnesium blends for salinity management and playing surface hardness control.
Agriculture captures the largest tonnage position, while horticulture generates the steepest margin expansion trajectory.
End User:
Procurement sophistication separates price-taking commodity buyers from service-integrated purchasing cooperatives.
- Farmers:Individual growers in Spain's Castile-La Mancha and Italy's Po Valley rely on agronomic advice from regional extension services to time calcium and sulfur applications. Soil test interpretation variability delays adoption in risk-averse segments.
- Fertilizer Manufacturers:Compound fertilizer blenders in Germany and Poland integrate secondary macronutrients into NPK formulations. These operators negotiate sulfate supply contracts linked to ammonia pricing benchmarks.
- Retailers:Agricultural input distributors in France's cooperative sector bundle secondary macronutrients with variable-rate application services. Quarterly negotiation cycles replace annual contracts as purchasing groups consolidate.
- Agricultural Cooperatives:French cooperative groups in the Brittany and Normandy regions negotiate season-long agronomic packages. These buyers demand real-time application guidance bundled with product supply.
Fertilizer manufacturers dominate upstream volume flows, with agricultural cooperatives gaining procurement leverage fastest.
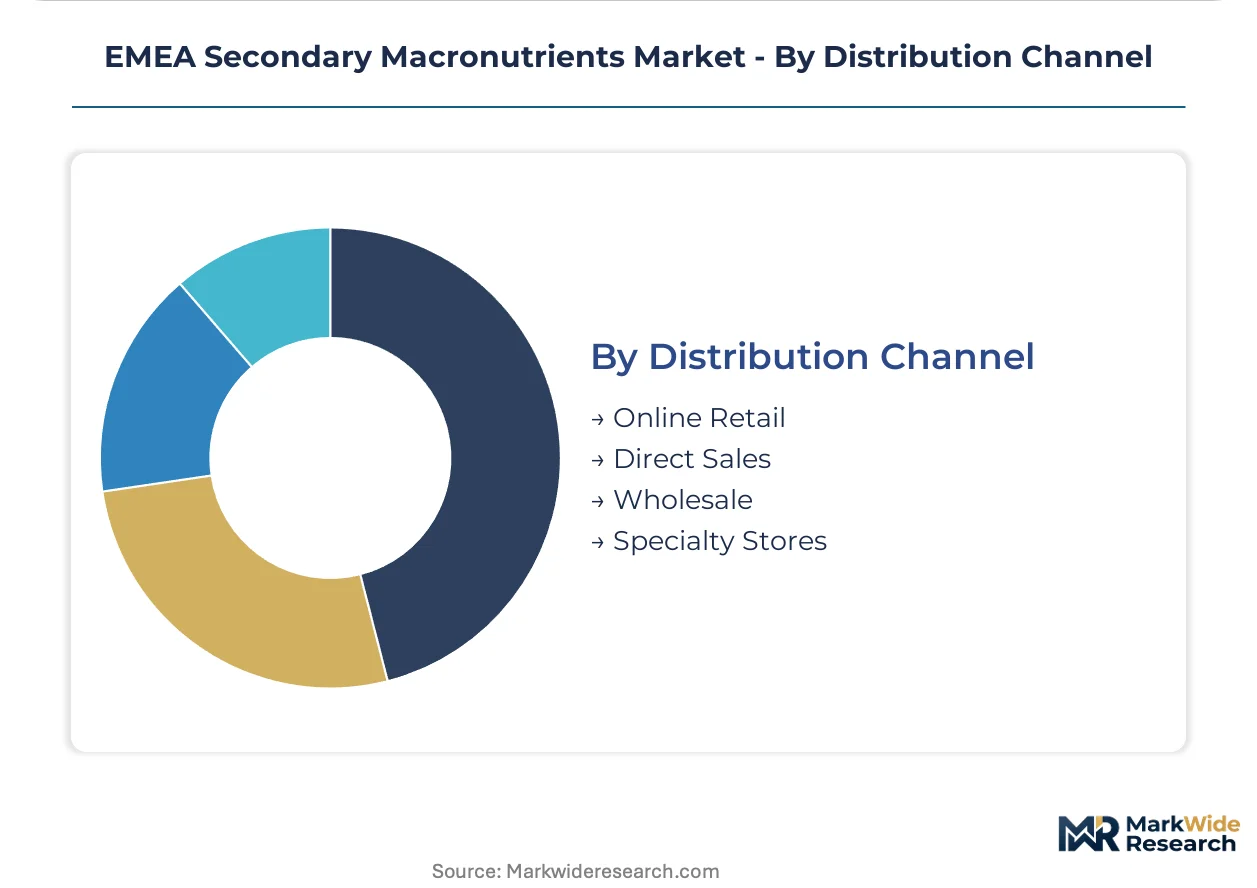
Distribution Channel:
Channel selection tracks customer scale and technical service requirements across the value chain.
- Direct Sales:Major formulators in Germany and the Netherlands sell calcium nitrate and liquid magnesium sulfate directly to large greenhouse operators. These relationships include on-site storage and automated dosing system maintenance.
- Wholesale:Regional distributors across Central Europe stock ammonium sulfate and kieserite for agricultural retailers. Inventory positioning follows seasonal application windows for winter wheat and spring barley.
- Specialty Stores:Horticultural suppliers in the UK and Scandinavia serve amateur and semi-professional growers with packaged magnesium sulfate and calcium products.
- Online Retail:E-commerce penetration remains limited for bulk agricultural grades but expands in specialty turf and hobby gardening segments.
Direct sales command the highest customer lifetime value, with wholesale maintaining the widest geographic coverage footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic expertise clusters in the Netherlands and Germany anchor technical service capabilities, while Mediterranean greenhouse operators concentrate demand for high-value calcium formulations.
Germany
Sulfur deficiency correction in wheat and declining atmospheric deposition drive purchased sulfate demand across Lower Saxony and the Paris Basin extension. The EU Green Deal's Farm to Fork strategy tightens nutrient management windows through national nitrate directive enforcement. The Ruhr Valley's former industrial belt now requires deliberate sulfur fertilization as free deposition inputs vanish.
France
Intensive arable operations in the Paris Basin prioritize sulfur replacement programs for protein synthesis in bread wheat. EFSA establishes maximum residue benchmarks that shape calcium nitrate application timing in vegetable production. Cooperative purchasing groups around Nantes and Tours negotiate season-long agronomic service packages bundling secondary macronutrients with variable-rate guidance.
Spain
Greenhouse vegetable producers in Almería and Murcia apply liquid calcium through drip systems to prevent blossom-end rot and extend shelf life for German retail chains. The EU REACH framework governs fertilizer product registration and environmental release thresholds. Table grape and cherry orchards in Murcia adopt foliar calcium sprays during fruit expansion phases to reduce splitting.
Netherlands
Tomato growers in Westland and Noord-Brabant deploy precision fertigation systems demanding high-purity calcium nitrate and magnesium sulfate. Streamlined EU-wide approval pathways under REACH amendments accelerate commercialization timelines for novel calcium-magnesium blends. Dutch greenhouse clusters supply technical expertise that shapes formulation standards across the EMEA region.
Italy
Specialty crop operators in Sicily and Apulia expand calcium and magnesium applications to improve fruit quality and post-harvest durability. National agricultural extension services maintain inconsistent calcium-magnesium ratio thresholds that delay adoption decisions by risk-averse growers in the Po Valley. Protected vegetable production near Naples demands customized fertigation formulations commanding margin premiums over agricultural-grade products.
EMEA Secondary Macronutrients Market Competitive Landscape
Top-tier vendors anchor integrated ammonia and mining positions, while mid-tier blenders compete on phosphate-sulfur combination formulations and regional distribution density. The market exhibits tiered consolidation with three to five dominant players controlling upstream sulfate and magnesium salt supply. Strategic archetypes include integrated nitrogen-sulfur producers, potash-magnesium miners, and phosphate-sulfur compound specialists. Capacity expansion in Central European magnesium processing and backward integration into sulfur recovery operations represent the dominant competitive vectors.
Among integrated producers, Yara International ASA exemplifies the ammonia-network archetype leveraging captive nitrogen positions for downstream sulfur compound availability. K+S Aktiengesellschaft occupies a position within the potash-magnesium mining tier, anchoring Central European supply through domestic salt deposit access. Eurochem Group AG represents the phosphate-sulfur combination segment, competing on multi-nutrient formulations addressing deficiency profiles in single applications.
| Leading Market Players |
|---|
| Yara International ASA |
| K+S Aktiengesellschaft |
| Israel Chemicals Ltd |
| The Mosaic Company |
| Nutrien Ltd |
| Eurochem Group AG |
| Haifa Group |
| Rovensa |
| Van Iperen International |
| Others |
Supply & Pricing Matrix
Natural gas costs for ammonia synthesis cascade through sulfur compound pricing tiers, with TTF hub volatility compressing margins for ammonium sulfate manufacturers serving Germany's wheat belt while premium calcium nitrate formulations for Dutch greenhouse operators capture value through bundled agronomic services.
Pricing Analysis
Bundled agronomic service packages separate premium pricing tiers from commodity sulfur sales, with French cooperative purchasing groups in the Paris Basin now negotiating quarterly contracts that integrate variable-rate application guidance. Price differentiation hinges on formulation purity grades and REACH registration status, with horticulture-grade calcium nitrate commanding multiples over agricultural-grade ammonium sulfate. Pricing pressure stems from ammonia feedstock cost volatility, squeezing nitrogen-sulfur compound margins. Individual farmers in Spain's Castile-La Mancha exhibit highest price sensitivity, while Dutch greenhouse operators show lowest sensitivity due to shelf-life premiums.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's circular economy action plan are redirecting magnesium sourcing toward struvite recovery from wastewater treatment plants in Germany and the Netherlands. Raw material supply concentrates in Morocco and Russia for phosphate rock, Germany and Poland for potash-magnesium salts, and Norway for ammonia feedstock. Sulfur recovery from oil refining and natural gas processing feeds ammonium sulfate production. Single-source vulnerability in Moroccan phosphate rock creates geopolitical exposure for Central European blenders. Distribution runs through cooperative purchasing groups in France, direct sales to Dutch greenhouse operators, and wholesale networks across Poland's cereal regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between sulfur-deficient wheat regions in Germany and France where atmospheric deposition has collapsed, and magnesium-rich potash mining districts in Central Europe where feedstock costs remain structurally lower.
For Market Incumbents: Deploy backward integration into sulfur recovery operations to secure captive sulfate supply against ammonia price volatility. Incumbent nitrogen-sulfur producers should expand polymer-encapsulation coating capacity in France's intensive arable belt to capture precision application premiums. Defensive consolidation around Central European magnesium processing assets counters emerging recycled-nutrient competitors. For New Entrants and Emerging Players: Begin with liquid magnesium sulfate formulations for Morocco's expanding drip irrigation sectors in the Souss-Massa region, where solid fertilizer handling infrastructure remains underdeveloped. White-space targets include fertigation-compatible sulfate liquids for Ethiopian and Kenyan horticulture export quality programs, and struvite-derived magnesium channels serving Dutch circular economy mandates. A technical service partnership with regional distributors accelerates market entry faster than greenfield asset builds. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier blenders lack integrated ammonia positions or captive magnesium salt deposits, leaving them exposed to feedstock volatility. Long-term viability favors vertically integrated producers with backward control into sulfur recovery and potash mining. Acquisition targets include regional compounders with dense distribution in Poland's cereal belt or specialized calcium nitrate formulators serving Mediterranean greenhouse clusters. The signal to watch is EU nutrient recovery mandate implementation timelines, which would revalue secondary raw material channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Recovery | Captive sulfate supply insulates margins from TTF natural gas volatility. |
| Controlled-Release Coating Capacity Expansion | Polymer-sulfur encapsulation captures precision agriculture premiums in France. |
| Struvite-Derived Magnesium Channel Development | Circular economy compliance opens wastewater treatment plant feedstock contracts. |
| Liquid Fertilizer Formulation Investment | Drip irrigation expansion in Morocco's Souss-Massa region favors high-purity sulfate liquids. |
| Cooperative Service Package Bundling | Quarterly agronomic contracts with French purchasing groups replace commodity tonnage sales. |
Research Methodology
Direct dialogue with fertilizer formulator technical directors, cooperative purchasing managers in France and Germany, Dutch greenhouse operations managers, and EMEA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from EU REACH registration databases, EFSA maximum residue level filings, customs trade data for sulfur and magnesium compound flows, and national agricultural extension service soil test interpretation protocols. Bottom-up volume estimates from crop-specific application rates triangulated against top-down manufacturer capacity disclosures.
Segment-level value projections across calcium, sulfur, magnesium, and micronutrient blend categories tracked application intensity variations by crop system and regional soil deficiency profiles. The analytical framework incorporated product type, application method, end-user procurement sophistication, and distribution channel structure as core segmentation dimensions. CAGRs emerged from trend extrapolation of atmospheric sulfur deposition decline rates, EU Green Deal implementation timelines, and precision agriculture adoption curves. Key inputs included TTF natural gas price scenarios and phosphate rock import dependency ratios.
Several conditions sit outside the modeled scope, including abrupt geopolitical disruptions to Moroccan or Russian phosphate rock supply, unforeseen EFSA residue threshold revisions affecting calcium nitrate labeling, and rapid technological displacement of controlled-release coatings by novel delivery systems. Forecasts reflect documented assumptions about regulatory implementation pacing and farmer adoption behavior. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
High-Brix Fruit Quality Enhancement Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Global Nitrogen Fertilizers Market