
 Europe Specialty Fertilizer Market | 2026-2036
Europe Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Specialty Fertilizer Market Foresight
The price gap between premium coated formulations and commodity nitrogen blends is hardening as input cost volatility widens. Yara International ASA leverages its integrated ammonia network to sustain margin stability across Nordic markets. EuroChem Group AG anchors its position through captive phosphate rock access and Black Sea logistics. Grupa Azoty S.A competes on ammonium nitrate specialization for Central European cereal growers.
Europe Specialty Fertilizer denotes crop nutrition products engineered with defined nutrient release kinetics, micronutrient chelation, or biostimulant co-formulations, typically manufactured through compaction granulation, polymer coating, or fermentation-based biological activation, designed to match nutrient supply with crop uptake curves and reduce environmental losses. Organic fertilizers and biofertilizers capture expanding margin pools as the EU Farm to Fork Strategy tightens synthetic input ceilings, while coated and liquid forms command premium positioning in greenhouse and fertigation systems where application precision directly correlates with yield outcomes. Granular micronutrient blends remain the volume backbone for broad-acre agriculture, though powder formulations gain traction in high-value horticulture across Iberian and Italian production zones.
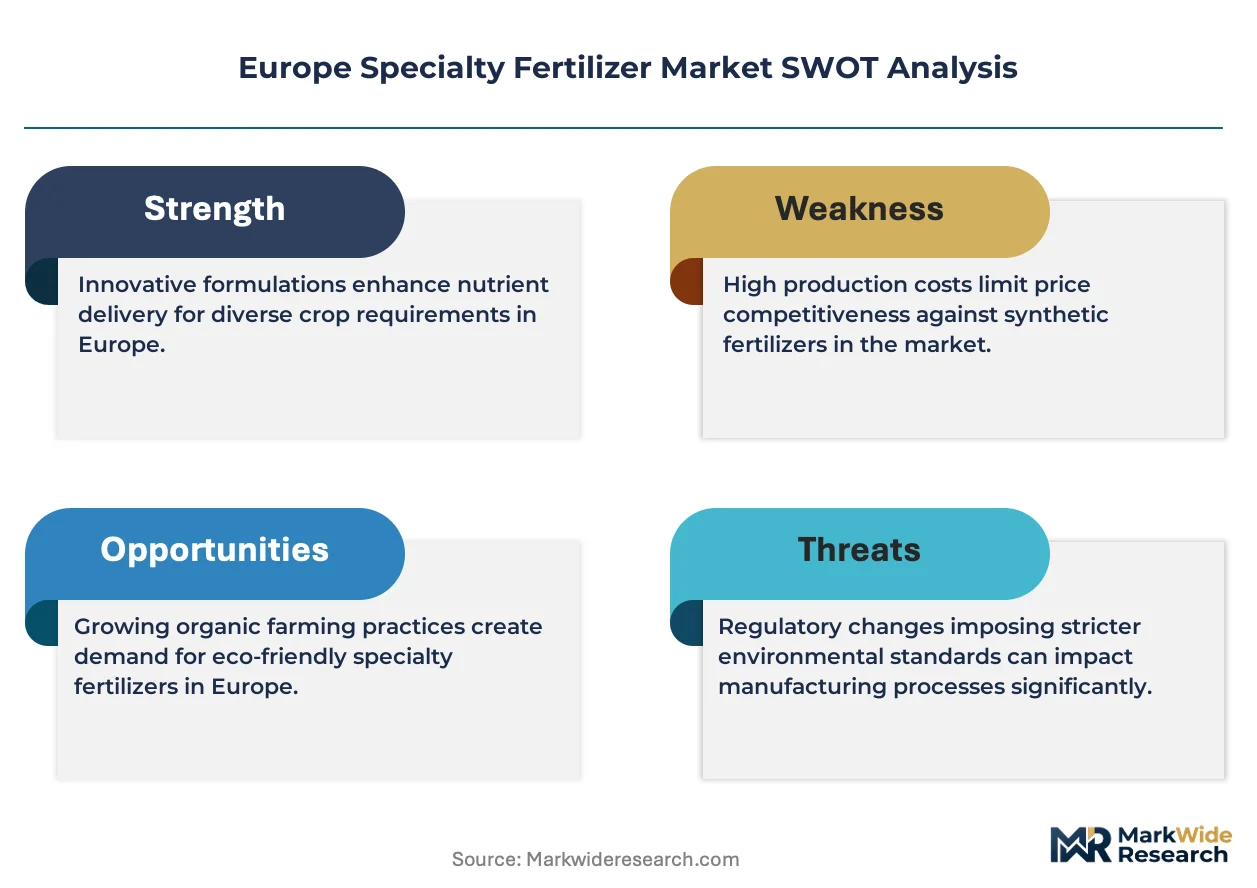
The EU Green Deal, REACH, and national implementations of the Nitrates Directive collectively reshape product registration pathways and place liability for environmental runoff on manufacturers. ECHA's evolving criteria for polymer coatings in controlled-release products are forcing reformulation investments that smaller blenders cannot absorb. Stakeholders must monitor how the EU AI Act and digital farming subsidies converge to reward fertilizer products with embedded sensor-compatibility and variable-rate application certificates.
Market Dynamics
The EU Green Deal's nutrient-loss reduction targets are forcing manufacturers to redesign release kinetics and coating chemistries ahead of 2030 compliance deadlines, compressing product development cycles and raising R&D breakeven thresholds.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating adoption of non-fluorinated polymer coatings in controlled-release fertilizers across German and Dutch greenhouse operations.
- Precision fertigation systems:Vegetable producers in Spain's Almería corridor are retrofitting drip infrastructure with sensor-compatible liquid specialty formulations that synchronize nutrient delivery with real-time crop uptake data.
- Italy's organic conversion subsidies:National recovery plan allocations for biological input transition are expanding manufacturing capacity for fermentation-derived biostimulant co-formulations in Lombardy and Emilia-Romagna.
Market Restraints
- Natural gas price volatility:Ammonia synthesis costs swing with TTF hub pricing, eroding margin stability for nitrogen-based specialty products and forcing hedging complexity on mid-scale blenders.
- Phosphate rock supply concentration:Dependence on Moroccan and Russian phosphate reserves exposes European formulators to export quota disruptions and shipping route bottlenecks through the Strait of Gibraltar.
- ECHA polymer coating criteria uncertainty:Evolving hazard classification protocols for microplastic-containing controlled-release products are delaying product registrations and requiring costly reformulation cycles.
Strategic Opportunities
- Poland's underpenetrated orchard sector:Apple and berry producers in Greater Poland Voivodeship lack access to chelated micronutrient programs, creating first-mover potential for foliar application specialists.
- Carbon farming certification integration:The EU Carbon Removal Certification Framework creates premium positioning for fertilizers with verified soil carbon sequestration co-benefits in French and German broad-acre markets.
- Drone-based variable-rate application:Convergence of aerial spreading platforms with prescription mapping software is opening direct-to-farmer channels that bypass traditional agrochemical distributors in Denmark and Sweden.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for controlled-release coating design concentrates among retiring specialists at legacy research institutes, constraining new product pipeline velocity.
- REACH registration cost burden:Full substance dossier preparation for novel biostimulant active ingredients demands seven-figure euro investments that exclude smaller fermentation startups from commercialization.
- Legacy ERP integration friction:Batch manufacturing execution systems at established granulation plants resist interoperability with traceability platforms required for EU digital product passport compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Specialty Fertilizer Market |
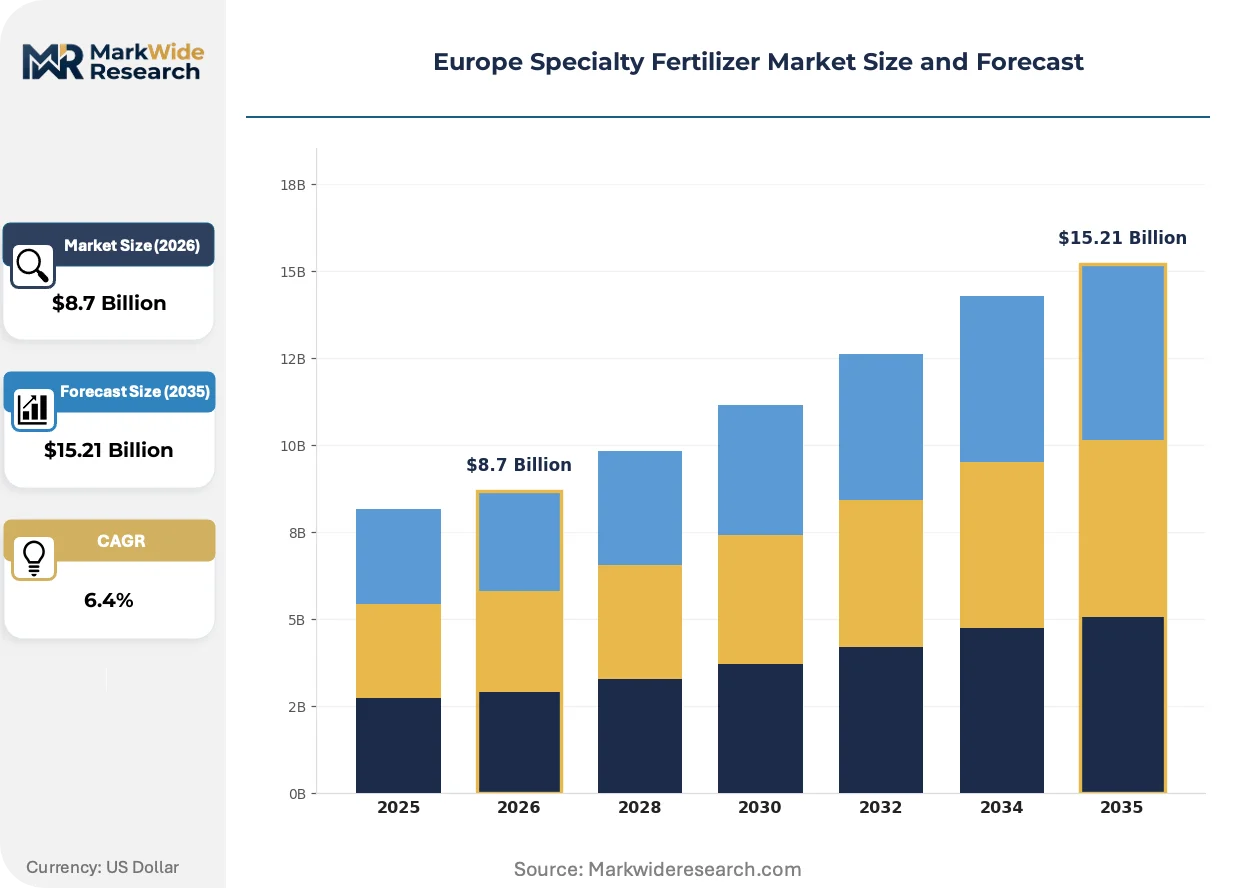
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fertilizers, Inorganic Fertilizers, Biofertilizers, Micronutrients Application: Agriculture, Horticulture, Turf & Ornamentals, Greenhouse Form: Granular, Liquid, Powder, Coated Delivery Method: Foliar, Fertigation, Broadcasting, Side Dressing |
| Companies Covered | ICL Group Ltd, Yara International ASA, EuroChem Group AG, Fertiberia, Kingenta Ecological Engineering Group Co., Ltd., K+S AG, Grupa Azoty S.A, Haifa Chemicals Ltd., CF Industries Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Specialty Fertilizer Market Shifts & Advancements
Biological activation pathways and sensor-integrated application hardware are converging to redefine how nutrient efficiency is measured and monetized across European cropping systems.
Biostimulant-fermentation platforms are rewriting the economics of specialty fertilizer production. Microbial consortia cultivated on agricultural waste streams are replacing synthetic hormone additives in rooting and stress-resistance formulations. French and Italian vine growers are piloting these biological activators at scale, compressing the premium gap between organic-certified and conventional specialty products.
REACH authorization timelines for polymer microplastics are tightening compliance windows for controlled-release coating technologies. Manufacturers must submit substitution plans for conventional polyurethane and alkyd resin coatings by 2026, accelerating research into biodegradable alternatives such as chitosan and lignin-based barriers. Dutch and Belgian formulators with existing biopolymer expertise are capturing early registration advantages.
Outcome-based nutrient efficiency guarantees are displacing volume-based purchasing contracts in high-value horticulture. Greenhouse operators in the Netherlands now specify yield-per-unit-nitrogen metrics rather than tonnage, transferring agronomic risk to fertilizer suppliers. This contracting shift favors integrated providers with diagnostic capabilities and on-staff crop advisors over commodity blenders.
Europe Specialty Fertilizer Market Segmentation
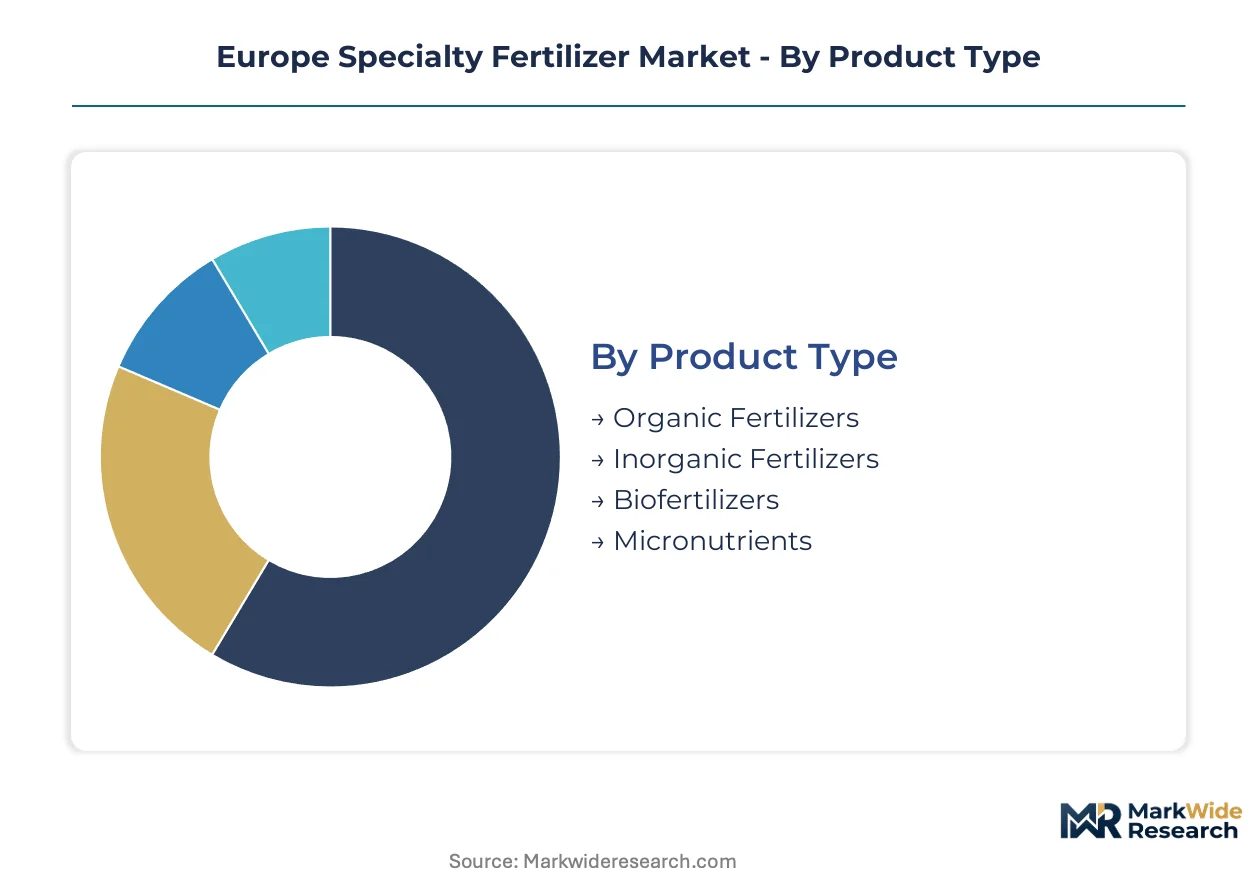
Specialty fertilizer segmentation in Europe reflects divergent regulatory burdens across product categories. REACH dossier requirements, EU Fertilizing Products Regulation certification pathways, and national organic input approvals create tiered compliance costs that reshape competitive positioning.
Product Type:
REACH registration intensity varies sharply across this category, with inorganic formulations facing substance dossier obligations while biofertilizers navigate novel active ingredient pathways under evolving ECHA guidance.
- Organic Fertilizers:Composted and processed animal or plant-derived materials with defined carbon-to-nitrogen ratios and pathogen thresholds. Demand clusters in France's intensive vegetable belt where the EU Farm to Fork Strategy tightens synthetic input ceilings for export-oriented producers.
- Inorganic Fertilizers:Chemically synthesized macronutrient products including coated urea and compound NPK formulations with engineered solubility profiles. German precision farming corridors favor these products for variable-rate application compatibility.
- Biofertilizers:Microbial inoculants containing nitrogen-fixing or phosphate-solubilizing strains. Lombardy and Emilia-Romagna fermentation facilities expand capacity to serve Italy's organic conversion subsidies.
- Micronutrients:Chelated zinc, boron, manganese, and iron formulations addressing specific soil deficiencies. Iberian citrus and olive producers drive specification intensity for foliar-grade powder forms.
Leading the category by volume: Inorganic Fertilizers. Growing fastest: Biofertilizers.
Application:
Margin structures across applications correlate with crop value intensity and input precision requirements, with greenhouse operations commanding premium pricing for sensor-compatible formulations.
- Agriculture:Broad-acre cereal and oilseed production utilizing granular micronutrient blends and controlled-release nitrogen. Polish cereal growers anchor volume demand through ammonium nitrate specialization programs.
- Horticulture:High-value fruit, vegetable, and ornamental crop nutrition requiring chelated micronutrients and biostimulant co-formulations. Spain's Almería corridor drives precision fertigation retrofit investments.
- Turf & Ornamentals:Sports field, golf course, and landscape maintenance formulations with controlled-release nitrogen for aesthetic performance. German and Dutch municipal procurement specifications tighten environmental loss thresholds.
- Greenhouse:Soilless and substrate-based cultivation systems demanding liquid specialty products with pH-buffered nutrient solutions. Dutch operators now contract on yield-per-unit-nitrogen metrics rather than tonnage.
Agriculture dominates volume throughput. Greenhouse applications expand most quickly as protected cultivation area increases across Southern Europe.
Form:
Manufacturing capital intensity and coating technology requirements create distinct competitive moats between form categories, with liquid production favoring integrated chemical processors.
- Granular:Compacted or prilled products with uniform particle size distribution for mechanical spreading equipment. Remains the volume backbone for Central European cereal production.
- Liquid:Fully soluble or suspension concentrates compatible with injection and drip irrigation infrastructure. Almería vegetable producers retrofit drip systems with sensor-compatible formulations.
- Powder:Fine-milled products for foliar spray or hydroponic dissolution. Gains traction in Italian and Iberian high-value horticulture where application precision correlates directly with yield outcomes.
- Coated:Polymer- or sulfur-encapsulated controlled-release products with defined nutrient availability windows. ECHA's evolving microplastic criteria force reformulation investments toward chitosan and lignin-based barriers.
Granular forms lead volume. Coated products gain share fastest amid nutrient-loss reduction mandates.
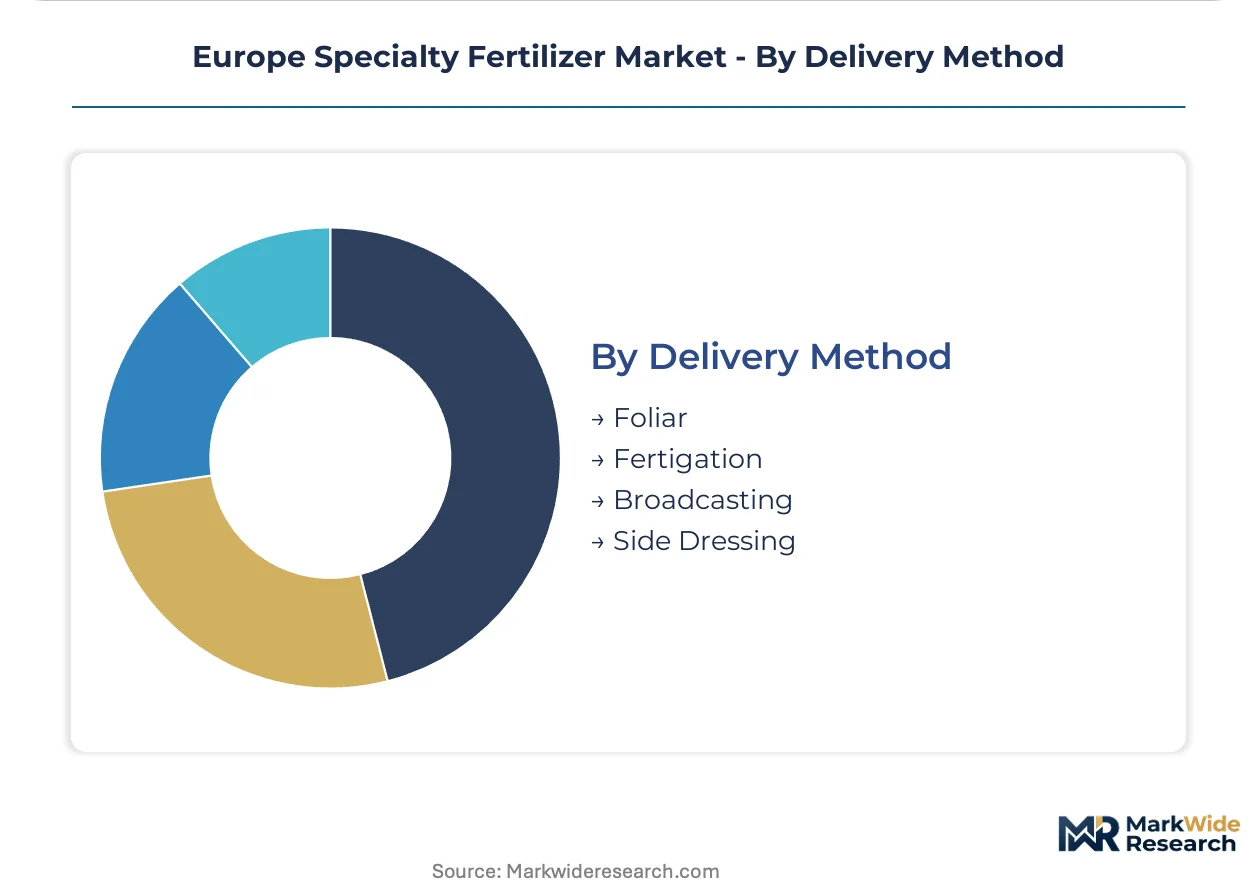
Delivery Method:
Application technology compatibility determines product specification requirements, with fertigation and foliar methods demanding higher purity and solubility standards than broadcast alternatives.
- Foliar:Direct leaf-surface application of micronutrient solutions or biostimulant suspensions for rapid uptake during critical growth stages. Polish orchard sectors lack access to chelated micronutrient programs.
- Fertigation:Nutrient delivery through irrigation water requiring complete solubility and compatibility with drip emitters and filtration systems. Spanish greenhouse operators synchronize delivery with real-time crop uptake data.
- Broadcasting:Surface or incorporated spreading of granular products via ground equipment or aerial platforms. Danish and Swedish drone-based variable-rate systems open direct-to-farmer channels.
- Side Dressing:Banded application alongside crop rows during vegetative growth for targeted nitrogen supplementation. German precision farming corridors favor this method for maize and sugar beet.
Broadcasting remains volume-dominant. Fertigation climbs fastest as protected cultivation and precision irrigation expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almería's greenhouse corridor anchors Europe's specialty fertilizer demand intensity, with Dutch precision farming clusters and German industrial agriculture zones completing the continent's nutrient innovation triangle.
Germany
Variable-rate application corridors in Lower Saxony and Bavaria drive demand for sensor-compatible liquid formulations. The F-Gas Regulation accelerates non-fluorinated polymer coating adoption across greenhouse operations. Erfurt-based blending facilities expand capacity for precision maize and sugar beet nutrition programs.
France
Intensive vegetable production in the Île-de-France and Hauts-de-France belts tightens synthetic input ceilings under EU Farm to Fork mandates. The national recovery plan channels subsidies toward organic conversion infrastructure. Lyon-formulated chelated micronutrients capture premium positioning in export-oriented viticulture.
Netherlands
Outcome-based contracting now governs greenhouse procurement, with operators specifying yield-per-unit-nitrogen metrics rather than tonnage. REACH dossier requirements for novel biostimulants compress registration timelines for fermentation startups. Wageningen research clusters pilot sensor-integrated fertigation synchronization systems.
Spain
Almería's protected cultivation corridor retrofits drip infrastructure with real-time uptake monitoring capabilities. The EU Green Deal's nutrient-loss targets force coating chemistry redesigns ahead of 2030 deadlines. Valencia-based formulators expand powder micronutrient capacity for Iberian citrus and olive foliar programs.
Italy
Lombardy and Emilia-Romagna fermentation facilities scale biostimulant co-formulation output under national organic conversion subsidies. ECHA's evolving microplastic criteria delay controlled-release product registrations. Po Valley cereal and horticulture operations integrate biological activators into conventional nutrient management protocols.
Europe Specialty Fertilizer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology and captive raw material access. The vendor base stratifies into integrated ammonia producers, phosphate rock controllers, and regional blending specialists. Three archetypes dominate: nitrogen specialists with hedging infrastructure, phosphate-integrated formulators with Black Sea logistics, and fermentation-based biostimulant innovators. Capacity expansion and portfolio diversification toward biological inputs represent the dominant competitive vectors.
Among Nordic-integrated producers, Yara International ASA occupies a position exemplifying ammonia network control. EuroChem Group AG represents the phosphate-anchored archetype with legacy Black Sea supply chain configurations. Grupa Azoty S.A sits within the Central European nitrogen specialization tier, anchoring ammonium nitrate supply for cereal production zones.
| Leading Market Players |
|---|
| ICL Group Ltd |
| Yara International ASA |
| EuroChem Group AG |
| Fertiberia |
| Kingenta Ecological Engineering Group Co., Ltd. |
| K+S AG |
| Grupa Azoty S.A |
| Haifa Chemicals Ltd. |
| CF Industries Holdings Inc. |
| Others |
Supply & Pricing Matrix
Backward integration into captive ammonia synthesis anchors margin stability for nitrogen-based specialty producers while exposing them to TTF hub volatility that compresses pricing power for unhedged blenders. The EU F-Gas Regulation and REACH polymer coating criteria reshape input sourcing decisions, forcing manufacturers to absorb reformulation costs or surrender premium positioning.
Pricing Analysis
Yield-per-unit-nitrogen guarantees now anchor Dutch greenhouse procurement contracts, displacing tonnage-based purchasing and transferring agronomic risk to suppliers. Three-tier pricing structure across premium, standard, and economy levels separates sensor-compatible liquid formulations from commodity granular blends, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard-tier nitrogen products is intensifying because natural gas price swings erode blender margins. Broad-acre cereal growers in Poland exhibit highest price sensitivity, while Almería vegetable producers accept premiums for precision fertigation compatibility.
Supply Chain Analysis
Domestic-content mandates under the EU Fertilizing Products Regulation are reshaping sourcing toward Lombardy and Emilia-Romagna fermentation facilities for biostimulant actives. Supply concentrates in Morocco and Russia for phosphate rock, Norway and the Netherlands for ammonia derivatives, and Germany for precision coating technologies. Raw material dependencies rest on natural gas feedstocks, polymer coating chemistries, and chelated micronutrient precursors. Single-source vulnerability runs through Strait of Gibraltar shipping routes for Moroccan phosphate. Distribution runs through agrochemical distributor networks, though drone-based direct-to-farmer channels are emerging in Denmark and Sweden.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological activation platforms are displacing synthetic hormone additives, compressing the premium gap between organic-certified and conventional specialty products and forcing incumbents to retool fermentation capacity or cede share.
For Market Incumbents: Acquire biostimulant fermentation assets to defend against organic conversion subsidies eroding synthetic nitrogen demand. Expand chitosan and lignin-based coating R&D ahead of ECHA microplastic substitution deadlines. Anchor position through captive phosphate rock access or Black Sea logistics partnerships to offset Moroccan supply concentration risk.
For New Entrants and Emerging Players: Direct-to-farmer drone application platforms offer lowest channel friction for bypassing established distributor networks in Scandinavian cereal zones. Target Poland's underpenetrated orchard sector for chelated micronutrient foliar programs. White-space exists in carbon farming certification integration for French and German broad-acre markets.
For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation-based biostimulant innovators with REACH dossier progress and Lombardy manufacturing footprints. Five-to-ten year viability favors integrated players with ammonia network control or captive mineral access. Watch ECHA polymer coating authorization timelines as inflection indicator for controlled-release product registration velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Synthesis | Yara-style network control insulates margins from TTF hub volatility across Nordic markets. |
| Biostimulant Fermentation Capacity Expansion | Lombardy and Emilia-Romagna facilities capture Italy's organic conversion subsidy flows. |
| Biodegradable Coating R&D Investment | Chitosan and lignin barriers secure early registration advantages under ECHA microplastic criteria. |
| Drone-Based Variable-Rate Application Partnership | Aerial spreading platforms bypass traditional distributors in Danish and Swedish cereal zones. |
| Carbon Farming Certification Integration | Verified soil carbon co-benefits unlock premium positioning in French and German broad-acre procurement. |
Research Methodology
Document review covered EU Fertilizing Products Regulation implementation guidance, ECHA polymer coating hazard classification protocols, and national recovery plan organic conversion allocations, complemented by interviews with plant managers at granulation facilities, procurement leads at greenhouse cooperatives, distribution channel partners, and technical R&D directors for coating formulation. Secondary validation drew from customs and trade data, Cefic fertilizer industry reports, and SEC 10-K filings for listed nitrogen producers. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Historical shipment data cross-referenced against expert panel input on coating chemistry transition timelines and biological input adoption curves. Segmentation dimensions modeled include product type, application intensity, form factor, and delivery method compatibility with precision irrigation infrastructure. CAGRs were derived through regression analysis of historical growth patterns adjusted for regulatory intervention effects. Forecast inputs incorporated EU Green Deal nutrient-loss reduction targets and F-Gas Regulation phase-down schedules.
Inputs from ECHA pre-registration consultations and national agricultural ministry subsidy disbursement records were available through the study window; gaps in real-time TTF hub forward curve data and proprietary blender hedging positions introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding coating substitution timelines and organic conversion subsidy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Asia-Pacific Specialty Fertilizer Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Global Urea Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Germany Fertilizer Market