
 Europe Agricultural Enzymes Market | 2026-2036
Europe Agricultural Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Enzymes Market Foresight
A shift from single-source enzyme procurement to multi-supplier blending programs is pivoting how European formulators manage input risk. Novozymes A/S leverages its Danish fermentation infrastructure to dominate bulk cellulase supply. BASF SE anchors its position through backward integration into proprietary strain development. AB Enzymes competes via specialized phosphatase formulations tailored to calcareous soils.
Europe agricultural enzymes comprise proteinaceous biocatalysts—typically derived from fungal or bacterial fermentation at 30–37°C—that accelerate biochemical reactions in rhizosphere and foliar applications. These molecules function primarily to unlock bound nutrients, degrade crop residues, and enhance plant stress tolerance under variable climatic conditions. Phosphatase formulations command premium positioning where phosphate fixation limits yield potential, while cellulase blends gain traction in no-till residue management systems across the End User segment. Soil Health applications lead current volume, though Crop Protection enzyme coatings represent the fastest-expanding margin pool as biological registration pathways shorten under EU regulatory reform.
EMA and EFSA jointly govern biocidal and food-chain enzyme claims, while the EU Green Deal's Farm to Fork strategy mandates synthetic input reductions that directly expand biological alternatives. REACH compliance and CE marking requirements for microbial inoculant formulations create non-tariff barriers favoring established European producers with dedicated regulatory affairs capacity. Stakeholders must track evolving F-Gas Regulation analogs for fermentation emissions and position strain libraries for dual-use claims across fertilizer and biostimulant categories.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing synthetic input windows and forcing formulators to rebuild product portfolios around biological catalysts. This regulatory compression is redrawing competitive boundaries between established chemical suppliers and specialized fermentation houses.
Growth Catalysts
- Phosphatase demand in calcareous soil zones:French cereal growers facing phosphate fixation are expanding enzyme-based nutrient unlocking programs. Premium formulations now penetrate the Paris Basin intensive farming corridor.
- EU Green Deal input restrictions:Synthetic pesticide reduction mandates under Farm to Fork are accelerating biological registration pathways for enzyme coatings. This policy compression directly expands addressable market for biocatalytic crop protection.
- No-till residue management adoption:Cellulase blends gain traction across Spain's specialty crop sector as minimum-tillage practices spread. Soil remediation applications in Mediterranean climates drive volume growth.
Market Restraints
- Fermentation feedstock volatility:Molasses and grain-based substrate costs fluctuate with commodity grain markets, compressing margin predictability for bulk cellulase producers.
- REACH compliance burden:Microbial inoculant registration requirements create non-tariff barriers favoring established European producers with dedicated regulatory affairs capacity.
- Synthetic fertilizer substitution economics:Ammonium nitrate and urea price cycles periodically narrow the cost gap with enzyme-based nutrient solutions, slowing adoption in price-sensitive segments.
Strategic Opportunities
- Poland's underpenetrated cereal belt:Eastern European intensive farming regions show low enzyme penetration relative to yield potential. Local distribution partnerships could unlock volume growth.
- Biostimulant-fertilizer dual-use claims:Evolving EU regulatory frameworks enable single products to register across multiple claim categories, expanding addressable revenue per formulation.
- Drone-based foliar application channels:Precision agriculture service providers are integrating enzyme coatings into aerial application protocols, creating new technical service partnerships.
Industry Challenges
- Fermentation strain optimization talent scarcity:Industrial microbiology and metabolic engineering expertise concentrates at specialized research institutes, constraining in-house R&D scaling.
- CE marking timeline compression:Microbial inoculant certification pathways require 18-24 month validation cycles, delaying product commercialization and freezing working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Enzymes Market |
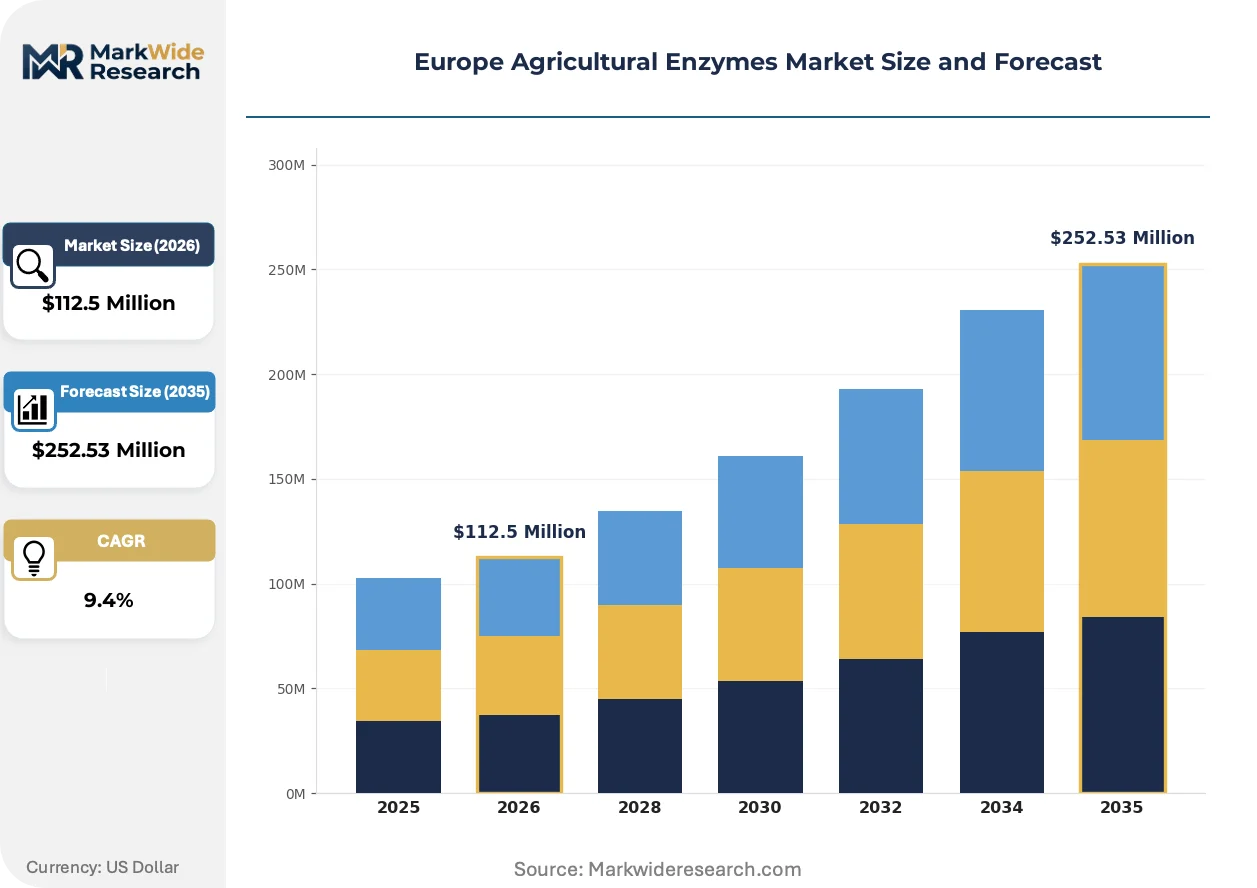
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $252.53 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylases, Proteases, Cellulases, Phosphatases Application: Soil Health, Crop Protection, Fertilizer Management, Plant Growth End User: Farmers, Agronomists, Research Institutions, Agricultural Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Agrochemical Suppliers |
| Companies Covered | Novozymes A/S, BASF SE, Syngenta AG, AB Enzymes, BioWorks Inc, Biolchim SPA, Stoller Europe, Elemental Enzymes, DuPont de Nemours, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Enzymes Market Shifts & Advancements
Multi-enzyme consortia are displacing single-active formulations as European formulators seek to compress input complexity and reduce supplier count. This formulation convergence is redrawing technical service relationships across the value chain.
Metagenomic screening platforms are unifying enzyme discovery with strain optimization workflows. Danish fermentation houses deploy these tools to compress development cycles for temperature-tolerant cellulase variants. The technology is unifying previously separate R&D silos and enabling rapid customization for specific soil microbiome conditions.
EMA and EFSA regulatory convergence is compressing biocidal and food-chain claim pathways. Joint guidance documents now enable parallel rather than sequential registration processes. Enzyme coating suppliers targeting crop protection applications benefit most, with registration timelines shortening for foliar treatment categories.
Specialty crop producers in Spain are consolidating procurement through cooperative blending programs. These farmer-owned entities now contract directly with fermentation houses for customized phosphatase-cellulase ratios. Mediterranean vegetable and fruit operations lead this channel disintermediation, bypassing traditional agrochemical distributors.
Europe Agricultural Enzymes Market Segmentation
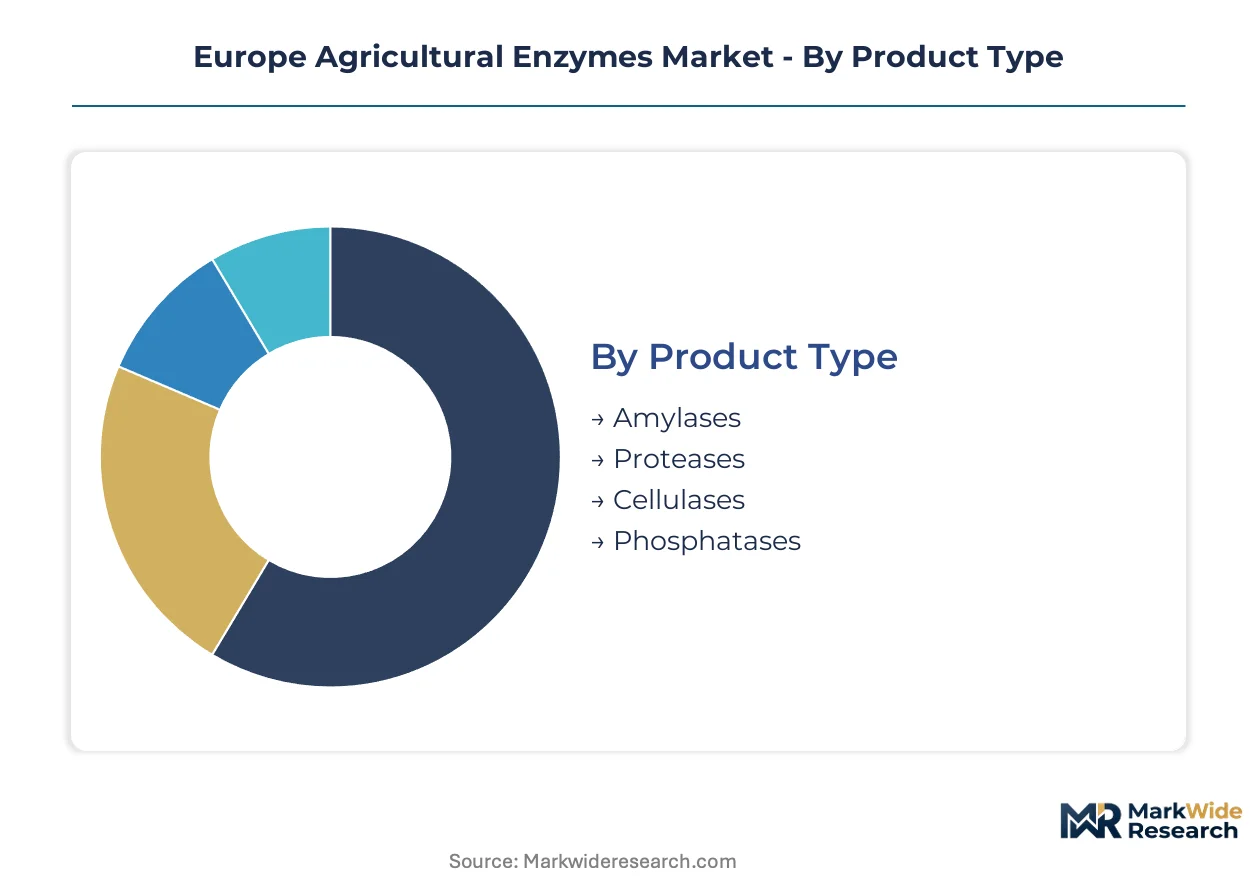
European agricultural enzyme procurement patterns diverge sharply across buyer sophistication tiers and application intensity. Formulators and end-users prioritize different performance specifications, creating distinct margin pools within each segment category.
Product Type:
Buyers differentiate primarily by soil chemistry constraints and residue management protocols rather than price sensitivity.
- Phosphatases:These enzymes catalyze the hydrolysis of organic phosphate esters into plant-available inorganic forms. French cereal growers in the Paris Basin deploy premium phosphatase formulations where calcareous soils lock phosphate in insoluble complexes. EFSA registration pathways for biostimulant claims now enable dual-use positioning.
- Cellulases:Multi-component enzyme systems depolymerize cellulose into fermentable sugars and soil-conditioning humic precursors. Spanish specialty crop producers in Valencia and Murcia drive adoption for post-harvest residue decomposition under no-till regimes. EU Green Deal residue reduction mandates accelerate procurement.
- Amylases:Starch-degrading enzymes facilitate seed coating applications and pre-planting soil conditioning. Italian maize growers in the Po Valley represent concentrated demand.
- Proteases:Protein-hydrolyzing biocatalysts support organic fertilizer activation and composting acceleration. German biodynamic farming cooperatives constitute the core customer base.
Cellulases lead volumes today; phosphatases are gaining share fastest.
Application:
Application selection tracks regulatory pressure intensity and input substitution economics across member states.
- Soil Health:Enzyme consortia rebuild microbial biomass and accelerate organic matter mineralization. This segment commands the largest current volume across France, Spain, and Germany as intensive farming regions confront soil degradation metrics under EU soil monitoring directives.
- Crop Protection:Enzyme-based coatings disrupt pathogen cell walls and induce systemic acquired resistance. EMA biocidal registration convergence with EFSA food-chain pathways shortens commercialization timelines for foliar treatments.
- Fertilizer Management:Nutrient unlocking formulations reduce synthetic phosphate and nitrogen application rates. Polish cereal operations show emerging procurement interest.
- Plant Growth:Biostimulant-registered enzymes modulate hormone signaling and abiotic stress response. Mediterranean horticulture clusters drive premium pricing.
Soil Health dominates current procurement; Crop Protection exhibits the steepest expansion trajectory.
End User:
End-user category reflects technical service requirements and formulation complexity tolerance.
- Farmers:Direct procurement concentrates in large-scale cooperative structures, particularly French CUMAs and Spanish SATs. These entities now contract fermentation houses for customized multi-enzyme blends.
- Agricultural Companies:Integrated input suppliers blend enzymes into proprietary biostimulant and biofertilizer portfolios. REACH compliance capacity determines supplier qualification.
- Agronomists:Technical advisors specify enzyme programs for client farms, functioning as de facto distribution gatekeepers in Italy and Portugal.
- Research Institutions:Wageningen University and INRAE trial stations generate strain performance data that shapes commercial adoption curves.
Farmers represent the largest addressable base; Agricultural Companies are consolidating procurement fastest.
Distribution Channel:
Channel selection correlates with buyer scale and regulatory documentation requirements.
- Distributors:Traditional agrochemical distribution networks retain dominance in fragmented smallholder markets across Eastern Europe. These intermediaries provide CE marking documentation and storage compliance.
- Direct Sales:Large cooperative buyers and multinational agricultural companies bypass intermediaries to negotiate volume contracts with Novozymes A/S and BASF SE fermentation facilities.
- Agrochemical Suppliers:Integrated input retailers bundle enzymes with synthetic fertilizer and crop protection portfolios, particularly in Germany's BayWa and France's InVivo networks.
- Online Retail:Digital procurement channels emerge for standardized enzyme formulations in specialty crop segments with established CE marking and usage protocols.
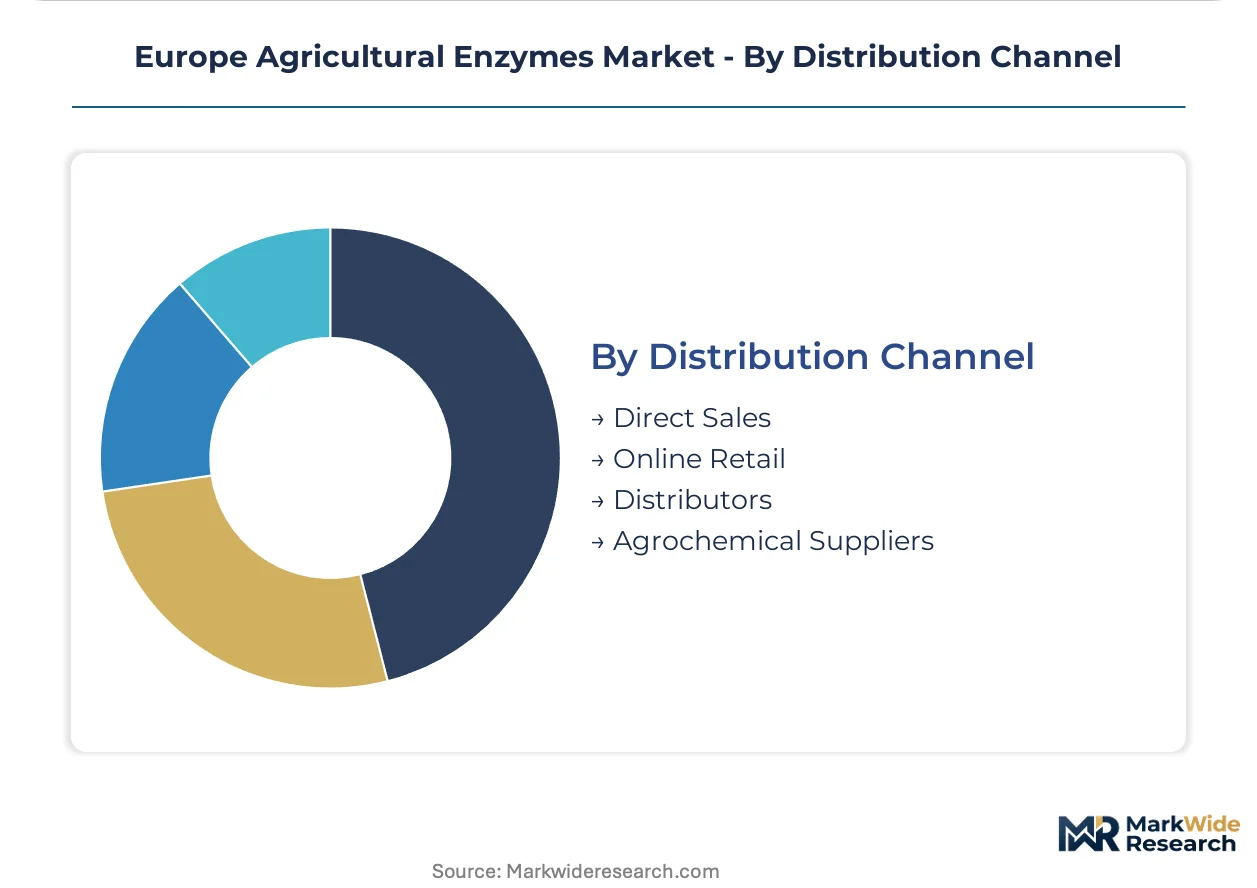
Distributors retain volume leadership today; Direct Sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paris Basin intensive farming corridor anchors European enzyme demand, where calcareous soil chemistry and phosphate fixation pressures concentrate procurement of premium phosphatase formulations. France, Spain, Germany, Poland, and Italy collectively shape regional adoption curves through divergent regulatory pressures and soil management protocols.
France
Cereal growers in the Paris Basin deploy phosphatase-cellulase blends to unlock fixed phosphate in high-pH soils. The EU Green Deal's Farm to Fork strategy mandates synthetic input reductions that expand biological alternatives. Cooperative blending programs in Île-de-France and Hauts-de-France now contract directly with fermentation houses for customized multi-enzyme ratios.
Spain
Specialty crop producers in Valencia and Murcia drive cellulase adoption for post-harvest residue decomposition under no-till regimes. EFSA biostimulant registration pathways enable dual-use claims for soil remediation products. Farmer-owned cooperatives in Andalusia are consolidating procurement through direct fermentation house contracts, bypassing traditional distributors.
Germany
Biodynamic farming cooperatives in Bavaria and Baden-Württemberg constitute the core protease demand base for organic fertilizer activation. REACH compliance requirements create non-tariff barriers favoring established producers with dedicated regulatory affairs capacity. BayWa distribution networks bundle enzymes with synthetic input portfolios across the Po Valley corridor.
Poland
Eastern European cereal operations show emerging procurement interest in nutrient unlocking formulations as intensive farming expands. The EU soil monitoring directives pressure yield-maximizing regions to adopt soil health interventions. Local distribution partnerships in the Masovian and Greater Poland voivodeships could unlock volume growth in underpenetrated acreage.
Italy
Maize growers in the Po Valley represent concentrated amylase demand for seed coating and pre-planting soil conditioning. Agronomists function as de facto distribution gatekeepers, specifying enzyme programs for client farms across Lombardy and Emilia-Romagna. CE marking requirements for microbial inoculant formulations delay commercialization timelines for new entrants.
Europe Agricultural Enzymes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized phosphatase formulations for calcareous soil zones. The market structure concentrates around fermentation houses with backward integration into proprietary strain development and chemical conglomerates diversifying into biological portfolios. Three archetypes dominate: Danish fermentation specialists leveraging temperature-tolerant cellulase variants, German chemical majors with regulatory compliance scale, and Italian-Spanish cooperative suppliers serving Mediterranean horticulture clusters. Competitive moves center on multi-supplier blending program partnerships and drone-based foliar application channel development.
Within the fermentation specialist tier, Novozymes A/S and AB Enzymes exemplify divergent positioning strategies. Novozymes A/S anchors the bulk cellulase supply segment through Danish infrastructure scale. AB Enzymes occupies a specialized position in phosphatase formulations tailored to high-pH soil chemistry. BASF SE represents the chemical conglomerate archetype, integrating biological catalysts into broader agricultural input portfolios. These three entities collectively illustrate how regulatory compliance capacity and strain library depth determine tier placement in European procurement.
| Leading Market Players |
|---|
| Novozymes A/S |
| BASF SE |
| Syngenta AG |
| AB Enzymes |
| BioWorks Inc |
| Biolchim SPA |
| Stoller Europe |
| Elemental Enzymes |
| DuPont de Nemours |
| Others |
Supply & Pricing Matrix
Metagenomic screening platforms are compressing R&D cycles for temperature-tolerant cellulase variants while simultaneously concentrating production among Danish and German fermentation houses with capital-intensive infrastructure. This technological shift rewards scale players who can amortize strain optimization costs across bulk volumes, while smaller formulators face margin compression from feedstock volatility and REACH compliance burdens.
Pricing Analysis
Molasses and grain-based substrate costs pass through directly to enzyme pricing, with bulk cellulase producers absorbing commodity grain market fluctuations that compress margin predictability. Three-tier pricing structure across premium, standard, and economy levels separates phosphatase formulations for calcareous soils from commodity cellulase blends. Pricing pressure stems from synthetic fertilizer substitution economics, where ammonium nitrate and urea price cycles periodically narrow the cost gap with enzyme-based nutrient solutions. Smallholder segments in Eastern Europe exhibit highest price sensitivity; large French cooperatives in the Paris Basin tolerate premium positioning for specialized phosphatase-cellulase blends.
Supply Chain Analysis
Refrigerated freight costs for temperature-sensitive fermentation outputs constrain distribution radius from production hubs in Denmark, Germany, and the Netherlands. Raw material dependencies center on molasses substrates from sugar beet processing, proprietary fungal and bacterial strain libraries, and specialized bioreactor equipment. Single-source vulnerability concentrates in bulk cellulase supply where Novozymes A/S dominates through Danish infrastructure scale. Distribution runs through traditional agrochemical networks in fragmented Eastern European markets, while direct sales channels expand among large cooperative buyers in France and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe agricultural enzymes function as a geographic-arbitrage play where Polish and Romanian cereal operations face EU soil monitoring directives without the regulatory compliance capacity of Western European incumbents, creating cost-advantaged entry windows for mid-tier formulators.
For Market Incumbents: To counter emerging fermentation houses in Southern Europe, Novozymes A/S and BASF SE should deepen backward integration into proprietary strain development and expand direct contracting relationships with French CUMAs and Spanish SATs to lock in volume offtake. Capacity investments in temperature-tolerant cellulase production at existing Danish and German facilities would reinforce bulk supply dominance against specialized phosphatase challengers. For New Entrants and Emerging Players: Metagenomic screening capabilities offer entry wedges into underpenetrated Polish and Romanian cereal belts where intensive farming expansion meets low enzyme adoption rates. Target nutrient unlocking formulations for calcareous soil zones in Eastern Europe, leveraging shorter CE marking pathways for biostimulant-registered products. Direct technical service partnerships with agronomist networks in Italy and Portugal provide go-to-market traction without distributor margin stacking. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Italian and Spanish cooperative suppliers serving Mediterranean horticulture clusters with specialized phosphatase-cellulase blending capabilities. Long-term viability hinges on dual-use biostimulant-fertilizer registration positions that expand addressable revenue per formulation. Watch for EMA-EFSA regulatory convergence milestones as inflection indicators for crop protection enzyme coating commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | BASF SE's proprietary fermentation libraries reduce royalty costs and accelerate product customization for calcareous soil zones. |
| Direct Cooperative Contracting | Farmer-owned entities in Île-de-France and Andalusia now bypass distributors to negotiate volume-based multi-enzyme formulations. |
| Biostimulant-Fertilizer Dual Registration | EFSA pathway convergence enables single products to claim across multiple regulatory categories, expanding per-unit revenue capture. |
| Drone-Based Foliar Application Partnerships | Precision agriculture service providers in Spain integrate enzyme coatings into aerial protocols, creating technical service lock-in. |
| Eastern European Distribution Partnerships | Local alliances in Masovian and Greater Poland voivodeships unlock volume growth in underpenetrated intensive cereal acreage. |
Research Methodology
Direct dialogue with fermentation plant managers, regulatory affairs specialists at EFSA and ECHA, procurement leads at French agricultural cooperatives, and technical directors at biostimulant formulators grounded qualitative findings in operational reality. Secondary validation drew from REACH registration databases, EU Green Deal policy documentation, Cefic sector reports, and customs trade data for molasses and enzyme product flows. Bottom-up volume estimates from individual country-level procurement patterns triangulated against top-down market sizing from fermentation capacity utilization rates across the analysis window.
Segment-level projections for phosphatase, cellulase, amylase, and protease categories incorporated soil chemistry constraints, residue management protocol adoption curves, and regulatory compression timelines under Farm to Fork mandates. CAGRs derived from weighted average of historical procurement growth rates and policy-driven substitution elasticity assumptions, with cross-checks against bioreactor capacity expansion announcements and strain patent filings. Modeled variables included temperature-tolerant variant adoption rates, no-till acreage expansion in Mediterranean zones, and dual-use registration pathway completion timelines.
The model holds under stable EU regulatory enforcement and gradual synthetic input reduction schedules; deviation in fertilizer price volatility or accelerated F-Gas Regulation analogs for fermentation emissions would shift adoption trajectories. Forecasts embed assumptions about EMA-EFSA convergence timelines and cooperative procurement consolidation patterns. Stakeholders should weight assumptions against their own operating context and regulatory compliance capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Agricultural Drones Market