
 Single Superphosphate (SSP) Market | 2026-2036
Single Superphosphate (SSP) Market Size, Share, and Industry Trends Forecast 2026-2036
Single Superphosphate (SSP) Market Intelligence
Customized blend formulation services, which pair soil analysis with tailored nutrient mixes, is expanding the value proposition beyond bulk SSP sales. Coromandel International Limited leverages its extensive distribution network in South Asia to offer such value-added products. Meanwhile, The Mosaic Company specializes in high-purity phosphate production for both direct application and complex fertilizer manufacturing. In Europe, Yara International ASA positions its SSP products within broader crop nutrition programs.
Single Superphosphate (SSP) is a phosphate fertilizer produced by reacting rock phosphate with sulfuric acid. It typically contains 16-22% phosphorus pentoxide (P2O5) and also supplies essential secondary nutrients like sulfur and calcium, making it a multi-nutrient source for crops. Granular SSP holds the largest market share due to its ease of handling and application with mechanical spreaders, while powdered SSP is used for specific soil amendment needs. Demand for SSP in cereal crops and oilseeds remains foundational, with applications in horticulture representing a niche, higher-margin segment.
Regulatory frameworks governing fertilizer composition and soil health, such as the EU's REACH and the US EPA's nutrient management guidelines, shape market access and product standards. In India, government subsidies administered through agencies like the Department of Fertilisers influence procurement patterns among farming cooperatives. Producers must now navigate a complex landscape balancing raw material costs with evolving demands for nutrient efficiency and environmental stewardship.
Market Dynamics
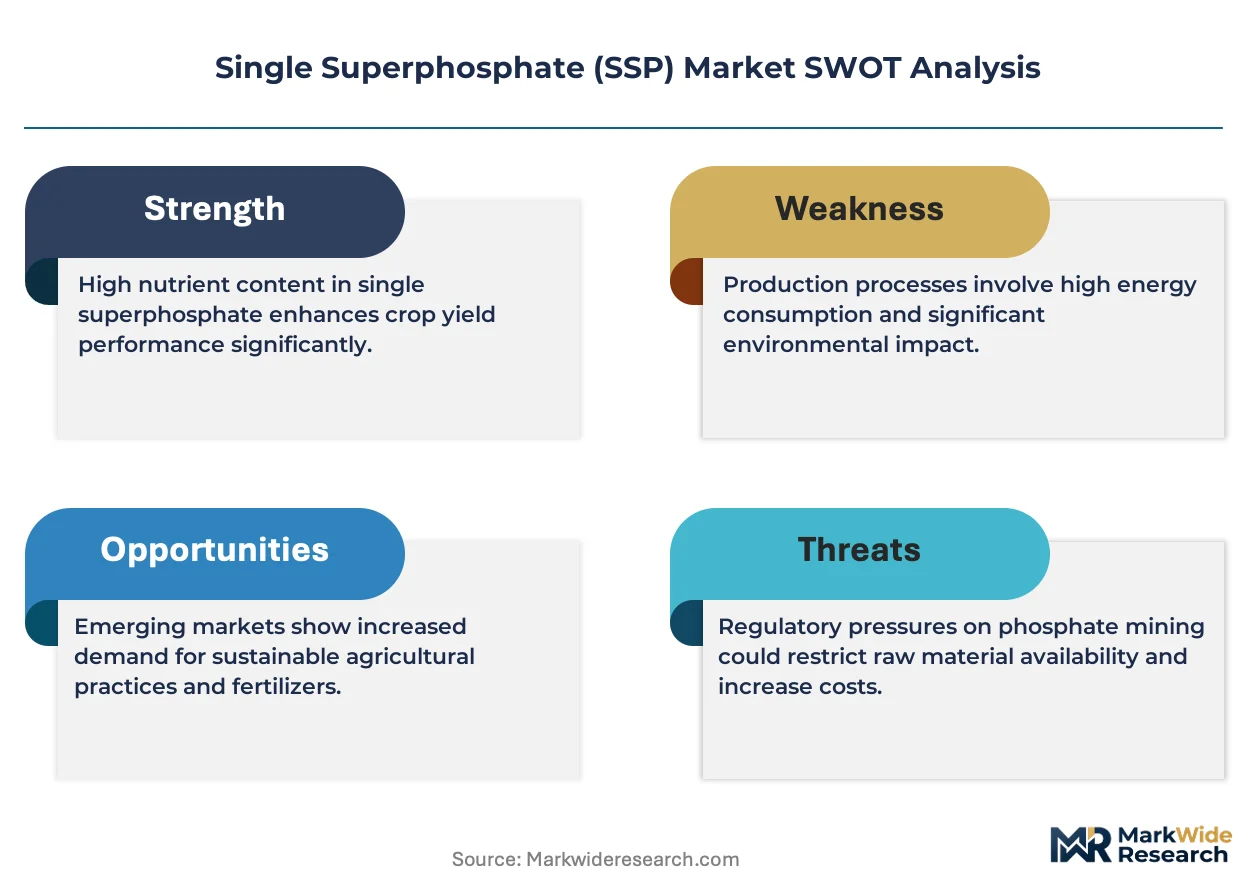
The central market dynamic is the push for nutrient use efficiency, forcing a shift from commodity sales toward value-added, customized formulations tailored to specific soil and crop needs.
Growth Catalysts
- Government Subsidies:In India, subsidies via the Department of Fertilisers maintain SSP affordability for farmers, sustaining demand for cereal crops.
- Multi-Nutrient Value:The inherent sulfur and calcium in SSP addresses secondary nutrient deficiencies, benefiting crops like oilseeds and legumes.
- Soil Health Focus:A growing emphasis on balanced fertilization to improve soil structure drives adoption of SSP for its calcium and sulfur content.
Market Restraints
- Raw Material Volatility:Production costs are directly exposed to volatile prices for rock phosphate and sulfuric acid, compressing manufacturer margins.
- Competition from Concentrated Phosphates:Higher-analysis fertilizers like DAP and MAP offer superior logistical efficiency due to greater phosphorus content per unit weight.
- Regulatory Compliance Burden:Frameworks such as the EU's REACH increase costs by setting limits on impurities in phosphate rock and governing emissions.
Strategic Opportunities
- Fortification with Micronutrients:Developing SSP products fortified with zinc or boron addresses specific soil deficiencies and allows for premium pricing.
- Expansion in African Markets:Sub-Saharan Africa's agricultural regions with phosphorus and sulfur deficiencies represent a large, underpenetrated market for SSP application.
- Custom Blending Services:Offering tailored SSP blends based on soil analysis provides a path away from commodity pricing toward value-added services.
Industry Challenges
- Logistical Inefficiency:The high-bulk, low-nutrient-density nature of SSP results in significant transportation and handling costs, particularly for reaching remote farming communities.
- Subsidy Program Complexity:Navigating disparate and often bureaucratic national subsidy programs, such as those in India, requires significant administrative overhead and can delay payments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Superphosphate (SSP) Market |
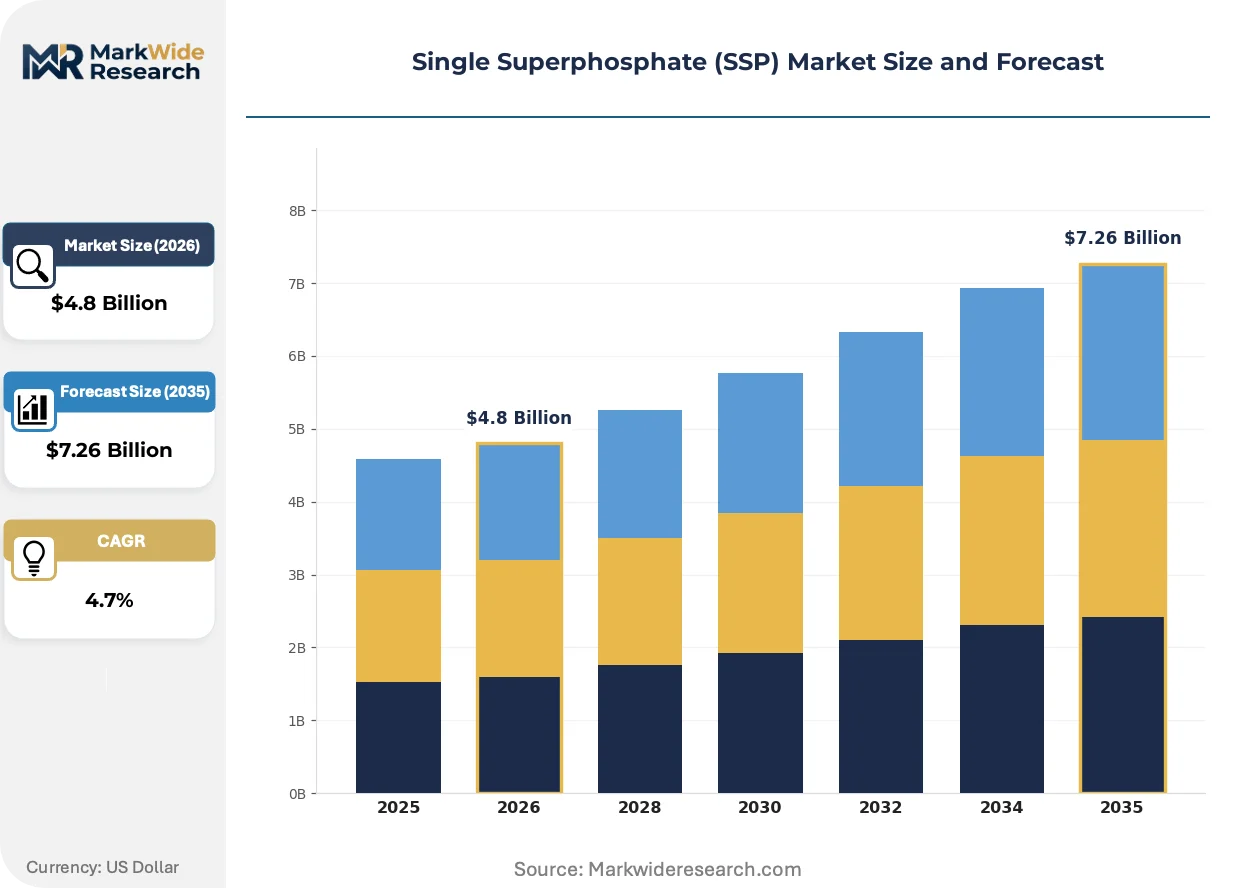
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular SSP, Powdered SSP, Liquid SSP, Customized Blends Application: Cereal Crops, Oilseeds, Pulses, Horticulture, Plantation Crops End Use Industry: Farming Cooperatives, Independent Growers, Agricultural Consultants, Government Agencies Packaging Type: Jute Bags, Polypropylene Bags, Bulk Containers, Paper Bags |
| Companies Covered | The Mosaic Company, Coromandel International Limited, ICL Group Limited, PCC Group, Yara International ASA, Gujarat Narmada Valley Fertilizers & Chemicals, Madhya Bharat Agro Products Limited, Jubilant Industries Ltd, OCP Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Superphosphate (SSP) Market Strategic Shifts & Innovations
Product development focuses on enhancing nutrient use efficiency and environmental performance. Innovations are moving beyond simple P2O5 content to include secondary nutrient delivery, improved physical forms, and integration with digital farming platforms.
Precision agriculture technology, including soil sensors and GPS-guided spreaders, enables variable-rate application of fertilizers. Large-scale commercial farms in North America and Europe are steadily adopting these systems. This technology is rewriting the traditional model of uniform fertilizer application, shifting value toward products compatible with data-driven nutrient management plans.
Regulatory frameworks like the EU Green Deal and its Farm to Fork strategy mandate reductions in nutrient losses to the environment. This directly incentivizes the development of fertilizers with improved uptake efficiency. European producers and importers are most affected, responding with enhanced SSP formulations and integrated crop nutrition programs that document efficient use.
A clear shift is underway from transactional purchases of bulk fertilizer to acquiring integrated agronomic solutions. This model disrupts traditional distributors by bundling soil testing, customized nutrient blends, and application advice into a single service package. This trend is most prominent among large agricultural cooperatives in the US and progressive farming enterprises in Brazil.
Single Superphosphate (SSP) Market Segmentation
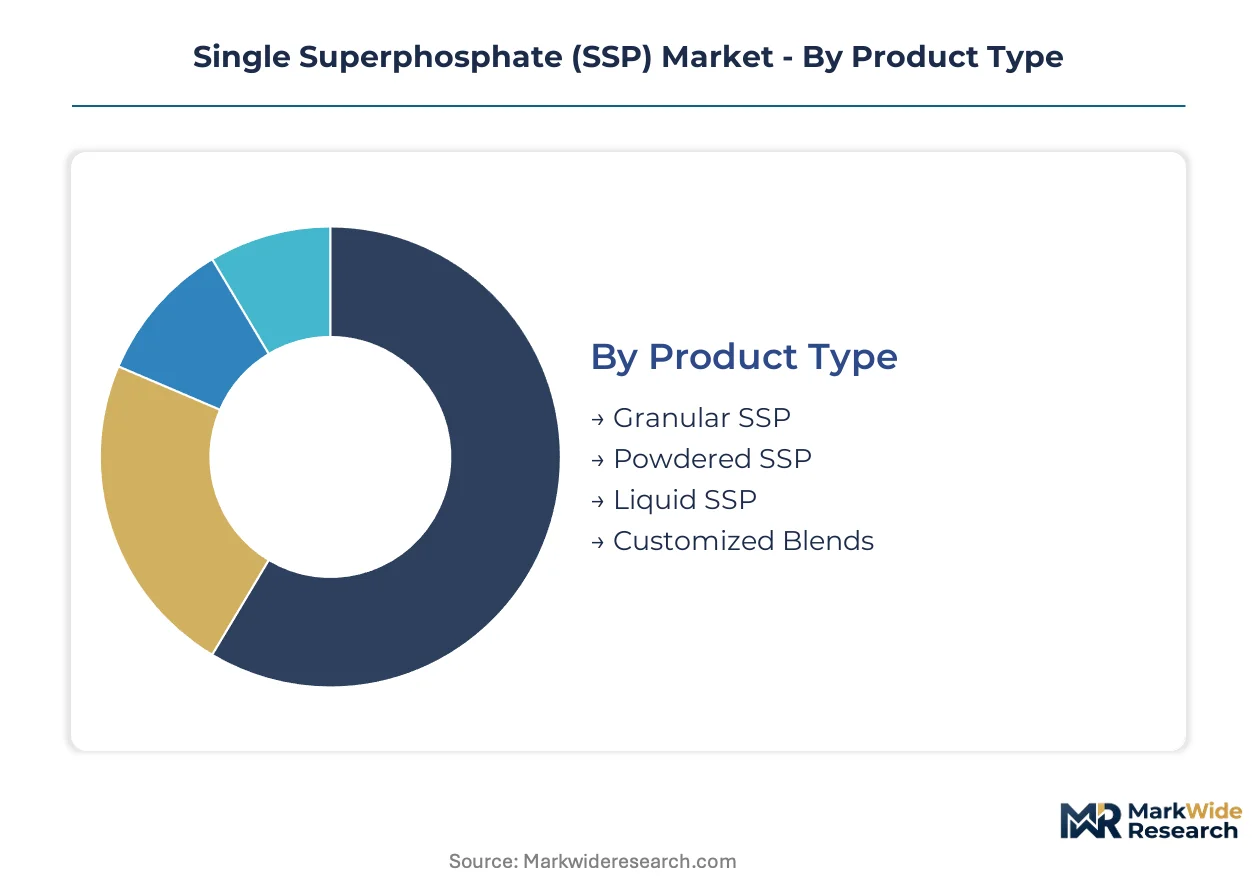
Market segmentation for single superphosphate reveals distinct product forms, application areas, and end-user profiles. Understanding these segments is crucial for manufacturers to align product development and distribution strategies with specific market demands and regulatory landscapes.
Product Type:
The customization-vs-standardization spectrum defines product type segmentation, ranging from bulk commodities to tailored formulations.
- Granular SSP:This form represents the largest market share due to its excellent handling properties and compatibility with mechanical spreading equipment. Granular SSP provides consistent nutrient distribution across large agricultural fields, particularly for cereal crops in India.
- Customized Blends:These formulations combine SSP with other nutrients or micronutrients, tailored to specific soil analysis results and crop requirements. Demand for customized blends is concentrating among progressive farming enterprises in Europe, driven by precision agriculture initiatives.
- Powdered SSP:This fine particulate form is often used for direct soil amendment or in specific applications requiring rapid nutrient release. Powdered SSP addresses immediate nutrient deficiencies in smaller plots or specialized horticulture.
- Liquid SSP:This niche product form offers precise application through irrigation systems, providing targeted nutrient delivery. Liquid SSP serves specialized agricultural practices focused on high-value crops.
Most installed capacity flows through Granular SSP. Expansion is steepest in Customized Blends.
Application:
Application segmentation reflects diverse crop nutritional needs and cultivation practices across agricultural regions.
- Cereal Crops:This segment constitutes the foundational demand for SSP, driven by the extensive cultivation of wheat, rice, and maize globally. SSP application in cereal crops addresses widespread phosphorus deficiencies and supports food security initiatives in countries like India.
- Horticulture:This niche segment, encompassing fruits, vegetables, and ornamental plants, represents a higher-margin opportunity for SSP producers. Horticulture applications often require specific nutrient balances, prompting interest in enhanced SSP formulations.
- Oilseeds:Crops such as soybeans, rapeseed, and sunflowers benefit significantly from the sulfur content in SSP, improving oil content and yield. Oilseeds cultivation in North America and Brazil drives consistent SSP demand.
- Pulses:Leguminous crops like lentils and chickpeas utilize SSP for both phosphorus and sulfur, enhancing nitrogen fixation and overall plant vigor. Pulses production in arid and semi-arid regions relies on efficient nutrient delivery.
- Plantation Crops:Perennial crops like tea, coffee, and rubber require sustained nutrient supply over long growth cycles, making SSP a suitable choice for foundational fertilization. Plantation crops in Southeast Asia utilize SSP for long-term soil health.
Demand for Cereal Crops remains foundational, while Horticulture exhibits strong growth potential.
End Use Industry:
End-use industry segmentation highlights distinct procurement channels and decision-making processes for fertilizer acquisition.
- Farming Cooperatives:These organizations aggregate demand from numerous small and medium-sized farmers, influencing procurement patterns through collective bargaining and government subsidy programs. Farming cooperatives in India manage significant SSP volumes for their members.
- Independent Growers:Individual farmers, ranging from smallholders to large commercial operations, directly purchase SSP based on their specific crop plans and soil conditions. Independent growers in Europe increasingly adopt customized blends for precision agriculture.
- Agricultural Consultants:These advisory services recommend specific fertilizer types and application rates to their client farmers, influencing product selection based on agronomic expertise. Agricultural consultants in the US guide nutrient management for commercial farms.
- Government Agencies:National and regional agricultural departments procure and distribute SSP, often as part of subsidy schemes or food security programs. Government agencies in Africa support smallholder farmers through subsidized fertilizer distribution.
Procurement patterns largely center on Farming Cooperatives, with Independent Growers increasingly influencing product selection.
Packaging Type:
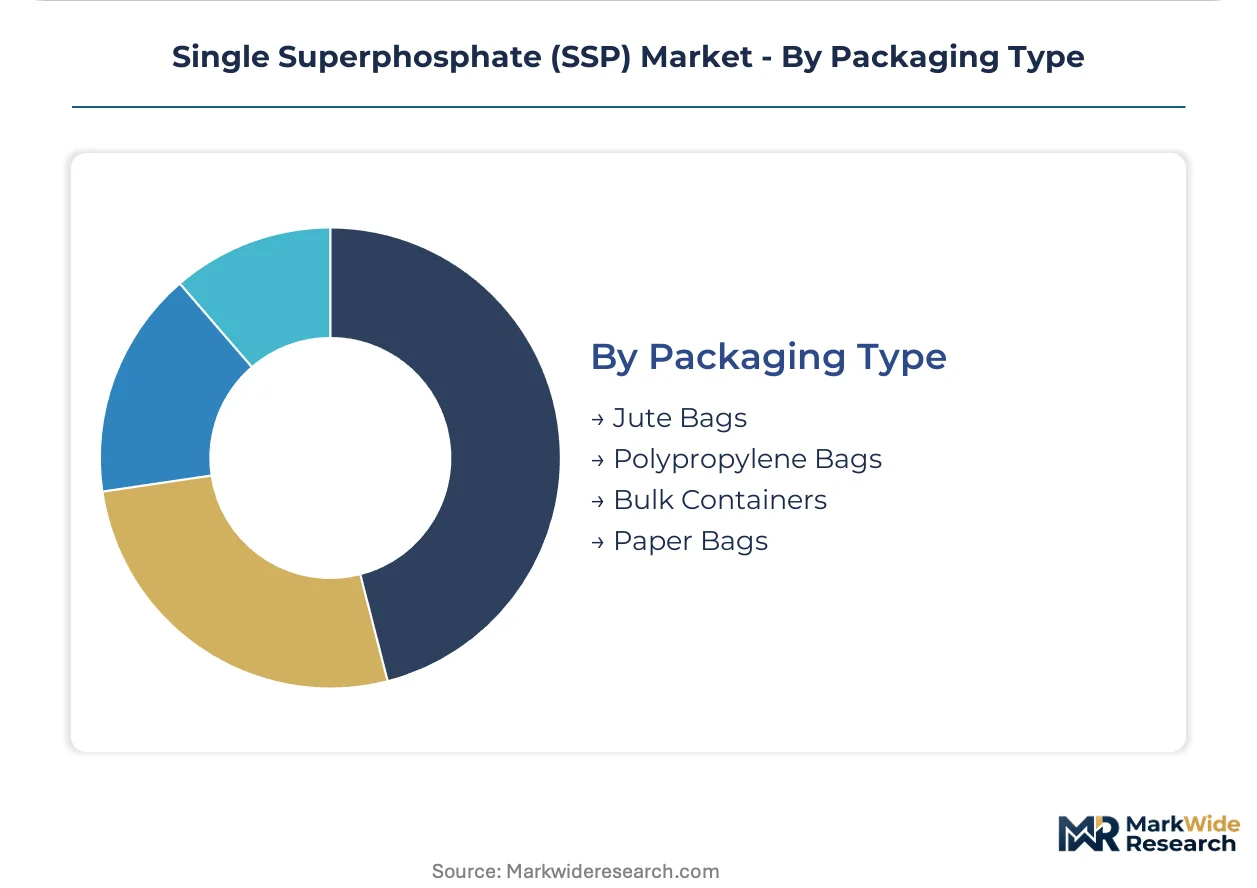
Packaging type segmentation is driven by logistical efficiencies and varying scales of agricultural operations, influencing handling and storage.
- Polypropylene Bags:These durable, moisture-resistant bags are the most common packaging choice for SSP, facilitating transport and storage for farmers. Polypropylene bags are widely used across all agricultural regions due to their cost-effectiveness.
- Bulk Containers:Large-scale agricultural operations and fertilizer blenders utilize bulk containers for cost-efficient transportation and handling of massive SSP volumes. Bulk containers are prevalent in major agricultural economies like Brazil.
- Jute Bags:Traditionally used in some regions, jute bags offer biodegradability but provide less moisture protection compared to synthetic alternatives. Jute bags serve localized markets with specific environmental preferences.
- Paper Bags:These bags are less common for SSP due to moisture susceptibility, but find use in specific niche markets or for smaller quantities. Paper bags offer an environmentally friendly option for specialized applications.
Efficiency in distribution relies heavily on Polypropylene Bags, while Bulk Containers support large-scale industrial farming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's significant government subsidies sustain demand for Single Superphosphate, contrasting with Europe's focus on nutrient efficiency driven by environmental regulations. Agricultural economies worldwide balance food security imperatives with evolving demands for sustainable farming practices. This dynamic influences SSP consumption patterns across diverse regions.
India
Demand for SSP in India primarily stems from extensive cultivation of cereal crops, supporting national food security initiatives. The Department of Fertilisers administers subsidies, maintaining product affordability for farmers. Farming cooperatives in states like Uttar Pradesh manage large SSP procurement volumes for their members.
Brazil
Brazil's vast agricultural sector drives SSP demand, particularly for oilseeds like soybeans, which benefit from the fertilizer's sulfur content. The Ministry of Agriculture, Livestock and Food Supply (MAPA) promotes efficient fertilizer use to optimize crop yields. Large-scale commercial farms in Mato Grosso utilize SSP for foundational soil health management.
United States
Cereal crop production and the adoption of precision agriculture techniques drive SSP application in the United States. US EPA nutrient management guidelines influence product formulations and application methods for environmental stewardship. Commercial farms in the Corn Belt region, including Iowa, increasingly integrate customized SSP blends.
Germany
Germany's agricultural sector emphasizes sustainable farming and nutrient use efficiency, aligning with broader European environmental goals. The EU Green Deal mandates reductions in nutrient losses, encouraging enhanced SSP formulations. Progressive farming enterprises in Bavaria incorporate SSP into integrated crop nutrition programs.
South Africa
South Africa represents a significant market opportunity for SSP, addressing widespread phosphorus and sulfur deficiencies in agricultural soils. The Department of Agriculture, Land Reform and Rural Development supports initiatives for improved fertilizer efficiency. Commercial farms in the Western Cape region seek tailored nutrient solutions for diverse crops.
Single Superphosphate (SSP) Market Key Industry Players
Top-tier vendors anchor global supply, while regional players offer specialized solutions for localized agricultural needs. The market exhibits a tiered structure with significant fragmentation in local distribution channels. Strategic archetypes include integrated global producers, regional specialists focused on specific crop requirements, and emerging players emphasizing sustainable formulations. Key competitive moves involve expanding value-added services and exploring new agricultural markets.
Among global phosphate producers, The Mosaic Company represents a major player specializing in high-purity phosphate for direct application and complex fertilizers. Coromandel International Limited, an India-based entity, exemplifies regional strength through its extensive distribution network and customized blend formulation services in South Asia. Yara International ASA, a European firm, positions its SSP products within broader crop nutrition programs, highlighting a focus on integrated agronomic solutions. These companies collectively demonstrate the market's diverse approaches to product and service delivery.
| Leading Market Players |
|---|
| The Mosaic Company |
| Coromandel International Limited |
| ICL Group Limited |
| PCC Group |
| Yara International ASA |
| Gujarat Narmada Valley Fertilizers & Chemicals |
| Madhya Bharat Agro Products Limited |
| Jubilant Industries Ltd |
| OCP Group |
| Others |
Cost & Logistics Intelligence
Vertically integrated global producers, alongside regional specialists, influence SSP supply behavior and pricing discipline by managing raw material access and distribution networks.
Pricing Analysis
Capacity additions in India are reshaping price floors, particularly for granular SSP. Transactional, per-unit pricing dominates for bulk SSP, while customized blends command value-based pricing. Price differentiation stems from P2O5 content and geographic delivery costs. Raw material volatility for rock phosphate and sulfuric acid creates pricing pressure. Farming cooperatives, influenced by subsidies, exhibit high price sensitivity, contrasting with lower sensitivity among commercial farms seeking tailored solutions.
Supply Chain Analysis
Regulatory frameworks like EU REACH and national fertilizer standards gate market access and influence supply chain configurations. Supply concentrates in major phosphate rock-producing nations like Morocco and in large processing hubs in China and India. The SSP supply chain draws from rock phosphate and sulfuric acid. Logistical inefficiency due to SSP's bulk nature presents a structural risk. Distribution runs through extensive networks of farming cooperatives and independent agricultural distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Single Superphosphate market presents a geographic-arbitrage play, with India's subsidy-driven affordability contrasting sharply with Europe's regulatory push for nutrient use efficiency and lower environmental impact.
For Market Incumbents: Hedge against raw material price volatility by securing long-term rock phosphate supply contracts in Morocco. Invest in advanced granulation technologies to reduce logistical inefficiency and compete with concentrated phosphates. Diversify product portfolios with micronutrient-fortified SSP to counter margin pressure from commodity sales. Expanding value-added services like soil analysis and custom blending strengthens customer loyalty.
For New Entrants and Emerging Players: Digital farming platforms offer a direct channel to progressive growers in Europe and North America. Target the horticulture segment with specialized liquid SSP formulations for high-value crops. Focus on Sub-Saharan Africa's underpenetrated agricultural regions with tailored SSP products addressing phosphorus and sulfur deficiencies. A go-to-market strategy emphasizing agronomic support and precision application services can build market trust.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional SSP producers lacking advanced blending capabilities. Long-term viability for SSP hinges on its multi-nutrient value and role in sustainable soil health over the next decade. Target acquisition archetypes include specialized blenders with strong regional distribution networks or technology providers offering precision application solutions. A signal to watch is the increasing adoption rate of customized nutrient management plans by farming cooperatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Custom Blending Capacity | This initiative supports precision agriculture demands from independent growers in Europe. |
| Secure Rock Phosphate Offtake Agreements | Long-term agreements mitigate raw material price volatility for manufacturers like The Mosaic Company. |
| Develop Micronutrient-Fortified SSP | Enhances product value proposition for specific soil deficiencies in regions like Sub-Saharan Africa. |
| Invest in Digital Agronomy Integration | Aligns SSP products with precision farming technologies adopted by commercial farms in North America. |
| Optimize Logistics for Bulk Transport | Reduces transportation costs, improving market access for farming cooperatives in remote Indian regions. |
Research Approach
Bottom-up cereal crop application modeling reconciled against top-down SSP production tracking forms the analytical core. This approach integrates primary interviews with fertilizer plant managers, agricultural cooperative leaders, and agronomists, validated against extensive secondary research. Secondary sources include FAOSTAT, national agricultural ministry reports, and company annual filings. This triangulation ensures robust data integrity and market sizing accuracy.
Historical trendline analysis informs the projection of future SSP market dynamics across the analysis window. The market is segmented by product type, application, end-use industry, packaging type, and regional regulatory environment. Compound Annual Growth Rates were derived from econometric modeling and expert consensus. Key forecast inputs include global crop acreage forecasts and national fertilizer subsidy policies.
The model assumes a particular technology adoption path for precision agriculture; alternative pathways for nutrient delivery systems would alter the outlook. Forecasts reflect assumptions regarding raw material price stability and regulatory evolution. A model refresh is warranted upon material change in global agricultural trade policies or major raw material supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Italy Water Soluble Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Vietnam Fertilizers Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Boron Fertilizers Market