
 United States Controlled Release Fertilizer Market | 2026-2036
United States Controlled Release Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Controlled Release Fertilizer Market Analytics
Modular nutrient bundling is realigning how agricultural retailers configure seasonal programs for row-crop operators. Nutrien Ltd. leverages its integrated retail network to control distribution depth across the Midwest. ICL Group Ltd. differentiates through polymer-coating technology leadership in specialty horticulture. ScottsMiracle-Gro anchors consumer-facing turf and garden channels with branded slow-release portfolios.
Controlled release fertilizers incorporate barrier coatings—urea-formaldehyde, sulfur, or polymer resin—that meter nitrogen availability over weeks to months, reducing leaching and volatilization losses in field applications. Polymer-coated variants command premium positioning due to superior release predictability in variable soil moisture, while sulfur-coated grades occupy cost-sensitive bulk agricultural segments. Agricultural Crops remains the dominant application category, though Greenhouse operations represent the fastest-growing demand pool as controlled-environment agriculture expands. Farmers constitute the largest end-user group, but Agricultural Retailers increasingly intermediate purchasing through precision agriculture service bundles.
The EPA enforces Clean Water Act provisions that constrain nutrient runoff from fertilizer application, pushing manufacturers toward enhanced-efficiency formulations that meet voluntary NRCS standards. State regulators in Florida and California impose additional water-quality mandates that favor slow-release and polymer-coated products in sensitive watersheds. Stakeholders must monitor evolving state-level 4R implementation timelines and carbon accounting methodologies that could revalue nitrogen-use efficiency in agricultural supply chains.
Market Dynamics
Polymer-coating technology maturation is compressing release-rate variability, forcing sulfur-coated urea producers to defend position through cost engineering while specialty formulators capture margin in precision agriculture bundles.
Growth Catalysts
- 4R Nutrient Stewardship mandates:State-level implementation in Florida and Iowa requires nitrogen-use efficiency plans that favor slow-release formulations in designated watersheds.
- Controlled-environment agriculture expansion:Greenhouse operators in California's Salinas Valley are converting substrate systems to polymer-coated blends for labor reduction and crop uniformity.
- Polymer resin supply localization:Domestic coating material production in Texas and Louisiana is shortening lead times for Midwest blenders serving corn-soy rotations.
Market Restraints
- Natural gas price volatility:Urea synthesis feedstock costs swing fertilizer base pricing, squeezing margin on value-added coating upgrades.
- Coating technology IP concentration:Polymer formulation patents cluster with three multinational licensors, limiting domestic manufacturer differentiation.
- Release rate soil-temperature sensitivity:Sulfur-coated products exhibit unpredictable nitrogen availability in cool spring conditions across northern Corn Belt states.
Strategic Opportunities
- Carbon accounting integration:USDA conservation programs are piloting nitrogen-use efficiency metrics that could revalue controlled-release adoption in carbon credit markets.
- Drone-enabled variable-rate application:Aerial platform compatibility is opening precision placement services for specialty crop growers in Washington's apple districts.
- Water-quality trading programs:Nutrient credit exchanges in Chesapeake Bay watersheds create direct economic incentives for runoff-reducing formulations.
Industry Challenges
- Polymer chemist talent scarcity:Coating R&D functions compete with petroleum and materials sectors for formulation specialists in Gulf Coast chemical corridors.
- Release certification timeline compression:EPA accelerated review schedules for enhanced-efficiency claims strain analytical validation capacity at third-party laboratories.
- Legacy blender equipment retrofit costs:Bulk handling systems designed for conventional urea require capital modification to prevent polymer coating damage during pneumatic transfer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Controlled Release Fertilizer Market |
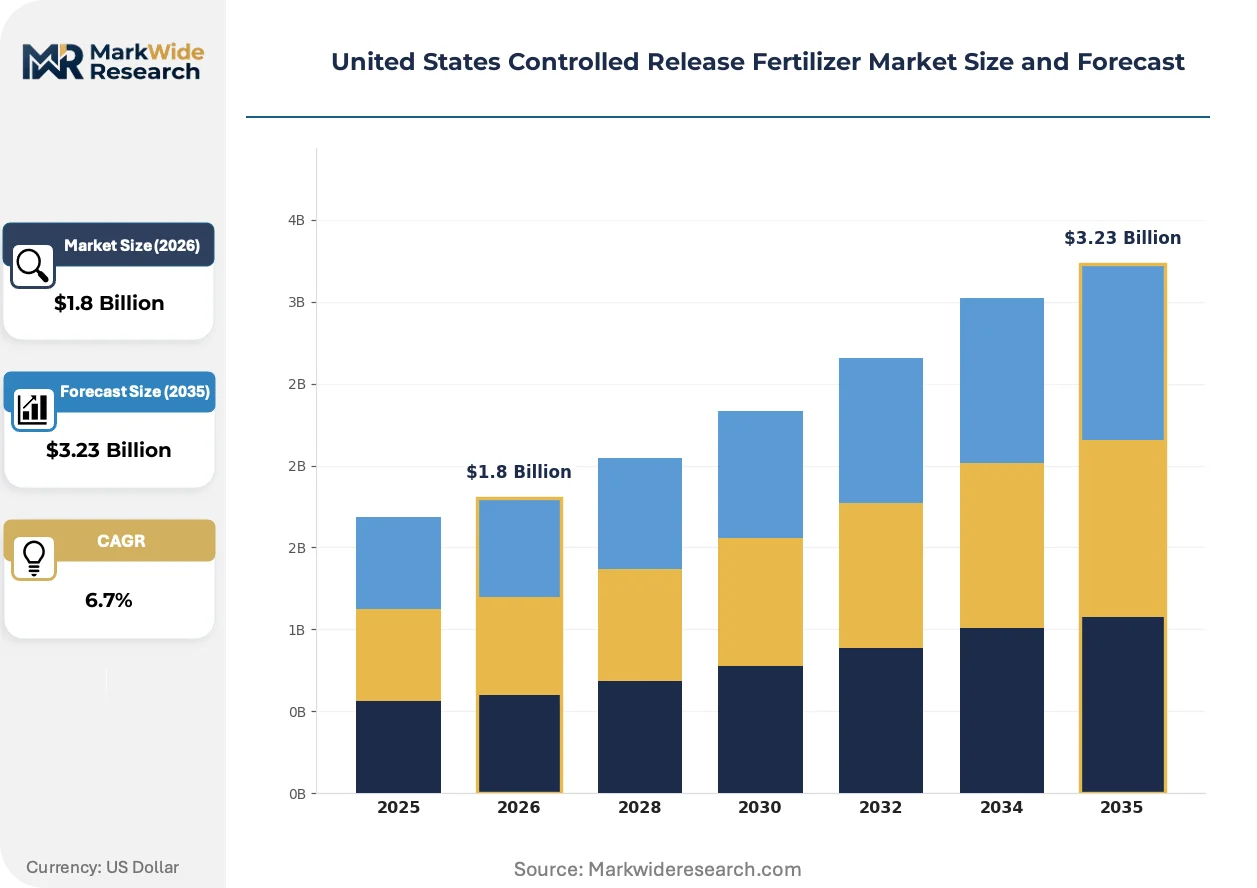
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
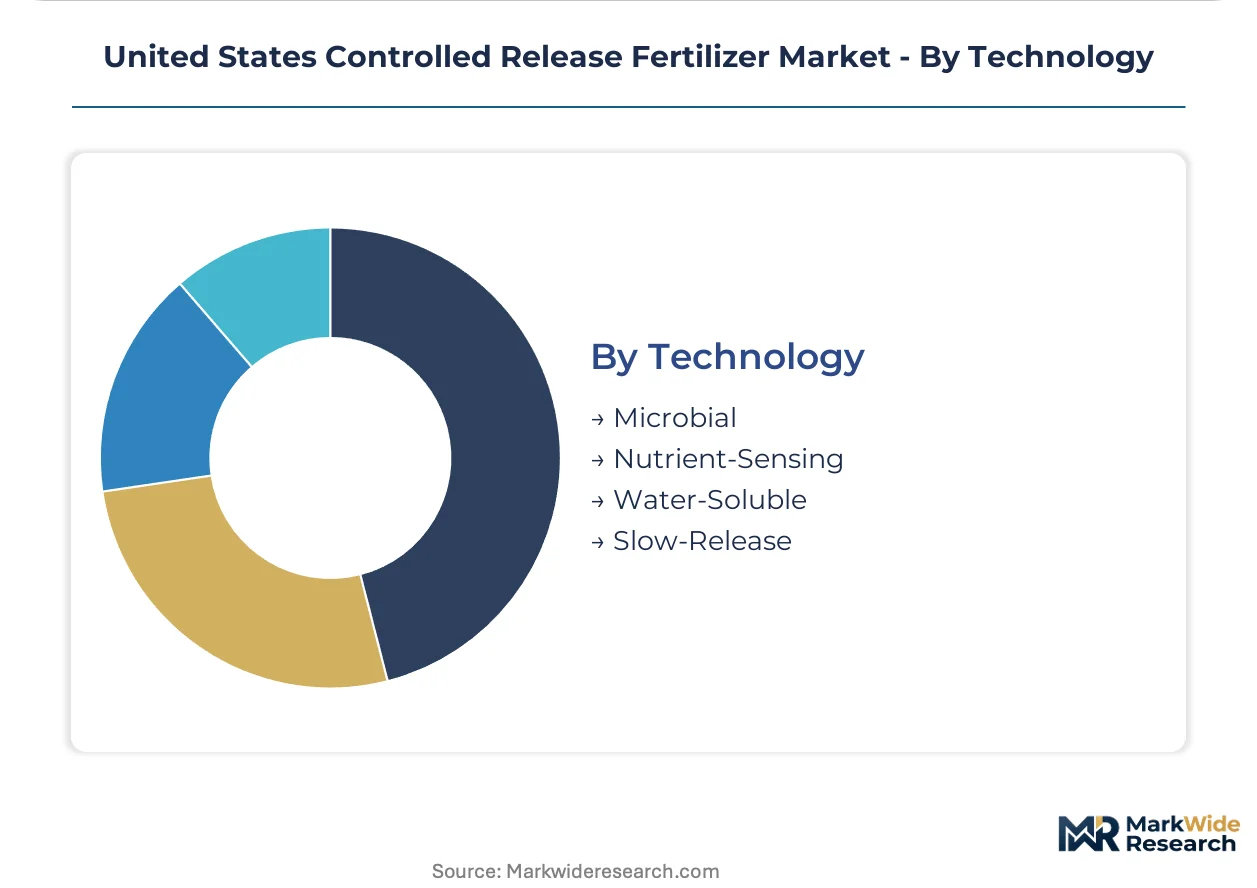
| Segmentation | Product Type: Urea-Coated, Sulfur-Coated, Polymer-Coated, Resin-Coated Application: Agricultural Crops, Horticulture, Turf, Greenhouse End User: Farmers, Nurseries, Landscape Professionals, Agricultural Retailers Technology: Microbial, Nutrient-Sensing, Water-Soluble, Slow-Release |
| Companies Covered | Nutrien Ltd., ICL Group Ltd., The Mosaic Company, Koch Fertilizer LLC, Florikan ESA LLC, Pursell Agri-Tech LLC, ScottsMiracle-Gro, Lebanon Seaboard Corp., Kugler Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Controlled Release Fertilizer Market Evolving Landscape
Release mechanism engineering is converging with digital agriculture infrastructure, creating demand for fertilizers that communicate with soil sensor networks and automated irrigation systems.
Responsive polymer coating chemistry is modularizing product architecture for specialty crop programs. These formulations adjust nitrogen solubility to real-time moisture and temperature conditions detected by field sensor arrays. Strawberry and tomato greenhouse operators in Florida are piloting subscription-based nutrient programs built around this adaptability. The technology is modularizing how retailers bundle agronomic services with physical inputs, compressing traditional product-margin structures into integrated per-acre service fees.
EPA Clean Water Act enforcement is tightening discharge permits for agricultural runoff into impaired waterways. The agency's 2023 nutrient management guidance elevates enhanced-efficiency fertilizers to preferred practice status in watershed implementation plans. Corn Belt states with Mississippi River basin drainage are responding by incorporating slow-release mandates into cost-share program eligibility criteria for precision equipment subsidies.
Precision agriculture service bundling is restructuring retailer-farmer relationships in row-crop territories. Nutrient management planning, variable-rate prescriptions, and product fulfillment are consolidating under single-provider contracts that displace transactional input purchases. This consolidation is most visible in Illinois and Iowa, where cooperatives and independent retailers compete to anchor acreage through integrated agronomy platforms rather than price-based commodity sales.
United States Controlled Release Fertilizer Market Segmentation
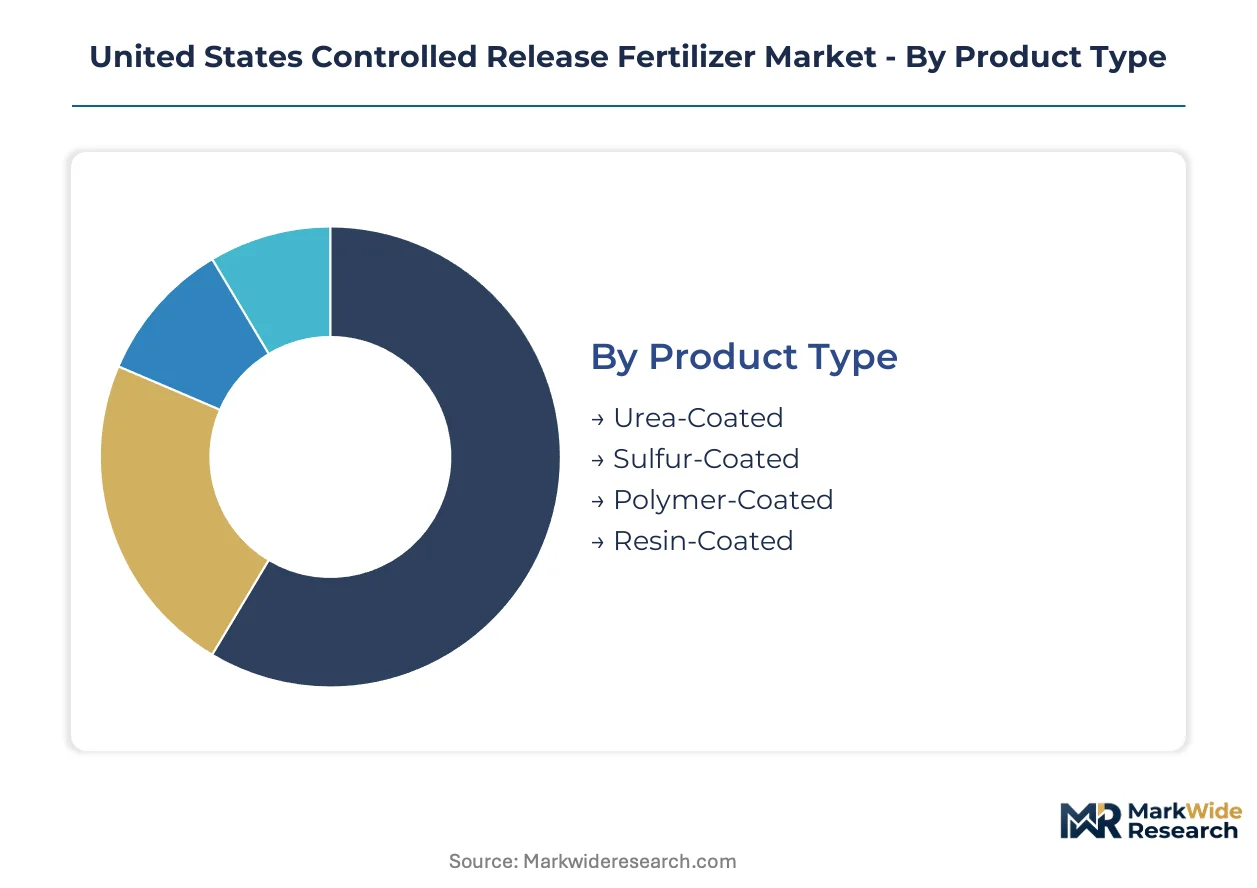
Coating chemistry and release mechanism specifications determine pricing power and distribution channel access across the United States controlled release fertilizer market. Each segment boundary reflects distinct manufacturing asset requirements, agronomic validation protocols, and farmer purchasing behavior patterns.
Product Type:
Supply concentration in polymer resin production along the Gulf Coast creates tiered cost structures that segment manufacturers by coating technology ownership.
- Polymer-Coated:Multi-layer thermoplastic or thermoset polymer barriers deliver highly predictable nitrogen release curves calibrated to soil temperature and moisture. Specialty crop operators in Florida's citrus belt and California's Central Valley pay premiums for this precision, driven by EPA water-quality mandates in impaired watersheds.
- Sulfur-Coated:A sulfur primary layer sealed with wax or polymer secondary coating offers intermediate release control at lower unit cost. Corn Belt states with cost-share program eligibility criteria favor this grade for bulk row-crop applications where absolute release precision carries less economic weight.
- Urea-Coated:Urea-formaldehyde condensation products provide extended nitrogen availability through microbial decomposition pathways.
- Resin-Coated:Specialized alkyd or polyurethane resin formulations target greenhouse substrate systems requiring acid-resistant barriers.
Today's leader: Polymer-Coated. Tomorrow's challenger: Sulfur-Coated.
Application:
End-use margins separate dramatically between bulk commodity agriculture and controlled-environment operations with labor cost sensitivity.
- Agricultural Crops:Field corn, soybean, and wheat systems consume the largest volume tonnage, with nutrient management planning services bundling slow-release formulations into precision agriculture subscriptions. Iowa and Illinois retailers anchor acreage through these integrated per-acre service fees rather than transactional input sales.
- Greenhouse:Soilless substrate cultivation in California's Salinas Valley and Florida's tomato districts demands exact nutrient timing for crop uniformity. Labor reduction through automated fertigation compatibility drives conversion from conventional soluble fertilizers to polymer-coated blends.
- Horticulture:Container nursery stock and perennial production utilize coated products for reduced application frequency.
- Turf:Golf course superintendents and municipal grounds managers specify sulfur-coated urea for seasonal greening programs.
Greenhouse operations are expanding most quickly. Agricultural Crops retains volume dominance.
End User:
Procurement authority migration from individual farmers to intermediary agronomy platforms restructures segment access requirements.
- Agricultural Retailers:Cooperatives and independent dealers in the Corn Belt now intermediate the majority of controlled-release purchases through precision agriculture service bundles. These entities demand manufacturer technical support for variable-rate prescription compatibility and soil sensor network integration.
- Farmers:Direct procurement persists among large-scale operators with in-house agronomy staff, particularly in Minnesota and Nebraska where farm consolidation has created professionalized nutrient management capabilities.
- Nurseries:Container production specialists in Oregon and Pennsylvania specify coated products for seasonal crop cycles.
- Landscape Professionals:Commercial turf maintenance contractors source sulfur-coated formulations through wholesale distribution.
Current procurement authority: Agricultural Retailers. Emerging direct channel: Farmers with captive agronomy.
Technology:
Release mechanism intellectual property concentration with multinational licensors constrains domestic manufacturer differentiation strategies.
- Slow-Release:Conventional diffusion-controlled coatings dominate installed manufacturing capacity and generate predictable cash flows. EPA enhanced-efficiency fertilizer designation in watershed implementation plans sustains demand visibility for this established category.
- Nutrient-Sensing:Responsive polymer chemistry adjusts nitrogen solubility to real-time soil moisture and temperature conditions detected by field sensor arrays. Strawberry and tomato greenhouse operators in Florida pilot subscription-based nutrient programs built around this adaptability.
- Microbial:Bio-stimulant integration with coated fertilizers targets soil health metrics in USDA conservation program pilots.
- Water-Soluble:Rapid dissolution formulations serve specialty irrigation systems requiring immediate nutrient availability.
Established base: Slow-Release. Steepest expansion trajectory: Nutrient-Sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controlled release fertilizer manufacturing scaled in the United States through Gulf Coast petrochemical corridors where polymer resin feedstock concentrated during the post-war chemical expansion. The industry now distributes through regional blending networks anchored to Midwest agricultural demand centers and coastal specialty crop zones.
California
Specialty vegetable growers in the Salinas Valley and Central Valley citrus operators drive polymer-coated formulation demand under EPA regional water-quality mandates for impaired watersheds. The state's Central Valley Regional Water Quality Control Board enforces nitrogen management plans that favor slow-release products in discharge-sensitive zones. Greenhouse substrate operations in Ventura County are converting to resin-coated blends for automated fertigation compatibility.
Florida
Citrus belt growers and tomato greenhouse operators in the Immokalee region specify sulfur-coated and polymer-coated grades to comply with state-level 4R Nutrient Stewardship implementation. The Florida Department of Environmental Protection administers basin management action plans that designate enhanced-efficiency fertilizers as preferred practice in springs protection zones. Polymer-coated product penetration runs deepest in the southern peninsula where water-table proximity elevates leaching risk.
Iowa
Corn-soy rotations across the Des Moines Lobe and Iowan Erosion Surface consume bulk sulfur-coated urea volumes through cooperative retail networks bundling precision agriculture services. The Iowa Department of Agriculture and Land Stewardship ties cost-share program eligibility for nitrogen management equipment to documented use of enhanced-efficiency formulations. Agricultural retailers in the Cedar Rapids-Waterloo corridor anchor acreage through integrated per-acre service contracts displacing transactional input sales.
Illinois
Central Illinois corn producers and western soybean operators intermediate purchasing through independent dealers and cooperative systems demanding manufacturer technical support for variable-rate prescription compatibility. The Illinois EPA coordinates with USDA NRCS to align state nutrient loss reduction strategy targets with slow-release product cost-share incentives. Precision agriculture subscription bundles in the Champaign-Urbana research corridor are compressing traditional product margins into service fees.
Texas
Gulf Coast polymer resin production in the Houston Ship Channel and Beaumont-Port Arthur complex supplies coating materials to Midwest blenders with shortened lead times. The Texas Commission on Environmental Quality regulates petrochemical emissions from coating material synthesis while the state's agricultural extension service promotes nitrogen-use efficiency demonstrations in the High Plains cotton belt. Domestic resin localization is reducing import dependency for sulfur-coated and polymer-coated formulation manufacturers.
United States Controlled Release Fertilizer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology ownership and agronomic service integration depth. The vendor base concentrates around integrated fertilizer majors with captive retail networks, specialty coating technology licensors, and regional blending specialists serving discrete watersheds. Three archetypes dominate: Gulf Coast resin-integrated manufacturers, precision agriculture platform operators, and horticultural-focused coating specialists. Competitive moves center on backward integration into polymer feedstock and forward integration into retailer agronomy service bundles.
Within the integrated-major tier, Nutrien Ltd. and The Mosaic Company occupy positions defined by distribution network depth across Midwest row-crop territories. Among coating technology specialists, ICL Group Ltd. and ScottsMiracle-Gro exemplify divergent end-market anchoring—ICL toward specialty horticulture polymer formulations, ScottsMiracle-Gro toward consumer-facing turf and garden channels. Regional blending specialists including Pursell Agri-Tech LLC and Florikan ESA LLC represent the watershed-responsive tier, situating manufacturing and technical service capacity adjacent to Florida water-quality mandate zones. Koch Fertilizer LLC anchors the scale-driven commodity segment with sulfur-coated volume production serving bulk agricultural applications.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| ICL Group Ltd. |
| The Mosaic Company |
| Koch Fertilizer LLC |
| Florikan ESA LLC |
| Pursell Agri-Tech LLC |
| ScottsMiracle-Gro |
| Lebanon Seaboard Corp. |
| Kugler Company |
| Others |
Value Network & Pricing Analysis
Agricultural retailers in Iowa and Illinois now intermediate the majority of controlled-release fertilizer purchases through precision agriculture service bundles, compressing traditional product margins into integrated per-acre fees and shifting pricing power toward volume-anchored distributors.
Pricing Analysis
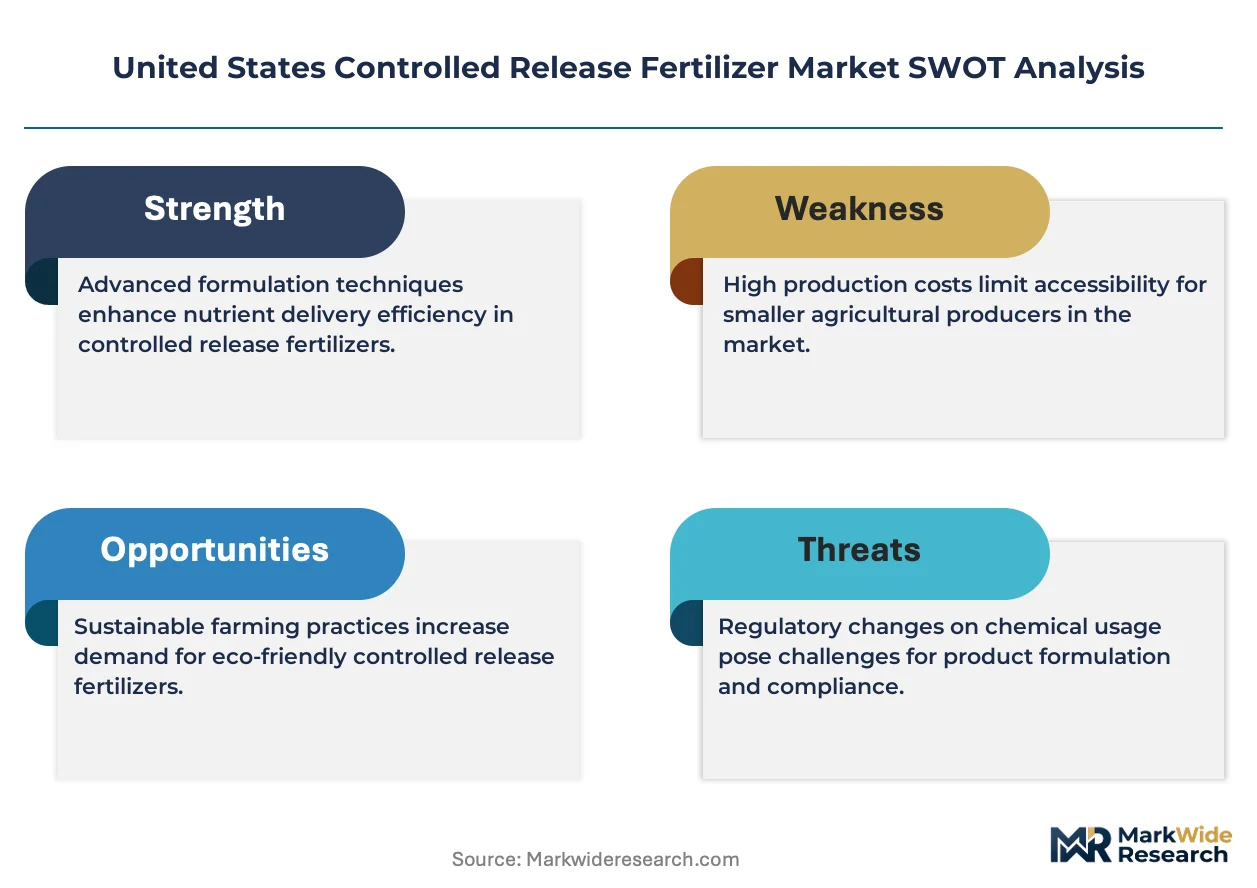
Three-tier pricing structure across premium polymer-coated, standard sulfur-coated, and economy uncoated urea levels dominates the market. Price differentiation separates specialty crop operators in California and Florida from bulk row-crop buyers in the Corn Belt, with certification under EPA enhanced-efficiency standards commanding additional premiums. Pricing pressure stems from natural gas feedstock volatility squeezing margins on value-added coating upgrades. Bulk agricultural buyers exhibit highest price sensitivity, while greenhouse operators in controlled-environment agriculture accept premium positioning for labor reduction benefits.
Supply Chain Analysis
Polymer resin supply rests on Gulf Coast petrochemical production in Texas and Louisiana, with sulfur coating materials drawing from domestic petroleum refining byproduct streams. Raw material dependencies center on natural gas for urea synthesis, thermoplastic polymers for precision coatings, and sulfur for intermediate-grade formulations. Single-source vulnerability concentrates in polymer formulation patents held by multinational licensors, constraining domestic manufacturer differentiation. Distribution runs through regional blending networks anchored to Midwest agricultural demand centers and coastal specialty crop zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States controlled release fertilizer market functions as a regulatory compounder, with EPA Clean Water Act enforcement and state-level 4R Nutrient Stewardship mandates creating structural demand for enhanced-efficiency formulations in impaired watersheds.
For Market Incumbents: Acquire polymer resin production assets or captive coating technology licenses to defend against sulfur-coated urea producers engineering cost advantages. Backward integration into Gulf Coast petrochemical corridors secures feedstock access against natural gas price volatility. Capacity expansion in Iowa and Illinois strengthens retailer service bundle anchoring against cooperative competitors. For New Entrants and Emerging Players: The price-point gap between premium polymer-coated formulations and economy sulfur-coated grades creates white-space opportunity for mid-tier responsive polymer chemistry. Nutrient-sensing technology adoption in Florida strawberry and tomato greenhouses represents the most penetrable application segment. Go-to-market through subscription-based per-acre service contracts bypasses established retail channel control. For Investors and Strategic Acquirers: Integrated fertilizer majors with captive retail networks are the most active acquirers in this space, seeking coating technology specialists to deepen agronomic service integration. Long-term viability hinges on carbon accounting methodology adoption revaluing nitrogen-use efficiency in agricultural supply chains. Watch USDA conservation program pilot expansions as the inflection signal for controlled-release adoption in carbon credit markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Gulf Coast petrochemical corridor access shortens lead times for Midwest blenders serving corn-soy rotations. |
| Precision Agriculture Service Bundling | Iowa and Illinois retailers anchor acreage through integrated per-acre contracts displacing transactional input sales. |
| Responsive Polymer Chemistry Development | Florida greenhouse operators pilot subscription programs adjusting nitrogen solubility to real-time sensor data. |
| Carbon Accounting Certification Investment | USDA conservation program pilots could revalue nitrogen-use efficiency in emerging agricultural carbon markets. |
| Regional Blending Capacity Expansion | Texas and Louisiana resin localization reduces import dependency for coating material supply security. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fertilizer manufacturing executives, agricultural retail cooperative managers, EPA regional enforcement officers, and precision agriculture platform engineers with secondary validation. Trade data from the Fertilizer Institute, USDA NRCS program documentation, EPA Clean Water Act discharge permit filings, and state agriculture department cost-share program records anchored volume estimates. Bottom-up coating technology adoption curves and top-down watershed implementation plan targets were triangulated for segment sizing.
Historical reference periods spanning pre- and post-4R Nutrient Stewardship mandate implementation anchored the forecast window across the projection horizon. Segmentation modeling incorporated coating chemistry tier, application intensity by crop system, end-user procurement authority migration, and regional water-quality regulatory cluster. CAGRs were derived from demand elasticity to nitrogen management plan compliance deadlines and precision agriculture equipment subsidy cycles, with polymer resin supply localization and natural gas feedstock volatility as key forecast inputs.
Caveats apply where EPA accelerated review schedules for enhanced-efficiency claims or state-level 4R implementation timeline shifts could materially shift the outlook. Forecasts reflect assumptions around carbon accounting methodology adoption rates and precision agriculture subscription bundle penetration. A small set of triggers—USDA conservation program expansion, polymer chemist talent availability, and water-quality trading program activation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Nano Fertilizer Market
Fertilizers
Africa Specialty Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
China Fertilizers Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market