
 Global Nitrogenous Fertilizer Market | 2026-2036
Global Nitrogenous Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nitrogenous Fertilizer Market Foresight
The EU Green Deal is realigning nitrogen management standards across European agriculture, forcing fertilizer manufacturers to reformulate products for lower emission profiles. Yara International ASA leverages its ammonia technology leadership to develop low-carbon fertilizer lines. CF Industries sustains its position through captive natural gas access and Gulf Coast production scale. EuroChem Group anchors its competitiveness in phosphate-nitrogen integration across Russian and Belgian assets.
Nitrogenous fertilizers are compounds containing nitrogen in forms plants absorb, primarily ammonia, nitrate, or urea derivatives, synthesized through Haber-Bosch ammonia conversion followed by downstream processing into solid or liquid carriers; their primary purpose is correcting soil nitrogen deficits to optimize protein synthesis and vegetative yield in crop systems. Urea dominates volume globally due to its high nitrogen content and cost-efficient transport, though coated and stabilized variants are capturing margin pools as environmental compliance tightens. Ammonium sulfate occupies a specialized position in sulfur-deficient soils and horticulture applications where micronutrient pairing commands price premiums over standard nitrogen grades.
The EPA regulates ammonia emissions and nutrient runoff under the Clean Water Act, while China's MEE enforces dual carbon goals that cap coal-based ammonia capacity and accelerate green hydrogen pilot projects. India's CEA coordinates with state fertilizer departments to manage urea subsidy allocation and natural gas feedstock pricing. Stakeholders must monitor regulatory divergence between emission-trading jurisdictions and subsidy-dependent markets to align capital deployment with shifting cost structures.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing emission allowances for ammonia production, forcing nitrogenous fertilizer manufacturers to reconfigure feedstock sourcing and product formulations toward lower-carbon intensity grades.
Growth Catalysts
- Controlled-release urea technology:Specialty crop growers in Brazil are expanding purchases of polymer-coated variants that reduce nitrogen volatilization losses. This aligns with precision agriculture adoption in Mato Grosso and São Paulo states.
- India's state subsidy programs:The CEA coordinates natural gas feedstock pricing with state fertilizer departments, channeling volume into the rice-wheat belt. This procurement mechanism sustains baseline demand regardless of international price spikes.
- EU nutrient management rules:The Farm to Fork strategy mandates reduced fertilizer application rates per hectare. This regulatory pressure is accelerating demand for stabilized and enhanced-efficiency nitrogen products that maintain yield at lower input volumes.
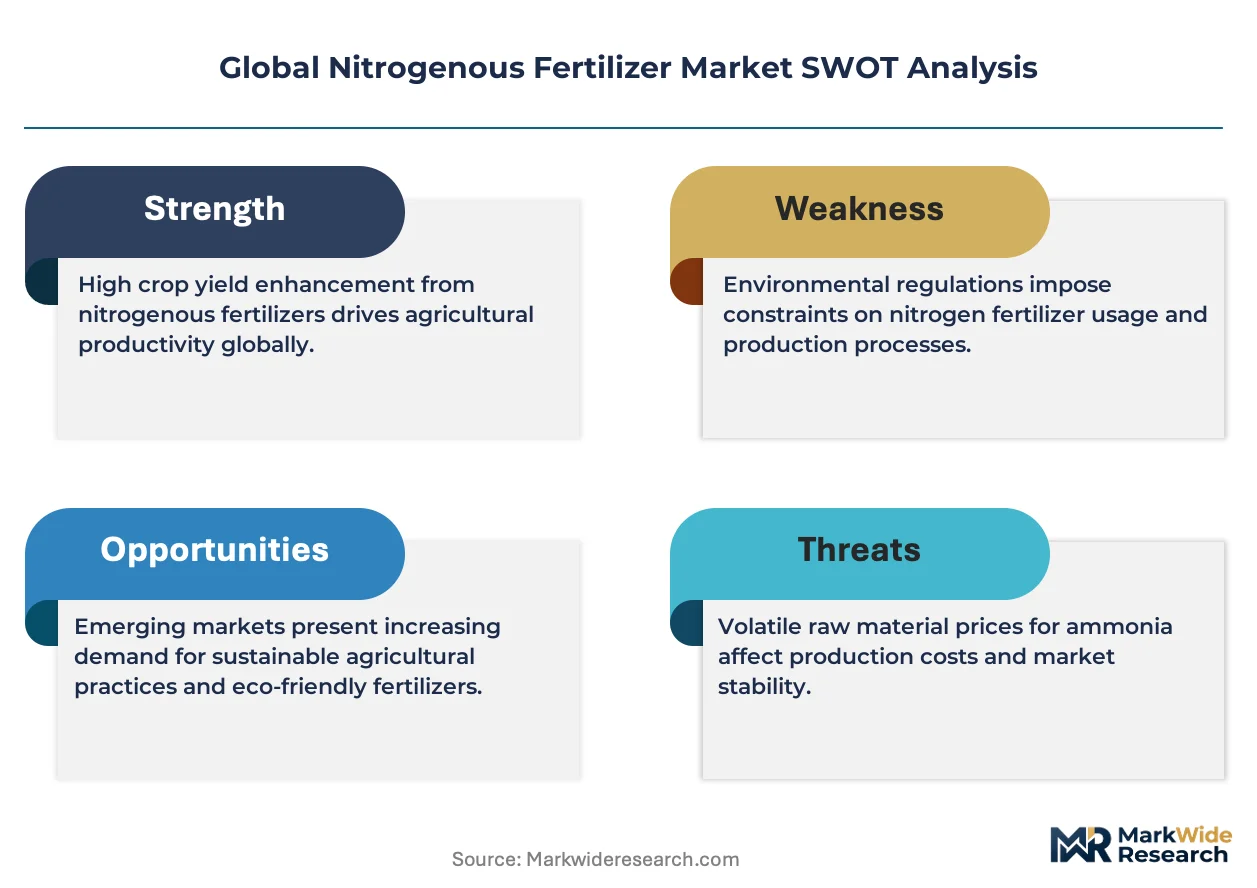
Market Restraints
- Natural gas feedstock volatility:Ammonia synthesis depends on natural gas as primary hydrogen source. Price swings in European and Asian gas markets transmit directly to urea production economics, compressing margins for non-integrated producers.
- Coal-based capacity caps:China's MEE enforces dual carbon goals that limit new coal-to-ammonia installations. This supply-side constraint in the world's largest nitrogen producer tightens global export availability.
- Organic and biological substitutes:Microbial inoculants and green manures are displacing synthetic nitrogen in premium horticulture segments. Dutch and Danish vegetable cooperatives are piloting nitrogen-fixing cover crop systems.
Strategic Opportunities
- Green hydrogen ammonia pilots:Electrolytic hydrogen production powered by renewable electricity offers a pathway to zero-carbon ammonia. Norwegian and Australian projects are scaling demonstration plants toward commercial viability.
- Sulfur-deficient soil expansion:Ammonium sulfate captures margin premiums in Southeast Asian palm oil plantations and Indian tea estates where sulfur depletion accompanies intensive cultivation. These applications command price multiples over standard urea.
- Direct-to-farm digital channels:Agritech platforms in India and Brazil are disintermediating traditional distributor networks. Farmers access customized blends through mobile-enabled cooperative procurement, reducing working capital requirements.
Industry Challenges
- Haber-Bosch process engineering talent:The specialized skill set for ammonia plant operations and catalyst management is aging across European and North American facilities. Knowledge transfer gaps threaten operational continuity at legacy installations.
- Enhanced-efficiency fertilizer certification:EU fertilizer product regulations require multi-year field trials for novel coating technologies. The timeline from formulation to market authorization extends 4-7 years, delaying revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nitrogenous Fertilizer Market |
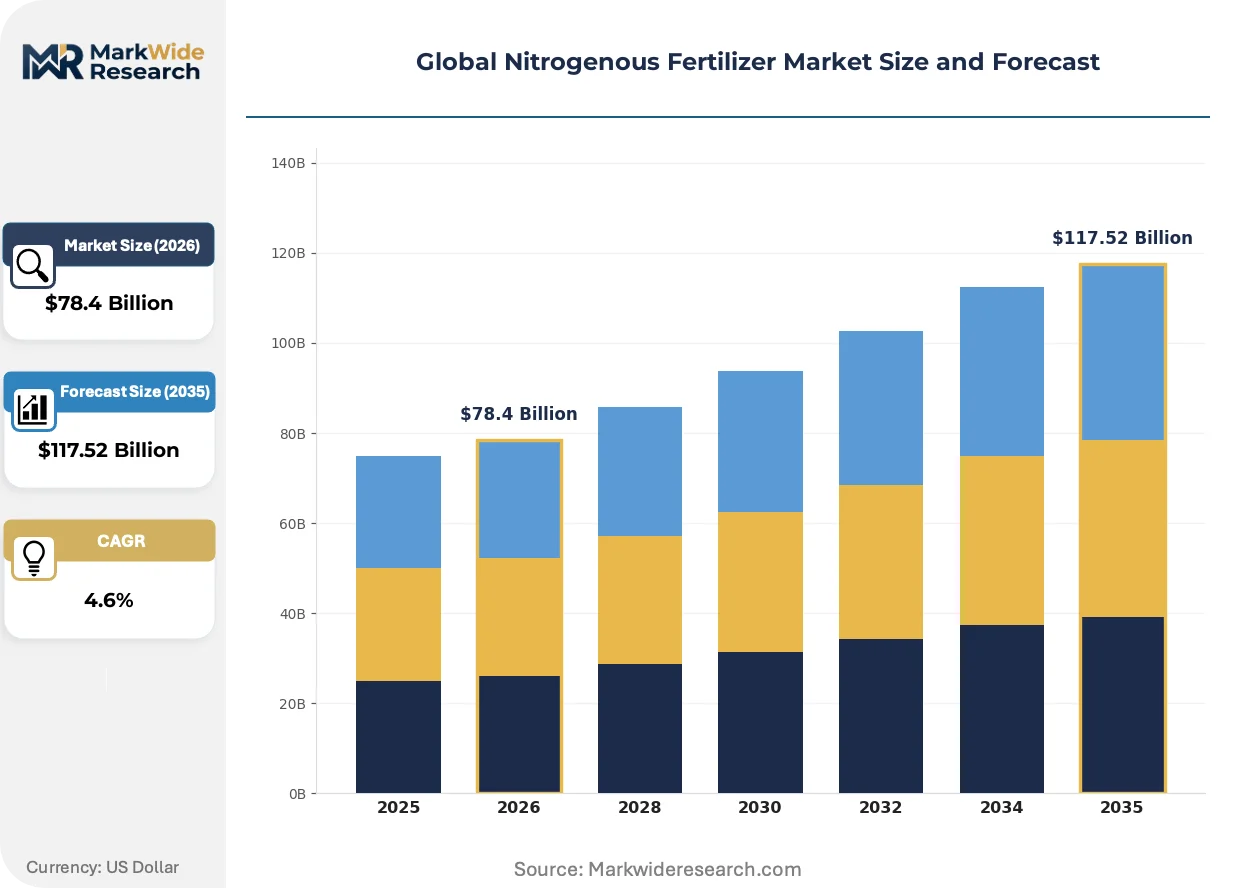
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $117.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Calcium Ammonium Nitrate, Ammonium Sulfate Application: Crops, Horticulture, Turf, Landscaping Form: Granular, Liquid, Powder, Coated Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | Haifa Group, OCI N.V., CF Industries, BASF SE, Acron Group, Nutrien, Indian Farmers Fertiliser Co-operative Limited (IFFCO), EuroChem Group, Yara International ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nitrogenous Fertilizer Market Shifts & Advancements
Digital agronomy platforms are converging with controlled-release chemistry to enable variable-rate nitrogen application. This integration is compressing the traditional one-size-fits-all distribution model.
Polymer-coated urea is integrating nitrification and urease inhibitors into single-granule formulations. Specialty crop operators in California's Central Valley and Florida's citrus belt are adopting these stabilized products at accelerating rates. The technology is integrating precision nutrient timing with automated irrigation systems, reducing labor input per hectare.
REACH authorization requirements for ammonia and nitric acid derivatives are tightening emission disclosure thresholds across European manufacturing. Industrial consequence includes mandatory adoption of catalytic reduction systems and continuous emissions monitoring. Nitrogen fertilizer blenders in Germany and Poland are retrofitting plants to meet the 2026 compliance deadline, passing capital costs through contract renegotiations.
Cooperative procurement collectives are consolidating smallholder demand into volume contracts with price hedging mechanisms. Traditional village-level distributors in India's Punjab and Haryana states are losing share to farmer producer organizations with direct pipeline access. This concentration is most visible in the rice-wheat belt where state subsidy reconciliation favors entities with digital compliance infrastructure.
Global Nitrogenous Fertilizer Market Segmentation
Nitrogenous fertilizer segmentation reveals how product chemistry, application intensity, and supply chain configuration interact to determine margin capture. Manufacturers align R&D investment and regional production footprints against these axes to defend position.
Product Type:
Technology and specification differentiation separate commodity volume from specialty margin pools across nitrogen chemistries.
- Urea:Contains the highest nitrogen concentration among solid fertilizers at 46% N by weight, synthesized via ammonia and carbon dioxide reaction. Demand concentrates in India's rice-wheat belt where CEA-coordinated subsidy programs channel procurement volume regardless of international price spikes.
- Ammonium Nitrate:Delivers rapid nitrogen availability through dual nitrate-ammonium pathways, requiring stabilization for transport safety. Specialty explosives-grade applications in Australian mining and construction command price multiples over agricultural grades due to stringent ANSM authorization requirements.
- Calcium Ammonium Nitrate:Combines nitrogen delivery with calcium supplementation for fruit quality and storage durability. Spanish citrus cooperatives and Italian tomato processors specify this grade for export-oriented production.
- Ammonium Sulfate:Pairs nitrogen with sulfur in 21-0-0-24S formulation, addressing dual nutrient deficiency in Southeast Asian palm oil plantations and Indian tea estates.
Urea leads on scale; ammonium sulfate leads on momentum.
Application:
End-use intensity and crop value per hectare determine formulation sophistication and price realization.
- Crops:Field grain and oilseed production consumes bulk nitrogen volume through broadcast or fertigation application. Brazil's Mato Grosso soybean operators are expanding polymer-coated urea purchases to align with precision agriculture adoption and reduce volatilization losses.
- Horticulture:High-value fruit and vegetable production demands micronutrient-fortified and pH-optimized formulations. Dutch and Danish vegetable cooperatives are piloting nitrogen-fixing cover crop systems that displace synthetic inputs in premium segments.
- Turf:Golf course and sports field maintenance requires slow-release formulations that sustain color without surge growth. Florida's golf course superintendents specify stabilized products integrated with automated irrigation systems.
- Landscaping:Ornamental and municipal green space applications favor visual uniformity and low odor profiles. California's Central Valley landscaping contractors adopt single-granule formulations combining nitrification and urease inhibitors.
Crops dominate volume; horticulture captures the steepest expansion trajectory.
Form:
Physical state determines logistics economics, application equipment compatibility, and nutrient release control.
- Granular:Free-flowing prilled or compacted particles enable mechanical spreading with standard farm equipment. Indian farmer producer organizations in Punjab and Haryana are consolidating procurement through digital cooperative platforms that favor granular standardization.
- Liquid:Urea-ammonium nitrate solutions and anhydrous ammonia enable precision injection and fertigation integration. California's Central Valley specialty crop operators adopt liquid systems for variable-rate nitrogen application synchronized with soil moisture sensors.
- Powder:Fine-ground formulations dissolve rapidly for foliar feeding and hydroponic systems. Japanese greenhouse tomato producers specify powder grades for closed-loop nutrient film technique systems.
- Coated:Polymer or sulfur encapsulation extends nitrogen release over 30-120 days, reducing application frequency. Brazil's São Paulo state citrus growers are expanding purchases of polymer-coated variants that align with precision agriculture adoption.
Granular leads on scale; coated formulations gain share fastest.
Distribution Channel:
Channel structure reflects working capital requirements, technical service intensity, and geographic fragmentation of demand.
- Retail:Village-level dealers and agricultural supply stores serve smallholders with immediate availability and credit terms. Traditional distributors in India's rice-wheat belt are losing share to farmer producer organizations with direct pipeline access and digital compliance infrastructure.
- Wholesale:Volume aggregation through regional distributors serves cooperative procurement and institutional buyers. EuroChem Group anchors competitiveness through phosphate-nitrogen integration across Russian and Belgian assets that feed wholesale channels.
- Direct Sales:Manufacturer-to-farm contracts eliminate margin stacking for large-scale operators. CF Industries sustains position through captive natural gas access and Gulf Coast production scale that enables direct volume contracting.
- Online:Agritech platforms in India and Brazil disintermediate traditional networks through mobile-enabled cooperative procurement. Farmers access customized blends with reduced working capital requirements and price hedging mechanisms.
Wholesale retains volume dominance; online channels show the steepest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized agronomists and ammonia plant engineers concentrate in nitrogen fertilizer corridors across five countries where feedstock access and subsidy infrastructure anchor production economics.
China
Coal-to-ammonia capacity constraints under MEE dual carbon goals are tightening export availability from Shandong and Inner Mongolia production clusters. Provincial environmental regulators are capping emissions-intensive installations while green hydrogen pilot projects advance in Ningxia. The Yangtze River Delta chemical engineering workforce is migrating toward electrolytic ammonia demonstration plants.
India
State-coordinated urea procurement through CEA-managed natural gas pricing sustains volume in the Punjab-Haryana rice-wheat belt regardless of international price volatility. Farmer producer organizations with digital compliance infrastructure are displacing traditional village-level distributors. The Gujarat fertilizer corridor leverages imported LNG feedstock and port proximity to serve western agricultural zones.
Brazil
Mato Grosso soybean operators are expanding polymer-coated urea purchases to align with precision agriculture adoption and reduce nitrogen volatilization losses. São Paulo state citrus growers specify stabilized products integrated with automated irrigation systems. The country's nitrogen import dependency creates working capital pressure during currency depreciation cycles.
United States
Gulf Coast ammonia producers leverage captive natural gas access and pipeline infrastructure to supply Corn Belt corn-soybean rotations. EPA Clean Water Act enforcement on nutrient runoff is tightening application timing restrictions in Chesapeake Bay watershed states. The Illinois-Iowa corridor maintains the densest concentration of anhydrous ammonia storage and application equipment.
Germany
REACH authorization requirements for ammonia derivatives are mandating catalytic reduction retrofits at Ludwigshafen and Brunsbüttel chemical complexes. The EU Green Deal's Farm to Fork strategy is compressing emission allowances for domestic ammonia production. Rhineland-Palatinate fertilizer blenders are reformulating products for lower-carbon intensity grades to maintain access to Dutch and Danish vegetable cooperatives.
Global Nitrogenous Fertilizer Market Competitive Landscape
Capital-heavy ammonia producers compete with asset-light fertilizer blenders and distributors for margin capture across the nitrogen value chain. The market structure concentrates upstream synthesis capacity among integrated energy-chemical conglomerates while fragmenting downstream formulation into regional specialists. Three archetypes dominate: captive feedstock operators with Gulf Coast or North Sea gas access, phosphate-nitrogen integrators leveraging mining-chemical synergies, and cooperative-owned distributors with state subsidy channel control. Competitive moves center on backward integration into green hydrogen pilot projects and forward integration into direct-to-farm digital procurement platforms.
Among European integrated chemical producers, BASF SE and Yara International ASA exemplify divergent strategic positions within the low-carbon transition. BASF SE anchors its competitiveness through Ludwigshafen Verbund site scale and catalyst technology depth. Yara International ASA occupies a position emphasizing ammonia technology leadership and maritime logistics integration. CF Industries represents the captive feedstock archetype through its Gulf Coast production concentration and pipeline infrastructure control.
| Leading Market Players |
|---|
| Haifa Group |
| OCI N.V. |
| CF Industries |
| BASF SE |
| Acron Group |
| Nutrien |
| Indian Farmers Fertiliser Co-operative Limited (IFFCO) |
| EuroChem Group |
| Yara International ASA |
| Others |
Supply & Pricing Matrix
Natural gas feedstock costs transmit directly from ammonia synthesis reactors through to farmgate urea prices, with European and Asian spot gas volatility compressing margins for non-integrated blenders while Gulf Coast producers with captive pipeline access maintain contract pricing discipline. This cost cascade stratifies pricing across premium polymer-coated formulations, standard prilled grades, and economy bulk urea, with buyers in India's rice-wheat belt shielded by CEA-coordinated subsidy mechanisms.
Pricing Analysis
Service bundling splits between basic commodity offtake and agronomic advisory packages, with three-tier pricing structure across premium, standard, and economy levels separating enhanced-efficiency formulations from bulk urea. Price differentiation hinges on nitrogen use efficiency certification and volume scale, with large-scale Mato Grosso soybean operators commanding discounts unavailable to smallholders. Cost compression in standard grades is intensifying because coal-based capacity caps in China tighten export availability. Smallholder cooperatives in Punjab and Haryana exhibit highest price sensitivity, while California specialty crop operators absorb premiums for stabilized products.
Supply Chain Analysis
Single-source vulnerability sits with Chinese coal-to-ammonia clusters in Shandong and Inner Mongolia, where MEE dual carbon goals are capping emissions-intensive installations. Manufacturing concentrates in China, Russia, and India, with feedstock sourcing drawing from domestic coal reserves, North Sea gas fields, and imported LNG respectively. Raw material dependencies include natural gas, metallurgical coal, and phosphate rock for integrated nitrogen-phosphate operations. Tariff exposure runs through European border carbon adjustments on import volumes. Distribution runs through wholesale aggregators serving cooperative procurement collectives, with direct-to-farm digital channels gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nitrogenous fertilizer market functions as a regulatory compounder, with the EU Green Deal's Farm to Fork strategy mandating reduced application rates per hectare and accelerating demand for enhanced-efficiency formulations. This regulatory milestone reconfigures competitive advantage toward low-carbon ammonia technology leadership.
For Market Incumbents: To counter margin compression from natural gas feedstock volatility, backward integration into green hydrogen pilot projects secures zero-carbon ammonia positioning for EU market access, while capacity rationalization at legacy European installations preserves operational continuity amid REACH authorization timelines. Certification investment in polymer-coated urea formulations defends price realization against commodity urea substitution. For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for electrolytic ammonia demonstration plants serving Dutch and Danish vegetable cooperatives with carbon-intensity-compliant supply. Southeast Asian palm oil plantations represent the most penetrable segment for ammonium sulfate specialization, with sulfur-deficient soil expansion commanding price multiples over standard nitrogen grades. A direct-to-farm digital channel go-to-market angle disintermediates traditional distributor networks in Brazil and India. For Investors and Strategic Acquirers: Consolidation pressure builds where farmer producer organizations with digital compliance infrastructure displace traditional village-level distributors in India's rice-wheat belt. Long-term viability favors ammonia technology leaders with maritime logistics integration and captive renewable energy access for electrolytic hydrogen feedstock. Acquisition targets include mid-scale blenders with regional formulation expertise and established state subsidy channel relationships. The signal to watch is green hydrogen project FIDs crossing commercial viability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Ammonia Pilots | Norwegian and Australian demonstration plants advance zero-carbon feedstock positioning for EU compliance. |
| Polymer-Coated Urea Capacity Expansion | Brazil's Mato Grosso and São Paulo states drive precision agriculture-aligned formulation demand. |
| Direct-to-Farm Digital Platform Launch | Mobile-enabled cooperative procurement in India and Brazil reduces working capital requirements for smallholders. |
| Phosphate-Nitrogen Integration | Russian and Belgian asset synergies anchor EuroChem Group competitiveness in wholesale channel control. |
| Catalytic Reduction Retrofit Programs | German and Polish blenders meet REACH 2026 compliance deadlines through plant modernization investments. |
Research Methodology
Coverage spans Asia-Pacific, Europe, North America, and South America, with primary inputs from each region combining interviews with ammonia plant engineers, procurement leads at downstream fertilizer blenders, distribution channel partners, and specialty crop agronomists with secondary validation. Data synthesis draws from customs and trade statistics, national fertilizer department reports, SEC filings of listed producers, and energy regulator disclosures. Bottom-up demand modeling triangulates against top-down capacity and trade flow analysis.
Rate-of-change decomposition separates volume growth from price realization across the analysis window, with segmentation dimensions covering product chemistry tier, application intensity, physical form, and distribution channel structure. CAGRs derive from fitted trend extrapolation moderated by regulatory milestone timing and feedstock cost scenario testing. Industry-specific forecast inputs include natural gas price band assumptions and subsidy program continuity parameters for India and Brazil.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained European gas price spikes or accelerated coal-to-ammonia capacity retirements in China. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Nano Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Fertilizer Additives Market
Fertilizers
India Organic Fertilizer Market
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market