
 Nitrogen Fertilizer Additives Market | 2026-2036
Nitrogen Fertilizer Additives Market Size, Share, and Industry Trends Forecast 2026-2036
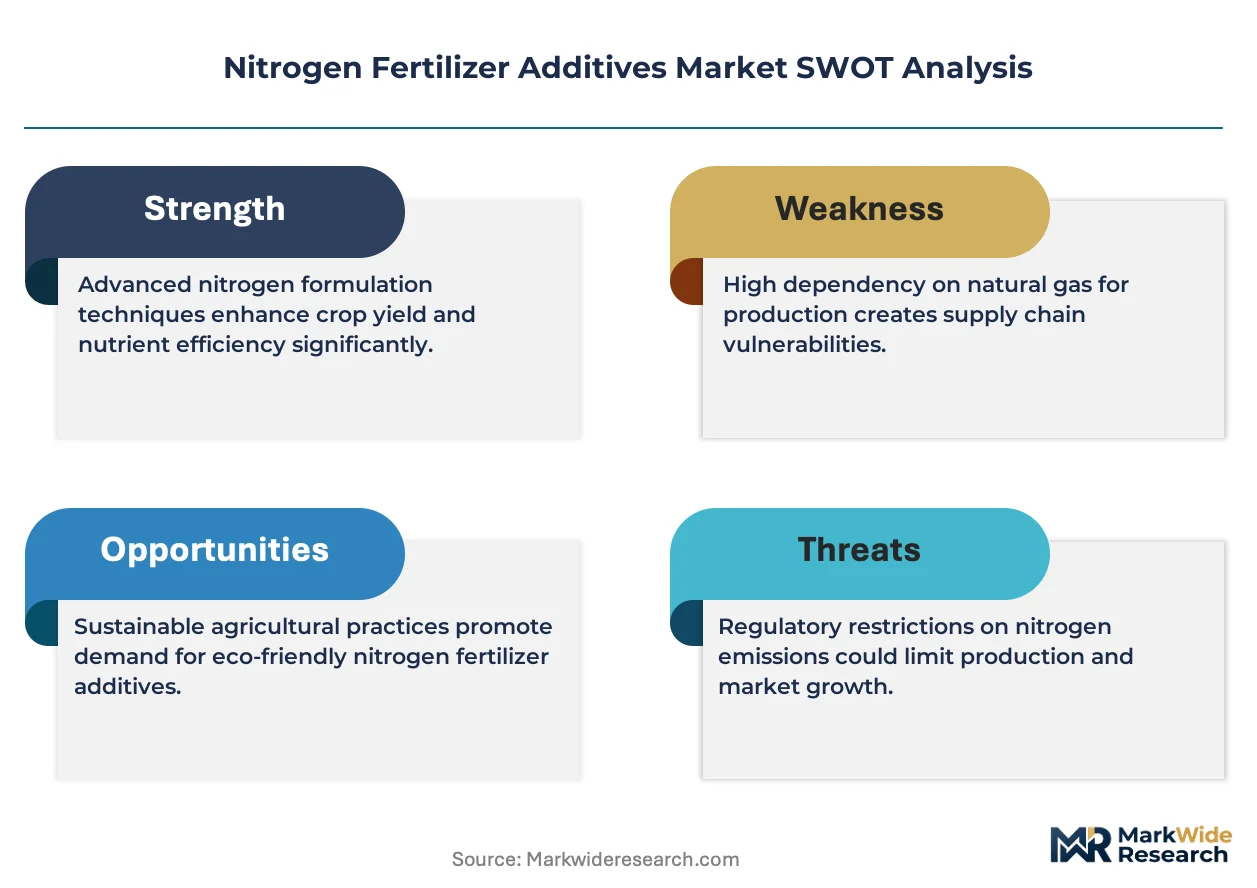
Nitrogen Fertilizer Additives Market Outlook
Commodity grain operators is collapsing as the dominant buyer archetype while specialty crop and precision agriculture adopters gain share. Koch Agronomic Services leverages its controlled-release technology portfolio to anchor demand among high-value fruit and vegetable growers. BASF SE competes through nitrification inhibitor formulations that extend nitrogen availability in intensive horticulture systems. Yara dominates bulk urea additive supply to Brazilian soybean operations while building digital nutrient management platforms.
Nitrogen fertilizer additives comprise chemical formulations—urease inhibitors, nitrification inhibitors, and urea coatings—designed to slow nitrogen conversion and reduce gaseous or dissolved losses from applied fertilizers. These additives typically incorporate active compounds such as NBPT or DCD at concentrations between 0.1% and 1.0% by weight, functioning to improve nitrogen use efficiency and cut environmental emissions across agricultural systems. Urea-based additives lead volume given urea's global dominance as a nitrogen source, though ammonium nitrate formulations command premium positioning in controlled-environment horticulture where precision matters. Premium Grade products capture concentrated margin pools among export-oriented specialty crop producers, while Commercial Grade segments sustain volume through broadacre commodity applications.
The EPA regulates ammonia emissions under the Clean Air Act while the EU Green Deal and F-Gas Regulation tighten nitrogen loss thresholds across member states, forcing reformulation toward lower-volatility chemistries. BIS standards in India and China's MEE directives on agricultural non-point source pollution are converging on additive performance certification requirements that shape market access. Stakeholders must monitor regulatory divergence between emission-limiting jurisdictions and productivity-focused emerging markets to align R&D pipelines and regional registration strategies.
Market Dynamics
Environmental compliance mandates are compressing formulation timelines as regulators tighten ammonia and nitrous oxide thresholds, forcing additive suppliers to accelerate low-volatility chemistry development cycles.
Growth Catalysts
- EPA Clean Air Act enforcement:Ammonia emission limits in the US Corn Belt are accelerating urease inhibitor deployment on corn and wheat operations.
- Specialty crop expansion:High-value fruit and vegetable growers are adopting controlled-release nitrogen to protect input investments against volatilization losses.
- Digital nutrient platforms:Precision agriculture systems are integrating additive recommendations with variable-rate application equipment.
Market Restraints
- Active ingredient concentration limits:NBPT and DCD formulation ceilings restrict efficacy differentiation between product tiers.
- Petrochemical feedstock volatility:Urea coating polymer costs fluctuate with crude oil derivatives, compressing margin predictability.
- Application equipment compatibility:Legacy sprayer systems lack calibration precision for micro-dose additive delivery.
Strategic Opportunities
- Brazilian soybean belt:Bulk urea additive penetration remains below North American levels despite comparable acreage scale.
- Controlled-environment horticulture:Ammonium nitrate additive demand commands premium positioning in greenhouse vegetable production.
- EU Green Deal nitrogen loss targets:Member state incentive programs are subsidizing nitrification inhibitor adoption in intensive dairy regions.
Industry Challenges
- Formulation chemist scarcity:Expertise in slow-release polymer synthesis concentrates among a narrow talent pool.
- Multi-jurisdiction registration timelines:Divergent performance certification requirements between EPA, ECHA, and BIS delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Fertilizer Additives Market |
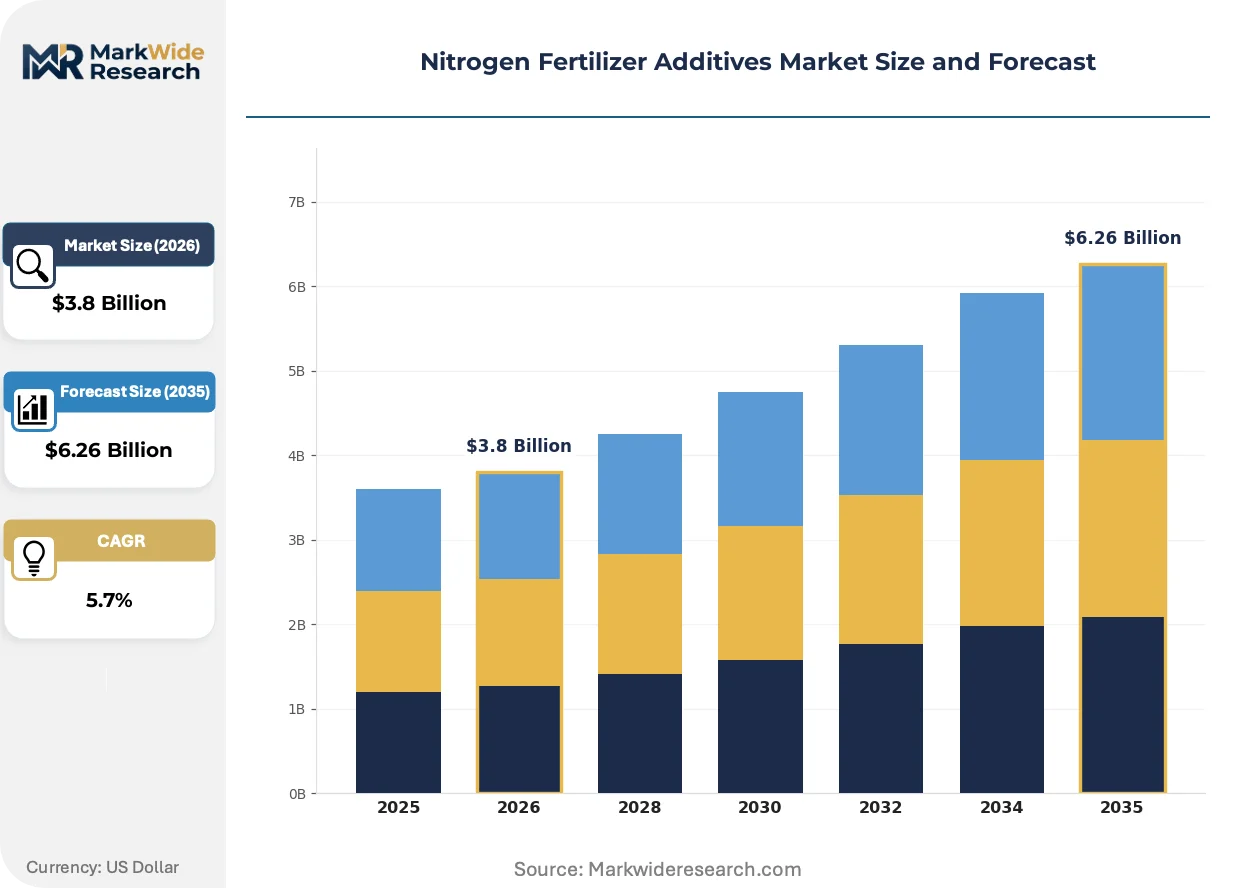
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Calcium Nitrate, Ammonium Sulfate Application: Agricultural Crops, Turf, Landscape, Horticulture Grade: Technical Grade, Commercial Grade, Premium Grade, Low Biuret Grade Distribution Channel: Direct Sales, E-commerce, Retail Stores, Wholesale |
| Companies Covered | Solvay, BASF SE, Yara, Koch Agronomic Services, Clariant, Corteva Agriscience, KAO Corporation, Helena Agri-Enterprises, Innvictis Crop Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Fertilizer Additives Market Strategic Shifts
Active compound delivery systems are undergoing fundamental redesign as manufacturers seek to extend nitrogen availability windows while reducing application complexity.
Encapsulated urea coating technology is miniaturizing particle size distribution to sub-millimeter ranges, enabling uniform distribution through precision planting equipment. Specialty crop producers in California's Central Valley are piloting these formulations at scale. The technology is miniaturizing equipment requirements and opening acreage previously excluded from additive treatment due to application constraints.
The EU F-Gas Regulation is tightening nitrous oxide emission thresholds for agricultural inputs, forcing reformulation toward lower-volatility chemistries. Manufacturers are accelerating DCD-based nitrification inhibitor development to meet 2030 reduction targets. Intensive horticulture operations in the Netherlands and Spain are absorbing compliance costs fastest due to proximity to regulatory enforcement.
Input purchasing is consolidating through cooperative buying groups that negotiate additive-inclusive fertilizer bundles directly with manufacturers. Independent agronomic retailers are losing share to vertically integrated grain handlers in the US Midwest. This consolidation is most pronounced in Iowa and Illinois, where three cooperatives now control majority additive procurement volume.
Nitrogen Fertilizer Additives Market Segmentation
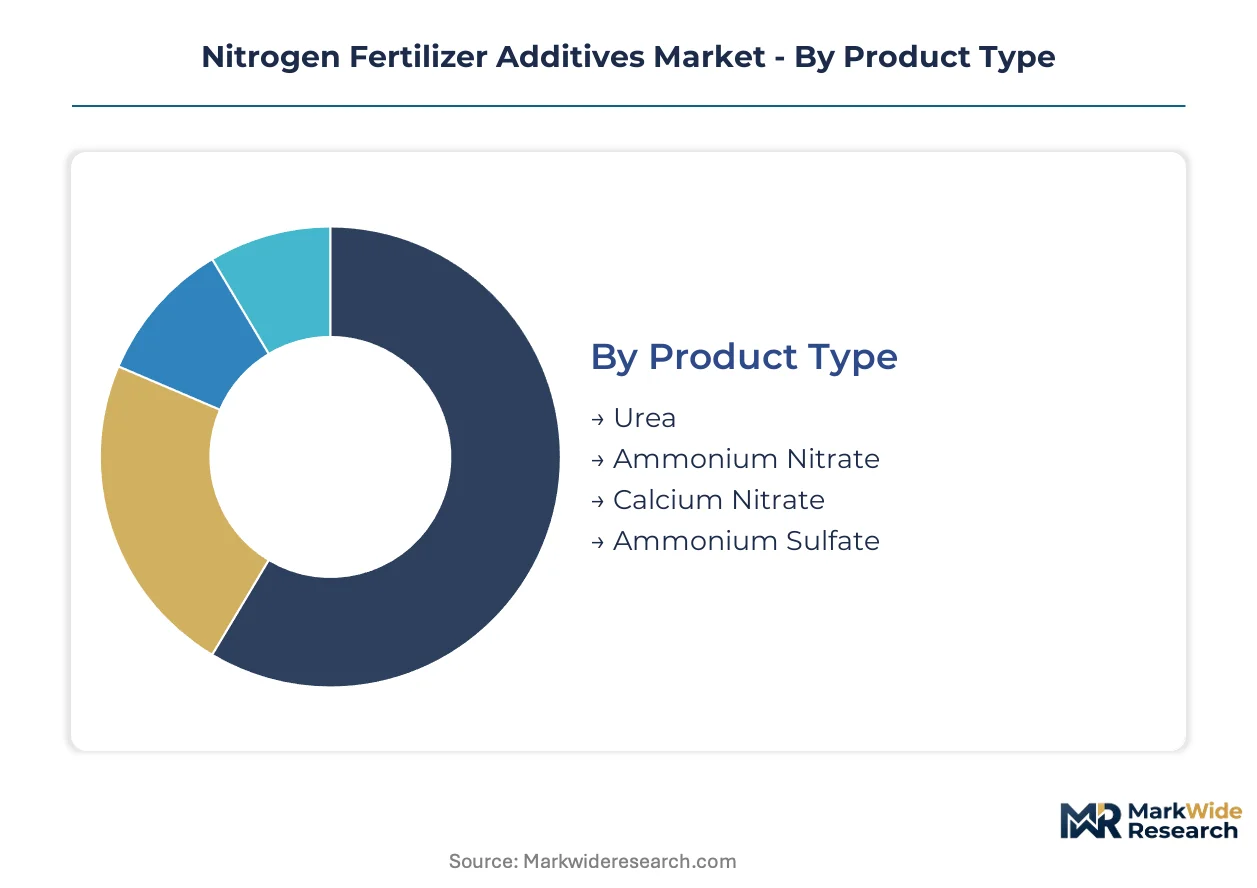
Nitrogen fertilizer additives flow through distinct commercial pathways shaped by crop value, application precision, and procurement scale. Segment boundaries determine margin capture, with premium grades commanding formulation premiums while bulk channels drive volume throughput.
Product Type:
Urea-based formulations dominate wholesale channel throughput, while ammonium nitrate additives concentrate in direct sales to controlled-environment operators.
- Urea:Coatings incorporate NBPT or polymer barriers at 0.1-1.0% active concentration to suppress volatilization. Demand concentrates in the US Corn Belt, where corn and wheat operations deploy urease inhibitors to meet EPA Clean Air Act ammonia thresholds.
- Ammonium Nitrate:Nitrification inhibitor formulations extend nitrogen availability in intensive systems. Greenhouse vegetable producers in the Netherlands and Spain absorb premium pricing to comply with EU F-Gas Regulation nitrous oxide limits.
- Calcium Nitrate:Specialty fruit growers in California's Central Valley source through direct sales channels for drip irrigation compatibility.
- Ammonium Sulfate:Sulfur-deficient soils in Brazil's Mato Grosso drive wholesale procurement through cooperative buying groups.
By volume, Urea leads. By growth pace, Ammonium Nitrate is expanding most quickly.
Application:
Cost tier stratification separates commodity broadacre from precision horticulture, with turf and landscape occupying mid-tier positioning.
- Agricultural Crops:Corn, wheat, and soybean operations in Iowa and Illinois represent the core volume base. Cooperative buying groups now control majority additive procurement in these states, squeezing independent retailer margins.
- Horticulture:Controlled-environment vegetable production commands premium-grade formulations with sub-millimeter particle distribution for precision planting equipment. California's Central Valley pilots encapsulated coatings at commercial scale.
- Turf:Golf course and sports field managers source through specialized retail channels with seasonal demand concentration.
- Landscape:Municipal and commercial landscaping contractors prioritize cost-efficient commercial-grade bundles through wholesale distributors.
Agricultural Crops anchors absolute volume. Horticulture generates steepest margin expansion.
Grade:
Margin concentration follows certification intensity, with technical specifications determining access to export-oriented specialty crop contracts.
- Premium Grade:Ultra-low biuret content and controlled-release polymer specifications serve export-oriented fruit and vegetable producers. Koch Agronomic Services anchors demand through controlled-release technology portfolios.
- Commercial Grade:Standard urease and nitrification inhibitor formulations sustain volume across broadacre commodity applications. BASF SE competes through formulation breadth in this tier.
- Technical Grade:Precise active compound concentrations for research institutions and specialty blender operations.
- Low Biuret Grade:Reduced phytotoxicity specifications for foliar application in sensitive high-value crops.
Premium Grade captures concentrated margin pools. Commercial Grade sustains volume foundations.
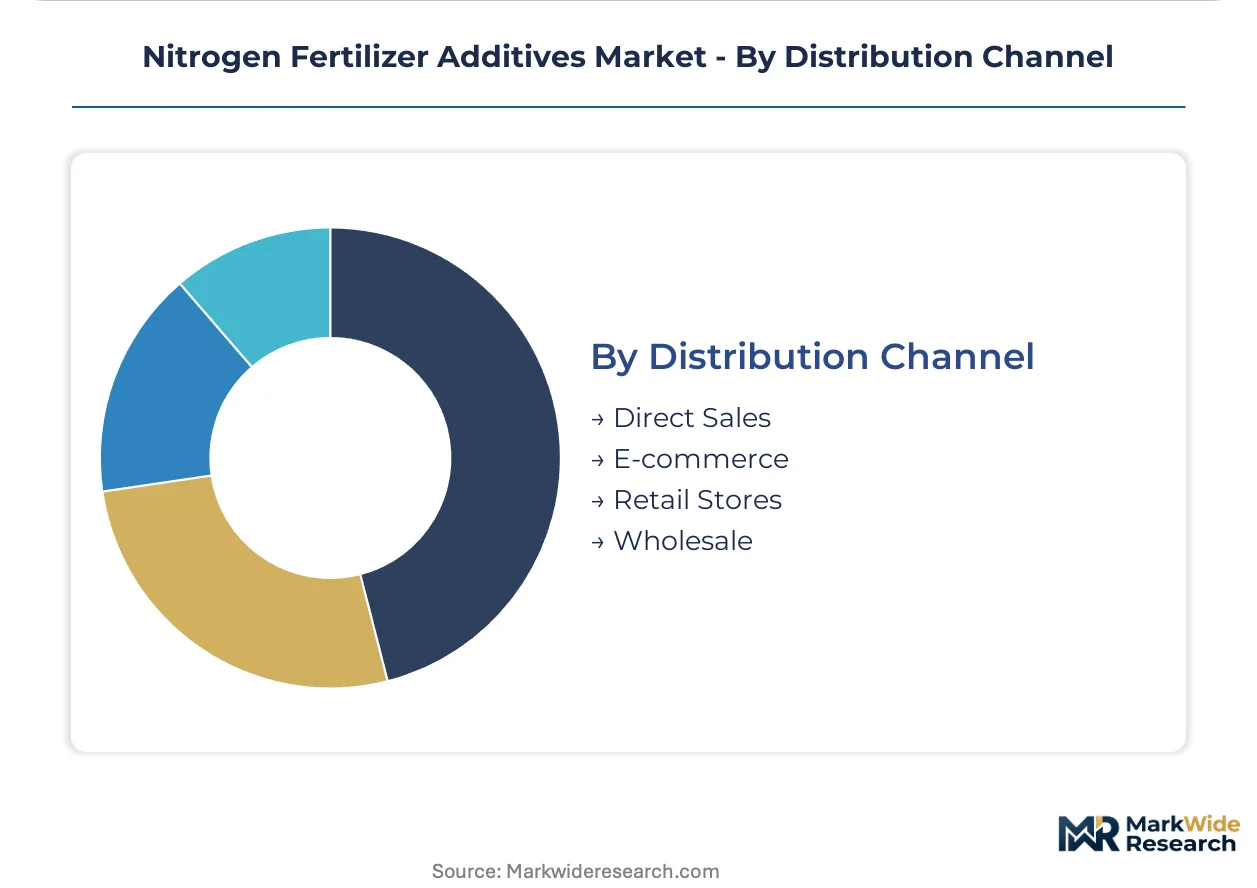
Distribution Channel:
Customer type and procurement scale reshape channel viability, with cooperative consolidation displacing legacy retail networks.
- Direct Sales:Manufacturers negotiate additive-inclusive fertilizer bundles with large cooperative buying groups. Three Iowa and Illinois cooperatives now control majority additive procurement volume in the US Midwest.
- Wholesale:Regional distributors serve independent agronomic retailers losing share to vertically integrated grain handlers. Yara dominates bulk supply to Brazilian soybean operations through this channel.
- E-commerce:Digital nutrient platforms integrate additive recommendations with variable-rate application equipment, gaining traction among precision agriculture adopters.
- Retail Stores:Independent agronomic retailers retain foothold in specialty crop regions with high service intensity requirements.
Direct Sales commands volume leadership. E-commerce is gaining share fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean operations import bulk urea additives from North American suppliers, creating a trade-flow corridor that shapes procurement patterns across the Atlantic basin.
United States
Corn and wheat operations in Iowa and Illinois drive urease inhibitor consumption to meet EPA Clean Air Act ammonia thresholds. The EPA enforces emission limits that accelerate additive deployment across the Corn Belt. Three cooperatives in these states now control majority procurement volume, displacing independent retailers.
Brazil
Soybean acreage in Mato Grosso and Rio Grande do Sul sustains demand for sulfur-compatible ammonium sulfate additives. ANVISA coordinates with agricultural ministries on import certification for active compound formulations. Cooperative buying groups in the Cerrado region negotiate directly with manufacturers for bundled supply.
China
MEE directives on agricultural non-point source pollution are converging on additive performance standards for domestic urea production. The ministry's dual carbon goals pressure nitrogen loss reduction in intensive rice systems. Yangtze River Delta fertilizer blenders are reformulating to meet emerging certification requirements.
Germany
Intensive dairy regions in Lower Saxony absorb nitrification inhibitors to comply with EU Green Deal nitrogen loss targets. ECHA oversees REACH compliance for DCD-based formulations entering member state markets. Bavarian cooperative networks subsidize adoption through environmental stewardship programs.
Netherlands
Greenhouse vegetable producers in Westland and North Brabant command premium-grade ammonium nitrate additives with sub-millimeter particle specifications. The EU F-Gas Regulation tightens nitrous oxide thresholds, forcing rapid reformulation cycles. Dutch horticulture clusters absorb compliance costs fastest due to enforcement proximity.
Nitrogen Fertilizer Additives Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with agronomic service divisions, creating a tiered structure where formulation expertise concentrates among established industrial names. The competitive landscape segments into three strategic archetypes: controlled-release technology specialists, bulk commodity additive suppliers, and precision horticulture formulators. Capacity expansion and portfolio diversification dominate competitive moves, with players extending coating technology portfolios and acquiring regional distribution networks.
Within the controlled-release technology tier, Koch Agronomic Services anchors demand among high-value crop producers through polymer barrier formulations. BASF SE and Yara occupy positions across the formulation breadth spectrum, with the former emphasizing nitrification inhibitor development and the latter dominating bulk supply channels to South American operations. These three companies exemplify the scale-driven and specialty-tier vectors that define competitive positioning.
| Leading Market Players |
|---|
| Solvay |
| BASF SE |
| Yara |
| Koch Agronomic Services |
| Clariant |
| Corteva Agriscience |
| KAO Corporation |
| Helena Agri-Enterprises |
| Innvictis Crop Care |
| Others |
Value Chain & Pricing Dynamics
Polymer coating substitution for traditional urea surface treatments is redrawing supply geography toward Gulf Coast petrochemical corridors while compressing margin structures for legacy formulation tiers.
Pricing Analysis
Next-generation encapsulated coating systems command 40-60% premiums over conventional NBPT-doped urea, while prior-generation uncoated commodities face persistent price erosion. Three-tier pricing structure across premium, standard, and economy levels stratifies by active compound concentration and release-kinetics certification. Cost compression in the commercial-grade tier is intensifying because cooperative buying groups extract volume discounts through bundled procurement. Specialty crop producers in California's Central Valley exhibit lowest price sensitivity; commodity grain operators in Iowa and Illinois absorb highest.
Supply Chain Analysis
The United States anchors active compound synthesis for NBPT and DCD formulations, while Germany concentrates precision polymer coating production and China dominates bulk urea substrate supply. Formulation draws from petrochemical derivatives, specialty chemical intermediates, and agricultural-grade urea. Single-source vulnerability concentrates in polymer resin supply for controlled-release coatings. Distribution runs through vertically integrated cooperative networks displacing independent agronomic retailers in the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nitrogen fertilizer additives occupy an early-cycle expansion phase as Brazilian soybean penetration lags North American adoption rates by approximately 15 percentage points, creating a multi-year volume uplift trajectory.
For Market Incumbents: Secure formulation chemist talent pools through captive R&D partnerships with land-grant university agriculture departments. Expand backward integration into polymer resin production to offset petrochemical feedstock volatility. Koch Agronomic Services exemplifies this defensive posture through controlled-release technology portfolio depth that emerging entrants cannot replicate without 5-7 year development cycles.
For New Entrants and Emerging Players: Anchor in Brazilian cooperative buying groups where additive penetration remains sub-scale despite comparable acreage to the US Corn Belt. Target Mato Grosso and Rio Grande do Sul soybean operations with sulfur-compatible ammonium sulfate formulations. Pursue white-label manufacturing partnerships with established distributors to bypass multi-jurisdiction registration barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical platforms lacking agronomic service divisions. Five-to-ten year viability hinges on coating technology IP durability and regulatory registration moats. Monitor ANVISA import certification timelines as inflection indicators for Brazilian market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Gulf Coast petrochemical proximity secures coating supply against crude derivative volatility. |
| Long-term Supply Agreement | Cooperative buying groups in Iowa and Illinois lock volume commitments through additive-inclusive fertilizer bundles. |
| Geographic Expansion | Brazilian Cerrado region offers additive penetration headroom comparable to 2015 US Corn Belt levels. |
| Joint Venture | Yara's digital nutrient platforms integrate with regional distributors to capture precision agriculture adopters. |
| Capacity Expansion | Dutch greenhouse cluster demand for sub-millimeter particle coatings outstrips current European supply. |
Study Parameters
Desk research of EPA enforcement actions, EU F-Gas Regulation implementation guidance, and Brazilian ANVISA import certifications preceded structured interviews with formulation R&D directors, cooperative procurement managers, and specialty crop agronomists. Primary fieldwork with distribution channel partners and controlled-environment horticulture operators combined with secondary validation against customs trade data and SEC 10-K filings. Bottom-up volume modeling triangulated against top-down regulatory mandate impact assessments.
Variance decomposition across the projection horizon isolates price elasticity effects, regulatory compliance cost pass-through, and technology substitution rates. Segmentation dimensions include product type, application intensity, grade certification tier, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to historical penetration data and enforcement timeline scenarios. Industry-specific inputs incorporate EPA Clean Air Act ammonia threshold trajectories and EU Green Deal nitrogen loss reduction mandates.
Material uncertainties — regulatory delay in emerging markets, polymer feedstock price shocks, and cooperative consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions about enforcement continuity and technology cost curves. Recalibration cycles align with material shifts in EPA rulemaking, ECHA REACH amendments, and Brazilian agricultural ministry incentive programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
India Fertilizers Market