
 Irrigation Controllers Market | 2026-2036
Irrigation Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Irrigation Controllers Market Intelligence
The expansion of asset-light leasing and subscription models for advanced irrigation systems is narrowing the competitive field to firms with significant capital reserves and service infrastructure. The Toro Company leverages its extensive portfolio in commercial turf and landscape management to bundle controller sales with other equipment. Hunter Industries differentiates through its focus on residential and light commercial systems, while Rain Bird Corporation sustains its market position via a vast global distribution network and brand recognition in both professional and retail channels.
An irrigation controller is an electronic device that automates the operation of a watering system by controlling valves to a pre-set schedule. These devices range from simple electromechanical timers to sophisticated processors that support numerous valve stations and integrate sensor inputs for soil moisture or rain. The primary function is to optimize water application, ensuring plant health while minimizing water waste. Smart controllers, particularly those with Wi-Fi and Cellular connectivity, are rapidly displacing older timer-based units in both agricultural and landscape applications. Weather-based controllers command higher margins due to their advanced water-saving capabilities.
Regulatory frameworks directly influence product design and market access. In the United States, the EPA's WaterSense label certifies controllers that meet stringent water efficiency criteria, creating a clear market advantage. In Europe, all electronic controllers must comply with CE marking for safety and the RoHS directive restricting hazardous materials. These standards establish essential performance and compliance benchmarks for all manufacturers. Vendor success now depends on navigating complex semiconductor supply chains and securing resilient access to wireless communication modules.
Market Dynamics
The irrigation controller market's evolution is governed by the dual pressures of water resource scarcity and the proliferation of IoT connectivity. This convergence compels a structural transition from rudimentary electromechanical timers to intelligent, data-driven systems that optimize water use in real-time.
Growth Catalysts
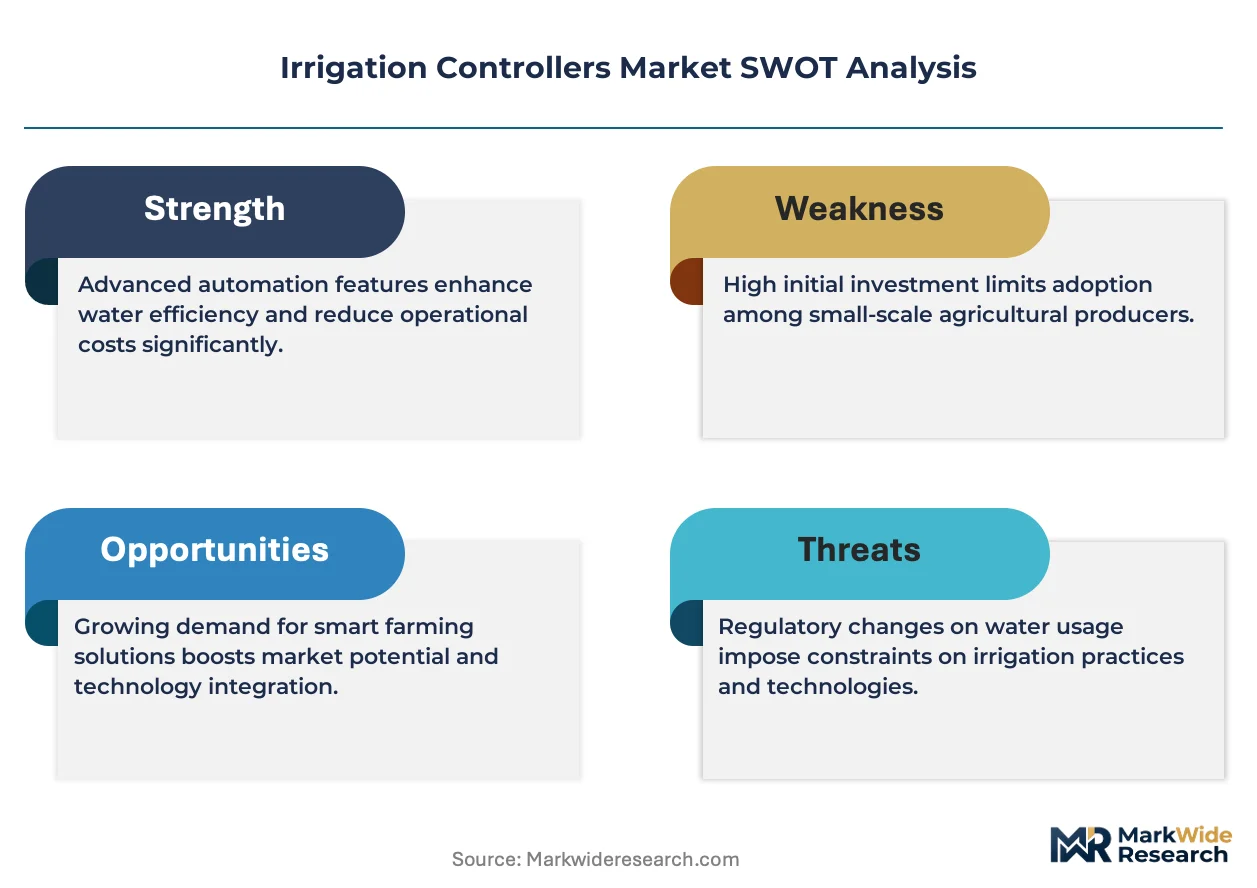
- Water Conservation Mandates:Government programs, such as the EPA's WaterSense label in the United States, provide rebates and create clear market incentives for upgrading to certified, water-efficient smart controllers.
- Precision Agriculture Demand:The need for enhanced crop yield and resource management in large-scale agricultural operations, particularly in water-stressed regions of Australia and India, drives adoption of controllers with advanced sensor integration.
- Component Cost Reduction:Declining costs for Wi-Fi and cellular communication modules are making internet-connected smart controllers more accessible and economically viable for the residential and light commercial landscape segments.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of sophisticated, multi-station smart controllers and associated sensors remains a primary adoption barrier for small-scale agricultural producers and budget-conscious residential consumers.
- Semiconductor Supply Volatility:A heavy reliance on a concentrated global supply chain for essential microprocessors and wireless modules exposes controller manufacturers to significant risks of production delays and input price instability.
- Interoperability Deficiencies:The absence of universal communication standards between controller brands and third-party sensors creates closed ecosystems, complicating system integration and limiting choices for end-users.
Strategic Opportunities
- Service-Based Business Models:Offering controllers through subscription or leasing models, bundling hardware with weather data services and remote support, can lower adoption barriers and create recurring revenue streams.
- Smart Home Ecosystem Integration:Developing compatibility with major smart home platforms like Amazon Alexa and Google Assistant opens new retail channels and enhances the value proposition for residential users.
- Emerging Agricultural Markets:Underpenetrated agricultural economies in Southeast Asia and parts of Africa, where irrigation infrastructure is being modernized, represent substantial long-term growth frontiers for controller deployment.
Industry Challenges
- Skilled Technician Scarcity:A deficit of installation professionals trained to configure and troubleshoot networked, sensor-integrated irrigation systems creates a bottleneck in service delivery and customer support, particularly for complex commercial projects.
- Legacy System Integration:Ensuring new smart controllers are backward-compatible with the vast installed base of older wiring, solenoids, and valves presents a persistent and costly engineering challenge for manufacturers.
- Wireless Compliance Complexity:Navigating the divergent and evolving radio frequency certification requirements for connected devices, such as FCC standards in the US and CE marking in Europe, adds significant cost and lead time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irrigation Controllers Market |
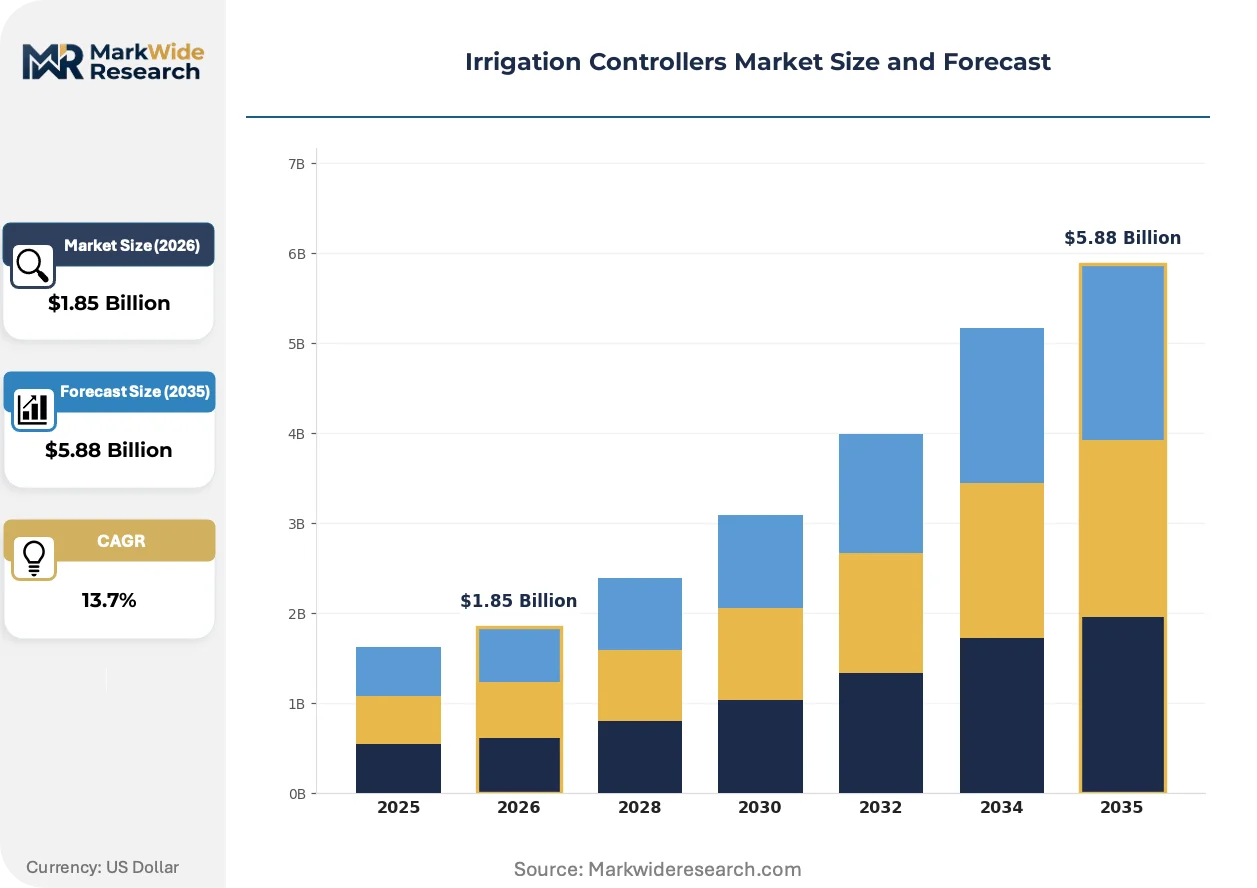
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Controllers, Centralized Controllers, Weather-Based Controllers, Timer-Based Controllers Technology: Wireless, Bluetooth, Wi-Fi, Cellular, Hardwired End User: Golf Courses, Sports Facilities, Landscape Management, Parks & Recreation Application: Agricultural Fields, Commercial Lawns, Greenhouses, Urban Landscaping |
| Companies Covered | Rain Bird Corporation, Hunter Industries, Toro Company, Netafim, Orbit Irrigation Products, Rachio, Weathermatic, Valmont Industries, Lindsay Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irrigation Controllers Market Strategic Shifts & Innovations
A fundamental shift from scheduled, mechanical control to dynamic, data-informed water management defines the current market landscape. This transformation is accelerated by accessible connectivity solutions and increasing regulatory pressure for verifiable water efficiency across agricultural and landscape applications.
Weather-based irrigation controller technology uses real-time local weather and evapotranspiration data to automatically modify watering schedules. Commercial turf managers and agricultural enterprises are the primary adopters, driven by the need to comply with strict water budgets. This technology is digitizing water allocation, converting it from a fixed schedule into a responsive, optimized resource management function.
European Union regulations, particularly the RoHS directive restricting hazardous substances, directly influence controller design and manufacturing. This compliance mandate forces vendors to re-evaluate and re-source components for circuit boards and casings, impacting material costs and supply chain partnerships. All products sold within the EU must meet these standards, creating a non-negotiable benchmark for global manufacturers.
Subscription-based models for irrigation software and premium data services are gaining favor over traditional one-time hardware sales. This change disrupts established distribution through retail and wholesale channels by creating a direct, ongoing relationship between the manufacturer and the end-user. This trend is most advanced in North American commercial agriculture, where data-driven optimization provides a clear return on investment.
Irrigation Controllers Market Segmentation
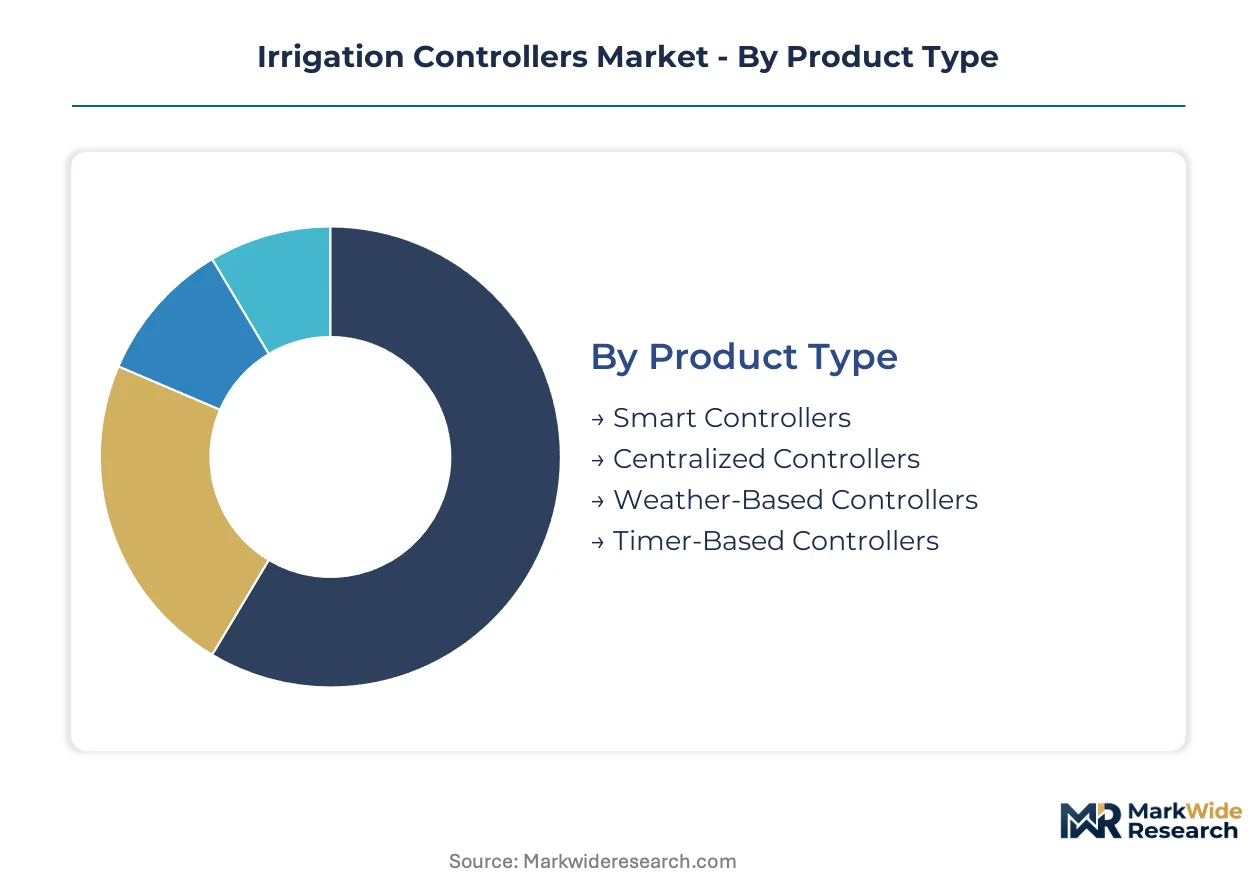
The irrigation controllers market is a mosaic of diverse technologies and applications, each requiring tailored water management solutions. Understanding these segments clarifies the market's structural evolution and pinpoints areas of concentrated demand and technological advancement.
Product Type:
The product type segmentation reveals a market transitioning from mature, simple devices to emerging, advanced controller solutions.
- Smart Controllers:These devices integrate advanced algorithms and sensor data, often with Wi-Fi or cellular connectivity, to automatically adjust irrigation schedules based on real-time conditions. Demand is concentrating in large-scale agricultural regions like California, driven by stringent water conservation mandates.
- Centralized Controllers:Sophisticated systems manage multiple irrigation zones across extensive properties, typically found in commercial or municipal settings, offering remote monitoring and control capabilities. Golf courses and large corporate campuses in the United States utilize these for precise resource allocation.
- Weather-Based Controllers:These units utilize local weather data, including evapotranspiration rates, to optimize watering schedules and minimize water waste.
- Timer-Based Controllers:Basic electromechanical or digital timers operate on pre-set schedules, offering fundamental automation without dynamic adjustments.
Timer-Based Controllers retains volume leadership; Smart Controllers holds the steepest expansion curve.
Technology:
Technology categories define the connectivity and operational sophistication available in irrigation controllers.
- Wi-Fi:Controllers with Wi-Fi connectivity enable remote access and programming via smartphones or web interfaces, facilitating real-time adjustments and data integration. Residential and light commercial landscapes in North America are rapidly adopting Wi-Fi enabled units due to declining component costs.
- Cellular:Cellular-enabled controllers provide robust connectivity in remote agricultural areas or locations without Wi-Fi infrastructure, ensuring reliable data transmission and command execution. Large-scale farms in Australia leverage cellular for broad-acre irrigation management.
- Wireless:This broad category includes various short-range communication protocols for connecting controllers to sensors and accessories, enhancing system flexibility.
- Bluetooth:Bluetooth connectivity offers convenient short-range programming and control, often used for residential systems where direct proximity to the controller is common.
- Hardwired:Traditional hardwired systems rely on physical cable connections for communication between the controller and valves, providing robust but less flexible installations.
Wireless connectivity remains foundational; Cellular solutions demonstrate the most dynamic growth.
End User:
End-user segments highlight distinct operational scales and water management priorities for irrigation systems.
- Landscape Management:Professionals managing commercial and residential green spaces require controllers that balance aesthetic needs with water efficiency and ease of programming. The need for remote management in urban centers drives demand.
- Golf Courses:Extensive turf areas and specialized watering requirements for greens and fairways necessitate advanced, centralized control systems capable of managing hundreds of zones. Water scarcity in regions like the Southwestern US pushes technological upgrades.
- Sports Facilities:Athletic fields demand precise irrigation for optimal playing conditions and turf health, often requiring controllers with weather-based adjustments.
- Parks & Recreation:Public green spaces utilize controllers for efficient water use across diverse plant types and high-traffic areas.
Golf Courses represent a high-value segment; Landscape Management shows consistent expansion.
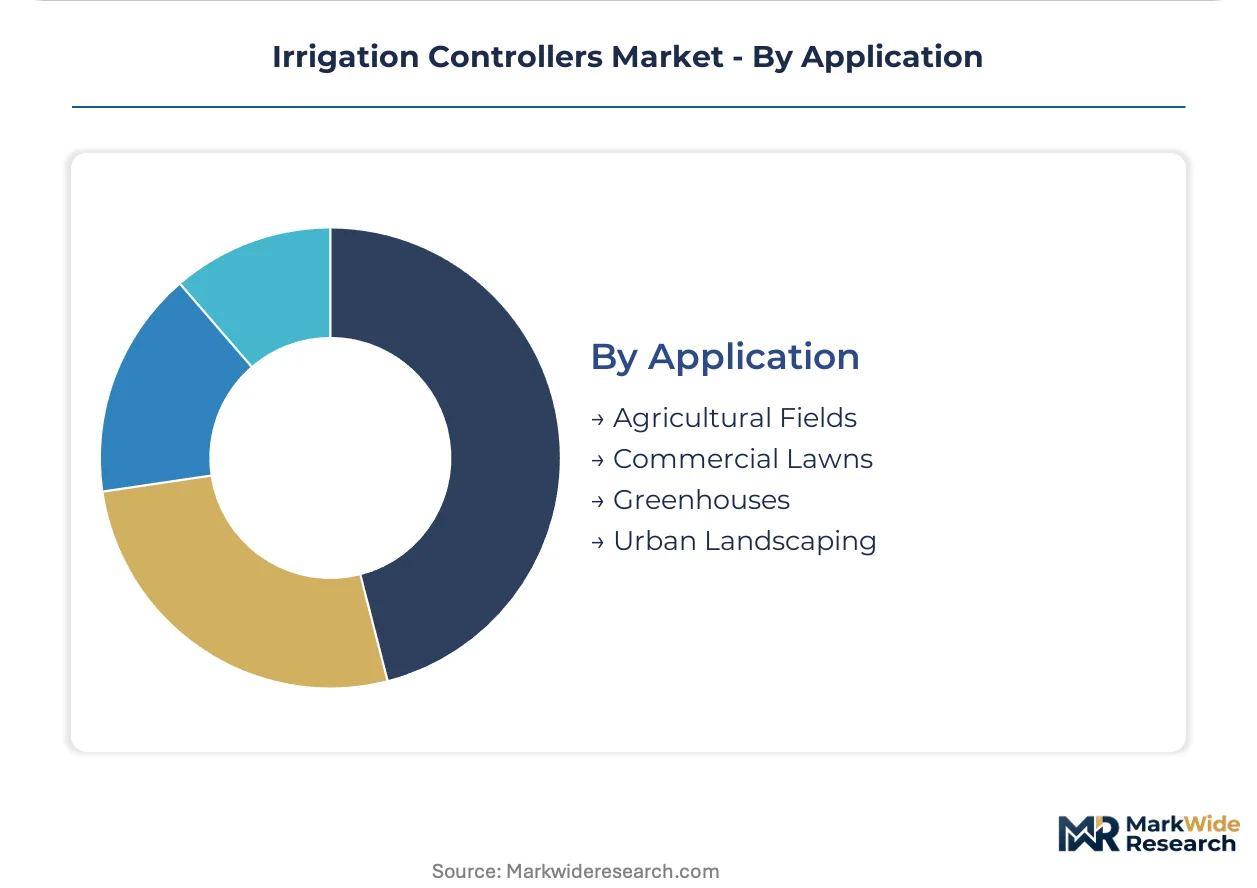
Application:
Application areas differentiate controller requirements based on environmental conditions and scale of water distribution.
- Agricultural Fields:Large-scale crop production demands robust, multi-station controllers integrated with soil moisture sensors and weather data for precise water application. Water-stressed agricultural zones in India and Australia are key adoption centers.
- Commercial Lawns:Businesses and institutions use controllers to maintain aesthetic appeal and comply with local watering restrictions, often favoring Wi-Fi or centralized systems. Property management firms across Europe prioritize efficiency and remote monitoring.
- Greenhouses:Controlled environments require specialized irrigation controllers that integrate with climate control systems for optimal plant growth.
- Urban Landscaping:Public and private green spaces within cities utilize controllers for efficient water use in diverse and often fragmented areas.
Agricultural Fields drive significant volume demand; Greenhouses are gaining share rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global irrigation controllers market reflects a dynamic interplay between regional demand for water conservation and localized manufacturing capabilities. Export-driven agricultural economies often seek advanced water management solutions, while domestic production hubs serve both local and international markets. This balance shifts with technological advancements and evolving regulatory landscapes.
United States
Precision agriculture and landscape management drive demand for smart controllers in the United States. The EPA's WaterSense program provides rebates, incentivizing upgrades to certified water-efficient devices. California's Central Valley, facing acute water scarcity, actively adopts sensor-integrated systems for optimizing crop irrigation.
Australia
Large-scale agricultural operations in Australia require robust cellular-enabled controllers for broad-acre irrigation management. Water scarcity challenges push for advanced resource management, particularly in regions like the Murray-Darling Basin. Farmers there leverage data-driven systems to enhance crop yield and comply with water quotas.
India
Modernization of irrigation infrastructure in India fuels demand for advanced controllers in water-stressed agricultural zones. The government's push for micro-irrigation schemes supports the adoption of smart solutions for efficient water use. States like Maharashtra and Rajasthan are seeing increased deployment of sensor-integrated systems to improve crop productivity.
Germany
European Union regulations, including CE marking and the RoHS directive, influence controller design and market access in Germany. Demand concentrates on water-efficient solutions for commercial landscaping and specialized agriculture. Manufacturers in Bavaria focus on developing compliant, high-margin weather-based controllers for diverse applications.
China
China's expanding agricultural sector and urban greening initiatives create significant demand for irrigation controllers. Government policies promoting water-saving technologies encourage the adoption of smart systems. Manufacturers in the Yangtze River Delta region focus on producing cost-effective, connected controllers for domestic and export markets.
Irrigation Controllers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential microprocessors and wireless modules for advanced controllers. The market structure exhibits a tiered consolidation, with larger firms leveraging extensive distribution networks and brand recognition. Key strategic archetypes include full-spectrum solution providers and niche technology innovators focused on specific applications. Companies frequently pursue portfolio diversification and strategic partnerships to navigate semiconductor supply volatility and expand geographic reach.
Within the established market, companies like Rain Bird Corporation and Hunter Industries exemplify firms with strong brand recognition and broad product portfolios across residential and commercial segments. The Toro Company, leveraging its extensive portfolio in commercial turf and landscape management, represents a player bundling controller sales with other equipment. These entities anchor distinct market segments, from professional landscaping to light commercial systems, maintaining market presence through vast distribution channels and robust service infrastructures. Their strategies often involve integrating new connectivity features and weather data services.
| Leading Market Players |
|---|
| Rain Bird Corporation |
| Hunter Industries |
| Toro Company |
| Netafim |
| Orbit Irrigation Products |
| Rachio |
| Weathermatic |
| Valmont Industries |
| Lindsay Corporation |
| Others |
Cost & Logistics Intelligence
Under-capacity in semiconductor and wireless module manufacturing drives both supplier behavior and pricing posture across the irrigation controller market. This component scarcity leads to extended lead times and cost increases for advanced smart controllers.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing model for irrigation controllers, combining per-unit transactional sales with subscription-based data services. Price differentiation stems from WaterSense certification and advanced weather-based functionality, offering superior water savings. Pricing pressure stems from input price instability due to semiconductor supply volatility, impacting manufacturing costs. Small-scale agricultural producers and residential consumers exhibit high price sensitivity, while large commercial and agricultural operations prioritize value from advanced features.
Supply Chain Analysis
Semiconductor supply volatility dominates the irrigation controller supply chain, creating significant risks of production delays and input price instability. Geographic concentration for microprocessors and wireless modules centers on Taiwan, South Korea, and China. Manufacturers rely on these regions for essential components, including communication modules and integrated circuits, alongside plastic polymers for casings. Distribution runs through a mix of direct sales to large agricultural enterprises and indirect channels via wholesale and retail partners for residential and commercial landscape segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The irrigation controllers market presents a fragmentation opportunity, driven by diverse demand for water-efficient solutions across agricultural and landscape applications. This shift creates distinct niches for specialized hardware and service offerings.
For Market Incumbents: Harden existing distribution channels by offering bundled solutions that integrate hardware with premium data services. Deepen vertical integration into wireless module and microprocessor sourcing to mitigate semiconductor supply volatility. This defends against emerging entrants leveraging asset-light subscription models. Invest in R&D for advanced weather-based algorithms and smart home platform compatibility to maintain technological leadership. For New Entrants and Emerging Players: Underpenetration in agricultural economies of Southeast Asia represents a significant white-space target for basic smart controller deployment. Focus on subscription-based models for hardware and data services to lower initial capital outlay for small-scale producers. Developing compatibility with major smart home platforms, like Amazon Alexa, offers a rapid go-to-market angle in residential segments. Target regions with modernizing irrigation infrastructure for early adoption. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms offering bundled hardware with premium data and support services. The market's long-term viability remains strong over the next decade due to persistent water scarcity and increasing IoT connectivity. Target niche technology innovators specializing in advanced sensor integration or AI-driven water optimization. The signal to watch is the widespread implementation of new regional water conservation mandates beyond current levels.| Strategic Initiative | Industry Significance |
|---|---|
| Expand Subscription-Based Service Models | This lowers adoption barriers for small-scale agricultural producers and creates recurring revenue streams. |
| Invest in Advanced Sensor Integration | Enhances precision agriculture capabilities, optimizing water use in large-scale agricultural operations. |
| Diversify Semiconductor Sourcing | Mitigates production delays and input price instability stemming from global supply chain volatility. |
| Develop Smart Home Ecosystem Compatibility | Opens new retail channels and enhances value for residential users of smart controllers. |
| Target Emerging Agricultural Markets | Captures long-term growth frontiers in underpenetrated economies modernizing irrigation infrastructure. |
Research Approach
A standing panel of irrigation system integrators, agricultural engineers, and smart home technology developers provided ongoing calibration for primary insights. This involved interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included EPA WaterSense program documentation and EU regulatory frameworks. Both bottom-up and top-down market sizing were triangulated for data integrity.
Scenario-bracketing provided a robust analytical framework, encompassing baseline, optimistic, and conservative growth projections across the analysis window. Segmentation dimensions modeled included product type, technology, end-user, application, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and growth catalysts. Key forecast inputs included regional water conservation mandate adoption rates and communication module cost reductions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by niche technology innovators would shift outcomes. Forecasts reflect assumptions on stable regulation and supply; geopolitical shifts or swift water mandate changes are key risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Zero Turn Mowers Market