
 South America Irrigation Machinery Market | 2026-2036
South America Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Irrigation Machinery Market Analytics
Dealer networks across Brazil and Argentina is tilting toward agricultural cooperatives and direct manufacturer partnerships, bypassing traditional distributor markups in high-volume soybean and sugarcane zones. Valmont Industries anchors its South American position through localized manufacturing and service infrastructure. Lindsay Corporation competes on pivot system durability tailored to Cerrado soil conditions. Netafim differentiates through drip irrigation specialization for high-value fruit and vegetable exports.
South America irrigation machinery encompasses mechanized systems for controlled water delivery to agricultural crops, including center-pivot and lateral-move sprinklers, pressure-compensating drip emitters, and buried subsurface tubing rated for 0.5–4.0 bar operating pressure, designed to optimize yield per cubic meter in water-stressed growing regions. Sprinkler systems dominate installed base across extensive grain operations, while drip systems command premium margins in Brazil's fruit-export corridors and Peru's coastal valleys. Smart irrigation technology is gaining fastest traction among commercial growers managing multiple plots, though traditional systems still occupy the majority of smallholder procurement budgets.
Brazil's ANA water permitting framework and Argentina's provincial groundwater extraction regulations constrain new system deployment without flow-metering and efficiency certification. ANVISA and Brazil's Ministry of Agriculture set equipment material standards for food-contact irrigation components. Stakeholders must monitor evolving water-rights enforcement intensity and align product portfolios with tightening efficiency thresholds before regulatory gaps close.
Market Dynamics
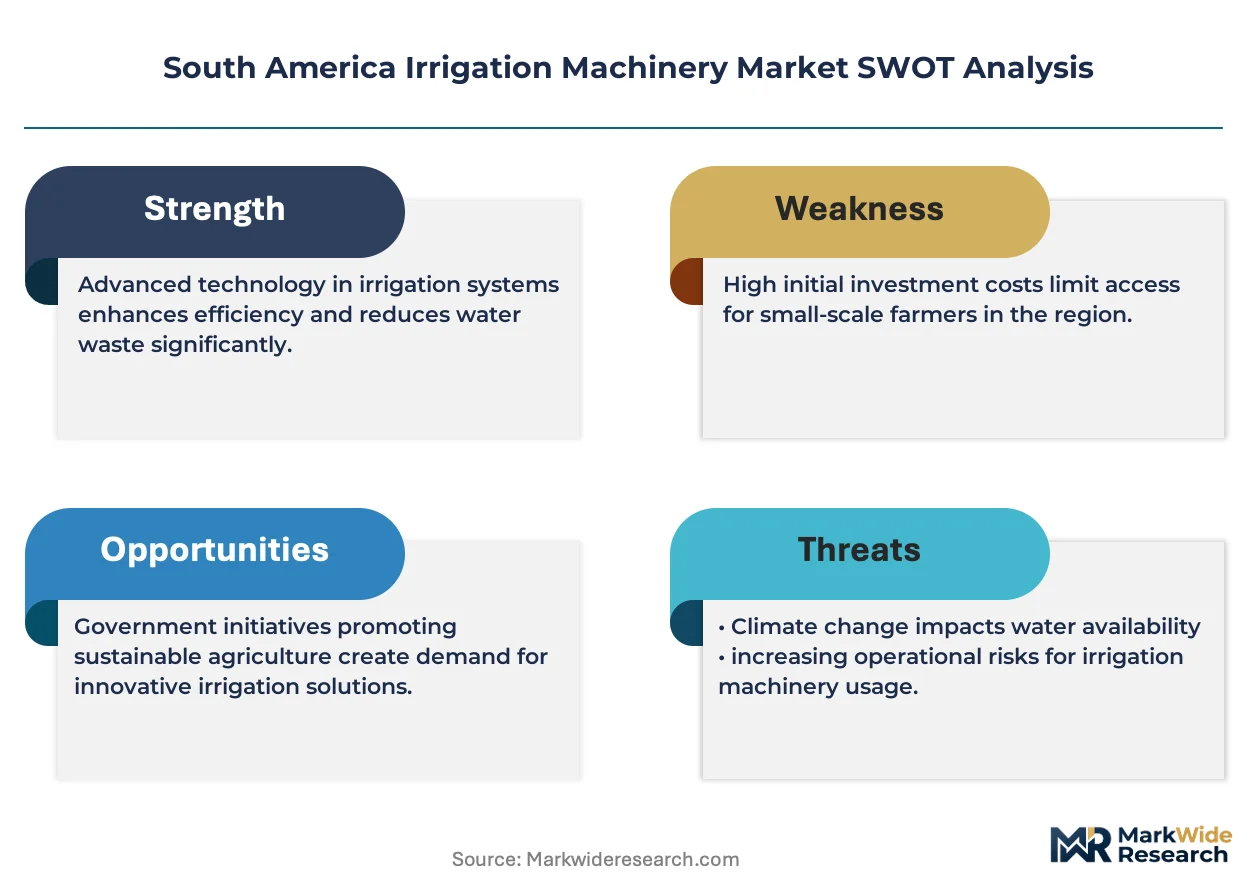
ANA water-use permitting in Brazil and Argentina's provincial groundwater regulations are compressing deployment timelines, forcing manufacturers to pre-certify flow-metering and efficiency compliance before equipment reaches farms. This regulatory front-loading is restructuring competitive advantage toward integrated solution providers with in-house compliance capabilities.
Growth Catalysts
- Cerrado soybean mechanization:Large-scale producers in Brazil's Mato Grosso and Goiás states are expanding center-pivot coverage amid intensifying dry-season water stress, pulling demand for high-capacity sprinkler systems.
- ANA efficiency mandates:Brazil's National Water Agency now requires flow-metering and certification for new irrigation permits, creating pull for precision equipment with embedded monitoring.
- Drip-compatible precision agriculture:Argentina's shift toward subsurface drip installations in fruit-export corridors is opening premium-margin equipment categories previously dominated by grain-focused sprinklers.
Market Restraints
- Steel and polymer input volatility:Center-pivot towers and polyethylene tubing face cost pressure from commodity swings, compressing margins for equipment assemblers without backward integration into raw materials.
- Dealer network concentration:Agricultural cooperatives in Brazil's soybean belt are consolidating procurement power, squeezing traditional distributor markups and threatening smaller regional equipment vendors.
- Subsurface drip installation complexity:Buried emitter systems require specialized trenching and filtration infrastructure that limits adoption outside high-value horticulture and export-oriented operations.
Strategic Opportunities
- Peru coastal valley expansion:Desert agriculture zones along Peru's Pacific coast remain underpenetrated by mechanized irrigation, offering first-mover positioning for drip system specialists.
- Smart controller convergence:Integration of soil-moisture sensors with variable-frequency drives is creating premium-priced precision packages for commercial growers managing dispersed plots.
- Direct manufacturer partnerships:Bypassing distributor layers through cooperative-direct relationships is capturing volume in Brazil's high-throughput sugarcane and soybean zones.
Industry Challenges
- Certification timeline compression:ANA and ANVISA parallel approval tracks for equipment materials and water-efficiency ratings are extending product launch cycles by 8-14 months.
- Legacy system integration friction:Retrofitting smart monitoring onto installed center-pivot bases requires proprietary adapter hardware that fragments service ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Irrigation Machinery Market |
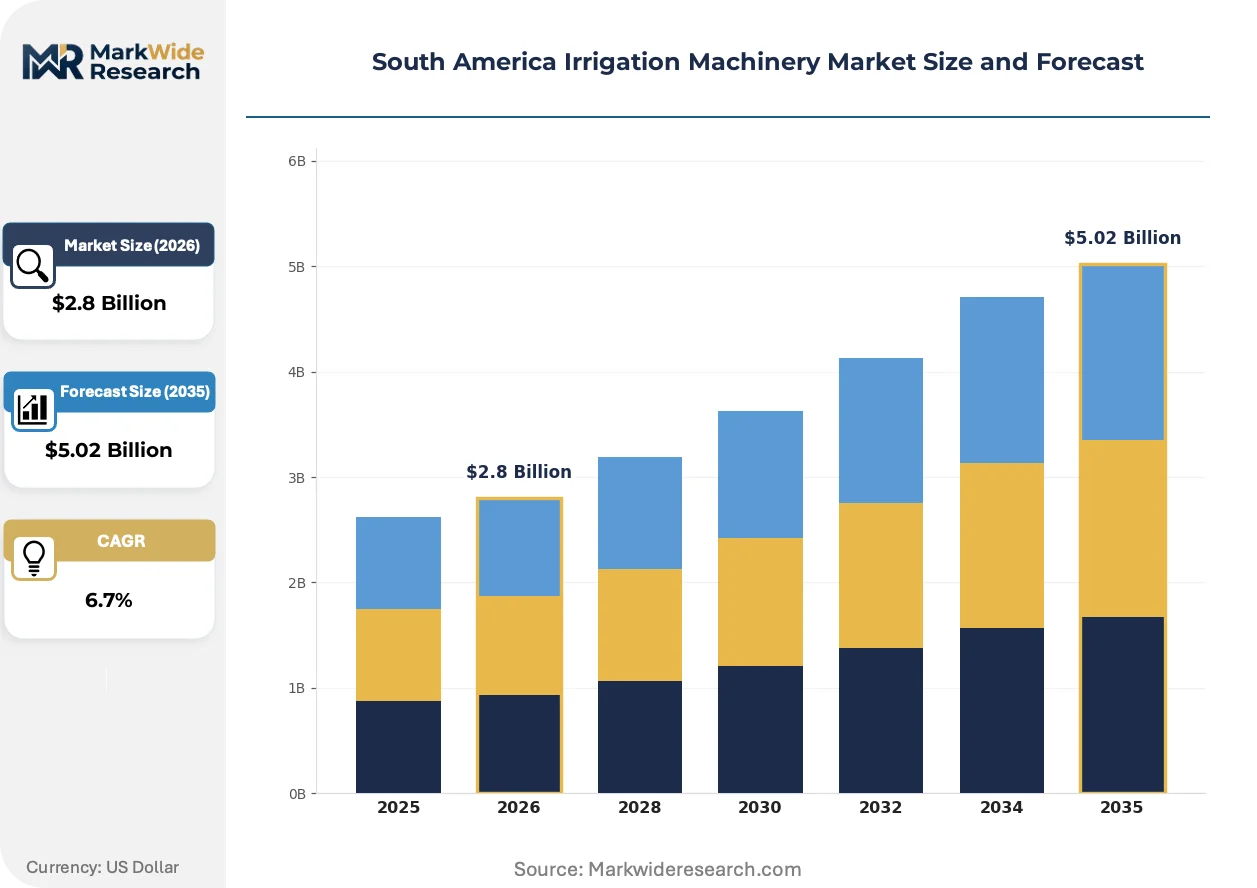
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Systems, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation Technology: Automated Systems, Smart Irrigation, Sensor-Based Technology, Traditional Irrigation End User: Agricultural Producers, Commercial Growers, Residential Users, Government Agencies Distribution Channel: Direct Sales, Distributors, Online Retail, Agricultural Cooperatives |
| Companies Covered | Rivulis Irrigation, Lindsay Corporation, Valmont Industries, The Toro Company, Nelson Irrigation Corporation, Netafim, Rain Bird Corporation, Orbia Advance Corporation, Jain Irrigation Systems, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Irrigation Machinery Market Evolving Landscape
Telematics-enabled irrigation control is displacing manual valve adjustment across South American commercial agriculture, compressing labor requirements while tightening water accountability. Equipment vendors are racing to embed compliance-ready data logging that satisfies ANA audit requirements without retrofit.
Variable-rate irrigation (VRI) technology is rendering obsolete uniform water application across heterogeneous field zones. Large-scale grain operations in Brazil's Cerrado are adopting GPS-guided pivot speed and nozzle control to match application maps with soil-type variation. This precision layering is compressing water-use intensity per ton of soybean output while raising equipment specification thresholds.
Argentina's provincial groundwater extraction regulations are mandating volumetric monitoring and efficiency thresholds for new well permits. Equipment suppliers must now bundle certified flow meters and pressure-compensating emitters to qualify for licensing. Horticulture exporters in Mendoza and Rio Negro are responding by specifying integrated drip systems with embedded compliance documentation.
Cooperative procurement consolidation is restructuring channel economics across Brazil's grain belt. Mato Grosso and Goiás agricultural cooperatives are aggregating demand into volume tenders that bypass traditional equipment distributors. Manufacturers with localized service infrastructure are capturing this disintermediated volume through direct partnership structures.
South America Irrigation Machinery Market Segmentation
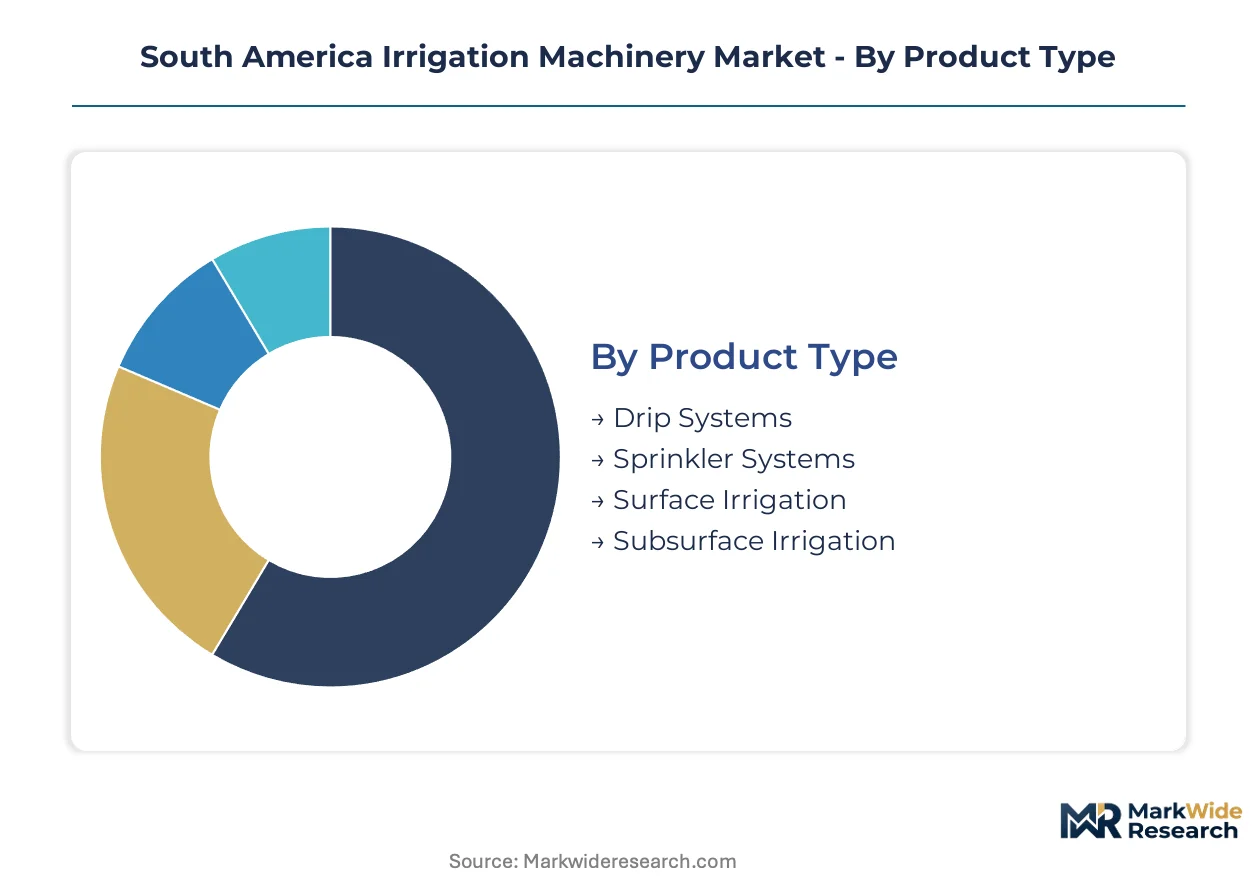
Equipment specification varies sharply across South American irrigation machinery segments, with water-stressed soybean operations in Brazil's Cerrado pulling high-capacity sprinkler systems while export-oriented horticulture in Argentina's Mendoza province specifies precision drip infrastructure. Regulatory front-loading by ANA and provincial groundwater authorities is compressing deployment timelines and forcing technology choices that embed compliance capabilities.
Product Type:
Mature sprinkler installations dominate extensive grain operations, while emerging subsurface technologies capture premium positioning in high-value crop corridors.
- Sprinkler Systems:Center-pivot and lateral-move configurations rated for 0.5–4.0 bar operating pressure constitute the installed base across Brazil's Mato Grosso and Goiás states. Large-scale soybean producers under ANA water-use permitting are expanding mechanized coverage amid intensifying dry-season stress.
- Drip Systems:Pressure-compensating emitters and surface tubing optimize yield per cubic meter in water-constrained growing regions. Argentina's shift toward precision agriculture in fruit-export corridors is opening premium-margin equipment categories previously dominated by grain-focused alternatives.
- Subsurface Irrigation:Buried emitter systems with specialized trenching and filtration infrastructure limit adoption to high-value horticulture and export-oriented operations in Peru's coastal valleys.
- Surface Irrigation:Gravity-fed flood and furrow methods persist among smallholder procurement budgets in legacy agricultural zones with abundant water access.
Sprinkler systems handle the majority of throughput; subsurface irrigation is gaining share fastest in premium export corridors.
Technology:
Cost tier stratification separates precision-enabled packages from baseline equipment, with compliance-ready data logging commanding substantial premiums.
- Automated Systems:Variable-frequency drives and programmable controllers reduce labor requirements across commercial operations managing multiple plots. Telematics-enabled control is displacing manual valve adjustment throughout South American commercial agriculture.
- Smart Irrigation:Soil-moisture sensor integration with GPS-guided pivot speed and nozzle control enables variable-rate application matching soil-type variation. Large-scale grain operations in Brazil's Cerrado are adopting this precision layering to compress water-use intensity per ton of output.
- Sensor-Based Technology:Embedded flow-metering and efficiency certification hardware satisfies ANA audit requirements without retrofit, extending product launch cycles but capturing regulatory-compliant demand.
- Traditional Irrigation:Manual valve systems and mechanical timers occupy the majority of smallholder procurement budgets, though retrofit friction fragments service ecosystems when upgrading to smart monitoring.
Traditional technology retains volume leadership in smallholder segments; smart irrigation climbs fastest among commercial growers with dispersed plot portfolios.
End User:
Customer type determines specification intensity, with volume aggregators consolidating procurement power against fragmented residential demand.
- Agricultural Producers:Extensive grain operations in Brazil's soybean belt specify high-capacity center-pivot systems with durability ratings tailored to Cerrado soil conditions. Cooperative procurement consolidation is restructuring channel economics through direct manufacturer partnerships.
- Commercial Growers:Export-oriented horticulture operations in Argentina's Mendoza and Rio Negro provinces specify integrated drip systems with embedded compliance documentation for provincial groundwater extraction regulations.
- Government Agencies:ANA and provincial water authorities mandate volumetric monitoring and efficiency thresholds for new well permits, creating institutional demand for certified equipment specification.
- Residential Users:Small-scale lawn and garden applications represent price-sensitive demand with limited regulatory exposure and minimal technology penetration.
Agricultural producers command the dominant share of equipment throughput; commercial growers represent the steepest expansion trajectory as export horticulture scales.
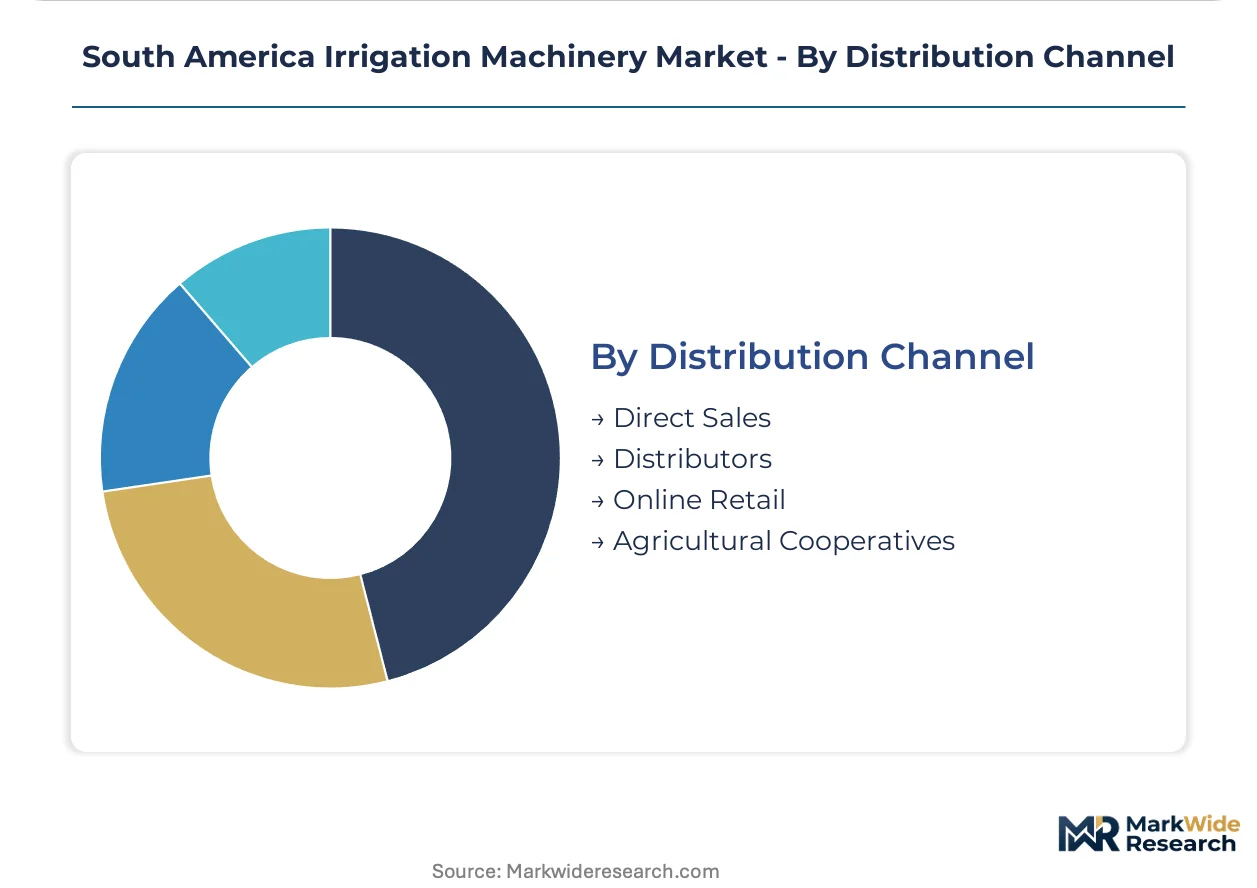
Distribution Channel:
Supply concentration favors integrated solution providers with localized service infrastructure over fragmented retail alternatives.
- Agricultural Cooperatives:Mato Grosso and Goiás cooperatives are aggregating demand into volume tenders that bypass traditional equipment distributors. Manufacturers with captive service infrastructure capture this disintermediated volume.
- Direct Sales:Manufacturer partnerships with large-scale operators eliminate distributor markups in high-throughput sugarcane and soybean zones, compressing margins for regional equipment vendors without backward integration.
- Distributors:Traditional dealer networks face procurement power consolidation from cooperatives, squeezing markups and threatening smaller regional vendors unable to match service density.
- Online Retail:Digital channels capture replacement parts and consumables demand, though capital equipment transactions remain relationship-driven through cooperative and direct channels.
Agricultural cooperatives channel the largest equipment volumes; direct sales expands most quickly as manufacturers build localized service infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paraguay-Paraná Waterway and Brazil's North-South Railway underpin agricultural corridor development, linking Mato Grosso production zones to Atlantic export terminals and enabling heavy machinery distribution across the continent's interior.
Brazil
Mato Grosso and Goiás states anchor center-pivot expansion as soybean producers confront intensifying Cerrado dry seasons. ANA water-use permitting mandates flow-metering and efficiency certification for new irrigation licenses. The Rondonópolis industrial cluster hosts localized manufacturing and service infrastructure for equipment assemblers.
Argentina
Mendoza and Rio Negro provinces drive subsurface drip adoption among fruit-export horticulture operations. Provincial groundwater extraction regulations require volumetric monitoring and efficiency thresholds for new well permits. The Alto Valle del Río Negro corridor concentrates precision agriculture equipment deployment.
Peru
Coastal valleys along the Pacific desert agriculture belt remain underpenetrated by mechanized irrigation infrastructure. The country's national water authority supervises extraction licensing with emerging efficiency requirements. The Ica Valley cluster presents first-mover positioning for drip system specialists targeting asparagus and grape exports.
Chile
Central Valley fruit producers specify pressure-compensating emitters for wine grape and berry export operations. The national agricultural service enforces water-use efficiency standards in drought-affected watersheds. The O'Higgins Region concentrates high-value horticulture mechanization investment.
Colombia
Coffee zone modernization and palm oil expansion pull sprinkler system demand in the Andean foothills. Regional environmental authorities administer watershed-based extraction permits with efficiency documentation requirements. The Quindío and Risaralda departments cluster precision irrigation adoption among diversified agricultural operations.
South America Irrigation Machinery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base stratifies between full-system providers with captive service networks and regional assemblers dependent on third-party distribution. Three archetypes dominate: multinational platform builders with localized manufacturing, regional equipment fabricators serving cooperative procurement channels, and precision technology specialists focused on drip and sensor integration. Competitive moves concentrate on direct manufacturer partnerships with agricultural cooperatives and backward integration into polymer and steel component production.
Among Israel-based precision specialists, Netafim exemplifies the drip technology archetype with embedded compliance capabilities for regulated export corridors. Lindsay Corporation and Valmont Industries represent the full-system platform tier, anchoring center-pivot and lateral-move configurations across Brazil's grain belt. These three occupy positions that align with the market's regulatory front-loading and cooperative procurement consolidation dynamics.
| Leading Market Players |
|---|
| Rivulis Irrigation |
| Lindsay Corporation |
| Valmont Industries |
| The Toro Company |
| Nelson Irrigation Corporation |
| Netafim |
| Rain Bird Corporation |
| Orbia Advance Corporation |
| Jain Irrigation Systems |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazil's steel rolling mills and polymer extrusion plants is compressing supplier margins while elevating spot pricing volatility for center-pivot tower components. This utilization squeeze forces equipment assemblers to pre-position inventory or absorb cost pass-throughs, reshaping procurement calendars across Mato Grosso and Goiás cooperative networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates South American irrigation machinery procurement. ANA-certified smart systems with embedded flow-metering command substantial premiums over baseline sprinkler configurations, while stripped mechanical systems serve price-sensitive smallholder segments in legacy agricultural zones. Cost compression in standard-tier center-pivot equipment is intensifying because Brazilian agricultural cooperatives are consolidating volume tenders and squeezing distributor markups. Grain-focused commercial growers exhibit lowest price sensitivity due to yield-per-hectare optimization mandates, whereas residential lawn and garden buyers remain highly elastic.
Supply Chain Analysis
Contract manufacturing for precision emitters and sensor modules concentrates in Israel, China, and the United States, with final system assembly anchored in Brazil's Rondonópolis industrial cluster. Steel tower fabrication draws from Argentine and Brazilian mills, while polyethylene tubing feeds from petrochemical complexes along Brazil's southeastern coast. Single-source vulnerability in pressure-compensating emitter technology creates exposure if geopolitical friction disrupts Israeli component flows. Distribution runs through agricultural cooperatives and direct manufacturer partnerships that bypass traditional dealer layers in high-volume soybean and sugarcane territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Irrigation Machinery Market is entering a cyclical recovery phase as Cerrado soybean producers accelerate mechanization amid intensifying dry-season water stress. Equipment replacement cycles and ANA regulatory compliance deadlines are synchronizing to pull demand through the projection horizon.
For Market Incumbents: Harden service infrastructure density across Mato Grosso and Goiás cooperative territories to defend against direct manufacturer partnership encroachment. Backward integration into polymer compounding and steel component production buffers margin compression from commodity input volatility. Certification investment in ANA-compliant flow-metering systems captures regulatory-front-loaded demand before compliance gaps close.
For New Entrants and Emerging Players: Pursue white-space positioning in Peru's Ica Valley and coastal desert agriculture corridors where mechanized drip penetration remains minimal. Argentina's Mendoza and Rio Negro fruit-export zones offer premium-margin entry points for subsurface irrigation specialists. Direct technical partnership with export-oriented horticulture cooperatives bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart irrigation sub-segments as sensor integration and compliance-ready data logging become baseline specifications. Long-term viability favors platform integrators with captive service networks over component assemblers dependent on third-party distribution. Acquisition targets should demonstrate localized manufacturing presence and cooperative channel access. The signal to watch is ANA enforcement intensity escalation as water-rights permitting tightens.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive supply of polyethylene tubing insulates margins from petrochemical price swings in Brazil. |
| ANA Compliance Certification Investment | Pre-certified flow-metering systems capture regulatory-front-loaded demand from Mato Grosso cooperatives. |
| Direct Cooperative Partnership Structure | Bypassing distributor markups captures volume in high-throughput soybean and sugarcane zones. |
| Peru Coastal Valley Market Entry | First-mover positioning in Ica Valley asparagus and grape export corridors opens premium drip demand. |
| Smart Controller Convergence Development | Soil-moisture sensor integration with variable-frequency drives creates precision packages for dispersed plot managers. |
Research Methodology
A standing panel of agricultural cooperative procurement managers, center-pivot maintenance directors, ANA regulatory affairs officers, drip system installation contractors, and export horticulture operations managers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with equipment vendors and end-users, validated against secondary sources including ANA water permitting databases, Brazil's Ministry of Agriculture equipment certification registries, Argentine provincial groundwater extraction records, and customs trade data for irrigation machinery imports. Bottom-up demand aggregation from cooperative procurement tenders was triangulated against top-down production capacity estimates from Brazilian manufacturing clusters.
Scenario-bracketing around ANA enforcement intensity and commodity input price volatility anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and distribution channel structure, with additional granularity on regulatory compliance status. CAGRs were derived from equipment deployment trajectories in water-stressed growing regions, cross-referenced with agricultural expansion forecasts for soybean and export horticulture acreage.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, agricultural commodity prices, or global steel and polymer costs would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and cooperative consolidation velocity. Quarterly review of ANA permitting issuance rates, agricultural credit availability indicators, and input commodity price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
Global Irrigation Automation Market