
 Global Irrigation Machinery Market | 2026-2036
Global Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Irrigation Machinery Market Outlook
Dealer-direct and cooperative purchasing networks is reconfiguring how irrigation machinery reaches farm operators across major agricultural belts. Valmont Industries leverages its Valley Irrigation dealer footprint to sustain aftermarket parts revenue and control service touchpoints in North American row-crop regions. Lindsay Corporation anchors its position through Zimmatic center-pivot systems that dominate large-scale field applications across the Great Plains and Brazilian Cerrado.
Irrigation machinery comprises engineered water delivery systems—center-pivot, lateral move, drip line, and micro-sprinkler assemblies—designed to apply controlled volumes at specified pressures, flow rates, and distribution uniformities to optimize crop water productivity. These systems integrate pumps, filtration units, valves, and control heads to reduce evaporative losses and match soil-plant-atmosphere demand curves in commercial agriculture. Drip irrigation leads product type margins due to polymer emitter precision and filtration complexity, while automated systems within the technology dimension are expanding fastest as soil moisture telemetry and variable-rate valve actuation displace timer-based scheduling. Solar-powered irrigation represents an emerging installation category where photovoltaic pump drives reduce diesel dependency in remote or grid-limited farm locations.
The EPA regulates agricultural runoff under the Clean Water Act, pressuring machinery makers to certify systems for chemigation backflow prevention and nutrient application precision. India's BIS enforces emitter discharge uniformity standards under IS 13487, while the EU Green Deal's Farm to Fork strategy tightens water-efficiency benchmarks that CE-marked equipment must satisfy for market access. Stakeholders must monitor how groundwater basin adjudications and energy pricing reforms reshape total cost-of-ownership calculations for mechanized irrigation investments.
Market Dynamics
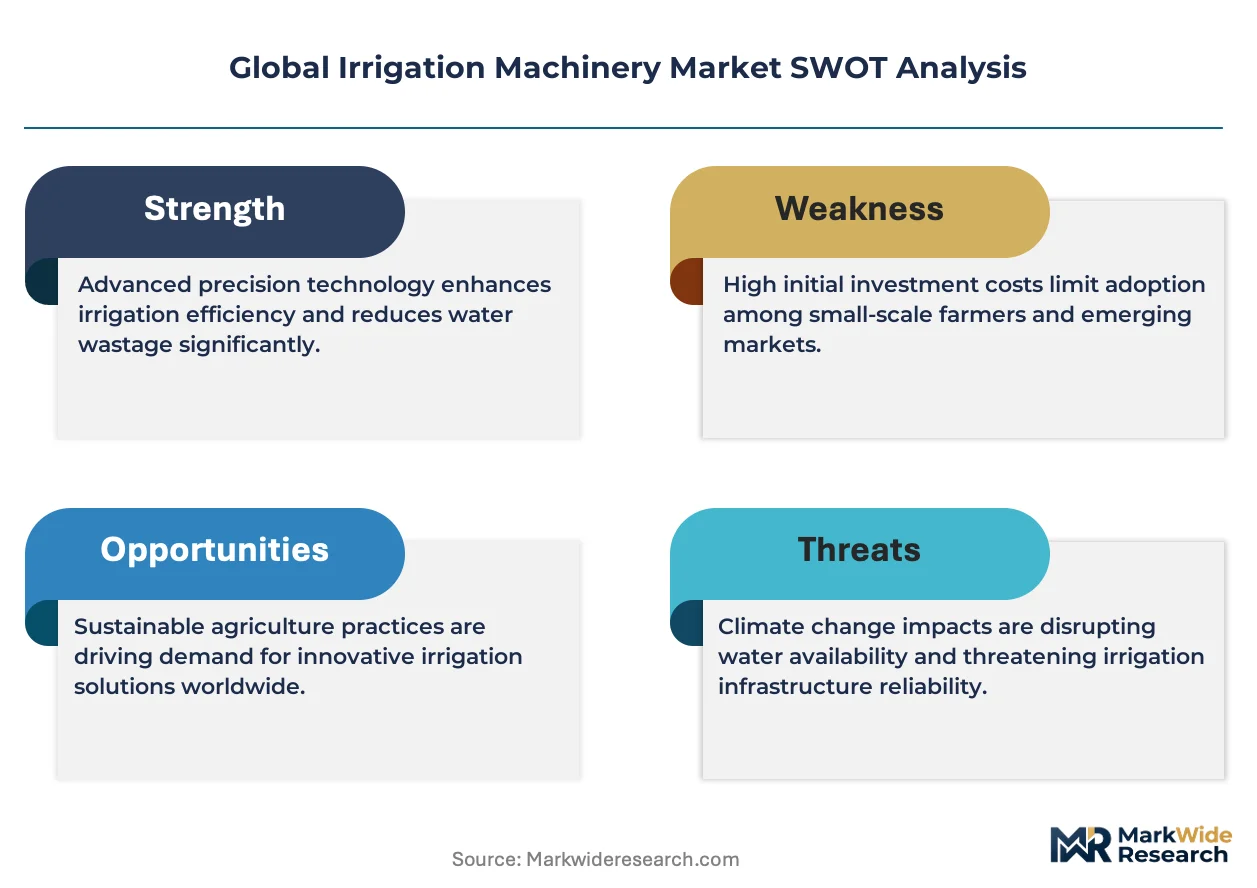
Groundwater basin adjudications and energy pricing reforms are restructuring capital deployment cycles for mechanized irrigation, forcing operators to recalculate total cost-of-ownership before committing to center-pivot or drip infrastructure.
Growth Catalysts
- SGMA compliance deadlines:California's Sustainable Groundwater Management Act mandates measurable water-use reductions across critically overdrafted basins, accelerating precision system retrofits in specialty crop operations.
- Soil moisture telemetry integration:Variable-rate valve actuation linked to real-time sensor networks is replacing timer-based scheduling, lifting water productivity metrics in broadacre wheat and cotton systems.
- Photovoltaic pump drives:Solar-powered irrigation installations are expanding across remote Australian stations and Indian smallholdings where grid extension costs or diesel price volatility previously blocked mechanization.
Market Restraints
- Polymer emitter cost volatility:Drip line margins compress when polyethylene and ethylene-vinyl acetate resin prices spike, squeezing mid-tier manufacturers without captive polymer supply.
- Filtration complexity:Emitter clogging from biological and chemical precipitates demands multi-stage filtration systems that raise upfront capital requirements and maintenance labor intensity.
- Backflow certification friction:EPA chemigation prevention standards under the Clean Water Act impose testing protocols that delay system commissioning and inflate compliance documentation costs.
Strategic Opportunities
- Smallholder aggregation platforms:Cooperative purchasing networks in Maharashtra and Gujarat are consolidating fragmented demand to negotiate volume pricing on drip kits and solar pumps.
- EU Farm to Fork alignment:Water-efficiency benchmarks embedded in the Green Deal's sustainability criteria create preferential market access for CE-marked equipment with documented distribution uniformity.
- Telemetry-to-actuator convergence:Integration of satellite-derived evapotranspiration data with automated scheduling algorithms is opening subscription revenue streams for machinery OEMs.
Industry Challenges
- Hydraulic engineering skill scarcity:Design of pressure-compensating emitter networks and pump sizing for variable topography requires specialized fluid mechanics expertise that irrigation districts struggle to retain.
- Legacy flood-to-precision migration:Reconfiguration of field layouts and drainage infrastructure to accommodate linear move or lateral roll systems demands multi-year capital cycles that test farmer liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Irrigation Machinery Market |
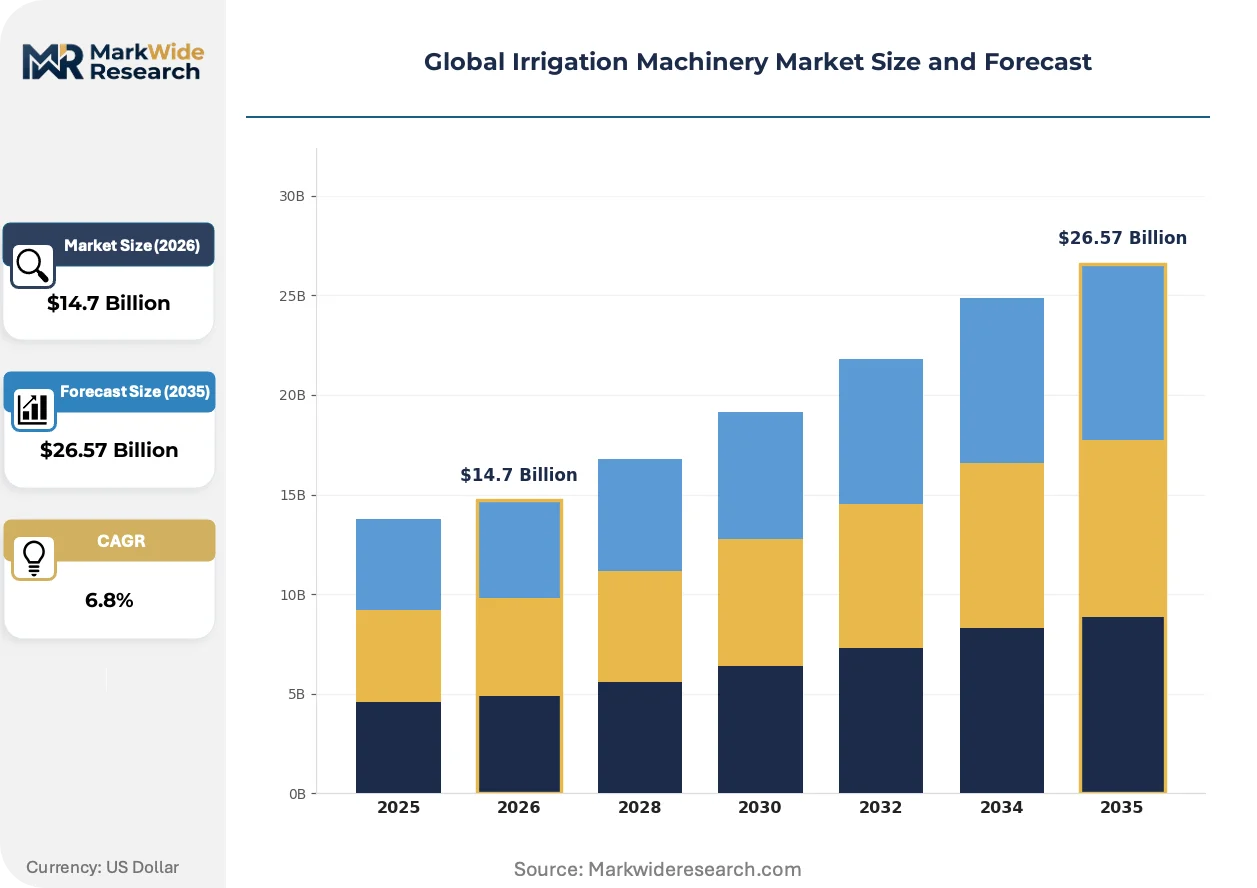
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation End User: Agricultural Farms, Golf Courses, Landscapers, Municipalities Technology: Mechanical Irrigation, Automated Systems, Remote Monitoring, Solar-Powered Irrigation Installation: On-site Installation, Pre-fabricated Systems, Retrofit Solutions, Turnkey Projects |
| Companies Covered | Valmont Industries, Hunter Industries, The Toro Company, Rivulis Irrigation, Lindsay Corporation, Netafim Ltd., Rain Bird Corporation, Nelson Irrigation Corporation, Jain Irrigation Systems Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Irrigation Machinery Market Strategic Shifts
Automation layers are compressing decision cycles in water application, collapsing the lag between soil-plant demand detection and valve response while redistributing value capture from hardware sales toward data services.
Variable-rate irrigation (VRI) technology is collapsing the historical trade-off between field-scale mechanization and zone-specific water management. VRI systems modulate nozzle flow across pivot spans based on prescription maps derived from electroconductivity surveys and yield monitor histories. Large-scale corn and soybean operators in Nebraska and Iowa are retrofitting existing center-pivot infrastructure with VRI packages at replacement cycles rather than full system overhaul. The technology is collapsing per-acre water application variance, enabling deficit irrigation protocols that were previously executable only on manually-managed drip blocks.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to transition center-pivot and lateral move systems away from high-global-warming-potential refrigerants in climate-controlled greenhouse applications. The industrial consequence is accelerated R&D spending on alternative cooling architectures for integrated HVAC-irrigation systems in protected cultivation. Dutch greenhouse operators and Spanish Almería cluster growers face the most immediate compliance timelines, with equipment certification deadlines concentrating procurement decisions into 2025-2027 windows.
Service unbundling is fragmenting traditional dealer revenue models. Aftermarket parts and remote diagnostics subscriptions are separating from original equipment sales as farm operators source filtration media, emitter replacement kits, and telemetry modules through direct channels. Australian broadacre cooperatives and Brazilian Cerrado farming syndicates are piloting subscription-based scheduling advisory that displaces per-call technician visits. The shift is most visible in Murray-Darling Basin cotton operations and Mato Grosso soybean estates where scale justifies in-house agronomy teams purchasing decision-support software independent of hardware bundles.
Global Irrigation Machinery Market Segmentation
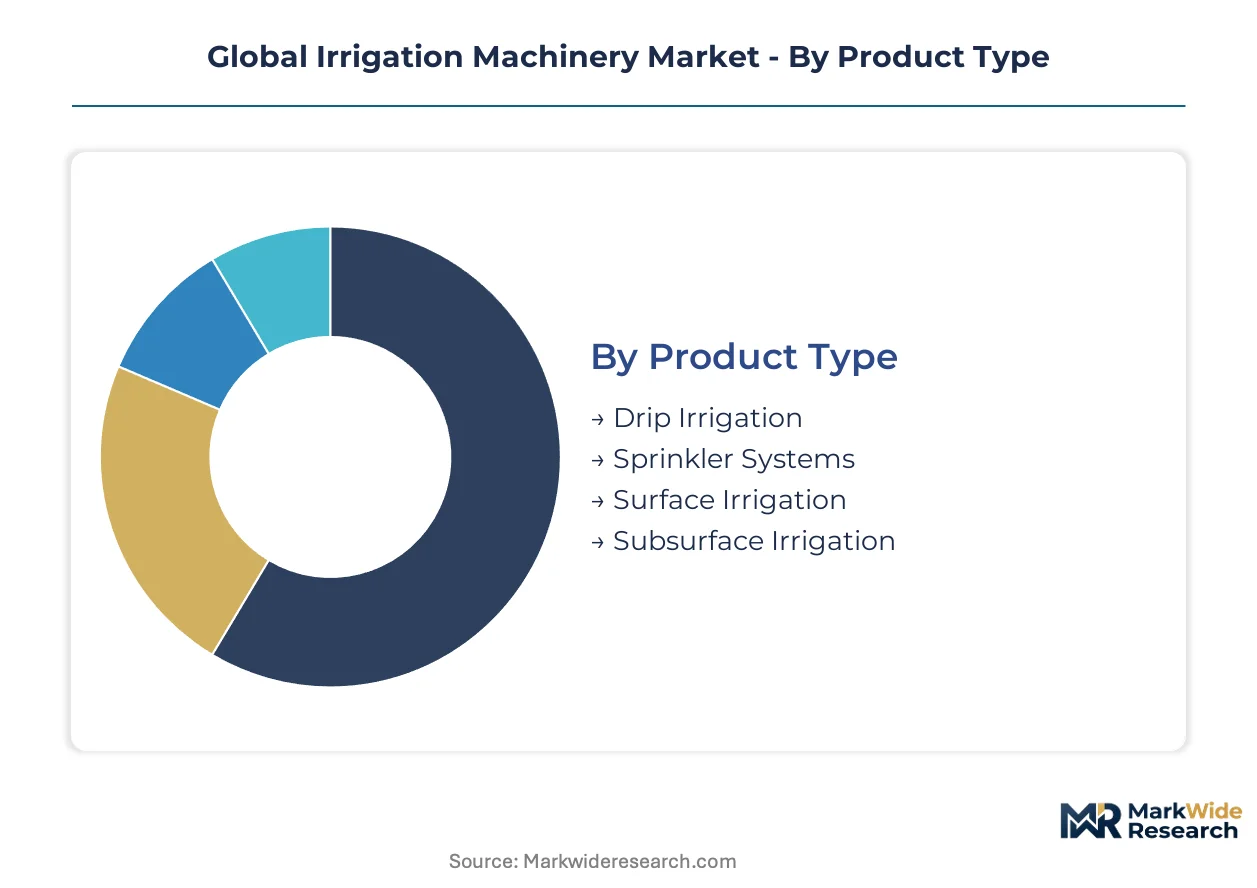
Segmentation in irrigation machinery determines service contract structures, spare parts stocking density, and technician deployment models. Equipment complexity varies dramatically across product categories, creating divergent aftermarket revenue profiles and customer retention mechanics.
Product Type:
After-sales intensity peaks with drip irrigation due to emitter replacement cycles and filtration maintenance, while center-pivot systems generate lower-frequency but higher-value service events.
- Drip Irrigation:Polymer emitter networks deliver water at root-zone pressure through labyrinth-flow channels. Demand concentrates in California specialty crop operations facing SGMA groundwater extraction limits. Clogging susceptibility from biological precipitates drives recurring filtration media sales and seasonal technician visits.
- Sprinkler Systems:Center-pivot and lateral-move assemblies apply water through overhead nozzle distribution. Australian Murray-Darling Basin broadacre operators dominate procurement as deficit irrigation protocols replace flood methods. VRI retrofits on existing infrastructure extend replacement cycles while lifting water productivity metrics.
- Surface Irrigation:Gravity-fed flood and furrow methods remain prevalent in rice cultivation and developing smallholdings with limited capital access.
- Subsurface Irrigation:Buried drip lines or porous tubing minimize evaporative losses in high-value turf and greenhouse applications.
Drip irrigation holds the largest share; momentum sits with sprinkler systems as VRI retrofits accelerate.
End User:
Customer type shapes procurement channel preference and financing structure, with agricultural cooperatives negotiating volume terms distinct from municipal tender processes.
- Agricultural Farms:Row-crop and specialty operations span Nebraska corn-soy rotations to Brazilian Cerrado cotton estates. Indian smallholder cooperatives in Maharashtra aggregate fragmented demand for solar pump and drip kit procurement.
- Golf Courses:Turf managers prioritize distribution uniformity and chemigation compatibility for fertility integration. EPA backflow prevention certification requirements extend commissioning timelines and documentation burdens.
- Landscapers:Commercial grounds maintenance contractors favor portable micro-sprinkler and drip solutions for irregular planting geometries.
- Municipalities:Parks departments and roadside vegetation programs specify durable above-ground systems with vandal-resistant components.
Agricultural farms command the dominant revenue pool; golf courses exhibit the steepest expansion trajectory for precision application technology.
Technology:
Technology tier determines capital intensity and operational skill requirements, with automated systems demanding telemetry integration expertise absent from mechanical equivalents.
- Mechanical Irrigation:Timer-based valves and manual pump controls persist in cost-sensitive smallholdings and legacy installations.
- Automated Systems:Soil moisture sensors trigger variable-rate valve actuation through programmable logic controllers. Spanish Almería greenhouse clusters and Dutch protected cultivation operations lead adoption as EU Farm to Fork water-efficiency benchmarks tighten.
- Remote Monitoring:Satellite-linked telemetry transmits flow rate and pressure data to centralized dashboards. Australian station managers and Brazilian farming syndicates pilot subscription-based advisory displacing per-call technician visits.
- Solar-Powered Irrigation:Photovoltaic pump drives eliminate diesel dependency in remote Indian smallholdings and off-grid Australian pastoral operations.
Mechanical irrigation retains the installed base majority; automated systems are climbing the fastest as telemetry-to-actuator convergence accelerates.
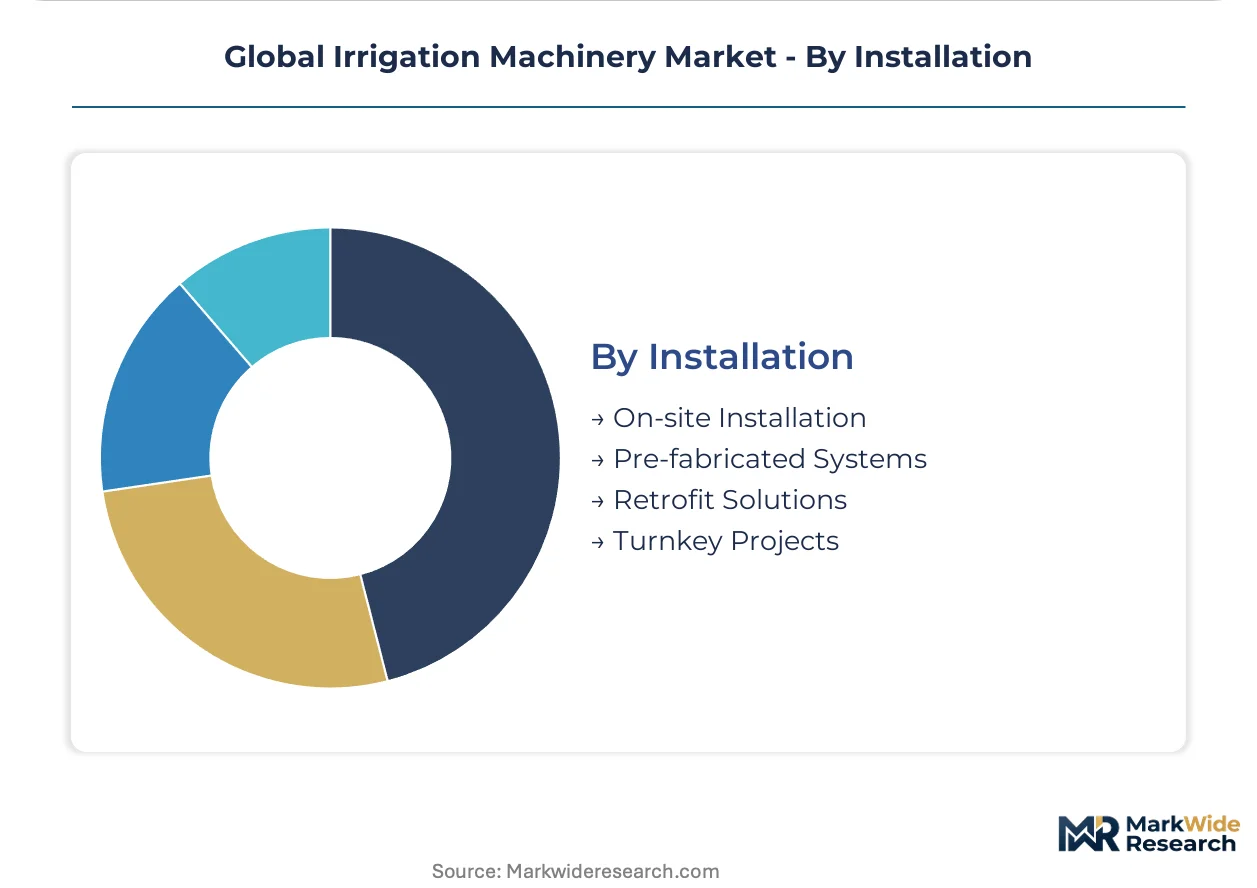
Installation:
Installation modality affects project margin structure and customer capital commitment phasing, with turnkey contracts absorbing design risk distinct from component-only supply.
- On-site Installation:Custom field assembly of center-pivot towers and lateral-move tracks accommodates variable topography. Hydraulic engineering scarcity in irrigation districts delays project completion and inflates labor costs.
- Pre-fabricated Systems:Factory-assembled skid-mounted pump stations and filtration trains reduce commissioning time for standardized broadacre applications.
- Retrofit Solutions:VRI packages and automation upgrades extend existing infrastructure service life. Nebraska and Iowa operators retrofit center-pivots at replacement cycles rather than full system overhaul.
- Turnkey Projects:Design-build contracts bundle engineering, procurement, and construction for large-scale district irrigation schemes.
On-site installation represents the largest service revenue category; retrofit solutions are gaining share fastest as capital constraints prolong replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Australian broadacre cooperatives and Brazilian farming syndicates, while Indian smallholder aggregation platforms compress margins through volume negotiations. Regulatory stringency in California and the EU reshapes procurement timelines, accelerating capital deployment in telemetry-integrated systems.
United States
Nebraska and Iowa corn-soy operators retrofit center-pivot infrastructure with variable-rate packages at replacement cycles rather than full system overhaul. EPA chemigation backflow prevention standards under the Clean Water Act extend commissioning timelines and inflate compliance documentation costs. The Central Valley specialty crop belt accelerates precision system retrofits as SGMA groundwater extraction limits tighten.
Australia
Murray-Darling Basin cotton estates and broadacre wheat operations replace flood-based methods with deficit irrigation protocols and automated scheduling tools. The country's national agricultural regulator enforces water trading compliance frameworks that reshape total cost-of-ownership calculations for mechanized investments. Queensland and New South Wales pastoral stations pilot solar-powered pump drives to eliminate diesel dependency in remote locations.
India
Maharashtra and Gujarat smallholder cooperatives aggregate fragmented demand to negotiate volume pricing on drip kits and solar pumps. BIS enforces emitter discharge uniformity standards under IS 13487, pressuring mid-tier manufacturers without captive polymer supply. Karnataka and Tamil Nadu farming clusters expand photovoltaic pump installations where grid extension costs previously blocked mechanization.
Brazil
Mato Grosso soybean estates and Cerrado cotton operations anchor procurement of large-scale center-pivot and lateral-move assemblies. ANVISA agricultural chemical application standards intersect with irrigation system design, influencing chemigation compatibility requirements. Farming syndicates in Goiás and Bahia pilot subscription-based scheduling advisory displacing per-call technician visits.
Spain
Almería greenhouse clusters and protected cultivation operations lead automated system adoption as EU Farm to Fork water-efficiency benchmarks tighten. The EU F-Gas Regulation phase-down schedules pressure manufacturers to transition climate-controlled greenhouse applications away from high-global-warming-potential refrigerants. Valencia and Murcia vegetable producers integrate soil moisture telemetry with variable-rate valve actuation through programmable logic controllers.
Global Irrigation Machinery Market Competitive Environment
Full-system integrators and component specialists split the market along capital intensity and service bundling lines. The vendor base concentrates around established pivot manufacturers with captive dealer networks and emerging precision agriculture technology providers. Two strategic archetypes dominate: vertically integrated OEMs controlling aftermarket parts revenue through service touchpoints, and modular technology suppliers licensing telemetry-to-actuator convergence platforms. Competitive moves center on retrofit solution portfolios that extend existing infrastructure service life, and subscription revenue streams displacing per-call technician visits.
Among North American full-system integrators, Valmont Industries and Lindsay Corporation exemplify the vertically integrated archetype with established dealer footprints sustaining aftermarket revenue. Netafim Ltd. occupies a position within the precision component tier, representing Israeli-origin drip emitter and filtration expertise. Jain Irrigation Systems Limited anchors the Indian subcontinent's cooperative purchasing channel, exemplifying volume-scale supply to fragmented smallholder demand.
| Leading Market Players |
|---|
| Valmont Industries |
| Hunter Industries |
| The Toro Company |
| Rivulis Irrigation |
| Lindsay Corporation |
| Netafim Ltd. |
| Rain Bird Corporation |
| Nelson Irrigation Corporation |
| Jain Irrigation Systems Limited |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese polymer extrusion facilities is compressing emitter manufacturing margins while simultaneously enabling aggressive supplier financing programs that extend payment terms for Indian and Southeast Asian distributors. This utilization dynamic forces mid-tier machinery OEMs to absorb cost volatility or cede share to vertically integrated competitors with captive resin supply.
Pricing Analysis
Configured-to-order center-pivot systems command 35-50 percent premiums over standard span packages due to topography-specific tower spacing and VRI nozzle configurations. Project-based contracting dominates large-scale installations, with price differentiation resting on CE certification tier and after-sales service bundling. Cost compression in drip line segments is intensifying as polyethylene resin volatility squeezes manufacturers without backward integration into polymer production. Smallholder cooperatives in Maharashtra exhibit the highest price sensitivity, while Australian broadacre syndicates prioritize distribution uniformity metrics over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard for tier-one dealers purchasing from Israeli and Italian precision component suppliers. Manufacturing concentrates in China for polymer emitters, Israel for filtration technology, and the United States for center-pivot structural steel. Raw material dependencies rest on high-density polyethylene, ethylene-vinyl acetate resins, and galvanized steel tubing. Single-source vulnerability in precision emitter nozzles creates exposure when geopolitical friction disrupts Israeli export logistics. Distribution runs through dealer-direct networks in North America and cooperative purchasing platforms in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydraulic engineering expertise for pressure-compensating network design is scarce across irrigation districts, creating persistent bottlenecks that constrain project completion timelines and inflate labor costs for precision system deployments.
For Market Incumbents: Pre-empt margin erosion in drip line segments by securing captive polymer supply through backward integration or long-term offtake agreements with Saudi and Qatari resin producers. Defend dealer network control against direct-channel encroachment by embedding telemetry subscription services into hardware bundles, raising switching costs for Australian and Brazilian farming syndicates. For New Entrants and Emerging Players: Pursue solar-powered irrigation retrofits in remote Queensland pastoral stations and Karnataka smallholdings where grid extension economics previously blocked mechanization. Target Maharashtra cooperative purchasing platforms with modular drip kit configurations that aggregate fragmented demand into volume pricing tiers. Lead with subscription-based scheduling advisory to bypass capital-intensive dealer infrastructure requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telemetry-to-actuator convergence platforms as software margins displace hardware-dependent revenue models. Long-term viability favors acquisition targets with established satellite data partnerships and recurring revenue streams from automated scheduling algorithms. Watch for inflection signals in EPA enforcement intensity around chemigation backflow certification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive resin access insulates margins from ethylene-vinyl acetate price volatility affecting mid-tier manufacturers. |
| Telemetry-to-Actuator Platform Integration | Subscription revenue streams from soil moisture-linked valve control displace per-call technician visits in Australian cotton operations. |
| Solar Pump Drive Deployment | Photovoltaic installations eliminate diesel dependency for Indian smallholders and remote Australian stations facing grid extension barriers. |
| CE Certification Investment | EU Farm to Fork water-efficiency benchmarks create preferential market access for documented distribution uniformity performance. |
| Cooperative Purchasing Channel Expansion | Maharashtra and Gujarat smallholder aggregation platforms consolidate fragmented demand to negotiate volume pricing on drip infrastructure. |
Study Parameters
The analysis maps center-pivot, drip irrigation, and solar-powered pump segments, each validated through irrigation district engineers, cooperative purchasing managers, and aftermarket service directors. Primary interviews with OEM procurement leads and dealer network operators combined with secondary validation from EPA enforcement databases, BIS certification registries, and EU F-Gas Regulation implementation timelines. Customs records from Indian DGFT and Australian water trading compliance frameworks provided import volume cross-checks. Bottom-up equipment shipment tallies and top-down agricultural water consumption estimates were triangulated to reconcile market sizing.
Assumptions held fixed include SGMA groundwater extraction limit enforcement intensity, EU Farm to Fork water-efficiency benchmark adoption curves, and photovoltaic cost decline trajectories. Variables included polymer resin price volatility bands, diesel-to-solar fuel switching elasticities, and telemetry subscription renewal rates. The projection framework modeled product type, technology tier, installation modality, and end-user segment dimensions across the analysis window. CAGRs were derived from logistic diffusion curves fitted to precision irrigation adoption patterns in California and Spain, with scenario weighting for regulatory acceleration or delay.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, interest rate environments affecting farm capital expenditure cycles, or energy pricing reform trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market