
 Grass Trimmer Market | 2026-2036
Grass Trimmer Market Size, Share, and Industry Trends Forecast 2026-2036
Grass Trimmer Market Analysis
Chinese battery pack manufacturers are broadening output for cordless outdoor power equipment, creating downstream availability for grass trimmer assemblers worldwide. Stihl leverages in-house engine production to sustain premium positioning in petrol-powered professional units. Husqvarna Group anchors its portfolio with robotic and battery platforms across European retail channels. Greenworks competes aggressively on lithium-ion price points through direct-to-consumer distribution in North America.
A grass trimmer is a handheld or autonomous motorized device utilizing a rotating monofilament line, plastic blade, or metal blade to cut grass and light vegetation at precise heights, typically operating at motor speeds between 6,000 and 12,000 RPM for clean shearing action. Cordless units now dominate residential replacement purchases as lithium-ion energy density improves and runtime extends beyond thirty minutes per charge. Gas-powered systems retain structural importance among commercial landscapers who prioritize continuous operation and high-torque cutting through dense brush. Robotic trimmers occupy an emerging niche in municipal and golf course maintenance where labor scarcity pushes automation adoption.
EPA emissions standards in the United States and Ecodesign regulations under the EU Green Deal constrain two-stroke engine sales, redirecting manufacturer R&D toward electrified platforms. China's GB standards and MIIT directives on battery safety and recycling shape component sourcing requirements for cordless trimmer exports. Stakeholders must monitor regulatory phase-out timelines for internal combustion engines while calibrating inventory and platform investments across power source categories.
Market Dynamics
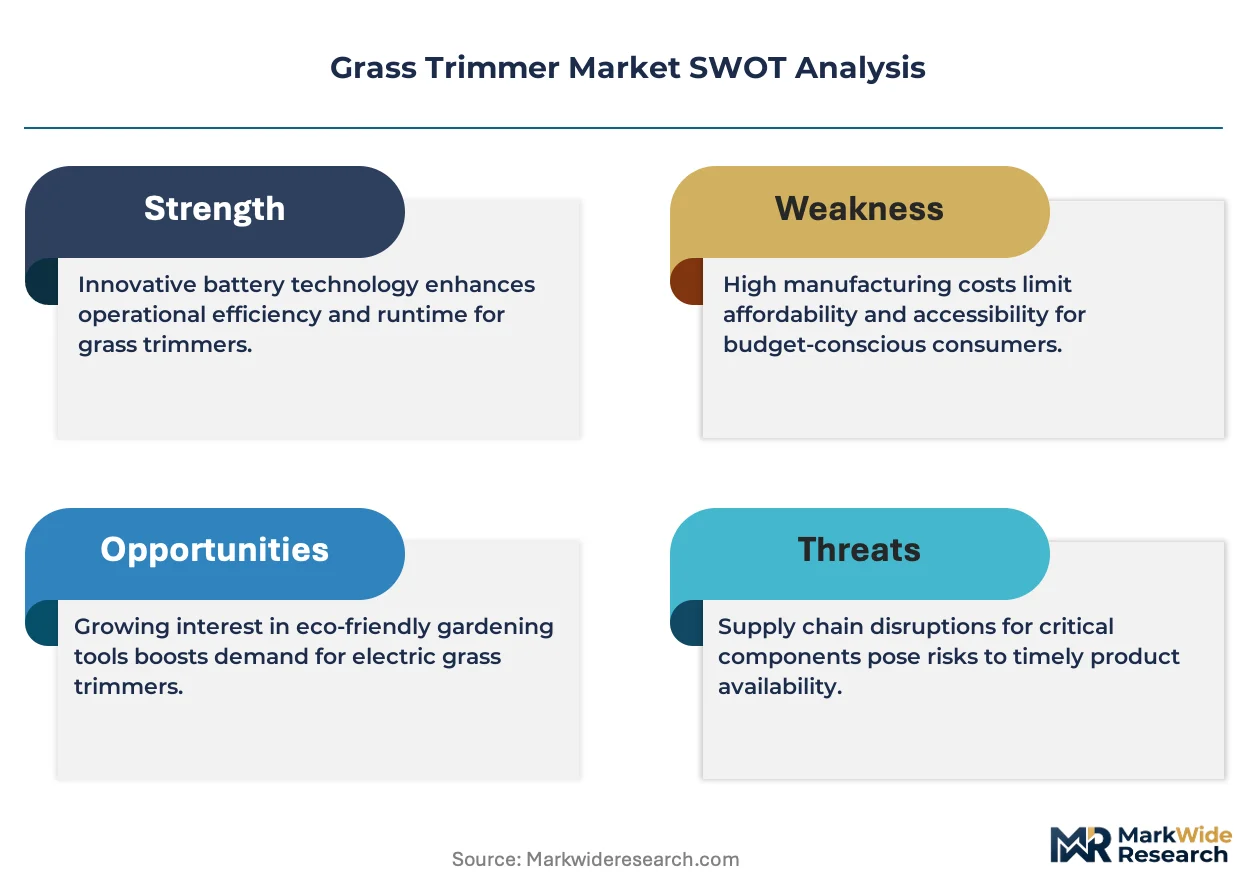
Battery chemistry breakthroughs and Ecodesign regulatory deadlines are forcing simultaneous platform transitions across petrol-dependent manufacturers, compressing development cycles while creating first-mover advantages for electrified portfolios.
Growth Catalysts
- EU Ecodesign Regulation:Mandatory efficiency standards and emissions limits on two-stroke engines are accelerating manufacturer investment in brushless motor platforms and lithium-ion integration.
- Landscaping services expansion:Commercial grounds maintenance contract volume is multiplying across municipal parks, corporate campuses, and golf facilities, sustaining professional-grade equipment replacement cycles.
- Lithium-ion energy density improvements:Cell manufacturers in China are scaling 21700 and 26650 formats specifically for outdoor power equipment, extending cordless runtime beyond thirty minutes per charge.
Market Restraints
- Raw material volatility:Lithium carbonate and cobalt price swings inflate battery pack costs, compressing assembler margins on mid-tier cordless units.
- Supply concentration risk:Ningbo and Suzhou manufacturing clusters control over seventy percent of global brushless motor output, creating single-source vulnerability for European and North American brands.
- Technical limitation:Battery thermal management constraints prevent cordless systems from matching petrol torque output for dense brush clearing applications.
Strategic Opportunities
- Robotic automation:Autonomous perimeter-trimming systems for golf courses and municipal greenways address acute labor scarcity in Germany and the United States.
- Direct-to-consumer channels:E-commerce platforms and brand-owned digital storefronts bypass traditional retail markups, capturing margin and customer data simultaneously.
- IRA clean energy incentives:United States tax credits for battery-powered commercial equipment reduce effective procurement costs for landscaping fleet operators.
Industry Challenges
- Skill gap in mechatronics:Servicing integrated battery management systems and brushless controllers requires technician training programs that OEMs must build from minimal existing infrastructure.
- Certification timeline compression:Parallel UL 2595 battery safety and CE machinery directive approvals demand synchronized testing resources, delaying regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grass Trimmer Market |
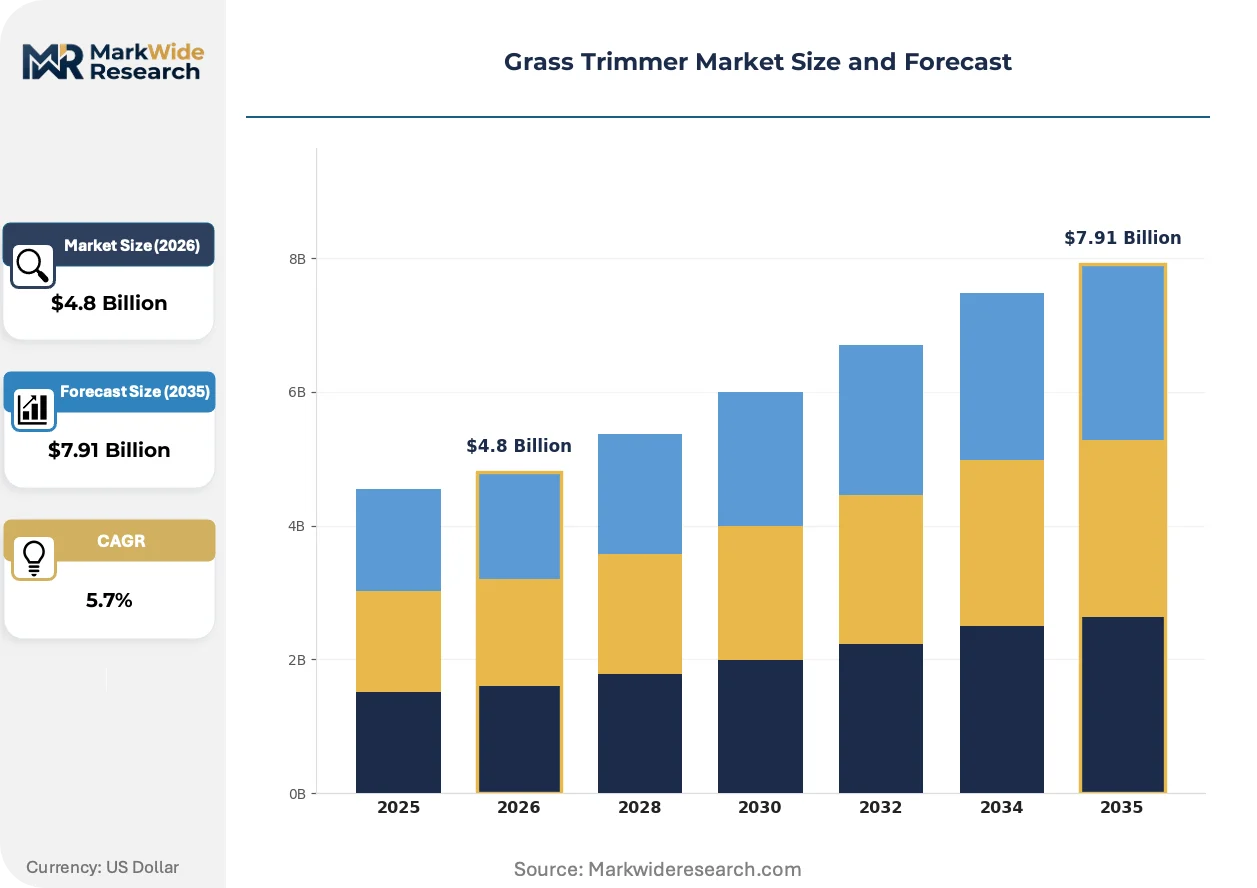
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Gas-Powered, Robotic End User: Homeowners, Landscapers, Groundskeepers, Commercial Users Cutting Width: 10 inches, 12 inches, 14 inches, 16 inches Power Source: Electric, Petrol, Battery, Hybrid |
| Companies Covered | Stihl, Husqvarna Group, DeWalt, Stanley Black & Decker, The Toro Company, Echo, Makita, Greenworks, EGO Power+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grass Trimmer Market Emerging Trajectories
Electrification is rewriting competitive positioning across power source categories, while automation and regulatory compliance are creating divergent R&D investment paths between residential and professional segments.
Brushless DC motor platforms paired with intelligent battery management systems are automating torque modulation and thermal protection previously handled by mechanical governors in petrol units. Municipal maintenance departments in the Netherlands and Denmark are piloting these systems for noise-sensitive urban corridors. The technology is automating operator skill requirements while compressing training timelines for seasonal workforce expansion.
REACH chemical restrictions and EU Green Deal implementation timelines are phasing out chromium-plated steel components and specific solvent-based coatings in trimmer head assemblies. Manufacturers serving European retail channels are accelerating aluminum and polymer substitutions to maintain market access. Professional-grade petrol units face the steepest redesign burden, as these segments historically prioritized metal durability over material compliance.
Commercial landscaping contractors are consolidating vendor relationships and demanding fleet management integration, unbundling equipment purchases from traditional dealer service bundles. Large regional operators in Texas and Florida are negotiating direct volume agreements with manufacturers, bypassing independent distributor networks. This concentration is most visible in the United States, where private equity-backed landscaping roll-ups are standardizing equipment specifications across acquired locations.
Grass Trimmer Market Segmentation
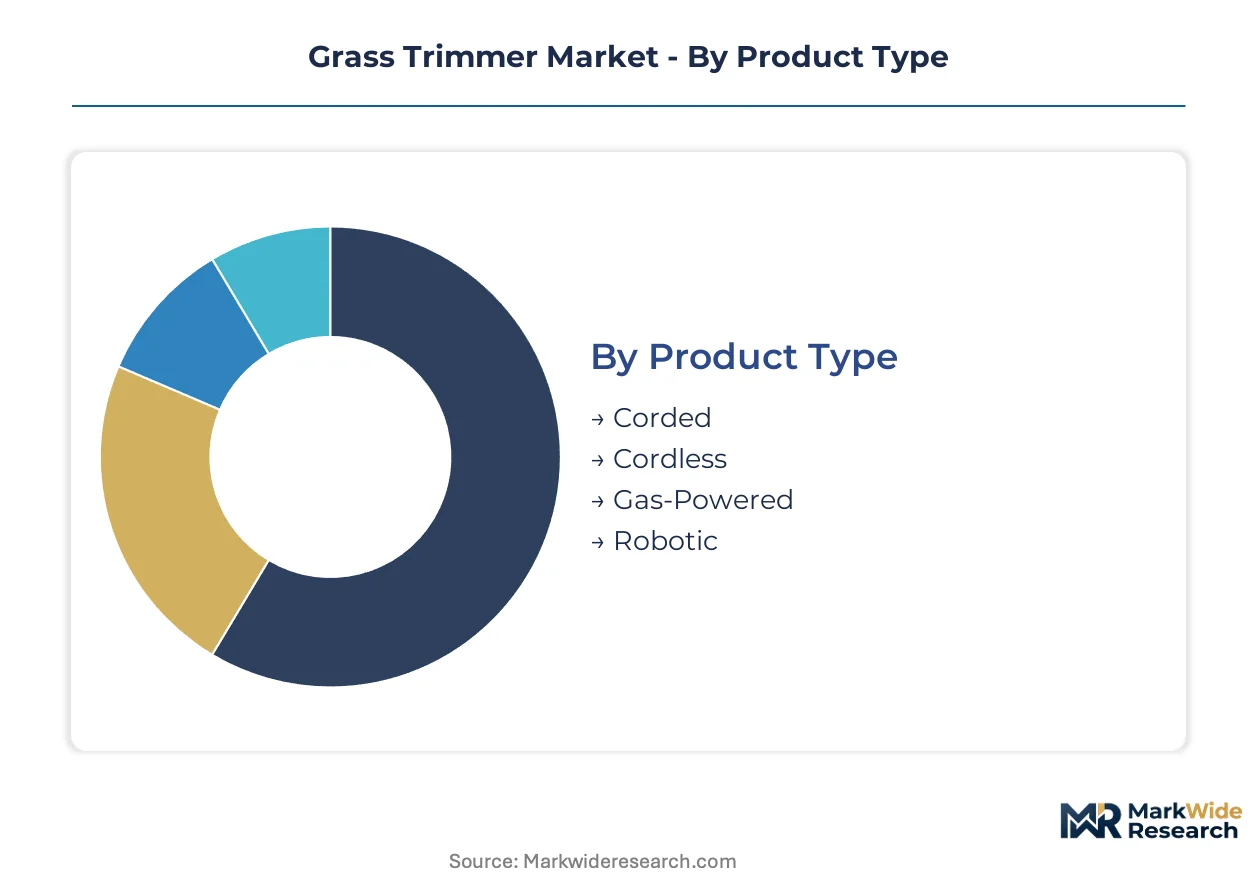
Grass trimmer purchasing decisions split across power platform preferences, professional intensity of use, and physical cutting specifications. Manufacturers calibrate motor architecture, battery chemistry, and blade geometry to match distinct performance requirements across these axes.
Product Type:
Cordless lithium-ion platforms now command residential replacement cycles as energy density improvements extend runtime past thirty minutes per charge.
- Corded:Continuous AC power delivery suits small urban gardens and fixed-perimeter maintenance where outlet proximity eliminates runtime anxiety. Demand concentrates in German apartment complexes and Japanese suburban plots where lot sizes rarely exceed five hundred square meters.
- Cordless:Brushless DC motors paired with 21700-format battery cells deliver torque curves matching entry-level petrol units. Landscapers in Texas and Florida are standardizing cordless fleets for noise-restricted municipal contracts and corporate campus maintenance.
- Gas-Powered:Two-stroke engines retain structural importance for dense brush clearing and continuous commercial operation. EPA emissions constraints and EU Ecodesign deadlines are compressing development timelines for compliant small-displacement powerheads.
- Robotic:Autonomous perimeter systems with RTK-GPS navigation address labor scarcity in golf course rough management and municipal greenway maintenance. Pilot deployments are active in Netherlands municipal corridors and Danish urban parks.
Mature deployment sits with gas-powered professional units. Newer deployment is concentrated in robotic systems for institutional maintenance.
End User:
Professional intensity of use dictates motor thermal management requirements and service interval expectations.
- Homeowners:Intermittent seasonal use favors lightweight cordless platforms with integrated battery storage. North American big-box retail channels capture this volume through private-label and direct-to-consumer brand placement.
- Landscapers:Daily runtime demands exceeding four hours sustain petrol platform dominance for high-torque applications. Fleet standardization across private equity-backed roll-ups in the United States is consolidating vendor relationships and unbundling dealer service agreements.
- Groundskeepers:Institutional maintenance crews at universities and hospital campuses prioritize noise compliance and emissions reduction. Battery platforms with rapid-swap battery systems are climbing the fastest in this segment.
- Commercial Users:Corporate facilities management and retail property operators specify equipment for liability and brand consistency. Procurement runs through national maintenance service contracts rather than direct equipment purchase.
Established volume sits with homeowner replacement purchases. Steepest expansion trajectory is visible in groundskeeper electrification mandates.
Cutting Width:
Swath diameter directly determines productivity metrics and operator fatigue profiles across vegetation density gradients.
- 10 inches:Compact head geometry suits precision edging and confined-space maintenance around landscape features. Japanese garden specialists and European cemetery maintenance crews specify this format for manicured aesthetics.
- 12 inches:Mid-range swath balances residential lawn efficiency with maneuverability in irregular terrain. This specification anchors cordless platform standard configurations for North American consumer retail.
- 14 inches:Professional-grade cutting diameter accelerates open-area productivity for commercial crews. Landscapers in Australian and South African markets favor this format for expansive turf maintenance with lower operator density.
- 16 inches:Maximum swath diameter demands reinforced drive systems and elevated power output. Specialized brush-clearing contractors deploy these units for right-of-way maintenance and firebreak vegetation management.
Volume concentration rests with 12-inch residential specifications. Performance differentiation is migrating toward 14-inch professional cordless platforms.
Power Source:
Energy architecture determines regulatory compliance pathways and total cost of ownership calculations across use intensities.
- Electric:AC mains connection eliminates battery degradation concerns and delivers consistent power output. Fixed-installation municipal trimmers in European pedestrian zones utilize this format for unlimited runtime in noise-sensitive corridors.
- Petrol:Liquid fuel energy density sustains all-day operation without refueling infrastructure dependence. Ecodesign Regulation phase-out timelines are forcing manufacturer R&D redirection toward electrified alternatives.
- Battery:Modular cell architectures enable capacity scaling from 2Ah homeowner packs to 12Ah professional configurations. Chinese cell manufacturers in Ningbo and Suzhou are scaling 21700 and 26650 formats specifically for outdoor power equipment export.
- Hybrid:Dual-fuel flexibility addresses range anxiety in transitional fleet deployments. Experimental configurations are emerging for large-scale municipal maintenance where charging infrastructure remains incomplete.
Established infrastructure favors petrol distribution networks. Investment flow is concentrating in battery platform development and cell manufacturing capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate deposits in Chile's Atacama Desert and cobalt mining in the Democratic Republic of Congo feed battery supply chains that power cordless platform expansion across major demand centers.
United States
Residential lawn care culture sustains replacement cycles for cordless units, while commercial landscaping fleet operators in Texas and Florida standardize battery platforms for noise-restricted municipal contracts. EPA emissions standards constrain two-stroke engine sales, redirecting manufacturer R&D toward electrified alternatives. Manufacturing and distribution clusters concentrate in Midwest industrial corridors serving big-box retail channels.
Germany
Precision engineering traditions anchor professional-grade equipment demand from municipal maintenance departments and landscaping contractors. EU Ecodesign regulations under the Green Deal mandate efficiency standards and emissions limits on two-stroke engines, accelerating brushless motor platform investment. Industrial concentration sits in Baden-Württemberg and Bavaria, where component suppliers and final assemblers maintain integrated production networks.
China
Urban green space mandates in tier-one cities drive municipal procurement of battery-powered maintenance equipment. MIIT directives on battery safety and recycling shape component sourcing requirements for cordless trimmer exports. Manufacturing gravity centers on Ningbo and Suzhou, where brushless motor and battery pack output supplies assemblers worldwide.
Japan
Compact lot sizes and manicured garden aesthetics favor precision trimming equipment for residential and cemetery maintenance applications. METI efficiency standards and JIS certification requirements govern product safety and electromagnetic compatibility for domestic and export markets. Industrial activity clusters in the Chubu region around Nagoya, where precision motor and cutting head component specialists maintain supplier relationships.
Australia
Expansive turf maintenance requirements and lower operator density favor larger cutting diameter specifications for commercial crews. State-level environmental regulations in New South Wales and Victoria restrict petrol-powered equipment use in noise-sensitive urban corridors and national park buffer zones. Distribution and service infrastructure concentrates in Melbourne and Sydney industrial suburbs, with regional dealer networks extending into Queensland and Western Australia.
Grass Trimmer Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automation and direct-to-consumer channels. The market structure shows moderate consolidation around heritage power equipment brands with deep dealer networks, while battery-specialist entrants fragment the residential cordless segment. Three archetypes dominate: engine-heritage manufacturers pivoting to electrification, pure-play battery platform specialists, and Asian contract manufacturers scaling component supply. Competitive dynamics center on portfolio diversification into adjacent outdoor power categories and backward integration into battery cell and brushless motor production.
Among heritage engine manufacturers, Stihl and Husqvarna Group exemplify the transition archetype, leveraging established dealer service infrastructure while redirecting R&D toward brushless platforms. Greenworks occupies a position within the battery-native specialist tier, competing on lithium-ion price points through direct-to-consumer distribution. These three anchors illustrate divergent strategic paths: captive engine production versus outsourced cell manufacturing, professional dealer networks versus digital-first channels, and premium positioning versus aggressive price competition.
| Leading Market Players |
|---|
| Stihl |
| Husqvarna Group |
| DeWalt |
| Stanley Black & Decker |
| The Toro Company |
| Echo |
| Makita |
| Greenworks |
| EGO Power+ |
| Others |
Supply Flow & Price Mechanics
Private equity-backed landscaping roll-ups in the United States concentrate procurement volume, forcing manufacturers toward unbundled equipment pricing with separate service contracts. This buyer consolidation compresses margin capture for mid-tier cordless platforms while premium petrol units retain pricing power through captive dealer networks.
Pricing Analysis
Warranty and service bundling separates premium professional tiers from economy residential offerings, with Stihl and Husqvarna commanding fifteen to twenty percent price premiums through integrated dealer maintenance programs. Price differentiation rests on UL 2595 battery safety certification tier and brushless motor thermal management specifications. Cost compression in mid-tier cordless segments intensifies as Chinese cell manufacturers flood Ningbo and Suzhou export channels. Homeowners through big-box retail channels exhibit highest price sensitivity, while municipal groundskeepers prioritize total cost of ownership over upfront unit cost.
Supply Chain Analysis
Workforce availability constraints in Ningbo and Suzhou manufacturing clusters are elevating automation investment among brushless motor suppliers. Battery pack assembly draws from lithium carbonate deposits in Chile and cobalt mining in the Democratic Republic of Congo. Single-source vulnerability concentrates in 21700-format cell output from three dominant Chinese producers. Distribution runs through Midwest industrial corridors serving North American big-box retail, with parallel dealer networks handling professional-grade equipment in Germany and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive battery cell production and in-house brushless motor manufacturing determine margin sustainability. Players pursuing upstream control over 21700-format cell supply secure cost advantages against assembler-dependent competitors.
For Market Incumbents: Cement dealer service infrastructure loyalty through rapid-swap battery system standardization and proprietary fleet management software integration. Defend against Greenworks and EGO Power+ direct-to-consumer encroachment by locking municipal landscaping contracts into multi-year equipment replacement cycles with embedded service agreements.
For New Entrants and Emerging Players: Enter via robotic perimeter-trimming systems for golf course rough management in the Netherlands and Denmark, where labor scarcity exceeds equipment price sensitivity. Target groundskeeper electrification mandates at university and hospital campuses with noise-compliant battery platforms and rapid-swap architectures. Pursue e-commerce direct-to-consumer channels to bypass established dealer markups and capture customer data for predictive maintenance services.
For Investors and Strategic Acquirers: Distressed-cycle entries favor brushless motor specialists in Baden-Württemberg with ISO-certified thermal management IP and existing relationships with Stihl or Husqvarna supply chains. Long-term viability hinges on regulatory compliance engineering capabilities as EU Ecodesign deadlines compress petrol platform relevance. Watch EPA enforcement acceleration on small-displacement two-stroke emissions as inflection signal for electrified portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive 21700-format supply secures margin against raw material volatility from Chilean lithium and DRC cobalt. |
| Robotic Automation Platform Launch | RTK-GPS navigation systems address acute labor scarcity in German municipal maintenance and Danish urban parks. |
| Direct-to-Consumer Channel Expansion | Brand-owned digital storefronts bypass retail markups and capture usage data for predictive battery replacement services. |
| Fleet Management Software Integration | Private equity-backed landscaping roll-ups in Texas and Florida demand unified equipment tracking across acquired locations. |
| EU Ecodesign Compliance Certification | CE machinery directive alignment maintains market access as REACH chemical restrictions phase out chromium-plated components. |
Methodological Framework
Document review covered customs and trade data from Ningbo and Suzhou export channels, EPA emissions filings, and EU Ecodesign regulatory impact assessments, complemented by interviews with procurement directors at private equity-backed landscaping operators, aftermarket service heads at Midwest dealer networks, and brushless motor engineering leads in Baden-Württemberg. Secondary validation drew from SEC 10-K disclosures of Stanley Black & Decker and The Toro Company, MIIT battery safety directives, and UL 2595 certification databases. Bottom-up segment sizing triangulated against top-down manufacturer shipment estimates across power source categories.
Unit shipment and revenue estimates emerged from integrated modeling across the projection horizon, with segmentation dimensions spanning power platform architecture, end-user intensity tier, cutting width specification, and regional regulatory cluster. CAGRs derived from historical replacement cycle analysis calibrated to lithium-ion energy density improvement curves and Ecodesign implementation timelines. Industry-specific inputs included municipal procurement budget flows from Netherlands and Denmark pilot programs, and landscaping fleet standardization patterns across Texas and Florida roll-ups.
Revisions become necessary when EPA enforcement acceleration on two-stroke emissions, sudden lithium carbonate price spikes from Atacama supply disruptions, or EU Green Deal timeline compression materialize beyond baseline assumptions. Forecasts reflect documented regulatory phase-out schedules and cell manufacturer capacity expansion announcements. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market