
 Smart Irrigation Market | 2026-2036
Smart Irrigation Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Irrigation Market Intelligence
Aftermarket service revenue is fragmenting across hardware vendors and third-party analytics platforms. Netafim leverages its drip irrigation heritage to extend into subscription-based soil monitoring services. Lindsay Corporation anchors its position through manufacturing scale in mechanized pivot systems. Rachio competes in the residential controller segment with cloud-native scheduling algorithms.
Smart irrigation encompasses sensor-actuator networks that apply water based on real-time soil volumetric water content, evapotranspiration rates, and weather forecast integration, primarily reducing agricultural water consumption while maintaining crop yield targets. Drip irrigation systems and weather-based controllers capture the dominant margin pools as established hardware categories with proven payback periods. IoT-based solutions and AI-driven machine learning platforms represent the fastest-expanding segments, though cloud computing infrastructure underpins their deployment economics across greenhouse and orchard applications.
The EPA enforces water-efficiency standards under the WaterSense program, while the EU Green Deal's Farm to Fork strategy imposes binding agricultural sustainability targets that mandate precision water management. California's State Water Resources Control Board operates the most restrictive agricultural water allocation regime in the United States, directly conditioning market access on documented conservation technology adoption. Stakeholders must weigh capital deployment timing against the accelerating regulatory compliance deadlines that will eventually eliminate conventional timer-based systems from subsidized procurement programs.
Market Dynamics
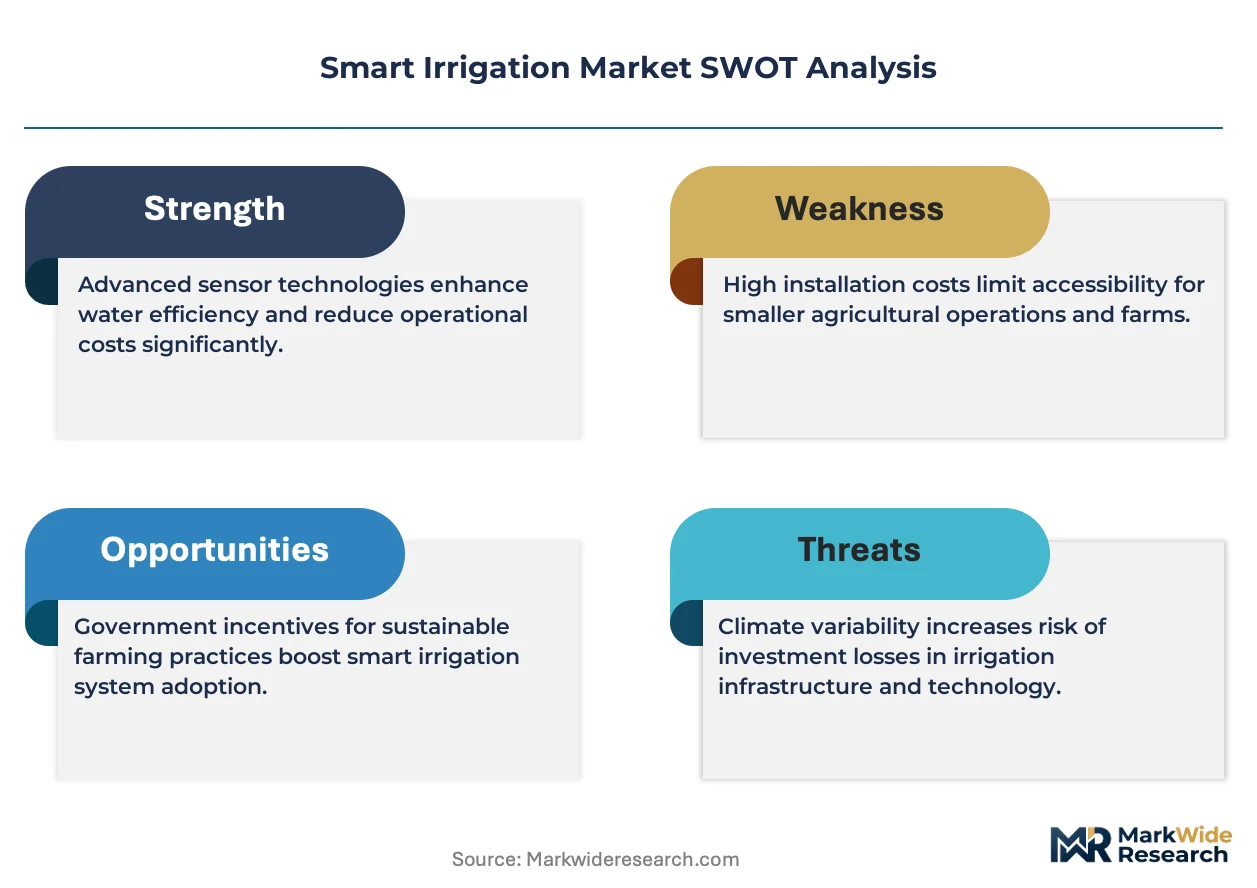
Water scarcity mandates from California's State Water Resources Control Board are forcing capital reallocation toward sensor-actuator networks, eliminating conventional timer-based systems from subsidized procurement programs and compressing payback period requirements for precision agriculture investments.
Growth Catalysts
- EPA WaterSense Standards:The program's efficiency certification requirements drive replacement demand for outdated controllers across agricultural and residential installations, with documented water savings now mandatory for rebate eligibility.
- Soil Volumetric Sensors:Real-time moisture monitoring hardware enables variable-rate irrigation scheduling that maintains crop yield targets while reducing applied water volumes in drought-stressed growing regions.
- Central Valley Procurement Concentration:California's agricultural water allocation restrictions have concentrated North American demand in this corridor, where precision technology adoption rates exceed national averages by substantial margins.
Market Restraints
- Semiconductor Supply Concentration:IoT sensor production depends on concentrated Asian foundry capacity, exposing hardware vendors to input cost volatility and extended lead times for microcontroller components.
- Cellular Connectivity Gaps:Rural agricultural zones lack reliable LTE infrastructure, degrading real-time data transmission from remote field sensors to cloud analytics platforms.
- CapEx Intensity for Smallholders:Drip irrigation retrofits and weather station installations require upfront capital beyond the financing capacity of sub-500 acre farming operations without subsidy support.
Strategic Opportunities
- EU Green Deal Farm to Fork Mandates:Binding agricultural sustainability targets create compliance-driven demand across member states for documented precision water management systems with audit trails.
- AI-ML Convergence with Edge Computing:On-device inference reduces cloud dependency and latency, enabling autonomous valve actuation decisions without continuous connectivity in remote orchard applications.
- Third-Party Analytics Platforms:Hardware-agnostic software subscriptions offer recurring revenue models that decouple vendor economics from one-time controller sales and capture ongoing data monetization value.
Industry Challenges
- Agronomy-Data Science Integration:Effective deployment requires personnel capable of interpreting soil science alongside machine learning outputs, a skill combination scarce in both agricultural extension services and technology vendors.
- Legacy Pivot System Interoperability:Mechanized irrigation infrastructure from prior decades lacks standardized communication protocols, forcing costly gateway installations or complete hardware replacement for smart retrofit compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Irrigation Market |
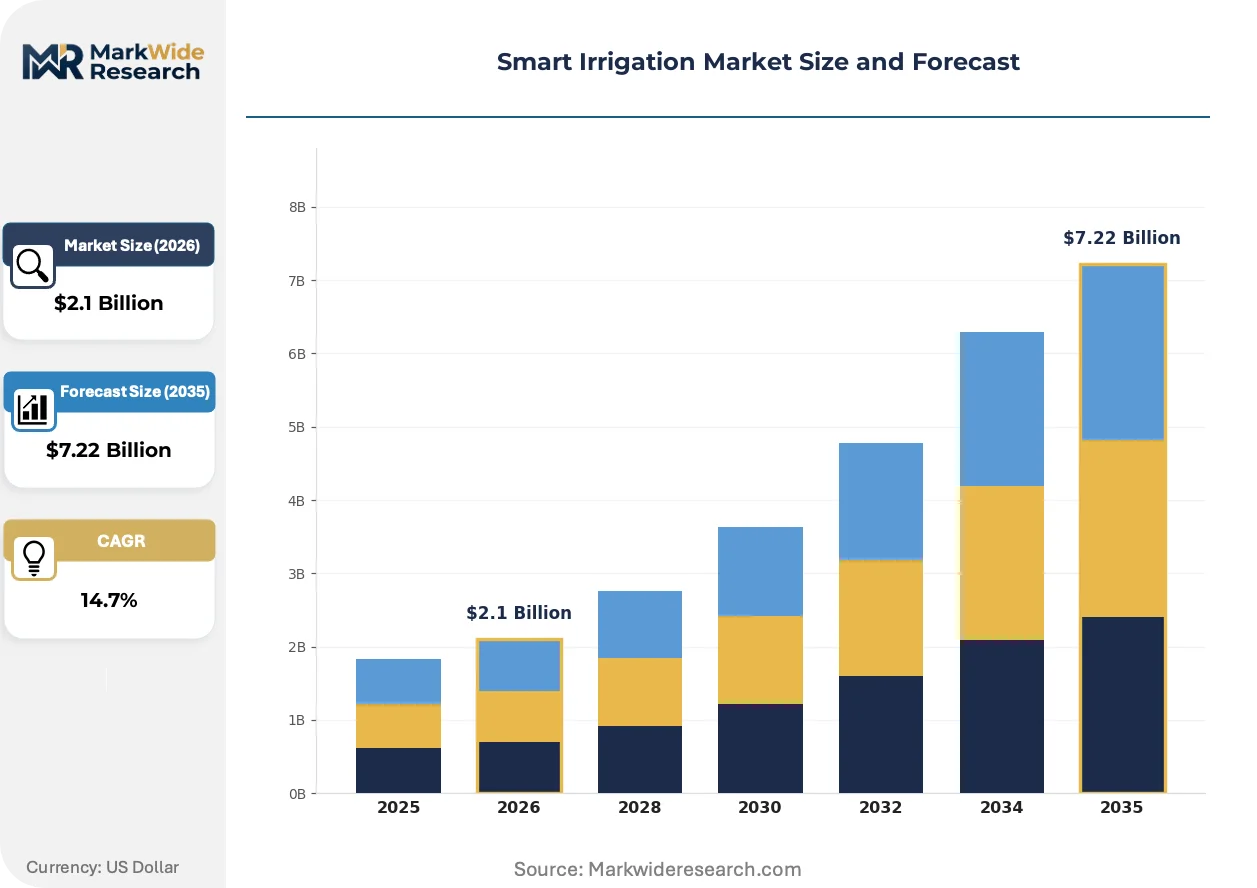
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.22 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
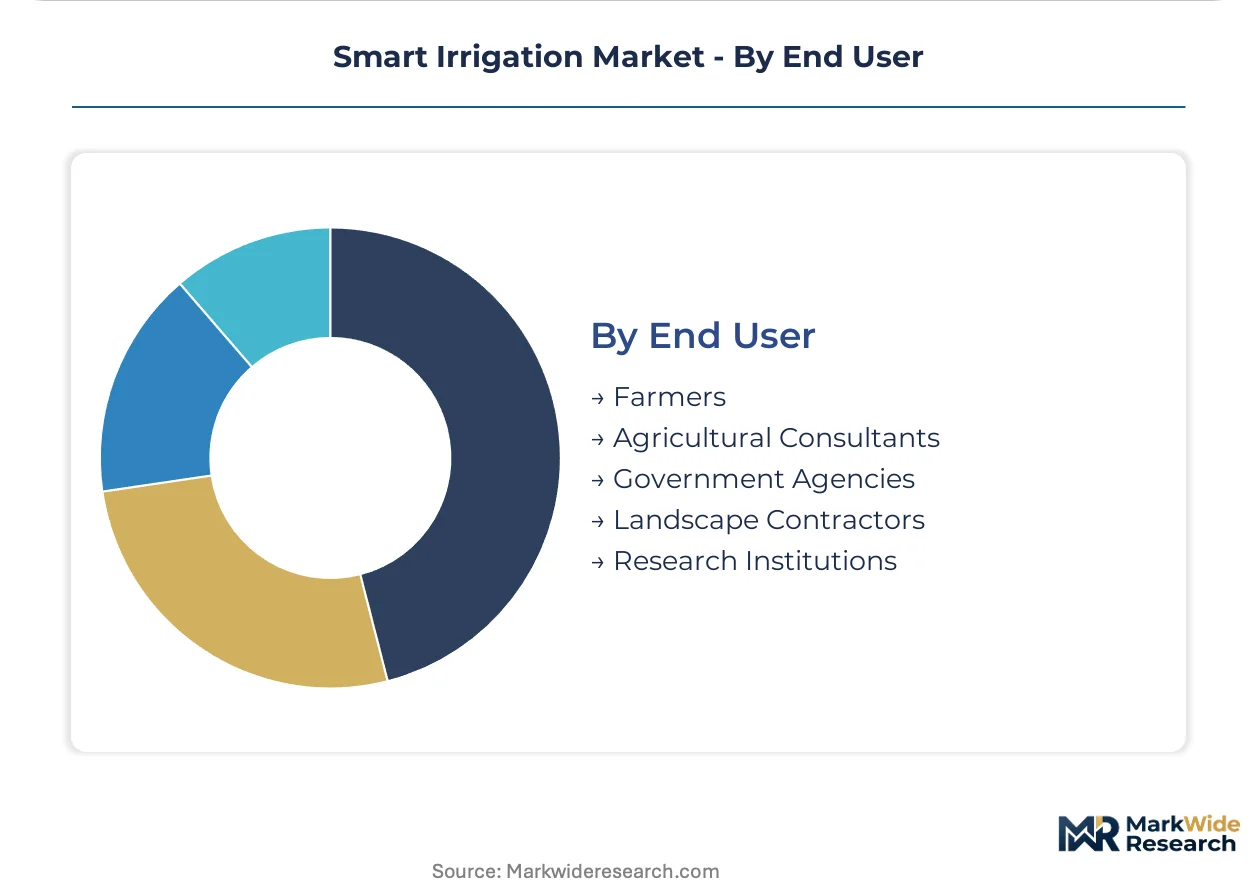
| Segmentation | Product Type: Drip Irrigation System, Sprinkler System, Soil Moisture Sensor, Weather-Based Controller, Flow Metering Device Technology: IoT-Based Solutions, Wireless Sensor Networks, Cloud Computing, AI & Machine Learning, Remote Monitoring Application: Field Crops, Greenhouses, Orchards, Turf Management, Landscaping End User: Farmers, Agricultural Consultants, Government Agencies, Landscape Contractors, Research Institutions |
| Companies Covered | Netafim, Rivulis Irrigation, The Toro Company, Rachio, Lindsay Corporation, Rain Bird Corporation, Jain Irrigation Systems Limited, Valmont Industries, Hunter Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Irrigation Market Strategic Shifts & Innovations
Evapotranspiration-based scheduling algorithms are collapsing the historical separation between meteorological data services and irrigation hardware, compressing the value chain into integrated platform offerings that bundle sensing, forecasting, and actuation.
Machine learning platforms trained on multi-season crop response datasets are collapsing the trial-and-error calibration period for new installations, enabling commercial vineyards and nut orchards to achieve optimized water application within a single growing season rather than the traditional three-to-five year establishment phase. Large-scale farming cooperatives in water-stressed regions are adopting these systems fastest, with adoption timelines compressing from multi-year pilots to single-season rollouts as confidence in yield protection algorithms hardens.
The EU Green Deal's binding sustainability disclosure requirements are accelerating technology substitution across member state agricultural sectors, with the CSRD mandate for environmental impact reporting extending precision water management from efficiency preference to documented compliance necessity. German and Dutch greenhouse operators face the most immediate compliance deadlines, driving concentrated procurement of sensor networks with audit-grade data logging capabilities.
Service unbundling is fragmenting the traditional hardware-sale model, with commercial buyers now separating equipment procurement from analytics subscriptions and maintenance contracts to optimize total cost of ownership across multi-year horizons. This pattern is most pronounced in California's Central Valley, where agricultural water districts negotiate enterprise-scale platform access that spans multiple farming operations under unified data governance frameworks.
Smart Irrigation Market Segmentation
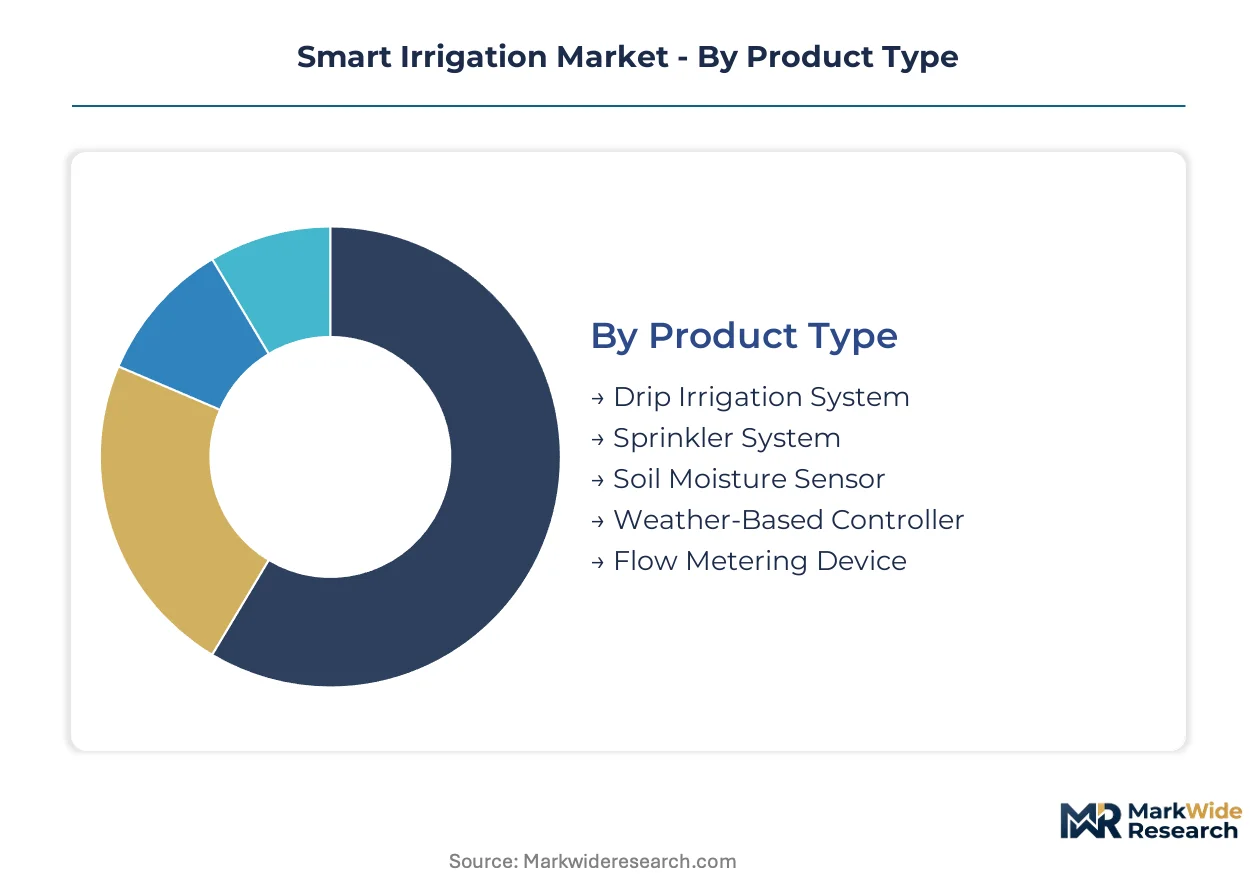
Smart irrigation procurement patterns diverge sharply across hardware categories, connectivity architectures, and end-use environments. Understanding these segment boundaries reveals where service revenue concentrates and which technology combinations command sustainable margin structures.
Product Type:
After-sales service intensity varies dramatically across product categories, with sensor networks requiring continuous calibration support while controllers demand periodic firmware updates.
- Drip Irrigation System:Pressure-compensating emitters and subsurface tubing configurations deliver precise water application directly to root zones. California's Central Valley almond and pistachio growers dominate procurement, driven by State Water Resources Control Board mandates that disqualify conventional flood irrigation from water allocation programs.
- Weather-Based Controller:ET-sensing units integrate local meteorological data with evapotranspiration algorithms to automate scheduling adjustments. Residential and commercial landscaping sectors in drought-stressed US states concentrate demand, with EPA WaterSense certification now mandatory for rebate eligibility.
- Sprinkler System:Mechanized pivot and linear move systems cover extensive field acreage with uniform distribution patterns.
- Soil Moisture Sensor:Capacitance and tensiometer probes measure volumetric water content at multiple soil depths.
- Flow Metering Device:Ultrasonic and electromagnetic meters track consumption volumes for compliance documentation.
Drip irrigation systems hold the largest share; momentum sits with weather-based controllers.
Technology:
Deployment costs scale non-linearly with connectivity sophistication, separating commodity hardware from platform-enabled recurring revenue models.
- IoT-Based Solutions:Networked sensor-actuator architectures transmit field data to centralized dashboards via cellular or LoRaWAN protocols. Large-scale farming cooperatives in water-stressed regions drive adoption, compressing payback period requirements through enterprise-scale deployments.
- AI & Machine Learning:Predictive algorithms trained on multi-season crop response datasets optimize irrigation timing without human calibration cycles. Commercial vineyards and nut orchards lead implementation, achieving yield protection within single growing seasons rather than traditional multi-year establishment phases.
- Wireless Sensor Networks:Mesh topology configurations extend coverage across irregular field geometries without infrastructure dependency.
- Cloud Computing:Centralized data processing and storage infrastructure supports analytics platform delivery.
- Remote Monitoring:Mobile-accessible dashboards enable real-time intervention from off-site locations.
IoT-based solutions anchor current revenue; AI and machine learning platforms are gaining share fastest.
Application:
Water allocation restrictions and crop value density determine technology investment thresholds across cultivation environments.
- Field Crops:Extensive grain and oilseed operations deploy mechanized systems with variable-rate capabilities. US Midwest corn and soybean producers concentrate demand where subsurface drip retrofit costs compete with center-pivot depreciation schedules.
- Greenhouses:Controlled-environment agriculture integrates fertigation with climate management through unified automation platforms. Dutch and German operators face immediate EU Green Deal compliance deadlines, driving sensor procurement with audit-grade data logging.
- Orchards:Permanent tree crops justify capital-intensive precision installations with multi-decade amortization horizons.
- Turf Management:Golf courses and sports fields prioritize aesthetic consistency through soil-moisture-driven scheduling.
- Landscaping:Municipal and commercial grounds maintenance balances water restrictions against visual standards.
Field crops represent the largest application segment; greenhouses are climbing the fastest.
End User:
Procurement authority and technical capability gaps shape vendor engagement models and support service packaging.
- Farmers:Owner-operators weighing capital deployment against yield risk and water cost exposure. California agricultural water districts negotiate enterprise platform access spanning multiple operations under unified data governance.
- Agricultural Consultants:Independent advisors specifying technology configurations and managing implementation projects. These intermediaries concentrate influence in fragmented smallholder markets where direct vendor relationships prove uneconomical.
- Government Agencies:Public irrigation districts and conservation authorities administering subsidy programs.
- Landscape Contractors:Installation and maintenance service providers specifying residential and commercial systems.
- Research Institutions:University extension services and agricultural experiment stations conducting validation trials.
Farmers dominate procurement volume; agricultural consultants are expanding their share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturing for sensor-actuator networks concentrates in the United States, Germany, China, Israel, and the Netherlands, with each jurisdiction deploying distinct regulatory levers to accelerate technology substitution.
United States
California's Central Valley dominates procurement volume as almond and pistachio growers face State Water Resources Control Board mandates that disqualify flood irrigation from water allocation programs. EPA WaterSense certification requirements drive replacement demand for outdated controllers across agricultural and residential installations. Fresno and Kern counties anchor North American demand concentration, where precision technology adoption rates exceed national averages.
Germany
Dutch and German greenhouse operators face immediate EU Green Deal compliance deadlines, driving concentrated procurement of sensor networks with audit-grade data logging capabilities. The CSRD mandate for environmental impact reporting extends precision water management from efficiency preference to documented compliance necessity. Bavaria's agricultural technology clusters coordinate cross-border supply relationships with Dutch horticulture automation specialists.
Israel
Drip irrigation heritage anchors export-oriented manufacturing capacity serving water-stressed growing regions across Australia, India, and the Middle East. National water conservation policies dating to the 1950s created institutional expertise in deficit irrigation techniques now embedded in commercial system designs. Tel Aviv metropolitan engineering centers coordinate field validation partnerships with Jordan Valley farming cooperatives.
China
Xinjiang and Inner Mongolia autonomous regions deploy mechanized pivot systems across extensive cotton and maize operations, with state-funded agricultural modernization programs subsidizing variable-rate retrofit installations. The Ministry of Agriculture and Rural Affairs mandates water-use efficiency targets that accelerate substitution of conventional flood methods. Shandong Province greenhouse clusters integrate domestic sensor manufacturing with climate control automation platforms.
Australia
Murray-Darling Basin water buyback programs condition market access on documented conservation technology adoption, compressing payback period requirements for precision agriculture investments. Bureau of Meteorology data integration standards enable evapotranspiration-based scheduling algorithms that automate irrigation timing adjustments. Riverina district farming cooperatives pilot enterprise-scale platform deployments spanning multiple operations under unified data governance frameworks.
Smart Irrigation Market Key Industry Players
Drip irrigation heritage specialists and mechanized pivot manufacturers split the market between precision delivery hardware and extensive field coverage systems. Israeli and American engineering traditions anchor distinct technology lineages, with consolidation pressure intensifying as platform economics favor integrated sensing-actuation offerings over component sales. Strategic archetypes include heritage irrigation equipment manufacturers extending into subscription services, cloud-native controller developers capturing residential segments, and agricultural automation platforms bundling fertigation with climate management. Dominant competitive moves encompass backward integration into sensor manufacturing and geographic expansion through distribution partnerships in water-stressed growing regions.
Among heritage irrigation specialists, Netafim exemplifies the archetype of drip equipment manufacturers extending into soil monitoring subscriptions, while Lindsay Corporation occupies a position representing mechanized pivot scale manufacturing. Rachio sits within the cloud-native residential controller segment, anchoring algorithm-driven scheduling automation. These three companies represent the strategic positioning spectrum from industrial-scale hardware through connected consumer devices.
| Leading Market Players |
|---|
| Netafim |
| Rivulis Irrigation |
| The Toro Company |
| Rachio |
| Lindsay Corporation |
| Rain Bird Corporation |
| Jain Irrigation Systems Limited |
| Valmont Industries |
| Hunter Industries |
| Others |
Cost & Logistics Intelligence
Shandong Province's sensor manufacturing clusters feed component pricing power into downstream controller assembly, with domestic Chinese greenhouse operators capturing cost advantages unavailable to import-dependent buyers in Europe or North America. This geographic concentration of capacitance probe and LoRaWAN module production creates tiered equipment economics that ripple through global procurement patterns.
Pricing Analysis
EPA WaterSense certification dictates the pricing tier structure across residential and agricultural controller segments, separating rebate-eligible premium hardware from economy timer-based units facing phased elimination from subsidized programs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling rather than raw hardware capability. Cost compression in economy tiers is intensifying because Asian microcontroller foundries pass through input volatility. Smallholder farming operations under 500 acres demonstrate highest price sensitivity, while California agricultural water districts negotiating enterprise-scale platform access show least sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Export control restrictions on semiconductor manufacturing equipment limit foundry capacity expansion in Taiwan, South Korea, and mainland China, constraining IoT sensor microcontroller availability for irrigation hardware vendors. Component sourcing draws from Taiwanese wafer fabrication for processing chips, German precision engineering for pressure sensors, and Israeli drip emitter manufacturing. Single-source vulnerability concentrates in advanced node semiconductor supply, where agricultural IoT competes with automotive and consumer electronics for allocation. Distribution runs through agricultural equipment dealers in North America, specialized horticulture automation integrators in the Netherlands and Germany, and state procurement channels in China's Xinjiang cotton belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among California agricultural water districts and German greenhouse cooperatives, with fragmented smallholder demand increasingly intermediated through consultant-led procurement that squeezes vendor margins.
For Market Incumbents: Pre-empt platform unbundling by capturing analytics subscription revenue before third-party software vendors displace hardware-agnostic offerings. Accelerate backward integration into sensor manufacturing to reduce exposure to Asian foundry lead time volatility. Defensive consolidation through drip irrigation heritage extension into soil monitoring services protects against cloud-native entrants like Rachio expanding upstream. For New Entrants and Emerging Players: Build out edge computing capabilities for autonomous valve actuation in remote orchard applications where cellular connectivity gaps degrade cloud-dependent competitors. Target Australian Murray-Darling Basin farming cooperatives, where water buyback program documentation requirements create compliance-driven demand with compressed procurement cycles. Go-to-market through agricultural consultant channels bypasses direct smallholder engagement economics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-ML platform vendors with multi-season crop response datasets that generate switching costs through yield optimization algorithms. Long-term viability favors hardware-agnostic software subscriptions over capital-intensive mechanized pivot manufacturing. Acquisition focus should center on sensor networks with audit-grade data logging capabilities serving EU Green Deal compliance deadlines. Signal to monitor: California State Water Resources Control Board mandate expansion beyond almond and pistachio into row crops.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of capacitance probes insulates margin from Asian foundry volatility. |
| AI-ML Platform Acquisition | Multi-season crop datasets compress customer calibration cycles from years to single seasons. |
| EU Green Deal Compliance Certification | Audit-grade data logging capabilities unlock German and Dutch greenhouse procurement. |
| Edge Computing Capability Buildout | On-device inference enables autonomous actuation in California Central Valley cellular dead zones. |
| Agricultural Consultant Channel Partnership | Intermediary access to fragmented smallholder demand bypasses direct sales economics. |
Research Approach
A standing panel of irrigation district procurement officers, precision agriculture consultants, greenhouse automation engineers, and drip system maintenance technicians provided ongoing calibration against field deployment realities. Primary interview data combined with secondary validation from EPA WaterSense certification databases, EU CSRD disclosure filings, California State Water Resources Control Board allocation records, and Israeli Ministry of Agriculture irrigation efficiency reports. Bottom-up sensor shipment tracking and top-down agricultural water consumption modeling triangulated market sizing across hardware categories.
Scenario bracketing anchored projections through sensitivity analysis on regulatory compliance deadline acceleration and semiconductor supply normalization trajectories. Segmentation modeling spanned product type, connectivity architecture, application environment, and end-user procurement authority across the projection horizon. CAGRs derived from fitted adoption curves calibrated to documented precision technology penetration in water-stressed growing regions, with evapotranspiration algorithm accuracy improvement and edge computing cost decline as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by cloud-native residential controller vendors would shift outcomes beyond modeled ranges. Material shifts in EPA WaterSense mandate scope or EU Green Deal Farm to Fork enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Precision Forestry Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Agriculture Solutions Market
Smart Agriculture
Digital Agriculture Infrastructure Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
US Smart Agriculture Market
Smart Agriculture
Connected Agriculture Market
Smart Agriculture
Smart Agriculture Technology Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Smart Irrigation Controllers Market
Smart Agriculture
Global AI in Agriculture Market