
 North America Agricultural Microbials Market | 2026-2036
North America Agricultural Microbials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Microbials Market Analytics
RNA-guided microbial strain engineering is reconfiguring product development pipelines across the agricultural biologicals sector. BASF SE leverages its microbial screening platforms to identify novel biocontrol strains with enhanced environmental persistence. Bayer AG anchors its biologicals division through integrated seed treatment formulations that combine microbial inoculants with conventional chemistries. Novonesis competes in the specialized enzyme-microbe synergy space, targeting nitrogen fixation enhancement in legume systems.
Agricultural microbials comprise live or dormant microorganisms—bacteria, fungi, viruses, or protozoa—formulated at concentrations typically ranging from 10^6 to 10^9 colony-forming units per gram or milliliter, applied to seeds, soil, or foliage to confer crop protection, nutrient mobilization, or growth stimulation benefits. Biofertilizers containing nitrogen-fixing and phosphate-solubilizing bacteria dominate volume flows in row-crop applications where input cost sensitivity shapes farmer procurement decisions. Liquid formulations lead delivery mode adoption due to compatibility with existing spray equipment and irrigation infrastructure, though granular carriers gain traction in no-till systems where seed placement precision matters. Soil amendments represent the fastest-expanding product category as regenerative agriculture protocols reward measurable improvements in soil organic carbon and microbial biomass.
The US EPA's biopesticide division and Health Canada's PMRA govern microbial product registration timelines and data requirements across North America, with the US regulatory pathway typically offering faster market access than conventional pesticide channels. The Canadian Food Inspection Agency enforces strain-specific import permits and facility inspection protocols that constrain cross-border manufacturing flexibility. Stakeholders must monitor evolving EPA guidance on genetically edited microbial strains, as regulatory classification of gene-edited versus transgenic organisms will determine capital allocation toward next-generation biological platforms.
Market Dynamics
RNA-guided microbial strain engineering is collapsing development timelines from discovery to field deployment, forcing incumbents to reconfigure R&D infrastructure or cede ground to biotech-native entrants.
Growth Catalysts
- US EPA biopesticide registration pathway:The streamlined approval process accelerates commercialization timelines for novel microbial strains, reducing regulatory friction relative to conventional pesticide channels.
- Regenerative agriculture protocols:Carbon credit markets and soil health verification programs reward measurable microbial biomass improvements, expanding demand for soil amendment formulations.
- Rhizobia inoculant integration:Soybean and corn farmers across the US Corn Belt now embed nitrogen-fixing bacteria into standard fertility programs, creating recurring procurement patterns.
Market Restraints
- Strain-specific import permits:The Canadian Food Inspection Agency enforces facility inspection protocols that constrain cross-border manufacturing flexibility and inflate compliance costs.
- Environmental persistence variability:Field performance inconsistency limits microbial biocontrol adoption in high-value specialty crops where failure carries catastrophic revenue risk.
- Liquid formulation cold-chain dependency:Viability decay during storage and transport elevates spoilage rates versus chemical alternatives, compressing distributor margins.
Strategic Opportunities
- No-till system granular carriers:Seed placement precision requirements in zero-tillage corn and soybean operations create white space for dry formulation innovation.
- California Central Valley specialty crops:Vegetable and nut growers are expanding microbial-based crop protection programs ahead of regulatory restrictions on conventional chemistries.
- Gene-edited strain classification clarity:Evolving EPA guidance on genetically edited versus transgenic organism status will unlock capital flows toward next-generation biological platforms.
Industry Challenges
- Formulation chemist scarcity:The intersection of microbiology and agricultural chemistry expertise remains thinly distributed, constraining product pipeline velocity.
- Compatibility testing burden:Microbial inoculants require extensive tank-mix validation with existing pesticide and fertilizer regimens, elongating field trial cycles.
- Soil microbiome baseline variability:Native microbial community heterogeneity complicates efficacy prediction and trial design across geographic zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Microbials Market |
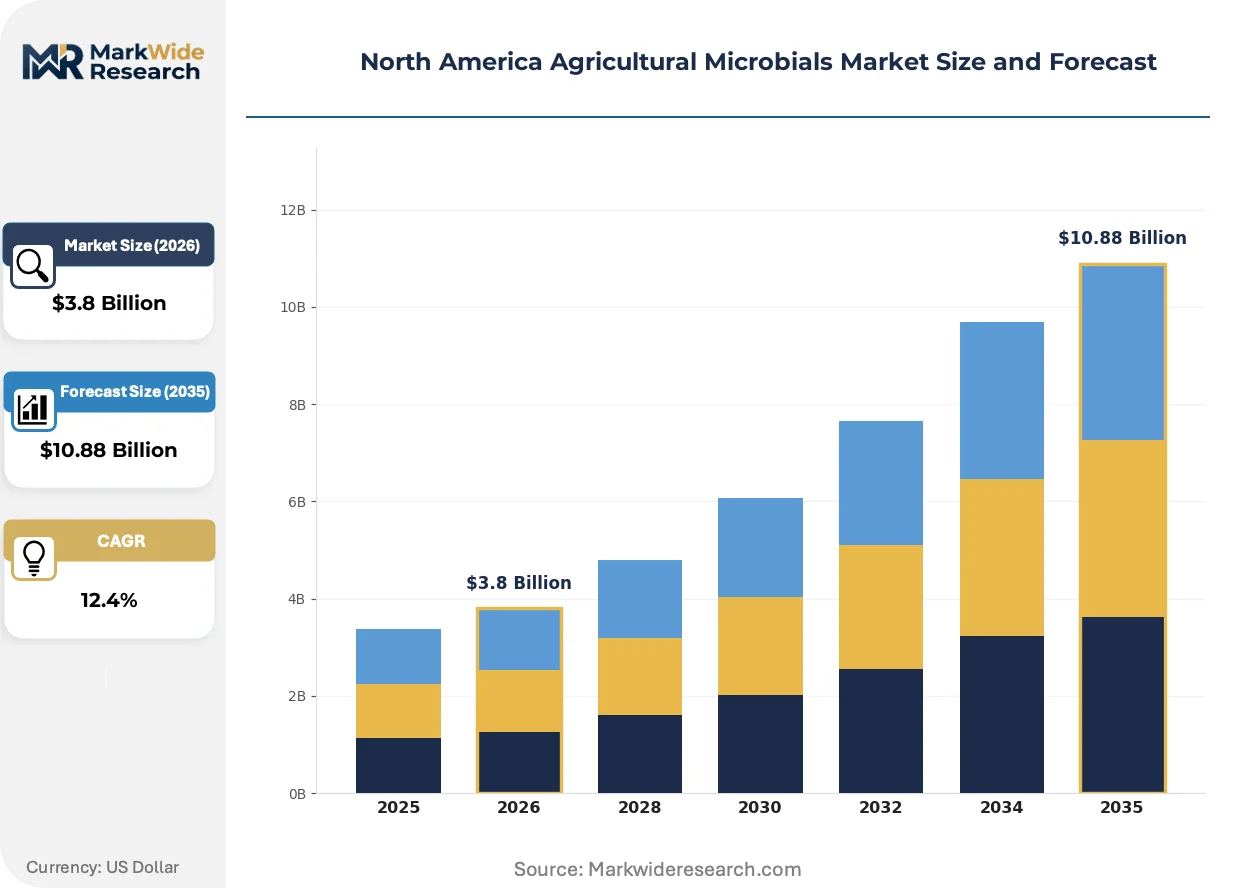
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bactericides, Fungal Inoculants, Biofertilizers, Soil Amendments Application: Crop Protection, Soil Health, Plant Growth Promotion, Organic Farming End User: Farmers, Agricultural Enterprises, Research Institutions, Growers Delivery Mode: Liquid Formulation, Granular Formulation, Powder Formulation, Others |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Certis USA, Koppert B.V., Novonesis, Syngenta Group, Marrone Bio Innovations, FMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Microbials Market Evolving Landscape
Convergence between synthetic biology tools and precision agriculture infrastructure is redefining how microbial products are discovered, formulated, and deployed across North American farmland.
CRISPR-Cas9 and base-editing platforms are collapsing the strain optimization cycle from years to months. Biocontrol developers now engineer enhanced environmental persistence directly into bacterial and fungal chassis. Large-scale row-crop operators are piloting these advanced strains through integrated seed treatment channels, compressing the traditional independent product testing phase.
The US EPA's evolving guidance on gene-edited microbial strains is creating regulatory clarity that separates edited organisms from transgenic classifications. This distinction determines whether products enter the biopesticide fast-track or conventional registration channels. Formulators are restructuring dossier preparation workflows to exploit this pathway advantage, with soil amendment categories seeing the most aggressive repositioning.
Buyer consolidation among agricultural retailers is shifting procurement toward multi-year biological supply agreements with performance guarantees. Independent agronomists and co-operatives are losing ground to vertically integrated distributors who bundle microbial inoculants with seed and chemistry portfolios. This pattern is most pronounced in the US Corn Belt, where input suppliers now embed biologicals into fertility program templates rather than offering standalone products.
North America Agricultural Microbials Market Segmentation
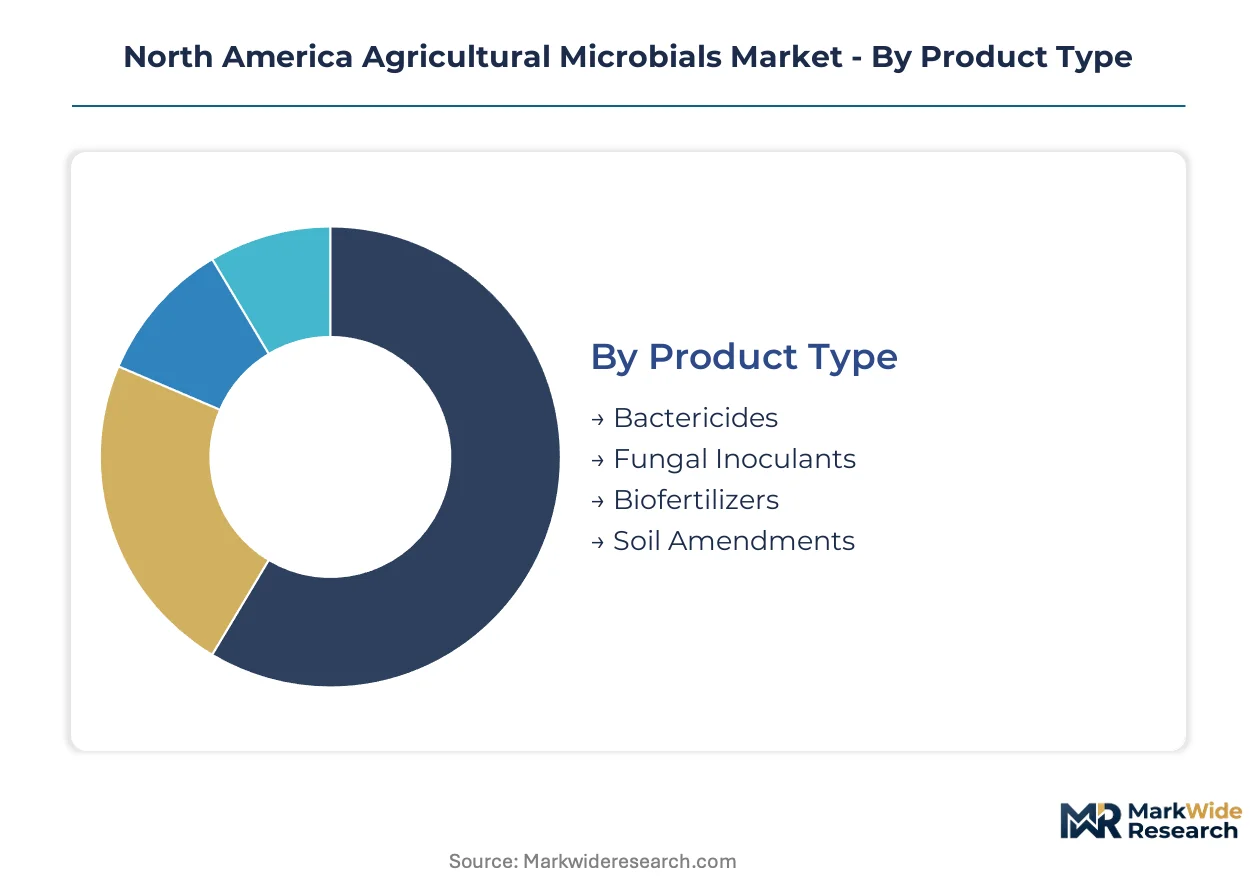
Product differentiation in agricultural microbials follows distinct technical specifications and application protocols that shape procurement patterns across North American farmland. Each segmentation dimension reveals how biological solutions align with specific agronomic challenges, from nitrogen fixation in Iowa cornfields to soil carbon accumulation in California orchards.
Product Type:
The use-case spectrum spans protective biocontrol through fertility enhancement, with each product category demanding unique formulation expertise and field deployment protocols.
- Biofertilizers:Nitrogen-fixing and phosphate-solubilizing bacteria dominate volume flows in cost-sensitive row-crop applications. US Corn Belt soybean and corn farmers embed these inoculants into standard fertility programs, creating recurring procurement anchored to planting calendars.
- Soil Amendments:Regenerative agriculture protocols reward measurable improvements in soil organic carbon and microbial biomass. California Central Valley specialty crop growers are expanding microbial-based amendment programs ahead of regulatory restrictions on conventional chemistries.
- Bactericides:Live bacterial strains formulated for pathogen suppression in high-value fruit and vegetable systems. EPA biopesticide registration pathways accelerate commercialization timelines relative to conventional pesticide channels.
- Fungal Inoculants:Mycorrhizal and antagonistic fungi targeting root disease complexes and nutrient scavenging. Demand concentrates in no-till systems where native fungal populations have degraded under intensive cultivation.
The dominant share belongs to biofertilizers, while soil amendments are closing the gap fastest.
Application:
Cost tier differentiation separates commodity row-crop adoption from premium specialty crop protocols.
- Crop Protection:Microbial biocontrol agents targeting insect pests, fungal pathogens, and nematodes in integrated pest management frameworks. Field performance inconsistency limits adoption in high-value specialty crops where failure carries catastrophic revenue risk.
- Soil Health:Carbon credit markets and soil health verification programs reward measurable microbial biomass improvements. This application category sees the most aggressive repositioning toward gene-edited strain platforms as EPA guidance clarifies regulatory pathways.
- Plant Growth Promotion:Phytohormone-producing bacteria and fungi stimulating root development and stress tolerance. Compatibility testing with existing pesticide and fertilizer regimens elongates field trial cycles.
- Organic Farming:Certified organic formulations meeting USDA National Organic Program standards for prohibited substance exclusion. Premium pricing structures reflect input cost insensitivity among organic producers.
Crop protection commands the largest installed base, though soil health applications are expanding most quickly.
End User:
Customer type stratification reflects divergent procurement sophistication and technical support requirements.
- Farmers:Individual operators across the US Corn Belt and Canadian Prairies integrating microbial inoculants through retail co-operative channels. Buyer consolidation among agricultural retailers is shifting procurement toward multi-year biological supply agreements with performance guarantees.
- Agricultural Enterprises:Large-scale row-crop operators piloting advanced strains through integrated seed treatment channels. These entities compress traditional independent product testing phases through direct R&D partnerships.
- Growers:Specialty crop producers in California's Central Valley and Florida's citrus belt demanding strain-specific efficacy data. Environmental persistence variability constrains adoption where crop failure carries catastrophic revenue exposure.
- Research Institutions:University extension services and federal agricultural research stations conducting field validation trials. Native microbial community heterogeneity complicates efficacy prediction and trial design across geographic zones.
Farmers represent the deepest volume base, while agricultural enterprises are driving technology adoption fastest.
Delivery Mode:
Volume concentration in liquid formulations reflects equipment compatibility, though granular carriers gain traction in precision planting systems.
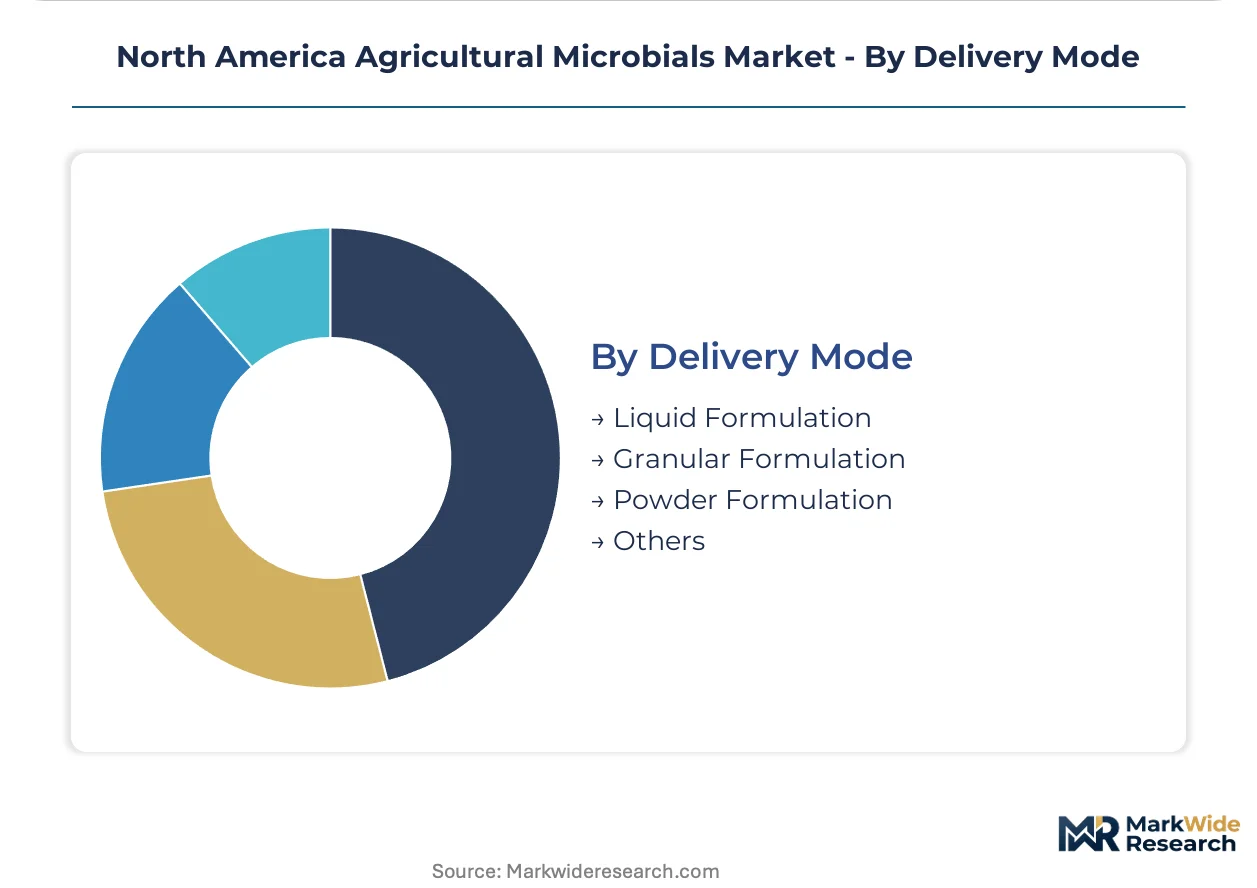
- Liquid Formulation:Compatibility with existing spray equipment and irrigation infrastructure dominates adoption. Cold-chain dependency for viability preservation elevates spoilage rates versus chemical alternatives, compressing distributor margins.
- Granular Formulation:Seed placement precision requirements in zero-tillage corn and soybean operations create white space for dry formulation innovation. These carriers gain traction where planting equipment modification costs deter liquid adoption.
- Powder Formulation:Dust-based delivery systems for soil incorporation and transplant dip applications. Shelf stability advantages offset handling complexity in smaller-scale operations.
- Others:Emerging encapsulation technologies and drone-compatible micro-granule formats. Formulation chemist scarcity constrains pipeline velocity for novel delivery mechanisms.
Liquid formulation holds the dominant position, while granular alternatives are gaining share fastest in no-till geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports microbial inoculants and biocontrol formulations to US Corn Belt distributors, while Mexican specialty crop operations import California-developed soil amendment technologies. This cross-border trade corridor shapes regional production priorities and regulatory harmonization pressures.
United States
US Corn Belt soybean and corn farmers embed rhizobia inoculants into standard fertility programs, creating recurring procurement anchored to planting calendars. The EPA's biopesticide registration pathway accelerates commercialization timelines for novel microbial strains relative to conventional pesticide channels. California's Central Valley specialty crop growers are expanding microbial-based crop protection programs ahead of regulatory restrictions on conventional chemistries.
Canada
Canadian Prairie wheat and canola producers integrate nitrogen-fixing bacteria through retail co-operative channels, with buyer consolidation shifting procurement toward multi-year biological supply agreements. Health Canada's PMRA and the Canadian Food Inspection Agency enforce strain-specific import permits and facility inspection protocols that constrain cross-border manufacturing flexibility. Ontario's agricultural research corridor hosts federal validation trials addressing native microbial community heterogeneity.
Mexico
Mexican vegetable and berry exporters in Sinaloa and Baja California adopt microbial biocontrol agents to meet US organic import standards and residue restrictions. The country's national agricultural regulator coordinates with EPA guidance on biopesticide equivalency for cross-border product registration. Guanajuato's intensive horticulture belt represents emerging demand concentration for mycorrhizal inoculants in protected cultivation systems.
North America Agricultural Microbials Market Competitive Landscape
On the supply side, the industry is consolidating around integrated seed treatment platforms and biological-chemistry combination portfolios. Tiered competitive positioning separates multinational agrochemical conglomerates with captive biologicals divisions from specialized microbial technology developers and regional formulation specialists. Dominant competitive moves include strategic partnerships between microbial discovery platforms and distribution networks, plus backward integration into strain engineering capabilities.
Within the integrated agrochemical tier, BASF SE and Bayer AG exemplify multinational conglomerates leveraging microbial screening platforms and seed treatment integration. Novonesis occupies a specialized position in enzyme-microbe synergy development. These three entities represent divergent strategic archetypes: platform-integrated biologicals, chemistry-biological convergence, and targeted enzymatic enhancement systems.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Certis USA |
| Koppert B.V. |
| Novonesis |
| Syngenta Group |
| Marrone Bio Innovations |
| FMC Corporation |
| Others |
Value Network & Pricing Analysis
Strain engineering expertise concentrates in Denmark and the Netherlands, where Novonesis and specialized biotech platforms command premium licensing fees that cascade into finished product markups across North American distribution channels. This upstream capability scarcity allows technology holders to extract disproportionate value while formulation specialists downstream compete on thinner margins.
Pricing Analysis
Next-generation gene-edited microbial strains command substantial premiums over conventional wild-type formulations, while legacy chemical-biological combination products face accelerating price erosion. The market operates on a contract-based long-term offtake structure, with pricing differentiation driven by EPA registration tier and cold-chain reliability certification. Cost compression in liquid formulation tiers is intensifying because distributor spoilage rates compress working capital returns. Agricultural enterprises purchasing through integrated seed treatment channels exhibit the lowest price sensitivity, while individual farmers procuring through retail co-operatives negotiate aggressively on per-acre application costs.
Supply Chain Analysis
Canadian strain import permit restrictions under CFIA oversight constrain cross-border manufacturing flexibility, fragmenting production footprints across US, Canadian, and Mexican facilities. Active ingredient supply draws from specialized fermentation capacity in Denmark, Brazil, and select US biotechnology corridors, with formulation packaging concentrated in Iowa and California to minimize cold-chain transit distances. Single-source vulnerability pervades the gene-edited strain pipeline where CRISPR-optimized chassis development rests on limited platform providers. Distribution runs through vertically integrated agricultural retailers who bundle biologicals with seed and chemistry portfolios, displacing independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise capable of stabilizing microbial viability across variable temperature regimes represents the critical bottleneck constraining product pipeline velocity and competitive differentiation. Firms that secure or develop this scarce capability will capture disproportionate margin pools as demand accelerates.
For Market Incumbents: Entrench biocontrol market position through backward integration into strain engineering capabilities, eliminating licensing dependencies on Danish and Dutch technology platforms. Expand granular formulation manufacturing capacity in Iowa and Illinois to capture no-till system demand before regional specialists consolidate this white space. Prioritize EPA biopesticide registration pathway expertise as a defensive moat against emerging biotech-native entrants unfamiliar with regulatory dossier preparation. For New Entrants and Emerging Players: Mexican protected cultivation systems in Guanajuato and Sinaloa present underpenetrated demand concentration for mycorrhizal inoculants, with less entrenched incumbent presence than US Corn Belt markets. Target specialty crop growers in Florida's citrus belt with strain-specific efficacy data packages that address environmental persistence variability concerns blocking adoption. Pursue direct partnerships with university extension services to compress field validation timelines and establish credibility before scaling retail distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microbial discovery platforms that have exhausted their initial growth capital but retain valuable strain libraries and EPA registration dossiers. The five-to-ten year viability window favors platforms with demonstrated environmental persistence enhancement and compatibility with precision agriculture infrastructure. Monitor EPA guidance publication timing on gene-edited organism classification as the definitive inflection indicator for capital allocation toward next-generation biological platforms versus conventional strain optimization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Engineering | Captures licensing value currently extracted by Danish and Dutch technology platforms. |
| Granular Formulation Capacity Expansion | Addresses no-till planting precision requirements in Iowa and Illinois corn-soy systems. |
| EPA Biopesticide Registration Investment | Accelerates commercialization timelines relative to conventional pesticide channels. |
| University Extension Partnership | Compresses field validation cycles through access to federal agricultural research station networks. |
| Multi-Year Biological Supply Agreements | Locks in procurement volumes as agricultural retailer consolidation shifts buyer power. |
Research Methodology
A spread of perspectives from microbial formulation chemists, EPA biopesticide registration consultants, agricultural retailer procurement directors, and specialty crop agronomists converged on the working assumptions governing market size and growth trajectory. Primary field engagement combined structured interviews with secondary validation through EPA registration databases, USDA National Organic Program certification records, and Health Canada PMRA submission filings. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against agricultural input expenditure flows anchored the quantitative framework.
Demand-supply-balance modeling across the projection horizon incorporated acreage expansion patterns, regenerative agriculture protocol adoption curves, and regulatory pathway throughput constraints. Segmentation dimensions included product type, application category, end-user archetype, and delivery mode, with additional granularity on EPA registration tier and gene-edited versus conventional strain status. CAGRs were derived from fitted growth curves applied to baseline penetration rates, with explicit incorporation of rhizobia inoculant integration timing and carbon credit market development as industry-specific demand drivers.
Practitioners should monitor EPA guidance evolution on genetically edited organism classification, CFIA import permit processing delays, and cold-chain infrastructure investment patterns for early signals of forecast deviation. Forecasts reflect assumptions regarding regulatory pathway stability and microbial viability preservation technology advancement. Material shifts in gene-edited strain regulatory classification or breakthrough stabilization formulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Latin America Animal Feed Additives Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Feed Mycotoxin Binders Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market