
 Lawn Edge Trimmer Market | 2026-2036
Lawn Edge Trimmer Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Edge Trimmer Market Analytics
Brushless motor integration and lithium-ion battery density improvements is tilting the lawn edge trimmer technology stack away from two-stroke gas engines toward cordless electric platforms. Husqvarna leverages its Nordic engineering heritage to sustain premium positioning in professional-grade battery systems. Black+Decker anchors mass-market penetration through big-box retail partnerships and accessible price points. Ego differentiates through proprietary 56V battery architecture that extends runtime for demanding edge applications.
A lawn edge trimmer is a powered or hand-operated horticultural tool employing a rotating monofilament line, metal blade, or fixed cutting edge to sever grass and vegetation at lawn boundaries, typically operating at cutting widths between 8 and 14 inches and rotational speeds exceeding 10,000 RPM for clean turf delineation. Battery-powered units now capture the fastest expansion as residential users prioritize reduced noise, zero exhaust emissions, and elimination of fuel mixing. Gas-powered trimmers retain structural importance in commercial landscaping services where continuous runtime and brush-cutting torque remain non-negotiable. Rotary technology dominates unit economics while dual-line systems command margin premiums through faster cutting efficiency and reduced line consumption.
EPA emission standards for small spark-ignition engines continue compressing the gas-powered segment's addressable market, while OSHA noise exposure regulations push commercial operators toward sub-75-decibel electric alternatives. California Air Resources Board zero-emission equipment mandates are reshaping municipal procurement specifications statewide. Stakeholders must monitor battery recycling infrastructure maturity and emerging right-to-repair legislation as these forces determine aftermarket profitability and brand loyalty mechanics.
Market Dynamics
The lawn edge trimmer market is undergoing a fundamental platform transition as brushless motor architectures and high-density lithium-ion cells systematically erode the operational rationale for two-stroke gasoline engines in residential and light-commercial applications. This technological inflection compresses legacy supply chains while rewiring distribution economics toward battery ecosystem vendors.
Growth Catalysts
- OSHA noise exposure regulations:Sub-75-decibel electric alternatives gain mandatory preference in commercial landscaping contracts across the United States, accelerating fleet turnover.
- Landscaping services procurement:Municipal and corporate grounds maintenance contracts multiply, creating concentrated demand for professional-grade battery platforms with interchangeable power systems.
- Lithium-ion energy density improvements:Cell chemistry advances extend runtime per charge, eliminating the historical performance gap between cordless and gasoline units for edge applications.
Market Restraints
- Raw material concentration:Cobalt and lithium supply chains concentrate in politically unstable extraction regions, exposing battery manufacturers to input cost volatility and ESG compliance burdens.
- Gasoline torque persistence:Brush-cutting applications in commercial vegetation management retain dependence on two-stroke engines for sustained high-torque output under continuous load.
- California Air Resources Board mandates:Zero-emission equipment requirements create compliance friction for national product lines, forcing parallel inventory and certification investments.
Strategic Opportunities
- Battery recycling infrastructure:Closed-loop recovery systems for lithium-ion packs create aftermarket revenue streams and regulatory compliance advantages in jurisdictions advancing extended producer responsibility frameworks.
- Right-to-repair legislation:Proposed state-level mandates in the United States favor modular battery platforms with standardized cell replacement, rewarding designs with serviceable architectures.
- Suburban lawn culture expansion:Australia and Canada exhibit underpenetrated cordless adoption relative to the United States, presenting whitespace for battery ecosystem rollouts.
Industry Challenges
- Technician skill reconfiguration:Small-engine repair networks must retrain for power electronics diagnostics and battery management system troubleshooting, compressing service capacity during transition.
- SKU proliferation complexity:Dual platform maintenance (gasoline and battery) strains inventory and working capital for distributors serving mixed commercial fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Edge Trimmer Market |
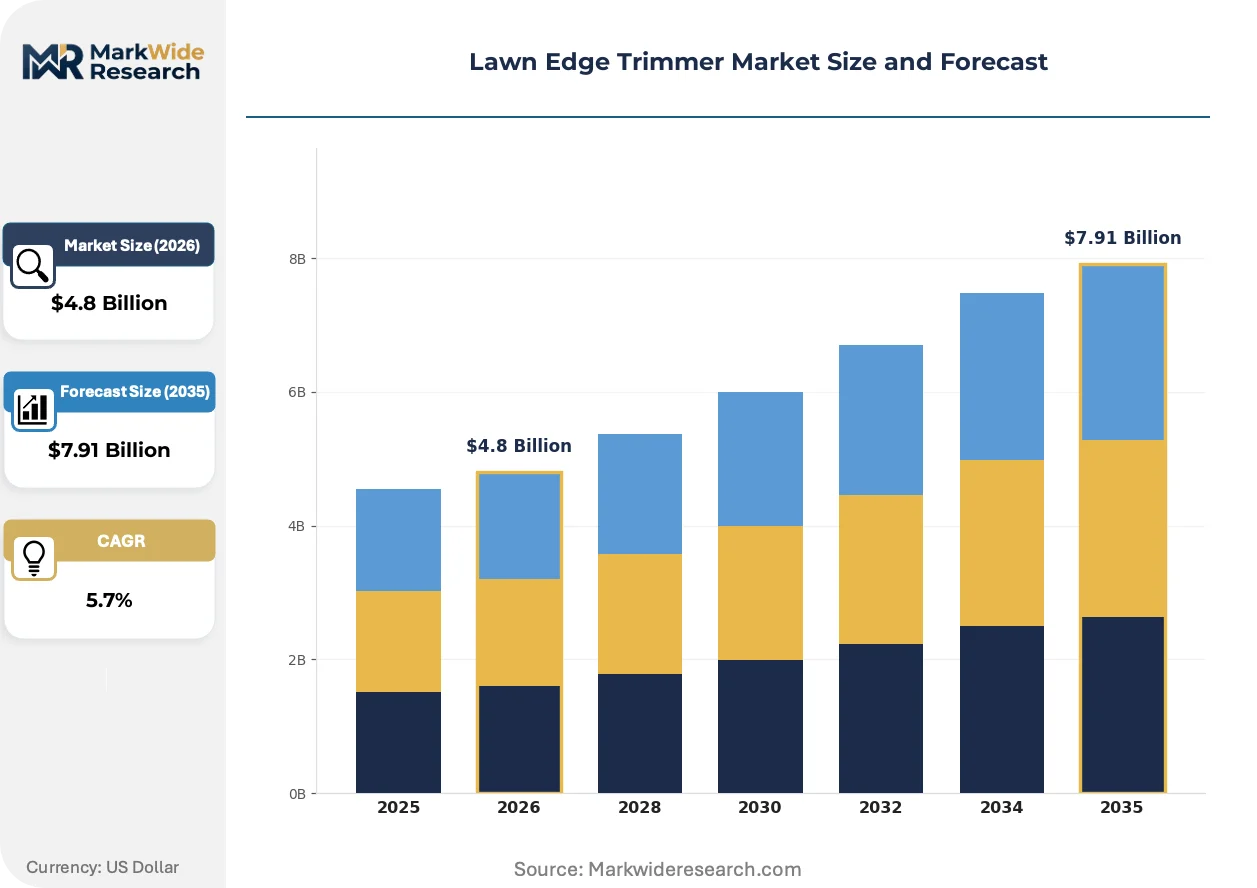
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded Electric, Battery-Powered, Gas-Powered, Manual End User: Residential, Commercial, Municipal, Landscaping Services Technology: Rotary, Dual-Line, Fixed Line, Edging Blade Distribution Channel: Online Retailers, Home Improvement Stores, Garden Centers, Distributors |
| Companies Covered | Echo, Black+Decker, Ego, Greenworks, Craftsman, Worx, Husqvarna, Hart, Maxlander, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Edge Trimmer Market Evolving Landscape
Brushless motor integration is actively compressing the technology stack, rendering mechanical commutators and carbon brush maintenance obsolete while enabling software-defined speed control. This shift reconfigures competitive advantage toward firmware and thermal management capabilities rather than casting and machining expertise.
Brushless permanent magnet motors is rendering obsolete the traditional two-stroke engine's dominance in residential edge trimming. Homeowners and light-commercial operators in the United States are adopting cordless platforms at replacement cycle acceleration. The technology is rendering obsolete the established dealer-service revenue model tied to seasonal engine maintenance, compressing aftermarket profitability for legacy distribution networks.
EPA emission standards for small spark-ignition engines continue tightening permissible hydrocarbon and carbon monoxide outputs from handheld power equipment. These regulations force engineering investment into catalytic converter miniaturization or platform abandonment toward electrification. Gasoline trimmer manufacturers serving the United States market face portfolio rationalization pressure, with some SKUs becoming economically unviable for national distribution.
Commercial landscaping procurement is consolidating around equipment-as-service models where battery platform standardization across mowers, blowers, and trimmers determines vendor selection. Fleet operators are unbundling capital expenditure into operational leases with guaranteed uptime commitments. This pattern concentrates most visibly in United States municipal contracts and large property management portfolios, where total-cost-of-ownership calculations now dominate point-of-purchase decisions.
Lawn Edge Trimmer Market Segmentation
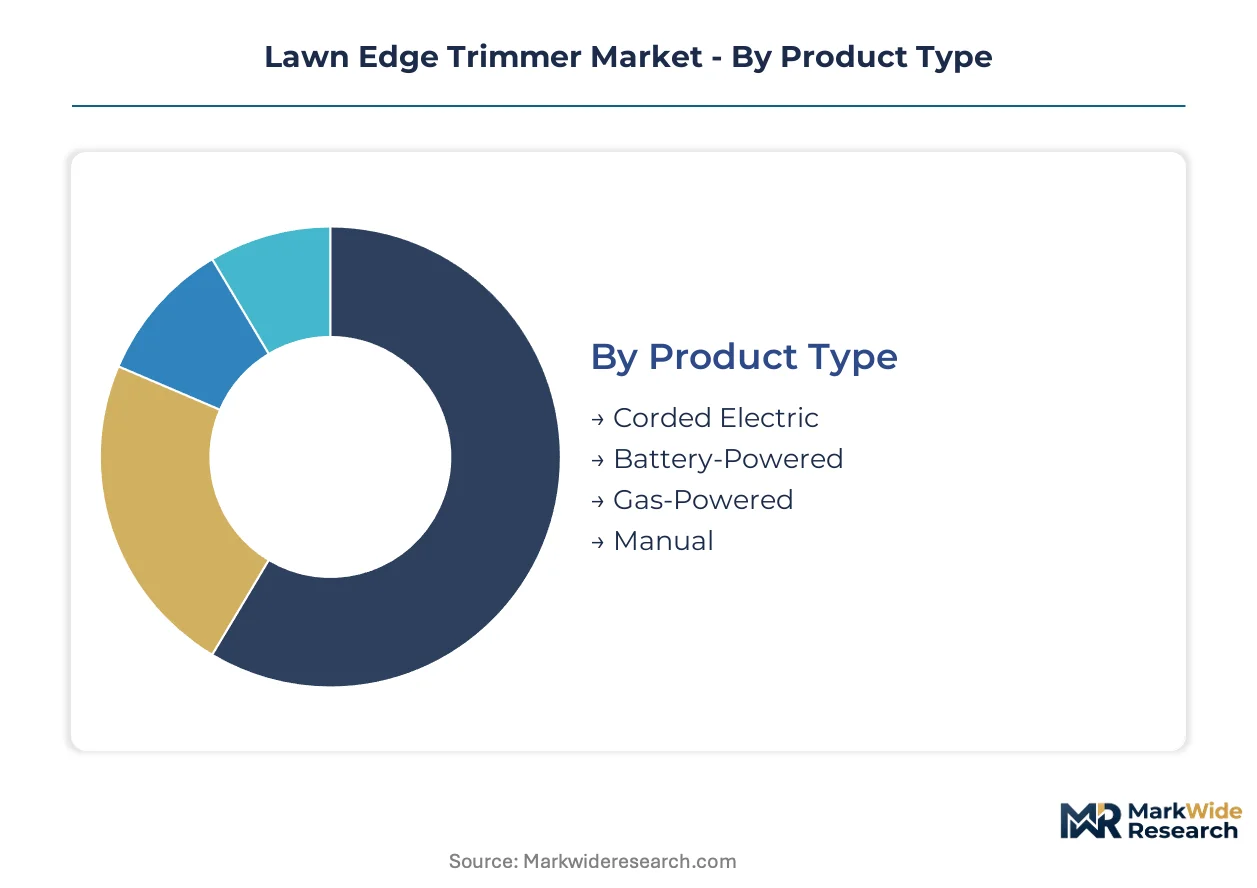
Lawn edge trimmer purchasing decisions hinge on runtime requirements, noise constraints, and fleet standardization needs. Segmentation reveals how battery platforms are displacing gasoline in residential settings while commercial operators maintain mixed fleets for specialized applications.
Product Type:
Cost tier determines technology stack selection, with upfront equipment expense weighed against lifetime fuel and maintenance economics.
- Battery-Powered:Lithium-ion cells paired with brushless motors deliver 10,000+ RPM cutting speeds with zero exhaust emissions. Landscaping services in the United States are consolidating procurement around interchangeable 56V and 80V battery ecosystems to reduce fleet complexity. OSHA sub-75-decibel compliance mandates accelerate replacement of gasoline units in municipal contracts.
- Gas-Powered:Two-stroke engines sustain torque output for brush-cutting and continuous commercial runtime. Vegetation management contractors retain gasoline dependence where battery runtime cannot match job duration, though EPA emission standards compress addressable market share.
- Corded Electric:AC-powered motors serve budget-conscious residential users with small lawns and proximity to outdoor outlets. Runtime is unlimited but mobility is constrained by cord length, limiting adoption to suburban properties under 0.25 acres.
- Manual:Hand-operated shears and wheeled edgers persist in niche applications requiring precision control or zero noise footprint. Heritage garden maintenance and noise-restricted historic districts sustain residual demand.
Gas-powered units command the established base. The steepest expansion runs through battery-powered platforms.
End User:
Application intensity separates occasional residential edging from fleet-scale commercial vegetation management.
- Landscaping Services:Route density and equipment utilization rates drive total-cost-of-ownership calculations. United States commercial operators prioritize battery platform standardization across mowers, blowers, and trimmers to minimize spare battery inventory and technician training overhead.
- Residential:Homeowners prioritize reduced noise, eliminated fuel mixing, and storage simplicity. Suburban lawn culture in the United States sustains replacement cycle volume as cordless platforms reach price parity with entry-level gasoline units.
- Municipal:Public grounds maintenance departments face procurement mandates for zero-emission equipment under California Air Resources Board regulations and similar state-level directives. Fleet turnover accelerates where grant funding offsets capital expenditure premiums.
- Commercial:Property management firms and corporate facilities balance aesthetic standards with liability exposure from noise complaints and emissions. Equipment-as-service leasing models gain traction for predictable operational expenditure.
Residential users anchor volume. Landscaping services are climbing the fastest as contract consolidation concentrates procurement authority.
Technology:
Cutting mechanism selection trades speed against precision and line consumption economics.
- Rotary:Single-line spinning heads dominate unit economics through manufacturing simplicity and universal line compatibility. The technology saturates entry-level cordless and gasoline segments where cutting speed outweighs precision requirements.
- Dual-Line:Paired cutting lines increase material removal rates and reduce vibration through balanced rotation. Professional-grade battery platforms from premium manufacturers feature dual-line systems as standard configuration for commercial fleet contracts.
- Fixed Line:Pre-cut line segments eliminate bump-feed mechanism failure points and reduce downtime in high-debris environments. Municipal operators favor fixed-line durability for median and right-of-way maintenance.
- Edging Blade:Metal blades replace filament for woody stem cutting and established sod edge definition. Brush-cutting applications in commercial vegetation management retain blade dependency where line systems would fracture.
Rotary systems command the established base. Dual-line configurations are gaining share fastest through professional-grade battery platform adoption.
Distribution Channel:
Customer type concentration shapes channel economics and working capital requirements for inventory holders.
- Home Improvement Stores:Big-box retail chains anchor mass-market penetration through seasonal promotional cycles and private-label battery platform bundling. Black+Decker and similar brands leverage endcap placement and co-op advertising for replacement cycle capture.
- Online Retailers:Direct-to-consumer channels enable battery ecosystem vendors to bypass distributor margins and capture first-party customer data. Ego and premium cordless specialists use proprietary websites for accessory attachment and battery expansion sales.
- Distributors:Independent dealer networks service commercial fleet accounts with repair parts availability and technician training. Gasoline trimmer legacy brands maintain distributor relationships for small-engine service revenue.
- Garden Centers:Specialty retailers capture high-engagement gardening enthusiasts seeking expert guidance and premium brand curation. Regional chains emphasize battery platform demonstration and seasonal tune-up services.
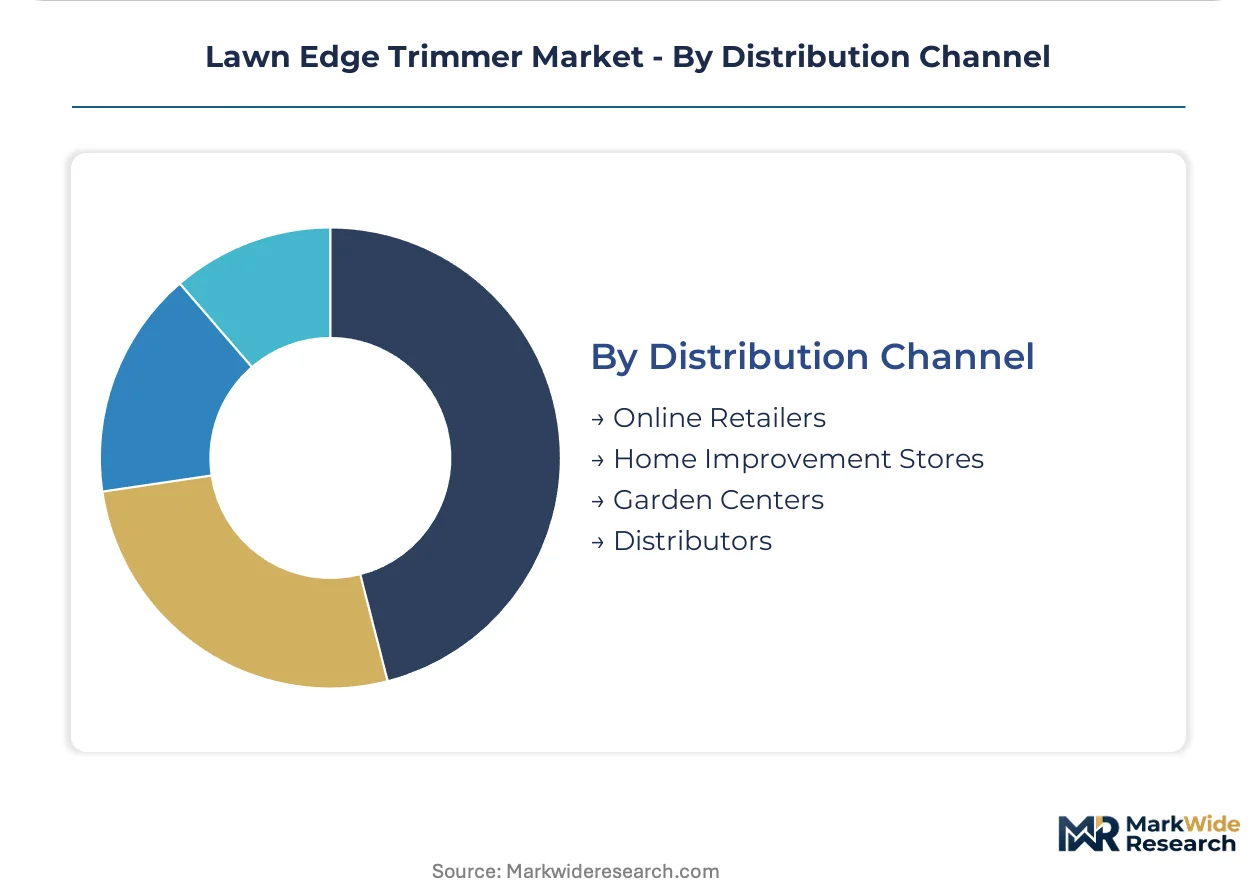
Home improvement stores command the established base. Online retailers are climbing the fastest as battery ecosystem vendors build direct customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of lawn edge trimmer components and finished units, exporting primarily to North American and European retail channels where suburban lawn maintenance sustains import volume.
United States
Suburban lawn culture and large-format retail infrastructure anchor category demand. OSHA noise exposure regulations below 75 decibels accelerate municipal fleet turnover toward electric platforms. The Midwest manufacturing corridor around Chicago hosts distribution centers serving big-box seasonal inventory cycles.
Germany
Precision engineering standards and commercial landscaping density drive professional-grade equipment procurement. REACH chemical regulations constrain gas-powered two-stroke lubricant formulations. The Stuttgart industrial cluster houses battery management system development for cordless platform integration.
China
Component fabrication and brushless motor assembly concentrate manufacturing output for global export. MIIT industrial policy incentivizes lithium-ion cell capacity expansion for power tool applications. The Yangtze River Delta around Shanghai exports finished cordless trimmers to North American and European buyers.
Australia
Underpenetrated cordless adoption relative to comparable markets creates whitespace for battery ecosystem expansion. State-level noise restrictions in New South Wales and Victoria limit gas-powered equipment in residential zones. Sydney and Melbourne metropolitan areas concentrate landscaping service contract density.
Canada
Seasonal lawn maintenance patterns and urban green space mandates sustain replacement cycle volume. Health Canada and PMRA emission guidelines align with tightening EPA standards for small engines. The Toronto-Waterloo corridor hosts retail distribution infrastructure serving Ontario's suburban markets.
Lawn Edge Trimmer Market Competitive Landscape
On the supply side, the industry is bifurcated between mass-market battery ecosystem vendors and legacy gasoline equipment manufacturers. Consolidation pressure concentrates around battery platform standardization and retail channel control. Two strategic archetypes dominate: cordless specialists with proprietary voltage architectures, and diversified power equipment conglomerates with multi-fuel portfolios. Competitive moves center on exclusive retail partnerships and backward integration into battery cell sourcing.
Within the cordless specialist tier, Ego and Greenworks exemplify voltage-differentiated positioning, while Black+Decker anchors mass-market penetration through big-box retail scale. Husqvarna occupies a position bridging professional-grade battery systems with Nordic engineering heritage. These three represent distinct competitive vectors: proprietary battery architecture, retail accessibility, and commercial durability certification.
| Leading Market Players |
|---|
| Echo |
| Black+Decker |
| Ego |
| Greenworks |
| Craftsman |
| Worx |
| Husqvarna |
| Hart |
| Maxlander |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta brushless motor foundries concentrate manufacturing capacity for lithium-ion lawn edge trimmers, anchoring margin capture in battery pack assembly and proprietary voltage architecture licensing downstream. Cobalt and lithium cell chemistry costs transmit directly to OEM pricing power, while EPA emission compliance burdens on gasoline units compress legacy pricing flexibility.
Pricing Analysis
Current-generation 56V and 80V cordless platforms command premium positioning over prior-generation 20V-40V residential tiers and next-generation solid-state battery concepts still in development. Three-tier pricing structure across premium, standard, and economy levels separates professional-grade dual-line systems with interchangeable fleet batteries from entry-level single-line cordless units and residual gasoline models. Price differentiation hinges on runtime certification and OSHA sub-75-decibel compliance tier. Cost compression in gasoline segments is intensifying because catalytic converter miniaturization investments erode margin without commensurate feature premiums. Residential homeowners exhibit highest price sensitivity, while municipal procurement officers prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
Contract manufacturing concentration sits with Shenzhen and Suzhou-based EMS providers holding dedicated power tool assembly lines for North American retail brands. Component sourcing draws from China for brushless motors and battery management systems, South Korea for lithium-ion cells, and Japan for precision bearings and magnetic materials. Raw material dependencies center on cobalt from the Democratic Republic of Congo, lithium from Chile and Australia, and rare-earth magnets from China's Inner Mongolia processing corridor. Single-source vulnerability in battery cell supply creates exposure to geopolitical export restrictions. Distribution runs through seasonal big-box retail allocation systems and direct-to-consumer battery ecosystem portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a battery-platform network-effect story where fleet standardization creates switching costs that entrench early ecosystem movers. Regulatory entrenchment through CARB zero-emission mandates and OSHA noise thresholds reinforces platform durability.
For Market Incumbents: Build battery-platform network effects by expanding 56V and 80V ecosystem interoperability across mowers, blowers, and trimmers to deepen fleet switching costs. Secure exclusive retail endcap placement ahead of seasonal inventory cycles to compress challenger access. Solid-state battery chemistry substitution threatens runtime leadership positions. Backward integration into battery cell sourcing reduces cobalt price volatility exposure. For New Entrants and Emerging Players: Underpenetrated commercial landscaping contracts in Australia and Canada represent the most penetrable entry point for 56V-class battery ecosystem rollouts. Municipal procurement white space under state-level zero-emission equipment mandates offers concentrated volume without incumbent brand loyalty. Direct-to-consumer demonstration programs bypass big-box margin extraction and capture first-party usage data for product iteration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cordless specialists holding proprietary voltage architectures but lacking multi-category platform breadth. Five-to-ten-year viability hinges on battery recycling infrastructure maturity and right-to-repair legislative positioning. Acquisition targets should demonstrate captive dealer-service networks or exclusive retail partnerships as defensive moats. Watch CARB mandate expansion into additional state jurisdictions as inflection signal for gasoline platform abandonment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interoperable 56V/80V ecosystems reduce fleet complexity for landscaping services consolidating procurement. |
| Backward Integration into Cell Sourcing | Captive lithium-ion supply insulates margin from cobalt price volatility and ESG compliance burdens. |
| Closed-Loop Battery Recycling | Extended producer responsibility frameworks in California and EU jurisdictions create aftermarket revenue streams. |
| Direct-to-Consumer Channel Expansion | Proprietary websites bypass distributor margins and capture usage data for attachment sales. |
| OSHA-Compliant Product Certification | Sub-75-decibel validation unlocks municipal contract eligibility under federal noise exposure regulations. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation across regulatory and trade databases. Primary interviews encompassed product development directors at cordless platform vendors, procurement managers at commercial landscaping services, aftermarket service technicians at independent dealer networks, and regulatory compliance officers at EPA and CARB. Secondary sources integrated EPA small engine emission filings, OSHA noise exposure enforcement data, customs import records for lawn equipment, and SEC 10-K disclosures from listed power equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Forecast inputs incorporated technology transition curves for brushless motor adoption, battery energy density improvement trajectories, and regulatory phase-in schedules across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, cutting technology, and distribution channel. CAGRs derived from logistic diffusion curves fitted to cordless platform replacement cycles and gasoline fleet turnover rates. Industry-specific inputs encompassed lithium-ion cell cost decline curves and municipal grant funding availability for zero-emission equipment procurement.
Practitioners should monitor cobalt supply disruptions, CARB mandate adoption in additional states, and solid-state battery commercialization timelines for early signals of forecast revision. Forecasts reflect assumptions regarding continued lithium-ion cost declines and regulatory enforcement consistency. Quarterly review of battery raw material spot prices and municipal procurement grant disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
South America Irrigation Machinery Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Drip Irrigation Market