
 Smart Irrigation Controllers Market | 2026-2036
Smart Irrigation Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Irrigation Controllers Market Outlook
Israeli precision agriculture manufacturers is restructuring supply chains for sensor-integrated controllers after sustained semiconductor sourcing stress. Rain Bird Corporation leverages its dominance in commercial landscape channels across North American golf and municipal segments. Hunter Industries anchors its position through deep backward integration into valve and rotor manufacturing. Jain Irrigation Systems competes on geographic reach, with extensive field operations across India and emerging markets.
Smart irrigation controllers are automated devices that regulate water delivery to landscapes or crops by processing real-time inputs from soil moisture sensors, weather feeds, or evapotranspiration models, typically operating through solenoid-actuated zone valves with flow rates calibrated to specific plant coefficients. Their primary commercial purpose is to reduce consumptive water use while maintaining agronomic or aesthetic outcomes through algorithm-driven scheduling. Weather-based controllers capture the dominant share of residential and light commercial deployments due to lower installed cost and minimal sensor maintenance. Sensor-based systems command premium positioning in high-value crop applications where soil heterogeneity demands granular zone control. Cloud-based technology architecture is displacing standalone timer units as firmware updates and remote diagnostics become baseline expectations.
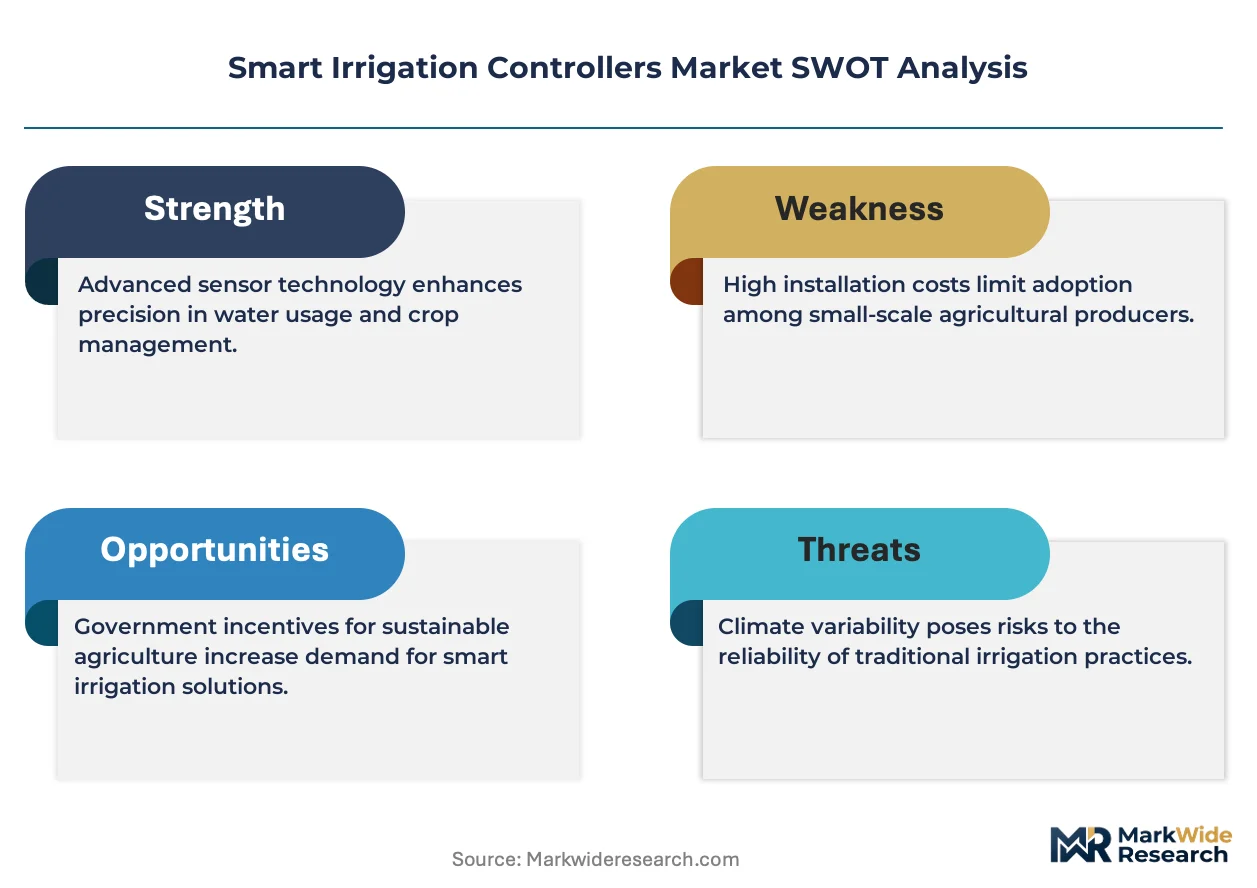
EPA WaterSense labeling shapes product eligibility for utility rebate programs across the United States, directly conditioning market access for residential and commercial entrants. California's CII regulations and Israel's national water efficiency standards enforce minimum performance thresholds that filter out non-connected mechanical timers. The EU Green Deal's water scarcity roadmap and Australia's WELS-equivalent irrigation ratings are converging toward interoperable data protocols. Stakeholders must monitor whether emerging interoperability mandates fragment platform ecosystems or consolidate vendor control over data layer monetization.
Market Dynamics
Cloud-native firmware architectures are compressing replacement cycles for standalone timer hardware while EPA WaterSense rebate eligibility requirements hardwire connectivity into baseline product specifications across US residential channels.
Growth Catalysts
- EPA WaterSense Labeling:Utility rebate programs in drought-stressed US states restrict eligibility to certified connected controllers, pulling residential upgrades forward.
- Soil heterogeneity in high-value crops:California almond and vineyard operators deploy sensor-based zone controllers to manage consumptive water allocations under SGMA groundwater sustainability mandates.
- Israeli precision agriculture export infrastructure:Decades of national water scarcity policy have created a concentrated supplier base with proven arid-climate controller performance.
Market Restraints
- Semiconductor sourcing volatility:Sustained tightness in MEMS moisture sensor and wireless SoC supply chains extends lead times for Israeli and US manufacturers.
- Mechanical timer installed base:Decades of durable electromechanical irrigation timers in existing landscapes create functional substitution resistance among cost-sensitive property managers.
- Interoperability protocol fragmentation:Proprietary cloud platforms from dominant valve manufacturers lock data layers, complicating third-party controller integration.
Strategic Opportunities
- India's fragmented agricultural water governance:State-level groundwater extraction limits in Maharashtra and Gujarat create regulatory pull for subsidized precision irrigation deployment.
- LoRaWAN-5G convergence:Low-power wide-area networks combined with cellular backhaul enable controller deployments in remote agricultural zones without Wi-Fi infrastructure.
- CII commercial landscape mandates:California's commercial, industrial, and institutional water efficiency regulations force retrofits of municipal and golf course irrigation infrastructure.
Industry Challenges
- Field calibration expertise scarcity:Proper evapotranspiration model tuning and soil sensor placement require agronomic training that distributor networks often lack.
- Legacy two-wire system compatibility:Existing buried valve wiring in mature landscapes constrains controller replacement options to backward-compatible architectures.
- EPA certification timeline compression:WaterSense testing protocols and documentation requirements extend product launch cycles for firmware-dependent feature updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Irrigation Controllers Market |
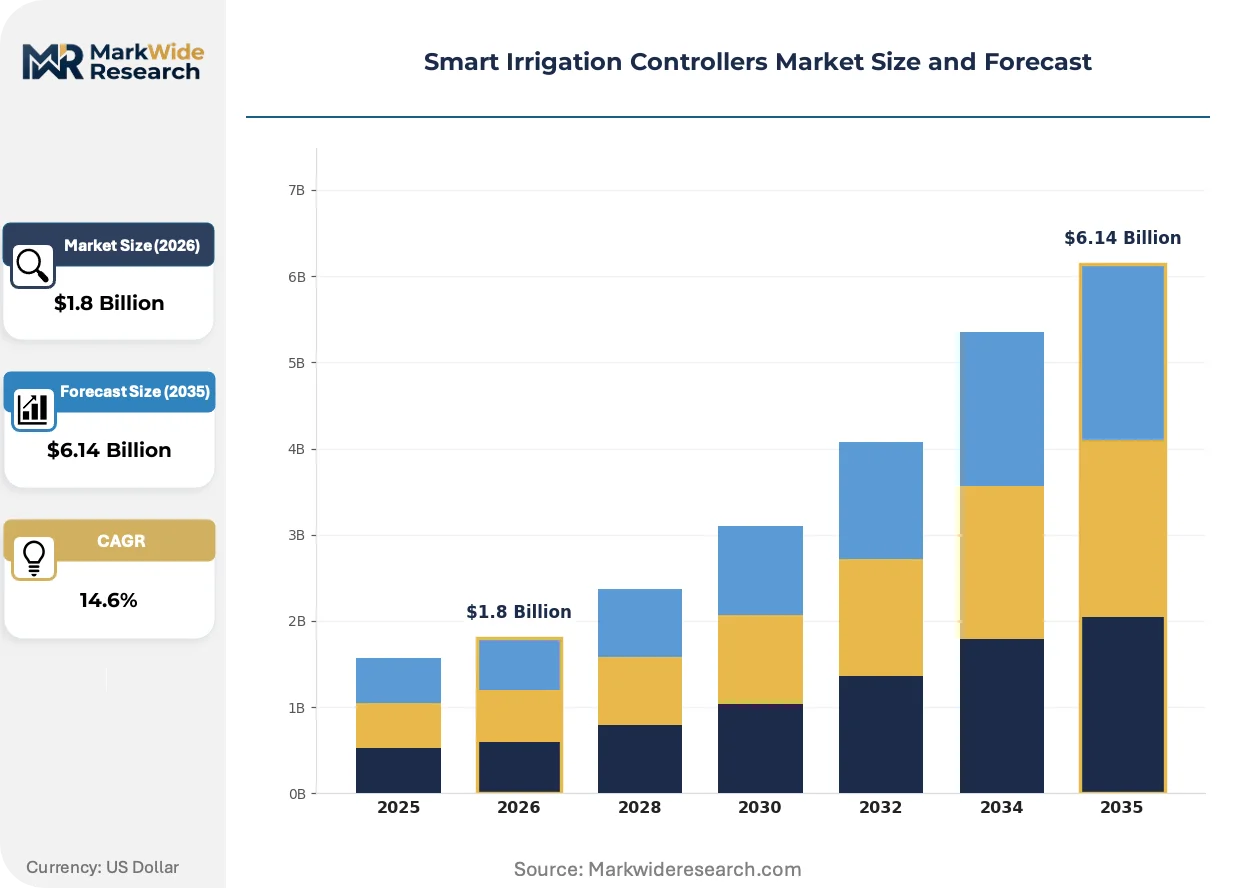
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather-Based, Sensor-Based, Timers, Smart Remotes Technology: Wireless, Wired, Cloud-Based, Satellite End User: Agricultural Producers, Residential Users, Commercial Landscapers, Institutions Application: Crop Irrigation, Lawn Care, Landscape Maintenance, Greenhouse Management |
| Companies Covered | Rain Bird Corporation, Hunter Industries, The Toro Company, Netafim Ltd., HydroPoint Data Systems, Inc., Jain Irrigation Systems, Ltd., Valmont Industries, Inc., Rachio, Inc., Weathermatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Irrigation Controllers Market Strategic Shifts
Algorithmic water scheduling is migrating from standalone devices to platform-embedded services, restructuring how hardware vendors capture value and how buyers evaluate total cost of ownership across multi-year deployment horizons.
Edge-computing soil moisture inference is converging with satellite-derived evapotranspiration data to enable sub-field irrigation prescriptions without dense sensor networks. Large-scale row-crop operators in Australia's Murray-Darling Basin are piloting these fused data streams to comply with basin plan water recovery targets. The convergence is compressing the price-performance gap between weather-based and sensor-based controller categories.
EU Green Deal water scarcity roadmaps are tightening interoperability requirements for connected water management devices sold in member states. The industrial consequence is pressure on proprietary cloud platforms to adopt open data protocols or risk exclusion from public procurement. Agricultural cooperatives in Spain and Italy are prioritizing controllers with documented API access for farm management system integration.
Subscription service models are displacing perpetual-license software sales among commercial landscape management firms. US golf course superintendents and municipal parks departments now expect remote diagnostics, seasonal algorithm updates, and consumables replenishment bundled into annual contracts. This shift concentrates purchasing authority with national facility management companies negotiating enterprise-wide platform agreements.
Smart Irrigation Controllers Market Segmentation
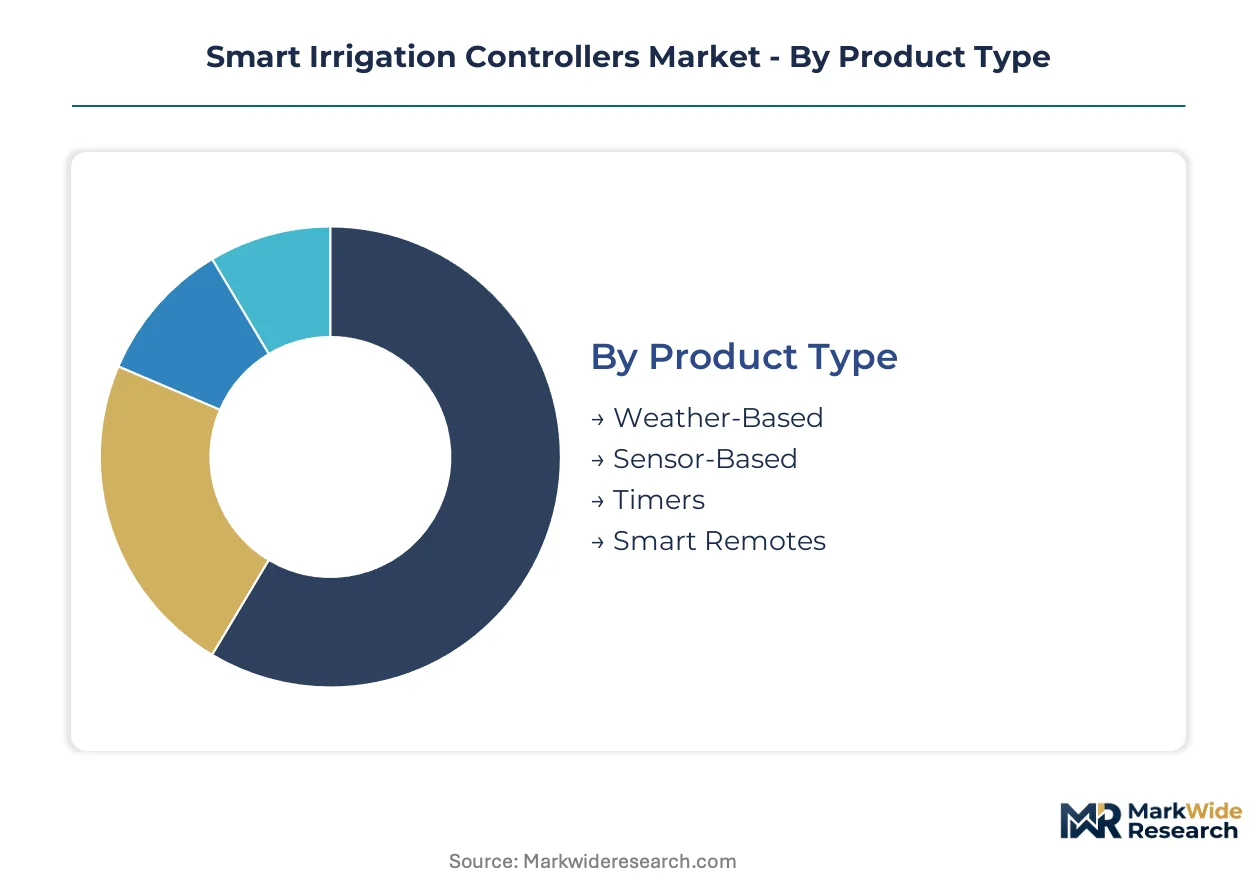
Segmentation in smart irrigation controllers reveals how hardware specifications, connectivity architectures, and user sophistication determine upgrade pathways from electromechanical timers to connected systems. Replacement cycles vary dramatically across these dimensions, with some categories compressing to 3-5 years while others extend beyond a decade.
Product Type:
Upgrade urgency and payback clarity separate the replacement trajectories across controller categories, with rebate eligibility and water cost exposure driving differential adoption velocity.
- Weather-Based:These controllers calculate evapotranspiration rates using local meteorological data feeds and historical plant coefficients to adjust watering schedules automatically. Residential demand concentrates in California, Texas, and Arizona where tiered municipal water pricing creates 18-24 month payback periods for EPA WaterSense-certified units.
- Sensor-Based:Direct soil moisture measurement through capacitance or tensiometric probes enables zone-level precision for heterogeneous terrain. California almond growers and vineyard operators deploy these under SGMA groundwater sustainability mandates to document consumptive use reductions for basin compliance.
- Timers:Electromechanical and basic digital interval timers persist in cost-sensitive residential retrofits and legacy commercial installations where Wi-Fi infrastructure is absent.
- Smart Remotes:Handheld or app-connected activation devices extend functionality to existing valve systems without full controller replacement.
Weather-Based controllers sit at the top of the volume ranking, with Sensor-Based climbing the fastest as agricultural water accounting requirements tighten.
Technology:
Connectivity infrastructure maturity determines deployment feasibility across remote agricultural zones and dense urban landscapes alike.
- Wireless:Wi-Fi, Bluetooth, and proprietary RF protocols dominate residential and light commercial installations where router proximity is assured. LoRaWAN expansion is opening rural agricultural corridors previously unreachable.
- Wired:Two-wire decoder systems and traditional multi-wire valve connections persist in municipal golf courses and institutional landscapes where electromagnetic interference or physical security concerns disqualify over-the-air protocols.
- Cloud-Based:Firmware-over-the-air updates, remote diagnostics, and algorithm refinements now constitute baseline expectations among commercial landscape management firms negotiating enterprise service contracts.
- Satellite:Direct-to-controller messaging enables operation in cellular dead zones across Australian pastoral operations and Israeli desert agriculture where terrestrial infrastructure is uneconomical.
Cloud-Based architectures are displacing standalone operation fastest, while Satellite maintains niche positioning for extreme remoteness.
End User:
Technical sophistication and procurement authority shape how controller capabilities translate to documented water savings and operational outcomes.
- Agricultural Producers:Large-scale operators in Australia's Murray-Darling Basin and California's Central Valley demand API-accessible platforms for integration with farm management systems and regulatory reporting.
- Residential Users:Utility rebate programs in drought-stressed US states pull upgrades forward among homeowners with existing in-ground sprinkler infrastructure.
- Commercial Landscapers:National facility management companies negotiate enterprise-wide platform agreements bundling hardware, connectivity, and seasonal algorithm updates.
- Institutions:Municipal parks departments and university campuses face CII retrofit mandates in California while managing legacy two-wire valve wiring constraints.
Agricultural Producers command the steepest expansion trajectory as groundwater accounting requirements proliferate, with Residential Users providing the installed volume base.
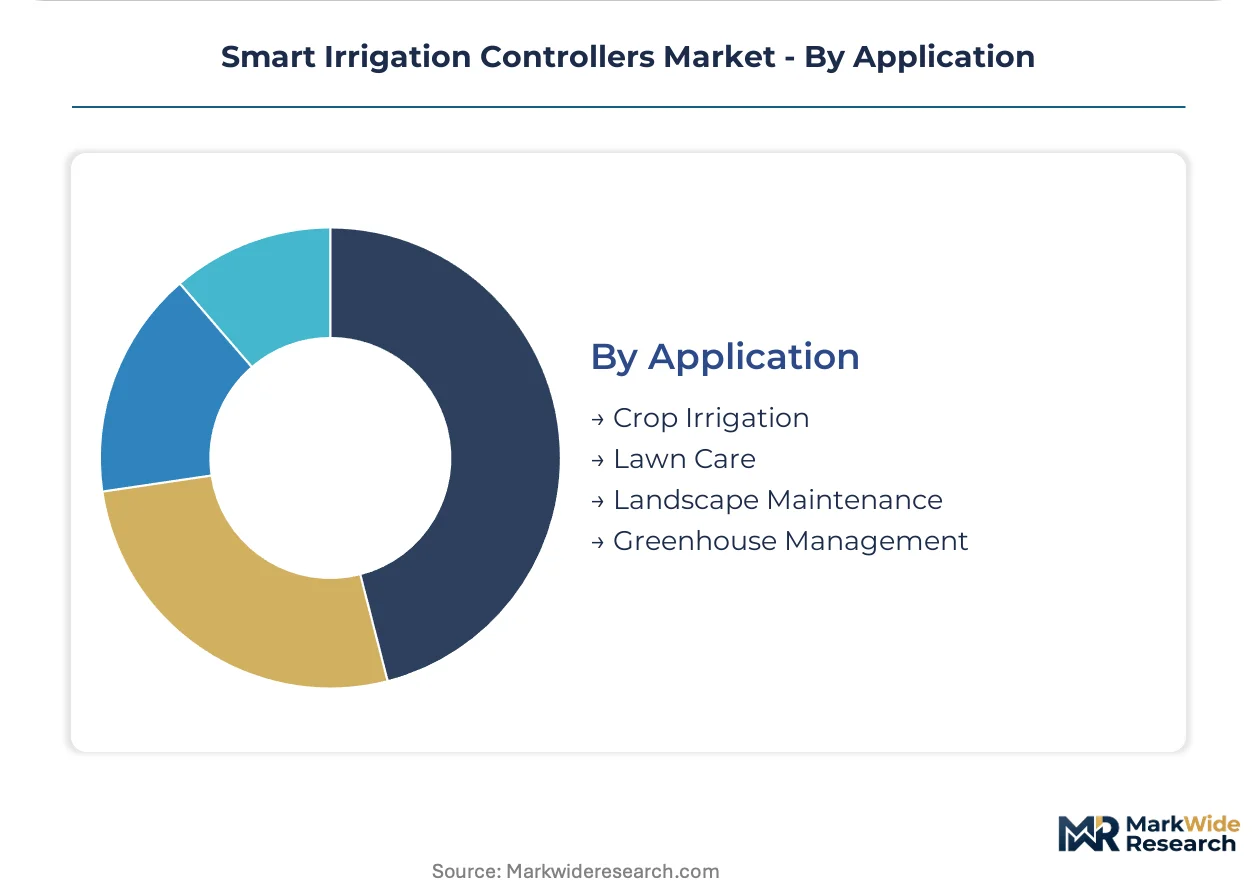
Application:
Value per acre-foot of water saved varies enormously across these use cases, determining acceptable controller cost thresholds and sensor density.
- Crop Irrigation:High-value permanent crops justify dense sensor networks and sub-field prescription capabilities that weather-based systems cannot deliver.
- Lawn Care:Uniform turf requirements and homogeneous soil conditions favor simpler weather-based controllers with minimal calibration demands.
- Landscape Maintenance:Mixed plantings with varying coefficients create zone complexity that drives demand for multi-station programmable units.
- Greenhouse Management:Controlled environment agriculture integrates irrigation controllers with climate computers, requiring standardized data protocols for system interoperability.
Crop Irrigation leads absolute spending on controller hardware and integration services, with Greenhouse Management gaining share fastest through controlled environment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as Israeli precision agriculture suppliers absorb semiconductor sourcing stress while California's tiered compliance costs push assembly toward lower-cost jurisdictions with equivalent certification capacity.
United States
EPA WaterSense rebate eligibility and California's CII mandates pull residential and commercial upgrades forward. Tiered municipal water pricing in Arizona, Texas, and Nevada compresses payback periods to 18-24 months. The Central Valley agricultural cluster drives sensor-based controller demand under SGMA groundwater accounting requirements.
Israel
National water scarcity policy spanning decades created concentrated supplier expertise in arid-climate controller performance. The country's national water efficiency standards enforce minimum connectivity thresholds that filter out mechanical timers. Precision agriculture manufacturers in the Negev Desert region are restructuring supply chains after sustained MEMS sensor sourcing volatility.
Australia
Murray-Darling Basin water recovery targets force large-scale row-crop operators toward algorithmic irrigation scheduling. The country's WELS-equivalent irrigation ratings are converging toward EU interoperability protocols. Queensland and New South Wales pastoral zones pilot satellite-to-controller messaging in cellular dead zones.
India
State-level groundwater extraction limits in Maharashtra and Gujarat create regulatory pull for subsidized precision irrigation deployment. The country's Bureau of Indian Standards is developing connected water management device certifications aligned with EU Green Deal roadmaps. Jain Irrigation Systems anchors field operations across the Deccan Plateau agricultural belt.
Germany
EU Green Deal water scarcity mandates tighten interoperability requirements for connected devices sold across member states. The country's industrial machinery base supplies valve and actuator components to Israeli and US controller manufacturers. Bavarian agricultural cooperatives prioritize API-accessible platforms for farm management system integration.
Smart Irrigation Controllers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cloud-native service models and subscription revenue streams. The vendor base stratifies across three functional layers: valve and rotor manufacturers with captive controller lines, standalone connectivity specialists, and agricultural system integrators bundling hardware with agronomic advisory. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion through distributor acquisition in water-stressed jurisdictions.
Among North American landscape irrigation specialists, Rain Bird Corporation and Hunter Industries exemplify divergent strategic positions. Rain Bird leverages dominance in commercial golf and municipal channels through deep backward integration into valve manufacturing. Hunter Industries anchors its market presence through in-house production of rotors and spray heads. Israeli precision agriculture supplier Netafim Ltd. occupies a distinct position as an agricultural system integrator with proven arid-climate controller performance.
| Leading Market Players |
|---|
| Rain Bird Corporation |
| Hunter Industries |
| The Toro Company |
| Netafim Ltd. |
| HydroPoint Data Systems, Inc. |
| Jain Irrigation Systems, Ltd. |
| Valmont Industries, Inc. |
| Rachio, Inc. |
| Weathermatic |
| Others |
Value Chain & Pricing Dynamics
Cloud-native firmware architectures are compressing replacement cycles for standalone timer hardware while simultaneously concentrating manufacturing among suppliers with captive sensor production capabilities. This technology shift elevates the cost premium for EPA WaterSense-certified units against basic electromechanical alternatives, tightening margin structures for distributors without backward integration into valve or sensor manufacturing.
Pricing Analysis
Distributor margins in the residential channel typically absorb 25-35 points before utility rebate programs reduce net consumer outlays. Pricing stratifies across premium sensor-based controllers, standard weather-based units, and economy-grade connected timers with limited zone capacity. Cost compression in the economy tier intensifies because Chinese manufacturers are flooding the market with uncertified Wi-Fi-enabled alternatives. Agricultural producers in California's Central Valley exhibit the lowest price sensitivity, while residential homeowners in Texas and Arizona respond aggressively to post-rebate net costs.
Supply Chain Analysis
India's Bureau of Indian Standards certification requirements and domestic-content preferences in Maharashtra and Gujarat are reshaping sourcing patterns for controller assembly destined for South Asian markets. Semiconductor fabrication concentrates in Taiwan, South Korea, and Israel, with MEMS moisture sensors and wireless SoCs drawing from these concentrated production hubs. Single-source vulnerability in MEMS foundry capacity extends lead times for Israeli and US manufacturers during demand surges. Distribution runs through irrigation specialty wholesalers in agricultural corridors and big-box retailers in residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory mandates for water efficiency create non-discretionary replacement demand across drought-stressed jurisdictions. Tiered municipal water pricing and groundwater sustainability accounting ensure sustained upgrade pull regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin compression from Chinese connectivity specialists entering through uncertified channels by deepening backward integration into soil sensor manufacturing. Defensive consolidation of distributor relationships in California's CII-mandated commercial landscape segment protects pricing power against cloud-native challengers bundling subscription diagnostics. For New Entrants and Emerging Players: Edge-computing soil moisture inference without dense sensor networks offers a technology-first wedge into Australia's Murray-Darling Basin compliance-driven row-crop segment. Target India's fragmented state-level groundwater governance for white-space penetration, deploying LoRaWAN-enabled controllers through agricultural cooperative procurement channels rather than retail distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier connectivity specialists lacking captive valve manufacturing but possessing proven API integration with farm management platforms. Five-to-ten year viability hinges on regulatory interoperability mandates consolidating platform ecosystems rather than fragmenting them. Watch EPA WaterSense protocol updates as the inflection signal for which cloud architectures achieve durable standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive MEMS supply secures margin protection against foundry volatility for Israeli and US incumbents. |
| LoRaWAN-5G Convergence Deployment | Low-power wide-area connectivity unlocks remote agricultural zones beyond Wi-Fi infrastructure reach. |
| API-First Platform Architecture | Open data protocols satisfy EU Green Deal interoperability mandates and Spanish cooperative procurement requirements. |
| Subscription Service Model Transition | Annual contracts bundling diagnostics and algorithm updates concentrate purchasing with national facility management firms. |
| State-Level Regulatory Arbitrage | Early certification alignment with India's BIS standards captures subsidized deployment in Maharashtra groundwater districts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with irrigation controller product managers, agricultural cooperative procurement officers, municipal water utility rebate administrators, and commercial landscape facility directors with secondary validation against EPA WaterSense certification databases, California Department of Water Resources SGMA compliance filings, Israeli Ministry of Agriculture export statistics, and Bureau of Indian Standards draft connected device specifications. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations across technology and end-user segments.
Segment-weighting applied differential growth coefficients to weather-based controllers, sensor-based systems, and cloud-connected architectures over the projection horizon, with installation channel splits modeled separately for residential rebate-driven upgrades versus agricultural compliance-mandated deployments. CAGRs derived from fitted trend analysis incorporating regulatory timeline acceleration, semiconductor supply elasticity assumptions, and water pricing trajectory sensitivity. Forecast inputs included EPA WaterSense label adoption curves and SGMA groundwater basin sustainability plan implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interoperability protocol standardization, MEMS foundry capacity expansion, and state-level groundwater governance enforcement intensity in India and Australia. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Smart Farming Technology Market
Smart Agriculture
Smart Cattle Market
Smart Agriculture
Smart Farming Machine Market
Smart Agriculture
IoT in Smart Farming Market
Smart Agriculture
Global AI in Agriculture Market
Smart Agriculture
Non-Agriculture Smart Irrigation Controllers Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Smart Agricultural Drone Market
Smart Agriculture
Smart Tap Timer Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Micro-Irrigation Systems Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Europe Agrivoltaics Market