
 Ride-On Mower Market | 2026-2036
Ride-On Mower Market Size, Share, and Industry Trends Forecast 2026-2036
Ride-On Mower Market Outlook
Commercial landscaping is expanding its share of ride-on mower procurement as property management firms consolidate vendor relationships and prioritize equipment uptime. Deere & Company leverages its dealer network density to anchor fleet sales in North American municipal contracts. Husqvarna Group competes through battery-electric specialization in European markets where noise ordinances tighten. Kubota Corporation dominates compact diesel configurations for agricultural estates requiring multi-terrain capability.
A ride-on mower is a self-propelled cutting machine with an operator seat, typically housing engines from 15 to 40 horsepower and cutting decks spanning 30 to 72 inches, designed to maintain turf across residential lawns, commercial grounds, and sports fields. Zero-turn models command premium positioning due to maneuverability advantages on obstacle-dense properties, while lawn tractors sustain volume leadership through residential replacement cycles. The 20-30 HP engine power band captures the widest buyer base, spanning estate owners and mid-sized landscaping contractors seeking balance between fuel efficiency and cutting throughput.
EPA small engine emissions regulations and EU F-Gas restrictions on refrigerants in related outdoor power equipment are reshaping powertrain development timelines and import certification requirements. OSHA landscaping safety directives influence rollover protection and blade engagement standards for commercial operators. Stakeholders must monitor battery platform interoperability and charging infrastructure deployment as electrification transitions from niche to fleet-viable economics.
Market Dynamics
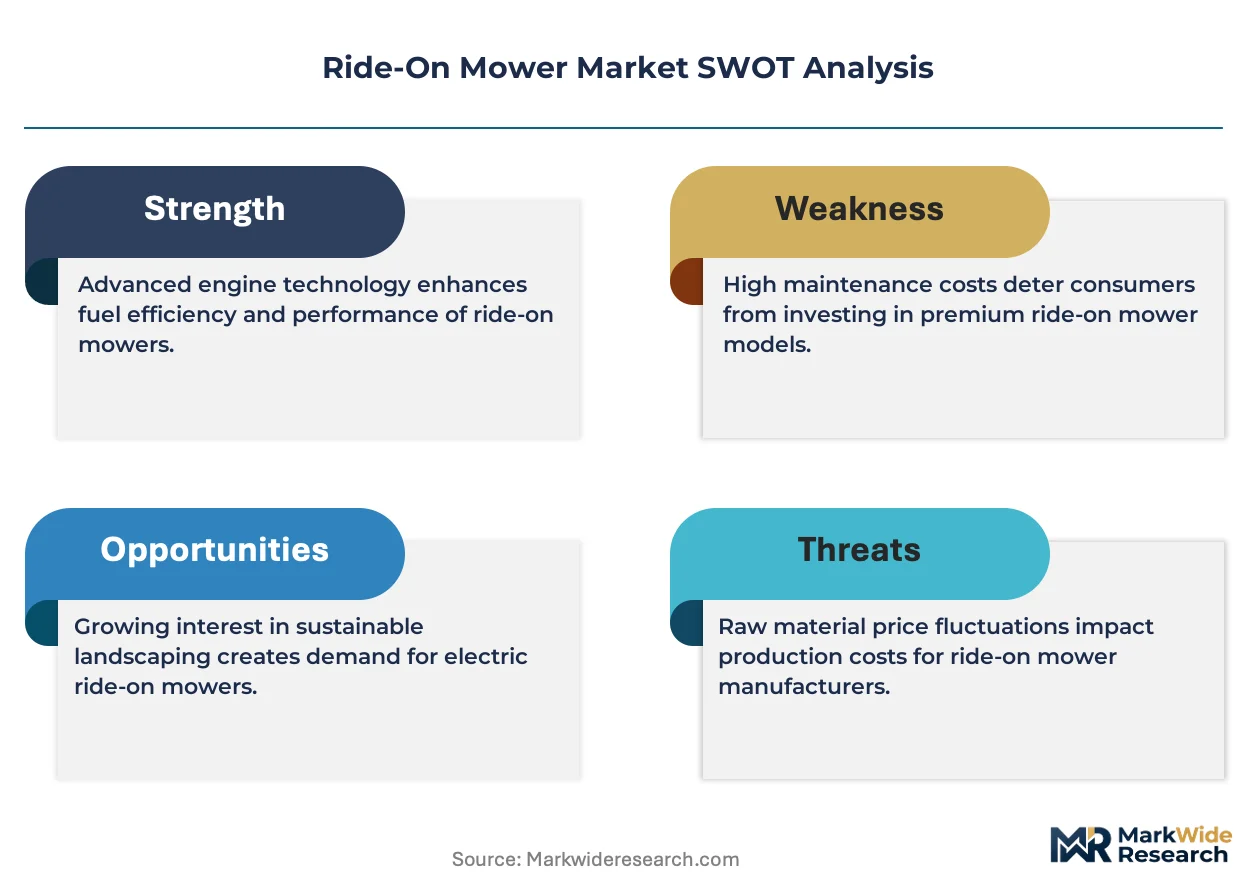
The ride-on mower sector faces a structural pivot as EPA Phase 3 emissions standards for small spark-ignition engines force simultaneous retooling of fuel injection architectures and acceleration of battery-electric platform development across all power classes.
Growth Catalysts
- Commercial landscaping fleet expansion:Property management firms consolidate vendor relationships and prioritize equipment uptime through standardized fleet procurement, driving volume commitments for zero-turn and stand-on configurations.
- EU F-Gas Regulation:Refrigerant restrictions on related outdoor power equipment are pushing European manufacturers toward closed-loop thermal management systems that favor electrified powertrains.
- Golf course infrastructure renewal:Municipal and private course operators in the United States are compressing replacement cycles for fairway maintenance equipment to address labor availability constraints.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing remains concentrated among East Asian cell manufacturers, creating input cost volatility and qualification timeline risks for Western OEMs scaling electric platforms.
- Small engine foundry capacity:Casting and machining capacity for gasoline engine blocks is consolidating in lower-cost manufacturing regions, raising freight and tariff exposure for brands maintaining North American assembly.
- OSHA rollover protection mandates:Commercial operator safety standards add structural cost to frame engineering and limit design flexibility for compact zero-turn architectures.
Strategic Opportunities
- Battery platform interoperability:Shared voltage architectures across handheld, walk-behind, and ride-on equipment categories enable cross-product charging infrastructure and reduce fleet operator total cost of ownership.
- Robotic autonomy convergence:Integration of RTK-GPS navigation with electric drive systems creates perimeter-mowing automation for solar farms and airport buffer zones.
- India estate agriculture mechanization:Large landholding consolidation in Punjab and Haryana is generating first-time demand for compact diesel ride-on mowers as sugarcane and fodder crop maintenance tools.
Industry Challenges
- Power electronics thermal management:Electric drive inverters and motor controllers for 40 HP-equivalent continuous output require liquid cooling architectures that demand new supplier qualifications and assembly process investments.
- Dealer technician electrification training:High-voltage system certification programs are creating bottlenecks in service network expansion, particularly for independent dealerships serving rural markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ride-On Mower Market |
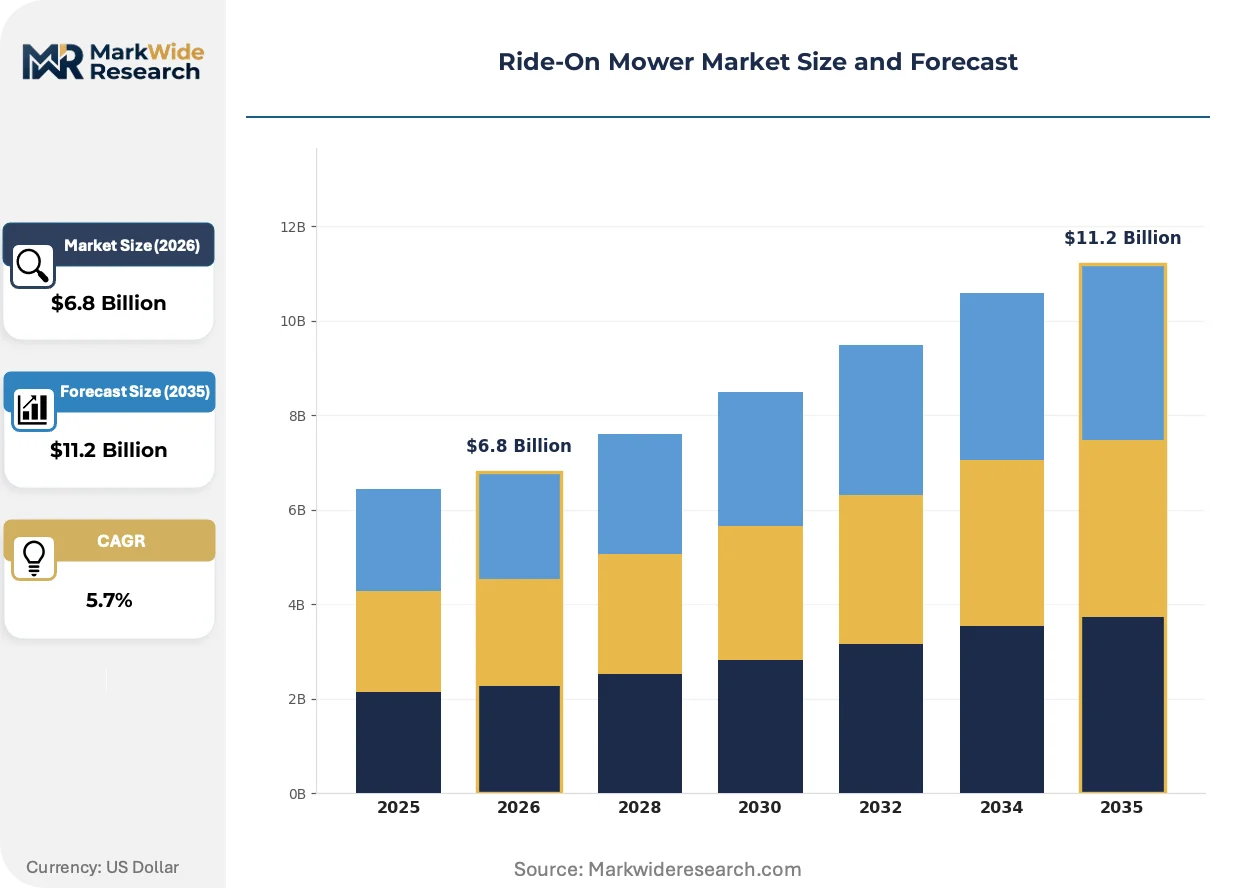
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Zero Turn, Garden Tractor, Lawn Tractor End User: Residential, Commercial, Agricultural, Landscapers Engine Power: Less than 20 HP, 20-30 HP, 30-40 HP, More than 40 HP Drive Type: Rear-Wheel Drive, Front-Wheel Drive, All-Wheel Drive, Hydrostatic |
| Companies Covered | Deere & Company, Husqvarna Group, The Toro Company, Kubota Corporation, Stanley Black & Decker, Ariens Company, Honda Motor Co., Ltd., Briggs & Stratton, STIGA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ride-On Mower Market Strategic Shifts
Powertrain architecture is splitting along regulatory fault lines, with gasoline direct injection and battery-electric platforms advancing in parallel rather than sequentially, compressing development resource allocation across engineering teams.
Lithium-iron-phosphate battery packs with active thermal management are replacing lead-acid and nickel-manganese-cobalt alternatives in commercial zero-turn mowers. Landscaping contractors operating 10-plus unit fleets in Florida and Texas are adopting these configurations to eliminate fuel logistics and reduce morning startup delays. Battery-electric powertrains is electrifying the 20-30 HP equipment class where daily runtime requirements previously favored internal combustion.
EPA Phase 3 exhaust emission standards for Class II engines are mandating closed-loop fuel injection and catalytic aftertreatment on all new gasoline models above 19 kW. Engine manufacturers are responding with port and direct injection hybrid architectures that preserve power density while meeting hydrocarbon limits. The 25-35 HP lawn tractor segment faces the steepest compliance cost escalation as these systems add assembly complexity and warranty exposure.
Equipment-as-a-service contracting is displacing traditional capital purchase and lease structures among multi-site property management firms. Third-party fleet operators in the United States are bundling machines, maintenance, and seasonal storage into per-acre pricing, transferring utilization risk from landscape contractors to specialized lessors. This model concentrates most rapidly in metropolitan corridor markets where labor scheduling optimization outweighs asset ownership preferences.
Ride-On Mower Market Segmentation
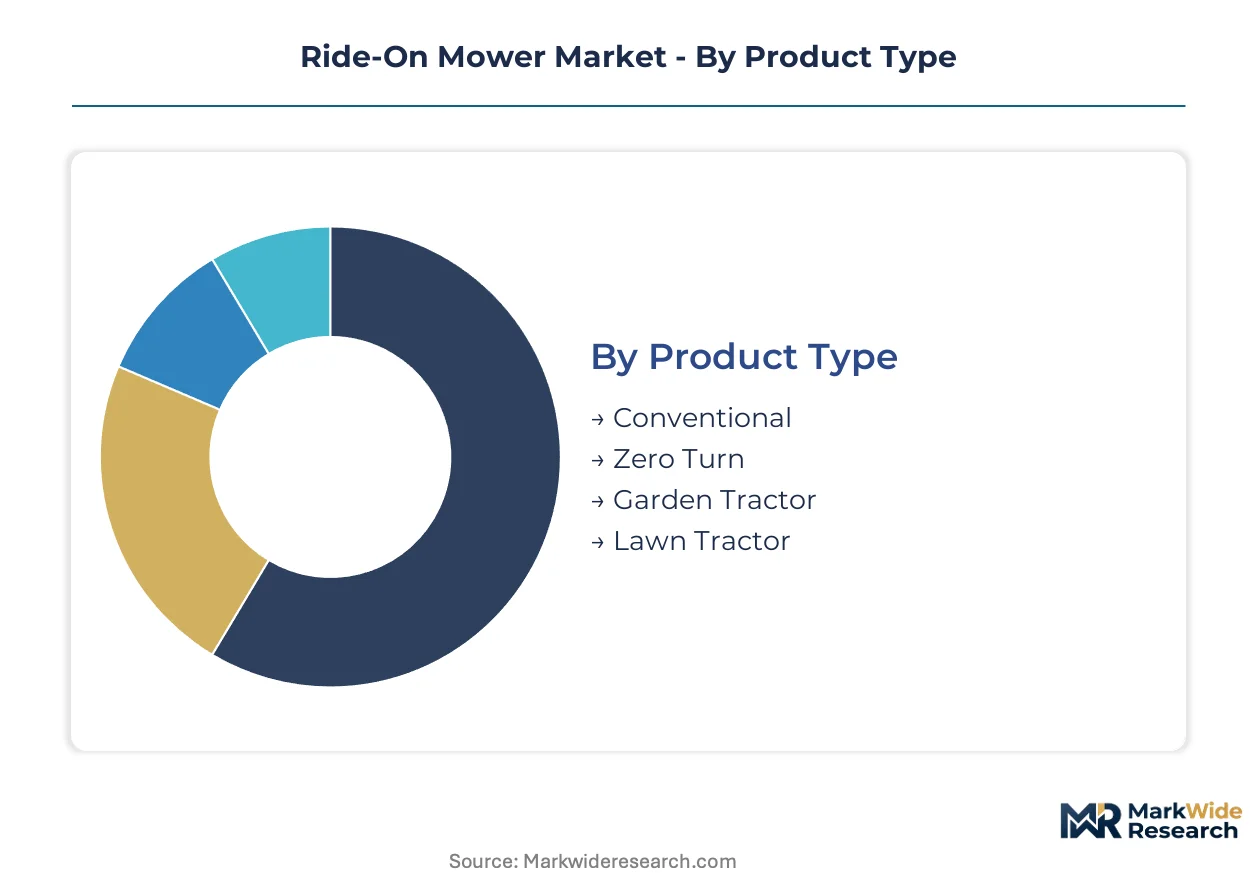
Segmentation in ride-on mowers reflects divergent equipment economics across property scales and operational intensity. Procurement patterns split sharply between homeowners prioritizing purchase price and commercial fleets optimizing lifetime operating cost.
Product Type:
Supply concentration tilts toward manufacturers with dedicated fabrication lines for high-maneuverability architectures.
- Zero Turn:Dual-hydrostatic drive systems enable independent wheel control for tight-radius cutting around landscape obstacles. Municipal golf courses in Florida and Texas specify these configurations to reduce labor hours per acre.
- Lawn Tractor:Front-engine layouts with manual or automatic transmissions dominate residential replacement cycles through dealer network availability and attachment compatibility. Estate owners across the US Midwest favor these units for snow-blower and cart hauling versatility.
- Conventional:Rear-engine designs persist in entry-level European markets where compact storage dimensions outweigh cutting speed priorities.
- Garden Tractor:Heavy-duty frame constructions support ground-engaging implements for small-scale agricultural estates requiring tillage and cultivation capability.
Lawn Tractor absorbs the bulk of installed capacity; Zero Turn is expanding most quickly.
End User:
Cost tier stratification separates capital-constrained purchasers from fleet operators with standardized replacement schedules.
- Commercial:Multi-site property management firms negotiate volume pricing through national fleet agreements. These buyers prioritize equipment uptime metrics and service response guarantees over initial acquisition cost.
- Landscapers:Independent contractors operating 5-15 unit fleets drive demand for mid-horsepower zero-turn configurations. Seasonal cash flow constraints favor financing programs with deferred payment structures.
- Residential:Homeowners on lots exceeding one acre represent the replacement-driven core of lawn tractor demand.
- Agricultural:Large landholding consolidation in India and Brazil is generating first-time mechanization demand for diesel-powered garden tractors.
Residential accounts for the largest unit volume base; Commercial is climbing the fastest.
Engine Power:
Application requirements dictate power band selection, with regulatory compliance costs escalating disproportionately above threshold outputs.
- 20-30 HP:This band captures the widest buyer base across estate owners and mid-sized landscaping contractors. EPA Phase 3 emissions standards impose the steepest compliance cost escalation here, accelerating battery-electric substitution.
- Less than 20 HP:Compact single-cylinder engines serve residential lawn tractors where cutting frequency and runtime duration remain moderate. European noise ordinances in Germany and France favor these lower-output configurations.
- 30-40 HP:Commercial zero-turn mowers and garden tractors require this output band for sustained blade speed under dense grass loads.
- More than 40 HP:Diesel configurations dominate agricultural and municipal applications requiring all-day continuous operation.
20-30 HP holds the deepest installed base; Less than 20 HP is gaining share fastest through electrification.
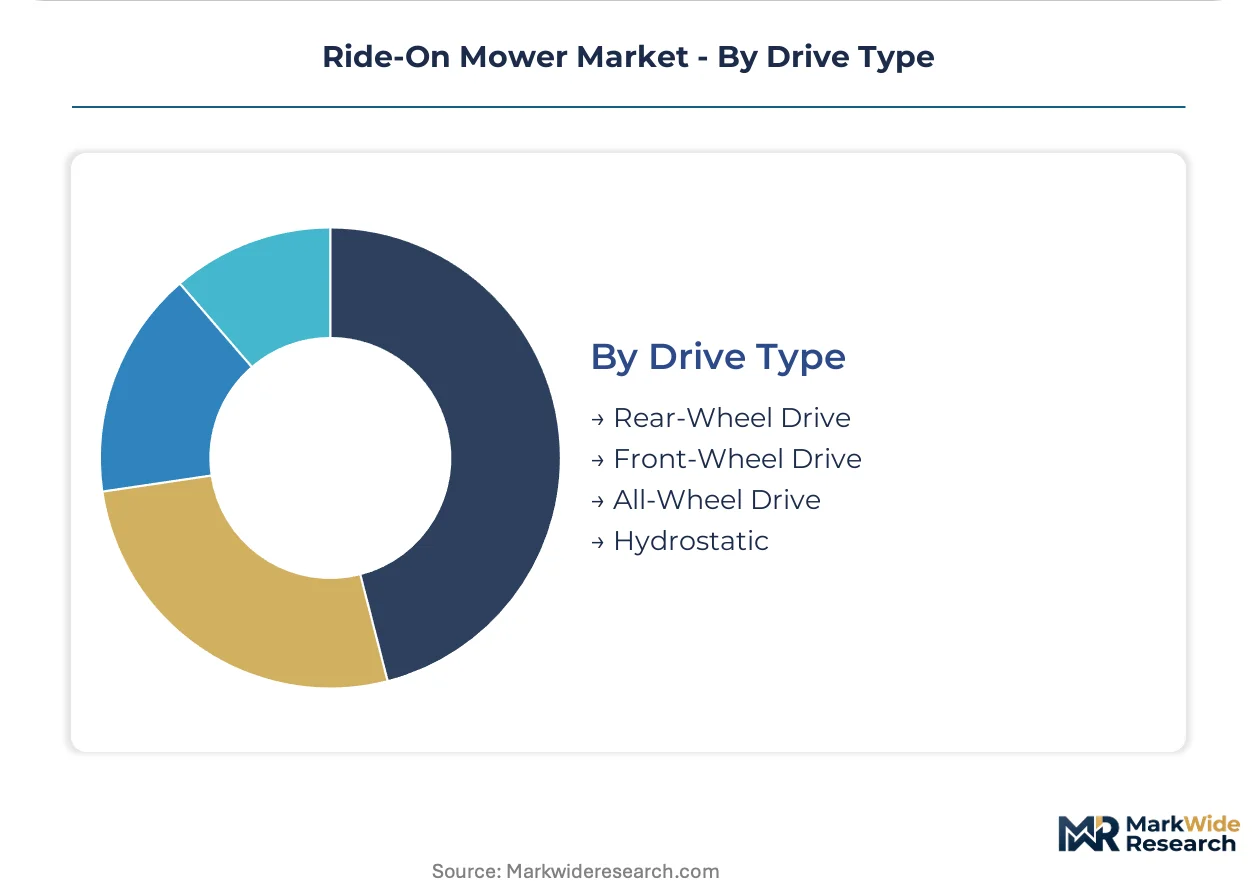
Drive Type:
Margin structures diverge sharply between mechanical transmission variants and precision hydrostatic systems.
- Hydrostatic:Variable displacement pumps and motor combinations deliver infinite speed control without clutch engagement. Commercial operators in the United States specify these systems to reduce operator fatigue during extended cutting sessions.
- All-Wheel Drive:Mechanical or hydrostatic power distribution to all four wheels enables slope stability and wet-terrain traction. Golf course superintendents in the Pacific Northwest require these configurations for fairway maintenance.
- Rear-Wheel Drive:Simpler mechanical layouts persist in price-sensitive residential segments.
- Front-Wheel Drive:Compact configurations suit European urban gardens with limited maneuvering space.
Hydrostatic commands the premium pricing tier; All-Wheel Drive shows the steepest expansion trajectory in commercial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration clusters in the United States and Germany, while demand absorption spreads across suburban North America, European golf corridors, and mechanizing agricultural estates in India and Brazil.
United States
Large lot residential properties and municipal golf course infrastructure sustain replacement cycles for zero-turn and lawn tractor configurations. EPA Phase 3 emissions standards for Class II spark-ignition engines above 19 kW mandate closed-loop fuel injection and catalytic aftertreatment. The Midwest manufacturing corridor spanning Wisconsin and Illinois anchors production capacity for hydrostatic drive systems and fabricated cutting decks.
Germany
Compact rear-engine designs serve noise-sensitive urban gardens and municipal maintenance contracts. EU F-Gas Regulation restrictions on refrigerants in related outdoor power equipment push manufacturers toward closed-loop thermal management favoring electrification. The Stuttgart industrial cluster hosts precision machining operations for variable displacement pump components used in premium hydrostatic transmissions.
India
Landholding consolidation in Punjab and Haryana generates first-time mechanization demand for compact diesel ride-on mowers in sugarcane and fodder crop maintenance. The Bureau of Indian Standards enforces safety and emissions compliance for agricultural machinery imports and domestic assembly. The Pune-Nashik manufacturing belt is developing supplier ecosystems for small diesel engine blocks and fabricated implements.
Brazil
Expanding agricultural estates in São Paulo and Minas Gerais states require multi-terrain garden tractors with ground-engaging implement compatibility. ANVISA regulates operator safety standards for commercial agricultural equipment, influencing rollover protection and blade engagement system designs. The São José dos Campos industrial district concentrates stamping and frame fabrication capacity for Latin American market supply.
Japan
Precision turf maintenance for golf courses and sports fields drives demand for compact, maneuverable configurations with low ground pressure. METI energy efficiency guidelines and noise ordinances favor battery-electric and advanced fuel injection architectures. The Ibaraki and Tochigi prefectures host compact engine manufacturing clusters supplying domestic OEMs and regional export markets.
Ride-On Mower Market Competitive Environment
Top-tier vendors anchor fleet procurement through dense dealer networks, while mid-scale specialists compete on battery-electric specialization and compact diesel configurations. The structure splits between diversified industrial conglomerates with agricultural equipment heritage and focused outdoor power equipment manufacturers. Three archetypes dominate: full-line agricultural-industrial conglomerates, dedicated turf maintenance specialists, and emerging battery platform pure-plays. Competitive moves concentrate on electrification platform development and fleet service network expansion.
Among diversified industrial conglomerates, Deere & Company and Kubota Corporation exemplify the agricultural equipment heritage archetype, leveraging legacy dealer density to anchor municipal and commercial fleet contracts. Husqvarna Group occupies a position within the dedicated outdoor power equipment tier, representing battery-electric specialization in noise-regulated European markets. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| Deere & Company |
| Husqvarna Group |
| The Toro Company |
| Kubota Corporation |
| Stanley Black & Decker |
| Ariens Company |
| Honda Motor Co., Ltd. |
| Briggs & Stratton |
| STIGA Group |
| Others |
Value Chain & Pricing Dynamics
Captive hydrostatic transmission production in Wisconsin and Illinois anchors both component availability and margin control for North American OEMs, while outsourced battery pack sourcing from East Asian cell manufacturers creates pricing volatility for electrified configurations.
Pricing Analysis
Lead-time-driven pricing stratification rewards spot inventory availability with premium positioning, particularly for EPA Phase 3-compliant gasoline engines facing foundry capacity constraints. Three-tier pricing structure across premium hydrostatic, standard gear-drive, and economy manual-transmission levels separates commercial fleet operators from residential replacement buyers. Cost compression in the 20-30 HP gasoline segment is intensifying because catalytic aftertreatment systems add assembly complexity and warranty exposure. Residential estate owners exhibit highest price sensitivity, while municipal golf course operators prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Freight cost escalation from consolidated casting operations in China and Mexico to North American assembly plants is reshaping sourcing economics for engine block forgings. Manufacturing gravity centers on the United States, Germany, and Japan for precision-machined hydrostatic components, while lithium-ion cell supply rests on South Korean and Chinese producers. Single-source vulnerability in semiconductor content for electric drive inverters creates qualification timeline risks. Distribution runs through authorized dealer networks for commercial fleet contracts, with big-box retail capturing residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ride-on mower sector sits in a powertrain-transition phase, with battery-electric platforms displacing small spark-ignition engines under regulatory pressure.
For Market Incumbents: Deploy dealer technician certification programs as a defensive moat against emerging battery-electric pure-plays. High-voltage service capability gaps in rural markets create retention risk for legacy gasoline-dependent customer bases. Backward integration into lithium-iron-phosphate pack assembly reduces East Asian cell supplier dependency.
For New Entrants and Emerging Players: Capture perimeter-mowing automation contracts for solar farms and airport buffer zones where RTK-GPS navigation creates first-mover positioning. Equipment-as-a-service contracting in metropolitan corridor markets offers the most penetrable entry path against capital-purchase incumbents. Partner with third-party fleet operators for bundled maintenance and seasonal storage offerings.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-specialist acquisitions by agricultural-industrial conglomerates seeking electrification capability. Long-term viability hinges on battery platform interoperability across handheld, walk-behind, and ride-on categories. Watch charging infrastructure deployment density in Florida and Texas landscaping corridors as inflection indicator for fleet-viable electric economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability | Shared voltage architectures across equipment categories reduce fleet operator total cost of ownership. |
| Dealer Network Electrification Training | High-voltage certification programs create service differentiation in rural markets lacking technician supply. |
| Equipment-as-a-Service Contracting | Per-acre pricing models transfer utilization risk from landscape contractors to specialized lessors. |
| Robotic Autonomy Integration | RTK-GPS navigation with electric drive opens perimeter-mowing automation for solar and airport applications. |
| Closed-Loop Thermal Management | EU F-Gas Regulation compliance favors electrified powertrains in noise-sensitive European markets. |
Study Parameters
Multi-period observation of EPA regulatory filing timelines, dealer inventory turns, and fleet procurement patterns anchored the trend analysis, supplemented by interviews with commercial landscaping operations managers, municipal golf course superintendents, OEM product planning directors, and hydrostatic transmission procurement leads. Secondary validation drew from EPA certification databases, EU F-Gas Regulation implementation notices, customs trade records for small engine imports, and SEC equipment manufacturer filings. Bottom-up unit economics triangulated against top-down market sizing across powertrain architectures.
Input-output matrices modeled unit shipments and revenue across product type, engine power band, end-user category, and drive configuration over the projection horizon. CAGRs derived from regression analysis of replacement cycle compression, fleet expansion rates, and electrification penetration curves. Industry-specific forecast inputs included lithium-ion cell price trajectories and small engine foundry capacity utilization rates.
The model holds under steady regulatory implementation timelines and stable commodity input costs; deviation in tariff regimes or battery supply chain disruptions would shift electrification adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Fertigation Control System Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market