
 Solar Powered Irrigation System Market | 2026-2036
Solar Powered Irrigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Irrigation System Market Analytics
Multi-source component procurement is realigning supply relationships across the solar irrigation value chain. Grundfos leverages its deep manufacturing footprint in pump electronics to sustain premium positioning in European markets. Jain Irrigation Systems anchors its competitive stance through backward integration into drip emitter production, while LORENTZ specializes in DC-native pump architectures for off-grid installations.
A solar powered irrigation system converts photovoltaic energy into mechanical pumping power, typically employing brushless DC motors rated between 0.5 kW and 75 kW to lift or pressurize water for crop delivery. These systems eliminate diesel dependence in remote agricultural zones, reducing lifecycle operating expenditure through direct solar-to-mechanical energy conversion without grid interconnection. Drip systems command the deepest margin pools where water scarcity elevates precision-application premiums, while surface systems retain volume leadership in smallholder contexts with lower capital thresholds. Smart controllers represent the fastest-expanding technology segment as telemetry integration enables remote flow modulation and predictive maintenance scheduling across distributed farm networks.
The EPA's WaterSense program and India's CEA renewable purchase obligations jointly shape product efficiency benchmarks and subsidy eligibility for solar pumping deployments. REACH compliance in Europe restricts certain polymer formulations in UV-exposed irrigation components, redirecting material selection toward certified alternatives. Stakeholders must monitor evolving carbon-border adjustment mechanisms and local-content requirements that threaten to fragment equipment certification pathways across jurisdictions.
Market Dynamics
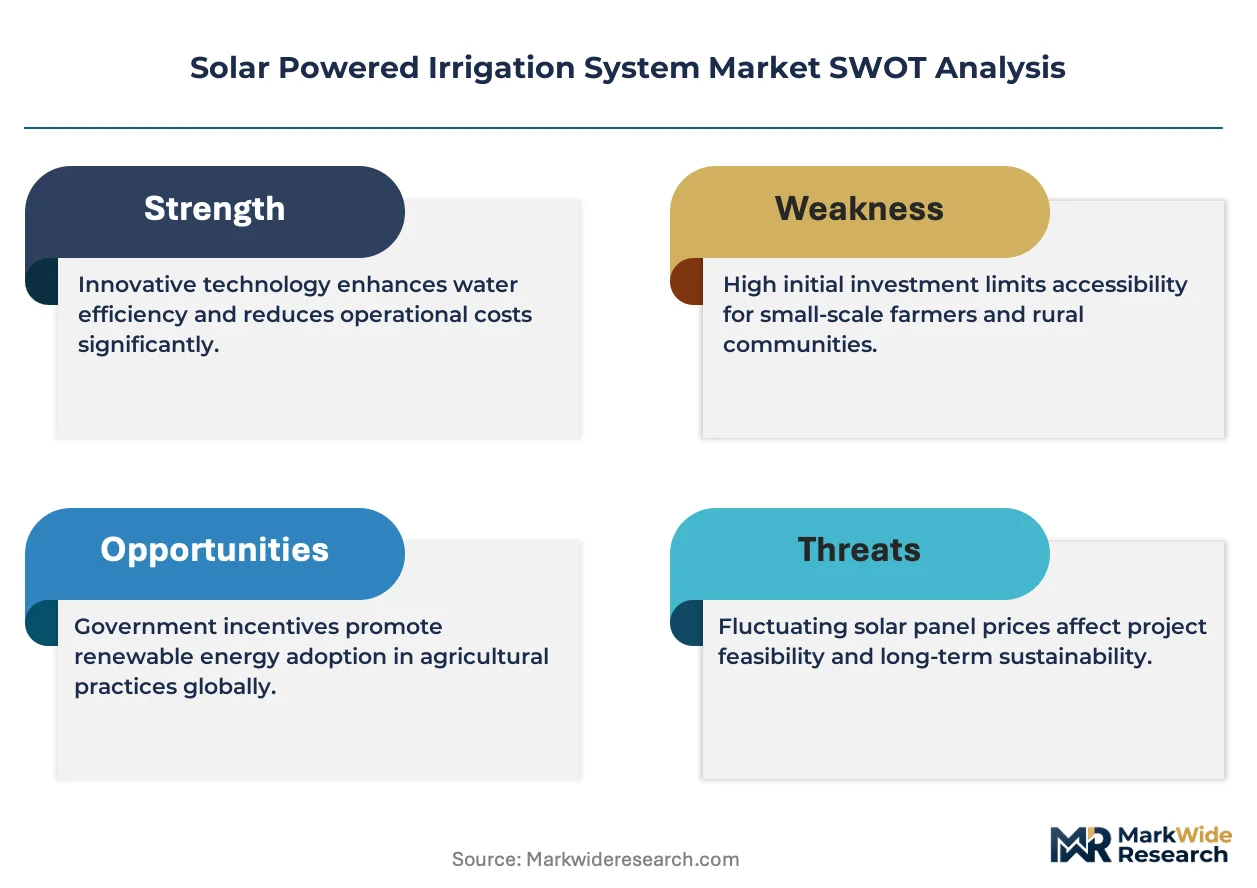
Photovoltaic module cost deflation is compressing system payback periods below diesel parity thresholds across arid agricultural zones, redirecting capital flows from conventional pumping infrastructure toward decentralized solar-to-mechanical conversion architectures.
Growth Catalysts
- PM-KUSUM scheme:India's CEA-mandated renewable purchase obligations combined with capital subsidies are accelerating decentralized solar capacity deployment across Rajasthan and Gujarat's commercial horticulture belt.
- Brushless DC motor architectures:DC-native pump designs rated between 0.5 kW and 75 kW are eliminating inverter conversion losses in off-grid installations across Sub-Saharan Africa's battery-backed drip irrigation networks.
- Water scarcity premiums:Precision-application drip systems are capturing margin pools in commercial vegetable cultivation where water stress elevates efficiency valuations above surface irrigation alternatives.
Market Restraints
- Polysilicon supply concentration:Upstream photovoltaic wafer production clusters in specific manufacturing geographies create input cost volatility exposure for system integrators without long-term supply agreements.
- REACH polymer restrictions:ECHA compliance mandates on UV-exposed irrigation components are redirecting material selection toward certified alternatives with elongated qualification timelines.
- Grid-tied diesel substitution:Established diesel pumping infrastructure with sunk capital costs and maintenance networks presents incumbent resistance in electrified agricultural zones with reliable grid access.
Strategic Opportunities
- Smart controller telemetry integration:Remote flow modulation and predictive maintenance scheduling capabilities are opening service revenue streams across distributed farm networks previously unreachable through conventional channel structures.
- Carbon border adjustment mechanisms:Emerging EU tariff structures on embodied carbon are creating competitive differentiation for solar irrigation equipment with documented lifecycle emission profiles versus fossil-fueled alternatives.
- Smallholder aggregation platforms:Cooperative procurement models in Kenya and Tanzania are lowering per-unit capital thresholds for surface system deployments through shared controller and battery assets.
Industry Challenges
- Photovoltaic-electromechanical integration expertise:Scarce technician capacity spanning both solar array commissioning and pump hydraulics is constraining deployment velocity in remote agricultural service territories.
- Multi-jurisdiction certification fragmentation:Divergent efficiency benchmarks between EPA WaterSense eligibility criteria and India's BIS standards are forcing product variant proliferation with elongated homologation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Irrigation System Market |
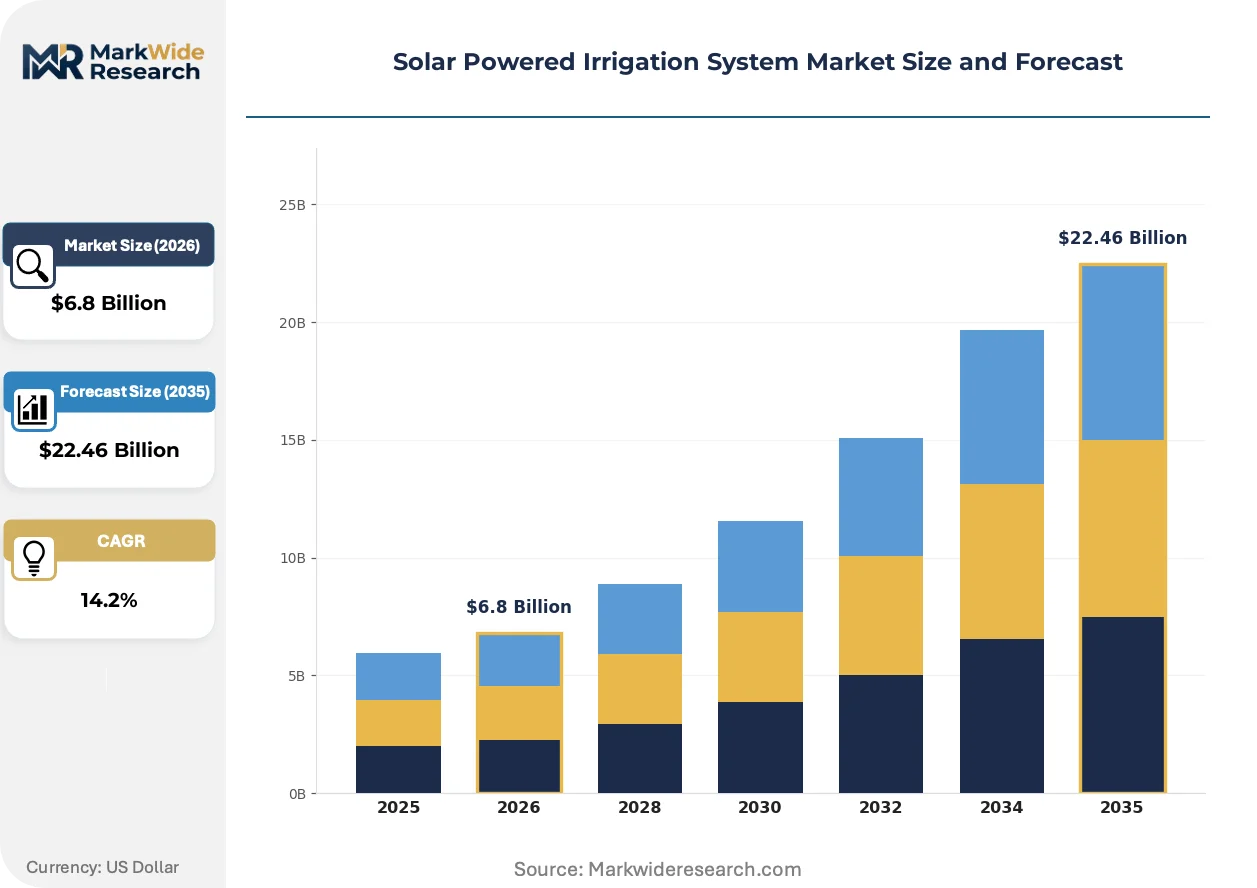
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Systems, Drip Systems, Sprinkler Systems, Subsurface Systems End User: Agricultural Producers, Government Entities, Non-profit Organizations, Commercial Growers Technology: Photovoltaic Panels, Battery Storage, Smart Controllers, Sensors Installation: Permanent Installation, Portable Systems, Hybrid Systems, Retrofit Solutions |
| Companies Covered | Grundfos, Valley Irrigation, Jain Irrigation Systems, Ooitech, Irrigatia, LORENTZ, C.R.I. (Solar Pumps), Redington Solar, Netafim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Irrigation System Market Evolving Landscape
Telematics integration is transforming solar irrigation from standalone mechanical systems into networked agricultural infrastructure, enabling predictive intervention models that compress maintenance response cycles and optimize water-energy dispatch.
Brushless DC motor drives with integrated maximum power point tracking are electrifying pump efficiency curves across variable solar irradiance conditions. Large-scale vegetable producers in Spain's Almería province are retrofitting existing boreholes with DC-native submersible units to eliminate inverter conversion losses. This electrification is compressing system footprint requirements and reducing balance-of-system costs for off-grid installations.
EPA WaterSense certification requirements are tightening efficiency benchmarks for pressurized distribution components in US agricultural deployments. Equipment manufacturers must now document flow-rate accuracy and pressure uniformity across variable solar input conditions to maintain subsidy eligibility. Drip emitter suppliers with in-house testing laboratories are capturing specification authority in California's Central Valley contracting channels.
Cooperative procurement collectives are displacing individual smallholder purchases in East African commercial horticulture. Aggregated demand pools in Kenya's Naivasha flower-growing cluster are negotiating volume discounts on battery-backed controller systems previously priced beyond single-farm capital budgets. This concentration is visible across Rwanda's tea irrigation cooperatives, where shared photovoltaic arrays serve multiple smallholdings through networked valve actuation.
Solar Powered Irrigation System Market Segmentation
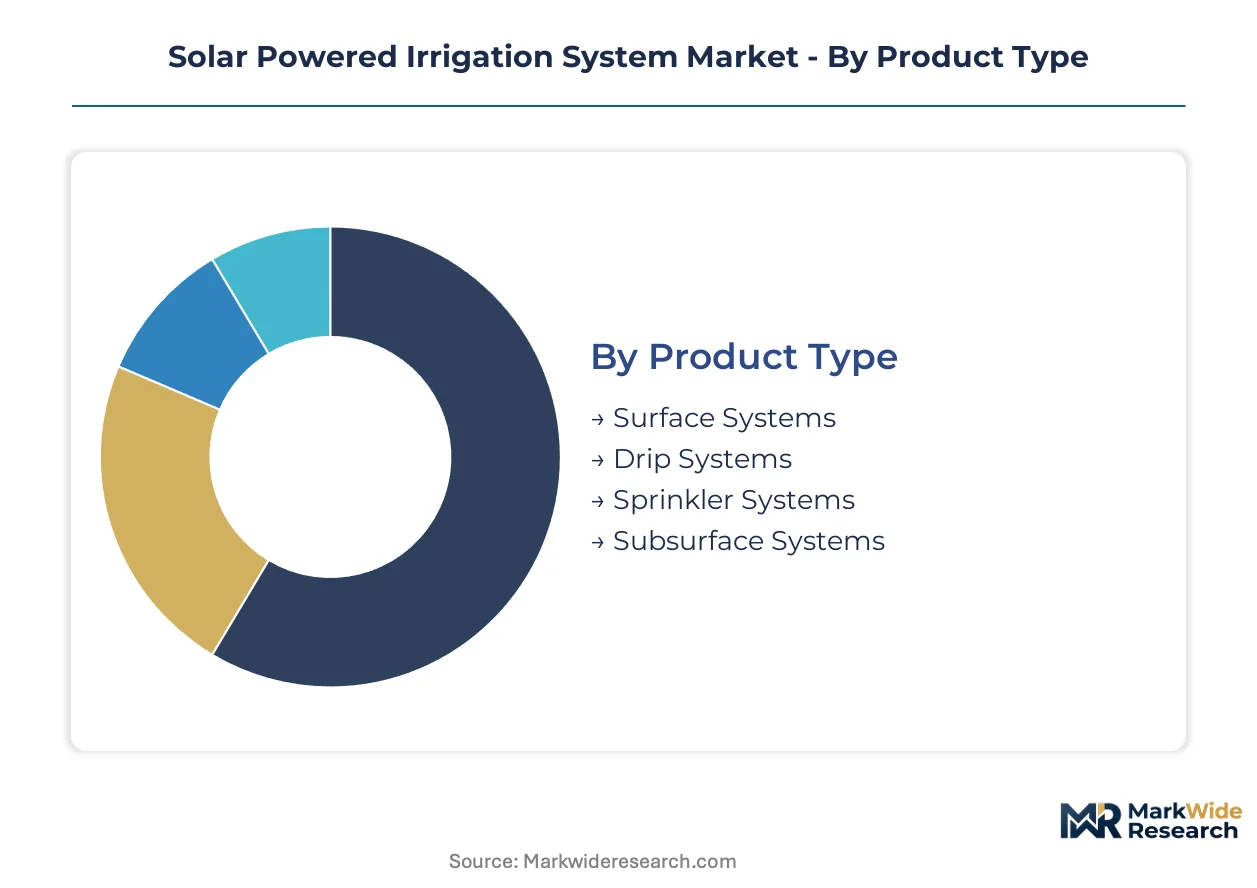
Solar irrigation procurement patterns diverge sharply across capital availability, technical sophistication, and water scarcity intensity. Buyers self-select into distinct technology tiers based on diesel displacement urgency and grid proximity, reshaping vendor go-to-market architectures.
Product Type:
Capital thresholds and water efficiency premiums differentiate buyer segments across commercial horticulture and smallholder contexts.
- Surface Systems:Open-channel or flood configurations deploy low-head centrifugal pumps for pasture and field crop irrigation. Smallholders in India's Gujarat state favor these units under PM-KUSUM capital subsidies that prioritize diesel displacement over precision application.
- Drip Systems:Pressure-compensating emitters integrated with photovoltaic pumps deliver targeted root-zone moisture in water-stressed vegetable cultivation. Kenya's Naivasha flower-growing cluster concentrates demand for battery-backed drip controllers that modulate flow across variable solar irradiance.
- Sprinkler Systems:Center-pivot and lateral-move configurations suit mechanized grain operations with moderate water stress.
- Subsurface Systems:Buried drip lines minimize evaporative losses in high-value orchard applications.
Volume sits with Surface Systems; growth tilts toward Drip Systems.
End User:
Procurement scale and subsidy access determine technology specification authority across deployment contexts.
- Agricultural Producers:Individual farm operators ranging from subsistence smallholders to commercial estates. Rajasthan's arid-zone cultivators leverage India's CEA renewable purchase obligations to secure decentralized solar capacity with 30% capital subsidy coverage.
- Commercial Growers:Large-scale horticulture and export-oriented operations with integrated cold-chain requirements. Spain's Almería province greenhouse complexes specify DC-native submersible pumps with integrated maximum power point tracking to eliminate inverter conversion losses.
- Government Entities:Public irrigation departments and rural electrification agencies deploying village-scale systems.
- Non-profit Organizations:Development agencies financing cooperative procurement models in Sub-Saharan Africa.
Procurement volume concentrates among Agricultural Producers; specification authority is climbing fastest among Commercial Growers.
Technology:
System architecture complexity tracks buyer technical capacity and remote monitoring requirements.
- Photovoltaic Panels:Crystalline silicon modules rated 1-100 kWp convert solar irradiance to DC electrical output. Module cost deflation below diesel parity thresholds is redirecting capital flows across Rajasthan's commercial horticulture belt.
- Smart Controllers:Telemetry-enabled pump drives with cellular connectivity enable remote flow modulation and predictive maintenance scheduling. These units are expanding most quickly across distributed farm networks previously unreachable through conventional service channels.
- Battery Storage:Lithium-ion and lead-acid banks extend pumping hours beyond daylight availability.
- Sensors:Soil moisture and weather station inputs automate irrigation scheduling decisions.
Photovoltaic Panels anchor installed base; Smart Controllers are gaining share fastest.
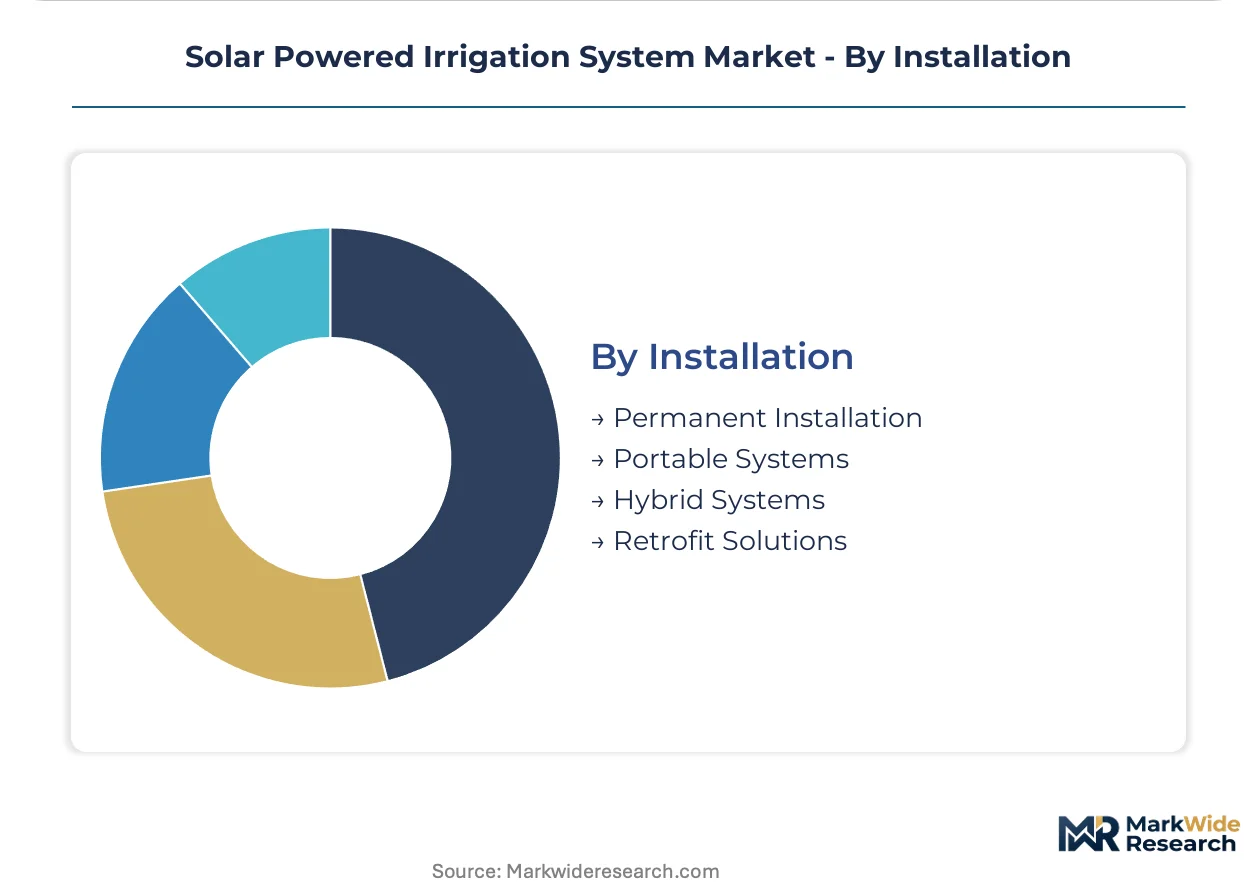
Installation:
Asset mobility requirements and existing infrastructure penetration shape deployment modality selection.
- Permanent Installation:Fixed solar arrays on ground-mount or rooftop structures serving dedicated boreholes or reservoirs. Spain's Almería greenhouse operators favor these configurations for year-round vegetable production with predictable water demand profiles.
- Retrofit Solutions:Photovoltaic pump replacements for existing diesel or grid-tied installations. These projects compress payback periods by leveraging sunk well infrastructure across India's Gujarat commercial horticulture zones.
- Portable Systems:Trailer-mounted solar arrays and pumps for seasonal or multi-site deployment.
- Hybrid Systems:Grid-tied solar with diesel backup for reliability-critical operations.
Permanent Installation dominates current deployment; Retrofit Solutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial horticulture operations in water-stressed zones are concentrating procurement authority across distinct national markets. Government subsidy programs and renewable energy mandates are accelerating capital deployment in arid agricultural belts. Regional deployment patterns track diesel displacement urgency and grid reliability gaps.
India
Rajasthan and Gujarat's commercial vegetable cultivators are expanding photovoltaic pumping capacity under the PM-KUSUM scheme. The CEA's renewable purchase obligations combined with capital subsidies covering decentralized solar installations are redirecting diesel-dependent irrigation toward DC-native pump architectures. The Alwar-Jaipur corridor anchors deployment volume for surface systems serving field crops.
Spain
Almería province greenhouse operators are retrofitting boreholes with DC-native submersible pumps to eliminate inverter conversion losses. REACH compliance mandates on UV-exposed irrigation components are redirecting material selection toward certified polymer alternatives. The southeastern horticulture belt concentrates specification authority for precision drip systems in export-oriented tomato and pepper cultivation.
United States
California's Central Valley almond and pistachio growers are specifying EPA WaterSense-certified pressurized distribution components. The state's SGIP energy storage incentives are accelerating battery-backed controller adoption for variable solar irradiance management. Fresno County contracting channels favor drip emitter suppliers with in-house testing laboratories.
Kenya
Naivasha flower-growing cooperatives are aggregating demand for shared photovoltaic arrays serving multiple smallholdings through networked valve actuation. The country's rural electrification agency is channeling development finance toward cooperative procurement models. Lake Naivasha basin commercial estates concentrate specification authority for battery-backed drip controllers.
Australia
Murray-Darling Basin cotton and wine grape producers are deploying permanent ground-mount solar arrays on dedicated borehole infrastructure. The country's national water regulator is tightening extraction licensing requirements that elevate solar pumping efficiency valuations. Riverina district irrigators are retrofitting existing diesel installations to compress payback periods through sunk infrastructure leverage.
Solar Powered Irrigation System Market Competitive Landscape
Backward integration into critical component manufacturing dominates the current landscape as vendors seek margin protection against photovoltaic module cost volatility. The vendor base stratifies across three tiers: multinational pump specialists with captive electronics production, integrated irrigation solution providers controlling emitter manufacturing, and regional assemblers sourcing modular subsystems. Two strategic archetypes have emerged: DC-native pump architects optimizing for off-grid efficiency, and full-system integrators bundling solar generation with precision distribution hardware. Competitive positioning hinges on multi-jurisdiction certification velocity and long-term polysilicon supply agreements.
Within the multinational specialist tier, Grundfos and LORENTZ exemplify divergent technical approaches to photovoltaic-electromechanical conversion. Grundfos leverages its Danish manufacturing footprint in pump electronics to sustain premium positioning in European markets with stringent efficiency benchmarks. LORENTZ occupies a position as a DC-native architecture specialist serving Sub-Saharan Africa's battery-backed off-grid installations. Jain Irrigation Systems anchors the integrated solutions archetype through in-house drip emitter production, capturing specification authority in India's subsidy-driven procurement channels. These three fabricators represent distinct competitive vectors: electronics depth, DC-native specialization, and vertical integration into precision distribution.
| Leading Market Players |
|---|
| Grundfos |
| Valley Irrigation |
| Jain Irrigation Systems |
| Ooitech |
| Irrigatia |
| LORENTZ |
| C.R.I. (Solar Pumps) |
| Redington Solar |
| Netafim |
| Others |
Value Network & Pricing Analysis
Photovoltaic-electromechanical technician scarcity in Rajasthan's Alwar-Jaipur corridor widens labor-cost differentials between premium European pump specialists and economy-tier regional assemblers, compressing mid-market pricing spreads.
Pricing Analysis
Warranty and predictive maintenance bundling separates Grundfos's premium European positioning from unbundled hardware transactions in India's PM-KUSUM procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service depth. Cost compression in the standard tier intensifies as Chinese photovoltaic module imports displace domestic panel production. Smallholder cooperatives in Kenya's Naivasha basin exhibit highest price sensitivity; commercial greenhouse operators in Spain's Almería province prioritize efficiency metrics over capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with polysilicon wafer production concentrated in China, South Korea, and Malaysia. Crystalline silicon modules, brushless DC motor drives, and lithium-ion battery cells anchor component dependencies. Tariff exposure on Chinese photovoltaic imports threatens cost structures for system integrators without long-term supply agreements. Distribution runs through agricultural equipment dealers and government procurement portals, with cooperative aggregators displacing individual smallholder purchases in East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure mounts as photovoltaic module cost deflation eliminates margin buffers for pure-play assemblers lacking captive component production.
For Market Incumbents: Acquire smart controller telemetry capabilities to capture recurring service revenue streams. Defensive consolidation requires backward integration into drip emitter manufacturing and securing REACH-compliant polymer supply chains against ECHA restriction expansion. Threat substitution from grid-tied diesel hybrid systems demands counter-positioning through battery-backed DC-native architectures. For New Entrants and Emerging Players: The premium-economy price-point gap in Sub-Saharan Africa's off-grid installations offers white-space entry. Target Kenya and Tanzania cooperative procurement models with shared controller and battery asset configurations. Channel partnership with rural electrification agencies accelerates market access without direct smallholder sales force buildout. For Investors and Strategic Acquirers: Re-rating potential sits with DC-native pump architects given carbon border adjustment mechanism differentiation in European markets. Long-term viability favors specialists with documented lifecycle emission profiles and multi-jurisdiction certification velocity. Watch India's BIS standard harmonization with EPA WaterSense benchmarks as inflection signal for product variant consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drip Emitter Production | Jain Irrigation Systems captures specification authority in India's subsidy-driven procurement channels. |
| Smart Controller Telemetry Integration | Remote flow modulation opens service revenue streams across distributed farm networks in Kenya. |
| DC-Native Pump Architecture Specialization | LORENTZ eliminates inverter conversion losses in Sub-Saharan Africa's battery-backed installations. |
| REACH-Compliant Polymer Qualification | Spanish greenhouse operators redirect material selection toward certified UV-exposed irrigation components. |
| Cooperative Procurement Platform Development | Aggregated demand pools in Tanzania lower per-unit capital thresholds for surface system deployments. |
Research Methodology
Independent corroboration across pump system engineers, agricultural cooperative managers, and photovoltaic EPC contractors underwrites the qualitative findings. Primary interviews with irrigation department procurement officers, drip emitter manufacturing leads, and rural electrification agency planners combined with secondary validation from India's CEA subsidy disbursement records, Spain's Ministry of Agriculture greenhouse cultivation statistics, and Kenya's Lake Naivasha Growers Group Association reports. Bottom-up installation counts and top-down energy consumption estimates triangulate market sizing.
Comparable-period anchoring to historical PM-KUSUM deployment trajectories and Almería province photovoltaic retrofit cycles frames the projection horizon. Segmentation dimensions span product type, end-user scale, technology architecture, and installation modality. CAGRs derive from fitted adoption curves calibrated against diesel parity threshold crossings and subsidy program renewal schedules. Forecast inputs incorporate polysilicon price volatility bands and REACH restriction implementation timelines.
Inputs from government procurement databases and cooperative financial disclosures were available through the study window; gaps in smallholder unbanked transaction records introduce uncertainty bands around Sub-Saharan Africa volume estimates. Forecasts reflect assumptions on subsidy program continuity and module cost deflation persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market