
 North America Agricultural Irrigation Machinery Market | 2026-2036
North America Agricultural Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Irrigation Machinery Market Analytics
Buyer concentration among large-scale farming operations across the Great Plains is hardening as acreage consolidates under fewer corporate and family-held entities. Valmont Industries leverages its manufacturing scale to dominate center-pivot supply chains across Nebraska and Kansas. Lindsay Corporation anchors its position through intensive R&D in remote monitoring and variable-rate irrigation technologies. Deere & Company competes by extending its precision agriculture ecosystem into automated water management, bundling irrigation controls with existing fleet telemetry.
North America agricultural irrigation machinery encompasses mechanical and electromechanical systems engineered to deliver controlled water volumes to crops, typically operating at pressures between 10 and 100 psi and integrating filtration, pumping, and distribution subsystems for field-scale moisture management. Pivot irrigation systems occupy the largest installed base across the region's grain belts, sustained by their compatibility with flat topography and their suitability for high-acreage corn and soybean rotations. Drip irrigation differentiates through premium margin capture in specialty crop zones, particularly where California's groundwater sustainability agencies enforce volumetric pumping limits. Smart irrigation technology leads growth velocity within the technology dimension, displacing manual systems as cellular connectivity and soil-moisture sensor networks achieve cost parity across mid-size operations.
The EPA, USDA Natural Resources Conservation Service, and state-level groundwater conservation districts collectively shape equipment demand through water-efficiency certification programs and cost-share incentives for pressurized system upgrades. California's Sustainable Groundwater Management Act and Texas groundwater district pumping caps directly accelerate replacement cycles for older flood-irrigation infrastructure. Stakeholders must monitor the divergence between federal conservation funding authorization and state-level enforcement timelines to align capital deployment with subsidy capture windows.
Market Dynamics
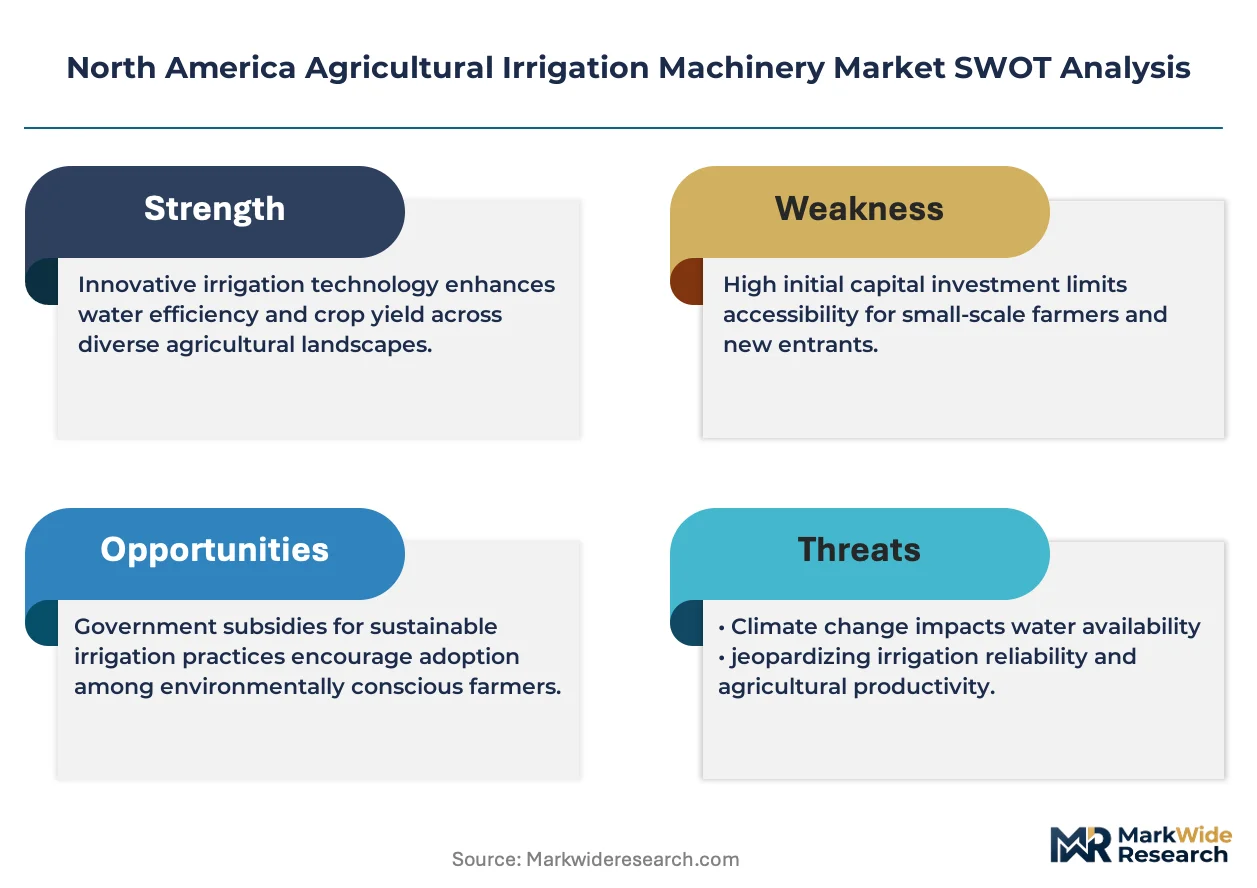
Groundwater depletion mandates across the Central Valley and Texas High Plains are forcing rapid replacement of flood-irrigation infrastructure with pressurized systems. The EPA's water-use efficiency certification under the Clean Water Act now filters equipment eligibility for federal cost-share programs, tightening procurement criteria for large-scale row-crop operations.
Growth Catalysts
- California's Sustainable Groundwater Management Act:Volumetric pumping limits imposed by groundwater sustainability agencies are accelerating center-pivot and drip system installations among specialty crop growers.
- USDA Natural Resources Conservation Service cost-share incentives:Pressurized irrigation upgrades qualify for 50-75% equipment subsidies, compressing payback periods for mid-size Nebraska and Kansas operations.
- Cellular-enabled soil-moisture sensor networks:Hardware cost parity achieved across Great Plains grain belts is displacing manual scheduling with automated variable-rate water delivery.
Market Restraints
- Steel and aluminum input volatility:Pivot tower fabrication costs fluctuate with commodity metal pricing, squeezing margin buffers for domestic center-pivot manufacturers.
- Supply concentration in Nebraska manufacturing clusters:Center-pivot component sourcing depends heavily on a narrow corridor of fabricators and drivetrain suppliers, amplifying disruption risk.
- Technical limitation in irregular topography:Pivot systems require slope gradients below 15%, excluding substantial acreage in the Missouri Ozarks and Appalachian foothills from mechanized coverage.
Strategic Opportunities
- Underpenetrated Texas High Plains:Ogallala Aquifer depletion rules are triggering wholesale infrastructure replacement among cotton and grain sorghum operators previously reliant on flood irrigation.
- Technology convergence of drone imagery and irrigation telemetry:Aerial crop-stress mapping layered with pivot control systems enables real-time nozzle modulation for water-stress mitigation.
- Equipment-as-a-service distribution models:Leasing platforms with bundled maintenance are emerging as an alternative to capital purchase for cash-constrained family farms in the Red River Valley.
Industry Challenges
- Integration complexity with legacy flood systems:Retrofitting gated pipe infrastructure with pressurized distribution requires field regrading and electrical trenching that extends project timelines.
- Certification timeline friction:EPA WaterSense and state-level low-emission equipment approvals lag 8-14 months behind product development, delaying commercialization of next-generation precision nozzles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Irrigation Machinery Market |
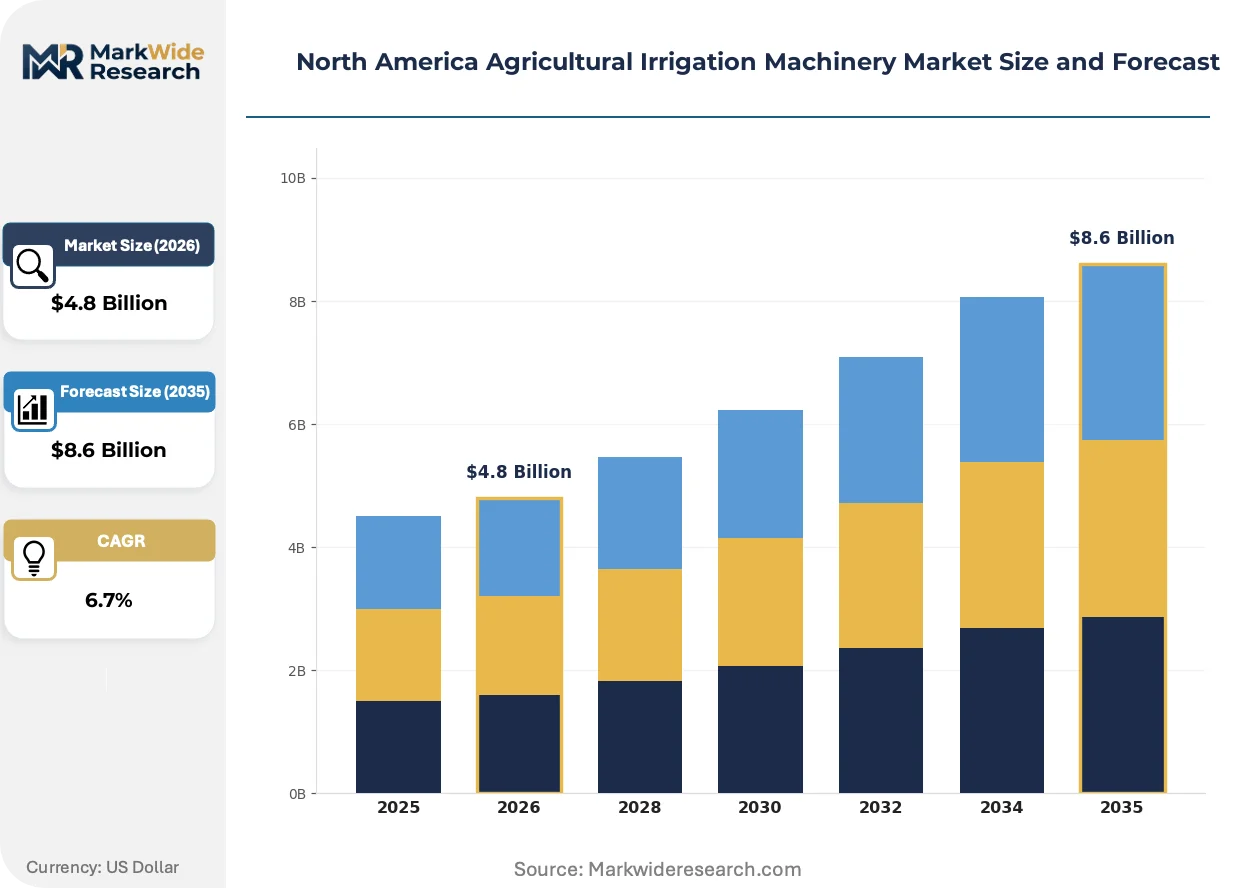
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Pivot Irrigation, Subsurface Irrigation Technology: Smart Irrigation, Traditional Irrigation, Automated Systems, Manual Systems End User: Farmers, Agricultural Cooperatives, Landscape Professionals, Government Agencies Application: Crop Irrigation, Turf Management, Greenhouse Irrigation, Landscape Irrigation |
| Companies Covered | Valmont Industries, Lindsay Corporation, Deere & Company, The Toro Company, Netafim Ltd., Nelson Irrigation, Rain Bird Corporation, T-L Irrigation, Hunter Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Irrigation Machinery Market Evolving Landscape
Automation architectures are collapsing the distinction between irrigation hardware and farm management software. The sector is witnessing rapid convergence of mechanical distribution systems with cloud-based analytics platforms that coordinate water delivery across multi-field operations.
Variable-rate irrigation (VRI) technology is unifying spatial water application with yield-map data layers. Large-scale corn and soybean operators across Iowa and Illinois are adopting VRI-enabled center pivots at accelerating velocity. This convergence is compressing equipment replacement cycles as growers trade functional mechanical systems for software-upgradable platforms.
The EPA's evolving effluent limitation guidelines under the Clean Water Act are tightening discharge standards for agricultural return flows. Equipment manufacturers must now certify systems for nutrient runoff reduction to maintain eligibility for federal conservation funding. Specialty crop zones in California's San Joaquin Valley face the steepest compliance ramps, driving demand for closed-loop drip systems with fertigation integration.
Consolidated procurement by multi-thousand-acre corporate farming entities is restructuring channel economics. Independent equipment dealers in the Corn Belt are losing ground to direct manufacturer relationships and integrated fleet-management contracts. This shift is most pronounced across Kansas and Nebraska, where three-generation family dealerships face margin compression from volume-based national accounts.
North America Agricultural Irrigation Machinery Market Segmentation
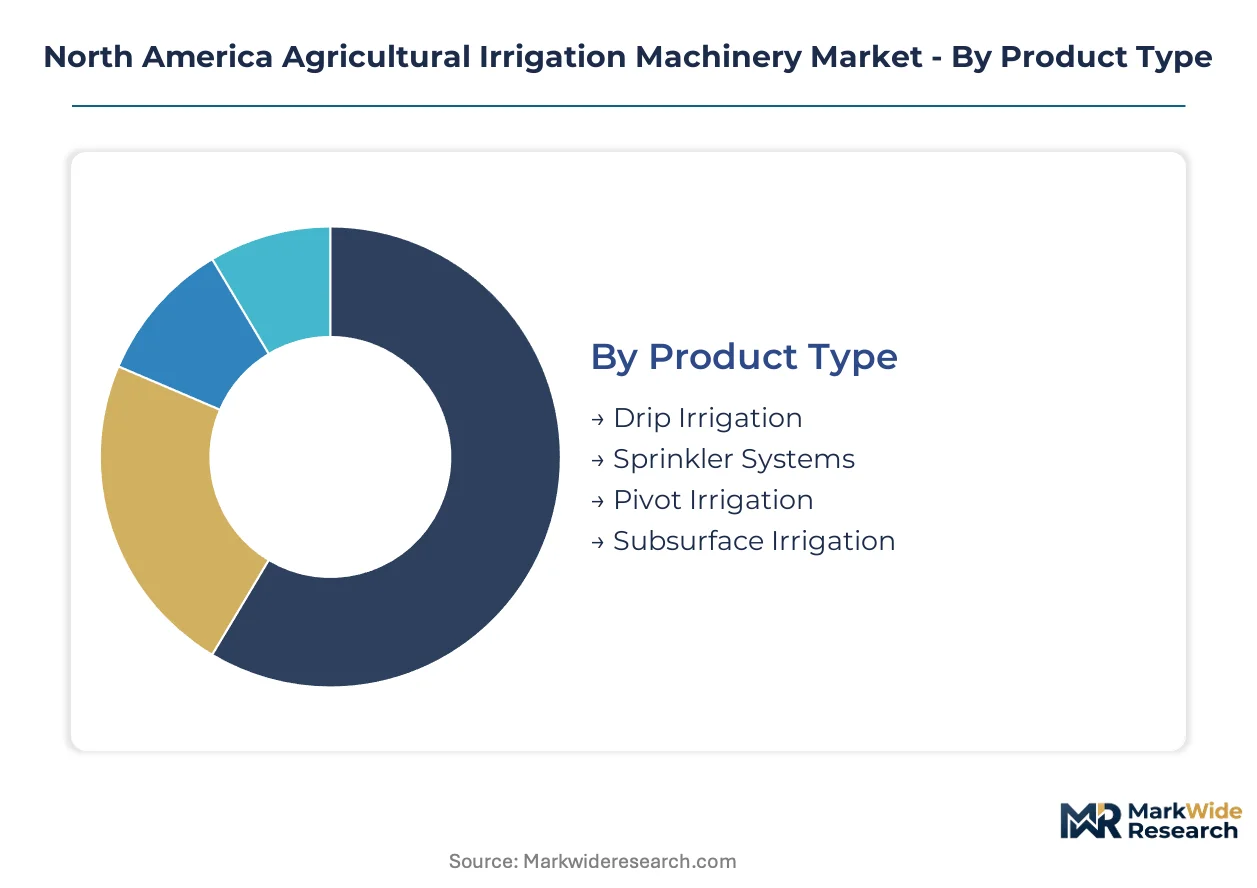
Segmentation in North American agricultural irrigation machinery reveals how water scarcity regulations and farm consolidation reshape procurement patterns. Equipment categories diverge sharply between high-volume commodity grain belts and premium-margin specialty crop zones.
Product Type:
Pivot systems dominate installed base volume while drip irrigation commands premium pricing in water-constrained jurisdictions.
- Pivot Irrigation:Center-pivot and lateral-move systems deliver pressurized water through rotating spans, typically covering 130-500 acre circles. Nebraska and Kansas grain operations drive replacement demand as USDA cost-share programs compress payback periods for mid-size farms.
- Drip Irrigation:Emitter-based networks apply water directly to root zones with 90%+ efficiency ratings. California's Central Valley specialty crop growers accelerate adoption under Sustainable Groundwater Management Act volumetric limits enforced by local groundwater sustainability agencies.
- Sprinkler Systems:Fixed and portable overhead distribution suits irregular topography excluded from pivot coverage.
- Subsurface Irrigation:Buried drip lines reduce evaporative losses in high-wind Texas High Plains cotton operations.
Today's leader: Pivot Irrigation. Tomorrow's challenger: Drip Irrigation.
Technology:
Automation intensity separates capital-intensive precision platforms from legacy mechanical systems.
- Smart Irrigation:Cellular-connected soil-moisture sensor networks coordinate variable-rate water delivery through cloud-based analytics. Great Plains corn and soybean operators displace manual scheduling as hardware achieves cost parity across mid-size acreage.
- Automated Systems:Programmable controllers with remote monitoring capability bridge mechanical distribution and software-defined management.
- Traditional Irrigation:Timer-based mechanical systems retain share among cash-constrained family farms in the Red River Valley.
- Manual Systems:Gravity-fed flood irrigation faces accelerated replacement under EPA Clean Water Act efficiency mandates.
Smart Irrigation expands most quickly; Traditional Irrigation contracts fastest.
End User:
Procurement authority concentrates as acreage consolidates under fewer operational entities.
- Farmers:Individual and family-held operations span subsistence-scale to multi-thousand-acre enterprises. Corporate farming entities across Iowa and Illinois negotiate direct manufacturer relationships, bypassing independent equipment dealers.
- Agricultural Cooperatives:Member-owned purchasing consortia aggregate volume for negotiated equipment pricing and shared precision agriculture infrastructure.
- Landscape Professionals:Commercial turf and municipal park managers source scaled-down pivot and sprinkler derivatives.
- Government Agencies:Federal and state conservation districts deploy demonstration systems for cost-share program validation.
Cooperative procurement gains leverage; individual farmer autonomy erodes.
Application:
Water scarcity severity determines technology selection across use cases.
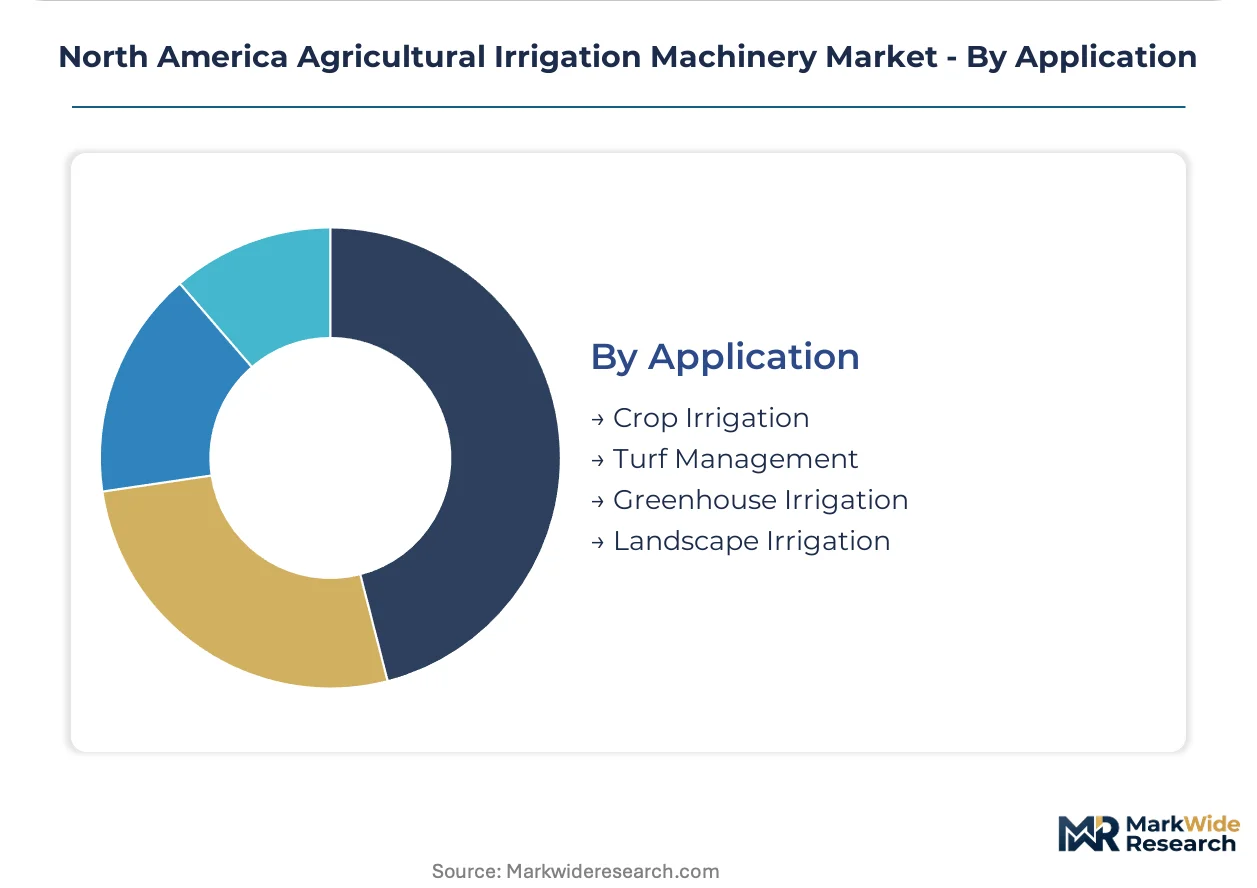
- Crop Irrigation:Field-scale moisture management for corn, soybean, cotton, and specialty produce dominates equipment deployment. Texas High Plains cotton operators replace flood infrastructure under Ogallala Aquifer depletion rules.
- Greenhouse Irrigation:Controlled-environment agriculture demands precision fertigation integration with closed-loop water recycling.
- Turf Management:Golf courses and sports fields adopt smart scheduling for regulatory compliance and labor reduction.
- Landscape Irrigation:Municipal and commercial ornamental plantings face municipal water restriction ordinances.
Crop Irrigation anchors volume; Greenhouse Irrigation climbs fastest on margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated around Midwest manufacturing corridors and California's ag-tech clusters anchor equipment innovation and field deployment capacity across the continent.
United States
Center-pivot fabrication clusters in Nebraska and Kansas drive domestic supply capacity, while California's Central Valley specialty crop zones accelerate precision drip adoption. The EPA's Clean Water Act water-use efficiency certification filters federal cost-share eligibility, tightening procurement standards for large-scale operations. Dallas-Fort Worth logistics hubs coordinate distribution networks serving the Texas High Plains cotton belt.
Canada
Prairie Province grain operations across Saskatchewan and Manitoba sustain demand for high-capacity pivot systems suited to expansive flat topography. Agriculture and Agri-Food Canada conservation programs subsidize pressurized irrigation conversions from gravity-fed systems. Manufacturing activity concentrates in southern Ontario fabrication facilities serving cross-border supply chains.
Mexico
Bajío Region vegetable and berry exporters drive adoption of drip fertigation systems for quality-sensitive produce destined for US markets. CONAGUA groundwater basin management plans restrict extraction volumes in overdrafted aquifers, accelerating infrastructure modernization. Guanajuato and Michoacán equipment assembly operations leverage proximity to California distribution channels.
North America Agricultural Irrigation Machinery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a consolidated vendor base where three-generation family dealerships face margin compression from national account procurement. Market structure reflects tiered competition between scale-driven manufacturers controlling center-pivot supply chains and precision-technology specialists capturing premium margins in specialty crop zones. Dominant competitive moves include backward integration into drivetrain component fabrication and strategic partnerships bundling hardware with cloud-based farm management platforms.
Among Nebraska-based manufacturing anchors, Valmont Industries and Lindsay Corporation exemplify the scale-driven archetype controlling domestic center-pivot fabrication capacity. Deere & Company represents the diversified conglomerate model extending precision agriculture ecosystems into automated water management. These three anchors collectively illustrate how competitive positioning stratifies between hardware scale advantages and software-integrated platform strategies.
| Leading Market Players |
|---|
| Valmont Industries |
| Lindsay Corporation |
| Deere & Company |
| The Toro Company |
| Netafim Ltd. |
| Nelson Irrigation |
| Rain Bird Corporation |
| T-L Irrigation |
| Hunter Industries |
| Others |
Value Network & Pricing Analysis
USDA cost-share program eligibility tightening under EPA Clean Water Act certification requirements is forcing equipment manufacturers to absorb compliance testing costs, compressing margin buffers across mid-tier fabrication operations. This demand-side specification shift cascades into supply chain restructuring as domestic producers prioritize certified component sourcing over lower-cost imports.
Pricing Analysis
Capacity additions in Nebraska and Kansas fabrication corridors are reshaping price floors for center-pivot tower assemblies. Three-tier pricing structure across premium smart-system, standard automated, and economy mechanical levels stratifies by telemetry integration depth. Cost compression in economy tiers is intensifying because steel and aluminum input volatility squeezes fabricator margins. Corporate farming entities negotiating national accounts exhibit lowest price sensitivity; cash-constrained family farms in the Red River Valley demonstrate highest elasticity.
Supply Chain Analysis
Domestic-content preferences embedded in USDA equipment subsidy programs are redirecting component sourcing toward Nebraska, Kansas, and Iowa manufacturing clusters. Raw material feeds from domestic steel mills, aluminum extrusion facilities, and electrical drivetrain suppliers anchor production. Single-source vulnerability concentrates in precision nozzle and sensor module categories currently imported. Distribution runs through manufacturer-direct national accounts and surviving independent dealerships serving fragmented family farm segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's Sustainable Groundwater Management Act enforcement timeline runs 18-24 months ahead of Texas groundwater district rulemaking, creating a regulatory arbitrage window for equipment deployment capital. This geographic divergence rewards early positioning in the Central Valley before compliance-driven replacement waves hit the High Plains.
For Market Incumbents: Lock in backward integration into drivetrain component fabrication to neutralize supply concentration risk around Nebraska manufacturing corridors. Prioritize EPA WaterSense pre-certification investment to capture federal cost-share program eligibility windows before state-level mandates tighten. Defensive positioning against emerging precision-agriculture software bundlers requires deepening telemetry platform integration. For New Entrants and Emerging Players: Begin with equipment-as-a-service leasing platforms targeting cash-constrained cotton operators in the Texas High Plains facing Ogallala Aquifer depletion compliance deadlines. The most penetrable segment sits among mid-size family farms excluded from corporate procurement volume discounts. Go-to-market execution should partner with regional agricultural cooperatives aggregating member demand for shared precision infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-telemetry specialists possessing cellular-enabled soil-moisture sensor networks and cloud-based variable-rate control software. Long-term viability hinges on recurring revenue streams from subscription analytics rather than transactional hardware sales. Acquisition targets should demonstrate installed base conversion momentum. The inflection signal to monitor is EPA effluent limitation guideline publication timing for agricultural return flow standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drivetrain Fabrication | Captive supply of tower motors and gearboxes insulates Valmont and Lindsay from component shortages. |
| Smart Irrigation Platform Launch | Cellular-connected sensor networks displace manual scheduling across Great Plains corn operations. |
| EPA WaterSense Certification Investment | Pre-qualified equipment eligibility locks in federal cost-share program revenue streams. |
| Equipment-as-a-Service Model Rollout | Leasing platforms with bundled maintenance expand addressable market to credit-constrained family farms. |
| Drone Imagery Integration Partnership | Aerial crop-stress mapping layered with pivot controls enables real-time nozzle modulation. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market informing demand-side calibration. Primary interviews with irrigation equipment dealers, agricultural cooperative procurement managers, farm operations executives, and USDA conservation district officers combined with secondary validation from EPA regulatory filings, state groundwater sustainability agency reports, and equipment manufacturer SEC disclosures. Bottom-up equipment shipment data triangulates against top-down agricultural acreage and water allocation statistics.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user scale, and application intensity. CAGRs derive from regression analysis against groundwater depletion rule implementation timelines and federal conservation funding authorization cycles. Industry-specific forecast inputs incorporate Ogallala Aquifer drawdown rates and California groundwater sustainability agency enforcement schedules.
Caveats apply where EPA effluent limitation guideline revisions or commodity metal price spikes could materially shift the outlook. Forecasts reflect assumptions around subsidy program continuity and cellular infrastructure rural coverage expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Farm Equipment Rental Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market