
 Global Sprinkler Irrigation Systems Market | 2026-2036
Global Sprinkler Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sprinkler Irrigation Systems Market Outlook
ISO 15886 certification for agricultural sprinklers is redrawing competitive boundaries in precision irrigation equipment. Rivulis leverages its drip-to-sprinkler integration expertise to anchor Mediterranean and Latin American markets. Valmont Industries sustains manufacturing scale across North American center-pivot production. Lindsay Corporation specializes in GPS-guided lateral-move systems for irregular field geometries.
Sprinkler irrigation systems are pressurized water-distribution networks using rotating or fixed spray heads to simulate rainfall across cultivated land, typically operating at 1-7 bar pressure with application rates of 3-50 mm per hour depending on nozzle design and crop requirements. Center-pivot systems dominate commercial agriculture due to lower labor intensity and proven reliability across thousands of hectares, while smart irrigation technology captures expanding margin pools through subscription-based remote monitoring and automated scheduling algorithms that reduce water consumption.
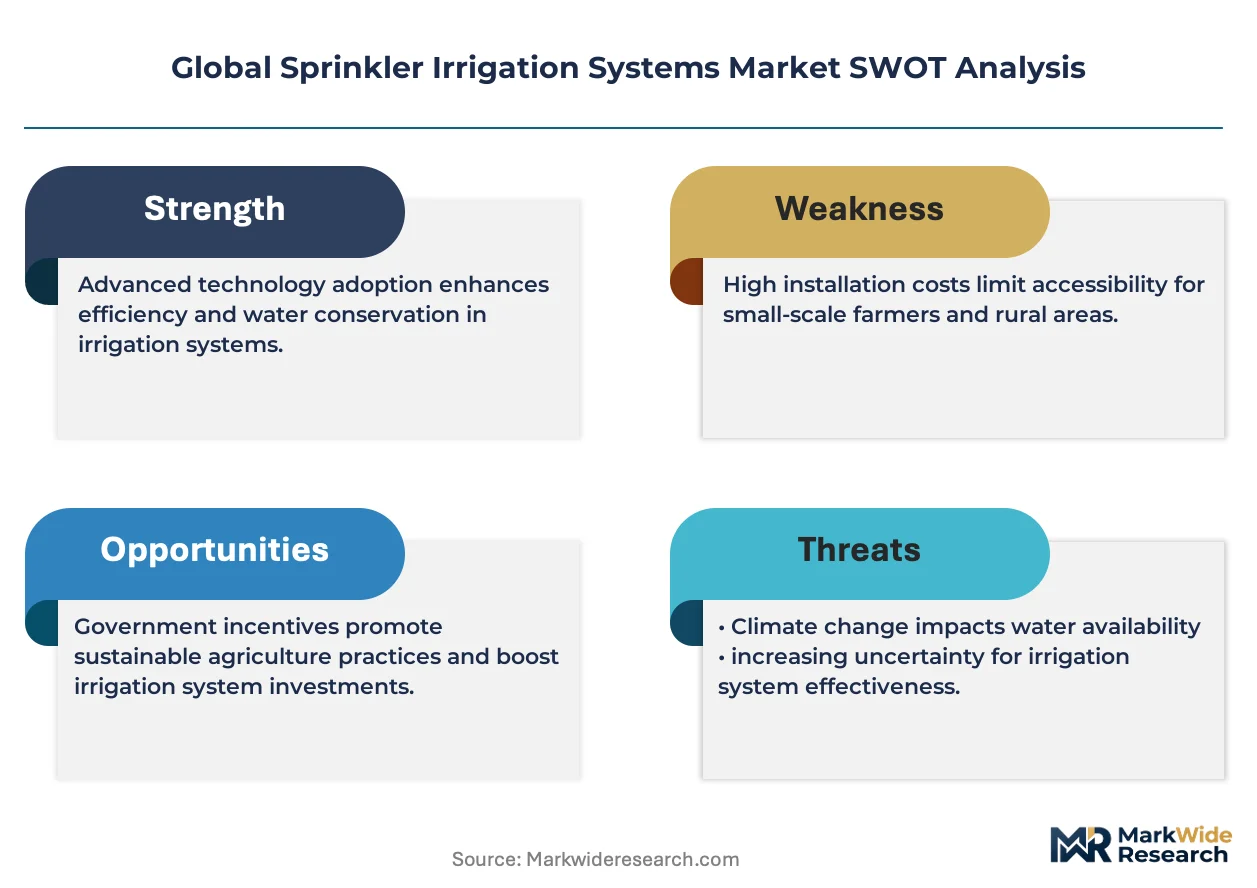
The US EPA WaterSense program and California's Sustainable Groundwater Management Act shape product development trajectories by mandating flow-rate efficiency thresholds and penalizing non-recharge basin extractions. India's Bureau of Indian Standards and China's Ministry of Ecology and Environment enforce pressure-rating and material-durability specifications that determine import eligibility for polyethylene mainline components. Stakeholders must monitor how groundwater basin adjudication in water-stressed regions restructures equipment replacement cycles and financing mechanisms for capital-intensive system upgrades.
Market Dynamics
Smart irrigation integration with soil moisture sensors and variable-rate controllers is compressing replacement cycles for legacy center-pivot hardware across water-stressed agricultural basins. Equipment specifications now prioritize telemetry compatibility over mechanical durability alone.
Growth Catalysts
- California's Sustainable Groundwater Management Act:Basin adjudication mandates metered extraction limits, forcing operators to retrofit center-pivot systems with flow-control nozzles and pressure-compensating emitters to maintain pumping permits.
- Brazilian large-scale row-crop operators:Intensifying drought cycles in Mato Grosso and Goiás are accelerating capital deployment into mechanized sprinkler networks that reduce labor dependence during narrow planting windows.
- Polyethylene mainline durability standards:India's BIS pressure-rating specifications for UV-stabilized piping are disqualifying substandard imports and consolidating procurement toward certified domestic and regional manufacturers.
Market Restraints
- Steel and polymer input volatility:Galvanized steel tower components and high-density polyethylene lateral tubing face commodity price swings that compress margin visibility for system integrators on fixed-bid contracts.
- Groundwater basin depletion physics:Falling water tables in the Ogallala Aquifer and North China Plain require deeper boreholes and higher-pressure pumps, raising capital intensity beyond smallholder financing thresholds.
- Drip irrigation substitution:Subsurface drip networks achieve 15-25% lower evaporation losses than overhead sprinklers in high-value orchard and vineyard applications, capturing share in premium crop segments.
Strategic Opportunities
- Sub-Saharan African commercial farming corridors:Zambia's Copperbelt and Tanzania's Southern Agricultural Growth Corridor present whitespace for solar-powered lateral-move systems where grid connectivity remains unreliable.
- EU Green Deal agricultural digitalization incentives:CAP pillar funding for precision irrigation infrastructure subsidizes sensor-to-nozzle integration, creating margin pools for subscription-based remote monitoring services.
- Vertical farming adjacency:Hybrid greenhouse operations in the Netherlands and UAE are adopting pressurized misting systems derived from agricultural sprinkler engineering for controlled-environment humidity management.
Industry Challenges
- ISO 15886 certification timelines:Third-party testing for uniformity coefficient and pressure-loss validation extends product launch schedules by 8-14 months for new nozzle geometries.
- Legacy system telemetry retrofit:Integrating IoT soil-moisture feedback loops into 1990s-era center-pivot infrastructure requires custom mechanical-to-digital interface engineering that fragments service provider capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sprinkler Irrigation Systems Market |
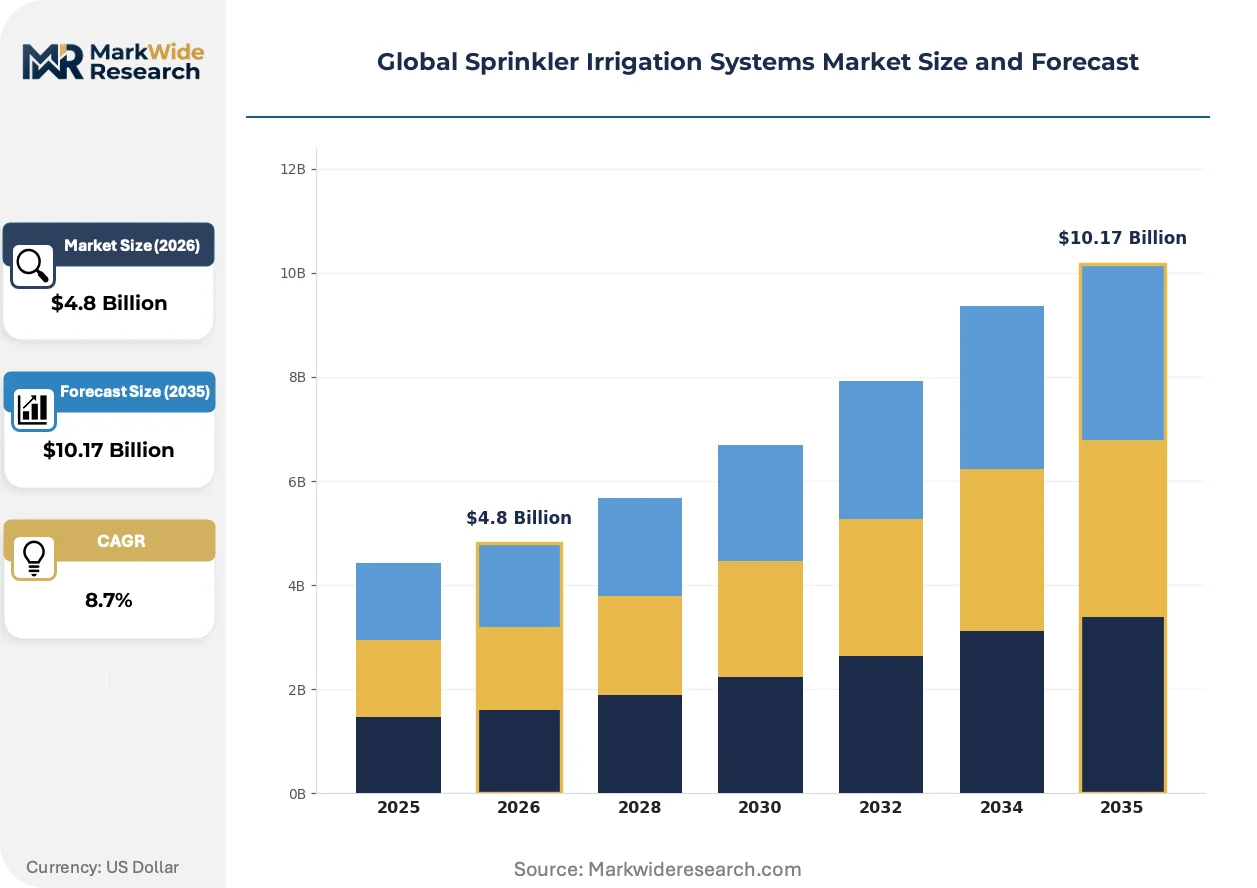
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip, Center Pivot, Lateral Move, Traveling Gun End User: Agriculture, Horticulture, Golf Courses, Residential Technology: Smart Irrigation, Automation, Remote Monitoring, Conventional Distribution Channel: Online, Direct Sales, Retail, Wholesalers |
| Companies Covered | Rivulis, Valmont Industries, Lindsay Corporation, Jain Irrigation Systems, Netafim, Rain Bird Corporation, The Toro Company, Hunter Industries, Reinke Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sprinkler Irrigation Systems Market Strategic Shifts
Variable-frequency drive technology and edge-computing irrigation controllers are redefining equipment performance benchmarks. Hardware differentiation is migrating from mechanical reliability to algorithmic water-use efficiency.
Electromechanical sector-drive units with GPS-guided corner-arm extensions are displacing traditional hydraulic drive systems in irregular field geometries. Large-scale operators in Australia and the US Great Plains are specifying these configurations to eliminate overspray on triangular headlands. The technology is displacing fixed-span center-pivot sales in fields under 130 hectares where full-circle coverage was previously uneconomical.
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants is tightening specifications for cooling-assisted precision agriculture equipment, indirectly pressuring sprinkler manufacturers to demonstrate standalone water-cooling efficiency without auxiliary climate systems. German and Dutch equipment purchasers now require energy-use disclosure documentation aligned with CSRD reporting obligations, favoring suppliers with lifecycle-assessment transparency.
Consolidated procurement through agricultural cooperatives and vertical integrators is compressing distributor margins and shifting specification influence from local dealers to centralized technical teams. Brazil's Amaggi and China's Beidahuang Group now negotiate direct manufacturer relationships for ten-thousand-hectare deployments, bypassing traditional equipment dealership networks in Mato Grosso and Heilongjiang respectively.
Global Sprinkler Irrigation Systems Market Segmentation
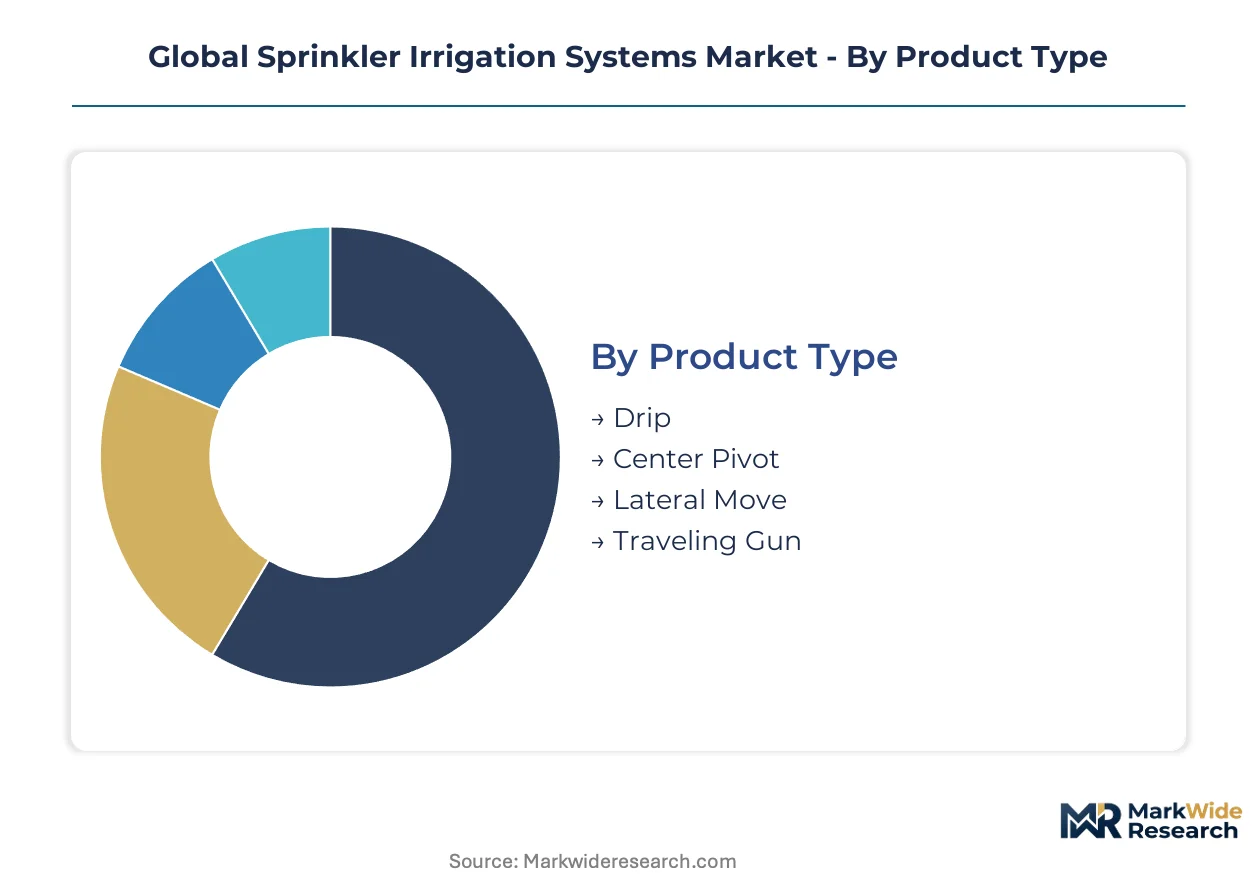
Segmentation in sprinkler irrigation systems reveals where capital deployment concentrates and where technology substitution threatens incumbent hardware. Product architecture, end-use water intensity, and telemetry integration determine margin durability across each slice.
Product Type:
Drip irrigation exerts the strongest substitution pressure on overhead sprinkler formats, reshaping competitive boundaries in water-stressed agricultural basins.
- Center Pivot:Circular-pattern mechanized systems rotate around a fixed pivot point, delivering uniform water distribution across large-scale row-crop operations. Demand concentrates in the US Great Plains and Brazil's Mato Grosso, where operators prioritize labor efficiency and proven reliability across thousand-hectare footprints.
- Drip:Low-pressure emitters deliver water directly to root zones through subsurface or surface tubing, achieving 15-25% lower evaporation losses than overhead alternatives. Adoption accelerates in California's Central Valley vineyards and Indian horticulture clusters facing groundwater extraction limits.
- Lateral Move:Linear-travel systems irrigate rectangular fields with higher uniformity coefficients than center-pivot alternatives. Australian broadacre wheat operators and Ukrainian commercial farming ventures specify these configurations for irregular field geometries.
- Traveling Gun:High-pressure mobile sprinklers traverse fields on cable or hose guidance, serving irregular terrain unsuited to fixed infrastructure. Demand persists in US forage hay operations and developing-market smallholder cooperatives with fragmented landholdings.
Center Pivot retains volume leadership; Drip holds the steepest expansion curve.
End User:
Water cost tiering separates capital-intensive commercial agriculture from price-sensitive residential installations, fragmenting procurement patterns and specification authority.
- Agriculture:Large-scale mechanized row-crop and broadacre grain operations deploy center-pivot and lateral-move systems across ten-thousand-hectare footprints. Brazilian soybean operators and Australian wheat producers drive replacement cycles as drought frequency intensifies.
- Horticulture:High-value fruit, vegetable, and nut cultivation demands precision application control to optimize yield quality and water-use efficiency. California almond orchards and Spanish greenhouse tomato clusters specify pressure-compensating emitters and soil-moisture feedback integration.
- Golf Courses:Turfgrass irrigation requires high-uniformity coverage across undulating terrain with strict aesthetic and playability standards. US Sun Belt and UAE desert course developments prioritize remote monitoring compatibility to manage labor costs and water restrictions.
- Residential:Single-family and multi-unit property owners install fixed-spray and rotor systems for lawn and garden maintenance. Demand concentrates in US suburban developments and Australian peri-urban housing estates with municipal water pricing pressure.
Agriculture commands the dominant revenue share; Horticulture posts the steepest technology premium capture.
Technology:
Margin pools are migrating from mechanical hardware durability toward algorithmic water-use efficiency and subscription-based service revenue.
- Smart Irrigation:Sensor-to-nozzle integration using soil-moisture probes, weather stations, and cloud-based scheduling algorithms reduces water consumption. California SGMA compliance deadlines and EU CAP digitalization subsidies accelerate specification in regulated basins.
- Automation:Programmable valve controllers and variable-frequency drive pumps enable unattended operation across extended irrigation windows. Large-scale operators in Brazil and Australia deploy these systems to narrow planting-window labor constraints.
- Remote Monitoring:Telemetry-enabled flow meters and pressure sensors transmit operational data to centralized dashboards for predictive maintenance. Agricultural cooperatives in the US Midwest and commercial farming ventures in Zambia specify these capabilities for distributed asset management.
- Conventional:Timer-based mechanical systems without sensor feedback or network connectivity serve cost-constrained smallholders and legacy infrastructure replacement cycles. Demand persists in Indian fragmented landholdings and developing-market irrigation rehabilitation programs.
Conventional retains installed-base dominance; Smart Irrigation climbs the fastest on new-capital deployment.
Distribution Channel:
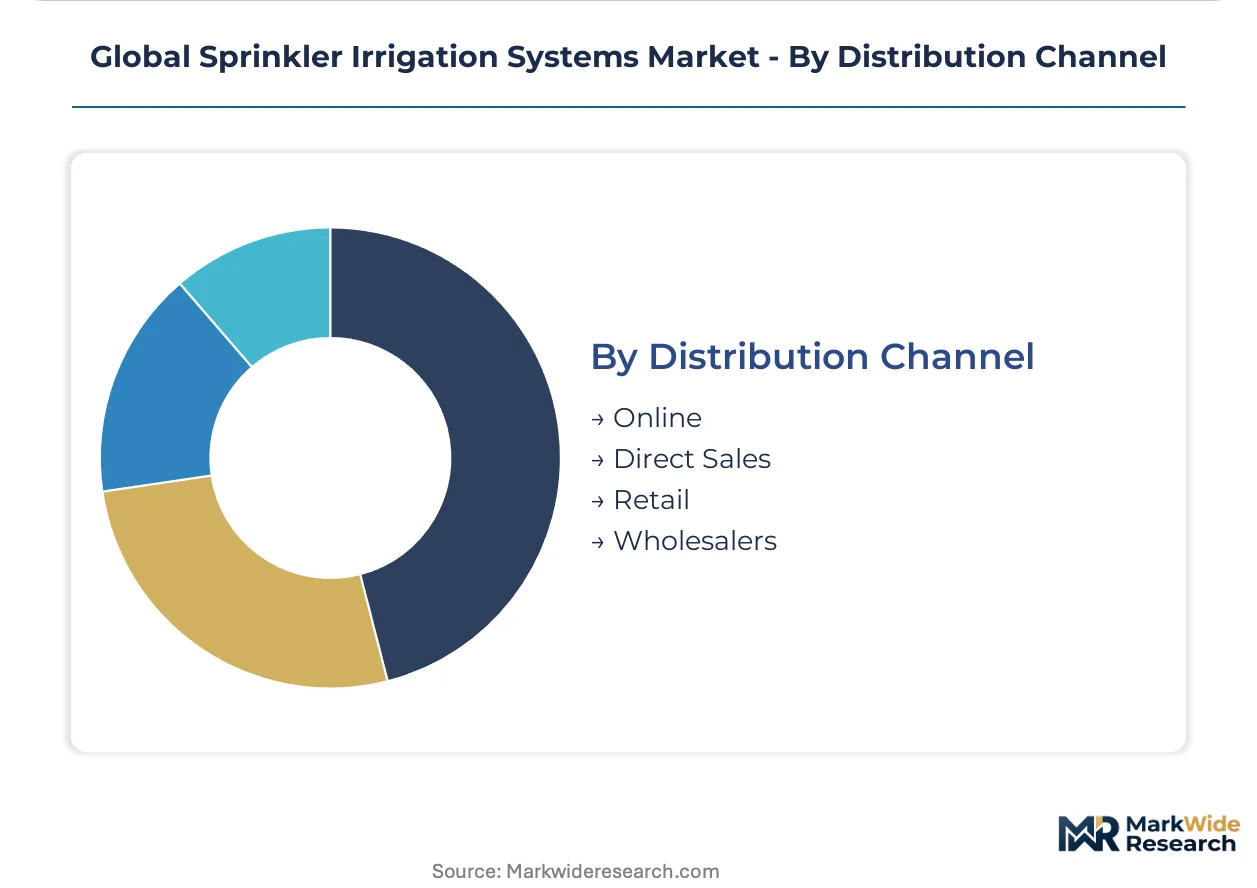
Supply concentration among consolidated agricultural cooperatives is compressing traditional dealer margins and shifting specification influence to centralized technical procurement teams.
- Direct Sales:Manufacturer-to-operator relationships bypass distributor markups for large-scale deployments exceeding five hundred hectares. Brazil's Amaggi and China's Beidahuang Group negotiate direct contracts for Mato Grosso and Heilongjiang corridor development.
- Wholesalers:Regional distributors maintain inventory depth and technical service capacity for mid-scale operators and dealer networks. US Great Plains irrigation suppliers and Australian rural merchant chains serve this intermediary function.
- Retail:Bricks-and-mortar agricultural equipment dealers provide local specification guidance and installation services for small-to-mid-scale operators. Demand concentrates in US Midwest farm supply cooperatives and Indian state-level agricultural extension networks.
- Online:E-commerce platforms enable component procurement and system configuration for technically sophisticated buyers with established specifications. Residential segment buyers and developed-market precision agriculture adopters utilize these channels for replacement parts and sensor peripherals.
Wholesalers retain volume throughput leadership; Direct Sales gains share fastest on large-farm consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale commercial farming operations in water-stressed basins drive procurement concentration, with regulatory compliance deadlines accelerating capital deployment into precision irrigation infrastructure.
United States
The US Great Plains and California's Central Valley anchor mechanized center-pivot demand as groundwater depletion intensifies. EPA WaterSense flow-rate efficiency thresholds and California's Sustainable Groundwater Management Act basin adjudication force retrofit cycles. Fresno County almond operators deploy pressure-compensating emitters to maintain pumping permits under SGMA-mandated extraction limits.
Brazil
Mato Grosso and Goiás soybean operators accelerate sprinkler network deployment amid intensifying drought cycles and narrow planting windows. ANVISA agricultural equipment import standards and state-level water use licensing reshape procurement specifications. Amaggi negotiates direct manufacturer relationships for ten-thousand-hectare corridor developments, bypassing traditional dealer networks.
China
The North China Plain faces falling water tables that demand deeper boreholes and higher-pressure pump configurations beyond smallholder financing thresholds. Ministry of Ecology and Environment polyethylene mainline durability specifications and GB standards pressure-rating enforcement disqualify substandard imports. Heilongjiang's Beidahuang Group consolidates procurement through centralized technical teams for large-scale deployments.
India
Fragmented landholdings in Maharashtra and Gujarat sustain demand for cost-conventional timer-based systems while horticulture clusters adopt precision alternatives. Bureau of Indian Standards UV-stabilized piping pressure-rating specifications determine import eligibility for polyethylene mainline components. Karnataka's precision agriculture adoption zones specify soil-moisture feedback integration for groundwater extraction compliance.
Australia
Broadacre wheat operators in New South Wales and Victoria specify GPS-guided lateral-move systems for irregular field geometries with higher uniformity coefficients. Murray-Darling Basin water buyback programs and state-level extraction metering reshape equipment replacement cycles. Queensland's solar-powered lateral-move deployments address grid connectivity gaps in remote agricultural corridors.
Global Sprinkler Irrigation Systems Market Competitive Environment
Player mix skews toward integrated irrigation infrastructure specialists with manufacturing scale across multiple product architectures. Tier-one participants combine center-pivot fabrication with smart telemetry integration capabilities, while regional specialists concentrate on drip-to-sprinkler hybrid configurations for Mediterranean and Latin American markets. Two dominant competitive moves define current positioning: direct procurement relationships with consolidated agricultural cooperatives eliminating distributor markups, and algorithmic water-use efficiency subscriptions capturing recurring revenue streams from regulatory compliance services.
Among North American infrastructure fabricators, Valmont Industries and Lindsay Corporation exemplify scale-driven manufacturing archetypes with proven center-pivot and lateral-move production footprints. Rivulis occupies a position within the integration-specialist tier, leveraging drip-to-sprinkler expertise to anchor Mediterranean and Latin American market penetration. These three entities represent distinct competitive positioning vectors—manufacturing scale, precision guidance specialization, and hybrid system integration—rather than overlapping strategic approaches.
| Leading Market Players |
|---|
| Rivulis |
| Valmont Industries |
| Lindsay Corporation |
| Jain Irrigation Systems |
| Netafim |
| Rain Bird Corporation |
| The Toro Company |
| Hunter Industries |
| Reinke Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with steel and polymer suppliers lock in polyethylene mainline component access for center-pivot fabricators while insulating margin visibility against commodity index volatility. These arrangements tie pricing to London Metal Exchange galvanized steel benchmarks and regional HDPE spot indices, creating pass-through mechanisms that stabilize procurement costs for large-scale system integrators serving Brazilian and North American agricultural cooperatives.
Pricing Analysis
Cost-plus contracts indexed to Chicago Mercantile Exchange steel futures and Singapore HDPE resin benchmarks dominate equipment procurement for center-pivot and lateral-move systems. Three-tier pricing structure across ISO 15886-certified premium, standard pressure-rated, and economy non-certified tiers separates precision agriculture adopters from cost-constrained smallholders. Pricing pressure stems from drip irrigation substitution in California vineyard and orchard applications where subsurface emitter networks achieve superior water-use efficiency. Agricultural cooperatives in Brazil's Mato Grosso exhibit lowest price sensitivity due to consolidated ten-thousand-hectare procurement scale, while Indian fragmented landholders in Maharashtra face acute cost compression on timer-based conventional systems.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Santos port congestion periods have elevated landed costs for Chinese-manufactured tower components and Israeli drip-to-sprinkler integration modules. Manufacturing concentration centers on the United States for center-pivot fabrication, China for polyethylene mainline extrusion, and Israel for precision emitter technology. Raw material dependencies rest on galvanized steel sheet, UV-stabilized HDPE resin, and precision-machined brass nozzle components. Single-source vulnerability runs through Taiwanese semiconductor supply for variable-frequency drive controllers. Distribution runs through agricultural equipment wholesalers in the US Great Plains and direct manufacturer relationships with Brazilian consolidated farming ventures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drip irrigation networks pose the most acute substitution threat to overhead sprinkler formats, forcing incumbent hardware fabricators to defend installed-base relationships through telemetry integration and algorithmic water-use efficiency services.
For Market Incumbents: Compound defensive positioning by embedding subscription-based remote monitoring capabilities into legacy center-pivot infrastructure to combat drip irrigation share capture in California and Mediterranean horticulture clusters. Pursue backward integration into polyethylene mainline extrusion to secure supply access under India's BIS pressure-rating enforcement. Prioritize ISO 15886 certification investment to maintain specification eligibility in EU Green Deal subsidized procurement channels. For New Entrants and Emerging Players: Lead with solar-powered lateral-move system configurations targeting Zambia's Copperbelt and Tanzania's Southern Agricultural Growth Corridor where grid unreliability excludes incumbent electrified offerings. Penetrate Sub-Saharan African commercial farming corridors through equipment-as-a-service financing models that bypass smallholder capital intensity constraints. Anchor go-to-market strategy through agricultural development agency partnerships rather than traditional equipment dealership networks. For Investors and Strategic Acquirers: Telemetry-enabled irrigation controller specialists with proven cloud-platform integration represent the most compelling acquisition target archetype within the smart irrigation value chain. Long-term viability hinges on recurring revenue capture from regulatory compliance services rather than transactional hardware margins. Monitor California SGMA basin adjudication enforcement velocity as the primary inflection indicator for precision irrigation capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Irrigation Platform Integration | Sensor-to-nozzle telemetry captures recurring revenue from California SGMA compliance deadlines. |
| Backward Integration into Polymer Extrusion | In-house HDPE mainline production secures margin control under India's BIS certification enforcement. |
| Solar-Powered System Development | Off-grid lateral-move configurations unlock Zambia and Tanzania commercial farming corridors. |
| ISO 15886 Certification Investment | Third-party uniformity validation maintains specification access to EU CAP digitalization subsidies. |
| Direct Procurement Relationship Expansion | Manufacturer-to-cooperative contracts bypass distributor markups in Brazil's Mato Grosso corridor. |
Study Parameters
A standing panel of irrigation equipment procurement directors at agricultural cooperatives, center-pivot maintenance engineers, polyethylene mainline distribution managers, and precision agriculture technology integrators provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with equipment specification authorities and aftermarket service technicians across the US Great Plains, Brazil's Mato Grosso, and India's Maharashtra clusters. Secondary sources encompassed EPA WaterSense certification databases, California Department of Water Resources SGMA basin adjudication filings, Bureau of Indian Standards pressure-rating notifications, and EU Common Agricultural Policy digitalization incentive documentation. Bottom-up equipment shipment tracking and top-down agricultural water-use intensity modeling were triangulated to anchor volume estimates.
Consistency checks validated projection outputs against external benchmarks including hyperscaler agricultural technology capex disclosures and regional groundwater extraction metering deployment rates. The analytical framework modeled demand across product architecture segments, technology integration tiers, end-use water intensity categories, and distribution channel structures throughout the forecast period. CAGRs were derived from regression analysis of historical replacement cycle data and regulatory compliance deadline clustering. Industry-specific inputs included drought frequency indices for Brazilian soybean regions and Murray-Darling Basin water buyback program implementation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of groundwater extraction limits or accelerated drip irrigation cost reduction would require recalibration. Forecasts reflect documented assumptions regarding polyethylene resin price stability and center-pivot mechanical durability replacement schedules. Recalibration cycles align with material shifts in California basin adjudication rulings and EU CAP subsidy allocation revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Pumps Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market