
 Smart Sprinkler Irrigation Systems Market | 2026-2036
Smart Sprinkler Irrigation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Sprinkler Irrigation Systems Market Outlook
Edge computing embedded directly into valve controllers is rewriting how irrigation decisions execute in the field. NETAFIM leverages decades of drip specialization to anchor precision agriculture deployments across arid growing regions. Rachio competes through consumer-facing automation software that simplifies zone-based scheduling for residential users. Hunter Industries dominates commercial landscaping with professional-grade wireless networks built for large-scale property management.
Smart sprinkler irrigation systems combine sensor arrays, actuated valves, and cloud-connected controllers to deliver site-specific water application based on real-time soil moisture, evapotranspiration rates, and weather data. These systems typically operate at pressures between 30 and 50 PSI with flow rates calibrated to match crop coefficients or turfgrass species requirements, reducing runoff and deep percolation losses. Sprinkler Systems and Smart Controllers together command the largest installed base, though Soil Moisture Sensors represent the fastest-expanding margin pool as growers demand closed-loop feedback. IoT Integration underpins nearly all new platform architectures, while Agricultural Producers generate the highest absolute volume despite Residential Users posting quicker upgrade cycles.
EPA WaterSense specifications and the EU Green Deal's farm-to-fork sustainability targets constrain product design by mandating flow verification, leak alerts, and remote shutoff capabilities. California's Sustainable Groundwater Management Act and Australia's Water Efficiency Labelling standards further shape regional demand by penalizing inefficient distribution. Stakeholders must weigh retrofit economics against full system replacement as sensor density requirements intensify and firmware update lifecycles extend.
Market Dynamics
EPA WaterSense certification tightening and California's Sustainable Groundwater Management Act enforcement are compressing upgrade timelines for legacy irrigation infrastructure across agricultural and commercial property segments.
Growth Catalysts
- Groundwater sustainability mandates:California's SGMA implementation compels Central Valley growers to retrofit flood-irrigation systems with sensor-driven precision networks to meet basin sustainability targets.
- Flow efficiency standards:EPA WaterSense specifications now require leak detection and remote shutoff capabilities, accelerating replacement cycles for non-compliant controllers in municipal and commercial installations.
- Edge computing architectures:Valve-embedded processing units enable real-time evapotranspiration adjustments without cloud latency, expanding deployment feasibility in bandwidth-constrained rural zones.
Market Restraints
- Copper and semiconductor input volatility:Sensor array manufacturing depends on stabilized commodity pricing that irrigation equipment margins struggle to absorb.
- Technical interoperability gaps:Proprietary wireless protocols between controller brands prevent seamless zone expansion without full system replacement.
- Substitution from subsurface drip:NETAFIM-style precision drip systems capture water-intensive crop applications where overhead sprinkler efficiency gains plateau.
Strategic Opportunities
- EU Green Deal farm-to-fork alignment:REACH-compliant smart controllers qualify for sustainability-linked agricultural financing across Mediterranean growing regions.
- Residential channel digitization:Big-box retail partnerships and direct-to-installer platforms bypass traditional irrigation contractor networks for consumer-grade system sales.
- Sensor-controller convergence:Integrated soil moisture-actuated valve units eliminate separate hardware procurement, reducing installation complexity for golf course superintendents.
Industry Challenges
- Field technician certification bottlenecks:EPA WaterSense installer credentials require specialized training that contractor workforces lack at scale.
- Legacy two-wire infrastructure incompatibility:Decades-old valve wiring in established landscapes demands complete trenching and replacement rather than controller-only upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Sprinkler Irrigation Systems Market |
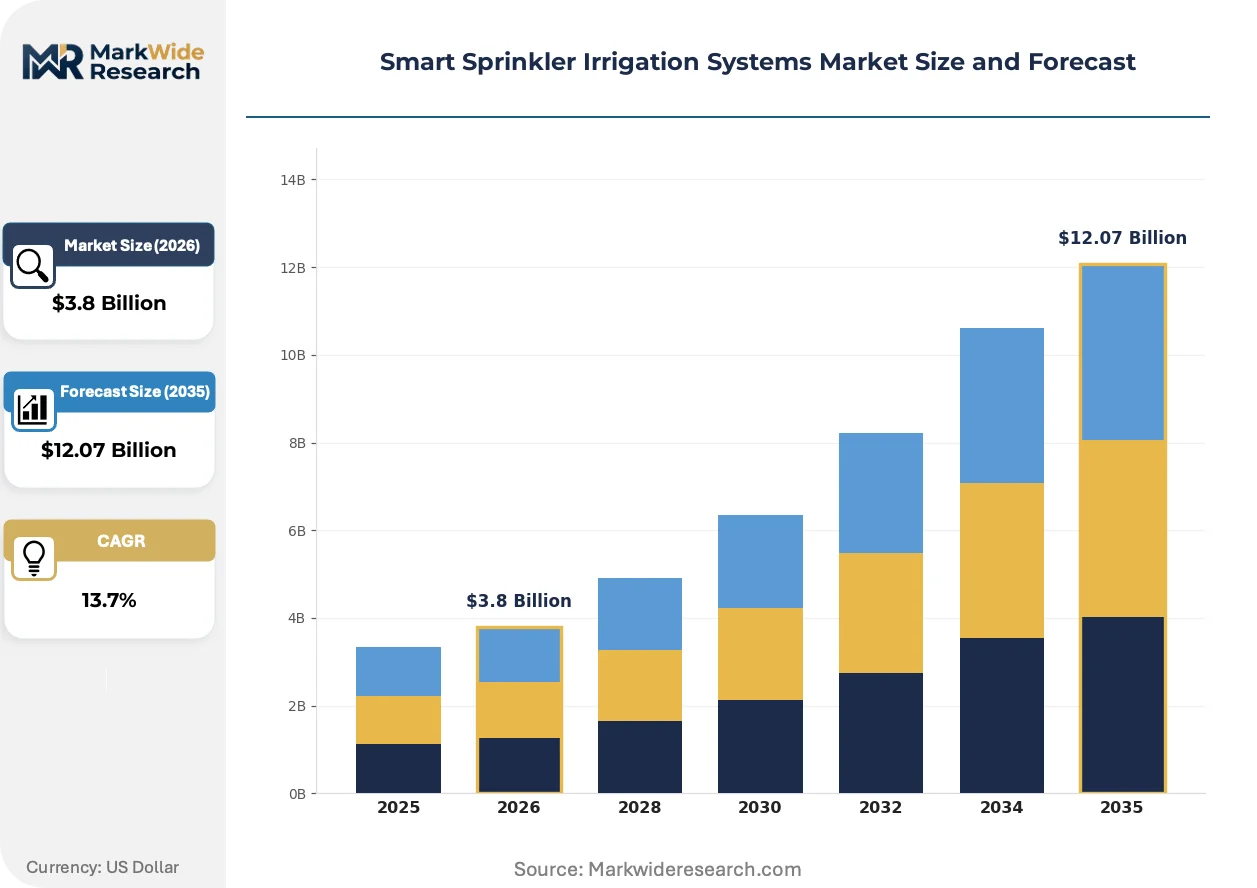
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Soil Moisture Sensors, Smart Controllers Technology: IoT Integration, Wireless Networks, Sensor Technology, Automation Software End User: Agricultural Producers, Landscapers, Golf Courses, Residential Users Installation Type: Permanent Systems, Portable Systems, Retrofit Installations, New Installations |
| Companies Covered | The Toro Company, Rain Bird Corporation, Hunter Industries, NETAFIM, HydroPoint, Rachio, Weathermatic, Orbit Irrigation Products, Netro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Sprinkler Irrigation Systems Market Strategic Shifts
Computational migration toward field-edge devices and regulatory pressure for verified water savings are restructuring how irrigation decisions execute and how equipment suppliers prove performance claims.
Machine learning inference engines deployed directly onto valve controllers are virtualizing the traditional cloud-dependent scheduling model. Large-scale agricultural operators in Australia's Murray-Darling Basin now process evapotranspiration calculations locally, eliminating connectivity dependency while compressing response latency from minutes to milliseconds. This distributed architecture reduces data transmission costs and enables autonomous operation during network outages that previously halted automated irrigation cycles.
The EU Green Deal's farm-to-fork sustainability targets now mandate flow verification and leak alert capabilities for agricultural equipment receiving public subsidy. Manufacturers must redesign controller firmware to log and transmit consumption data for audit compliance, adding development overhead but creating product differentiation through certified water stewardship. Mediterranean olive and citrus growers face the tightest compliance deadlines, driving concentrated demand for retrofit-ready smart valve systems.
Certification-driven specification now dominates municipal and institutional procurement, with EPA WaterSense labeling functioning as a gatekeeper for public project eligibility. Landscape architects and facility managers increasingly exclude non-certified controllers from bid lists, compressing market access for legacy equipment without verified efficiency testing. This preference shift is most visible across Arizona and Florida municipal golf courses, where bond-financed renovations require documented water savings to satisfy sustainability covenants.
Smart Sprinkler Irrigation Systems Market Segmentation
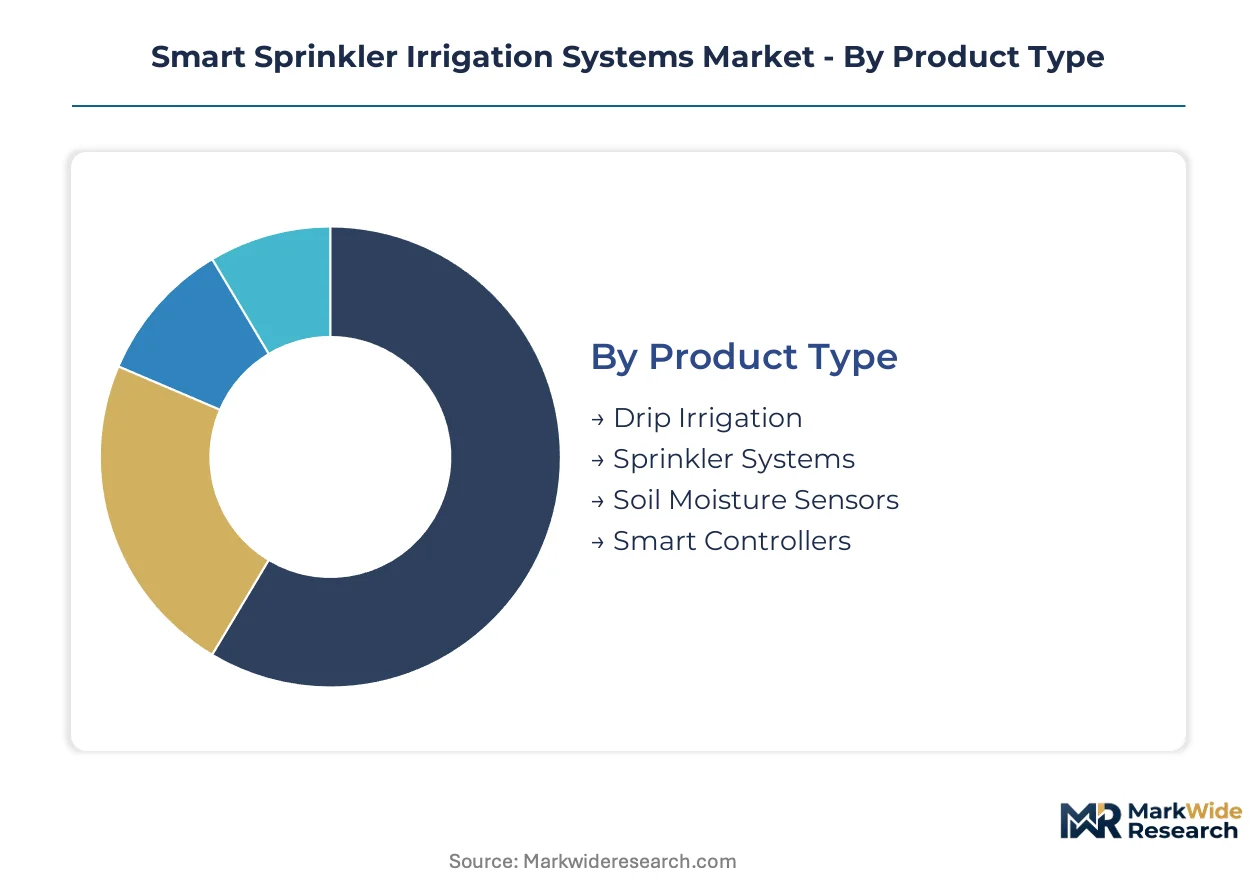
Smart sprinkler irrigation systems fragment across hardware, connectivity, and deployment models that carry radically different replacement cycles. Understanding these cadences reveals where recurring revenue concentrates versus where one-time equipment sales dominate.
Product Type:
Controller and sensor segments turn over every 5-7 years as firmware obsolescence accelerates, while buried infrastructure endures 15-20 year lifecycles that slow refresh rates.
- Sprinkler Systems:Underground valve networks and pop-up rotor heads constitute the physical distribution layer, with brass and PVC construction rated for decades of pressure cycling. California Central Valley almond growers and Arizona municipal golf courses represent the densest replacement demand as SGMA compliance deadlines force infrastructure overhaul.
- Smart Controllers:Cloud-connected scheduling units with WiFi, cellular, or LoRa backhaul process evapotranspiration data and execute zone commands. Residential channel velocity outpaces commercial as big-box retail and direct-to-installer platforms shorten procurement paths for California and Florida homeowners.
- Drip Irrigation:Pressure-compensating emitters and subsurface tubing deliver point-source water application directly to root zones.
- Soil Moisture Sensors:Capacitance and tensiometer probes provide closed-loop feedback for automated irrigation triggers.
Sprinkler Systems dominate installed base. Soil Moisture Sensors represent where expansion concentrates most steeply.
Technology:
Wireless protocol choices determine interoperability boundaries and lock-in economics that shape vendor switching costs.
- IoT Integration:Cloud platforms aggregate sensor telemetry, weather APIs, and controller commands into unified management dashboards. Australian Murray-Darling Basin operators and EU Green Deal subsidy recipients drive specification intensity as audit logging becomes mandatory for agricultural financing eligibility.
- Sensor Technology:Soil moisture, flow, and pressure transducers generate the data layer for precision irrigation decisions. Golf course superintendents across Arizona and Florida demand sensor-controller convergence to reduce hardware procurement complexity.
- Wireless Networks:Proprietary radio and mesh protocols connect field devices to central controllers.
- Automation Software:Machine learning scheduling engines optimize water application timing and duration.
IoT Integration commands the highest platform attach rates. Sensor Technology is where margin expansion concentrates.
End User:
Customer type dictates price tolerance, technical sophistication, and procurement channel preferences that fragment go-to-market requirements.
- Agricultural Producers:Large-scale farming operations managing hundreds to thousands of irrigated acres prioritize flow verification and remote monitoring for regulatory compliance. California Central Valley groundwater sustainability districts and Australia's Water Efficiency Labelling enforcement create concentrated retrofit demand.
- Residential Users:Single-family homeowners respond to drought messaging and utility rebate programs with quicker upgrade cycles than institutional buyers. Rachio-style consumer automation software simplifies zone-based scheduling for California and Florida metropolitan markets.
- Golf Courses:Turfgrass managers balance playability with water conservation across heterogeneous microclimates.
- Landscapers:Commercial property maintenance contractors specify professional-grade wireless networks for multi-site management.
Agricultural Producers generate the highest absolute volume. Residential Users post the quickest upgrade cycles.
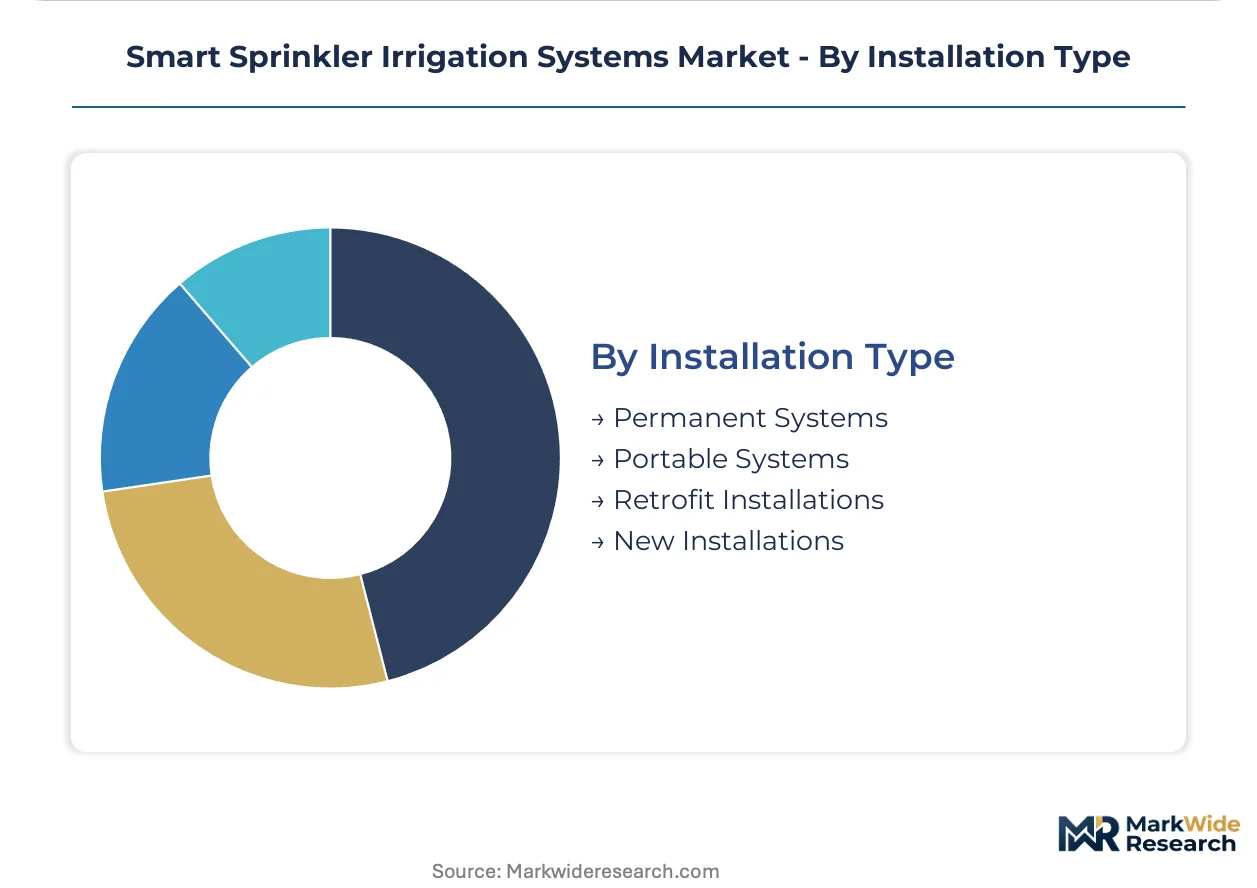
Installation Type:
Deployment mode determines labor intensity, permitting requirements, and whether incumbent infrastructure creates path dependency.
- Retrofit Installations:Controller-only upgrades onto existing valve wiring slash project cost but face compatibility limits with decades-old two-wire infrastructure. EPA WaterSense certification requirements accelerate replacement timelines as non-compliant legacy equipment loses municipal and commercial bid eligibility.
- New Installations:Complete system builds with trenching, valve manifolds, and integrated sensor networks command premium project values. California SGMA implementation zones and EU Green Deal farm-to-fork subsidy corridors concentrate greenfield specification.
- Permanent Systems:Buried infrastructure with fixed zone architecture dominates agricultural and golf course applications.
- Portable Systems:Above-ground hose-end and movable sprinkler units serve temporary or small-scale residential needs.
Retrofit Installations dominate near-term project volume. New Installations concentrate where regulatory deadlines force complete infrastructure replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel exports precision drip technology to California's agricultural corridor and Australia's Murray-Darling Basin, establishing a trade-flow corridor that shapes smart irrigation deployment patterns in water-stressed growing regions.
United States
California's Central Valley almond growers and Arizona municipal golf courses drive sensor-controller retrofit demand. EPA WaterSense certification requirements tighten eligibility for municipal procurement contracts. Phoenix and Scottsdale bond-financed golf renovations require documented water savings to satisfy sustainability covenants.
Australia
Murray-Darling Basin cotton and rice operators deploy edge-computing valve controllers to eliminate connectivity dependency during network outages. Water Efficiency Labelling standards enforce flow verification and audit logging for agricultural financing eligibility. Victoria and New South Wales irrigation districts concentrate retrofit-ready smart valve specification.
Israel
Decades of drip specialization anchor precision agriculture exports to arid growing regions worldwide. National water scarcity policies mandate leak detection and remote shutoff capabilities across all subsidized agricultural equipment. NETAFIM's headquarters in Tel Aviv anchors R&D concentration for pressure-compensating emitter technology.
Spain
Mediterranean olive and citrus growers face tight EU Green Deal farm-to-fork compliance deadlines for flow verification. REACH-compliant smart controllers qualify for sustainability-linked agricultural financing across Andalusia and Valencia. Seville and Murcia irrigation cooperatives concentrate demand for retrofit-ready valve systems.
China
Xinjiang cotton plantations and Shandong vegetable greenhouses adopt IoT-connected controllers to meet provincial water conservation targets. Dual carbon goals and agricultural modernization policies subsidize precision irrigation equipment in water-stressed northern provinces. The Yangtze River Delta and North China Plain concentrate manufacturing capacity for sensor arrays and valve actuators.
Smart Sprinkler Irrigation Systems Market Competitive Environment
On the supply side, the industry is fragmented across specialized drip manufacturers, consumer automation software developers, and professional-grade commercial equipment suppliers. Three strategic archetypes dominate: precision agriculture specialists with decades of irrigation engineering heritage, consumer-facing platform companies leveraging mobile app ecosystems, and commercial landscaping equipment providers with contractor distribution networks. M&A activity concentrates on sensor-controller convergence capabilities, while geographic expansion targets EU Green Deal subsidy corridors and California SGMA compliance zones.
Among precision agriculture specialists, NETAFIM exemplifies the engineering heritage archetype through its Tel Aviv-based drip specialization. Rachio and Hunter Industries occupy distinct positioning vectors—Rachio represents consumer-facing automation software simplified for residential zone scheduling, while Hunter Industries anchors professional-grade wireless networks built for large-scale property management. These three companies illustrate how technical specialization and channel strategy fragment competitive positioning across end-use segments.
| Leading Market Players |
|---|
| The Toro Company |
| Rain Bird Corporation |
| Hunter Industries |
| NETAFIM |
| HydroPoint |
| Rachio |
| Weathermatic |
| Orbit Irrigation Products |
| Netro |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese sensor array manufacturing is compressing controller margins while simultaneously enabling aggressive pricing for retrofit-ready valve systems across California's Central Valley and Australia's Murray-Darling Basin. This utilization asymmetry between component oversupply and finished-goods tightness reshapes how suppliers allocate pricing power across hardware tiers.
Pricing Analysis
Current-generation edge-computing valve controllers command substantial premiums over prior-generation cloud-dependent units, while next-generation AI-inference models remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels stratifies by EPA WaterSense certification status and after-sales telemetry bundling. Pricing pressure stems from copper and semiconductor input volatility that OEM margins struggle to absorb. Residential users in California and Florida exhibit highest price sensitivity, while agricultural producers in groundwater-stressed districts prioritize flow-verification capabilities over unit cost.
Supply Chain Analysis
Brass valve castings draw from foundry capacity concentrated in China, Taiwan, and Vietnam, while pressure-compensating emitters hinge on polymer compounding expertise centered in Israel and Germany. Semiconductor components for sensor arrays and wireless modules rest on fabrication capacity in South Korea and Japan. Single-source vulnerability around LoRa radio chipsets creates procurement risk for controller manufacturers targeting bandwidth-constrained rural zones. Distribution runs through irrigation contractor networks for commercial and agricultural segments, with big-box retail and direct-to-installer platforms capturing residential channel velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
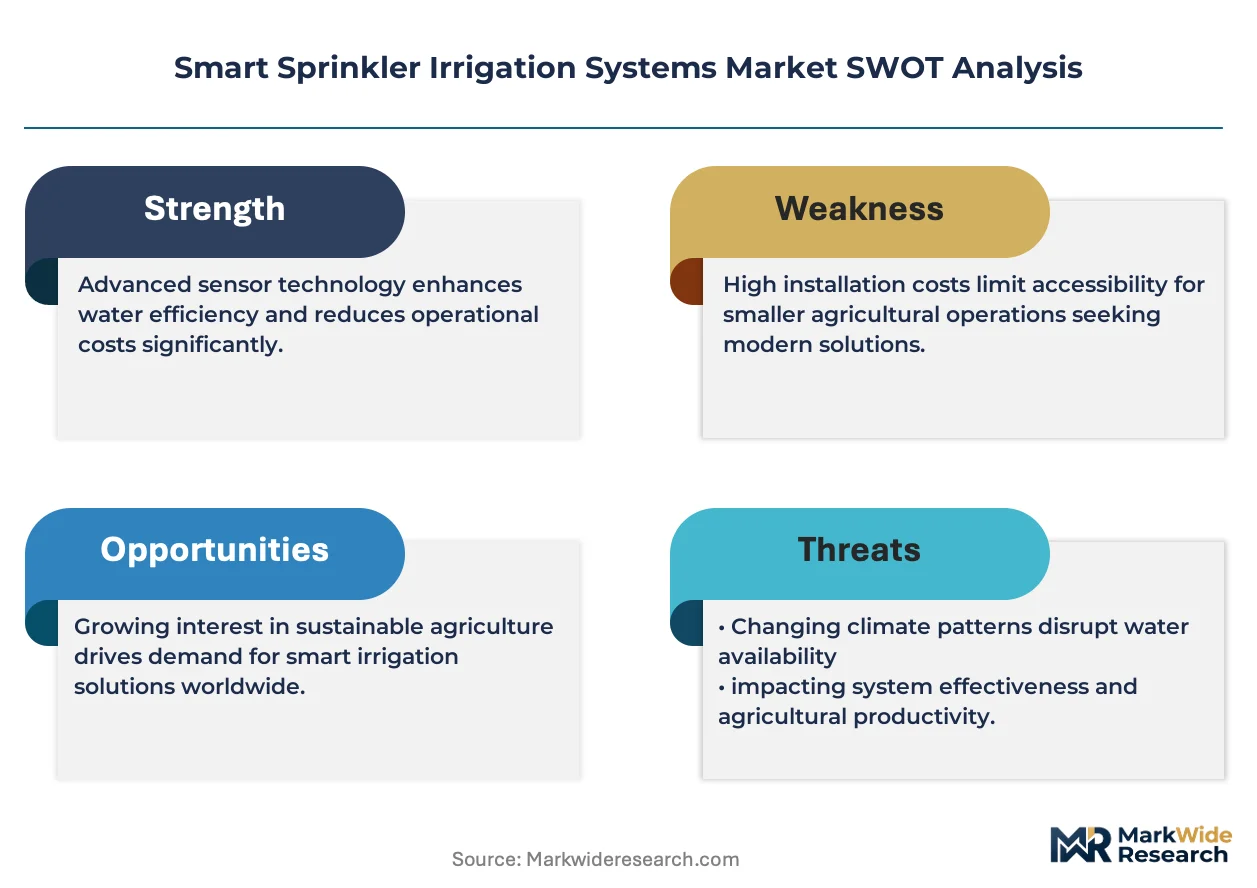
Smart sprinkler irrigation systems are approaching a platform-economics inflection where proprietary wireless protocols fragment into interoperable mesh standards, reshaping competitive moats from hardware lock-in toward data-layer network effects.
For Market Incumbents: Pre-empt sensor-controller convergence through backward integration into soil moisture probe manufacturing, neutralizing emerging entrants' hardware bundling advantage. Anchor certification investment in EPA WaterSense and EU Green Deal compliance to defend municipal and agricultural bid eligibility against lower-cost substitutes. Prioritize firmware update infrastructure that extends controller lifecycles and defends against replacement-cycle compression. For New Entrants and Emerging Players: Mid-market commercial landscapers in water-stressed U.S. Sun Belt metros represent the most penetrable entry point, as this segment lacks dedicated platform solutions between consumer-grade automation and enterprise-scale wireless networks. Target golf course superintendents in Arizona and Florida with sensor-controller integrated units that reduce procurement complexity. Pursue direct-to-installer digital channels that bypass entrenched contractor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across consumer-facing automation software, reducing barrier-to-entry estimates for platform plays. Long-term viability favors precision agriculture specialists with captive drip technology and proven regulatory compliance pathways. Acquisition target archetype: sensor-hardware developers with REACH-compliant product lines and established EU distribution. Monitor EPA WaterSense installer certification bottlenecks as signal for contractor consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Controller Convergence | Integrated soil moisture-actuated valve units reduce installation complexity for golf course superintendents. |
| EU Green Deal Certification Pathway | REACH-compliant controllers unlock sustainability-linked agricultural financing across Mediterranean growing regions. |
| Edge Computing Architecture Deployment | Valve-embedded processing eliminates cloud latency for Murray-Darling Basin operators facing connectivity outages. |
| Direct-to-Installer Platform Launch | Digital procurement bypasses traditional irrigation contractor networks for residential channel velocity. |
| Backward Integration into Sensor Manufacturing | Captive supply of capacitance probes defends margin position against semiconductor input volatility. |
Study Parameters
The analysis maps smart controller hardware, sensor arrays, connectivity protocols, and automation software tiers, each validated through irrigation equipment procurement managers, golf course superintendents, agricultural district water officers, and municipal facilities directors. Primary fieldwork combined with secondary validation from EPA WaterSense certification databases, EU Green Deal subsidy registries, California Department of Water Resources SGMA basin plans, and Australia Water Efficiency Labelling standards. Bottom-up equipment shipment tracking and top-down agricultural water use intensity modeling provide cross-verification.
Assumptions held fixed include regulatory enforcement timelines for California SGMA compliance and EU farm-to-fork targets, while commodity input pricing and wireless protocol standardization were treated as variable sensitivities. The forecast framework segments by product type, technology architecture, end-user category, and installation mode, with CAGRs derived from replacement-cycle analysis and regulatory deadline clustering. Modeled inputs include evapotranspiration data API adoption rates and edge-computing controller penetration across bandwidth-constrained zones.
Practitioners should monitor EPA WaterSense specification revisions and EU Green Deal subsidy eligibility criteria for early signals of demand inflection. Forecasts reflect assumptions around copper and semiconductor pricing stabilization and interoperability standardization timelines. Cross-checking against California Department of Water Resources groundwater extraction reporting and Australia Bureau of Meteorology irrigation water use surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Global Fruit Picker Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
Asia-Pacific Irrigation Machinery Market
Farm Equipment and Irrigations
Farm Equipment Rental Market