
 Non-Agriculture Smart Irrigation Controllers Market | 2026-2036
Non-Agriculture Smart Irrigation Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Agriculture Smart Irrigation Controllers Market Outlook
The hardware-software capability gap between legacy manufacturers and cloud-native entrants is unwinding competitive assumptions in this space. Rain Bird Corporation leverages decades of valve and sprinkler integration to sustain installed-base loyalty among landscape contractors. Rachio Inc. differentiates through direct-to-consumer app ecosystems and Wi-Fi controller simplicity. HydroPoint Data Systems, Inc. anchors municipal and enterprise accounts with weather-data-driven automation platforms.
Non-agriculture smart irrigation controllers are networked devices that regulate landscape water delivery through soil moisture thresholds, evapotranspiration algorithms, and remote command interfaces, typically operating on 24-volt AC solenoid circuits with IP-rated outdoor enclosures. Their commercial purpose is to reduce potable water consumption in turf and ornamental applications while maintaining plant health through data-driven scheduling. Wi-Fi controllers and cloud-based systems now capture the bulk of new residential and commercial installations, while moisture sensors command premium pricing in water-stressed jurisdictions where rebate programs require soil-monitoring verification. Golf course applications remain a specialized margin pool where multi-zone precision and salinity management justify higher controller investment.
EPA WaterSense specifications and state-level drought ordinances in California, Texas, and Florida shape product certification requirements and rebate eligibility for controller replacements. The EU Green Deal and F-Gas Regulation indirectly pressure irrigation equipment suppliers to document embedded carbon and refrigerant-free manufacturing even in outdoor electronics categories. Stakeholders must monitor how municipal procurement shifts from standalone hardware bids to outcome-based water-savings contracts that bundle installation, cloud service, and performance guarantees.
Market Dynamics
The transition from timer-based irrigation to evapotranspiration-driven automation is restructuring competitive advantage around data platform ownership rather than valve hardware manufacturing. Cloud-native controllers now capture specification authority in municipal RFPs previously dominated by legacy irrigation contractors.
Growth Catalysts
- EPA WaterSense Certification:Federal rebate eligibility requirements in the United States mandate third-party water efficiency verification, accelerating replacement of non-certified timers in drought-stressed municipalities.
- Soil Moisture Sensor Integration:California's turf replacement ordinances now require soil-monitoring verification for rebate qualification, driving demand for sensor-compatible controller architectures.
- Municipal Streetscape Procurement:Cities including Los Angeles, Phoenix, and San Antonio are bundling smart irrigation into climate resilience infrastructure packages, creating concentrated demand pools for weather-data-driven systems.
Market Restraints
- Semiconductor Supply Concentration:Wi-Fi module and microcontroller sourcing remains concentrated among Taiwanese and South Korean foundries, exposing controller manufacturers to allocation volatility.
- Copper Solenoid Coil Costs:24-volt AC valve actuators depend on copper winding supply, with price volatility transmitted directly to controller bill-of-materials.
- Interoperability Fragmentation:Absence of unified communication protocols between soil sensor brands and controller hardware forces redundant sensor purchases, inflating system costs.
Strategic Opportunities
- Golf Course Precision Irrigation:Salinity management and multi-zone turf health monitoring justify premium controller investment at facilities seeking reduced water budgets without playability degradation.
- Outcome-Based Water Savings Contracts:Municipal procurement in Texas and Florida is pivoting from hardware purchase to performance-guaranteed service agreements bundling installation, cloud analytics, and verified consumption reduction.
- LoRaWAN Network Convergence:Integration of low-power wide-area connectivity with existing Wi-Fi infrastructure enables battery-powered sensor deployment beyond residential router range.
Industry Challenges
- Field Technician Skill Gap:Installation and calibration of ET-based scheduling requires hydrology literacy absent from traditional landscape contractor training programs.
- Legacy Timer Replacement Complexity:Retrofit projects in established commercial landscapes face physical enclosure constraints and existing valve wiring degradation that complicate smart controller integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Agriculture Smart Irrigation Controllers Market |
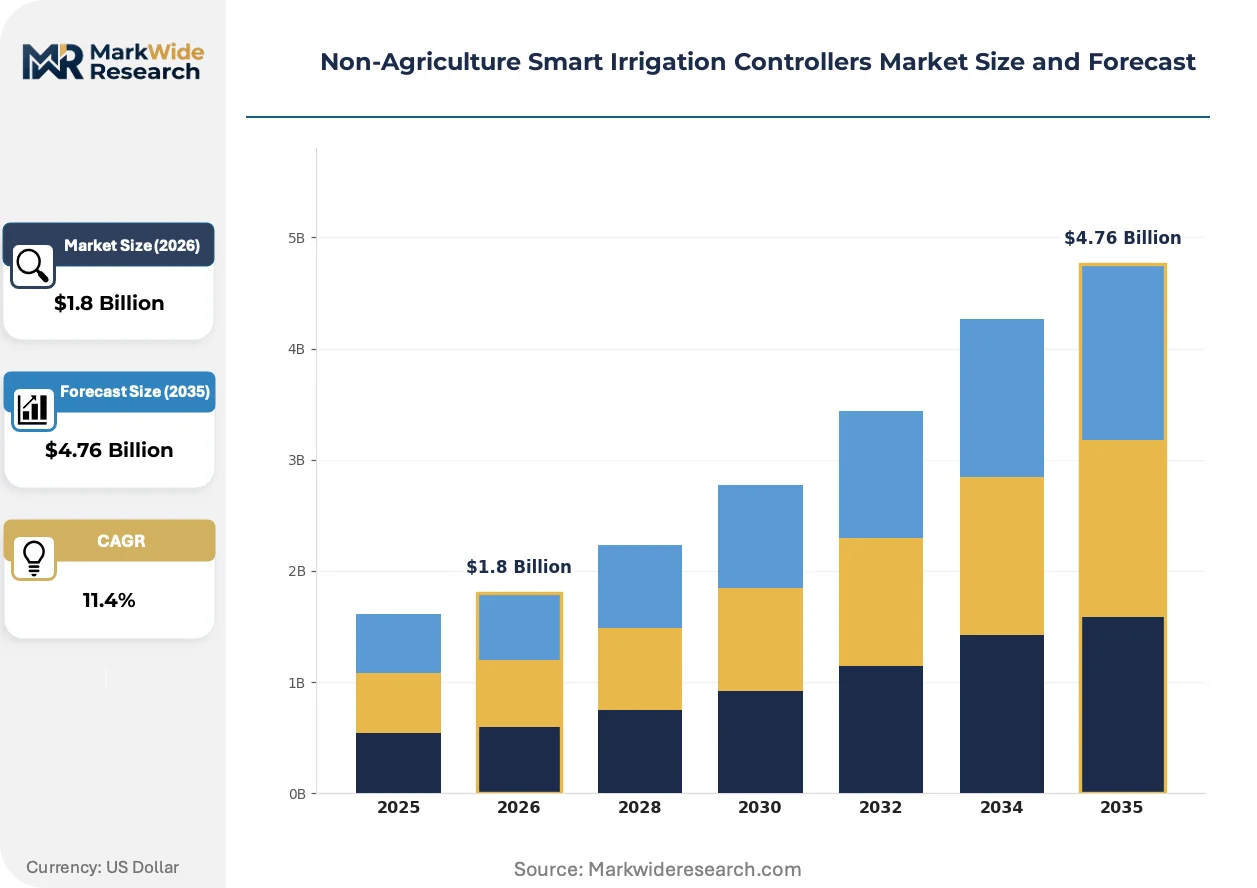
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Controllers, Moisture Sensors, Cloud-Based Systems, Soil Sensors Application: Residential Gardens, Commercial Landscaping, Public Parks, Golf Courses Technology: Automation, Remote Monitoring, Bluetooth Connectivity, Data Analytics End User: Homeowners, Landscape Contractors, Property Managers, Municipalities |
| Companies Covered | Rain Bird Corporation, Hunter Industries, The Toro Company, Rachio Inc., Weathermatic, HydroPoint Data Systems, Inc., Skydrop, LLC, CALSENSE, Galcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Agriculture Smart Irrigation Controllers Market Strategic Shifts
Algorithmic irrigation scheduling is displacing fixed-timer conventions across residential, commercial, and municipal verticals. Three concurrent developments are compressing product lifecycles and reshaping specification authority.
Evapotranspiration-based scheduling engines are supplanting day-interval timers in municipal park departments and homeowner associations. Los Angeles Department of Recreation and Parks has standardized ET-driven controllers across its portfolio, with maintenance crews now trained on cloud dashboard interpretation rather than manual dial adjustment. This capability shift is compressing replacement cycles from ten-year hardware lifespans to five-year software-refresh horizons.
The EU F-Gas Regulation is extending carbon documentation requirements to outdoor electronics categories, pressuring irrigation equipment suppliers to quantify embedded emissions in IP-rated enclosures and circuit boards. German municipal procurement offices now include lifecycle carbon scoring in smart irrigation tender evaluations, favoring manufacturers with documented refrigerant-free assembly processes and regional component sourcing.
Homeowner purchasing patterns are fragmenting away from contractor-mediated specification toward direct-to-consumer research and installation. Rachio and similar Wi-Fi-first brands have cultivated app-store visibility and retail distribution that bypasses traditional irrigation dealer networks. This channel compression is most pronounced in California and Texas single-family residential segments, where rebate program websites now link directly to qualified product SKUs rather than certified installer directories.
Non-Agriculture Smart Irrigation Controllers Market Segmentation
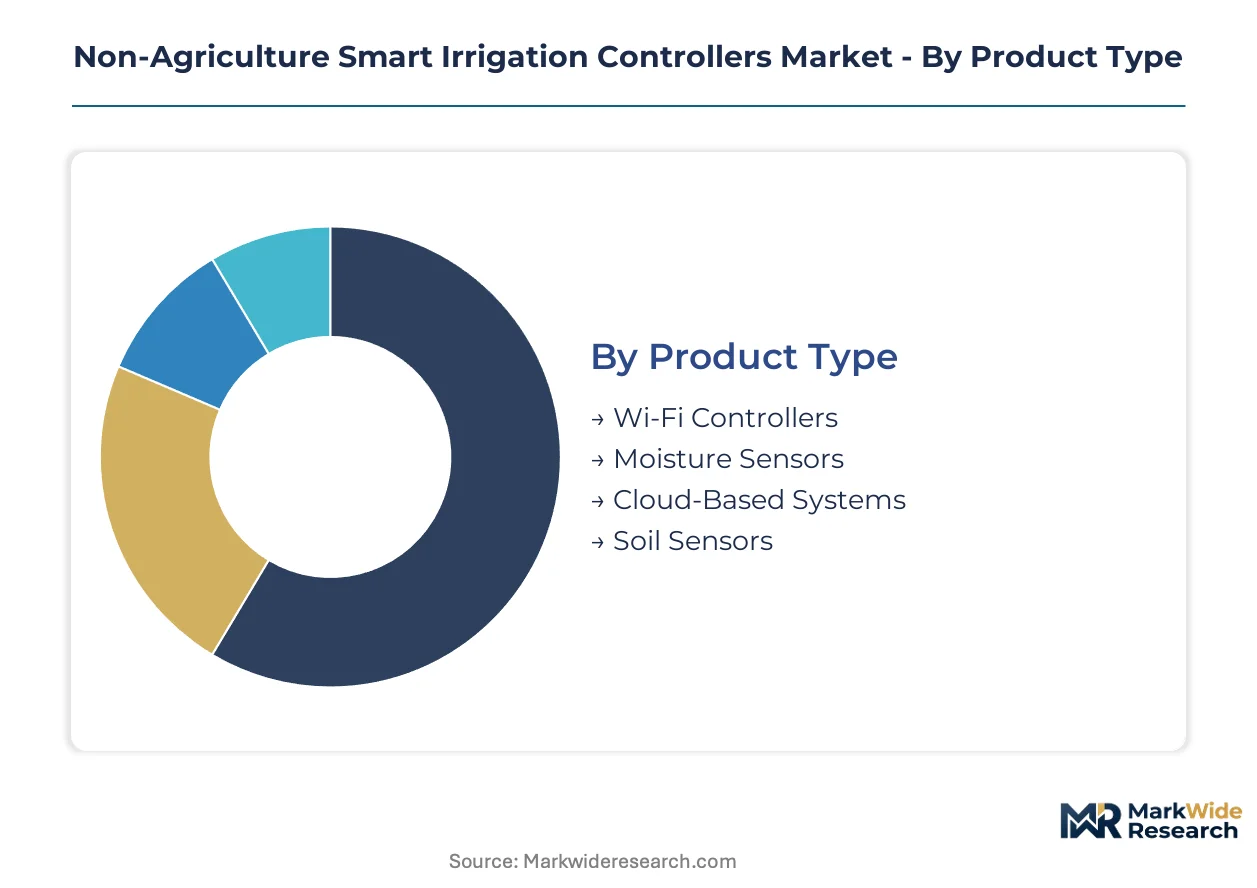
Product architecture and installation context fragment the Non-Agriculture Smart Irrigation Controllers Market into distinct specification environments. Each segment carries unique certification requirements, rebate eligibility rules, and procurement channel preferences that reshape competitive positioning.
Product Type:
Domestic manufacturing concentrates in Wi-Fi controllers and cloud-based systems, while soil sensors and moisture sensors rely heavily on specialized sensor foundries in Taiwan and South Korea. Export dependency varies sharply across hardware categories.
- Wi-Fi Controllers:These 24-volt AC solenoid devices integrate residential routers with IP-rated outdoor enclosures for smartphone scheduling. Demand clusters in California and Texas single-family residential markets where EPA WaterSense rebate programs mandate connected-device verification for qualification.
- Moisture Sensors:Capacitance-based probes measure volumetric water content at root-zone depth to trigger irrigation cycles. California turf replacement ordinances now require soil-monitoring verification, accelerating specification in drought-stressed municipalities including Los Angeles and San Diego.
- Cloud-Based Systems:ET-driven automation platforms aggregate weather data across multiple zones through centralized dashboards. Municipal park departments in Phoenix and San Antonio bundle these into climate resilience infrastructure contracts.
- Soil Sensors:Tensiometers and gypsum block sensors measure matric potential for precision agriculture crossover applications. Golf course superintendents in Florida deploy these for salinity management on coastal layouts.
Wi-Fi controllers command the established base. The steepest expansion runs through moisture sensors.
Application:
Cost tier separation distinguishes premium precision installations from mass-market residential deployments. Golf courses and public parks justify sensor-dense configurations that residential gardens cannot support.
- Residential Gardens:Single-family homeowners prioritize app simplicity and DIY installation over zone density. Rachio and similar direct-to-consumer brands bypass traditional irrigation dealers through retail and online channels in California and Texas rebate programs.
- Commercial Landscaping:Property management firms at office parks and retail centers demand multi-zone scalability with centralized billing visibility. Landscape contractors specify these through wholesale distribution relationships.
- Public Parks:Municipal procurement departments in Los Angeles, Phoenix, and San Antonio issue RFPs bundling installation, cloud service, and verified water savings into performance-guaranteed contracts. ET-driven scheduling engines are now standardized across these portfolios.
- Golf Courses:Salinity management and multi-zone turf health monitoring justify premium controller investment. Florida coastal facilities and Arizona desert layouts represent concentrated demand for precision irrigation with flow-sensing fault detection.
Residential gardens anchor volume. Golf courses deliver margin concentration.
Technology:
Maturity gradients separate proven automation from emerging connectivity protocols. Bluetooth and LoRaWAN represent capability extensions rather than core scheduling functions.
- Automation:Evapotranspiration algorithms and soil-moisture threshold triggers displace fixed-interval timers across all installation scales. Los Angeles Department of Recreation and Parks has standardized ET-driven controllers, compressing replacement cycles from ten-year hardware lifespans to five-year software refresh horizons.
- Remote Monitoring:Cloud dashboards enable real-time flow detection and valve fault alerts for municipal maintenance crews. This capability is reshaping specification authority in municipal RFPs previously dominated by legacy irrigation contractors.
- Bluetooth Connectivity:Short-range pairing supports field technician configuration without Wi-Fi infrastructure. Landscape contractors deploy these for initial setup in commercial zones with weak router coverage.
- Data Analytics:Consumption benchmarking and predictive maintenance algorithms aggregate across controller fleets. Enterprise accounts and municipal water districts subscribe to these as premium service tiers.
Automation underpins every installation. Remote monitoring is climbing the fastest as a differentiation layer.
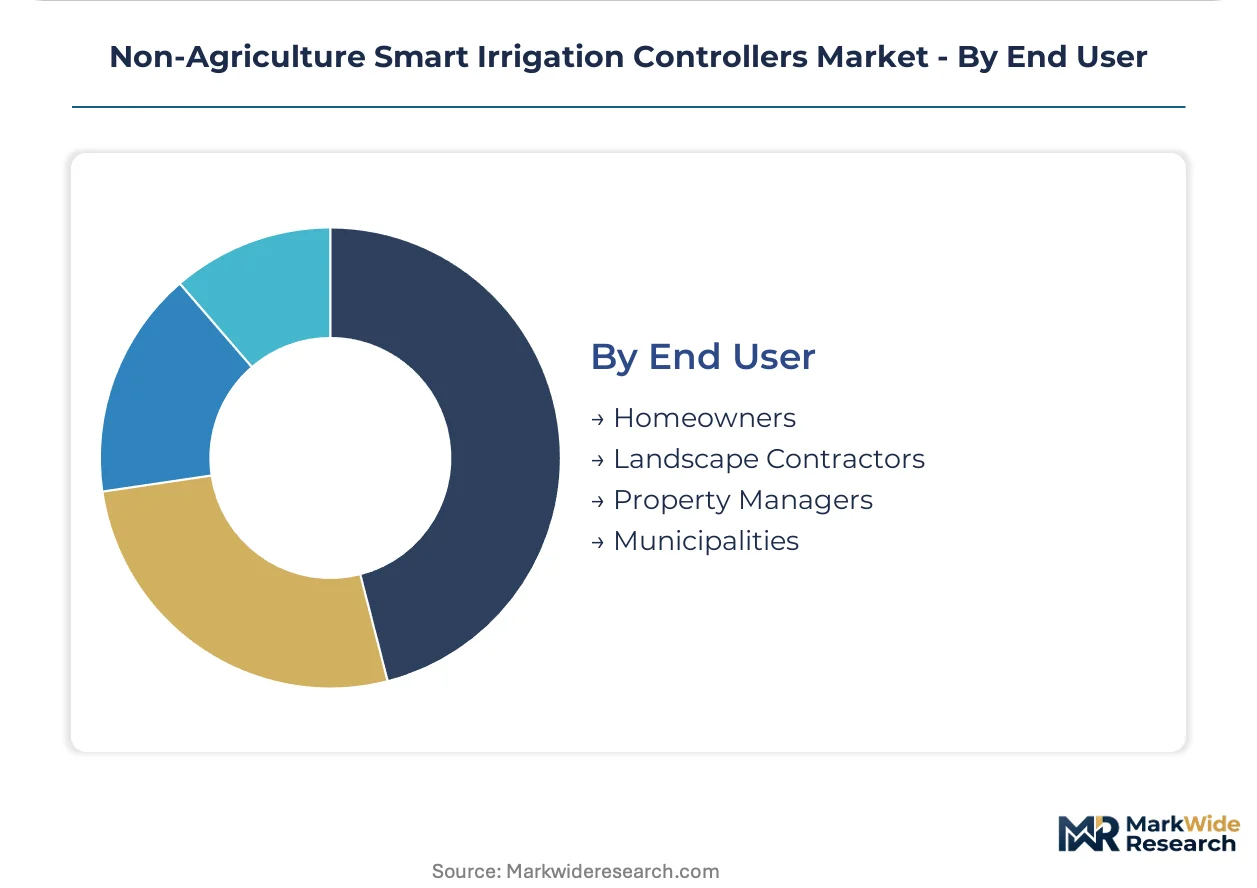
End User:
Customer type determines procurement channel and specification authority. Direct-to-consumer purchasing fragments traditional contractor-mediated distribution in residential segments.
- Homeowners:Rebate program websites in California and Texas now link directly to qualified product SKUs rather than certified installer directories. App-store visibility and retail placement drive brand selection.
- Landscape Contractors:These installation professionals maintain loyalty to legacy valve-integrated brands like Rain Bird through wholesale distribution and training certification programs.
- Property Managers:Commercial real estate firms prioritize outcome-based water savings contracts with performance guarantees over hardware purchase. Texas and Florida procurement is pivoting toward this model.
- Municipalities:Cities bundle smart irrigation into climate resilience infrastructure packages with ET-driven standardization. Procurement shifts from standalone hardware bids to service agreements bundling cloud analytics and verified consumption reduction.
Landscape contractors control the installed base. Municipalities are gaining share fastest as concentrated demand pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geographic consumption patterns diverge sharply between drought-stressed jurisdictions with rebate-driven replacement cycles and temperate regions where water efficiency remains a discretionary upgrade. Municipal procurement concentrates in water-scarce economies, while residential adoption spreads through retail channels in rebate-eligible states.
United States
California, Texas, and Florida dominate specification volume through municipal streetscape procurement and turf replacement incentives. EPA WaterSense certification requirements shape product eligibility for federal rebate programs. Los Angeles, Phoenix, and San Antonio bundle connected irrigation into climate resilience infrastructure contracts with performance-guaranteed water savings.
Germany
Municipal park departments prioritize lifecycle carbon scoring in tender evaluations under EU Green Deal implementation. The F-Gas Regulation extends embedded emissions documentation requirements to outdoor electronics categories. Procurement offices in Berlin and Munich now favor manufacturers with refrigerant-free assembly processes and regional component sourcing.
China
Urban greening initiatives in water-scarce northern municipalities drive specification of ET-driven automation for public landscapes. National dual carbon goals pressure equipment suppliers to document manufacturing emissions. Beijing and Tianjin park authorities pilot weather-data-driven systems as part of sponge city infrastructure investments.
Australia
Metropolitan water utilities in Sydney and Melbourne mandate smart controller installation for new commercial landscaping permits. State-level drought response frameworks align product certification with efficiency benchmarking requirements. Perth and Adelaide municipal portfolios have standardized remote monitoring capabilities across public park irrigation networks.
United Kingdom
Water company leakage reduction targets indirectly pressure commercial landscape efficiency through consumption benchmarking programs. The Environment Agency's abstraction licensing reforms tighten outdoor water use compliance for golf and hospitality sectors. London borough councils pilot LoRaWAN-connected sensor networks in street tree irrigation systems.
Non-Agriculture Smart Irrigation Controllers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in a structure defined by data platform ownership rather than valve hardware manufacturing. Legacy irrigation manufacturers leverage decades of contractor relationships and valve integration expertise. Cloud-native entrants capture specification authority through direct-to-consumer channels and municipal RFPs. Competitive moves center on outcome-based service contract bundling and low-power wide-area connectivity integration.
Among the integrated tier, Rain Bird Corporation exemplifies the legacy manufacturer archetype with sustained contractor loyalty through wholesale distribution and training certification programs. Rachio Inc. occupies the cloud-native position with direct-to-consumer app ecosystems and retail channel presence. HydroPoint Data Systems, Inc. anchors the municipal and enterprise segment with weather-data-driven automation platforms.
| Leading Market Players |
|---|
| Rain Bird Corporation |
| Hunter Industries |
| The Toro Company |
| Rachio Inc. |
| Weathermatic |
| HydroPoint Data Systems, Inc. |
| Skydrop, LLC |
| CALSENSE |
| Galcon |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for Wi-Fi modules and microcontroller shipments concentrate pricing power among Taiwanese and South Korean foundries, while copper coil volatility in 24-volt AC solenoid circuits transmits directly to controller bill-of-materials and shapes tiered pricing strategies across residential and municipal buyer segments.
Pricing Analysis
Long-term offtake agreements dominate municipal procurement in California, Texas, and Florida, where performance-guaranteed water savings contracts bundle installation, cloud service, and verified consumption reduction. Price differentiation hinges on EPA WaterSense certification tier and sensor integration depth, with rebate-eligible controllers commanding premium positioning. Pricing pressure stems from semiconductor allocation volatility and copper solenoid coil cost swings. Residential homeowners exhibit highest price sensitivity through direct-to-consumer channels, while golf course operators tolerate premium tiers for salinity management capabilities.
Supply Chain Analysis
Inbound logistics costs through the Trans-Pacific trade lane expose controller manufacturers to container availability fluctuations and port congestion at Long Beach and Los Angeles. Manufacturing concentrates in China for PCB assembly and enclosure fabrication, Taiwan for Wi-Fi modules, and South Korea for advanced microcontrollers. Raw material dependencies center on copper winding supply, IP-rated polymer resins, and weather-data API licensing. Single-source vulnerability in semiconductor foundry capacity represents the dominant structural risk. Distribution runs through wholesale irrigation dealer networks for contractor-mediated sales, with direct-to-consumer e-commerce channels fragmenting residential procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by municipal infrastructure refresh cycles in drought-stressed jurisdictions, where climate resilience funding and turf replacement ordinances synchronize replacement demand across California, Texas, and Florida.
For Market Incumbents: Fortify installed-base loyalty through backward integration into sensor manufacturing and captive cloud analytics development. Rain Bird Corporation and Hunter Industries should deepen contractor certification programs to counter cloud-native entrants like Rachio Inc. capturing specification authority in municipal RFPs. Priority investment in LoRaWAN connectivity modules defends against low-power wide-area challengers.
For New Entrants and Emerging Players: EPA WaterSense certification fast-track programs unlock rebate-eligible positioning in California and Texas single-family residential segments, the most penetrable white-space target. Municipal streetscape procurement in Phoenix and San Antonio offers concentrated demand pools with less entrenched legacy relationships. Direct-to-consumer app ecosystem development bypasses wholesale dealer networks entirely.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming irrigation divisions lacking cloud platform capabilities. Long-term viability over the coming decade rests on data platform ownership rather than valve hardware manufacturing. Watch for inflection signals in municipal procurement language shifting from hardware specifications to outcome-based water savings guarantees.
| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Service Contract Bundling | Transforms municipal procurement from hardware purchase to performance-guaranteed water savings agreements in Texas and Florida. |
| LoRaWAN Network Integration | Enables battery-powered sensor deployment beyond residential router range for municipal park applications. |
| EPA WaterSense Certification Investment | Unlocks federal rebate eligibility and state-level turf replacement incentive qualification in drought-stressed jurisdictions. |
| Backward Integration into Sensor Manufacturing | Reduces dependency on Taiwanese and South Korean foundries for soil moisture probe supply. |
| Direct-to-Consumer Channel Development | Bypasses traditional irrigation dealer networks through retail placement and app-store visibility in California residential markets. |
Study Parameters
The analysis maps Wi-Fi controllers, moisture sensors, cloud-based systems, and soil sensor sub-sectors, each validated through landscape contractors, municipal procurement officers, golf course superintendents, and property management executives. Primary interviews with irrigation equipment distributors and cloud platform engineers combined with secondary validation against EPA WaterSense certification databases, municipal RFP archives, and rebate program eligibility lists. Bottom-up unit shipment estimates triangulated against top-down water utility consumption benchmarking data.
Consistency checks validated volume and value outputs against weather-data API subscription growth, semiconductor foundry allocation reports, and copper commodity price indices. The forecast framework segments by product architecture, application context, technology maturity, and end-user procurement channel across the projection horizon. CAGRs derived from replacement cycle compression observations, software refresh horizon shortening, and municipal infrastructure spending patterns. Industry-specific inputs include evapotranspiration algorithm adoption curves and soil-monitoring verification mandate expansion.
Underlying assumptions cover sustained drought ordinance enforcement, semiconductor supply normalization, and copper price stabilization, with deviation risk concentrated in municipal budget austerity and rebate program funding discontinuation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Agriculture
Global Blockchain in Agriculture Market
Smart Agriculture
Smart Livestock Farming Market
Smart Agriculture
Smart Irrigation Software Market
Smart Agriculture
Artificial Intelligence (AI) in Agriculture Market
Smart Agriculture
Intelligent Agricultural Drone Market
Smart Agriculture
Global IoT in Agriculture Market
Smart Agriculture
Smart Farm Management Software Market
Smart Agriculture
Global Agrivoltaics Market
Smart Agriculture
Smart Irrigation Controllers Market
Smart Agriculture
Smart Tractor Market
Smart Agriculture
Asia-Pacific Smart Agriculture Market
Smart Agriculture
Smart Harvest Market
Smart Agriculture
Smart Agriculture Market
Smart Agriculture
Smart Farming Market
Smart Agriculture
Autonomous Farm Vehicle Market
Smart Agriculture
Smart Agricultural Drone Market