
 North America Oats Market | 2026-2036
North America Oats Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oats Market Intelligence
Single-serve oatmeal cups and modular breakfast kits are restructuring how consumers purchase oats, moving volume away from bulk bags toward portion-controlled formats. PepsiCo's Quaker Oats Company leverages its refrigerated supply chain to dominate ready-to-eat oat platforms across U.S. grocery channels. Bob's Red Mill Natural Foods sustains its position through heritage stone-milling specialization and gluten-free certification protocols. General Mills competes by extending Cheerios oat-based formulations into protein-fortified variants targeting adult nutrition segments.
Oats are cereal grains from Avena sativa, containing beta-glucan soluble fiber at 3-5% by weight, processed through steaming, flaking, or cutting to modify cooking time and texture for human food and animal feed applications. Rolled oats and instant oats lead product type segments due to their convenience positioning in North American breakfast routines, while steel-cut oats capture premium shelf space through slower digestion claims and artisanal branding. Snack foods and bakery products represent the fastest-growing end-use categories as oat flour replaces refined wheat in clean-label formulations, with granola bars and oat milk driving form innovation toward flakes and powder.
The FDA regulates oat health claims through qualified cardiovascular benefit labeling, while the USDA Organic seal and Non-GMO Project verification shape premium market access across U.S. and Canadian retail. Canada's Food and Drug Regulations enforce oat fiber content thresholds for cholesterol-reduction claims, creating formulation compliance costs that favor scaled processors. Stakeholders must monitor how evolving whole grain definitions from Health Canada and the FDA intersect with plant-based protein fortification trends to determine R&D allocation and label strategy.
Market Dynamics
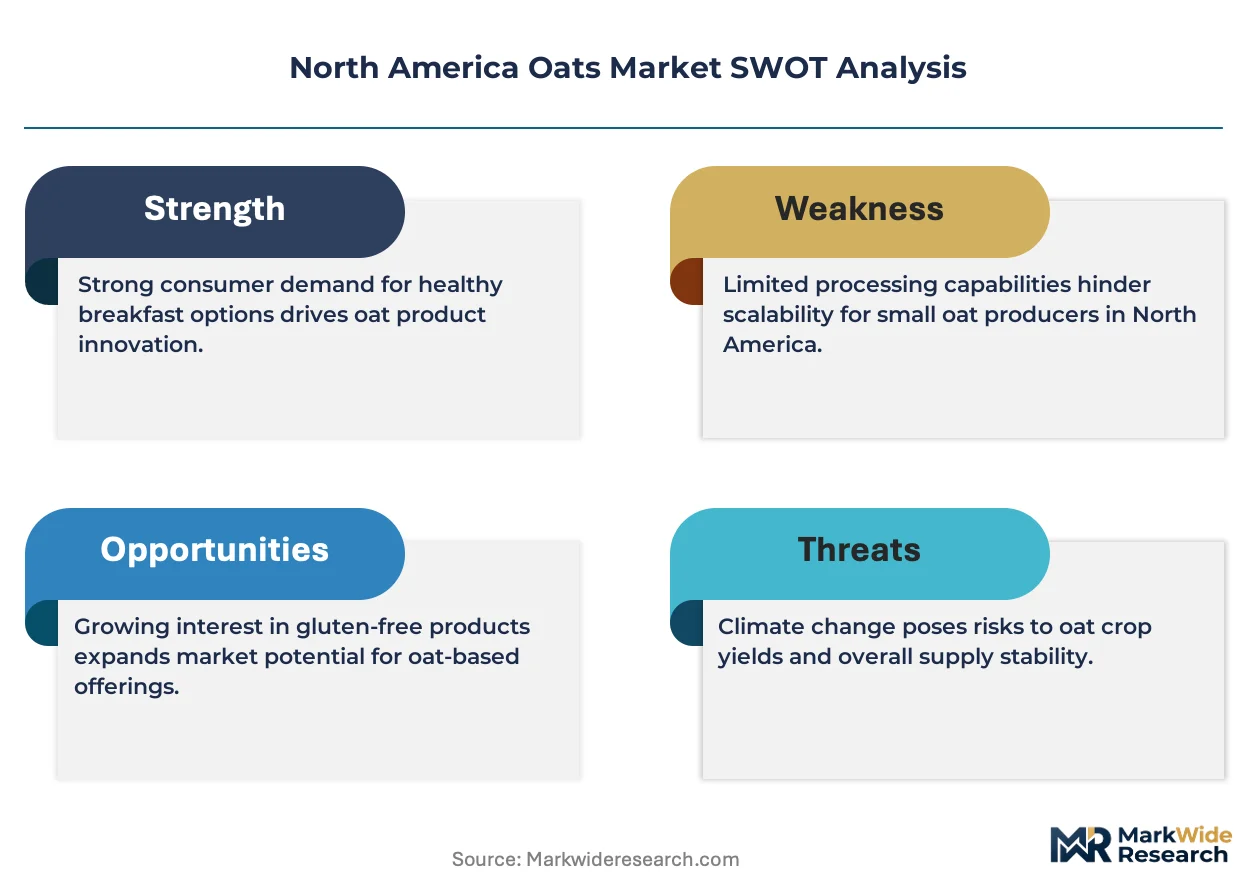
The FDA's qualified cardiovascular health claim for oat beta-glucan is restructuring formulation priorities across U.S. and Canadian food manufacturing, forcing processors to recalibrate fiber thresholds in product development pipelines.
Growth Catalysts
- USDA Organic certification expansion:Contract farming networks around Minneapolis and Winnipeg corridors are scaling acreage under organic protocols, channeling premiums into processor R&D budgets.
- Plant-based protein substitution:Bakery and snack food manufacturers are reformulating with oat flour to displace refined wheat in clean-label positioning.
- Single-serve format proliferation:Refrigerated supply chain investments by major retailers are enabling ready-to-eat oatmeal cup distribution across convenience channels.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings hit organic oat growers disproportionately, compressing contract margins in the U.S. Midwest.
- Supply concentration risk:Processing infrastructure clusters around Minneapolis-St. Paul and Winnipeg create geographic vulnerability to weather-driven crop failures.
- Regulatory friction:Canada's Food and Drug Regulations impose cholesterol-reduction claim thresholds that require specialized testing, favoring scaled processors over regional mills.
Strategic Opportunities
- Oat milk white space:Canadian retail channels show underpenetration in barista-format oat milk relative to U.S. penetration rates, creating import and local production openings.
- Dual carbon convergence:Renewable energy procurement by processors is intersecting with regenerative agriculture certifications to unlock ESG-linked financing.
- Direct-to-subscription channels:Modular breakfast kit platforms are bypassing traditional grocery slotting fees, capturing lifetime value through recurring revenue models.
Industry Challenges
- Gluten-free certification complexity:Cross-contamination protocols for oat processing require dedicated facility segments, extending capital deployment timelines.
- Stone-milling talent scarcity:Heritage milling expertise concentrates in aging workforces, constraining artisanal brand expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oats Market |
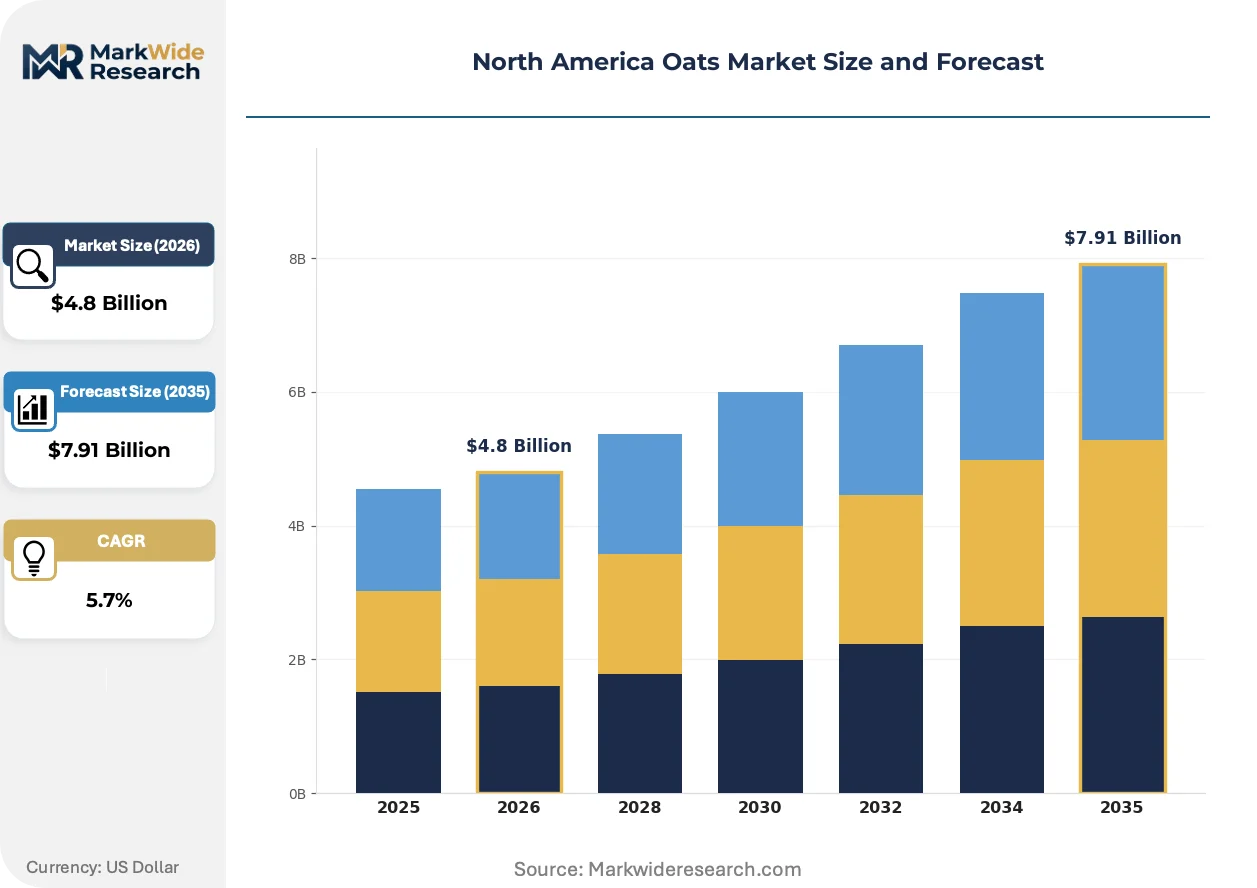
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oats, Rolled Oats, Steel-Cut Oats, Whole Oat Groats End Use: Breakfast Cereals, Snack Foods, Bakery Products, Nutritional Supplements Form: Flakes, Flour, Granules, Powder Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Nestlé, Bob's Red Mill Natural Foods, PepsiCo (Quaker Oats Company), Grain Millers, Nature's Path Foods, General Mills, Post Holdings, The Scoular Company, Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oats Market Strategic Shifts & Innovations
Refrigerated supply chain expansion is unlocking format innovation that was previously constrained by shelf-stable limitations, while regulatory precision around health claims is sharpening competitive differentiation.
High-pressure processing technology is absorbing into oat milk production lines, extending refrigerated shelf life without thermal degradation of beta-glucan content. Beverage manufacturers in California and New York are adopting HPP units at pace, compressing the window between production and consumption while enabling cleaner ingredient decks. This is absorbing capital that previously flowed into aseptic packaging infrastructure, reshaping equipment vendor priorities.
The FDA's updated Nutrition Facts label requirements are forcing disclosure of added sugars in flavored oatmeal products, prompting reformulation toward unsweetened base products with on-pack fruit inclusion. Breakfast cereal manufacturers are responding by stripping sugar content and repositioning around intrinsic oat sweetness. Adult nutrition segments show the most pronounced product line restructuring, with protein-fortified variants gaining shelf space formerly occupied by heritage formulations.
Retail buyer consolidation is compressing supplier negotiation cycles, with Walmart and Kroger demanding exclusive SKUs and volume commitments that strain mid-tier mill capacity. Direct-store-delivery networks are losing ground to warehouse consolidation models, displacing regional brand access in favor of national distribution footprints. The U.S. Southeast exhibits the most visible channel restructuring, where Publix and Aldi expansion is reallocating shelf space toward private-label oat platforms.
North America Oats Market Segmentation
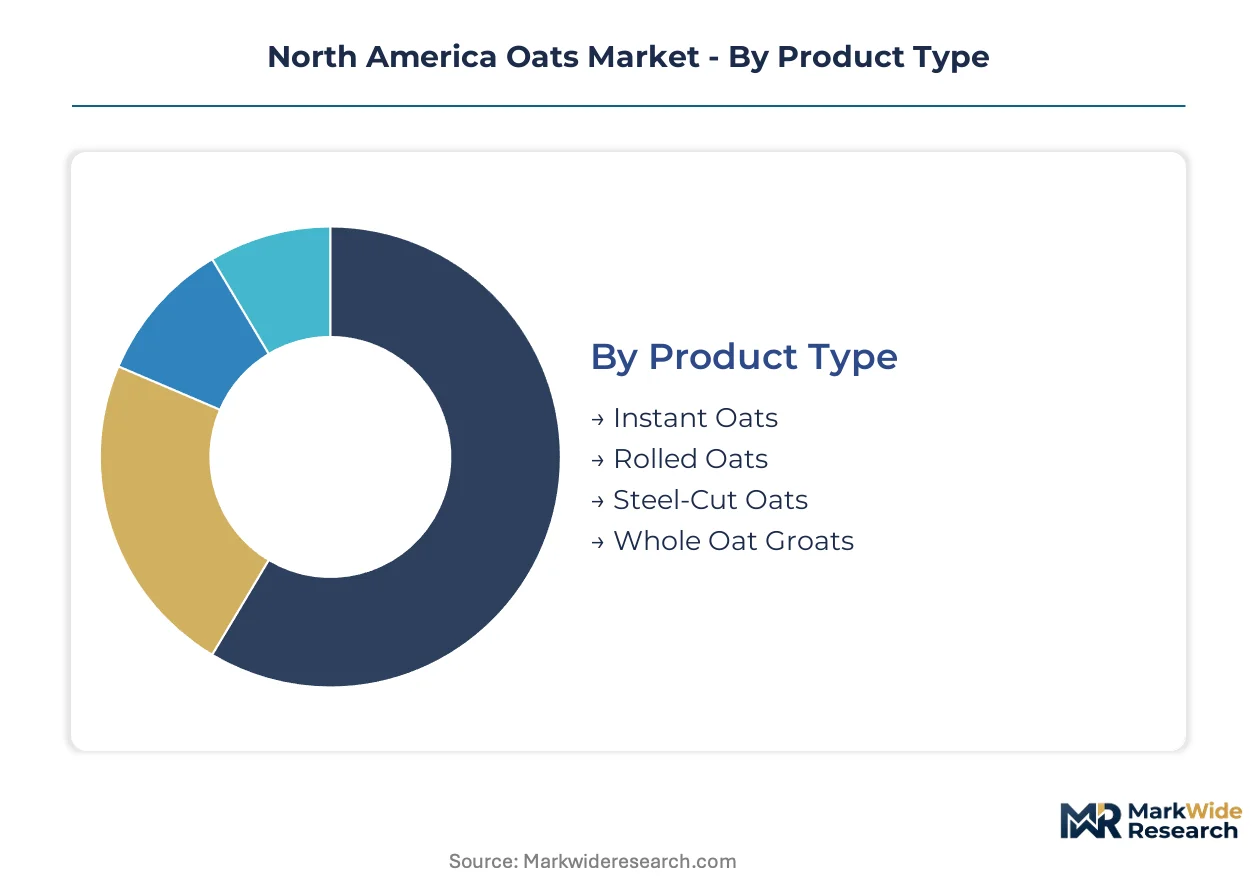
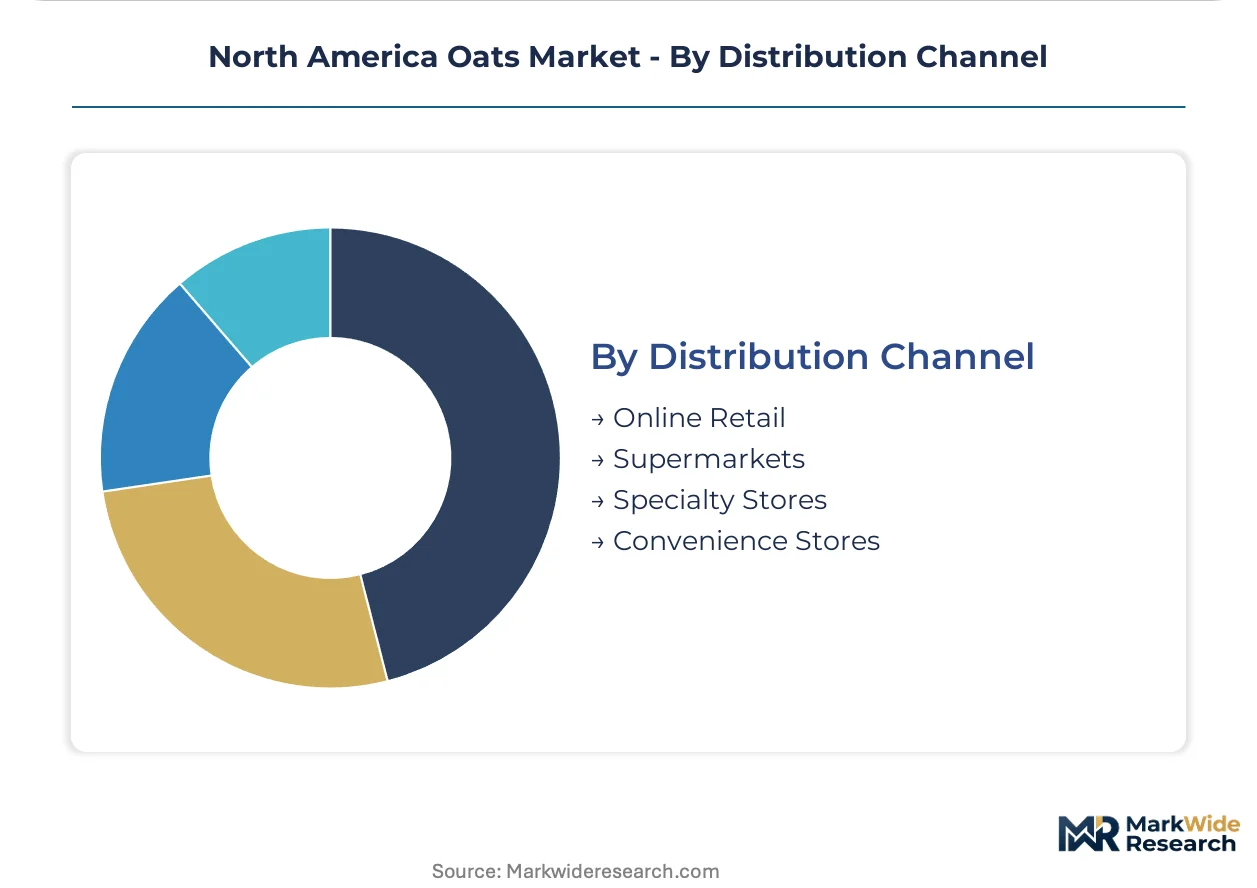
Segmentation in the North America Oats Market reveals how processing intensity and distribution format determine margin capture. Each dimension exposes distinct supply chain configurations and buyer willingness to pay for convenience or provenance claims.
Product Type:
Integration depth varies sharply across oat processing tiers, with minimally processed formats serving standalone breakfast applications while refined products embed into complex food manufacturing systems.
- Rolled Oats:Steam-stabilized and flattened groats that cook in 5-10 minutes, retaining 3-5% beta-glucan content. U.S. Midwest households and Canadian prairie consumers drive bulk purchases through warehouse clubs, though refrigerated single-serve cups are displacing bagged formats in urban corridors.
- Instant Oats:Pre-cooked and thin-rolled for sub-60-second preparation, often with flavor coatings that trigger FDA added-sugar disclosure rules. Convenience-seeking commuters in the U.S. Northeast and Ontario urban centers absorb volume through grab-and-go retail, while school nutrition programs specify unsweetened variants.
- Steel-Cut Oats:Groats chopped into pinhead pieces requiring 20-30 minute cooking, prized for lower glycemic index positioning. Artisanal branding supports premium shelf placement in natural foods channels.
- Whole Oat Groats:Unprocessed kernels demanding extended soaking and cooking, confined to specialty bulk bins and heritage grain enthusiasts.
Volume placements concentrate in Rolled Oats; the faster expansion belongs to Instant Oats.
End Use:
Application architecture separates direct-to-consumer formats from industrial ingredient streams, with divergent specification requirements and contract structures.
- Breakfast Cereals:Hot oatmeal and RTE cereal platforms absorbing reformulation pressure from FDA whole grain health claim thresholds. Minneapolis-St. Paul processing clusters supply branded and private-label manufacturers across the U.S. Upper Midwest.
- Snack Foods:Granola bars, energy bites, and savory clusters replacing refined wheat and corn bases. Clean-label positioning in California and New York metro markets accelerates oat flour and flake incorporation.
- Bakery Products:Oat flour substitution in breads, muffins, and cookies for fiber fortification and gluten-free positioning. Commercial bakeries specify particle size distributions that strain regional mill capacity.
- Nutritional Supplements:Beta-glucan concentrates and protein isolates targeting adult nutrition and clinical applications, requiring specialized extraction and certification protocols.
Breakfast Cereals anchor current volume; Snack Foods are climbing the fastest as formulation flexibility expands.
Form:
Physical state determines equipment compatibility and shelf-life engineering, with powder and flour formats penetrating manufacturing while flakes retain consumer visibility.
- Flakes:Rolled or instant oat formats dominating breakfast cereal and granola bar production. U.S. grocery channel buyers specify flake thickness for texture consistency in private-label programs.
- Flour:Stone-ground or hammer-milled particles replacing refined wheat in clean-label bakery applications. Particle size variability creates specification friction between artisanal mills and industrial bakeries.
- Granules:Intermediate sizing for textured protein applications and specialized cereal coatings, produced by selective grinding and sifting operations.
- Powder:Fine-milled substrates for oat milk production and instant beverage bases, absorbing capital investment in high-pressure processing lines.
Flakes retain the largest volume footprint; Powder is gaining share fastest through oat milk proliferation.
Distribution Channel:
Channel structure reflects buyer consolidation power and the economics of temperature-controlled logistics versus ambient shelf stability.
- Supermarkets:Dominant volume channel for bagged and boxed oat products, with slotting fee structures favoring national brands and private-label platforms. Kroger and Walmart consolidation in the U.S. Southeast and Midwest compresses regional supplier access.
- Online Retail:Subscription and direct-to-consumer platforms bypassing traditional grocery slotting, with modular breakfast kits capturing recurring revenue in urban coastal markets.
- Specialty Stores:Natural foods and co-op channels prioritizing organic certification, gluten-free protocols, and heritage stone-milling provenance.
- Convenience Stores:Refrigerated oatmeal cups and single-serve formats enabled by expanded cold-chain distribution, concentrated in highway corridors and urban commuter nodes.
Supermarkets hold the dominant volume position; Online Retail is expanding most quickly as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the U.S. Midwest and Canadian Prairies while consumption spreads across coastal urban corridors. Minneapolis-St. Paul and Winnipeg anchor processing infrastructure. Demand fragmentation between heartland bulk buyers and coastal premium-seekers shapes regional strategy.
United States
Breakfast cereal manufacturers in Chicago and Minneapolis drive rolled oats procurement for hot cereal and RTE platforms. The FDA's qualified cardiovascular health claim for beta-glucan forces reformulation toward higher oat content in legacy brands. Minneapolis-St. Paul processing clusters supply both branded and private-label channels across the Upper Midwest.
Canada
Organic contract farming networks around Winnipeg corridor channel premiums into processor R&D budgets. Health Canada's Food and Drug Regulations enforce cholesterol-reduction claim thresholds that favor scaled processors over regional mills. Winnipeg and Saskatoon anchor oat milling infrastructure serving domestic and export markets.
Mexico
Snack food manufacturers in Mexico City and Guadalajara incorporate oat flour for clean-label bakery reformulation. The country's national food safety regulator enforces labeling standards that align with U.S. FDA frameworks for cross-border product consistency. Bajío Region grain handlers are expanding storage capacity for imported North American oats.
California
Beverage manufacturers in Los Angeles and San Francisco adopt high-pressure processing for oat milk production. The state's agricultural department enforces organic certification protocols that exceed federal USDA standards. Central Valley processing facilities are absorbing capital diverted from aseptic packaging infrastructure.
New York Metro
Specialty food brands in Brooklyn and Manhattan drive demand for stone-ground heritage oats and gluten-free certified products. The state's department of agriculture and markets enforces strict cross-contamination protocols for gluten-free labeling. Hudson Valley co-packers are scaling modular breakfast kit assembly for direct-to-consumer subscription channels.
North America Oats Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. PepsiCo and General Mills leverage refrigerated supply chains and national distribution footprints to dominate ready-to-eat platforms. Three archetypes define competitive positioning: diversified food conglomerates with oat portfolios, heritage stone-milling specialists, and private-label processors serving retail consolidation. M&A activity concentrates among mid-tier mills seeking gluten-free certification capabilities, while capacity expansion targets oat milk powder production lines.
Among diversified food conglomerates, PepsiCo and General Mills exemplify scale-driven archetypes with integrated supply chain control. Bob's Red Mill Natural Foods occupies the heritage specialist tier, representing stone-milling provenance and gluten-free certification expertise. Nature's Path Foods anchors the organic pure-play segment, sitting within premium natural foods channels. These three companies illustrate how competitive positioning stratifies across convenience, provenance, and certification vectors.
| Leading Market Players |
|---|
| Nestlé |
| Bob's Red Mill Natural Foods |
| PepsiCo (Quaker Oats Company) |
| Grain Millers |
| Nature's Path Foods |
| General Mills |
| Post Holdings |
| The Scoular Company |
| Kellogg Company |
| Others |
Cost & Logistics Intelligence
Organic certification ladders bifurcate oat pricing into premium and commodity tiers, with USDA Organic and Non-GMO Project verification commanding shelf-space premiums that fund dedicated gluten-free facility investments while conventional bulk oats compete on volume scale through Minneapolis-St. Paul processor networks.
Pricing Analysis
Margin tightening in conventional rolled oats reflects fertilizer and fuel cost volatility hitting organic contract growers disproportionately across the U.S. Midwest. Three-tier pricing structure across certified organic, conventional bulk, and private-label economy levels separates buyer willingness to pay for provenance claims. Price differentiation traces to gluten-free certification protocols and stone-milling heritage branding. School nutrition programs and warehouse club buyers exhibit highest price sensitivity, while specialty natural foods channels absorb premium positioning.
Supply Chain Analysis
Fuel and freight cost escalation from Canadian Prairie farming corridors to U.S. coastal markets compresses processor margins on cross-border organic shipments. Supply concentrates in the United States, Canada, and Mexico with raw material dependencies on nitrogen fertilizers, diesel fuel, and specialized oat varieties. Single-source vulnerability clusters around Minneapolis-St. Paul and Winnipeg milling infrastructure exposed to weather-driven crop failures. Distribution runs through refrigerated warehouse consolidation models displacing direct-store-delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over organic acreage and downstream refrigerated channel access define the vertical-integration race, with processors securing contract farming networks to lock in beta-glucan supply for oat milk expansion.
For Market Incumbents: Extend gluten-free certification capabilities through dedicated facility segments to defend against private-label encroachment in natural foods channels. Backward integration into organic contract farming around Winnipeg and Minneapolis corridors secures premium supply tiers. Channel control through refrigerated distribution partnerships with Walmart and Kroger preserves slotting access against mid-tier mill consolidation. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable white space, bypassing grocery slotting fees through modular breakfast kit assembly. Barista-format oat milk in Canadian retail channels shows underpenetration relative to U.S. benchmarks. Co-packer partnerships with Hudson Valley assembly facilities enable rapid subscription channel scaling without capital-intensive milling infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with gluten-free certified mid-tier mills given FDA disclosure rules forcing reformulation toward unsweetened base products. Long-term viability centers on processors with dual capabilities in conventional commodity supply and premium certified organic streams. Watch Health Canada whole grain definition revisions as inflection signal for R&D allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Gluten-Free Facility Certification | FDA cross-contamination protocols require dedicated processing segments extending capital deployment timelines for regional mills. |
| Organic Contract Farming Expansion | USDA Organic acreage scaling around Minneapolis and Winnipeg corridors channels premiums into processor R&D budgets. |
| Refrigerated Supply Chain Investment | Cold-chain expansion enables ready-to-eat oatmeal cup distribution through convenience channels displacing bulk bag formats. |
| High-Pressure Processing Adoption | HPP technology absorption into oat milk lines extends refrigerated shelf life without thermal beta-glucan degradation. |
| Direct-to-Subscription Channel Launch | Modular breakfast kit platforms bypass traditional grocery slotting fees capturing lifetime value through recurring revenue models. |
Research Approach
USDA crop production surveys, FDA qualified health claim filings, and Nielsen retail audit data formed the secondary backbone, supplemented by primary interviews with oat processing plant managers, organic certification specialists, grocery category buyers, and supply chain planners at major food manufacturers. Bottom-up volume estimates from processor capacity utilization rates triangulated against top-down consumption surveys across breakfast cereal, snack food, and bakery end-use segments.
Historical trendline analysis of oat acreage, yield per hectare, and processor margin structures informed projection modeling across product type, end-use application, physical form, and distribution channel dimensions. CAGRs were derived through segmented growth rate synthesis with oat milk powder and refrigerated single-serve format adoption curves serving as primary demand-side inputs.
Several conditions sit outside the modeled scope, including extreme weather events affecting Prairie region harvests, abrupt FDA health claim revisions, and trade policy shifts impacting U.S.-Canada organic grain flows. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Cereals Market
Grains
Asia Pacific Maize Market
Grains
Green Pea Grits Market
Grains
Egypt Rice Market
Grains
Europe Wheat Protein Market
Grains
United States Rice Market
Grains
Wheat Fiber Market
Grains
Organic Oats Market
Grains
Barley Grass Market
Grains
Soy Grits Market
Grains
North America Maize Market
Grains
Grain Storage Silos Market
Grains
Gluten Free Ancient Grain Market
Grains
South American Maize Market
Grains
Grain Roller Market
Grains
North America Wheat Flour Market