
 Lawn Sprinkler Market | 2026-2036
Lawn Sprinkler Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn Sprinkler Market Analytics
Commercial landscaping and golf course maintenance is realigning toward precision water management, pulling demand toward high-efficiency sprinkler systems. Hunter Industries leverages its rotary nozzle technology leadership to dominate the commercial specification channel. Rain Bird Corporation sustains broad distribution through wholesale irrigation dealers across North America. The Toro Company anchors its position with golf course-centric control systems that integrate soil moisture monitoring.
A lawn sprinkler is a pressurized water distribution device engineered with brass, zinc, or thermoplastic bodies and orifice diameters typically ranging from 2 to 35 millimeters, designed to deliver controlled precipitation rates across turf and planted areas. Oscillating sprinklers remain the mature volume segment in residential retail, while smart sprinkler systems capture the fastest expansion as WiFi-enabled controllers with evapotranspiration algorithms penetrate connected-home ecosystems. Impact sprinklers retain margin concentration in agricultural pivot and linear-move installations where wind resistance and large-droplet delivery matter.
EPA WaterSense labeling mandates in the United States and the EU Green Deal water-efficiency directives constrain product entry for non-certified equipment, forcing redesigns toward pressure-compensating and weather-responsive architectures. China's GB standards for irrigation equipment and India's BIS certification for plastic sprinkler components add compliance layers for import-dependent markets. Stakeholders must monitor how municipal rebate programs for smart irrigation controllers reshape channel economics and whether sensor-embedded systems can displace traditional timer-based units in price-sensitive residential segments.
Market Dynamics
EPA WaterSense certification mandates and EU Green Deal water-efficiency directives are compressing product development cycles, forcing manufacturers to redesign pressure-compensating architectures before legacy inventory phases out.
Growth Catalysts
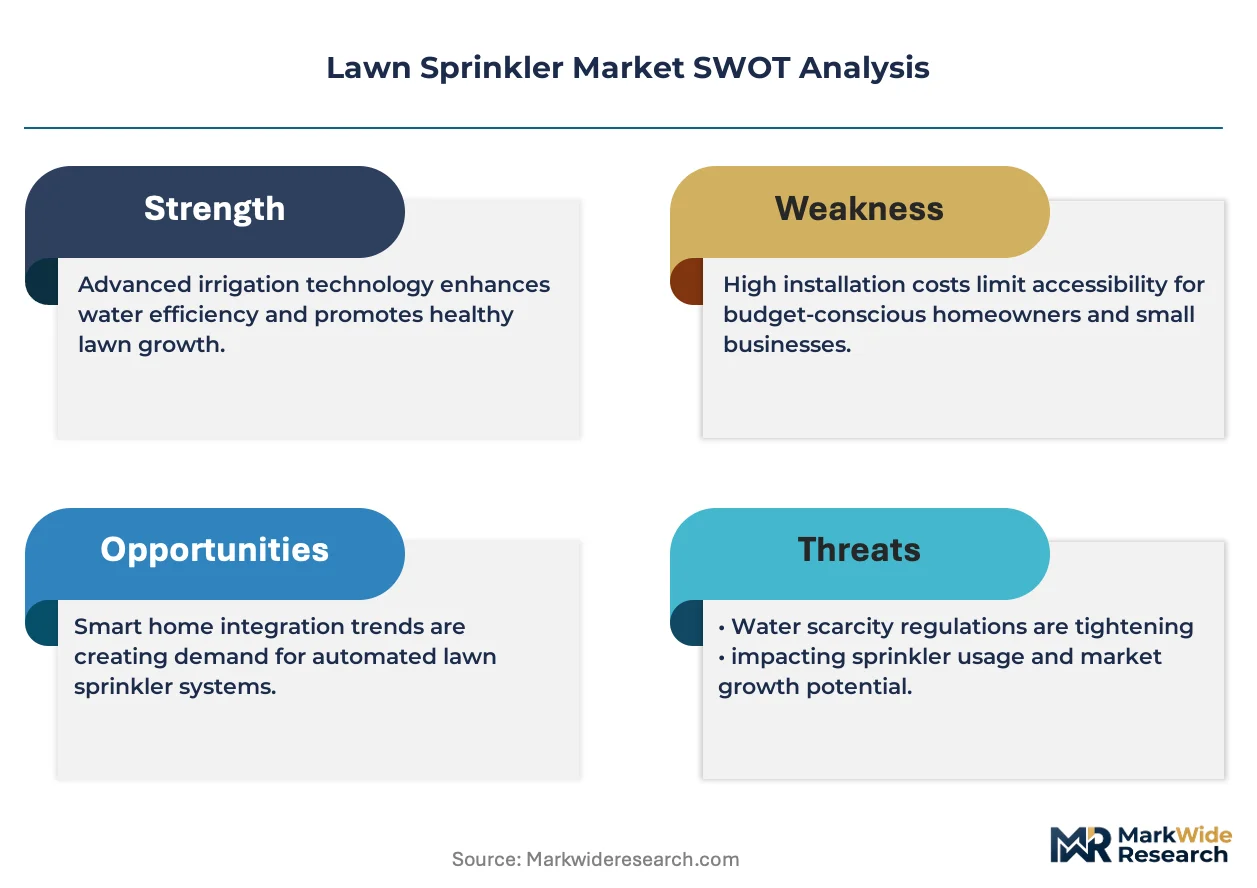
- EPA WaterSense Labeling:Federal rebate programs for smart irrigation controllers accelerate residential replacement of timer-based units across the United States.
- Municipal Greening:China's tier-two cities are expanding urban landscape irrigation as part of dual carbon goals implementation.
- Sensor Integration:Soil moisture monitoring technology is converging with golf course control systems to enable precision turf management.
Market Restraints
- Brass and Zinc Volatility:Base metal price swings compress margins on commercial-grade sprinkler bodies manufactured in import-dependent supply chains.
- Certification Friction:India's BIS plastic component standards and China's GB irrigation equipment rules create multi-jurisdiction compliance costs for exporters.
- Timer-Based Substitution Resistance:Price-sensitive residential segments in emerging markets delay smart controller adoption despite rebate availability.
Strategic Opportunities
- WiFi-Enabled Convergence:Evapotranspiration algorithms are converging with connected-home ecosystems to create subscription-based water management services.
- Agricultural Pivot Modernization:Impact sprinkler upgrades in wind-exposed linear-move installations offer margin concentration in farming corridors.
- Rebate-Driven Channel Shift:Utility-sponsored smart controller programs are opening wholesale irrigation dealer networks to technology entrants.
Industry Challenges
- Legacy System Integration:Retrofitting sensor-embedded controllers into existing commercial timer banks requires specialized technician training.
- Multi-Standard Certification Timelines:Simultaneous EPA WaterSense, EU CE marking, and BIS compliance stretches product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn Sprinkler Market |
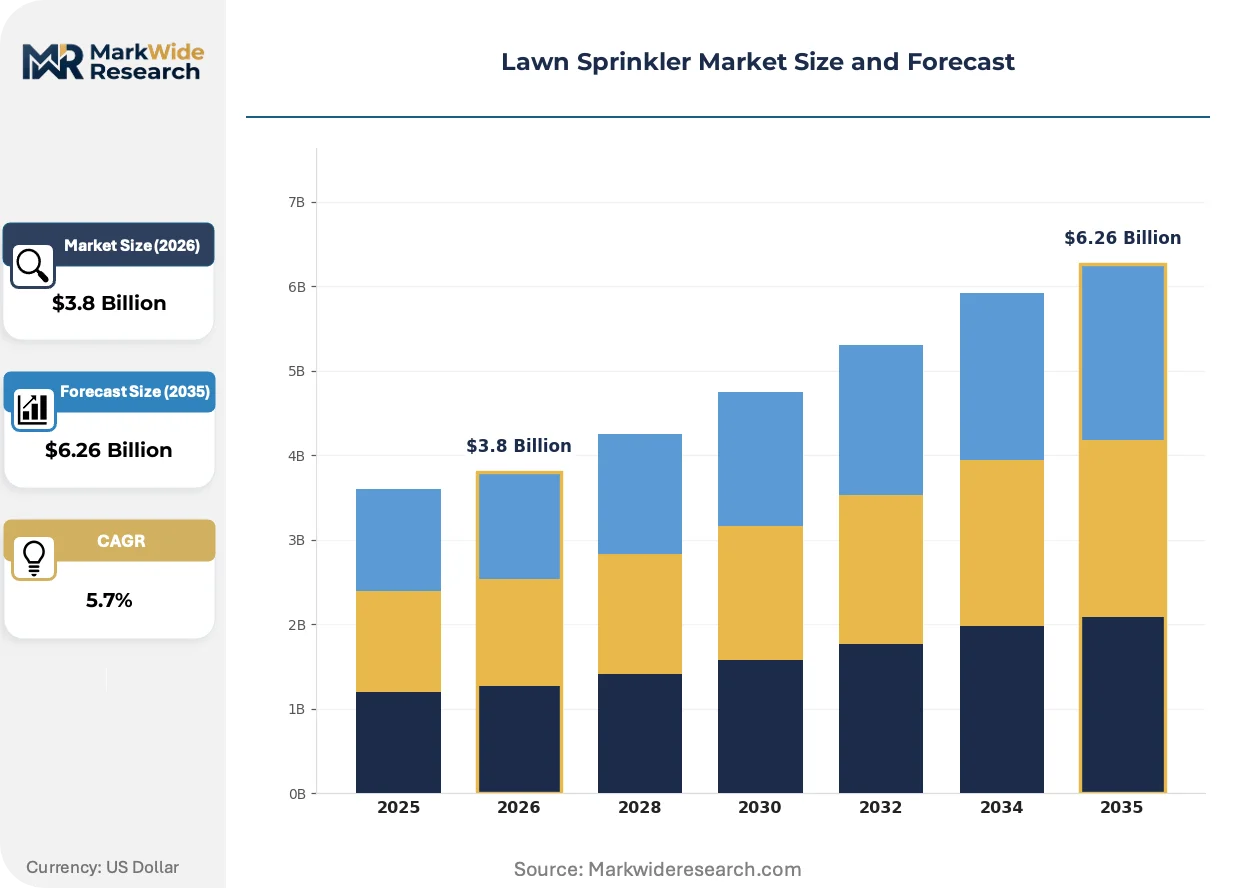
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Sprinklers, Oscillating Sprinklers, Impact Sprinklers, Drip Irrigation Technology: Smart Sprinkler Systems, Traditional Systems, Sensor-Based Systems, Manual Systems End User: Residential Users, Commercial Landscapers, Golf Courses, Agricultural Applications Distribution Channel: Retail Stores, Online Platforms, Wholesale Distributors, Direct Sales |
| Companies Covered | Orbit Irrigation Products, Inc., The Toro Company, Hunter Industries, Rain Bird Corporation, K-Rain, Gilmour, Fort Worth Lawn Sprinkler Company, Nelson Irrigation, Hydro-Rain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn Sprinkler Market Evolving Landscape
Connected irrigation hardware is converging with predictive analytics platforms, compressing the traditional separation between equipment sales and ongoing water management services.
Pressure-compensating nozzle technology is converging with variable-frequency drive pumps to maintain uniform precipitation across elevation changes. Golf course superintendents in Arizona and Nevada are specifying these integrated systems for reclaimed water distribution. The technology is converging with soil moisture telemetry to eliminate over-irrigation penalties under municipal drought restrictions.
EU Green Deal water-efficiency directives are mandating flow-rate limits on new irrigation equipment imports. Manufacturers serving European distribution must redesign orifice geometries to meet F-Gas Regulation-aligned efficiency benchmarks. Agricultural buyers in Spain and Italy face compressed equipment replacement cycles as national drought emergency declarations tighten usage permits.
Wholesale irrigation dealers are unbundling installation from equipment procurement as contractor labor shortages persist. Commercial landscaping firms in Texas and Florida now source controllers directly through distributor portals while subcontracting fieldwork to independent technicians. This channel fragmentation is most visible in Sun Belt metropolitan markets where municipal rebate programs require certified installer verification.
Lawn Sprinkler Market Segmentation
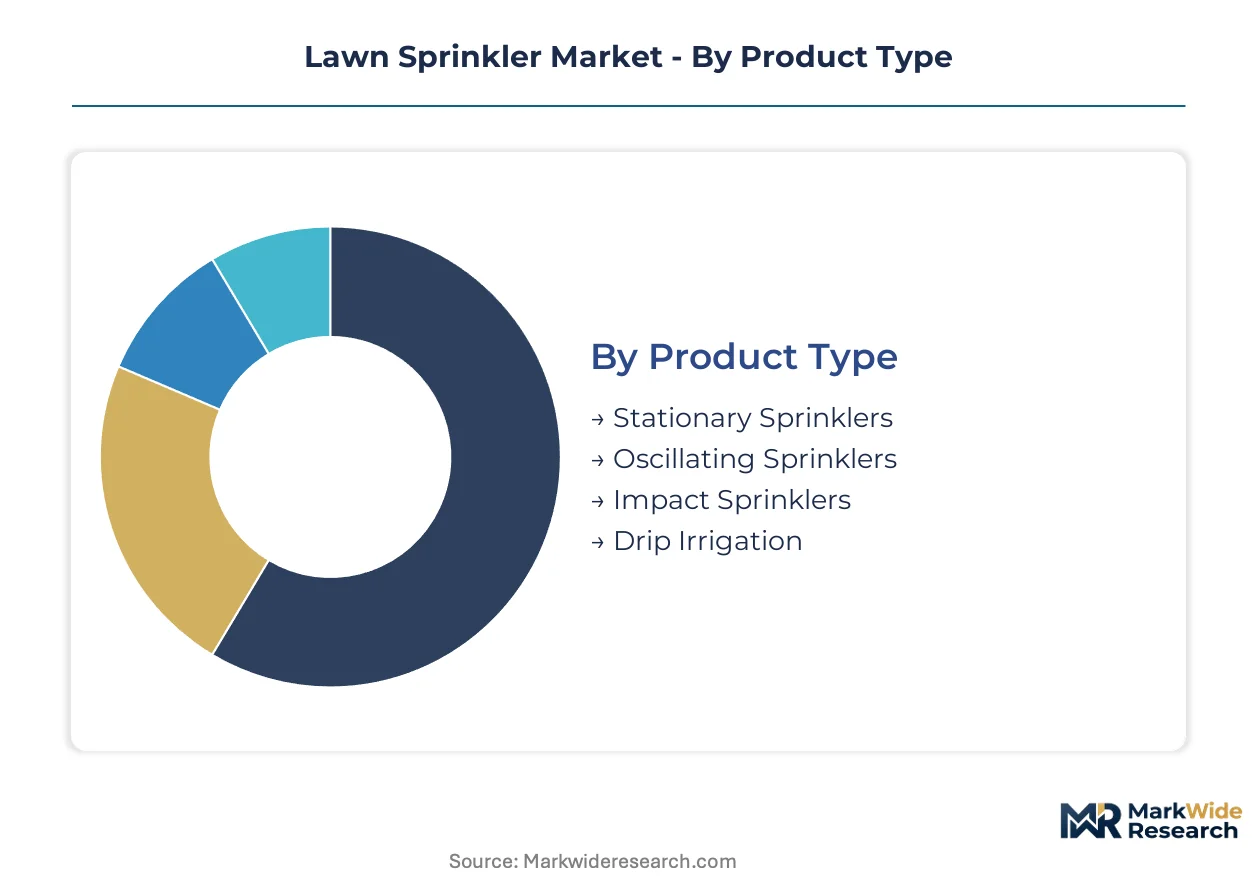
Product architecture in lawn sprinklers diverges sharply across water-pressure requirements, terrain adaptability, and certification complexity. Each segment carries distinct regulatory burdens and margin profiles that reshape procurement patterns for contractors and facility managers.
Product Type:
Certification intensity varies by product type, with brass-bodied commercial units requiring EPA WaterSense validation while thermoplastic residential models face lighter compliance loads.
- Oscillating Sprinklers:Rectangular spray pattern devices with aluminum or plastic bodies and adjustable sweep arcs. Demand concentrates in North American big-box retail channels where seasonal replacement cycles drive volume. EPA WaterSense exempts these timer-dependent units from smart-controller mandates, preserving their price-positioning in cost-conscious segments.
- Impact Sprinklers:Brass or zinc-bodied rotary heads with deflector-driven large-droplet delivery engineered for wind resistance. Agricultural pivot installations in the Texas Panhandle and Nebraska farming corridors specify these for linear-move systems where uniform distribution across elevation changes matters.
- Stationary Sprinklers:Fixed-pattern spray heads with pre-set orifice geometries for small-area coverage.
- Drip Irrigation:Pressure-compensating emitters and micro-tubing networks for targeted root-zone delivery.
Oscillating Sprinklers sits at the top of the volume ranking, with Smart Sprinkler Systems climbing the fastest.
Technology:
Cost tiering separates subscription-enabled platforms from hardware-only sales, with WiFi controllers commanding three-to-four times the installed cost of mechanical timers.
- Smart Sprinkler Systems:WiFi-enabled controllers running evapotranspiration algorithms with soil moisture API integration. Municipal rebate programs in California, Arizona, and Nevada accelerate residential replacement of legacy timers, with utility-sponsored installations requiring certified technician verification.
- Sensor-Based Systems:Soil moisture probes and weather station inputs feeding adaptive scheduling logic. Golf course superintendents in water-stressed jurisdictions deploy these to eliminate over-irrigation penalties under municipal drought restrictions.
- Traditional Systems:Electromechanical timers with zone-based programming and no connectivity.
- Manual Systems:Hose-connected portable units with no automation capability.
Traditional Systems retains the largest installed base, though Smart Sprinkler Systems is gaining share fastest among new construction and renovation projects.
End User:
Application severity dictates specification grade, with reclaimed water distribution systems requiring corrosion-resistant materials and pressure-compensating architectures absent in residential specifications.
- Golf Courses:Central control systems with satellite decoder programming and soil moisture telemetry integration. Facilities in Arizona and Nevada specify pressure-compensating nozzles paired with variable-frequency drive pumps for reclaimed water distribution across undulating terrain.
- Commercial Landscapers:Mixed-specification portfolios spanning municipal contracts, corporate campuses, and retail properties. Texas and Florida firms increasingly source controllers through distributor portals while subcontracting installation to independent technicians amid persistent labor shortages.
- Residential Users:Homeowner-installed or contractor-fitted systems for single-family properties.
- Agricultural Applications:Center-pivot and linear-move installations for row-crop irrigation.
Residential Users accounts for the highest unit volume, with Golf Courses showing the steepest expansion trajectory in control-system value per acre.
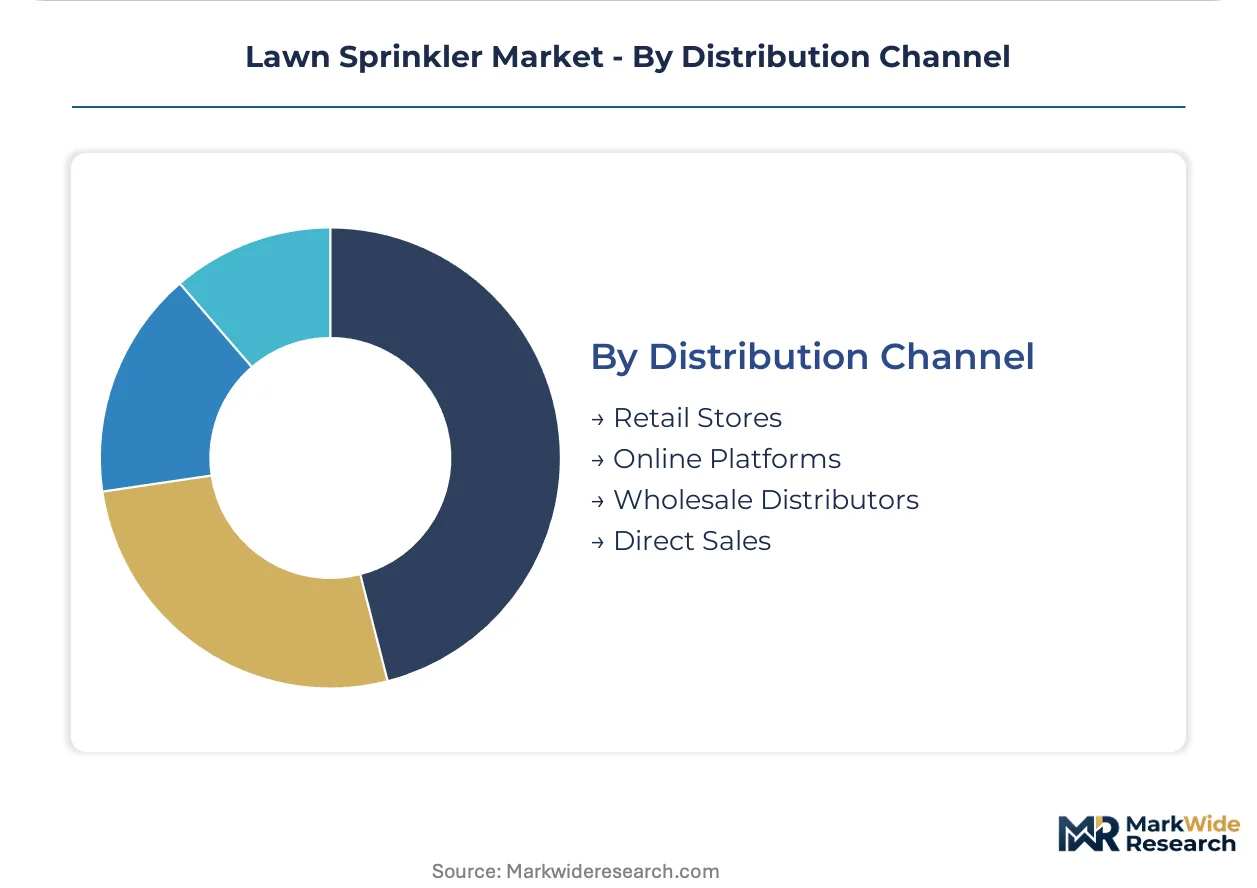
Distribution Channel:
Channel fragmentation accelerates as rebate programs force verification requirements that split equipment procurement from field installation.
- Wholesale Distributors:Irrigation-specialized dealers carrying specification-grade commercial portfolios with contractor pricing tiers. Sun Belt metropolitan markets see these channels absorb smart-controller rebate processing and certified installer matching.
- Online Platforms:Direct-to-consumer and contractor-portal sales with drop-ship fulfillment. Residential smart controllers move through Amazon and manufacturer-direct sites where EPA WaterSense certification badges influence search ranking and conversion.
- Retail Stores:Big-box and garden-center seasonal merchandising for homeowner-grade products.
- Direct Sales:Manufacturer-to-end-user relationships for large commercial and agricultural accounts.
Wholesale Distributors holds the dominant position in commercial specification flow, while Online Platforms is expanding most quickly in residential smart-controller transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Golf course superintendents in Arizona and Nevada anchor the precision irrigation demand cluster, with municipal rebate programs and reclaimed water mandates compressing replacement cycles across the United States.
United States
EPA WaterSense rebate programs in California, Arizona, and Nevada accelerate smart controller replacement of legacy timers. The agency's certification mandates for pressure-compensating architectures force redesigns ahead of legacy inventory phase-outs. Phoenix and Las Vegas metropolitan markets concentrate contractor networks handling utility-sponsored installations requiring certified technician verification.
China
Municipal greening projects across tier-two cities drive specification-grade sprinkler procurement as dual carbon goals implementation accelerates. GB standards for irrigation equipment add compliance layers for import-dependent supply chains. Chengdu and Xi'an urban landscape expansions concentrate demand for automated distribution systems in reclaimed water networks.
Germany
EU Green Deal water-efficiency directives mandate flow-rate limits on new irrigation equipment imports, compressing equipment replacement cycles. F-Gas Regulation-aligned efficiency benchmarks force orifice geometry redesigns for European distribution. Bavarian agricultural cooperatives specify pressure-compensating pivot upgrades amid national drought emergency declarations.
India
BIS certification requirements for plastic sprinkler components create multi-jurisdiction compliance costs for exporters targeting price-sensitive residential segments. Central government municipal greening allocations expand urban landscape irrigation in tier-two cities. Maharashtra and Gujarat farming corridors concentrate impact sprinkler demand for wind-exposed linear-move installations.
Australia
Municipal drought restrictions in New South Wales and Victoria eliminate over-irrigation penalties for golf courses deploying soil moisture telemetry. State-level water efficiency programs mirror EPA WaterSense rebate structures for smart controller adoption. Sydney and Melbourne metropolitan markets concentrate commercial landscaping procurement shifting toward distributor portal sourcing.
Lawn Sprinkler Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers redesign pressure-compensating architectures to satisfy EPA WaterSense and EU Green Deal mandates before legacy inventory phases out. The vendor base separates into specification-grade commercial specialists, residential retail suppliers, and agricultural pivot system providers. Three strategic archetypes occupy distinct positions: rotary nozzle technology leaders, wholesale distribution anchors, and golf course-centric control system integrators. M&A activity and technology licensing agreements represent the dominant competitive moves as firms acquire evapotranspiration algorithm capabilities and connected-home platform integrations.
Among North American irrigation specialists, Hunter Industries, Rain Bird Corporation, and The Toro Company exemplify the tiered competitive structure. Hunter Industries occupies a position within rotary nozzle technology leadership. Rain Bird Corporation anchors wholesale distribution networks across dealer channels. The Toro Company represents golf course-centric system integration with soil moisture monitoring convergence. These three firms illustrate how specification-grade commercial positioning, broad distribution scale, and vertical application depth create defensible market presence against technology entrants and agricultural pivot specialists.
| Leading Market Players |
|---|
| Orbit Irrigation Products, Inc. |
| The Toro Company |
| Hunter Industries |
| Rain Bird Corporation |
| K-Rain |
| Gilmour |
| Fort Worth Lawn Sprinkler Company |
| Nelson Irrigation |
| Hydro-Rain |
| Others |
Value Network & Pricing Analysis
EPA WaterSense certification gates both qualified supply and premium-tier pricing access, compressing margins on uncertified legacy inventory while rewarding pressure-compensating architectures with municipal rebate eligibility and specification-grade procurement channels. Brass and zinc volatility in import-dependent supply chains feeds back into sourcing decisions, pushing manufacturers toward thermoplastic residential models or captive metal foundry investments.
Pricing Analysis
Wholesale distributor margins anchor the three-tier pricing structure across premium, standard, and economy levels, with specification-grade commercial units commanding four-to-six times the per-zone cost of big-box retail oscillating sprinklers. Price differentiation separates EPA WaterSense-certified smart controllers from timer-dependent units, with California utility rebates masking installed-cost premiums for residential buyers. Cost compression in brass-bodied commercial segments intensifies because base metal price swings outpace contract hedging coverage. Agricultural pivot buyers in Nebraska and Texas show least price sensitivity, while tier-two Chinese municipal greening projects drive hardest bargain on volume tenders.
Supply Chain Analysis
Single-source vulnerability sits with brass ingot suppliers in China and zinc concentrate processors in Australia, where mining concentration and smelter capacity constraints amplify input cost volatility. Thermoplastic resin supply draws from Saudi petrochemical complexes and U.S. Gulf Coast polymer plants, with rotational molding capacity clustering in Guangdong and Zhejiang provinces. Tariff exposure on Chinese-manufactured controllers and nozzles threatens margin stability for North American distributors reliant on trans-Pacific container routes. Distribution runs through irrigation-specialized wholesale dealers in Sun Belt metropolitan markets, with direct-to-contractor portal sales capturing share in residential smart-controller segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lawn sprinkler market functions as a stable compounder, with municipal water-efficiency mandates and rebate programs generating predictable replacement cycles across residential and commercial installed bases.
For Market Incumbents: Anticipate sensor-embedded controller entrants by accelerating WiFi-enabled platform convergence and securing exclusive soil moisture API partnerships before technology licensing windows close. Backward integration into brass foundry capacity in Vietnam or India hedges against Chinese supply concentration and BIS certification friction. Prioritize EPA WaterSense pre-certification of next-generation pressure-compensating architectures to capture utility-sponsored installation channels ahead of legacy inventory phase-outs. For New Entrants and Emerging Players: Sensor-integrated drip irrigation for reclaimed water distribution in Arizona and Nevada golf courses offers the most penetrable white-space target, with specification-grade procurement bypassing retail channel gatekeepers. WiFi-enabled residential controllers in tier-two Chinese cities exploit municipal greening acceleration and underdeveloped local smart-irrigation competition. Partner with certified installer networks in Phoenix and Las Vegas to satisfy rebate program verification requirements without building captive field service capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier agricultural pivot specialists with impact sprinkler portfolios and underutilized linear-move engineering capabilities. The five-to-ten year viability window favors acquisition targets with established EPA WaterSense certification and golf course control system integration expertise. Monitor municipal drought emergency declaration frequency in Spain, Italy, and Australia as inflection indicator for precision irrigation hardware replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| EPA WaterSense Pre-Certification Investment | Unlocks utility rebate program eligibility and specification-grade commercial procurement channels. |
| Soil Moisture API Platform Integration | Converges hardware sales with subscription-based water management services for golf course accounts. |
| Brass Foundry Backward Integration | Captive supply of commercial-grade sprinkler bodies insulates margin from base metal volatility. |
| Tier-Two China Distribution Partnership | Local installer networks accelerate penetration of municipal greening projects in Chengdu and Xi'an. |
| Reclaimed Water Corrosion-Resistant Redesign | Meets Arizona and Nevada golf course specifications for pressure-compensating distribution systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with golf course superintendents, irrigation contractor network managers, wholesale distributor procurement leads, and municipal water utility rebate program administrators with secondary validation. EPA WaterSense certification databases, EU Green Deal regulatory filings, Chinese GB standards documentation, and Indian BIS plastic component registrations provided compliance tracking inputs. Customs trade data on brass and zinc ingot flows, alongside North American irrigation dealer sales records, anchored bottom-up and top-down triangulation.
Segment-weighting across product type, technology tier, end-user application severity, and distribution channel structure informed the analytical framework over the projection horizon. Smart sprinkler system adoption curves, golf course control system replacement cycles, and agricultural pivot modernization rates served as industry-specific forecast inputs. CAGRs derived from installed base erosion modeling and new construction penetration assumptions across residential, commercial, and agricultural segments.
The model holds under stable municipal rebate program funding and continued EPA WaterSense enforcement; deviation in federal environmental policy priorities or commodity price spikes beyond hedging coverage would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Irrigation Liner Market
Farm Equipment and Irrigations
North America Agricultural Tires Market
Farm Equipment and Irrigations
Watering Cans Market
Farm Equipment and Irrigations
Drip Irrigation Systems Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Weed Trimmer Market
Farm Equipment and Irrigations
United States Irrigation Valves Market
Farm Equipment and Irrigations
Lawn Edge Trimmer Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Solar Powered Irrigation System Market