
 United States Irrigation Valves Market | 2026-2036
United States Irrigation Valves Market Size, Share, and Industry Trends Forecast 2026-2036
United States Irrigation Valves Market Analytics
Domestic brass foundry capacity in the Ohio River Valley is expanding to serve irrigation valve OEMs with shorter lead times and alloy traceability. The Toro Company leverages integrated manufacturing to control distribution across the western states. Netafim USA sustains technology leadership in pressure-compensating valve systems for drip networks. GF Piping Systems anchors its position through specification-grade PVC valve portfolios for municipal water districts.
United States irrigation valves regulate water flow, pressure, and distribution in agricultural, landscaping, and municipal systems, typically constructed from brass, PVC, or stainless steel with operating pressures ranging from 150 to 300 PSI depending on application class. Ball valves dominate commercial agriculture due to quarter-turn reliability and lower maintenance cycles, while electric actuation represents the fastest-growing operating mechanism as farm automation penetrates the Corn Belt and Pacific Coast regions. Stainless steel valve demand concentrates in industrial and high-salinity irrigation environments where PVC degradation accelerates.
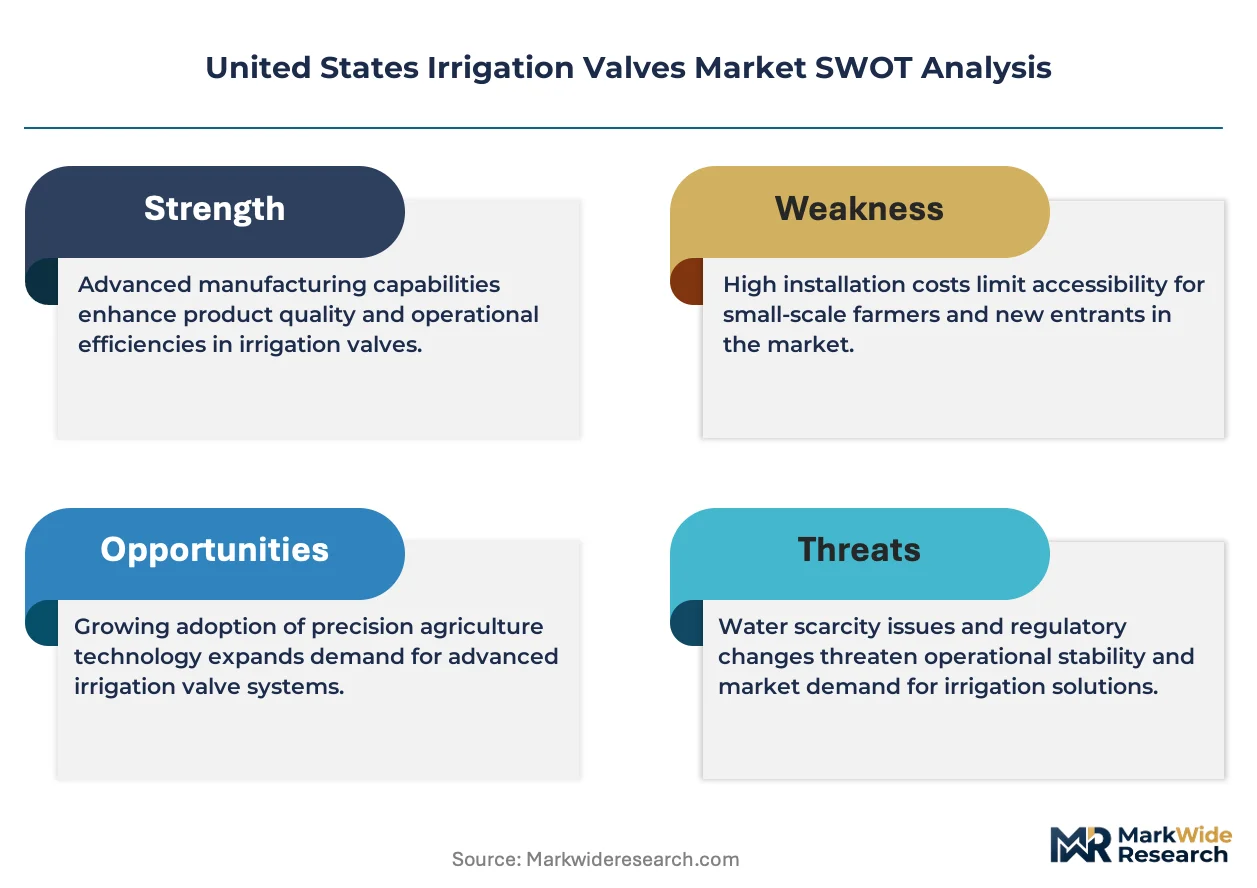
EPA WaterSense specifications and state-level agricultural water-use regulations in California and Arizona shape product efficiency mandates and certification requirements for valve manufacturers seeking public-sector eligibility. USDA conservation programs incentivize precision irrigation hardware upgrades, directing farm capital toward compliant valve and control systems. Stakeholders must monitor evolving state groundwater management plans and their downstream specification effects on valve sizing and flow-control technology procurement.
Market Dynamics
EPA WaterSense specifications and California's Sustainable Groundwater Management Act are compressing specification cycles for irrigation valve manufacturers serving agricultural and municipal buyers. Brass alloy traceability requirements and smart actuator integration demands are forcing OEMs to reconfigure supplier relationships and engineering priorities simultaneously.
Growth Catalysts
- USDA Conservation Programs:Financial incentives for precision irrigation hardware direct farm capital toward compliant valve and control system upgrades across the Corn Belt and Pacific Coast regions.
- Smart Actuator Convergence:Integration of IoT-enabled electric actuation with existing hydraulic infrastructure accelerates replacement cycles among large-scale row-crop operators.
- California Central Valley Concentration:Groundwater sustainability mandates in the nation's largest agricultural corridor sustain demand for pressure-compensating and flow-control valve technologies.
Market Restraints
- Brass Input Volatility:Copper and zinc price fluctuations from Chilean and Peruvian concentrate supply disruptions compress margin predictability for foundry-dependent OEMs.
- Ohio River Valley Supply Concentration:Domestic brass foundry capacity clustering creates lead time vulnerability when regional logistics constraints emerge.
- PVC Degradation Thresholds:High-salinity irrigation environments in Arizona and Texas accelerate material failure rates, limiting polymer valve addressable share in coastal and brackish water applications.
Strategic Opportunities
- Underpenetrated Drip Networks:Pressure-compensating valve technology holds expansion potential in Nebraska and Kansas pivot-to-drip conversion projects.
- FERC Hydropower Licensing:Agricultural water district eligibility for federal infrastructure grants creates specification pathways for municipal-grade valve portfolios.
- 5G-Enabled Telemetry Convergence:Real-time soil moisture data integration with valve actuation systems opens service revenue models beyond hardware sales.
Industry Challenges
- EPA Certification Timelines:WaterSense product qualification protocols extend new product introduction cycles by eight to fourteen months.
- Legacy Hydraulic Integration:Retrofitting smart actuators onto existing PVC and brass valve bodies requires custom adapter engineering that fragments production economics.
- Embedded Systems Talent Scarcity:Firmware development for IoT-enabled valve controllers outpaces available agricultural equipment engineering capacity in the Midwest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Irrigation Valves Market |
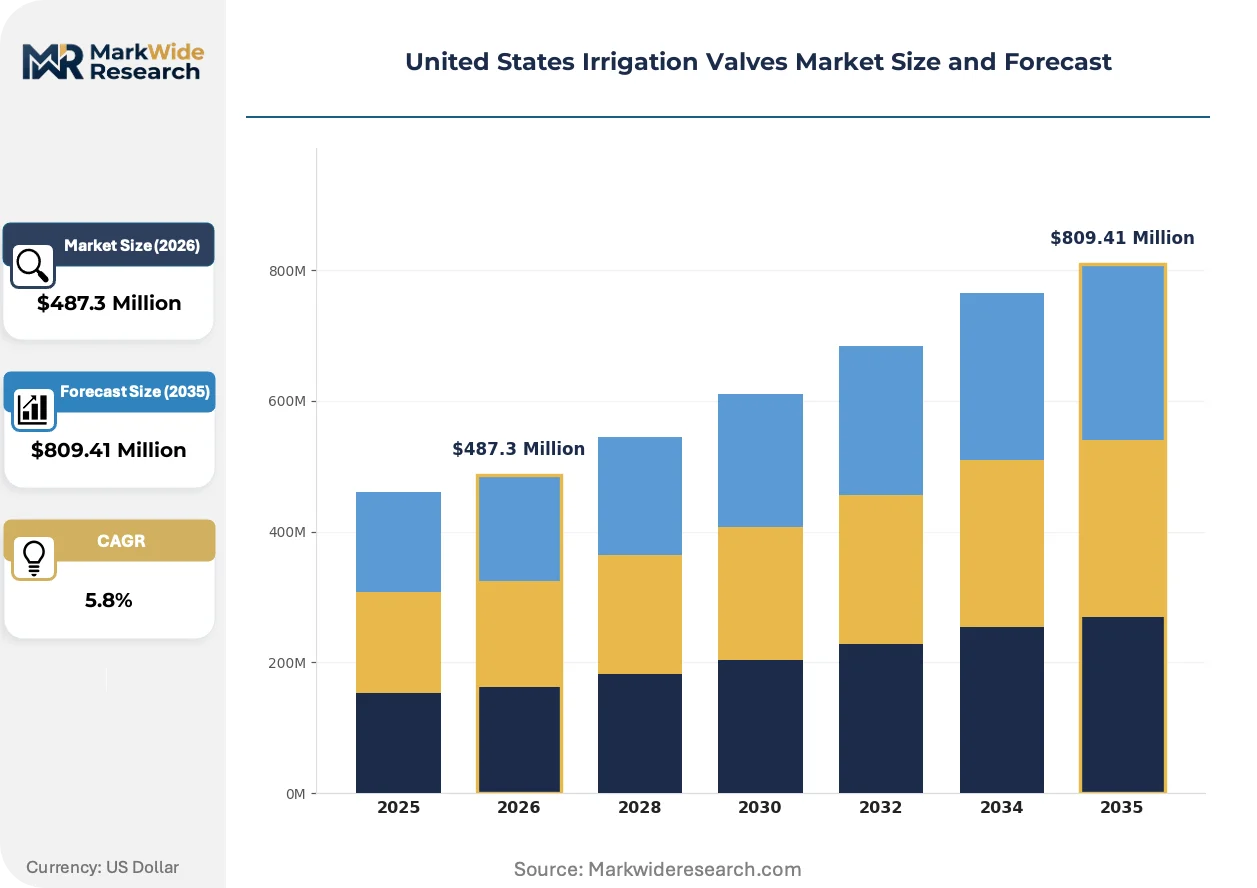
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valve, Globe Valve, Ball Valve, Check Valve Operating Mechanism: Manual, Electric, Pneumatic, Hydraulic Material: Brass, PVC, Stainless Steel, Polyethylene End User: Agriculture, Landscaping, Municipal, Industrial |
| Companies Covered | Bermad CS, GF Piping Systems, The Toro Company, Erdmann Corporation, Dorot, Raven Industries, Ace Pump Corporation, TVI, Netafim USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Irrigation Valves Market Evolving Landscape
Valve system architecture is fragmenting from monolithic hydraulic assemblies toward distributed, software-defined flow control. Manufacturers are reconfiguring R&D roadmaps around modularity, regulatory compliance automation, and service revenue attachment.
Edge-computing valve controllers with localized sensor fusion are modularizing irrigation zone management. Large-scale almond and pistachio growers in California's San Joaquin Valley are piloting these systems at hundred-acre scale. The technology is modularizing what had been centralized pump-station architecture into autonomous field-level decision nodes.
EPA WaterSense certification requirements are tightening flow-rate accuracy tolerances for commercial agricultural valves. Manufacturers must now submit third-party test data at three pressure points rather than one. Drip irrigation OEMs serving Arizona and Nevada municipal districts face the steepest compliance cost escalation.
Farm cooperatives are consolidating procurement authority through shared equipment purchasing agreements. Independent irrigation dealers in the Texas High Plains are losing specification influence to distributor networks with USDA program administration capabilities. This concentration is most visible in cotton and sorghum operations across the Oklahoma-Texas border region.
United States Irrigation Valves Market Segmentation
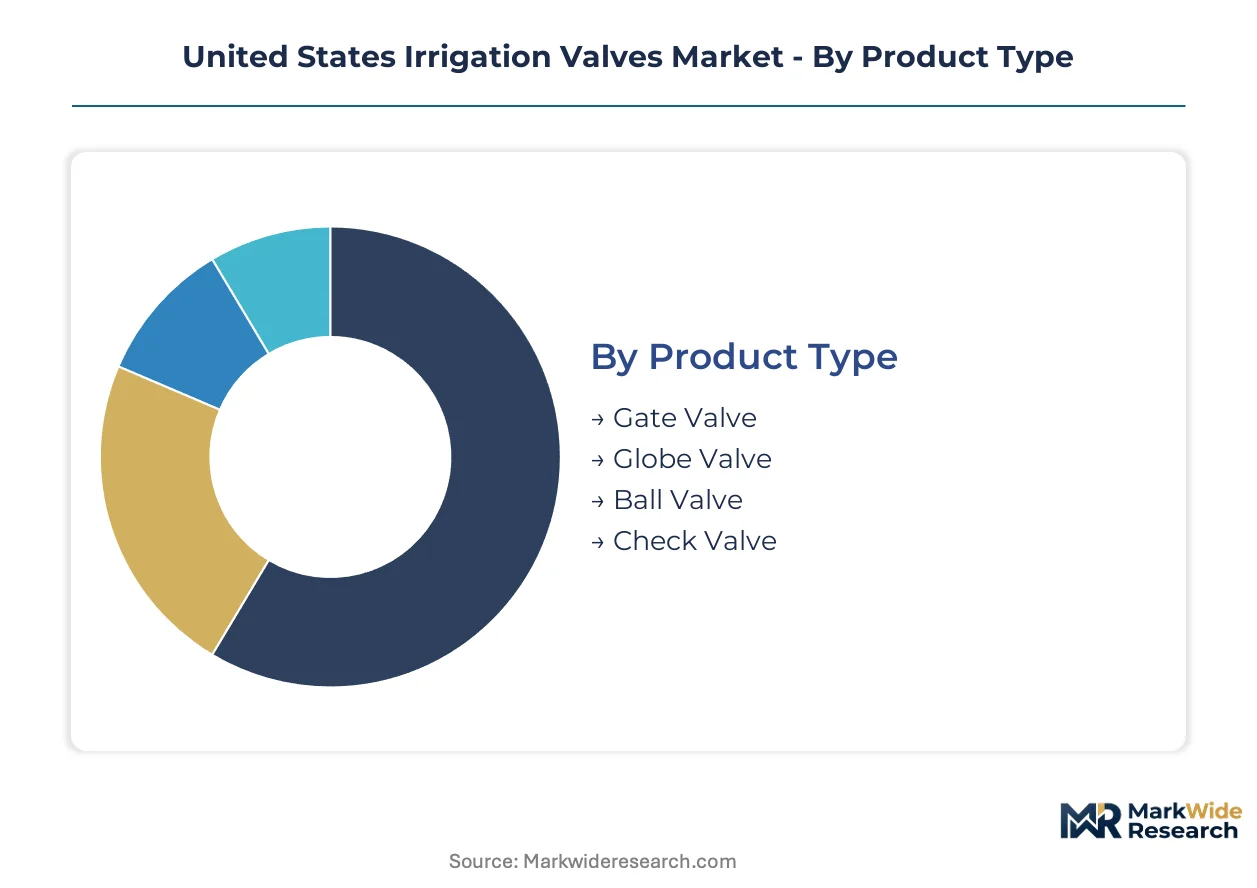
Irrigation valve procurement in the United States follows distinct specification pathways tied to pressure ratings, automation requirements, and regulatory compliance. Buyers segment their sourcing strategies across product architecture, actuation technology, material durability, and end-use application intensity.
Product Type:
Purchase decisions here pivot on cycle frequency, pressure tolerance, and maintenance accessibility in field conditions.
- Ball Valve:Quarter-turn brass or stainless steel construction delivers reliable shutoff across 150-300 PSI operating ranges. Large-scale row-crop operators in California's Central Valley specify these for mainline isolation points where downtime costs exceed replacement value.
- Gate Valve:Full-port bronze or cast-iron bodies with rising or non-rising stem configurations suit infrequent operation in municipal water district infrastructure. Arizona and Nevada utilities favor these for buried service line applications requiring decades-long service life.
- Globe Valve:Throttling precision for flow modulation in pump station discharge lines.
- Check Valve:Spring-loaded or swing-type configurations preventing backflow in elevation-variable terrain.
Ball valves lead on scale; electric-actuated variants lead on momentum.
Operating Mechanism:
Automation intensity divides the installed base between legacy manual infrastructure and connected control architectures.
- Electric:IoT-enabled actuators with 4-20mA feedback loops integrate with farm management software platforms. Corn Belt operators deploying precision agriculture systems specify these for zone-by-zone moisture-responsive irrigation.
- Manual:Handwheel or lever operators dominate cost-sensitive landscaping and small-acreage agricultural installations. Texas High Plains cotton growers retain these for secondary lateral lines where capital constraints limit automation penetration.
- Pneumatic:Compressed-air actuation for industrial-scale greenhouse and nursery operations requiring rapid cycle response.
- Hydraulic:Fluid-power systems in center-pivot and linear-move irrigation machinery.
Manual mechanisms retain installed-base dominance; electric actuation climbs the fastest on new specification share.
Material:
Corrosion resistance and alloy traceability requirements shape material selection against water chemistry and regulatory audit standards.
- Brass:Lead-free alloy formulations meet EPA Safe Drinking Water Act compliance for potable water contact. Ohio River Valley foundry sourcing provides domestic provenance documentation required by California agricultural water districts.
- Stainless Steel:316-grade austenitic compositions withstand high-salinity irrigation in coastal California and brackish groundwater zones of Arizona. Industrial processors and specialty crop operators absorb premium pricing for degradation resistance.
- PVC:Schedule 80 thermoplastic construction for cost-optimized agricultural laterals in neutral-pH water chemistry.
- Polyethylene:Injection-molded components for low-pressure drip distribution networks.
Brass commands specification authority in municipal and premium agricultural segments; stainless steel gains share fastest in salinity-challenged environments.
End User:
Application intensity and regulatory exposure create divergent procurement sophistication levels across customer categories.
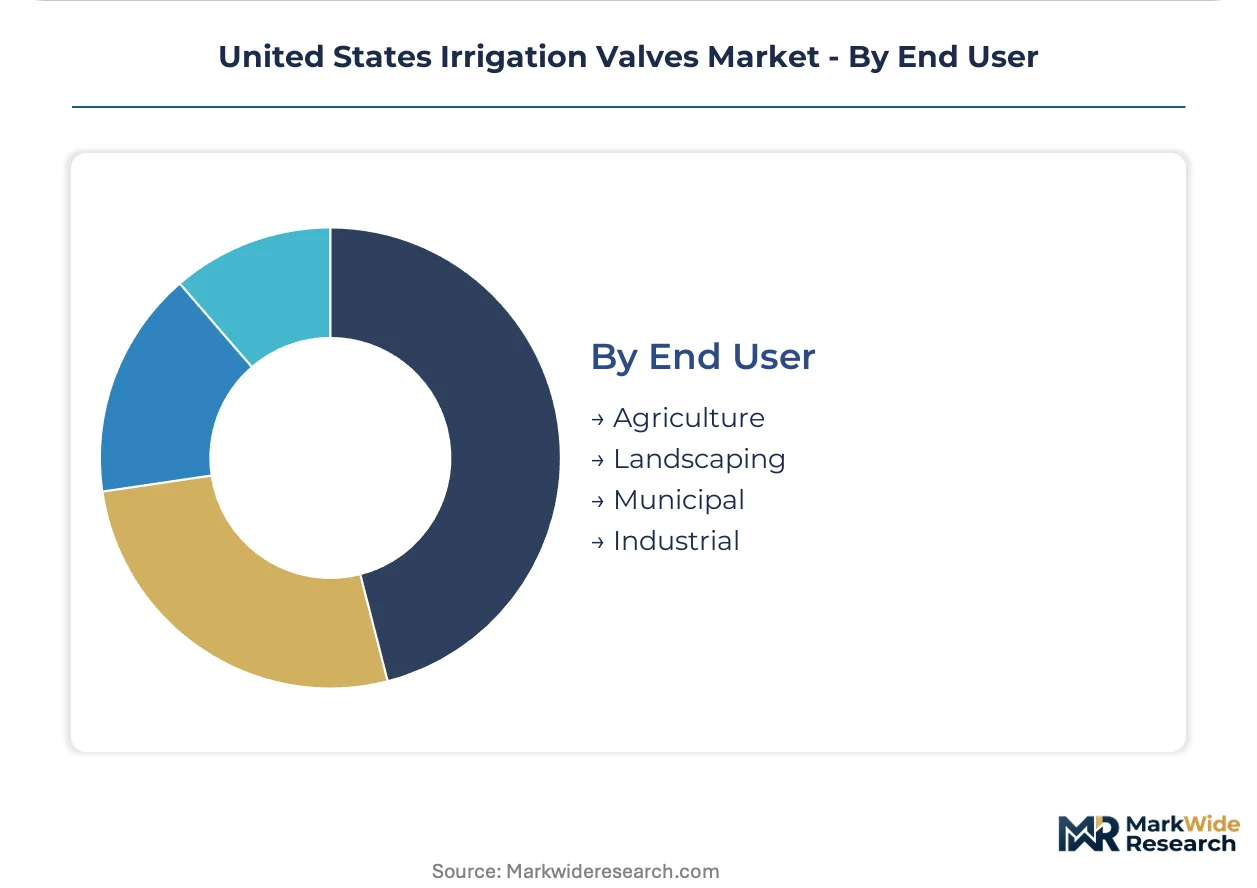
- Agriculture:Precision irrigation hardware investments accelerated by USDA Environmental Quality Incentives Program cost-share arrangements. California almond and pistachio growers drive specification for pressure-compensating valve technology at hundred-acre deployment scale.
- Municipal:Water district procurement governed by EPA WaterSense certification and American Water Works Association standards. Specification-grade documentation requirements favor established OEMs with third-party test data at multiple pressure points.
- Landscaping:Commercial grounds maintenance and golf course irrigation with seasonal operational patterns.
- Industrial:Food processing, mining, and energy sector water management with specialized corrosion and temperature requirements.
Agriculture leads on absolute volume; municipal specifications lead on compliance-driven technology upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic brass foundry capacity expansion in the Ohio River Valley reduces compliance-cost exposure for EPA-certified irrigation valve OEMs. California's groundwater sustainability mandates compress specification cycles. Texas and Arizona agricultural water districts face salinity-driven material selection pressures.
California
Almond and pistachio growers in the San Joaquin Valley deploy pressure-compensating valve systems at hundred-acre scale. EPA WaterSense specifications and the Sustainable Groundwater Management Act tighten flow-rate accuracy tolerances for commercial agricultural valves. Fresno and Kern counties concentrate precision irrigation hardware procurement authority through cooperative purchasing agreements.
Texas
Cotton and sorghum operations across the High Plains retain manual valve mechanisms for secondary lateral lines where capital constraints limit automation. The Texas Commission on Environmental Quality enforces agricultural water-use reporting requirements that shape specification-grade documentation needs. Lubbock and Plainview anchor independent irrigation dealer networks losing influence to USDA program-certified distributors.
Arizona
High-salinity irrigation environments accelerate PVC degradation, driving specification toward 316-grade stainless steel valve bodies in brackish groundwater zones. The Arizona Department of Water Resources administers groundwater management plans that mandate flow-control technology in active management areas. Yuma and Maricopa counties concentrate municipal water district procurement governed by American Water Works Association standards.
Nebraska
Pivot-to-drip conversion projects create underpenetrated demand for pressure-compensating valve technology in center-pivot replacement cycles. USDA Environmental Quality Incentives Program cost-share arrangements direct farm capital toward precision irrigation hardware upgrades. The Platte River Valley and North Platte regions concentrate large-scale row-crop operators deploying IoT-enabled electric actuation.
Ohio River Valley
Domestic brass foundry capacity expansion serves irrigation valve OEMs with shorter lead times and alloy traceability documentation. Lead-free alloy formulations meet EPA Safe Drinking Water Act compliance requirements for potable water contact applications. Cincinnati and Louisville industrial corridors anchor foundry-dependent supply chains vulnerable to regional logistics constraints.
United States Irrigation Valves Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart actuator integration and service revenue attachment. The vendor base clusters around three maturity tiers: integrated agricultural equipment conglomerates with captive distribution, specification-grade municipal water system specialists, and regional foundry-dependent OEMs serving cost-optimized agricultural laterals. Two strategic archetypes dominate: brass alloy traceability providers and IoT-enabled flow control platform builders. Competitive moves concentrate on backward integration into foundry capacity and technology licensing partnerships for edge-computing valve controllers.
Among integrated agricultural equipment providers, The Toro Company and Netafim USA exemplify divergent platform strategies. GF Piping Systems anchors the specification-grade municipal tier through third-party test data capabilities at multiple pressure points. These three companies represent the dominant archetypes: integrated manufacturing control, drip network technology leadership, and municipal certification authority.
| Leading Market Players |
|---|
| Bermad CS |
| GF Piping Systems |
| The Toro Company |
| Erdmann Corporation |
| Dorot |
| Raven Industries |
| Ace Pump Corporation |
| TVI |
| Netafim USA |
| Others |
Value Network & Pricing Analysis
Copper and zinc price fluctuations from Chilean and Peruvian concentrate markets cascade through brass foundry tiers into three distinct pricing levels for irrigation valve OEMs serving California agricultural water districts and municipal buyers.
Pricing Analysis
Distributor margin compression at the wholesale tier separates specification-grade brass valves from commodity PVC alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects EPA WaterSense certification status, alloy traceability documentation, and smart actuator integration. Cost compression in the standard tier is intensifying because Ohio River Valley foundry capacity expansion narrows lead-time premiums. Municipal water districts exhibit lowest price sensitivity due to federal infrastructure grant eligibility requirements, while Texas High Plains cotton growers retain highest sensitivity for secondary lateral line installations.
Supply Chain Analysis
Refurbishment flows for electric actuators and valve bodies create secondary parts channels that compete with new OEM sales in the Corn Belt. Raw material sourcing draws from Chilean copper concentrate, Peruvian zinc output, and domestic Ohio River Valley foundry capacity for lead-free brass formulations. PVC resin feeds from Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in the Ohio River Valley foundry cluster, where regional logistics constraints disrupt alloy traceability documentation. Distribution runs through independent irrigation dealers losing share to USDA program-certified distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in smart actuator attachment rates and service revenue models, as precision agriculture hardware shifts farm capital toward premium-tier specification.
For Market Incumbents: Lock in brass alloy traceability documentation through captive Ohio River Valley foundry relationships or long-term offtake agreements. Defend specification authority in California Central Valley groundwater sustainability zones by accelerating EPA WaterSense certification timelines. Priority levers include backward integration into edge-computing firmware development and exclusive distribution control across western state agricultural corridors. For New Entrants and Emerging Players: Enter via Nebraska and Kansas pivot-to-drip conversion projects where pressure-compensating valve technology remains underpenetrated. White-space targets include 5G-enabled telemetry service bundling for almond growers in California's San Joaquin Valley and stainless steel valve specification in Arizona brackish groundwater zones. Go-to-market angle should leverage USDA Environmental Quality Incentives Program administration partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded systems talent scarcity fragments IoT-enabled valve controller development capacity. Long-term viability favors platforms combining hardware specification authority with recurring telemetry service revenue. Acquisition target archetype: regional foundry-dependent OEMs with EPA certification assets and untapped smart actuator retrofit potential. Signal to watch: FERC hydropower licensing grant disbursement velocity as agricultural water district infrastructure eligibility indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Cincinnati and Louisville industrial corridors anchor lead-free brass supply with full alloy traceability. |
| EPA WaterSense Certification Acceleration | Third-party test data at multiple pressure points unlocks municipal water district procurement eligibility. |
| Smart Actuator Platform Integration | IoT-enabled electric actuation with 4-20mA feedback loops penetrates Corn Belt precision agriculture. |
| 5G Telemetry Service Bundling | Real-time soil moisture data integration creates recurring revenue beyond hardware transactional sales. |
| Nebraska-Kansas Geographic Expansion | USDA cost-share arrangements direct farm capital toward pivot-to-drip conversion valve specification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate irrigation valve procurement patterns. Primary engagement included brass foundry operations managers, agricultural water district procurement officers, precision irrigation OEM product directors, and USDA program administration specialists. Secondary validation drew from EPA WaterSense certification databases, FERC hydropower licensing records, USDA Environmental Quality Incentives Program disbursement reports, and American Water Works Association specification standards. Bottom-up demand modeling across crop types and acreage combined with top-down agricultural equipment spending analysis.
Segment-weighting applied product type, actuation mechanism, material grade, and end-use application intensity dimensions across the projection horizon. CAGRs derived from installed-base replacement cycles, precision agriculture penetration curves, and regulatory compliance mandate timelines. Forecast inputs incorporated California Sustainable Groundwater Management Act implementation velocity and Nebraska pivot-to-drip conversion project pipelines.
Inputs from EPA certification databases and USDA program records were available through the study window; gaps in real-time brass alloy pricing transparency introduce uncertainty bands around foundry cost pass-through assumptions. Forecasts reflect documented assumptions regarding smart actuator adoption curves and federal infrastructure grant disbursement rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Global Anal Irrigation Systems Market
Farm Equipment and Irrigations
Africa Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Global Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Greenhouse Irrigation Systems Market
Farm Equipment and Irrigations
Global Mechanized Irrigation Systems Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Smart Sprinkler Irrigation Systems Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Global Irrigation Machinery Market