
 North America Agricultural Tires Market | 2026-2036
North America Agricultural Tires Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Tires Market Analytics
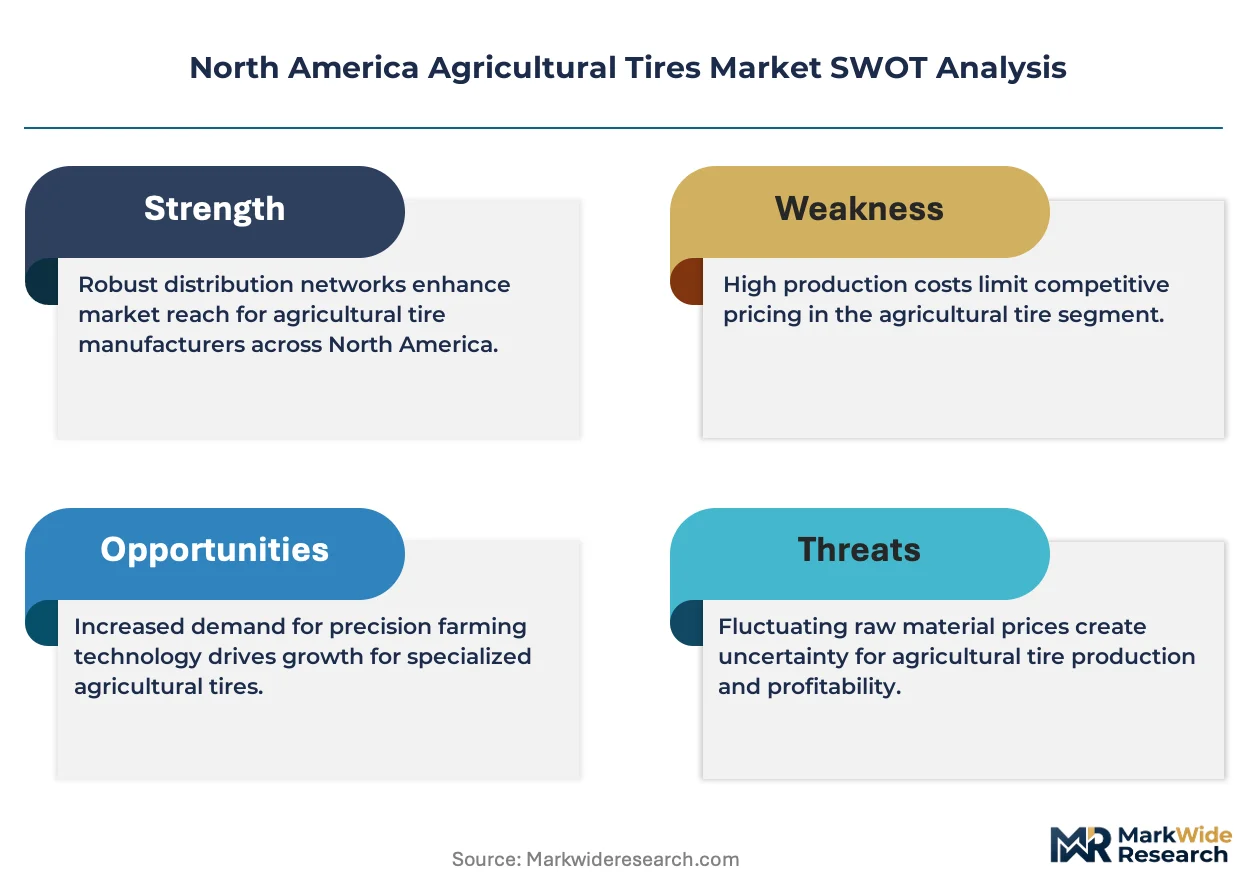
DOT FMVSS 139 certification is rotating the competitive landscape by disqualifying suppliers unable to meet endurance and high-speed performance benchmarks for agricultural tire imports. Bridgestone Corporation leverages its Tennessee manufacturing footprint to sustain just-in-time deliveries across the Southeast. Titan International anchors its position through captive rubber processing and wheel-tire integration for original equipment fitments on major tractor brands.
North America agricultural tires are pneumatic structures engineered with reinforced carcass plies, typically nylon or polyester, and tread compounds formulated for soil compaction resistance and self-cleaning in muddy field conditions; they function to transmit engine power to uneven terrain while minimizing yield-robbing ground pressure on cropland. Radial tires command the premium tier due to larger footprint area and fuel efficiency gains on high-horsepower tractors, while bias tires retain volume dominance among cost-sensitive livestock operators running smaller equipment. Specialty tires for flotation and forestry applications capture outsized margins by serving low-volume, high-downtime-cost niches where tire failure halts seasonal operations.
The US Department of Transportation enforces FMVSS standards that govern tire labeling, load ratings, and endurance testing for highway service, while EPA regulations on non-road diesel emissions indirectly shape tire demand by extending equipment replacement intervals and favoring durable, long-wear compounds. Canada's Transport Canada maintains parallel CMVSS requirements that synchronize cross-border product certification for manufacturers serving both markets. Stakeholders must monitor how evolving soil health regulations in California and emerging carbon intensity scoring for agricultural inputs could redirect procurement criteria toward tires with verified low-compaction credentials.
Market Dynamics
Precision agriculture adoption across the Corn Belt is accelerating fleet renewal cycles as farmers replace equipment to accommodate GPS-guided implements and variable-rate technology, compressing traditional replacement intervals and favoring tires engineered for high-horsepower, high-clearance machinery.
Growth Catalysts
- EPA Tier 4 Final emissions compliance:Extended equipment lifecycles under stricter non-road diesel standards drive demand for durable, long-wear tire compounds that match extended tractor replacement intervals.
- Row-crop mechanization in Iowa and Illinois:Large-scale corn and soybean operations prioritize radial tire upgrades to reduce soil compaction and protect yield on high-value acreage.
- IF/VF tire technology:Increased flexion and very high flexion sidewall designs enable lower inflation pressures, expanding footprint area and reducing ground pressure without sacrificing load capacity.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply disruptions transmit directly to tire manufacturer input costs, compressing margin visibility on long-distribution-cycle agricultural products.
- DOT FMVSS 139 certification barriers:Endurance and high-speed testing requirements disqualify import suppliers lacking domestic testing infrastructure, limiting price competition at the value tier.
- Steel-cord radial production concentration:Domestic manufacturing capacity for agricultural radial carcasses clusters among a handful of producers, creating bottleneck risk during peak seasonal demand windows.
Strategic Opportunities
- California soil health regulations:Emerging compaction-score mandates for agricultural inputs create verified low-ground-pressure tire categories that command procurement preference in specialty crop districts.
- Livestock sector bias tire replacement:Cost-conscious cattle and dairy operators in the Great Plains remain underpenetrated by radial conversion, representing volume upside for optimized bias-ply durability upgrades.
- Direct-to-farm digital channels:E-commerce platforms and manufacturer-native apps are compressing distributor margins while capturing real-time planting-season demand spikes bypassing traditional dealer networks.
Industry Challenges
- Certification timeline compression:FMVSS 139 testing protocols require months of endurance validation, delaying product launches and mismatching R&D cycles with annual planting-season procurement windows.
- Tire-TPMS integration complexity:Central tire inflation systems and telematics-enabled pressure monitoring demand cross-functional engineering coordination between tire makers and precision ag equipment OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Tires Market |
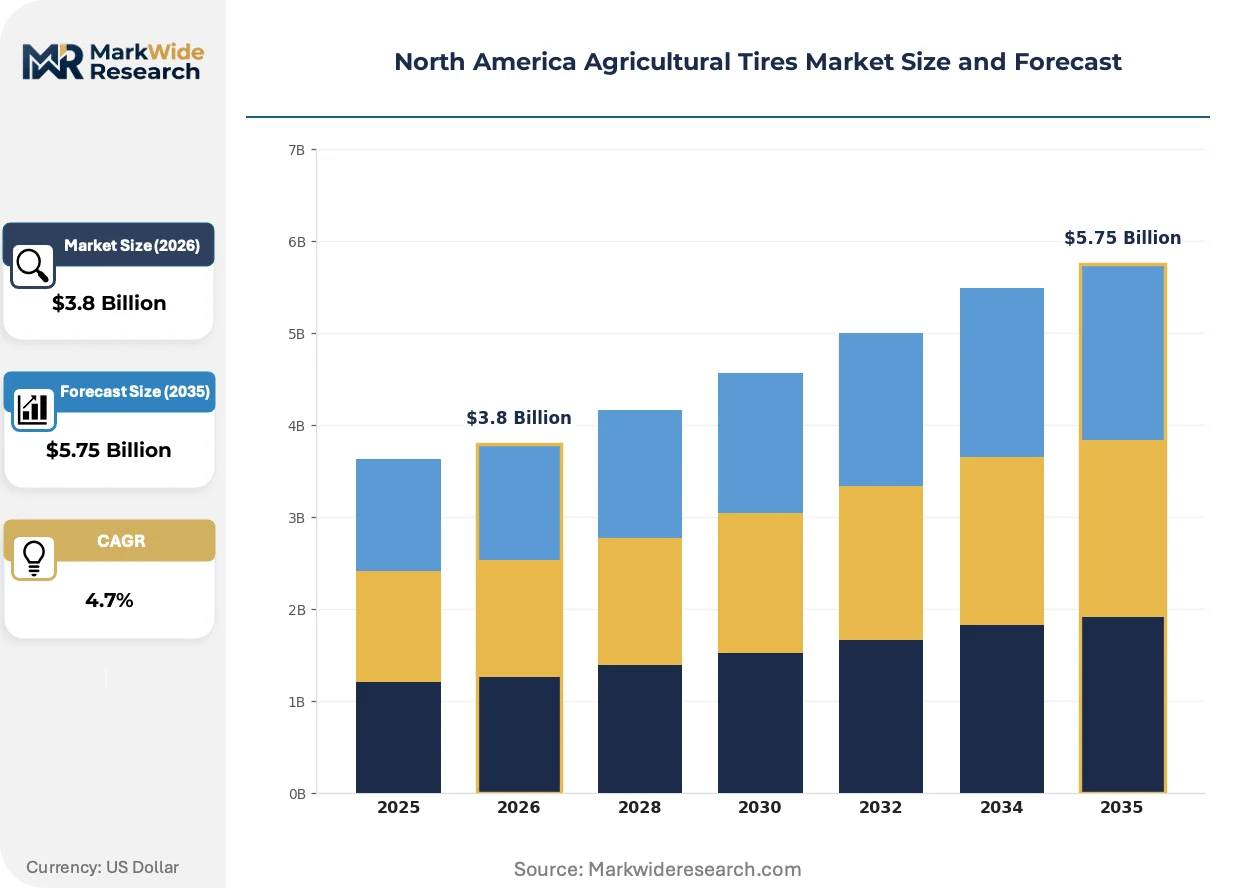
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Specialty Tires, Turf Tires End User: Farmers, Cooperatives, Rental Companies, Contractors Application: Tractors, Harvesters, Sprayers, Cultivators Distribution Channel: Retail Stores, Online Sales, Distributors, Wholesalers |
| Companies Covered | Bridgestone Corporation, Balkrishna Industries, Titan International, Mitas, Alliance Tire Group, Michelin North America, Continental AG, Sumitomo Rubber Industries, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Tires Market Evolving Landscape
Three interconnected developments are restructuring how agricultural tires are specified, procured, and monetized across North American farming operations.
VF (very high flexion) sidewall construction is displacing conventional radial designs in the premium tractor segment by enabling forty-percent load capacity at equivalent inflation pressure. Large-scale operations in Nebraska and Kansas are specifying VF fitments as standard on new equipment orders. This technology is displacing the traditional trade-off between flotation and load-bearing that constrained tire selection for heavy implements.
EPA non-road diesel emission standards are extending equipment replacement intervals and reshaping tire durability specifications across the Midwest. Tier 4 Final compliance costs have compressed new tractor sales volumes while concentrating demand in the replacement tire channel. The aftermarket segment is responding with extended-warranty compounds and retreadable carcass designs that align with longer asset holding periods.
Fleet data analytics are restructuring procurement relationships between tire suppliers and large-scale farming cooperatives. Aggregated usage telemetry from telematics platforms enables predictive replacement scheduling and volume contracting that disintermediates traditional dealer relationships. This shift is most visible across corporate farming operations in the Red River Valley and Central Valley of California where thousand-acre-plus contiguous blocks justify dedicated supply agreements.
North America Agricultural Tires Market Segmentation
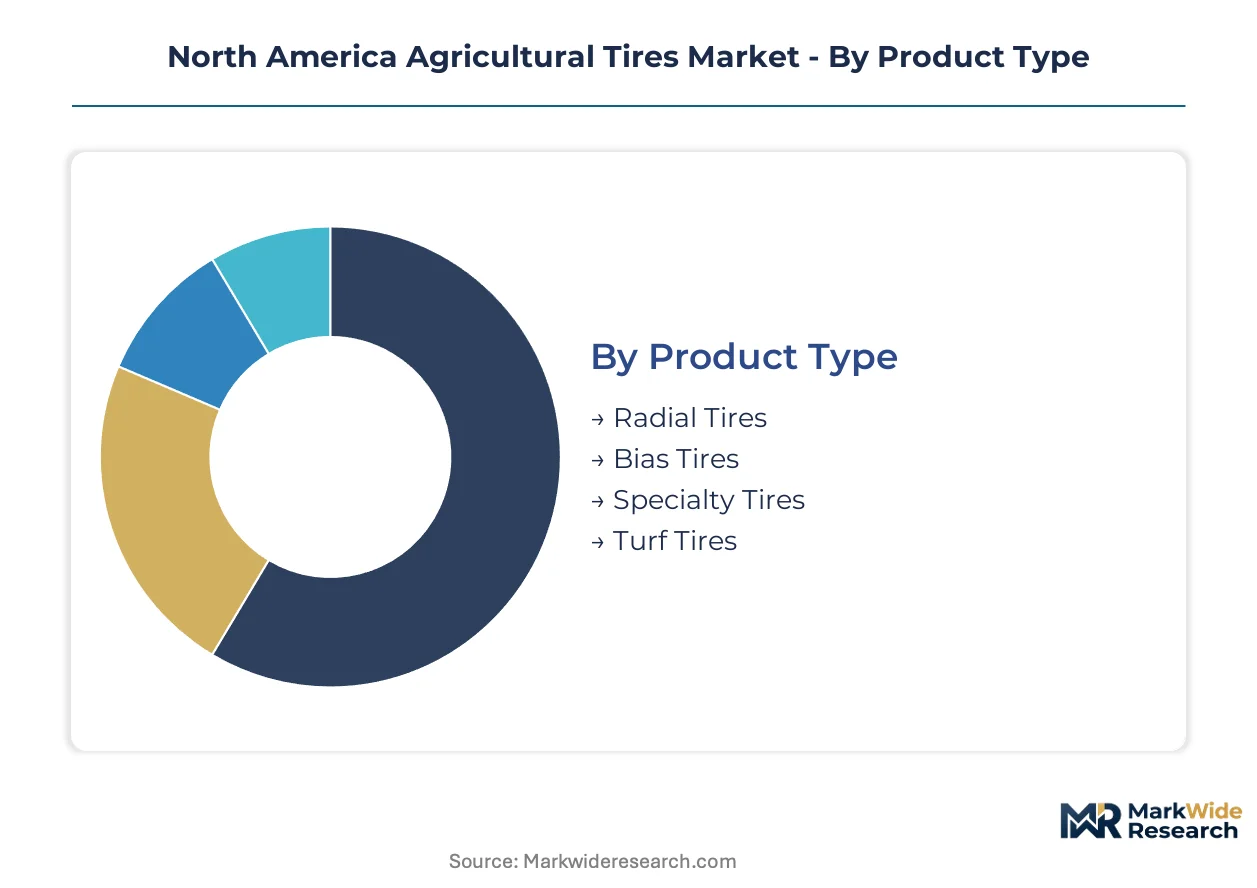
Agricultural tire procurement patterns diverge sharply across product architectures and user economics. Segmentation reveals how radial conversion rates, cooperative purchasing power, and precision ag equipment specifications reshape demand concentration across the Corn Belt and Great Plains.
Product Type:
Radial tire production concentrates at domestic steel-cord facilities serving Iowa and Illinois row-crop operators, while bias tire supply chains source more heavily from Southeast Asian rubber processors.
- Radial Tires:Steel-belted carcass construction with nylon or polyester plies delivers larger footprint area and fuel efficiency on high-horsepower tractors. Demand clusters in Nebraska and Kansas where large-scale corn operations prioritize soil compaction reduction on high-value acreage under precision ag management.
- Bias Tires:Cross-ply nylon construction offers lower unit cost and simpler repairability for smaller equipment. Livestock operators in Texas and Oklahoma retain this specification for cattle feeding operations where equipment utilization rates justify minimal capital outlay.
- Specialty Tires:Flotation and forestry carcasses serve low-volume, high-downtime-cost niches in Pacific Northwest timber operations and Mississippi Delta rice cultivation.
- Turf Tires:Shallow tread patterns minimize ground disturbance for golf course maintenance and sod farming across Florida and Georgia.
Radial tires hold the largest share; momentum sits with specialty tires as compaction-score regulations emerge in California specialty crop districts.
End User:
Cost tier stratification separates enterprise-scale cooperatives running thousand-acre blocks from price-sensitive individual operators.
- Farmers:Individual owner-operators in the Dakotas and Montana balance replacement timing against commodity price cycles, deferring purchases during low-margin growing seasons.
- Cooperatives:Aggregated procurement across Red River Valley corporate farming operations enables volume contracting and predictive replacement scheduling through telematics platforms.
- Rental Companies:Fleet standardization on radial specifications reduces maintenance complexity across dispersed equipment pools serving seasonal demand spikes.
- Contractors:Custom harvesters and planting operators in Kansas and Nebraska prioritize rapid turnaround and 24-hour service availability over unit price.
Cooperatives command the volume base; contractors are climbing the fastest as outsourced precision ag services expand.
Application:
Equipment replacement intervals vary by implement type, with harvester tires seeing accelerated wear from road transport segments between fields.
- Tractors:Primary power units across all farm sizes drive radial upgrade cycles as GPS-guided implements demand higher-horsepower, high-clearance chassis.
- Harvesters:Combine header and grain tank loads concentrate stress on drive wheel positions; Iowa and Illinois operators specify VF sidewall construction for flotation during wet autumn conditions.
- Sprayers:Self-propelled applicators with central tire inflation systems require engineered compatibility between tire carcass and automated pressure management.
- Cultivators:Secondary tillage implements run lighter bias configurations in the Great Plains where draft loads remain moderate.
Tractor fitments dominate unit volume; sprayers show steepest specification upgrade trajectory as variable-rate technology spreads.
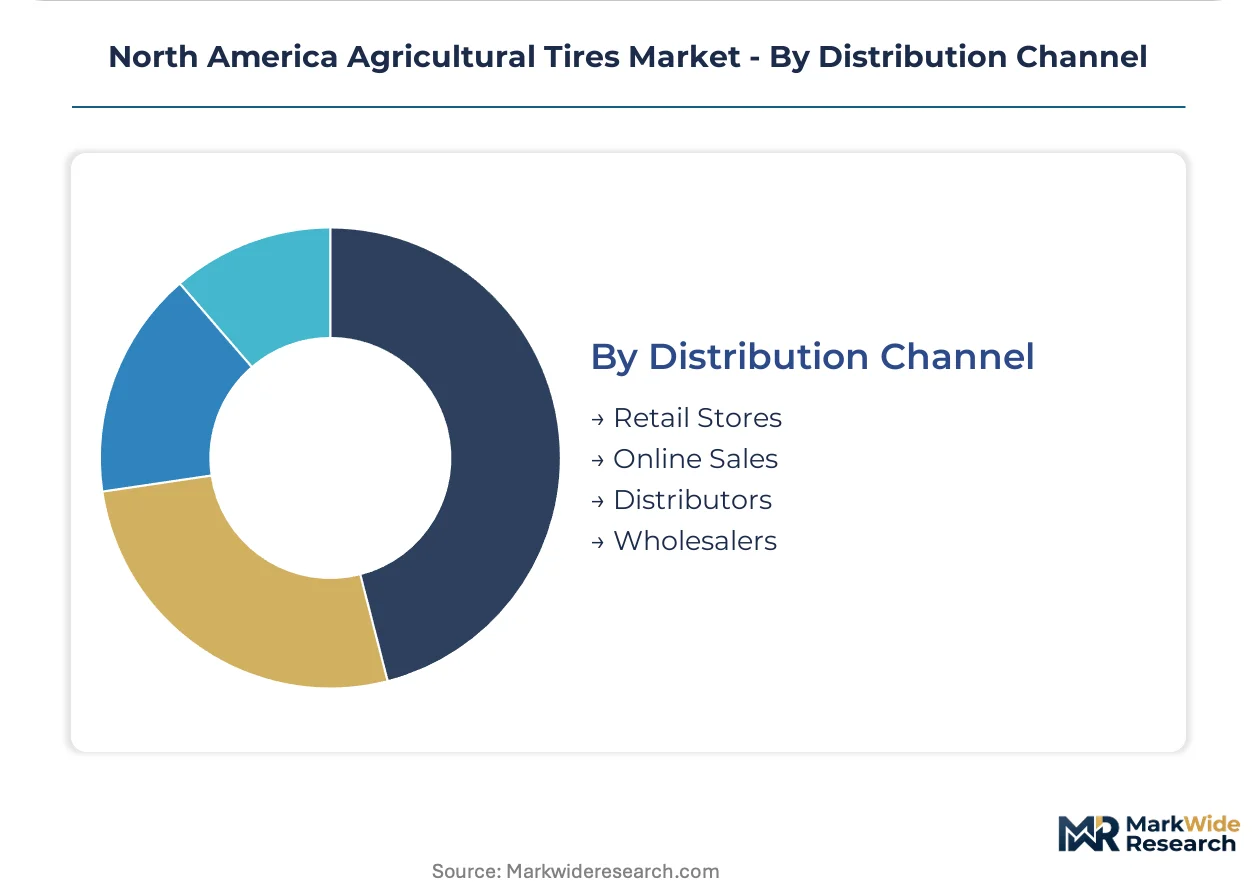
Distribution Channel:
Channel selection tracks operational scale and emergency replacement frequency, with large cooperatives bypassing traditional dealer networks.
- Retail Stores:Dealer-affiliated locations in Midwestern agricultural counties stock seasonal inventory for walk-in replacement during planting and harvest windows.
- Online Sales:Manufacturer-native apps and e-commerce platforms capture real-time demand from younger operators comfortable with digital procurement.
- Distributors:Regional tire distributors maintain just-in-time relationships with Bridgestone's Tennessee manufacturing footprint for Southeast coverage.
- Wholesalers:Volume aggregators serve price-sensitive livestock sectors in the Mountain West where dealer density remains thin.
Distributors retain the largest share; online sales are gaining share fastest as direct-to-farm digital channels compress traditional margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale row-crop operators concentrate procurement power across the Corn Belt and Prairie provinces, while livestock producers in the Southern Plains and Mountain West maintain distinct replacement cycles tied to commodity price exposure.
United States
Midwestern corn and soybean operations in Iowa and Illinois drive radial tire specification upgrades as precision agriculture equipment demands higher load capacities and soil compaction management. EPA Tier 4 Final emissions standards extend tractor replacement intervals, pushing demand toward durable long-wear compounds in the replacement channel. Manufacturing clusters in Tennessee and Ohio anchor domestic steel-cord radial production for just-in-time distribution across the Southeast and Corn Belt.
Canada
Prairie grain operations in Saskatchewan and Manitoba prioritize flotation tire configurations for wet spring seeding conditions on heavy clay soils. Transport Canada's CMVSS requirements synchronize cross-border certification with US FMVSS standards, streamlining product access for manufacturers serving both markets. Regional distribution hubs in Winnipeg and Regina coordinate seasonal inventory positioning ahead of compressed planting windows.
Mexico
Export-oriented vegetable and berry operations in Baja California and Sinaloa specify bias-ply tires for smaller-scale equipment amid capital constraints and shorter asset holding periods. The country's agricultural modernization programs under SADER (Secretaría de Agricultura y Desarrollo Rural) promote mechanization adoption in traditional labor-intensive districts. Guanajuato and Jalisco field equipment clusters represent emerging replacement demand as irrigation infrastructure expands.
North America Agricultural Tires Market Competitive Landscape
Player mix skews toward integrated tire-and-wheel manufacturers with captive rubber processing capabilities and regional distribution infrastructure. Market structure concentrates among three to five vertically positioned suppliers controlling steel-cord radial capacity, while import-dependent value-tier competitors face DOT certification barriers. Strategic archetypes separate domestic integrated producers, Asian scale manufacturers, and European premium specialists. Competitive moves center on capacity expansion in Southeast manufacturing zones and technology licensing for VF sidewall construction.
Within the integrated manufacturing tier, Titan International and Bridgestone Corporation exemplify archetypes combining captive rubber processing with wheel-tire integration for original equipment channels. Balkrishna Industries occupies a position representing Asian scale manufacturing with cost-optimized bias-ply supply chains. Among European premium specialists, Continental AG and Michelin North America anchor the high-performance radial segment through advanced carcass engineering and extended-warranty compound formulations.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Balkrishna Industries |
| Titan International |
| Mitas |
| Alliance Tire Group |
| Michelin North America |
| Continental AG |
| Sumitomo Rubber Industries |
| Trelleborg AB |
| Others |
Value Network & Pricing Analysis
DOT FMVSS 139 certification gates both supply qualification and price differentiation by disqualifying import suppliers lacking domestic testing infrastructure while enabling certified domestic producers to command sustained premiums on radial and VF-tier fitments.
Pricing Analysis
Cost-plus contracts with natural rubber indexation dominate long-term supply agreements between tire manufacturers and fleet operators across the Corn Belt. Three-tier pricing structure across premium VF sidewall, standard radial, and economy bias-ply levels separates certified steel-belted products from import-tier alternatives. Cost compression in the value tier intensifies as Thai and Indonesian supply disruptions transmit directly to compound formulations. Livestock operators in Texas and Oklahoma exhibit highest price sensitivity, while Iowa and Illinois row-crop cooperatives prioritize soil compaction metrics over unit cost.
Supply Chain Analysis
Thailand and Indonesia anchor natural rubber cultivation and initial processing, while Tennessee and Ohio concentrate steel-cord radial carcass manufacturing for just-in-time distribution across the Southeast and Midwest. Synthetic rubber polymers and carbon black feedstocks draw from Gulf Coast petrochemical complexes. Single-source vulnerability in Southeast Asian latex supply creates exposure during monsoon disruptions. Distribution runs through regional tire distributors maintaining seasonal inventory positions ahead of compressed planting windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VF sidewall technology and central tire inflation systems are disrupting traditional replacement cycles, creating first-mover advantages for suppliers integrating telematics-enabled pressure management.
For Market Incumbents: Consolidate steel-cord radial capacity in Tennessee and Ohio manufacturing clusters to defend against import competition from Asian scale manufacturers. Deepen backward integration into captive rubber processing to insulate margin structures from Thai supply volatility. Prioritize FMVSS 139 certification investment as a barrier against uncertified value-tier entrants. For New Entrants and Emerging Players: Lead with digital direct-to-farm channels targeting underpenetrated livestock operators in the Great Plains with optimized bias-ply durability upgrades. California specialty crop districts present the most penetrable segment as compaction-score regulations create verified low-ground-pressure procurement preferences. Partner with precision ag equipment OEMs on tire-TPMS integration to bypass entrenched dealer networks. For Investors and Strategic Acquirers: EPA Tier 4 Final compliance reshapes the acquisition landscape by extending equipment replacement intervals and concentrating aftermarket demand in retreadable carcass technologies. Five-to-ten-year viability favors vertically integrated manufacturers with wheel-tire integration capabilities and regional distribution infrastructure. Monitor California soil health regulation implementation timelines as inflection indicators for low-compaction tire category premiums.| Strategic Initiative | Industry Significance |
|---|---|
| VF Sidewall Technology Licensing | Very high flexion designs enable forty-percent load capacity gains for Nebraska and Kansas operators. |
| Captive Rubber Processing Expansion | Backward integration insulates Titan International and Bridgestone from Thai supply disruptions. |
| Telematics Platform Partnership | Central tire inflation system integration with precision ag OEMs creates switching costs. |
| Direct-to-Farm Digital Channel Buildout | Manufacturer-native apps bypass traditional dealer networks during planting-season demand spikes. |
| Retreadable Carcass Design Investment | Extended-warranty compounds align with Tier 4 Final extended equipment holding periods. |
Research Methodology
Desk research of USDA machinery census data, EPA non-road diesel compliance filings, and tire industry trade statistics preceded structured interviews with OEM procurement directors, regional tire distributors, cooperative fleet managers, and precision ag technology integrators. Primary fieldwork across Iowa, Illinois, Nebraska, and Kansas validated replacement cycle assumptions and VF adoption trajectories. Secondary sources included FMVSS certification databases, customs import records, and agricultural equipment registration data. Bottom-up unit demand estimates triangulated against top-down market value reconstructions.
Variance decomposition across product architecture, end-user scale tier, and regional equipment density shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include tire construction type, horsepower class, application implement, and cooperative purchasing power. CAGRs derived from equipment fleet turnover rates, precision ag adoption curves, and compound durability improvements. Industry-specific inputs encompassed central tire inflation system penetration and California regulatory timeline probabilities.
The analysis sits within stated boundaries; outcomes outside sustained commodity price recovery, stable natural rubber supply, or unmodified EPA enforcement posture would require recalibration. Forecasts reflect documented assumptions on fleet renewal timing and radial conversion rates. Recalibration cycles align with material shifts in precision ag equipment specifications and soil health regulatory implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Potato Planter Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Australia Irrigation Automation Market
Farm Equipment and Irrigations
Agricultural Solar Pumps Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
North America Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
China Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
India Agricultural Irrigation Machinery Market
Farm Equipment and Irrigations
Sprinkler Irrigation Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Lawn Sprinkler Market
Farm Equipment and Irrigations
Watering Cans Market