
 Intubation Tubes Market | 2026-2036
Intubation Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Intubation Tubes Market Intelligence
MDR is pivoting the European cost-of-entry calculus toward clinical evidence generation and notified body recertification. Smiths Medical leverages its vertically integrated manufacturing footprint to absorb these compliance burdens without margin erosion. Medtronic anchors its position through sustained R&D intensity in cuffed endotracheal platforms. Teleflex Incorporated differentiates via specialized distribution control across acute care channels.
Intubation tubes are polymer-based airway conduits, typically fabricated from polyvinyl chloride or silicone in diameters ranging from 2.0 mm to 10.0 mm, designed to secure ventilatory access during anesthesia induction, respiratory failure management, or surgical immobilization of the diaphragm. Endotracheal tubes occupy the largest volume share within product type segmentation due to their ubiquity in operating theaters and intensive care units. Silicone material formulations command premium positioning where biocompatibility tolerance and extended dwell times justify higher unit economics. Critical care applications are expanding fastest within the application dimension as prolonged mechanical ventilation protocols proliferate across tertiary hospitals.
FDA premarket notification pathways, EU MDR clinical evaluation requirements, and ISO 5361 dimensional standards collectively govern product design validation and commercial access across major markets. These frameworks elevate barriers for unproven entrants while rewarding incumbents with established quality management systems and predicate device libraries. Stakeholders must monitor evolving notified body capacity constraints and FDA guidance on antimicrobial-coated airway devices to anticipate certification timeline shifts.
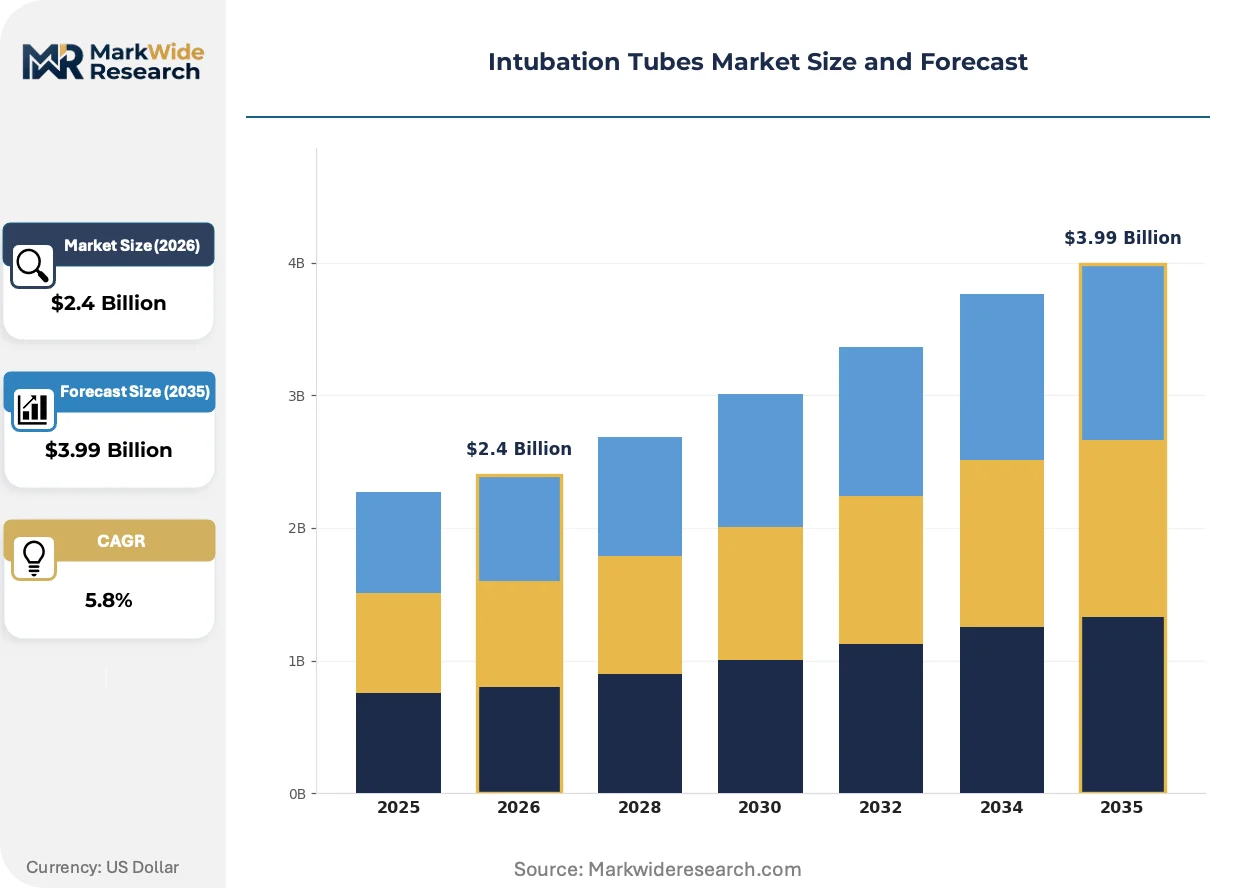
Market Dynamics
The Intubation Tubes Market is experiencing structural pressure from EU MDR recertification timelines, which are compressing notified body capacity and forcing manufacturers to front-load clinical evidence generation costs before legacy CE certificates expire.
Growth Catalysts
- EU MDR Clinical Evidence Mandates:Stricter post-market surveillance requirements under the Medical Device Regulation are filtering out marginal suppliers and consolidating procurement toward validated incumbents with predicate device libraries.
- Trauma Center Expansions:Hospital infrastructure buildouts across the United States are expanding procedural throughput for emergency airway management in Level I and Level II facilities.
- Silicone Formulation Advances:Enhanced biocompatibility tolerances in silicone-based tubes are extending safe dwell times for prolonged mechanical ventilation protocols in tertiary ICUs.
Market Restraints
- Polymer Input Cost Volatility:Medical-grade polyvinyl chloride resin prices fluctuate with petrochemical feedstock markets, compressing margin buffers for standard tube manufacturers.
- Notified Body Bottlenecks:EU MDR designation constraints have reduced the pool of accredited certification bodies to under thirty organizations, extending approval timelines for new market entrants.
- Reusable Video Laryngoscopes:Advanced visualization systems are reducing first-attempt intubation failure rates and potentially moderating per-procedure tube consumption in elective surgical settings.
Strategic Opportunities
- Antimicrobial Coating Differentiation:FDA guidance pathways for antimicrobial-impregnated airway devices are creating a regulatory tailwind for coating technology suppliers seeking 510(k) predicate strategies.
- Home Ventilation Transition:Post-acute care settings are emerging as a channel for specialized tracheostomy tubes designed for ambulatory mechanical ventilation outside hospital walls.
- ISO 5361 Dimensional Harmonization:Standardization across connector interfaces is enabling modular tube designs that reduce inventory complexity for multi-site health systems.
Industry Challenges
- Polymer Extrusion Expertise Scarcity:Precision manufacturing of thin-wall medical tubing requires specialized extrusion technicians, creating recruitment friction for capacity expansion.
- FDA 510(k) Predicate Device Pathway Complexity:Substantial equivalence determinations for novel tube designs are extending submission review cycles as the agency tightens predicate validation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intubation Tubes Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endotracheal Tubes, Nasotracheal Tubes, Laryngeal Masks, Tracheostomy Tubes Material: Polyvinyl Chloride, Silicone, Latex, Polyethylene Application: Anesthesia, Critical Care, Emergency Medicine, Surgical Procedures End User: Hospitals, Ambulatory Surgical Centers, Emergency Departments, Home Care Services |
| Companies Covered | Smiths Medical, Becton Dickinson and Company, Teleflex Incorporated, ConvaTec, Armstrong Medical, Medtronic, ICU Medical, Fuji Systems Corporation, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intubation Tubes Market Strategic Shifts & Innovations
Active innovation across the Intubation Tubes Market centers on material science differentiation, regulatory compliance automation, and procurement consolidation patterns that favor suppliers with integrated quality systems.
Subglottic secretion drainage technology is expanding into standard-of-care positioning for ventilator-associated pneumonia prevention in prolonged intubation cases. Critical care units in academic medical centers are adopting cuffed tubes with integrated suction lumens at accelerated replacement cycles. This capability is expanding into mid-tier hospital procurement specifications as bundled payment penalties for hospital-acquired infections intensify.
EU MDR Article 120 transition timelines are forcing manufacturers to revalidate technical documentation for legacy airway devices ahead of certificate expiration deadlines. The industrial consequence is a capital reallocation toward clinical evaluation reports and post-market clinical follow-up studies rather than greenfield product development. Tube suppliers with established notified body relationships are accelerating submissions to secure queue priority, while smaller competitors face exclusion from tender participation.
Consolidated purchasing organizations are consolidating supplier panels around vendors with vertically integrated sterilization and packaging capabilities. Health system procurement committees are replacing fragmented distributor relationships with direct manufacturer contracts that bundle tube SKUs across anesthesia, emergency, and ICU departments. This pattern is most visible in United States integrated delivery networks seeking to standardize connector compatibility and reduce SKU proliferation across affiliated facilities.
Intubation Tubes Market Segmentation
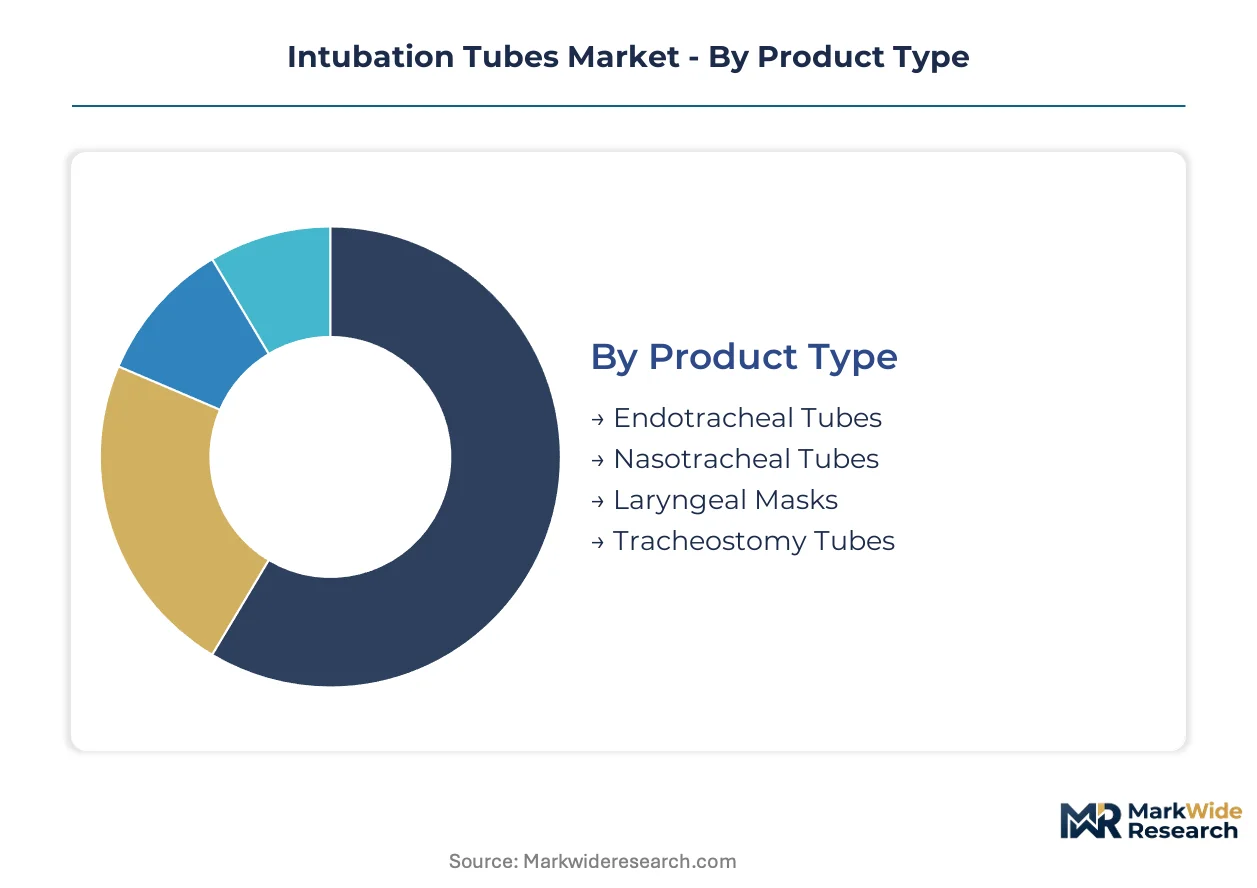
Intubation tube procurement patterns diverge sharply across clinical settings, with material biocompatibility requirements and procedure acuity driving SKU fragmentation. Manufacturers must balance standardized connector geometries against specialized feature sets for prolonged ventilation protocols.
Product Type:
Customization intensity varies from commodity anesthesia tubes to engineered critical care platforms with integrated monitoring capabilities.
- Endotracheal Tubes:Polyvinyl chloride or silicone conduits inserted orally or nasally to secure the trachea during mechanical ventilation. Demand concentrates in United States tertiary hospitals where trauma center expansions sustain high procedural throughput for emergency airway management.
- Nasotracheal Tubes:Narrower-diameter variants designed for nasal passage insertion, preserving oral access for dental or maxillofacial procedures. Critical care units in academic medical centers favor these for prolonged intubation cases requiring sustained patient comfort.
- Laryngeal Masks:Supraglottic airway devices providing ventilation without tracheal penetration, deployed in elective surgical settings.
- Tracheostomy Tubes:Surgically placed conduits for long-term ventilation, gaining traction in post-acute home care transitions.
Most installed capacity flows through Endotracheal Tubes. Expansion is steepest in Tracheostomy Tubes.
Material:
Cost tier stratification separates commodity polymer formulations from premium silicone platforms commanding extended-dwell premiums.
- Polyvinyl Chloride:Thermoplastic polymer offering dimensional stability and cost efficiency for standard single-use tubes. United States hospital purchasing organizations specify PVC formulations for high-volume anesthesia departments where per-procedure economics dominate procurement decisions.
- Silicone:Elastomeric material with superior biocompatibility tolerance and thermal stability for extended ventilation protocols. Tertiary ICUs in Germany and France specify silicone for patients requiring mechanical ventilation beyond standard replacement cycles.
- Latex:Natural rubber compound with elastic recovery properties, now restricted in many facilities due to hypersensitivity protocols.
- Polyethylene:Semi-crystalline thermoplastic selected for specialized low-friction surface requirements.
Volume concentration sits with Polyvinyl Chloride. Margin expansion is strongest in Silicone.
Application:
Procedure acuity determines feature complexity, from basic anesthesia induction to multi-lumen critical care platforms with subglottic drainage.
- Anesthesia:Standard intubation for operative procedures requiring temporary ventilatory support. Ambulatory surgical centers in the United States drive replacement demand through high turnover of elective procedures.
- Critical Care:Prolonged mechanical ventilation in intensive care units with integrated suction and monitoring capabilities. Academic medical centers in the United States are accelerating adoption of cuffed tubes with subglottic secretion drainage for ventilator-associated pneumonia prevention.
- Emergency Medicine:Rapid-sequence intubation in pre-hospital and trauma settings requiring standardized connector compatibility.
- Surgical Procedures:Specialized tubes for thoracic and cardiac operations requiring lung isolation or deflation.
Revenue concentration aligns with Critical Care. Procedure volume is highest in Anesthesia.
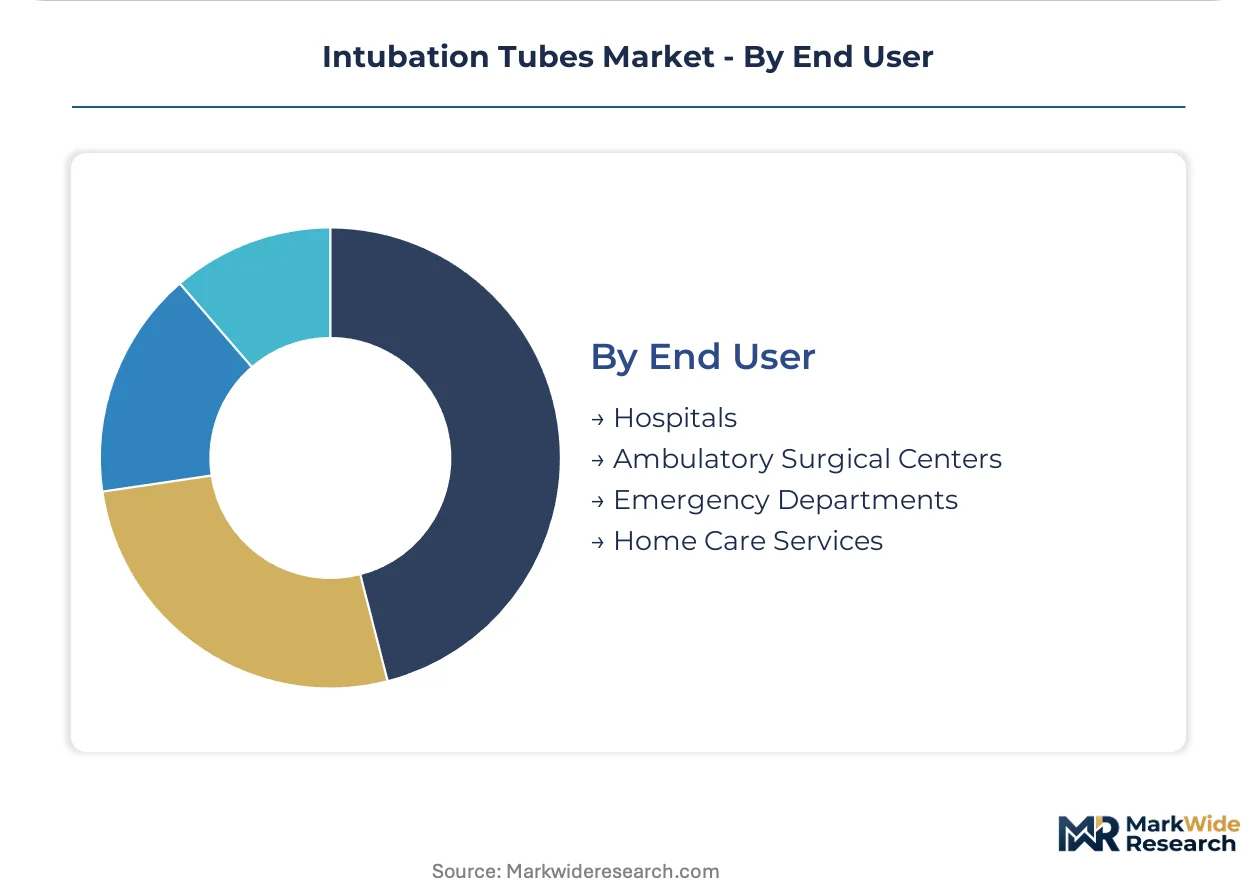
End User:
Customer type shapes distribution architecture, from consolidated health system contracts to fragmented home care channels.
- Hospitals:Integrated delivery networks with centralized procurement committees standardizing SKU portfolios across anesthesia, emergency, and ICU departments. United States health systems are consolidating supplier panels around vendors with captive sterilization and packaging capabilities.
- Ambulatory Surgical Centers:Freestanding facilities performing elective procedures with streamlined anesthesia protocols. These centers in the United States favor single-use PVC tubes with minimal feature sets to optimize per-case supply costs.
- Emergency Departments:Hospital-based acute care units requiring rapid inventory turnover for unscheduled airway events.
- Home Care Services:Post-acute providers managing tracheostomy patients outside institutional settings.
Procurement volume dominates in Hospitals. Channel growth is accelerating in Home Care Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The intubation tube industry traces its modern commercial origins to post-war medical polymer advances in the United States and Germany, where precision extrusion techniques first enabled mass production of disposable airway conduits for anesthesia and critical care.
United States
Trauma center expansions across Level I and Level II facilities sustain elevated procedural throughput for emergency airway management. FDA premarket notification pathways for airway devices enforce substantial equivalence standards that favor established manufacturers with predicate device libraries. The Texas Medical Center in Houston and Boston's Longwood Medical Area concentrate procurement decision-making for integrated delivery networks standardizing connector compatibility across anesthesia, emergency, and ICU departments.
Germany
Tertiary ICUs in academic medical centers specify silicone formulations for prolonged mechanical ventilation beyond standard replacement cycles. EU MDR clinical evaluation requirements and notified body recertification timelines compress approval pathways for new entrants while rewarding incumbents with established quality management systems. The MedTech cluster around Tübingen and Freiburg anchors precision polymer extrusion capabilities serving continental European hospital procurement.
France
Aging demographics and hospital infrastructure modernization sustain demand for ventilator-associated pneumonia prevention technologies including subglottic secretion drainage tubes. ANSM oversight aligns with EU MDR post-market surveillance mandates requiring front-loaded clinical evidence generation. The Paris-Saclay medical research corridor drives adoption of antimicrobial-coated airway platforms in academic critical care units.
Japan
PMDA regulatory frameworks emphasize biocompatibility testing for extended-dwell silicone tubes in aging patient populations requiring prolonged ventilation. METI industrial policy supports domestic polymer processing capabilities for medical-grade tubing. The Kansai region around Osaka maintains concentrated manufacturing expertise in thin-wall extrusion for specialized nasotracheal and tracheostomy applications.
China
NMPA medical device classification rules for airway management products are elevating documentation requirements for domestic and imported manufacturers alike. Hospital procurement centralization under volume-based purchasing compresses unit economics for standard PVC tubes while opening tiered opportunities for premium silicone platforms. The Yangtze River Delta medical device manufacturing belt around Shanghai scales polymer compounding and extrusion capacity for domestic and export markets.
Intubation Tubes Market Key Industry Players
The competitive structure tilts toward diversified medical device conglomerates with captive polymer processing capabilities and established notified body relationships. Incumbents leverage predicate device libraries and integrated sterilization infrastructure to absorb EU MDR compliance costs without margin erosion. Three archetypes dominate: vertically integrated multinational corporations, specialized airway management divisions within broader critical care portfolios, and regional fabricators serving price-sensitive procurement segments. Consolidation through direct manufacturer contracts with integrated delivery networks and backward integration into medical-grade resin compounding represent the dominant competitive vectors.
Within the multinational tier, Smiths Medical, Medtronic, and Teleflex Incorporated exemplify divergent strategic positioning. Smiths Medical occupies a fabrication-anchored position leveraging polymer extrusion depth. Medtronic represents the R&D-intensive archetype sustaining investment in cuffed platform engineering. Teleflex Incorporated sits within the distribution-control segment, channeling specialized acute care reach. These three entities collectively illustrate how scale, manufacturing integration, and channel architecture define competitive separation in airway device procurement.
| Leading Market Players |
|---|
| Smiths Medical |
| Becton Dickinson and Company |
| Teleflex Incorporated |
| ConvaTec |
| Armstrong Medical |
| Medtronic |
| ICU Medical |
| Fuji Systems Corporation |
| Medline Industries |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up polymer specialists have consolidated medical-grade PVC and silicone extrusion capacity across the United States and Germany, concentrating supply-side pricing power while compressing margin buffers for undifferentiated tube manufacturers serving ambulatory surgical centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with silicone formulations commanding extended-dwell premiums based on biocompatibility certification grade and FDA predicate device lineage. Price differentiation hinges on ISO 5361 dimensional compliance tier and volume scale commitments from integrated delivery networks. Cost compression in standard PVC segments is intensifying because of hospital procurement centralization under volume-based purchasing agreements. Ambulatory surgical centers exhibit highest price sensitivity, while tertiary ICUs prioritize performance over per-unit economics.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China anchor hub-and-spoke patterns that feed acute care inventory systems with 48-hour replenishment cycles. Medical-grade polyvinyl chloride resin and platinum-cured silicone elastomer feedstock draw from petrochemical complexes in Texas, Louisiana, and the Rhine-Ruhr basin. Single-source vulnerability concentrates in notified body certification capacity, where fewer than thirty accredited organizations handle EU MDR recertification. Distribution runs through direct manufacturer contracts with integrated delivery networks, bypassing fragmented distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Intubation Tubes Market functions as a regulatory compounder, with EU MDR Article 120 transition timelines and FDA antimicrobial coating guidance creating sustained demand for clinical evidence generation and predicate device validation.
For Market Incumbents: Extend predicate device libraries through accelerated 510(k) submissions before FDA tightens substantial equivalence standards further. Deepen backward integration into medical-grade resin compounding to absorb polymer input cost volatility without margin erosion. Consolidate sterilization and packaging capabilities to secure preferred supplier status with integrated delivery networks consolidating SKU portfolios. For New Entrants and Emerging Players: Begin with post-acute home ventilation channels, where specialized tracheostomy tube demand outpaces incumbent supply focus. Target antimicrobial coating technology partnerships as a regulatory-fast-track entry angle. Pursue direct-to-home-care-provider distribution models that bypass hospital GPO contracting barriers. For Investors and Strategic Acquirers: Diversified medical device conglomerates with captive polymer processing capabilities are the most active acquirers in this space, seeking notified body relationships and predicate device libraries. Acquisition targets should display established EU MDR technical documentation and post-market clinical follow-up infrastructure. Watch notified body queue priority allocation as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | Secures queue priority with limited notified body capacity before legacy CE certificates expire. |
| Antimicrobial Coating FDA Submission | Positions suppliers for 510(k) predicate strategies under emerging FDA guidance pathways. |
| Backward Integration into Resin Compounding | Captures medical-grade PVC and silicone supply chains to buffer petrochemical feedstock volatility. |
| Hospital System Direct Contracting | Bypasses fragmented distributor networks to standardize connector compatibility across anesthesia, emergency, and ICU departments. |
| Subglottic Secretion Drainage Platform Expansion | Addresses ventilator-associated pneumonia prevention protocols spreading from academic medical centers to mid-tier hospitals. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO certification registries. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable historical reference periods spanning pre-pandemic baselines through EU MDR implementation phases anchored the projection horizon across product type, material formulation, application acuity, and end-user channel dimensions. CAGRs were derived from segmented growth trajectory blending rather than single-point extrapolation. Forecast inputs incorporated procedural volume elasticity to trauma center expansions and silicone dwell-time extension protocols in tertiary ICUs.
Several conditions sit outside the modeled scope, including sudden notified body capacity collapses, polymer feedstock supply disruptions from geopolitical events, and radical displacement of endotracheal tubes by supraglottic alternatives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Cervical Implants Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
United States Implantable Medical Devices Market