
 United States Implantable Medical Devices Market | 2026-2036
United States Implantable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Implantable Medical Devices Market Intelligence
Polyetheretherketone is restructuring cost structures across spinal and orthopedic implant portfolios as it displaces traditional titanium alloys in load-bearing applications. Medtronic plc leverages its integrated neuromodulation pipeline to sustain leadership in active implantable systems. Boston Scientific Corporation anchors its cardiac rhythm franchise through deep catheter-lab relationships. Abbott Laboratories differentiates via miniaturized drug-eluting platforms that reduce revision rates.
Implantable medical devices encompass electromechanical and biocompatible constructs engineered for long-term residence within human tissue, typically incorporating hermetic titanium or polymer housings, platinum-iridium electrodes, and wireless telemetry operating at medical device radio frequencies. Their primary purpose is to restore physiological function, deliver targeted therapy, or provide structural support without repeated surgical intervention. Pacing devices and cardiac stents occupy mature margin pools where ASP erosion is offset by procedure volume expansion, while neurostimulators represent the fastest-growing product category as chronic pain and movement disorder indications broaden. Bioelectric technology platforms command premium positioning against metal-based alternatives due to closed-loop feedback capabilities and rechargeable power management.
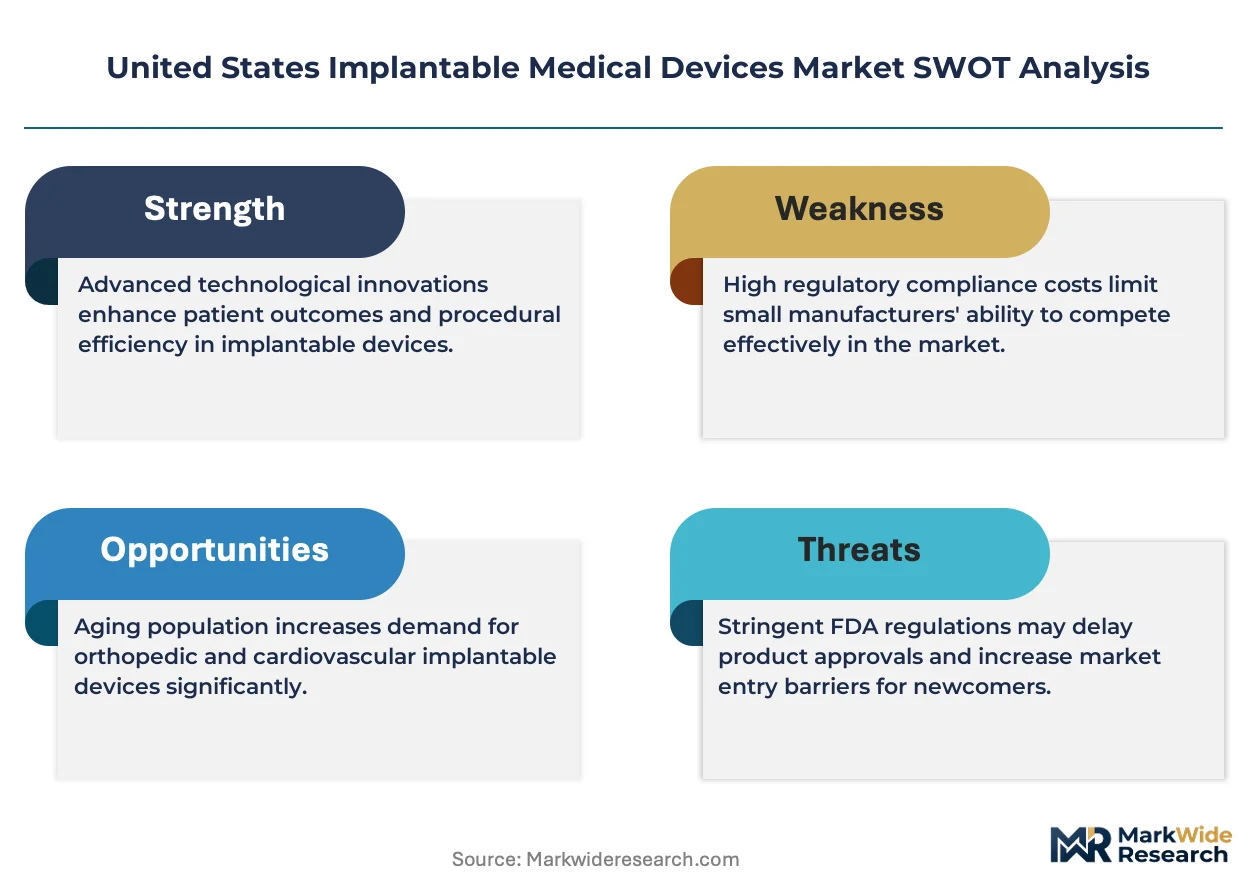
FDA premarket approval and 510(k) clearance pathways govern market access timelines, with FDA's Center for Devices and Radiological Health intensifying cybersecurity requirements for connected implants. NHTSA coordinates emergency responder protocols for patients carrying active implantable devices, while CMS reimbursement determinations directly shape hospital procurement decisions across Medicare-dependent states. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled implant diagnostics and state-level Medicaid expansion patterns that alter addressable patient populations.
Market Dynamics
Polyetheretherketone penetration into spinal fusion cages is compressing titanium alloy procurement cycles while reshaping orthopedic OEM sourcing strategies across the United States.
Growth Catalysts
- Medicare Reimbursement Expansion:CMS coverage determinations for dorsal root ganglion stimulation are expanding addressable patient pools for chronic pain management in ambulatory surgical centers.
- Florida Surgical Density:Concentration of Medicare-certified ambulatory surgery centers in Miami-Dade and Broward counties is attracting device-intensive orthopedic and cardiac procedures.
- Bioelectric Closed-Loop Systems:Rechargeable neurostimulators with adaptive feedback algorithms are commanding premium placement against fixed-output metal-based alternatives.
Market Restraints
- Platinum-Iridium Electrode Cost Volatility:Precious metal input fluctuations are pressuring margins on cardiac pacing leads and neurostimulation arrays.
- FDA Cybersecurity Mandates:CDRH premarket requirements for wireless telemetry authentication are extending 510(k) clearance timelines for connected implantable pulse generators.
- Bioresorbable Polymer Limitations:Mechanical degradation rates in magnesium-based vascular scaffolds are constraining adoption against permanent metal stents.
Strategic Opportunities
- Texas Medicaid Expansion Patterns:State-level coverage expansion for movement disorder therapies is enlarging addressable populations for deep brain stimulation systems.
- AI-Enabled Diagnostic Integration:Artificial intelligence algorithms embedded in implantable cardioverter-defibrillators are creating predictive maintenance revenue streams.
- Direct-to-Ambulatory Distribution:Manufacturer bypass of hospital purchasing committees through specialist-owned surgical centers is shortening sales cycles.
Industry Challenges
- Biocompatibility Certification Bottlenecks:ISO 10993 cytotoxicity testing backlogs are delaying polymer-to-metal conversion programs for load-bearing orthopedic implants.
- Legacy System Interoperability:Integration friction between next-generation wireless telemetry protocols and existing hospital IT infrastructure is complicating rollout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Implantable Medical Devices Market |
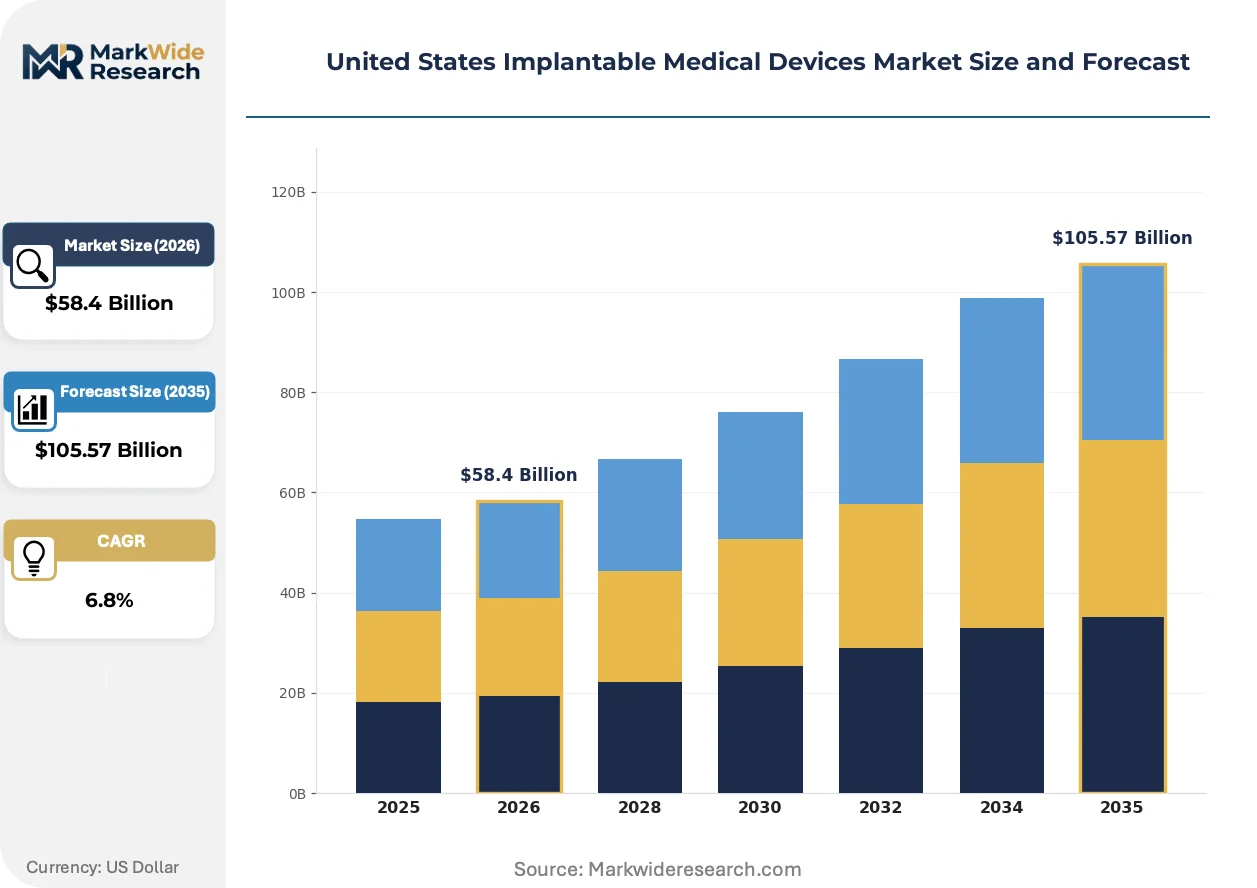
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacing Devices, Orthopedic Implants, Cardiac Stents, Neurostimulators Technology: Bioelectric, Active Implantable, Drug-Eluting, Metal-Based End User: Hospitals, Outpatient Clinics, Surgical Centers, Home Care Delivery Mode: Invasive, Minimally Invasive, Perioperative, Remote Monitoring |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Johnson & Johnson, Stryker Corporation, Zimmer Biomet Holdings, Inc., Edwards Lifesciences Corporation, Smith & Nephew plc, Globus Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Implantable Medical Devices Market Strategic Shifts & Innovations
Active implantable systems are absorbing computational capabilities that previously resided in external programmers, collapsing the boundary between device and diagnostic platform.
Polyetheretherketone is absorbing mechanical loading functions in lumbar interbody fusion devices, permitting radiolucent imaging that titanium cages obstruct. Academic medical centers in California are adopting PEEK-OPTIMA polymer formulations at accelerated pace for multi-level constructs. This material transition is absorbing revision surgery costs by enabling clearer postoperative fusion assessment via CT imaging.
FDA Center for Devices and Radiological Health is intensifying premarket cybersecurity documentation requirements for implants with radiofrequency telemetry capabilities. Manufacturers must now submit threat modeling and penetration testing protocols alongside traditional biocompatibility data. Cardiac rhythm management devices with Bluetooth connectivity are experiencing the most pronounced timeline compression as firms re-engineer authentication architectures.
Hospital purchasing committees are fragmenting into specialty-specific value analysis teams with divergent evaluation criteria. Cardiology service lines now negotiate cardiac device contracts independently from orthopedic procurement functions that previously consolidated spend. This organizational unbundling is most visible in Texas and Florida health systems where specialist employment models dominate.
United States Implantable Medical Devices Market Segmentation
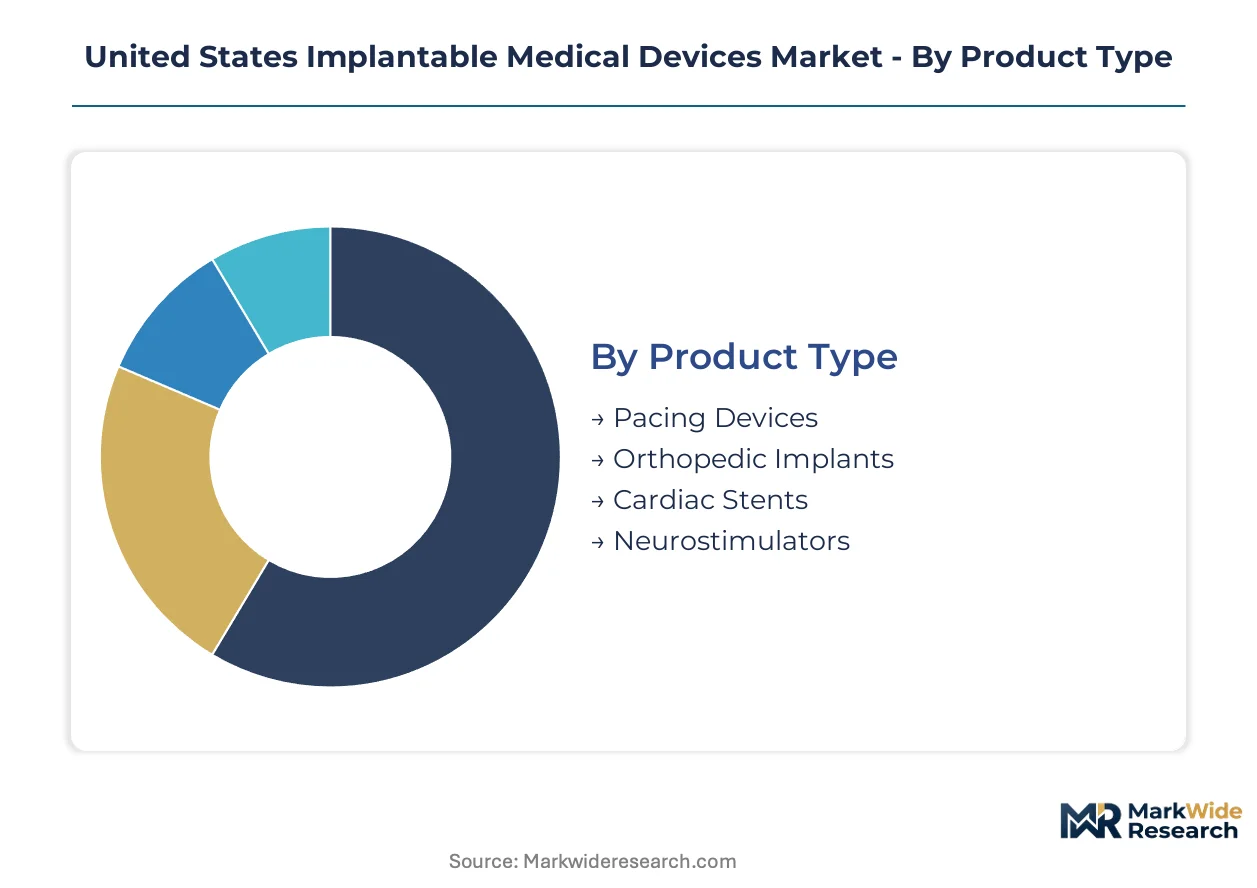
Segmentation in the United States implantable medical devices market reveals how procurement authority, reimbursement pathways, and clinical workflow constraints reshape vendor access. Buyers across hospitals, surgical centers, and outpatient clinics apply divergent evaluation criteria that fragment what appears to be a unified market.
Product Type:
Hospital value analysis committees weight revision risk and total episode cost when selecting between durable mechanical implants and bioelectric alternatives.
- Orthopedic Implants:Polyetheretherketone spinal cages and titanium alloy joint replacements dominate procurement cycles. Florida Medicare-certified ambulatory surgery centers are accelerating conversion to radiolucent polymer constructs that enable clearer postoperative CT assessment.
- Neurostimulators:Rechargeable closed-loop systems with adaptive feedback algorithms command premium placement. Texas and California specialist networks are expanding dorsal root ganglion stimulation programs as CMS broadens chronic pain coverage determinations.
- Pacing Devices:Cardiac rhythm management systems with wireless telemetry face extended FDA clearance timelines under intensified CDRH cybersecurity mandates.
- Cardiac Stents:Drug-eluting and bare-metal platforms occupy mature margin pools where procedure volume expansion offsets ASP erosion.
Volume sits with orthopedic implants; growth tilts toward neurostimulators.
Technology:
Technology selection hinges on power management architecture and feedback capability rather than material cost alone.
- Bioelectric:Closed-loop neuromodulation platforms with rechargeable power systems are displacing fixed-output alternatives. California academic medical centers are prioritizing adaptive algorithms for movement disorder applications.
- Active Implantable:Pulse generators with embedded diagnostic computation are collapsing boundaries between therapy delivery and patient monitoring. Miami-Dade surgical centers are demanding Bluetooth-enabled programmers for specialist-owned facilities.
- Drug-Eluting:Miniaturized platforms that reduce revision rates are penetrating cardiac and orthopedic applications.
- Metal-Based:Titanium alloys retain load-bearing roles where PEEK mechanical properties prove insufficient for multi-level constructs.
Procurement volume clusters around metal-based and active implantable systems; bioelectric platforms are climbing the fastest.
End User:
End-user segmentation tracks the unbundling of hospital purchasing committees into specialty-specific procurement functions.
- Surgical Centers:Specialist-owned facilities in Texas and Florida are bypassing hospital value analysis teams through direct manufacturer relationships. Medicare reimbursement rate differentials in these states attract device-intensive orthopedic and cardiac procedures.
- Hospitals:Integrated health systems retain cardiac device contracting but cede orthopedic procurement to service-line autonomy. Cardiology departments now negotiate rhythm management contracts independently from consolidated spend pools.
- Outpatient Clinics:Movement disorder and pain management practices are expanding deep brain stimulation and spinal cord stimulation patient volumes.
- Home Care:Remote monitoring integration is extending implant surveillance beyond acute settings.
Revenue concentration remains with hospitals; surgical centers are gaining share fastest.
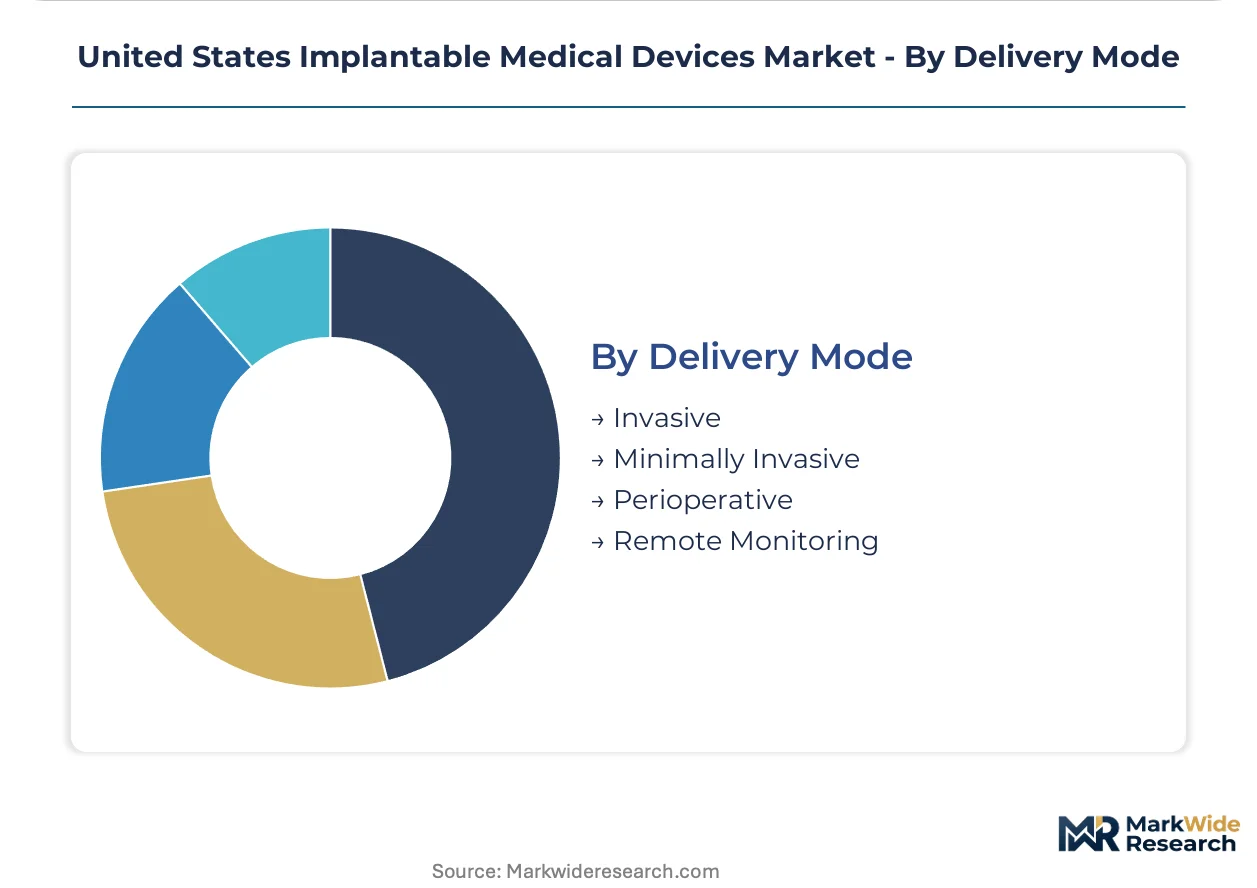
Delivery Mode:
Delivery mode selection reflects tension between invasiveness, recovery trajectory, and reimbursement coding precision.
- Minimally Invasive:Catheter-lab and percutaneous approaches are compressing length-of-stay metrics. Boston Scientific and Abbott catheter-lab relationships anchor cardiac rhythm franchise placement through procedure workflow integration.
- Invasive:Open surgical approaches retain dominance for multi-level spinal fusion and complex joint reconstruction. PEEK-OPTIMA polymer adoption in lumbar interbody fusion is absorbing revision costs via improved radiolucency.
- Perioperative:Device programming and parameter optimization during surgical episodes are standardizing across implant categories.
- Remote Monitoring:Wireless telemetry protocols are experiencing FDA timeline compression as CDRH intensifies authentication architecture requirements.
Procedure volume concentrates in invasive and minimally invasive modes; remote monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Medicare-dependent states with high specialist density and favorable reimbursement differentials. Florida, Texas, and California attract disproportionate volumes of device-intensive orthopedic and cardiac procedures. Regional procurement patterns diverge sharply between hospital-integrated systems and specialist-owned surgical centers.
Florida
Miami-Dade and Broward counties host the densest concentration of Medicare-certified ambulatory surgery centers nationwide. CMS reimbursement rate advantages draw orthopedic and cardiac device-intensive procedures from across the Southeast. Specialist-owned facilities in these metros bypass hospital purchasing committees through direct manufacturer relationships.
Texas
State-level Medicaid expansion for movement disorder therapies enlarges addressable populations for deep brain stimulation systems. Houston and Dallas-Fort Worth medical centers anchor cardiac rhythm management device procurement through catheter-lab workflow integration. Texas Health and Human Services Commission coverage determinations shape neurostimulator adoption timelines.
California
Academic medical centers in Los Angeles and San Francisco accelerate PEEK-OPTIMA polymer adoption for multi-level spinal fusion constructs. FDA's Center for Devices and Radiological Health maintains headquarters in Silver Spring with regional enforcement coordination through California district offices. Stanford and UCSF health systems prioritize bioelectric closed-loop systems with adaptive feedback algorithms.
Illinois
Chicago metropolitan health systems fragment cardiac device contracting from orthopedic procurement through service-line autonomy. Northwestern Medicine and Advocate Aurora negotiate rhythm management contracts independently from consolidated spend pools. Illinois Department of Healthcare and Family Services reimbursement policies influence hospital value analysis committee decisions.
New York
Greater New York hospital networks retain integrated purchasing for high-value cardiac implants while ceding orthopedic device selection to department-level autonomy. New York-Presbyterian and Mount Sinai health systems concentrate neurostimulator volumes for chronic pain management. State Department of Health certificate-of-need regulations constrain ambulatory surgery center expansion upstate.
United States Implantable Medical Devices Market Key Industry Players
Portfolio diversification dominates the current landscape as established players absorb adjacent therapeutic categories. The vendor base concentrates around three integrated conglomerates with full cardiac-to-orthopedic coverage, supplemented by mid-scale specialists with single-segment depth. Two strategic archetypes prevail: diversified health technology conglomerates with neuromodulation pipelines, and orthopedic-focused fabricators with polymer-to-metal conversion capabilities. Competitive moves center on FDA premarket approval pathway navigation and direct-to-ambulatory distribution channel development.
Among diversified health technology conglomerates, Medtronic plc, Boston Scientific Corporation, and Abbott Laboratories anchor the active implantable systems tier. These firms exemplify integrated neuromodulation and cardiac rhythm franchise positioning through catheter-lab relationship depth. Each occupies a distinct archetype within bioelectric closed-loop systems, miniaturized drug-eluting platforms, and rechargeable power management architectures respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Johnson & Johnson |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Edwards Lifesciences Corporation |
| Smith & Nephew plc |
| Globus Medical |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up orthopedic specialists in Florida and Texas are consolidating surgical center networks while enforcing procurement discipline that compresses implant price points and accelerates polymer-to-metal conversion timelines.
Pricing Analysis
Volume concentrates in cardiac rhythm management where procedure expansion offsets ASP erosion, while margins concentrate in bioelectric neuromodulation where closed-loop algorithms command premium placement. Three-tier pricing structure across premium rechargeable systems, standard fixed-output devices, and economy bare-metal platforms separates procurement tiers. Pricing pressure stems from platinum-iridium electrode cost volatility pressuring neurostimulation array margins. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement rate dependencies; academic medical centers show lowest sensitivity where clinical outcomes data dominates value analysis.
Supply Chain Analysis
Domestic-content mandates under FDA's intensified cybersecurity documentation requirements are reshaping sourcing toward US-based hermetic housing fabricators and domestic telemetry component suppliers. Manufacturing concentrates in the United States, Switzerland, and Ireland for precision electrode fabrication and polymer formulation. Supply chains draw from South African platinum group metals, German precision machining equipment, and Japanese battery cell technology. Single-source vulnerability concentrates in platinum-iridium alloy supply for pacing leads. Distribution runs through specialist-owned surgical centers in Medicare-advantageous states alongside traditional hospital value analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States implantable medical devices market sits in a materials-transition phase as polyetheretherketone displaces titanium alloys across spinal and orthopedic portfolios, compressing legacy metal supply chains while opening premium positioning for radiolucent polymer constructs.
For Market Incumbents: Deploy catheter-lab workflow integration as the defensive anchor against specialist-owned surgical center bypass threats. Deepen backward integration into PEEK-OPTIMA polymer formulation to capture margin from material conversion programs. Fortify FDA premarket approval pathway expertise as CDRH cybersecurity mandates extend 510(k) timelines for connected pulse generators. For New Entrants and Emerging Players: Direct-to-ambulatory distribution partnerships offer the lowest barrier entry point around hospital purchasing committee fragmentation. Target movement disorder therapy expansion in Texas Medicaid coverage zones as the most penetrable reimbursement environment. Pursue AI-enabled diagnostic integration for predictive maintenance revenue streams in cardiac rhythm management. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale neuromodulation specialists with FDA breakthrough device designation pipelines in California and Massachusetts clusters. Long-term viability hinges on bioelectric closed-loop platform ownership across the next decade. Watch CMS dorsal root ganglion stimulation coverage determinations as the inflection signal for chronic pain addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Investment | CDRH authentication architecture requirements compress 510(k) timelines for Bluetooth-enabled implants. |
| PEEK-OPTIMA Polymer Backward Integration | In-house formulation control captures margin from radiolucent spinal cage conversion programs. |
| Direct-to-Ambulatory Distribution Channel | Bypass of hospital value analysis committees shortens sales cycles in Florida and Texas surgical centers. |
| Reimbursement Strategy Development | CMS coverage determination navigation shapes addressable patient pools for dorsal root ganglion stimulation. |
| Software Companion Development | Embedded AI diagnostics in implantable cardioverter-defibrillators create predictive maintenance revenue streams. |
Research Approach
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, and biomedical engineering directors underwrites the qualitative findings in this study. Primary fieldwork with clinicians, FDA regulatory affairs specialists, and ambulatory surgical center operators combined with secondary validation from FDA 510(k) and PMA filings, CMS reimbursement databases, and hospital procurement records. Bottom-up implant volume modeling and top-down market sizing triangulate through independent verification.
Rate-of-change decomposition across product type, technology platform, end-user setting, and delivery mode segments drives the analytical framework. CAGRs derive from procedure volume trajectories, ASP erosion curves, and reimbursement expansion patterns across the projection horizon. Forecast inputs incorporate Medicare-certified surgical center density maps, state-level Medicaid expansion timelines, and platinum group metal price volatility indices.
Inputs from FDA CDRH guidance documents and CMS national coverage determinations were available through the study window; gaps in real-time proprietary GPO contract pricing introduce uncertainty bands around hospital procurement value analysis assumptions. Forecasts reflect modeled assumptions about reimbursement policy continuity and cybersecurity regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Cranial Clamps Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Neurostimulation Market
Medical Devices
Transport Chairs Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Nurse Call Systems Market