
 Glucose Tolerance Test Market | 2026-2036
Glucose Tolerance Test Market Size, Share, and Industry Trends Forecast 2026-2036
Glucose Tolerance Test Market Analysis
ISO 15189 accreditation is bifurcating the competitive landscape for glucose tolerance testing platforms. Roche Diagnostics leverages its centralized lab automation portfolio to sustain high-throughput contracts with national reference networks. Abbott Laboratories anchors its position through integrated continuous glucose monitoring systems that stream data directly into electronic health records. Siemens Healthineers competes on diagnostic instrument density across multi-site hospital systems.
A glucose tolerance test measures the body's ability to metabolize a standardized glucose load, typically 75 grams of anhydrous dextrose dissolved in water, by serially measuring plasma glucose concentration at fasting, one-hour, and two-hour intervals. The procedure serves primarily to diagnose diabetes mellitus, gestational diabetes, and impaired glucose tolerance in clinical and research settings. Oral glucose test products dominate volume due to established clinical guidelines, while continuous glucose monitoring represents the fastest-expanding segment as ambulatory patient management protocols replace episodic lab visits. Home testing kits are capturing margin pools through direct-to-consumer subscription models that bypass traditional diagnostics labs.
FDA pre-market notification requirements under 21 CFR 862 shape product development timelines for new glucose tolerance test devices, while Clinical Laboratory Improvement Amendments (CLIA) standards govern permissible testing sites and personnel qualifications. The Centers for Medicare & Medicaid Services reimbursement codes directly determine which delivery modes achieve viable economics at scale. Stakeholders must monitor evolving FDA guidance on interoperable glucose data standards to anticipate which platform architectures will secure preferential coverage decisions.
Market Dynamics
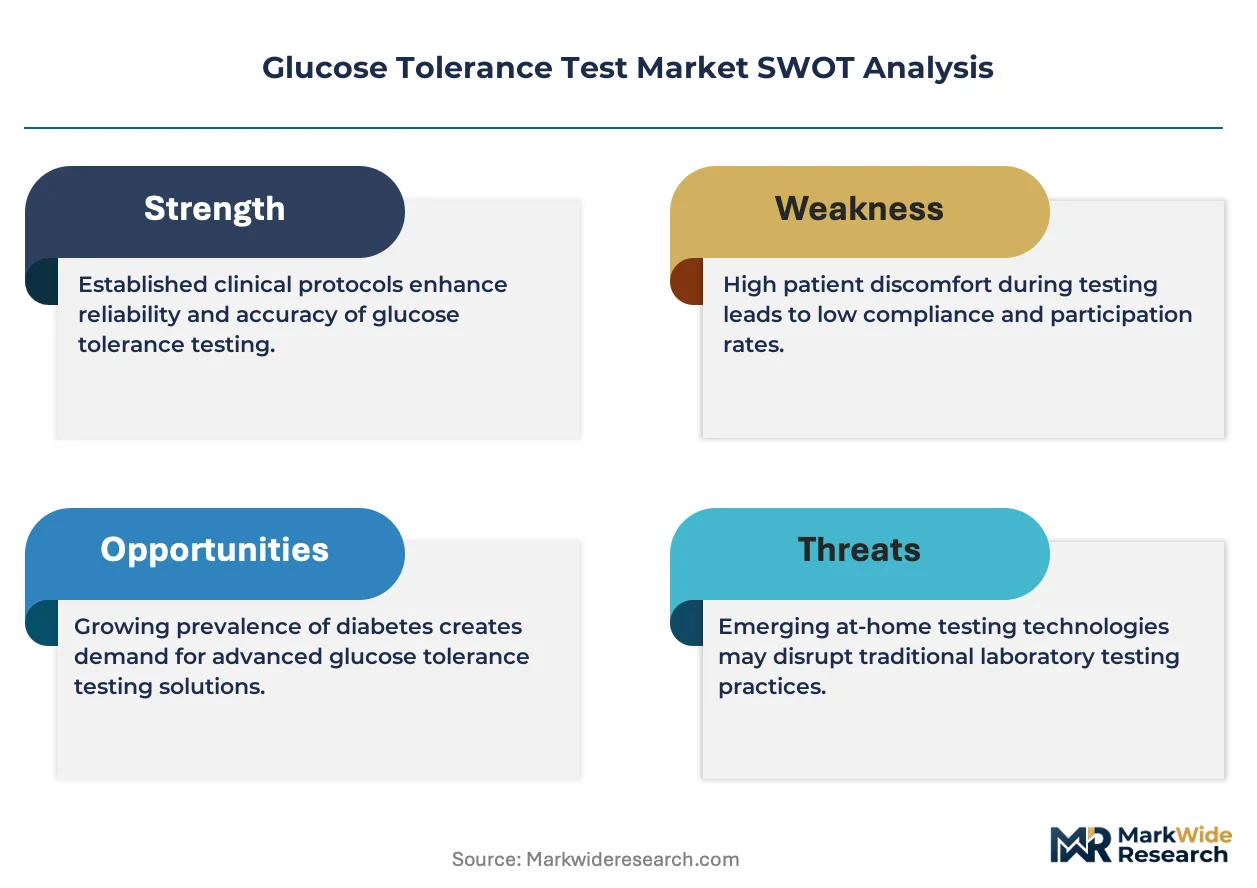
Continuous glucose monitoring protocols are displacing episodic laboratory testing as the dominant diagnostic paradigm, compressing revenue cycles for centralized reference labs while creating captive data streams for integrated health systems.
Growth Catalysts
- CLIA-waived point-of-care expansion:The Clinical Laboratory Improvement Amendments permit non-laboratory personnel to perform waived glucose tolerance tests, extending testing access to retail clinics and ambulatory surgical centers.
- Gestational diabetes screening mandates:National obstetric guidelines in the United States require universal glucose tolerance screening for pregnant patients, institutionalizing recurring demand across maternal health networks.
- Interoperable data standards:The 21st Century Cures Act mandates EHR integration for diagnostic devices, rewarding platforms that stream glucose data directly into patient records without manual transcription.
Market Restraints
- Reagent supply concentration:High-purity anhydrous dextrose production clusters with three specialty chemical suppliers in Germany and Switzerland, exposing test manufacturers to input volatility.
- FDA pre-market notification tightening:The 510(k) pathway for novel glucose tolerance devices now requires predicate device equivalence demonstrations that extend development timelines by 12-18 months.
- Continuous glucose monitor substitution:Ambulatory CGM systems eliminate the need for controlled glucose loads in pre-diabetes monitoring, eroding the addressable market for traditional oral tolerance protocols.
Strategic Opportunities
- Direct-to-consumer subscription channels:Home testing kits bypass laboratory networks entirely, capturing margin pools through recurring revenue models that eliminate third-party billing complexity.
- AI-enabled glucose curve interpretation:Machine learning algorithms applied to continuous monitoring data streams enable predictive insulin dosing recommendations that differentiate platform offerings.
- India's diagnostic infrastructure buildout:The country's PLI scheme for medical device manufacturing incentivizes local glucose tolerance test production to serve underserved tier-2 and tier-3 cities.
Industry Challenges
- ISO 15189 accreditation timelines:Laboratory quality management certification requires 18-24 month implementation cycles that delay market entry for new testing platforms.
- Legacy LIS integration complexity:Hospital information systems built on 1990s architectures resist API-based data exchange, forcing expensive middleware development for glucose data interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucose Tolerance Test Market |
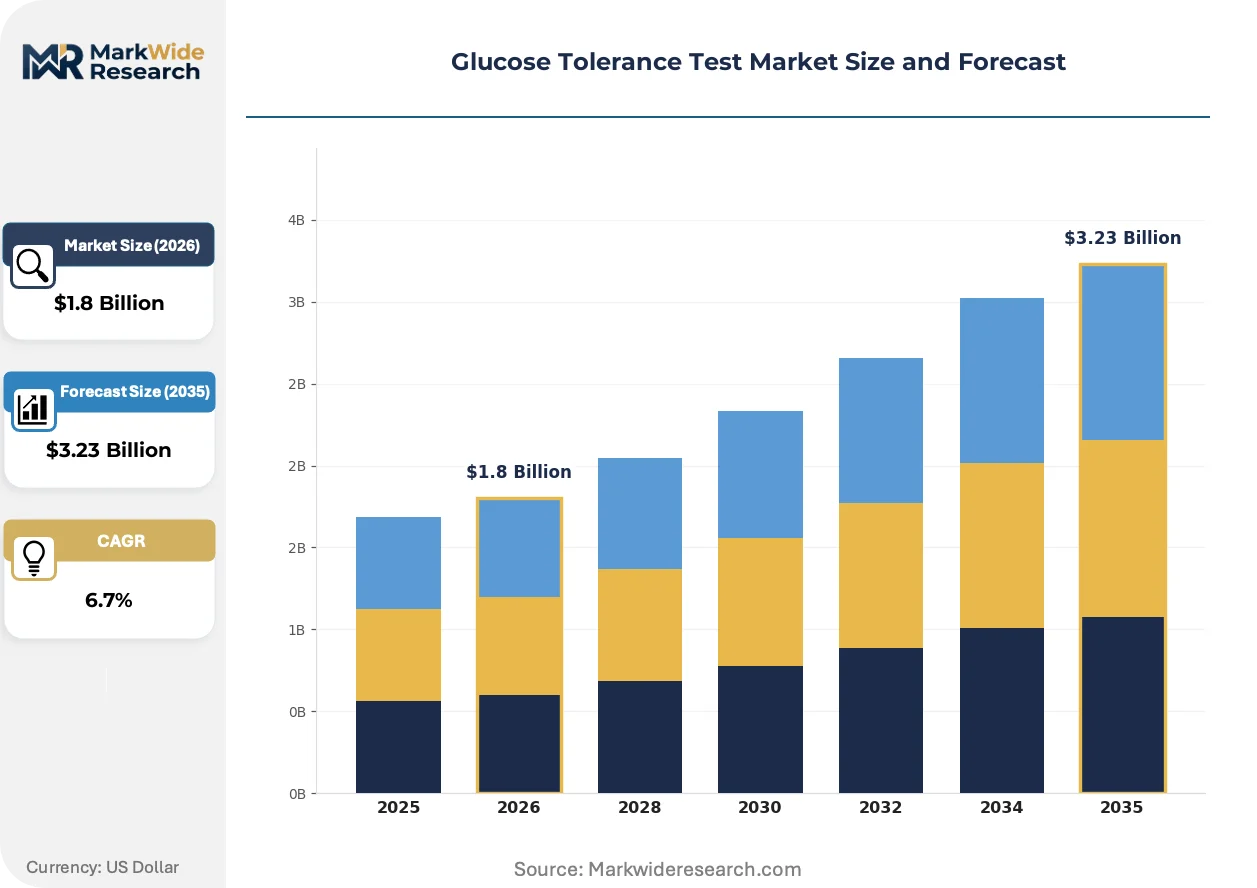
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Glucose Test, Intravenous Glucose Test, Continuous Glucose Monitoring, Self-Monitoring Devices End User: Diagnostics Labs, Hospitals, Physician Offices, Home Care Delivery Mode: Home Testing Kits, Lab Testing, Online Services, Mobile Testing Units Application: Diabetes Screening, Insulin Sensitivity Assessment, Pre-Diabetes Diagnosis, Clinical Research |
| Companies Covered | Medtronic plc, Arkray, Inc., Roche Diagnostics, Siemens Healthineers, LifeScan IP Holdings, LLC, Abbott Laboratories, Ascensia Diabetes Care Holdings AG, Panasonic Corporation, Dexcom, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucose Tolerance Test Market Emerging Trajectories
Non-invasive glucose sensing technologies and algorithmic interpretation tools are compressing the technical moats that protected incumbent diagnostics manufacturers, while regulatory data interoperability mandates are rewriting procurement criteria for hospital systems.
Micro-needle array biosensors are fragmenting the competitive landscape for glucose measurement by eliminating venipuncture requirements entirely. Primary care networks in the Netherlands and Denmark are piloting these devices for population-scale diabetes screening programs. The technology is fragmenting patient volume across retail pharmacy chains, workplace wellness vendors, and direct-to-consumer channels that bypass traditional laboratory infrastructure.
The FDA's 2023 guidance on interoperable glucose data standards mandates standardized API architectures for all new pre-market submissions. Device manufacturers must now engineer cloud-native data pipelines rather than proprietary closed systems. Integrated delivery networks in Texas and California are rewriting RFP specifications to exclude platforms lacking real-time EHR integration.
Hospital procurement committees are unbundling glucose tolerance testing from comprehensive metabolic panel contracts, enabling standalone negotiation for continuous monitoring services. Reference laboratories that previously bundled tests face margin compression as health systems source glucose management separately. This pattern is most visible among Medicare Advantage plans in Florida and Arizona seeking to reduce preventable emergency department visits through ambulatory glucose surveillance.
Glucose Tolerance Test Market Segmentation
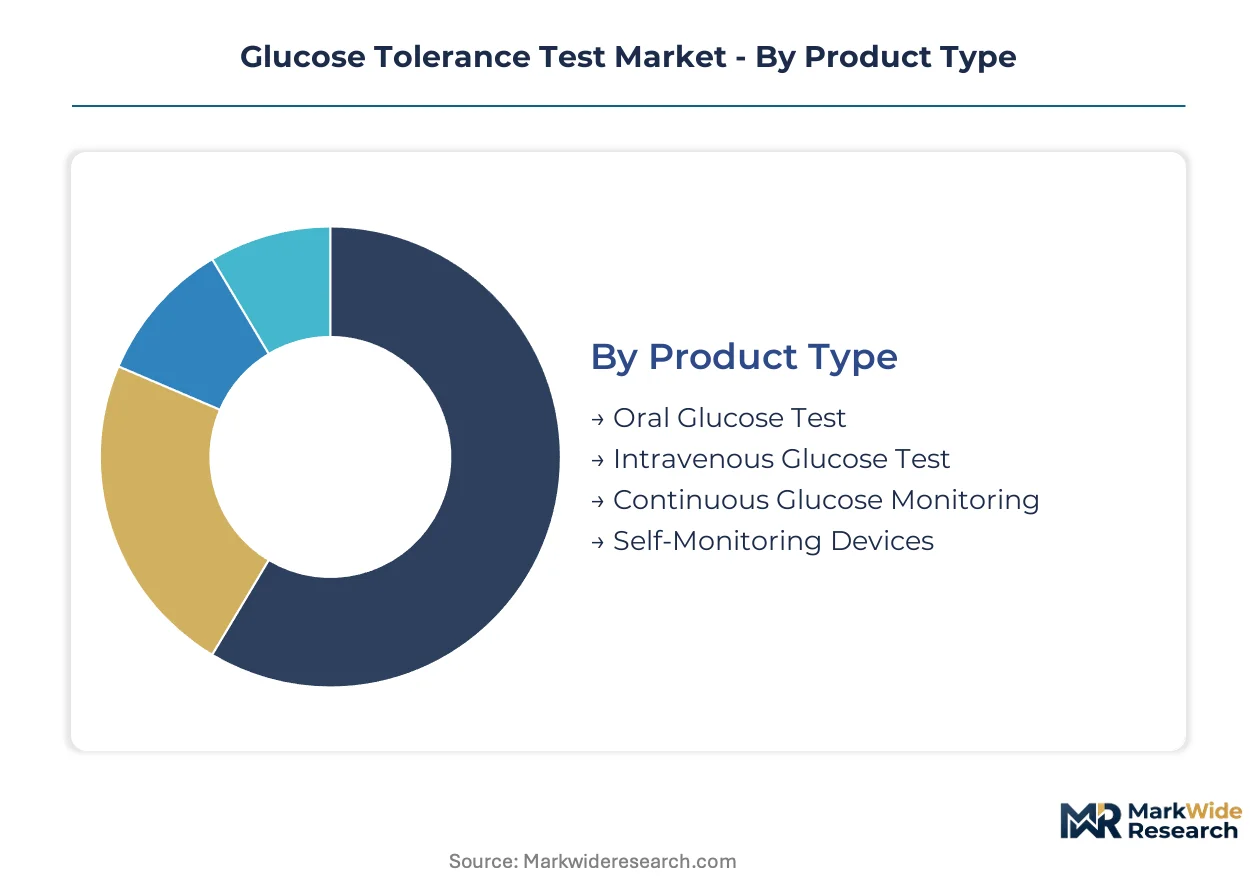
Glucose tolerance test platforms fragment across four distinct category axes. Product architecture determines reimbursement pathways. End-user concentration dictates procurement leverage. Delivery mode selection reshapes margin capture between laboratory networks and direct-to-consumer channels.
Product Type:
Continuous glucose monitoring systems command premium pricing through recurring sensor subscriptions, while oral glucose test reagents compete on high-throughput volume economics.
- Oral Glucose Test:The 75-gram anhydrous dextrose protocol remains the clinical reference standard for diabetes mellitus diagnosis. Demand concentrates in hospital-based reference laboratories serving maternal health networks with mandated gestational diabetes screening protocols.
- Continuous Glucose Monitoring:Interstitial fluid biosensors transmit glucose readings every 1-5 minutes to paired receivers or smartphones. Integrated health systems in Texas and California are rewriting procurement specifications to mandate real-time EHR data streaming without manual transcription.
- Intravenous Glucose Test:Reserved for research settings and patients with gastrointestinal absorption disorders.
- Self-Monitoring Devices:Fingerstick glucometers with test strip consumables dominate home-based diabetes management.
Oral glucose test platforms hold installed capacity across hospital networks. Continuous glucose monitoring is rotating up the share rankings as ambulatory protocols displace episodic laboratory visits.
End User:
Procurement authority varies sharply across settings, with integrated delivery networks consolidating purchasing power while home care channels bypass traditional billing intermediaries entirely.
- Hospitals:Multi-site health systems negotiate comprehensive metabolic panel contracts that historically bundled glucose tolerance testing. Medicare Advantage plans in Florida and Arizona are unbundling continuous monitoring services to reduce preventable emergency department visits.
- Diagnostics Labs:National reference networks process high-volume oral glucose test panels under CLIA-certified protocols. ISO 15189 accreditation timelines of 18-24 months protect incumbent positions against new market entrants.
- Physician Offices:CLIA-waived point-of-care devices extend testing access to primary care networks without laboratory personnel requirements.
- Home Care:Direct-to-consumer subscription models capture full margin pools by eliminating third-party reimbursement complexity.
Diagnostics labs hold installed capacity across commercial reference networks. Home care is rotating up the share rankings through direct-to-consumer channel expansion.
Delivery Mode:
Channel selection determines regulatory burden and reimbursement pathway, with laboratory-based testing governed by CLIA standards and home testing kits navigating FDA 510(k) pre-market notification requirements.
- Lab Testing:Centralized processing under Clinical Laboratory Improvement Amendments standards ensures result traceability for insurance reimbursement. Hospital information systems with 1990s architectures resist API-based data exchange, forcing expensive middleware development.
- Home Testing Kits:Direct-to-consumer glucose tolerance products bypass laboratory networks through subscription revenue models. The FDA's 2023 guidance on interoperable data standards mandates standardized API architectures for all new pre-market submissions.
- Online Services:Telehealth-integrated testing platforms coordinate sample collection and result delivery.
- Mobile Testing Units:Workplace wellness vendors and retail pharmacy chains deploy population-scale screening programs.
Lab testing holds installed capacity across commercial and hospital-affiliated networks. Home testing kits are rotating up the share rankings as direct-to-consumer channels capture margin pools.
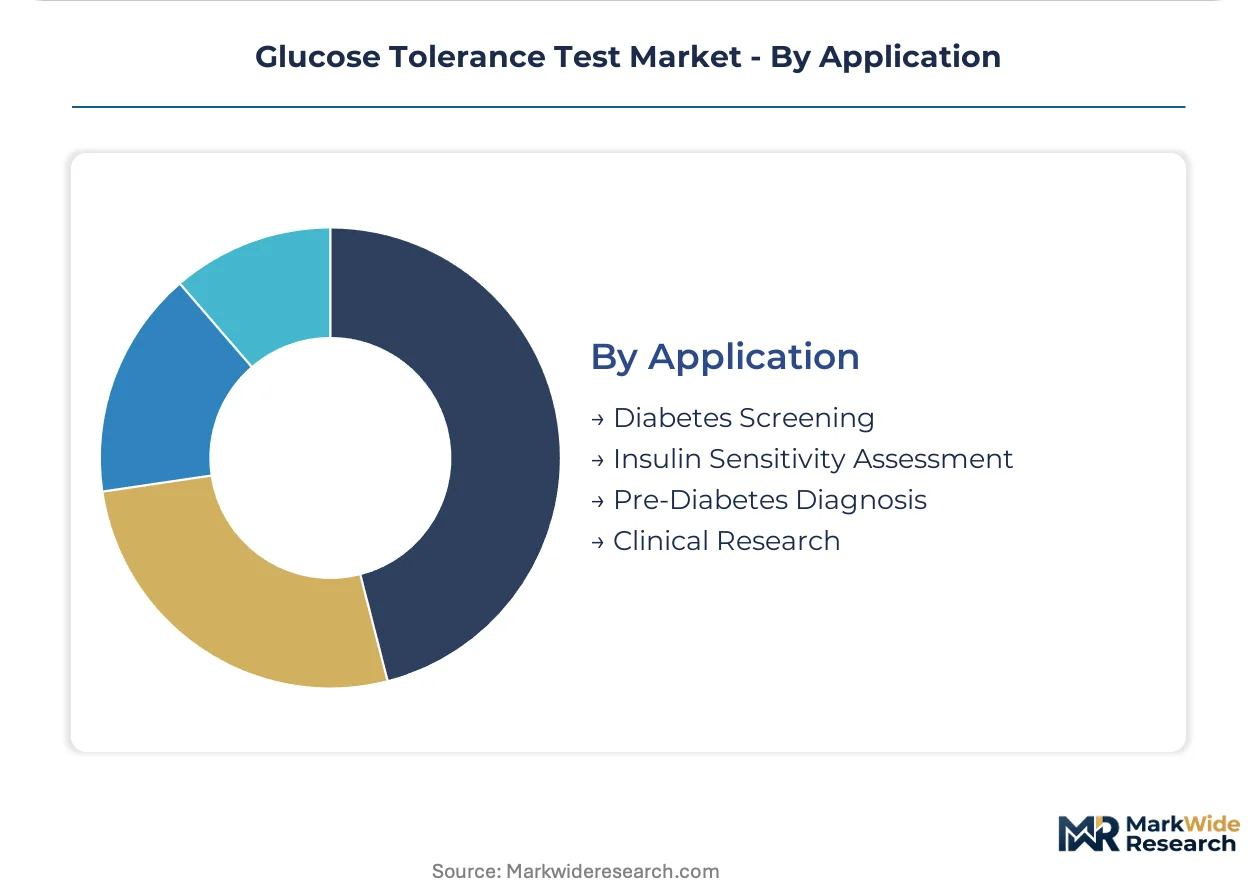
Application:
Clinical indication determines test frequency, reimbursement code eligibility, and competitive intensity between episodic laboratory protocols and continuous ambulatory monitoring.
- Diabetes Screening:Population-scale testing programs identify undiagnosed diabetes mellitus through fasting plasma glucose and oral glucose tolerance protocols. The Netherlands and Denmark are piloting micro-needle array biosensors for non-invasive population screening.
- Gestational Diabetes Screening:Universal maternal health mandates in the United States institutionalize recurring demand across obstetric networks. National obstetric guidelines require glucose tolerance testing for all pregnant patients.
- Pre-Diabetes Diagnosis:Impaired glucose tolerance identification drives preventive intervention protocols.
- Clinical Research:Standardized glucose load studies support pharmaceutical development and metabolic research.
Diabetes screening holds installed capacity across hospital and reference laboratory networks. Gestational diabetes screening is rotating up the share rankings as maternal health mandates expand testing volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pre-market notification tightening and CMS reimbursement code revisions are reshaping competitive positioning in the United States. India's PLI scheme for medical device manufacturing accelerates local production capacity buildout.
United States
Integrated health systems with captive laboratory networks concentrate glucose tolerance testing demand in Texas and California. Medicare Advantage plans in Florida and Arizona unbundle continuous monitoring services to reduce preventable emergency department visits. Hospital procurement committees in these states now mandate real-time EHR integration in device specifications.
Germany
High-purity anhydrous dextrose production clusters with specialty chemical suppliers in Germany expose test manufacturers to input volatility. EMA medical device regulations and ISO 15189 accreditation timelines protect incumbent laboratory positions. The Rhine-Ruhr metropolitan region hosts automated diagnostics manufacturing serving national reference networks.
India
CDSCO medical device regulations and the PLI scheme incentivize local glucose tolerance test production for underserved tier-2 and tier-3 cities. Maharashtra and Karnataka states anchor diagnostic infrastructure buildout. Domestic manufacturers in these regions target price-sensitive ambulatory care segments.
Japan
PMDA regulatory frameworks govern glucose monitoring device approvals with stringent clinical evidence requirements. METI industrial policy supports precision biosensor development. The Kanto region around Tokyo concentrates hospital system procurement authority for metabolic diagnostics.
Netherlands
Micro-needle array biosensor pilots for population-scale diabetes screening operate under Health Council of the Netherlands guidelines. ANSM/CNIL data protection requirements shape interoperable glucose data architectures. The Randstad urban corridor hosts primary care networks testing non-invasive screening protocols.
Glucose Tolerance Test Market Vendor Landscape
Player mix skews toward diversified medical technology conglomerates with centralized laboratory automation portfolios. Market structure concentrates around three strategic archetypes: integrated continuous glucose monitoring system providers, high-throughput diagnostics instrument manufacturers, and point-of-care device specialists. Competitive moves emphasize ISO 15189 accreditation maintenance and CLIA-waived product portfolio expansion.
Within the diversified conglomerate tier, Roche Diagnostics and Siemens Healthineers exemplify scale-driven positions anchored in automated laboratory infrastructure. Abbott Laboratories and Dexcom occupy positions representing continuous monitoring specialization. Medtronic plc sits within the integrated health system contracting archetype.
| Leading Market Players |
|---|
| Medtronic plc |
| Arkray, Inc. |
| Roche Diagnostics |
| Siemens Healthineers |
| LifeScan IP Holdings, LLC |
| Abbott Laboratories |
| Ascensia Diabetes Care Holdings AG |
| Panasonic Corporation |
| Dexcom, Inc. |
| Others |
Supply Flow & Price Mechanics
ISO 15189 accreditation gates both supplier qualification and price differentiation simultaneously, as laboratories without certification cannot access national reference network contracts while certified incumbents command premium positioning through audit-ready quality management systems. This regulatory threshold compresses margin pools for uncertified manufacturers while rewarding automated platform providers with multi-year hospital system agreements.
Pricing Analysis
Certification level (ISO 15189/FDA-grade) creates the primary spread between premium reference laboratory contracts and economy point-of-care segments. Pricing stratifies across premium, standard, and economy tiers based on automation density and CLIA-waiver status. Pricing pressure stems from continuous glucose monitor substitution eroding oral glucose test volumes. Hospital procurement committees exhibit lowest price sensitivity due to bundled metabolic panel contracting, while retail clinic channels demonstrate highest sensitivity to per-test economics.
Supply Chain Analysis
Germany and Switzerland anchor high-purity anhydrous dextrose production for standardized glucose loads. Reagent manufacturing draws from specialty chemical precursors, biosensor substrates, and precision micro-needle arrays. Single-source vulnerability concentrates around three European suppliers for pharmaceutical-grade dextrose. Distribution runs through national reference laboratory networks, direct-to-consumer subscription channels, and integrated health system captive laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glucose tolerance test market is recovering from episodic laboratory volume compression as ambulatory monitoring protocols institutionalize recurring sensor replacement cycles. This cyclical recovery is anchored in Medicare Advantage plan expansion of continuous glucose surveillance benefits.
For Market Incumbents: Compound ISO 15189 accreditation maintenance with CLIA-waived portfolio expansion to defend reference laboratory contracts against point-of-care displacement. Invest in backward integration into biosensor substrate manufacturing to reduce German-Swiss dextrose supplier dependency. Prioritize API-native data pipelines to meet Texas and California hospital EHR integration mandates.
For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 city diagnostic infrastructure buildout under PLI scheme incentives, where price-sensitive ambulatory care segments remain underserved by automated laboratory networks. Target direct-to-consumer subscription channels with AI-enabled glucose curve interpretation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous glucose monitoring sensor manufacturing as micro-needle array production scales. Long-term viability favors platform providers with captive data streams and recurring revenue models over transactional reagent suppliers. Monitor FDA interoperable glucose data standard enforcement as the inflection signal for procurement specification rewrites.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15189 Accreditation Investment | Unlocks national reference laboratory contracts with 18-24 month implementation cycles. |
| CLIA-Waived Device Expansion | Extends testing access to retail clinics without laboratory personnel requirements. |
| API-Native EHR Integration | Satisfies Texas and California hospital procurement mandates for real-time data streaming. |
| Direct-to-Consumer Subscription Launch | Captures full margin pools by eliminating third-party reimbursement complexity. |
| India PLI Manufacturing Localization | Serves price-sensitive tier-2 and tier-3 diagnostic infrastructure buildout. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS reimbursement code databases, hospital procurement contracts, and CDSCO medical device registrations. Primary interviews engaged laboratory directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and continuous glucose monitoring platform engineers. Bottom-up demand modeling triangulated against top-down expenditure tracking across integrated health systems.
Segmentation dimensions modeled include product architecture (oral glucose test, continuous glucose monitoring, intravenous protocol, self-monitoring device), end-user concentration (hospital, diagnostics lab, physician office, home care), delivery mode (lab testing, home testing kit, online service, mobile unit), and clinical application (diabetes screening, gestational diabetes, pre-diabetes diagnosis, clinical research). CAGRs derived from installed base rotation analysis and ambulatory protocol adoption curves. Forecast inputs incorporated CLIA-waiver expansion rates and EHR interoperability mandate compliance timelines.
Decision-makers should treat outputs as directional under stable FDA pre-market notification timelines and CMS reimbursement stability; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in continuous glucose monitor substitution rates and interoperable data standard enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Cancer Tissue Diagnostics Market