
 Tracheostomy Tubes Market | 2026-2036
Tracheostomy Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Tracheostomy Tubes Market Intelligence
The ISO 13485 quality management standard is unwinding the traditional competitive landscape by setting a high bar for market entry. Medtronic leverages its extensive distribution network to maintain a significant presence in hospital settings. Teleflex specializes in innovative airway management solutions, including specialized tracheostomy tubes. Smiths Group competes on the basis of its broad portfolio of critical care devices.
A tracheostomy tube is a curved hollow tube, often made from polyvinyl chloride or silicone, inserted through a stoma into the trachea. Its primary function is to establish and maintain a patent airway for patients requiring long-term ventilation or airway support. Cuffed tubes dominate hospital usage for providing a closed circuit for mechanical ventilation. The market is also seeing a shift towards specialized tubes for the home care segment, where patient comfort and ease of use are paramount.
Regulatory oversight from bodies like the US FDA and China's NMPA dictates stringent requirements for device approval and post-market surveillance. The EU's Medical Device Regulation (MDR) further elevates demands for clinical evidence and supply chain transparency. Stakeholder success will depend on navigating these complex compliance pathways while innovating materials for improved patient outcomes and infection control.
Market Dynamics
The central tension in the tracheostomy tube market is the conflict between the rising demand for patient-centric devices for home care and the escalating stringency of regulatory frameworks like the EU MDR, which increases development costs and timelines.
Growth Catalysts
- Reimbursement Frameworks:Established reimbursement codes for tracheostomy procedures and supplies in markets like the United States and Germany provide a stable financial foundation for hospital and home care provider purchasing.
- Material Science Advancement:The development of softer, more biocompatible silicone and polyurethane materials reduces tracheal irritation and the risk of stenosis, encouraging adoption for long-term patient use.
- Home Care Expansion:A demographic shift towards managing chronically ill patients outside of acute hospital settings directly stimulates demand for tubes designed for patient comfort and ease of use by non-specialist caregivers.
Market Restraints
- Risk of Complications:The inherent clinical risks associated with tracheostomy, including infection, bleeding, and tube displacement, act as a structural barrier and heighten the need for skilled clinical management.
- Stringent Regulatory Hurdles:The high cost and extensive data requirements for obtaining and maintaining approvals from bodies like the US FDA and for CE marking under the EU MDR limit market entry for new participants.
- Substitution by Non-Invasive Ventilation:Advances in non-invasive ventilation (NIV) technologies, such as CPAP and BiPAP masks, present a clinical alternative for some patients, potentially reducing the addressable population for tracheostomy.
Strategic Opportunities
- Integrated Sensor Technology:Incorporating micro-sensors into tubes to monitor cuff pressure, temperature, or CO2 levels offers a significant value-add for critical care settings and remote patient monitoring.
- Pediatric and Neonatal Niches:Developing anatomically correct and size-specific tubes for pediatric and neonatal patients represents a specialized, high-value market segment with distinct clinical needs.
- Emerging Market Healthcare Infrastructure:As countries in Southeast Asia and Latin America invest in upgrading their critical care and hospital capabilities, demand for essential airway management devices is set to increase.
Industry Challenges
- Caregiver Training Gap:The successful transition of patients to home care is often hampered by a shortage of family members or home health aides adequately trained to manage tracheostomy site care and emergency procedures.
- Compliance Documentation Burden:Manufacturers face a significant operational challenge in generating and maintaining the vast technical files and clinical evidence reports now required by regulators, particularly the EU MDR.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tracheostomy Tubes Market |
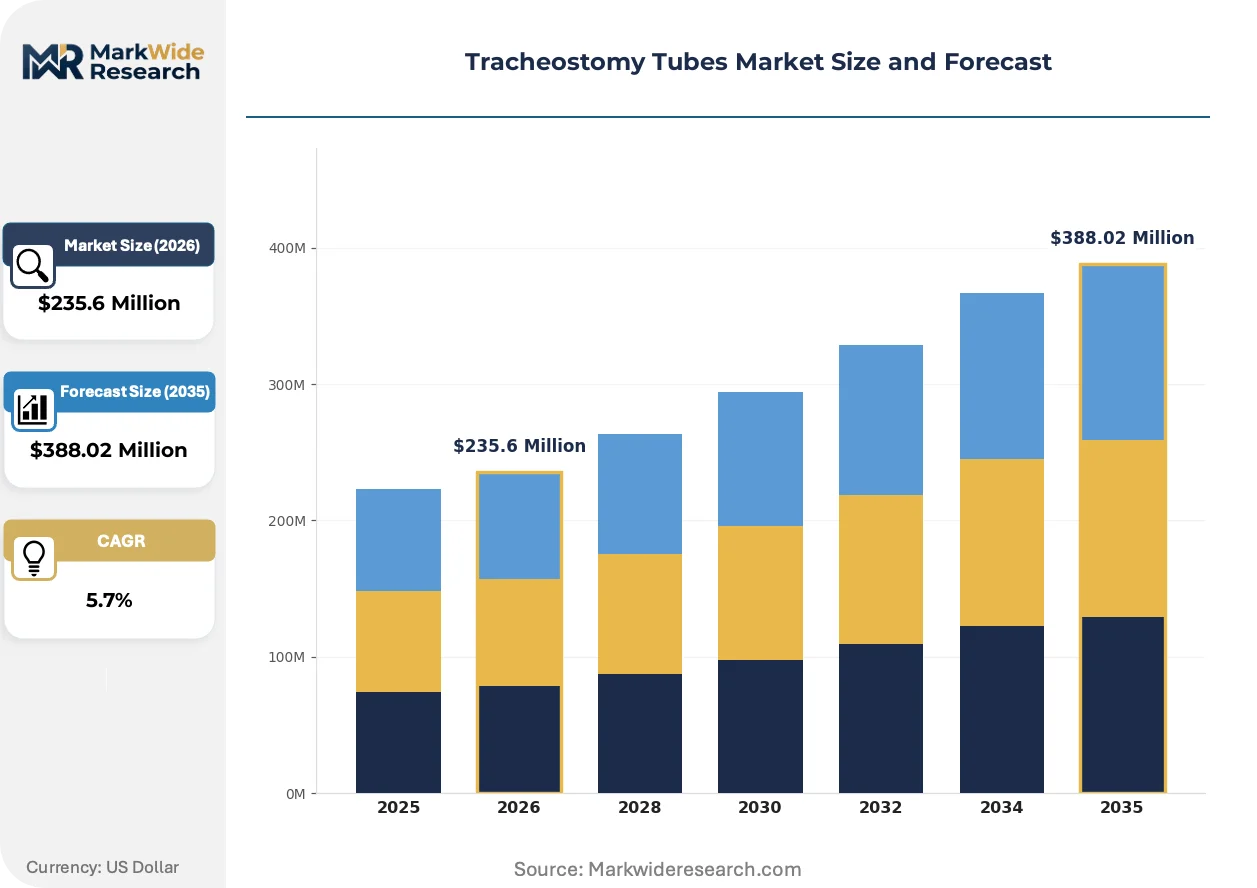
| Market Size in 2026 | $235.6 Million |
| Market Size in 2035 | $388.02 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cuffed, Uncuffed, Fenestrated, Non-Fenestrated, Adjustable Flange Material: Polyvinyl Chloride, Silicone, Polyurethane, Metal, Rubber Application: Airway Management, Mechanical Ventilation, Pulmonary Hygiene, Emergency Care, Neonatal Care End User: Hospitals, Ambulatory Surgical Centers, Long-Term Care Facilities, Home Care |
| Companies Covered | Medtronic, Teleflex, Smiths Group, TRACOE Medical GmbH, ConvaTec Group, Cook Group, Boston Medical, Fisher & Paykel Healthcare, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tracheostomy Tubes Market Strategic Shifts & Innovations
Innovation in the tracheostomy tube market is driven by the dual needs of enhancing clinical safety in acute care and improving patient quality of life in long-term settings. This is leading to significant advancements in material science and integrated device functionality.
Antimicrobial coatings, often using silver ions or other agents, are a key product evolution designed to reduce the risk of biofilm formation and ventilator-associated pneumonia. Adoption is accelerating in intensive care units where infection control is a primary performance metric. This focus on surface technology is miniaturizing the risk of microbial colonization on the device itself, improving patient safety during extended use.
The European Union's Medical Device Regulation (MDR) has become a dominant force shaping global manufacturing standards. It imposes stricter requirements for clinical evaluation, post-market surveillance, and supply chain transparency than its predecessor, the MDD. Consequently, manufacturers targeting the EU market must re-certify their entire tracheostomy tube portfolio, with specialized and cuffed tubes facing the most intense scrutiny.
Purchasing decisions within hospital systems are evolving from a focus on lowest unit cost to a total value assessment. This model considers factors like reduced complication rates, shorter ICU stays, and improved patient comfort linked to specific tube designs or materials. This shift is most visible in large healthcare networks across North America, where value-based purchasing initiatives are influencing procurement criteria for critical care devices.
Tracheostomy Tubes Market Segmentation
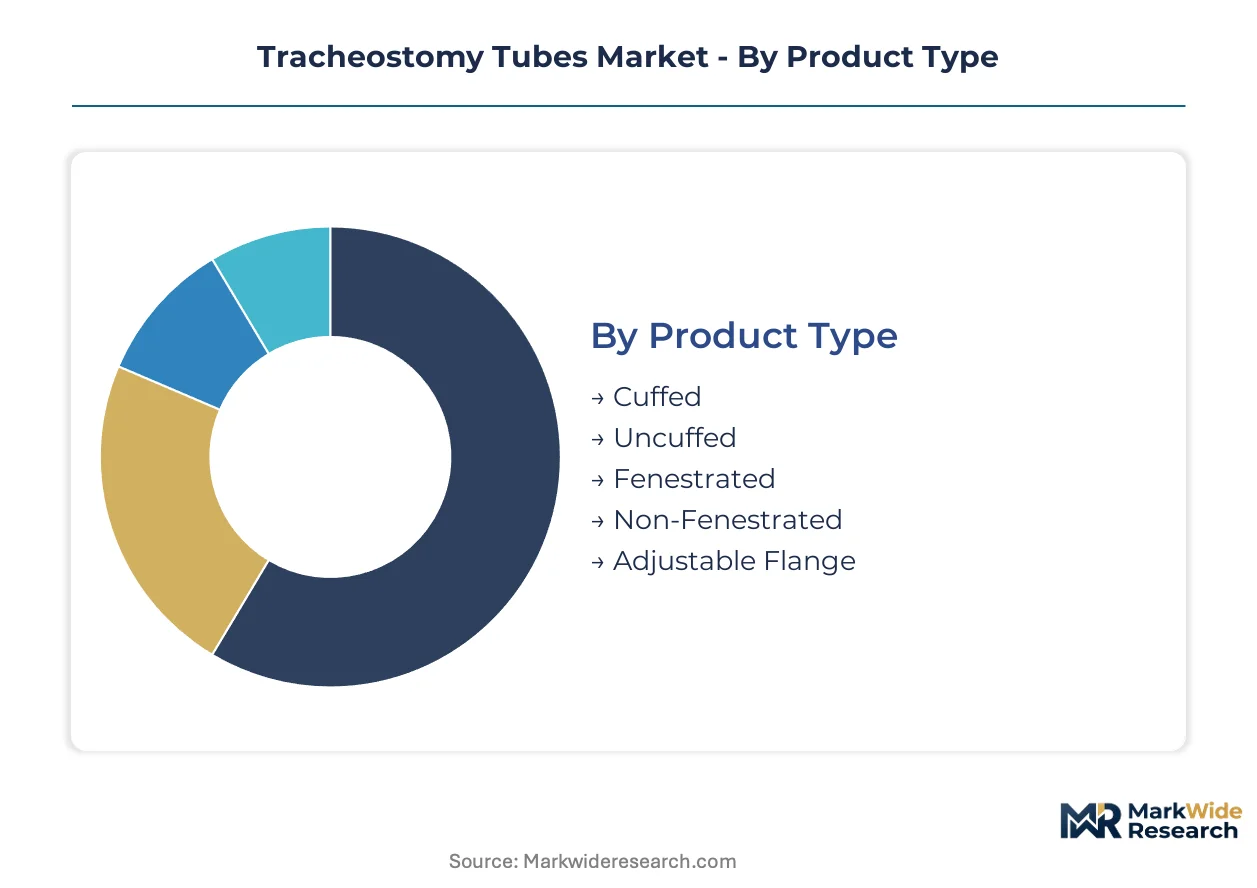
The tracheostomy tubes market segmentation provides a granular view of product evolution and end-user demands across diverse clinical settings. Understanding these distinct segments helps manufacturers tailor innovations and distribution strategies effectively. Each segment reflects specific patient needs and operational requirements within the healthcare ecosystem.
Product Type:
Margin pools within the product type category often concentrate in specialized designs offering enhanced patient safety or comfort, particularly for long-term use. Manufacturers focus on material advancements and integrated features to command higher pricing.
- Cuffed:These tubes feature an inflatable balloon that seals the trachea, preventing air leakage during mechanical ventilation and aspiration. Demand concentrates in hospital intensive care units, driven by the critical need for precise airway control.
- Uncuffed:Uncuffed tubes lack an inflatable cuff, allowing for air passage around the tube and vocalization, making them suitable for patients not requiring mechanical ventilation. Demand is high in long-term care facilities, supporting patient comfort and speech rehabilitation.
- Fenestrated:Fenestrated tubes include small holes in the outer cannula to allow airflow through the vocal cords, aiding speech.
- Non-Fenestrated:These tubes lack fenestrations, providing a continuous airway for patients who do not require speech assistance.
- Adjustable Flange:Adjustable flange tubes allow for customization of the tube length, optimizing fit for individual patient anatomy.
The dominant share belongs to Cuffed, while Uncuffed represents the fastest-growing trajectory.
Material:
The choice of material directly impacts the biocompatibility, flexibility, and longevity of tracheostomy tubes, influencing their suitability for various clinical applications. Different materials offer distinct advantages for patient comfort and infection control.
- Polyvinyl Chloride:PVC tubes are widely used due to their cost-effectiveness and ease of manufacturing, providing a standard solution for many short-term applications. Demand remains consistent in general hospital wards for routine procedures.
- Silicone:Silicone tubes offer superior flexibility, biocompatibility, and softness, reducing tracheal irritation and improving patient comfort during extended use. Adoption is increasing in home care settings due to enhanced patient outcomes.
- Polyurethane:Polyurethane materials provide a balance of stiffness and flexibility, offering good kink resistance and smooth insertion.
- Metal:Metal tracheostomy tubes, often made from stainless steel, are durable and reusable, particularly for long-term or permanent tracheostomies.
- Rubber:Rubber tubes are less common now but historically provided a flexible option, though they are being largely replaced by synthetic polymers.
Polyvinyl Chloride tubes maintain a substantial market presence, with Silicone materials gaining share fastest due to their enhanced biocompatibility.
Application:
The application segment delineates the primary medical purposes for which tracheostomy tubes are utilized, reflecting diverse patient populations and clinical needs. Each application demands specific design features and performance characteristics from the device.
- Airway Management:This broad application encompasses establishing and maintaining a patent airway for patients with upper airway obstruction or compromised respiratory function. Demand is fundamental across all acute and chronic care settings.
- Mechanical Ventilation:Tracheostomy tubes provide a secure conduit for delivering mechanical ventilation to patients requiring prolonged respiratory support. This application concentrates in critical care units and long-term acute care hospitals.
- Pulmonary Hygiene:Tubes facilitate the removal of secretions from the lungs, crucial for patients with impaired cough reflexes or excessive mucus production.
- Emergency Care:Rapid placement of tracheostomy tubes can be life-saving in emergency situations where other airway interventions fail.
- Neonatal Care:Specialized, small-sized tubes are critical for managing airways in premature infants and neonates with respiratory distress.
Airway Management constitutes the largest application segment, as Mechanical Ventilation applications are expanding most quickly.
End User:
The end-user segment highlights where tracheostomy tubes are predominantly purchased and utilized, indicating variations in procurement patterns and patient care models. Each setting has distinct requirements regarding product features, training, and support services.
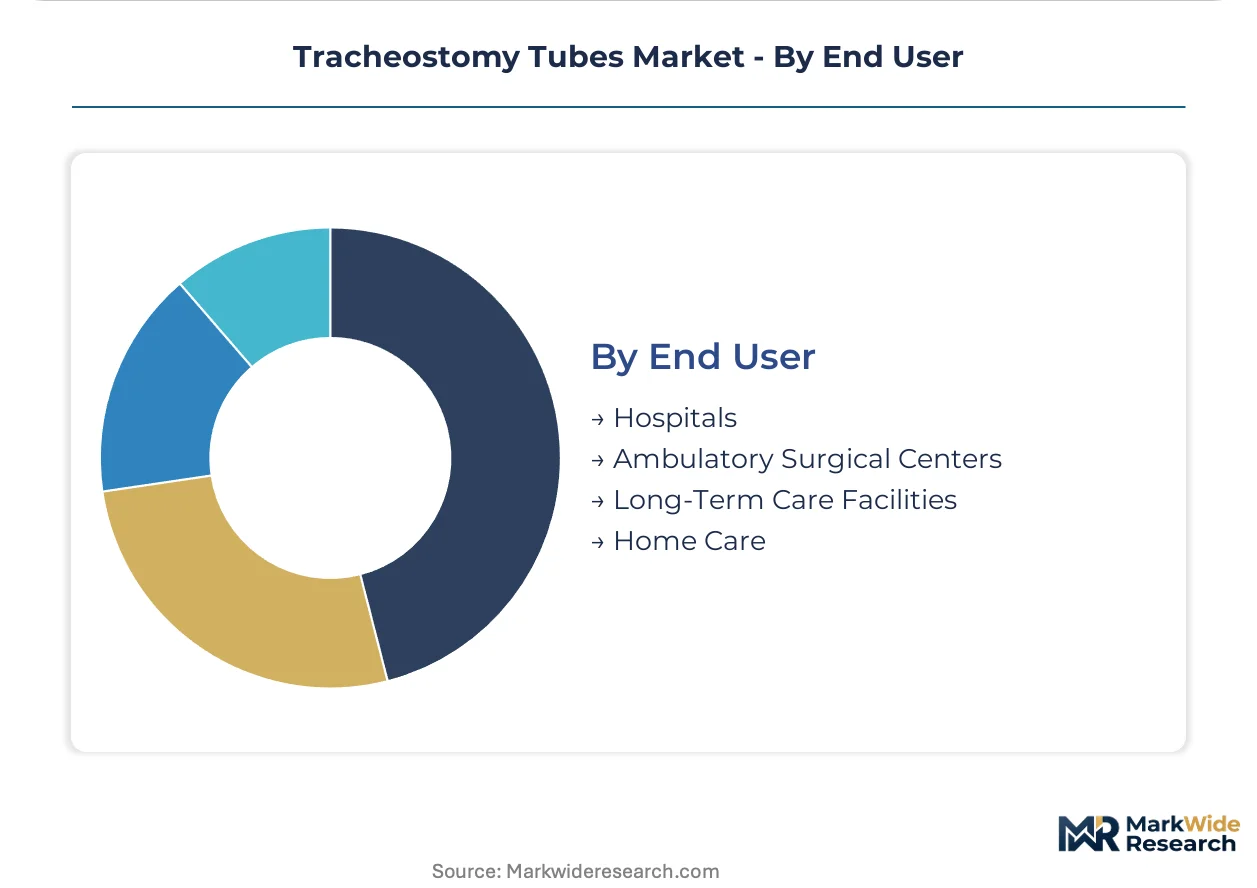
- Hospitals:Hospitals represent the largest end-user segment due to the high volume of acute respiratory conditions, surgical procedures, and critical care needs. Procurement often emphasizes bulk purchasing and established supplier relationships.
- Ambulatory Surgical Centers:These centers perform less complex procedures, including some elective tracheostomies, requiring a more focused range of tube types.
- Long-Term Care Facilities:LTCFs cater to patients requiring prolonged respiratory support and tracheostomy care, prioritizing comfort and ease of maintenance.
- Home Care:The home care segment is expanding rapidly, driven by the shift towards managing chronic conditions outside institutional settings.
Hospitals remain the primary end-user segment, while Home Care is climbing the fastest due to demographic shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Established healthcare infrastructure and robust reimbursement frameworks across key economies underwrite the global tracheostomy tubes market. Demand concentration reflects both chronic disease prevalence and advanced medical capabilities, driving regional growth and product innovation.
United States
A high incidence of chronic respiratory diseases and an aging population drive demand for tracheostomy tubes. The US FDA's stringent approval processes ensure product quality and safety, impacting market entry. Major medical device manufacturing clusters in Massachusetts and California foster continuous innovation in airway management solutions.
Germany
Germany's well-developed healthcare system and an aging demographic contribute to consistent demand for tracheostomy tubes. The EU's Medical Device Regulation (MDR) dictates rigorous compliance for devices sold in the German market. Bavaria and North Rhine-Westphalia serve as significant medical technology hubs, supporting local production and distribution.
China
Expanding critical care capabilities and rising respiratory illness rates across China fuel market expansion for tracheostomy tubes. The NMPA's regulatory oversight guides device approval and post-market surveillance. Industrial parks in the Yangtze River Delta region are increasingly focusing on advanced medical device manufacturing.
Japan
Japan's rapidly aging population and advanced medical technology infrastructure support a stable market for tracheostomy tubes. The PMDA ensures strict regulatory compliance for medical devices. Tokyo and Osaka remain key centers for medical device research, development, and distribution.
India
Improving healthcare access and a large patient pool requiring long-term ventilation are increasing demand for tracheostomy tubes in India. The CDSCO regulates medical device imports and manufacturing standards. Bengaluru's burgeoning medical device startup ecosystem and Chennai's manufacturing facilities are contributing to domestic supply.
Tracheostomy Tubes Market Key Industry Players
Listed leaders compete with private specialists across product innovation, distribution networks, and market access strategies. The market structure includes global diversified medical device companies, specialized airway management firms, and regional niche players. Competitive dynamics often involve strategic acquisitions, portfolio diversification, and geographic expansion to capture new patient segments.
Global diversified medical technology firms like Medtronic and Smiths Group anchor the market through extensive product portfolios and established hospital relationships. Specialized airway management solution providers, such as Teleflex, focus on innovation for specific patient needs, including home care and advanced material science. These companies represent different strategic approaches to market penetration and value creation within the tracheostomy tubes sector.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex |
| Smiths Group |
| TRACOE Medical GmbH |
| ConvaTec Group |
| Cook Group |
| Boston Medical |
| Fisher & Paykel Healthcare |
| ICU Medical |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for critical medical devices like tracheostomy tubes lock in consistent supply access and provide price visibility for both manufacturers and large hospital systems. This contract structure mitigates volatility in raw material costs and ensures stable procurement.
Pricing Analysis
Volume-discount tiering structures characterize pricing for tracheostomy tubes, with significant reductions for bulk hospital purchases. Price differentiation stems from material biocompatibility, such as advanced silicone, and specialized features like integrated sensor technology for critical care. Pricing pressure stems from value-based purchasing initiatives in North America, which prioritize patient outcomes over lowest unit cost. Home care patients seeking specialized, comfortable tubes exhibit lower price sensitivity compared to hospitals focused on high-volume transactional procurement.
Supply Chain Analysis
Port congestion and container availability challenges impact inbound logistics costs for specialized medical components, particularly from Asian manufacturing hubs. Geographic supply concentration for tracheostomy tubes centers on China, Germany, and the United States. Raw material dependencies include medical-grade polyvinyl chloride and advanced silicone polymers, alongside integrated micro-sensors. Regulatory restrictions, such as those from the EU MDR, represent a structural risk, increasing compliance costs for manufacturers. Distribution runs through a dual model of direct sales channels to major hospital networks and specialized medical distributors serving smaller facilities and the expanding home care segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tracheostomy tubes market is at a platform-economics inflection, driven by the emergence of integrated patient monitoring ecosystems that demand interoperability across critical care devices. This shift emphasizes connected health solutions beyond standalone products.
For Market Incumbents:Secure strong distribution networks within established hospital systems to counter market entry by specialized firms. This defensive move insulates against the threat of substitution by non-invasive ventilation technologies and escalating regulatory compliance costs from the EU MDR. Invest in R&D for advanced biocompatible materials and integrated sensor technology to maintain a competitive edge.
For New Entrants and Emerging Players:Anchor in underserved pediatric and neonatal niches, where demand for anatomically correct, size-specific tubes remains high. This specialized segment offers a penetrable entry point due to distinct clinical needs and less intense direct competition. A go-to-market angle focusing on patient comfort and ease of use for non-specialist caregivers will appeal to the rapidly expanding home care segment.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized airway management firms and material science innovators with proven track records in biocompatible polymer development. The market shows long-term viability, driven by chronic respiratory disease prevalence and an aging demographic. A signal to watch for inflection is the widespread adoption rates of integrated sensor technology in critical care settings, indicating a shift towards value-based purchasing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Ensures timely market access and compliance for diverse tracheostomy tube portfolios under the stringent EU MDR. |
| Hospital System Partnership Expansion | Strengthens procurement relationships and secures bulk purchasing contracts with major healthcare networks. |
| Software Companion Development | Integrates device data with remote patient monitoring platforms, enhancing care coordination for home users. |
| Reimbursement Strategy Optimization | Secures favorable coverage codes for advanced tracheostomy tube features in key markets like the United States. |
| Material Science R&D Investment | Develops next-generation biocompatible polymers to reduce tracheal irritation and improve patient comfort. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a robust understanding of the tracheostomy tubes market. Primary interviews included clinicians, hospital purchasing committee members, home health aides, and regulatory affairs specialists. This was complemented by secondary validation from sources like US FDA filings, China NMPA reports, EU MDR guidelines, and specialized medical journals. Bottom-up and top-down triangulation ensured data consistency across all market segments.
The forecasting window spans the projection horizon, utilizing a quantitative analytical framework to model market dynamics. Segmentation dimensions, including product type, material, application, end user, and regional regulatory environments, were meticulously analyzed. Compound annual growth rates were derived through historical trend analysis and future demand projections. Key forecast inputs included global chronic respiratory disease prevalence and aging population demographics.
Material uncertainties — unforeseen technological breakthroughs in non-invasive ventilation or significant shifts in global healthcare policy — sit outside the modeled envelope. Forecasts reflect a specific set of assumptions regarding market evolution and regulatory stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Slip Disc Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Electrophysiology Ablation Market