
 Asia-Pacific Medical Suction Device Market | 2026-2036
Asia-Pacific Medical Suction Device Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Suction Device Market Outlook
Hospital procurement consolidation across Southeast Asia is repositioning vendor relationships toward integrated supply contracts. INTEGRA Biosciences leverages its Swiss manufacturing heritage to anchor premium surgical suction system sales in Australian teaching hospitals. ZOLL Medical Corporation competes through emergency-care channel control, sustaining defibrillator-suction bundled placements across Japanese fire-department medical units. Olympus Corporation dominates endoscopic suction integration, extending its gastrointestinal procedural ecosystem into Korean and Taiwanese outpatient surgery centers.
Medical suction devices generate controlled negative pressure to evacuate fluids, gases, or tissue from body cavities during procedures, typically operating between 80 and 600 mmHg depending on clinical indication. These systems employ vacuum pumps, collection canisters, and bacterial filters to maintain sterile separation between patient effluent and mechanical components. Portable suction units lead volume shipments across the Asia-Pacific region due to ambulance retrofit mandates and rural clinic electrification programs. Electric suction devices command the technology margin pool, while battery-operated suction units represent the fastest-growing configuration category driven by India's home healthcare expansion and disaster-response mobile clinic deployments.
China's NMPA enforces GB standard compliance and clinical trial requirements for Class II medical suction devices, raising barriers for unregistered imports while privileging domestic certificate holders. Japan's PMDA maintains QMS inspection protocols that shape product reliability expectations across Northeast Asian export markets. India's CDSCO import licensing and BIS electrical safety standards filter supplier participation in government hospital tenders. Stakeholders must monitor regulatory divergence between ASEAN harmonization frameworks and national pharmacopeia requirements when configuring regional product portfolios.
Market Dynamics
Hospital procurement consolidation across Southeast Asia is compressing vendor margins and forcing manufacturers toward integrated supply contracts that bundle suction devices with broader surgical equipment portfolios.
Growth Catalysts
- India's tertiary care expansion:Government hospital construction programs in Maharashtra and Tamil Nadu are generating bulk tenders for electric suction systems across 500+ bed facilities.
- Japan's PMDA QMS protocols:Reliability standards shaped by Japanese inspections are elevating product quality expectations that premium manufacturers leverage across Northeast Asian export markets.
- Battery-operated configuration demand:Home healthcare expansion and disaster-response mobile clinic deployments are accelerating portable unit adoption in rural Indian districts and Indonesian archipelago clinics.
Market Restraints
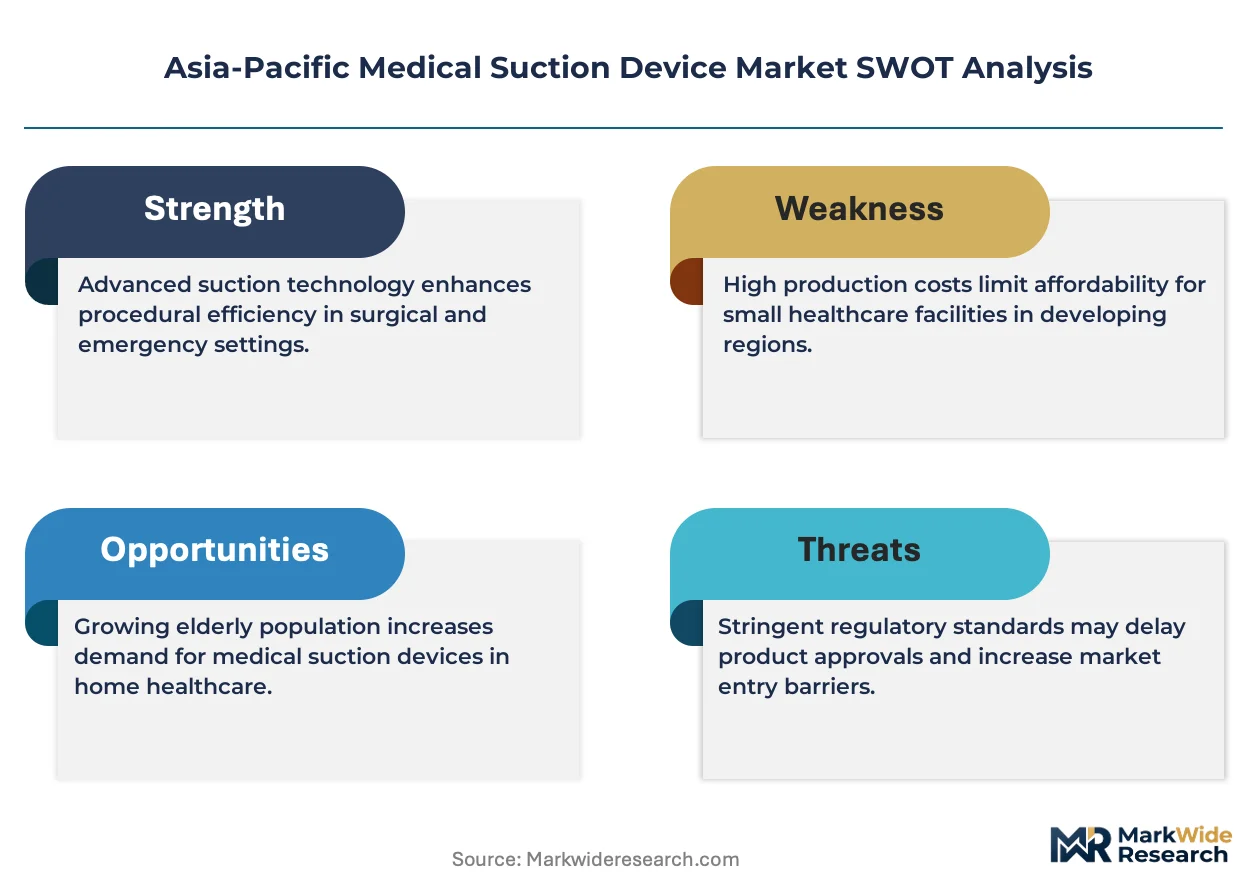
- Copper and rare-earth magnet cost volatility:Vacuum pump motor components face input price swings that squeeze mid-tier manufacturer margins.
- Domestic certificate concentration in China:NMPA Class II registration privileges held by local firms block unregistered import penetration in provincial hospital procurement.
- Manual suction device substitution:Foot-operated aspirators retain cost advantage in ultra-low-resource settings across Myanmar and Papua New Guinea.
Strategic Opportunities
- Vietnam's underpenetrated central region:Da Nang and Hue hospital networks lack standardized suction infrastructure, creating first-mover positioning for compliant suppliers.
- Telemedicine-integrated remote suction monitoring:IoT sensor convergence with negative pressure telemetry enables predictive maintenance contracts in Australian remote healthcare networks.
- Philippines DOH equipment modernization mandate:National health department capital programs prioritize suction device replacement in barangay health stations.
Industry Challenges
- Biomedical technician certification gaps:Malaysia and Indonesia lack accredited training pipelines for suction system preventive maintenance, forcing manufacturer reliance on expensive field service deployments.
- Legacy 220V/110V infrastructure incompatibility:Electrification variance across Pacific Island clinics complicates portable unit power adapter standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Suction Device Market |
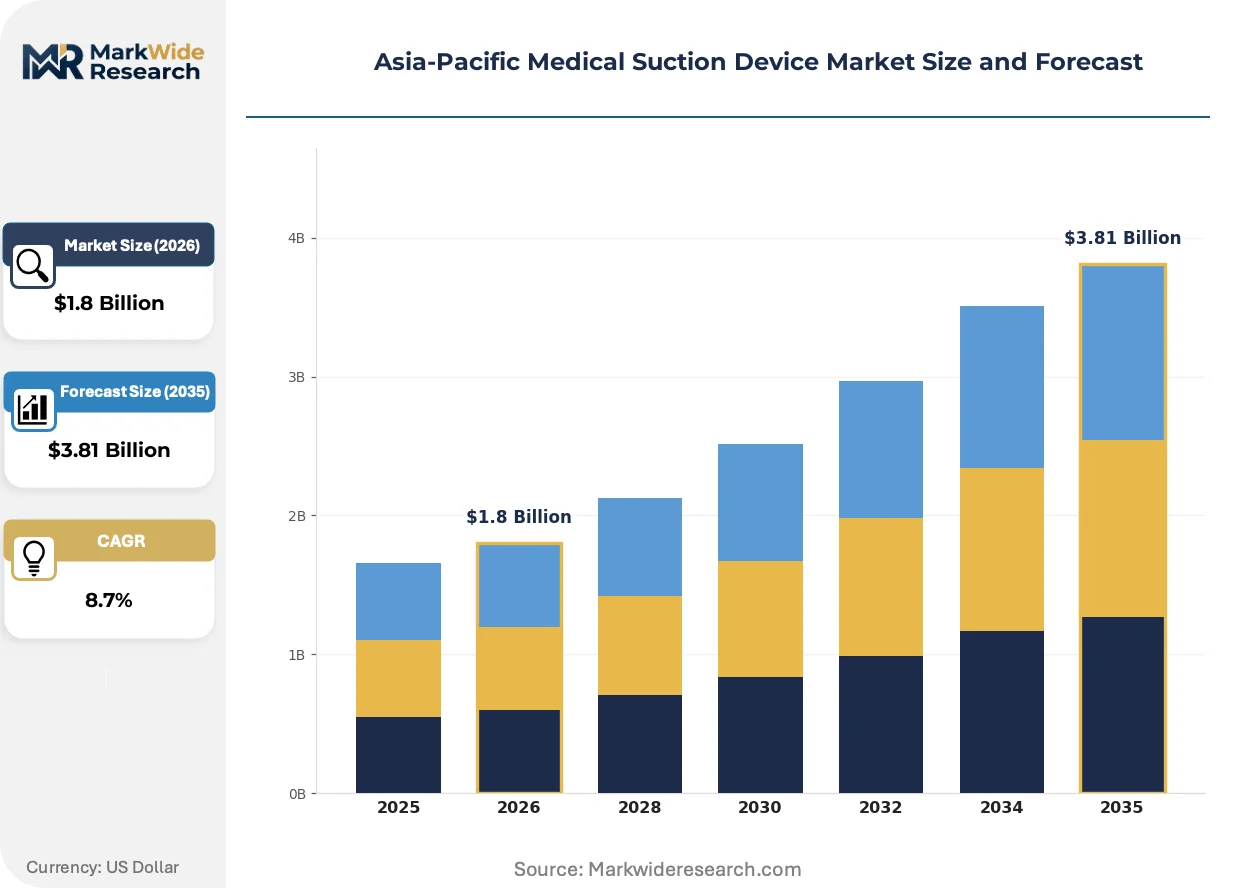
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Suction Units, Wall-Mounted Suction Devices, Surgical Suction Systems, High-Volume Suction Pumps End User: Hospitals, Ambulatory Surgery Centers, Home Healthcare, Dental Clinics Technology: Electric Suction Devices, Manual Suction Equipment, Battery-Operated Suction Units, Pneumatic Suction Systems Application: Respiratory Care, Surgical Procedures, Wound Care, Obstetric Use |
| Companies Covered | INTEGRA Biosciences, ZOLL Medical Corporation, Allied Healthcare Products, Amsino International, DeVilbiss Healthcare, ATMOS MedizinTechnik, Precision Medical, Laerdal Medical, Olympus Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Suction Device Market Strategic Shifts
Suction technology trajectories center on portability enhancement, regulatory compliance automation, and procurement relationship restructuring across Asia-Pacific healthcare systems.
Smart battery management systems with lithium-iron-phosphate chemistry are extending portable suction runtime beyond eight hours in field conditions. Australian Royal Flying Doctor Service and Indonesian disaster medical assistance teams are adopting these units for aeromedical evacuation. This capability is decentralizing emergency suction provision from fixed hospital infrastructure to point-of-injury care across remote Northern Territory and Sumatran highland operations.
China's NMPA updated medical device classification rules are mandating clinical trial documentation for Class II suction devices that previously qualified for predicate approval. Domestic manufacturers in Jiangsu and Zhejiang provinces are absorbing compliance costs through vertical integration of testing laboratories. Foreign suppliers without established China-based certificate holding organizations face 18-24 month registration timelines that freeze market access during regulatory transition periods.
Integrated supply contracting is consolidating vendor relationships in Thai and Vietnamese hospital group purchasing organizations. Single-source agreements spanning suction devices, anesthesia machines, and patient monitors are displacing standalone equipment tenders. This concentration is most visible in Bangkok's Chulalongkorn Hospital network and Ho Chi Minh City's 175 Military Hospital procurement reforms.
Asia-Pacific Medical Suction Device Market Segmentation
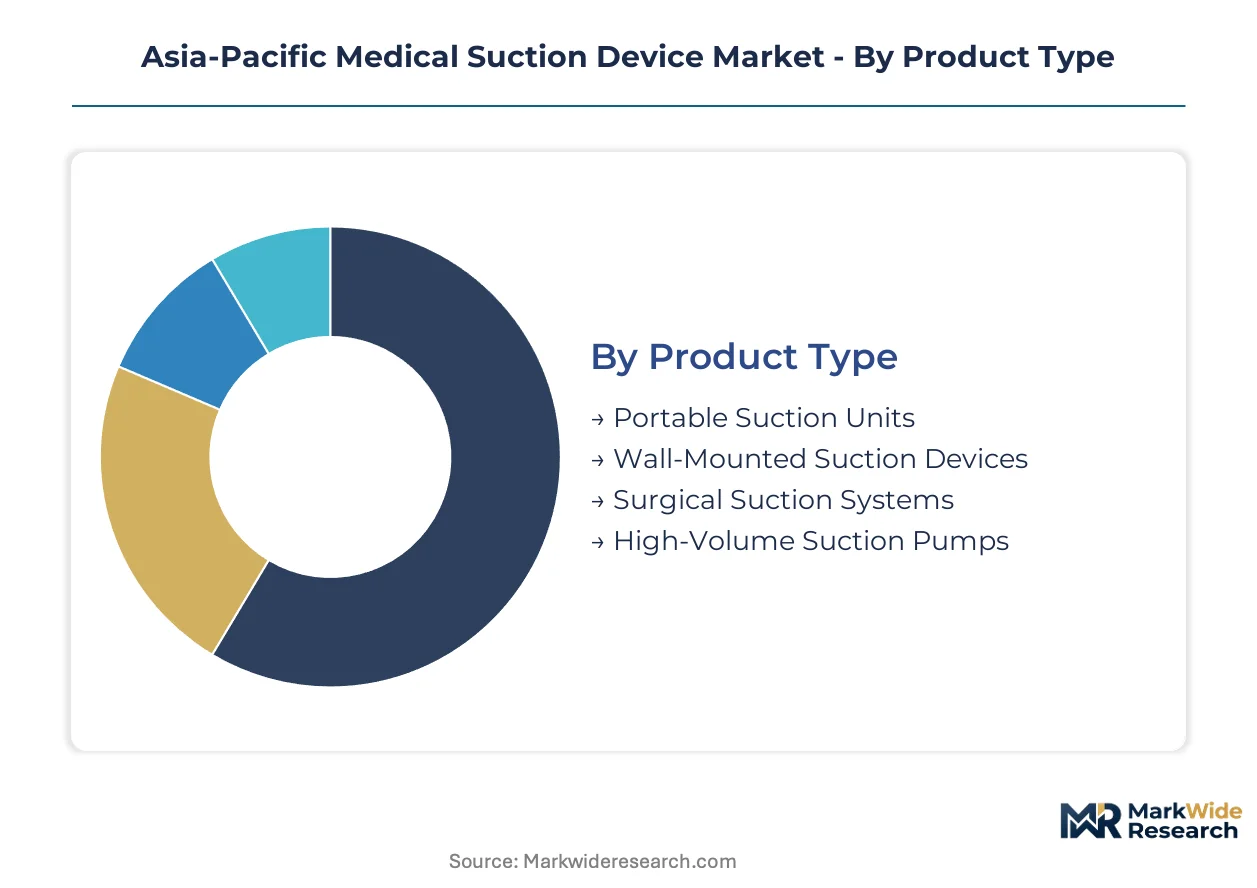
Medical suction device procurement patterns diverge sharply across Asia-Pacific healthcare systems based on infrastructure maturity, electrification reliability, and reimbursement structures. Understanding these segment boundaries enables suppliers to align product portfolios with specific tender requirements and clinical workflows.
Product Type:
Hospital infrastructure investment cycles and ambulatory expansion rates differentiate buyer priorities across this category.
- Portable Suction Units:Battery-powered or manual systems designed for field deployment and patient transport. Demand concentrates in Indonesian archipelago clinics and Indian rural health centers where grid instability necessitates mobile emergency equipment.
- Wall-Mounted Suction Devices:Fixed-installation vacuum systems integrated into hospital gas pipeline infrastructure. Procurement volumes track new construction in Maharashtra and Tamil Nadu government hospital programs, with tenders specifying centralized negative pressure distribution.
- Surgical Suction Systems:Operating room platforms delivering precise vacuum control for open and minimally invasive procedures. Australian teaching hospitals anchor premium segment demand through integrated surgical suite upgrades.
- High-Volume Suction Pumps:Industrial-capacity evacuation systems for trauma bays and intensive care units. Japanese tertiary facilities drive specifications emphasizing continuous-duty reliability under PMDA-influenced quality protocols.
Volume sits with wall-mounted installations in urban hospital construction; growth tilts toward portable configurations serving decentralized care networks.
End User:
Capital allocation authority and procurement centralization levels shape purchasing behavior across institutional categories.
- Hospitals:Multi-department institutions with dedicated biomedical engineering staff and bulk tender processes. Southeast Asian procurement consolidation is compressing vendor margins through integrated supply contracts bundling suction with anesthesia and monitoring equipment.
- Ambulatory Surgery Centers:Outpatient facilities prioritizing rapid turnover and space efficiency. Korean and Taiwanese centers are extending endoscopic procedural ecosystems, driving demand for compact suction integration.
- Home Healthcare:Post-acute and chronic care settings with patient-operated equipment. India's home healthcare expansion and Japan's aging-in-place transition are accelerating battery-operated unit adoption.
- Dental Clinics:Small-practice settings with cost-sensitive equipment refresh cycles. China's NMPA Class II registration requirements are filtering supplier participation in provincial dental equipment tenders.
Revenue concentrates in hospital procurement; margin expansion favors home healthcare as reimbursement shifts toward community-based care.
Technology:
Power source reliability and maintenance capability availability determine technology selection across healthcare settings.
- Electric Suction Devices:Mains-powered systems delivering consistent vacuum performance for continuous clinical use. Technology margin pools concentrate here, with Japanese PMDA QMS protocols elevating reliability expectations across Northeast Asian export markets.
- Manual Suction Equipment:Foot-operated or hand-powered aspirators requiring no electrical supply. Retain cost advantage in ultra-low-resource settings across Myanmar and Papua New Guinea where electrification remains incomplete.
- Battery-Operated Suction Units:Rechargeable systems with lithium-iron-phosphate chemistry extending runtime beyond eight hours. Australian Royal Flying Doctor Service and Indonesian disaster medical assistance teams are adopting these for aeromedical evacuation.
- Pneumatic Suction Systems:Compressed-gas-driven units integrated with hospital medical air infrastructure. Common in Australian and Japanese facilities with standardized gas pipeline networks.
Electric systems dominate installed base; battery-operated configurations are gaining share fastest through rural electrification programs and mobile clinic deployments.
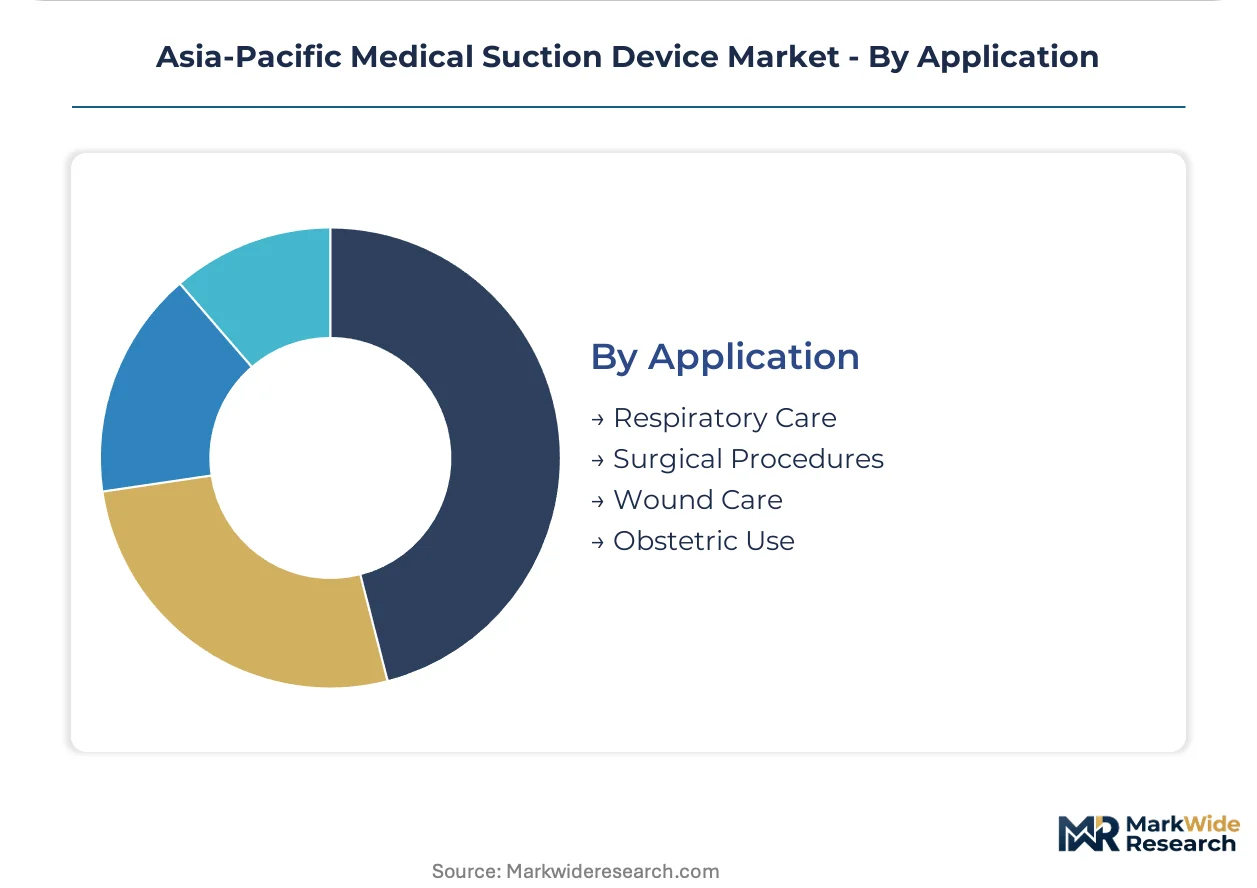
Application:
Clinical workflow intensity and reimbursement coding specificity influence equipment specification requirements.
- Respiratory Care:Airway clearance and secretion management in critical care and emergency settings. Demand tracks ICU bed expansion in Indian tertiary construction programs and Japanese aging-related respiratory disease prevalence.
- Surgical Procedures:Intraoperative fluid and tissue evacuation across open, laparoscopic, and endoscopic interventions. Olympus Corporation's gastrointestinal procedural ecosystem integration drives suction specification in Korean outpatient surgery centers.
- Wound Care:Negative pressure wound therapy and chronic wound management. Home healthcare reimbursement evolution in Japan is shifting wound suction from hospital to residential settings.
- Obstetric Use:Neonatal and maternal airway clearance during delivery. Philippine DOH equipment modernization mandates prioritize suction device replacement in barangay health stations covering maternal-child services.
Procedure volume concentrates in surgical applications; expansion rates are steepest in wound care as reimbursement migrates toward outpatient management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for medical suction devices concentrates in hospital procurement clusters across five Asia-Pacific economies, each shaped by distinct regulatory regimes and infrastructure investment cycles.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces absorb NMPA compliance costs through captive testing laboratories. Provincial hospital procurement increasingly favors Class II certificate holders, freezing unregistered import access during 18-24 month registration timelines. Shanghai's medical device industrial corridor anchors vertical integration of suction system component supply.
Japan
Aging-homecare transition accelerates battery-operated unit demand for residential respiratory management. PMDA QMS inspection protocols elevate reliability benchmarks that Japanese manufacturers leverage across Northeast Asian export markets. Tokyo-Osaka hospital networks drive premium surgical suction specifications through integrated suite upgrade programs.
India
Government hospital construction in Maharashtra and Tamil Nadu generates bulk tenders for electric suction systems across 500+ bed facilities. CDSCO import licensing and BIS electrical safety standards filter supplier participation in public sector procurement. Rural electrification programs and home healthcare expansion propel portable unit adoption in district health networks.
Australia
Teaching hospitals in Sydney and Melbourne anchor premium surgical suction system demand through integrated equipment portfolio tenders. Royal Flying Doctor Service adoption of extended-runtime portable units decentralizes emergency suction to point-of-injury care across Northern Territory remote operations. TGA regulatory alignment with international standards facilitates multi-source supplier access.
Vietnam
Central region hospital networks in Da Nang and Hue lack standardized suction infrastructure, creating positioning opportunities for compliant suppliers. Ministry of Health equipment modernization programs prioritize device replacement in provincial facilities. Ho Chi Minh City procurement reforms consolidate vendor relationships through integrated supply contracting with anesthesia and monitoring equipment bundles.
Asia-Pacific Medical Suction Device Market Competitive Environment
Japanese and Swiss producers anchor premium-tier positioning; Chinese fabricators hold volume-scale supply. The vendor structure fragments across three strategic tiers: integrated surgical equipment portfolios, emergency-care channel specialists, and domestic certificate-holding manufacturers. Competitive moves concentrate on regulatory compliance automation and procurement relationship consolidation through bundled supply agreements.
Within the premium surgical equipment tier, INTEGRA Biosciences and Olympus Corporation exemplify integrated portfolio positioning. ZOLL Medical Corporation occupies the emergency-care channel specialist archetype. These three entities represent distinct competitive vectors: Swiss manufacturing heritage anchoring teaching hospital relationships, endoscopic procedural ecosystem extension, and defibrillator-suction bundled placement control across fire-department medical units respectively.
| Leading Market Players |
|---|
| INTEGRA Biosciences |
| ZOLL Medical Corporation |
| Allied Healthcare Products |
| Amsino International |
| DeVilbiss Healthcare |
| ATMOS MedizinTechnik |
| Precision Medical |
| Laerdal Medical |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive testing laboratory integration across Jiangsu and Zhejiang provinces anchors both supply security and pricing power for domestic Chinese manufacturers absorbing NMPA compliance costs. This backward integration into regulatory certification infrastructure insulates certificate holders from import competition while compressing margins for foreign suppliers facing extended registration timelines.
Pricing Analysis
Volume concentrates in economy-tier electric suction systems serving Indian government hospital construction, while margin pools concentrate in premium surgical configurations for Australian teaching hospitals and Japanese tertiary facilities. Three-tier pricing structure across premium, standard, and economy levels differentiates by PMDA QMS certification grade and after-sales service bundling. Cost compression in mid-tier portable units is intensifying because copper and rare-earth magnet input volatility squeezes manufacturer margins. Government hospital procurement committees in Maharashtra and Tamil Nadu exhibit highest price sensitivity; fire-department medical units in Japan demonstrate lowest sensitivity due to emergency-care channel control.
Supply Chain Analysis
Direct-to-hospital channels handle bulk tender demand from Southeast Asian procurement consolidation, while distributor networks serve dispersed rural clinics across the Indonesian archipelago. Manufacturing concentrates in China, Japan, and Switzerland, with vacuum pump motor production drawing from rare-earth magnet supplies and precision-machined aluminum castings. Single-source vulnerability in lithium-iron-phosphate battery cells for portable units creates exposure to cell chemistry supply constraints. Distribution runs through integrated supply contracts bundling suction devices with anesthesia and monitoring equipment in Thai and Vietnamese hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over regulatory certification infrastructure and captive testing capacity determines competitive survival. Players are pursuing backward integration into component manufacturing to defend margin positions against input cost volatility.
For Market Incumbents: Hedge against NMPA registration timeline exposure by establishing certificate-holding organizations in Shanghai's medical device industrial corridor. Consolidate procurement relationships through integrated supply contracts spanning suction, anesthesia, and patient monitoring equipment. Battery-operated configuration specialists from domestic Chinese manufacturers pose substitution threats in India's home healthcare expansion. For New Entrants and Emerging Players: The price-point gap between premium Swiss-manufactured surgical systems and economy-tier manual aspirators creates positioning space for mid-tier electric portable units. Vietnam's underpenetrated central region hospital networks in Da Nang and Hue offer the most penetrable geographic entry point. Pursue compliance-first go-to-market alignment with Philippine DOH equipment modernization mandates for barangay health station replacement cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated surgical equipment portfolios seeking suction technology tuck-ins. Long-term viability centers on regulatory certification asset ownership rather than pure manufacturing scale. Watch for NMPA Class II registration approval velocity as inflection indicator for domestic Chinese manufacturer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Registration Investment | Certificate ownership unlocks provincial hospital procurement access in China's government tender system. |
| Integrated Supply Contracting | Bundled anesthesia-suction-monitor agreements consolidate vendor relationships in Thai GPOs. |
| Battery Chemistry Vertical Integration | Lithium-iron-phosphate cell sourcing control secures portable unit runtime leadership for field deployment. |
| PMDA QMS Certification Pathway | Japanese reliability protocols elevate product specifications across Northeast Asian export markets. |
| Telemedicine-Integrated Remote Monitoring | IoT sensor convergence enables predictive maintenance contracts in Australian remote healthcare networks. |
Study Parameters
Multi-period observation of hospital procurement tender patterns, regulatory approval timelines, and raw material input costs anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and NMPA regulatory consultants. Secondary validation drew from CDSCO import licensing databases, Philippine DOH equipment modernization mandates, Japanese PMDA QMS inspection protocols, and Australian TGA regulatory alignment documentation. Bottom-up segment sizing triangulated against top-down healthcare infrastructure investment forecasts.
Segment-weighting across product type, end user, technology, application, and country-level regulatory cluster dimensions shaped the analytical framework. CAGRs were derived from trend extrapolation of procurement volume patterns and reimbursement evolution trajectories across the projection horizon. Industry-specific forecast inputs included ICU bed expansion rates in Indian tertiary construction, aging-in-place transition velocity in Japan, and rural electrification program completion schedules in Indonesia.
Inputs from hospital procurement databases and regulatory filing records were available through the study window; gaps in real-time tender outcome reporting and confidential contract pricing introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions regarding NMPA registration timeline stability and copper price volatility persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Gamma Knife Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Light Therapy Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Global Otoscopes Market