
 Seizure Detection Devices Market | 2026-2036
Seizure Detection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Seizure Detection Devices Market Analytics
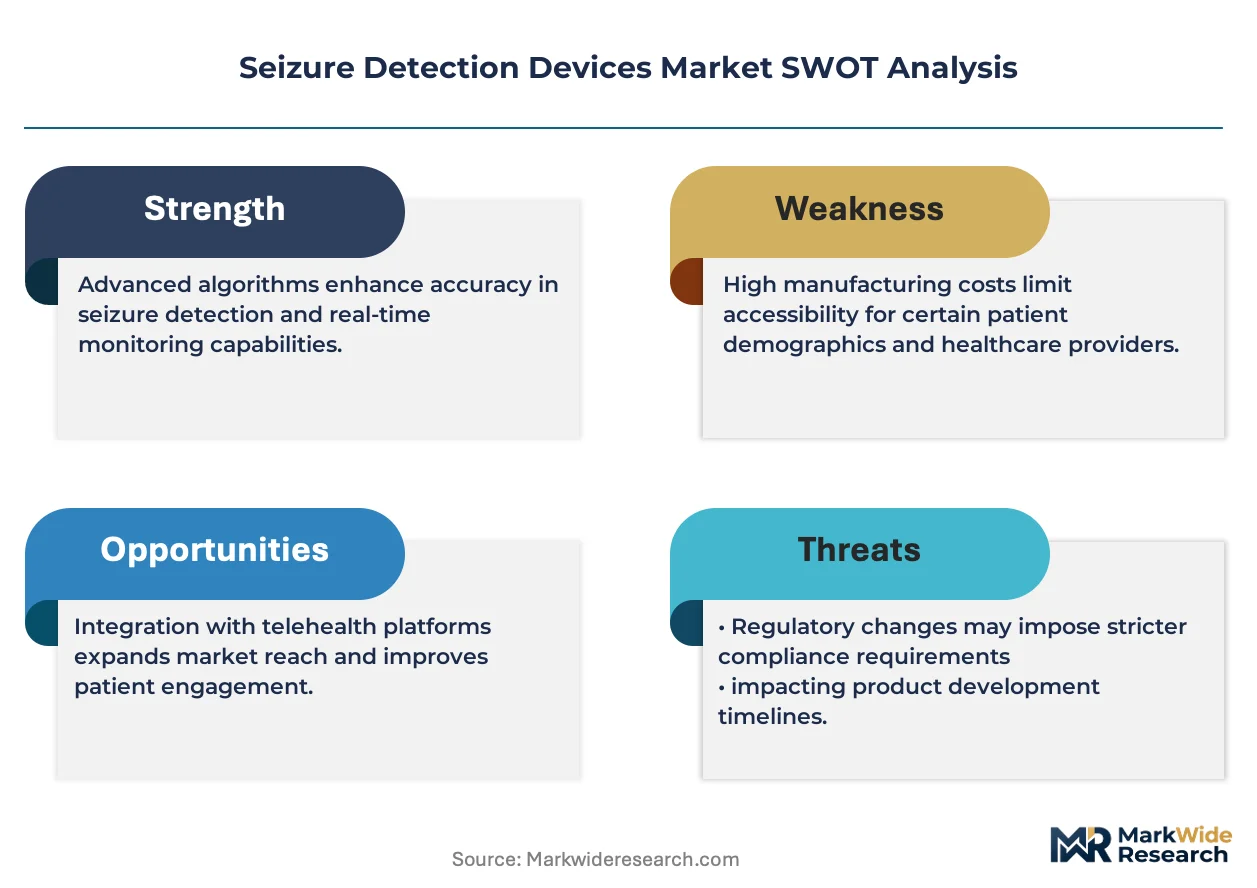
Hospital procurement departments are bifurcating from traditional EEG capital purchases toward subscription-based wearable monitor deployments. Empatica Inc. specializes in wrist-worn biosensors that leverage machine learning algorithms for real-time seizure classification. Natus Medical dominates conventional EEG device supply chains while Seer Medical anchors ambulatory monitoring services through its at-home video-EEG platform.
Seizure detection devices integrate electrophysiological sensors, accelerometers, and algorithmic classifiers to identify epileptiform activity and trigger automated alerts. Wearable monitors incorporate multi-day battery systems and waterproof enclosures to sustain continuous skin-contact recording during normal daily activity. EEG devices retain the largest installed base across neurology clinics, while mobile applications represent the fastest-expanding segment as smartphone-integrated photoplethysmography and accelerometry reduce hardware barriers. Implantable devices command concentrated margin pools due to surgical placement requirements and long-term monitoring contracts.
FDA breakthrough device designation and EU MDR conformity assessment shape product development timelines and market access trajectories for manufacturers. The EPA regulates lithium battery disposal from wearable units, while ISO 13485 quality management certification remains mandatory for component suppliers. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payors recalibrate coverage for algorithm-diagnosed events versus clinician-verified seizures.
Market Dynamics
Hospital neurology departments are abandoning capital-intensive EEG purchases for subscription-based wearable deployments, compressing vendor cash cycles while expanding patient monitoring continuity.
Growth Catalysts
- Remote patient monitoring reimbursement:CMS-established billing codes in the United States now cover algorithm-detected seizure events, incentivizing outpatient adoption of continuous biosensors.
- Wearable battery chemistry advances:Multi-day lithium-polymer systems enable uninterrupted skin-contact recording during normal daily activity, eliminating patient compliance barriers.
- FDA breakthrough device pathway:Expedited review timelines for seizure detection algorithms are compressing product-to-market intervals for novel classifiers.
Market Restraints
- Implantable device cost structure:Surgical placement requirements and neurosurgeon fees concentrate margin pools among a handful of academic medical centers, limiting addressable patient volume.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints are extending CE marking timelines for wearable biosensors, delaying European commercialization.
- Photoplethysmography accuracy limitations:Motion artifact susceptibility in smartphone-integrated optical sensors generates false-positive alerts, undermining clinical trust in mobile-only solutions.
Strategic Opportunities
- Pediatric epilepsy monitoring gaps:Underpenetrated demand in Germany's ambulatory pediatric neurology networks presents white space for child-form-factor wearables with school-day battery endurance.
- EEG-ECG convergence:Integration of cardiac arrhythmia detection with seizure classification creates dual-purpose diagnostic value for sudden unexpected death in epilepsy risk stratification.
- Direct-to-patient distribution channels:Telehealth platforms are bypassing traditional hospital procurement, enabling manufacturer-direct subscription models with recurring revenue streams.
Industry Challenges
- ISO 13485 certification timelines:Component suppliers face extended quality management audits, constraining supply elasticity for scaled wearable production.
- Algorithm validation complexity:Multi-site clinical trials required for FDA clearance demand specialized biostatistics talent that concentrates among contract research organizations in Boston and San Diego.
- Legacy EMR integration friction:Proprietary data formats from wearable devices require costly HL7 FHIR interface development for seamless hospital workflow incorporation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seizure Detection Devices Market |
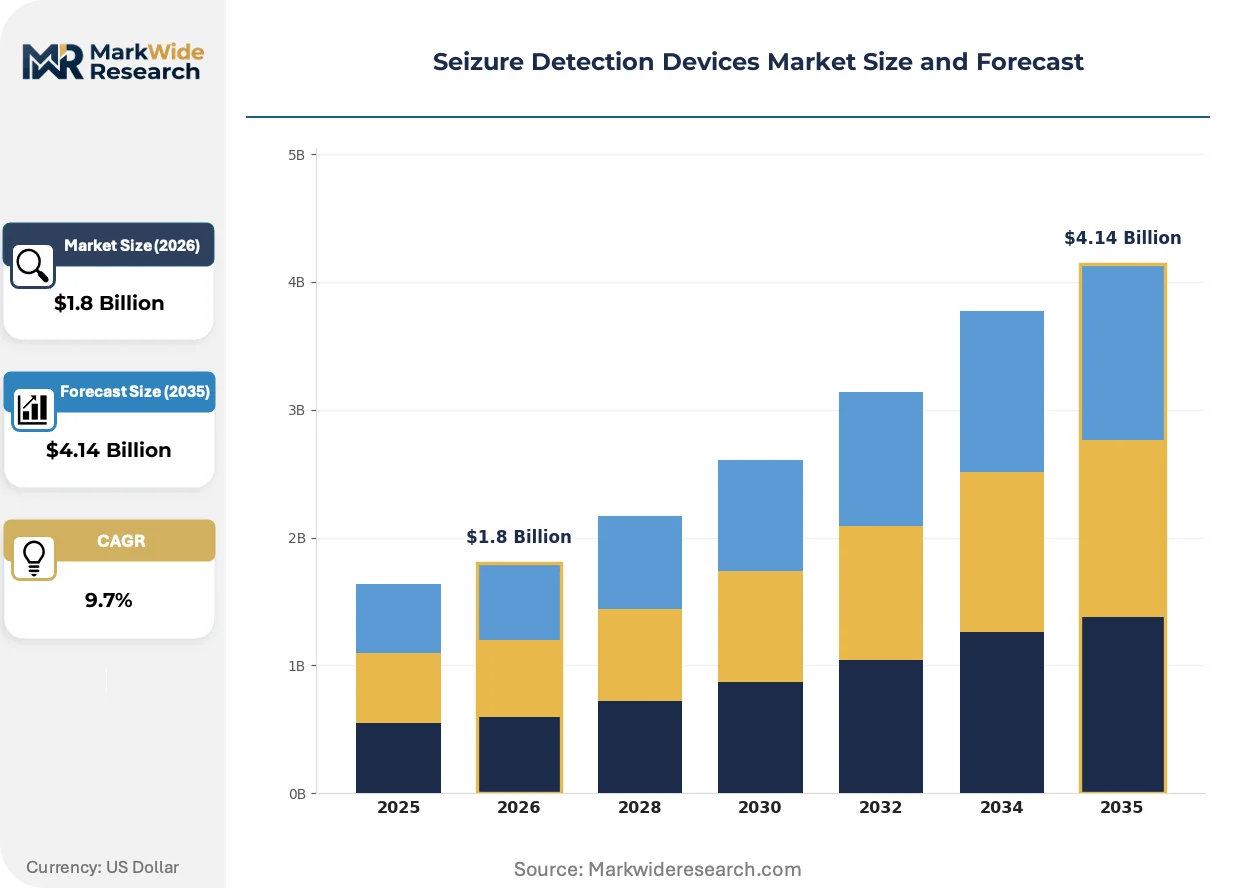
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Implantable Devices, Mobile Applications, EEG Devices End User: Hospitals, Home Care, Neurology Clinics, Research Institutions Technology: Wireless Transmission, Signal Processing, Machine Learning, Neurostimulation Application: Epilepsy Monitoring, Patient Alert Systems, Data Analytics, Clinical Research |
| Companies Covered | Medtronic, Nihon Kohden Corporation, Natus Medical, Compumedics Limited, Empatica Inc., GE Healthcare, Cadwell Industries, Seer Medical, Masimo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seizure Detection Devices Market Evolving Landscape
Machine learning classifiers trained on multi-modal biosignals are compressing the diagnostic latency between seizure onset and clinical intervention, while regulatory frameworks adapt to algorithm-centric evidence standards.
Wrist-worn photoplethysmography combined with 3-axis accelerometry is displacing conventional bedside EEG for nocturnal seizure surveillance in residential settings. Sleep clinics and home health agencies are adopting these systems to reduce overnight technician costs. The structural consequence is a channel shift from hospital-based diagnostic centers to distributed ambulatory monitoring networks.
EU MDR post-market surveillance requirements now mandate periodic safety updates for software-as-medical-device products, forcing manufacturers to maintain continuous clinical evidence generation. Notified bodies are demanding real-world performance data that exceeds pre-market trial scope. Wearable monitor vendors are responding by embedding automated outcome reporting into cloud platforms to satisfy vigilance obligations.
Japanese epilepsy centers are unbundling hardware acquisition from interpretation services, purchasing monitoring devices while contracting Seer Medical and similar platforms for remote video-EEG analysis. This separation of capital and operating expenditures aligns procurement with value-based care metrics. The model is spreading to German neurologist networks seeking to minimize fixed asset exposure.
Seizure Detection Devices Market Segmentation
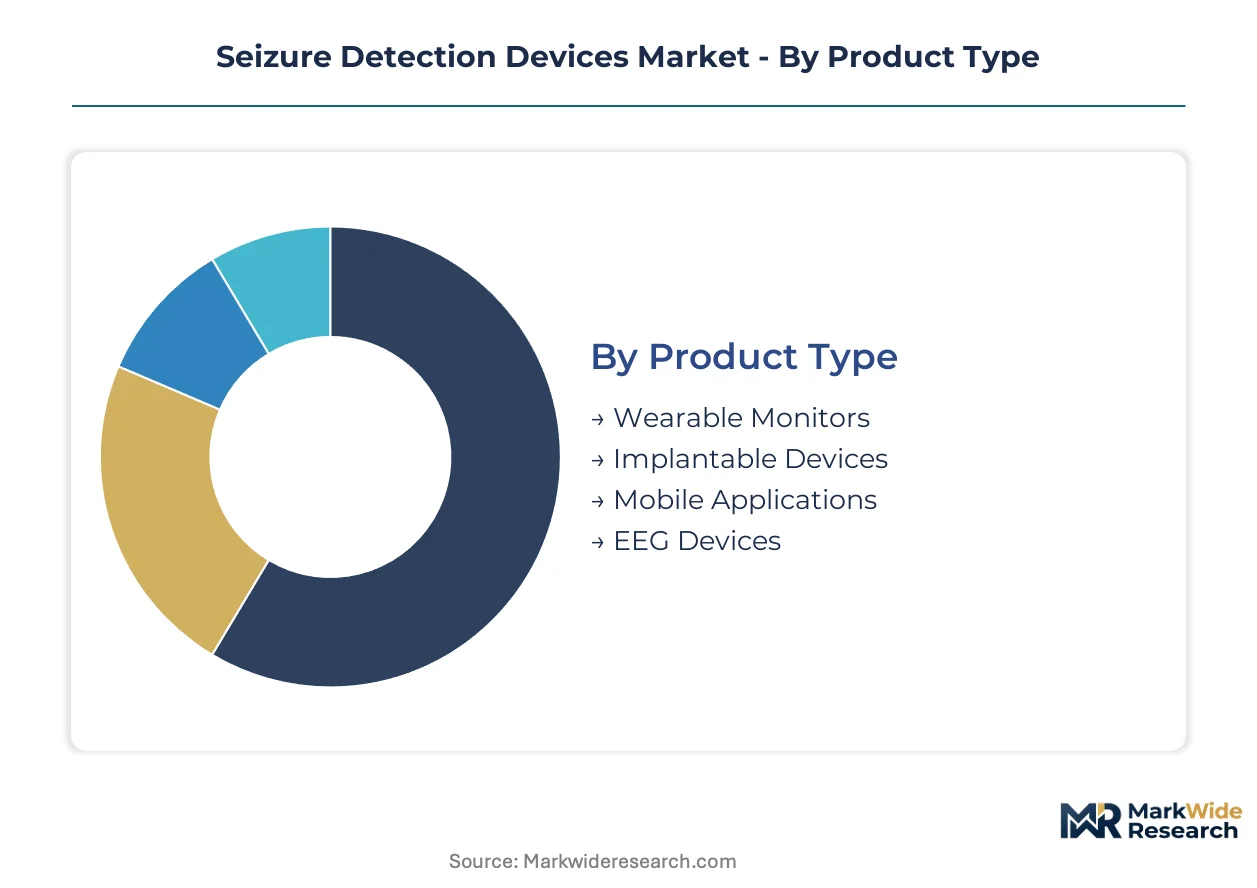
Product architecture in seizure detection determines reimbursement eligibility and procurement channel selection. Technology integration patterns and end-use workflow requirements create distinct margin profiles across segment boundaries.
Product Type:
Implantable devices capture concentrated margin pools due to surgical placement requirements and long-term monitoring contracts, while wearable monitors scale through subscription economics.
- Wearable Monitors:Multi-day lithium-polymer systems power wrist-worn biosensors with waterproof enclosures for continuous skin-contact recording. Hospital neurology departments in the United States are shifting procurement toward these subscription-based deployments to extend outpatient surveillance continuity.
- Implantable Devices:Surgical neurostimulation systems require operating room placement and specialized neurosurgeon fees. Academic medical centers in Germany and Japan concentrate demand for these high-margin units where reimbursement frameworks cover invasive monitoring.
- Mobile Applications:Smartphone-integrated photoplethysmography and accelerometry reduce hardware barriers for patient-initiated monitoring.
- EEG Devices:Conventional bedside and ambulatory electroencephalography systems retain the largest installed base across neurology clinics.
The dominant share belongs to EEG Devices, while Wearable Monitors are closing the gap fastest.
End User:
Procurement authority and reimbursement pathway maturity separate hospital systems from distributed care settings.
- Hospitals:Capital budgets and value-based care metrics drive acquisition of integrated monitoring platforms. Neurology departments in Japan are unbundling hardware from interpretation services to align with outcome metrics.
- Home Care:Sleep clinics and home health agencies adopt wrist-worn systems to eliminate overnight technician costs. CMS-established billing codes in the United States now cover algorithm-detected events in residential settings.
- Neurology Clinics:Outpatient facilities require seamless HL7 FHIR integration for proprietary wearable data formats.
- Research Institutions:Multi-site clinical trials demand specialized biostatistics talent for FDA algorithm validation.
Hospitals command the largest revenue concentration, though Home Care is expanding most quickly as telehealth platforms bypass traditional procurement.
Technology:
Signal processing sophistication determines regulatory pathway complexity and time-to-market duration.
- Machine Learning:Algorithmic classifiers trained on multi-modal biosignals compress diagnostic latency between seizure onset and intervention. FDA breakthrough device designation expedites review timelines for novel classifiers.
- Signal Processing:Real-time electrophysiological filtering and artifact rejection enable ambulatory recording quality comparable to controlled clinical environments. EU MDR post-market surveillance now mandates continuous safety updates for these software-as-medical-device products.
- Wireless Transmission:Cloud-connected architectures support automated outcome reporting to satisfy notified body vigilance obligations.
- Neurostimulation:Closed-loop responsive stimulation systems integrate detection with therapeutic intervention for drug-resistant epilepsy.
Signal Processing anchors current installed capacity, yet Machine Learning is gaining share fastest through regulatory acceleration.
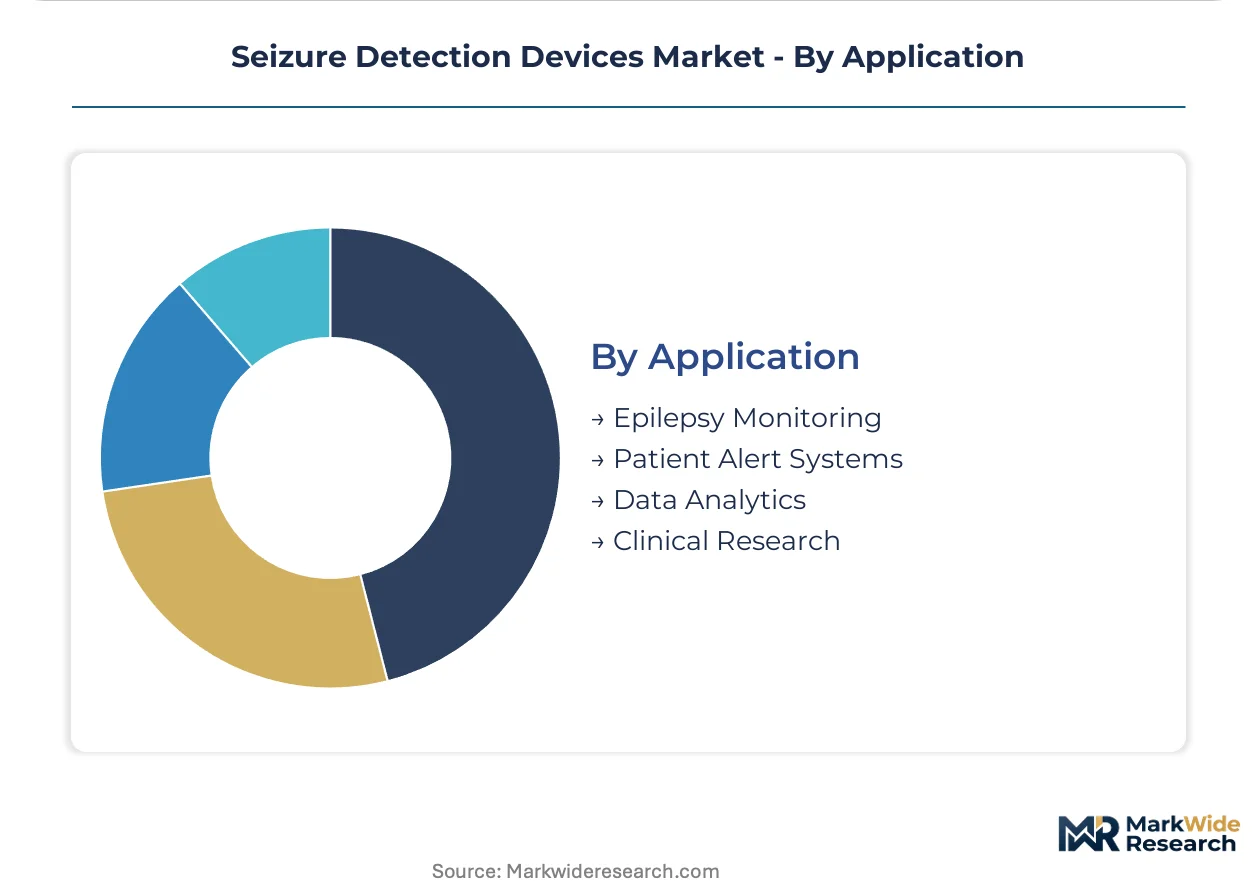
Application:
Clinical utility and reimbursement specificity separate diagnostic monitoring from alert and analytics functions.
- Epilepsy Monitoring:Continuous electrophysiological surveillance for seizure classification and localization supports surgical candidacy evaluation. German pediatric neurology networks present underpenetrated demand for child-form-factor wearables.
- Patient Alert Systems:Automated caregiver notification triggers clinical intervention or rescue medication administration. Motion artifact susceptibility in smartphone-integrated optical sensors generates false-positive alerts that undermine trust.
- Data Analytics:Longitudinal seizure pattern analysis enables medication optimization and lifestyle modification recommendations.
- Clinical Research:Standardized outcome measures for pharmaceutical trials require validated biomarker extraction from continuous recordings.
Epilepsy Monitoring holds the established revenue base, while Patient Alert Systems are climbing the fastest as consumer-facing platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export seizure detection hardware to Japanese epilepsy centers, establishing a trans-Eurasian procurement corridor that bypasses traditional US distribution channels.
United States
Hospital neurology departments in Boston and San Diego concentrate demand for wearable monitors as CMS reimbursement codes now cover algorithm-detected events. FDA breakthrough device designation accelerates clearance timelines for novel classifiers. The Mayo Clinic in Rochester anchors multi-site clinical trials for machine learning validation.
Germany
Ambulatory pediatric neurology networks in Bavaria and North Rhine-Westphalia drive demand for child-form-factor wearables with school-day battery endurance. EU MDR conformity assessment bottlenecks extend CE marking timelines for wearable biosensors. Berlin-based notified bodies demand real-world performance data exceeding pre-market trial scope.
Japan
Epilepsy centers in Tokyo and Osaka unbundle hardware acquisition from interpretation services to align with value-based care metrics. PMDA expedites review pathways for software-as-medical-device products. The Kansai region concentrates academic medical center demand for implantable neurostimulation systems.
United Kingdom
NHS England procurement frameworks favor subscription-based wearable deployments over capital-intensive EEG purchases. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines. London's digital health cluster hosts telehealth platforms enabling direct-to-patient distribution channels.
Australia
Home health agencies in New South Wales and Victoria adopt wrist-worn systems to eliminate overnight technician costs. TGA recognition of FDA breakthrough designations streamlines parallel market entry. Melbourne anchors Seer Medical's at-home video-EEG platform operations for Asia-Pacific expansion.
Seizure Detection Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with established neurology device portfolios. The competitive structure concentrates around three tiers: integrated hospital system suppliers, wearable-focused algorithm developers, and specialized ambulatory service platforms. Strategic archetypes include EEG capital equipment incumbents pivoting to subscription models, wrist-worn biosensor specialists leveraging cloud analytics, and surgical implant vendors capturing long-term monitoring contracts. Dominant competitive moves encompass M&A targeting algorithmic capabilities and strategic partnerships bridging hardware manufacturing with telehealth distribution.
Within the diversified medical technology tier, Medtronic and GE Healthcare represent capital-intensive infrastructure plays with global hospital procurement relationships. Natus Medical exemplifies the EEG incumbent archetype transitioning toward ambulatory monitoring services. Empatica Inc. and Seer Medical occupy distinct positions as algorithm-native and service-integrated specialists respectively, with the former anchoring wrist-worn innovation and the latter unbundling hardware from remote interpretation.
| Leading Market Players |
|---|
| Medtronic |
| Nihon Kohden Corporation |
| Natus Medical |
| Compumedics Limited |
| Empatica Inc. |
| GE Healthcare |
| Cadwell Industries |
| Seer Medical |
| Masimo |
| Others |
Value Network & Pricing Analysis
Subscription-based capacity reservation contracts now dominate hospital procurement, locking neurology departments into multi-year wearable monitor deployments that guarantee supply continuity while flattening price volatility across the forecast window.
Pricing Analysis
Current-generation wrist-worn biosensors command premium subscription rates against prior-generation bedside EEG capital purchases, while next-generation implantable neurostimulation systems concentrate margin pools through surgical placement bundling. Three-tier pricing structure across premium implantable, standard wearable, and economy mobile application levels reflects FDA breakthrough designation tiering and ISO 13485 certification depth. Pricing pressure stems from EU MDR conformity assessment bottlenecks extending vendor cash cycles. Home care agencies exhibit highest price sensitivity due to CMS reimbursement lag, whereas academic medical centers absorb premium implantable costs through bundled surgical contracts.
Supply Chain Analysis
Lithium-polymer cell fabrication in South Korea, China, and Japan anchors wearable monitor production, with single-source vulnerability concentrated in Seoul-based battery chemistry suppliers. Machine learning classifier development draws from Boston and San Diego contract research organization talent pools, while electrophysiological sensor fabrication rests on German precision component manufacturers. Tariff exposure runs through US-China semiconductor trade friction affecting accelerometer chip supply. Distribution runs through hospital procurement departments unbundling hardware from interpretation services, with telehealth platforms emerging as direct-to-patient bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across pediatric epilepsy monitoring, ambulatory home care, and algorithm-native service platforms creates multiple entry niches as reimbursement codes shift toward algorithm-detected events.
For Market Incumbents: Compound installed base advantages by embedding HL7 FHIR interfaces into legacy EEG systems before wearable-native competitors capture hospital IT integration budgets. Deepen backward integration into lithium-polymer cell supply through Korean battery manufacturer partnerships. FDA breakthrough designation acceleration threatens Natus Medical's capital equipment dominance unless subscription pivot completes within two procurement cycles. For New Entrants and Emerging Players: Anchor in Germany's ambulatory pediatric neurology networks where child-form-factor wearable demand outpaces domestic supply. Seize white space in NHS England subscription procurement frameworks favoring SaaS-tiered deployments over capital purchases. Target direct-to-patient telehealth distribution bypassing hospital procurement gatekeepers, leveraging TGA-FDA parallel recognition for accelerated Australian market entry. For Investors and Strategic Acquirers: Algorithm-native service platforms with cloud-embedded outcome reporting capabilities represent the highest-conviction acquisition archetype for EU MDR post-market surveillance compliance. Long-term viability hinges on reimbursement code expansion for remote patient monitoring across German and Japanese national health systems. Watch CMS algorithm-diagnosed event coverage decisions as the critical inflection signal for wearable monitor valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited review compresses time-to-revenue for novel seizure classifiers against standard 510(k) pathways. |
| CE Marking Pathway Under EU MDR | Notified body capacity constraints in Berlin extend timelines, favoring early applicants with real-world performance data. |
| Hospital System Partnership | Mayo Clinic and Boston academic anchors drive multi-site clinical trial recruitment for algorithm validation. |
| Software Companion Development | HL7 FHIR integration reduces EMR friction costs that currently block wearable data workflow adoption. |
| Reimbursement Strategy | CMS remote patient monitoring codes now cover algorithm-detected events, unlocking home care segment economics. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital neurology department heads, biomedical engineers, GPO contracts managers, and telehealth platform executives; and secondary validation against FDA 510(k) and breakthrough device filings, CMS reimbursement code databases, EU MDR notified body registers, and hospital procurement contract records. Bottom-up triangulation across wearable monitor shipment estimates and top-down reconciliation against neurology department capital expenditure surveys anchored volume projections.
Across the analysis window, the forecasting framework modeled product type segmentation by battery chemistry and enclosure durability, end-user segmentation by procurement authority concentration, technology segmentation by regulatory pathway complexity, and application segmentation by reimbursement specificity. CAGRs derived from fitted growth curves against historical EEG equipment replacement cycles and wearable adoption S-curves in adjacent cardiac monitoring markets. Algorithm validation trial timelines and notified body capacity constraints fed scenario-weighted projections.
Material uncertainties — EU MDR post-market surveillance requirement evolution, CMS remote monitoring code expansion decisions, and lithium supply chain geopolitical friction — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement pathway maturation and algorithm diagnostic accuracy convergence. Practitioners should keep alternative scenarios live as German pediatric network penetration rates and Japanese unbundled procurement adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Blood Collection Vacuum Devices Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Flow Diverters Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Peripheral Vascular Guide Wire Market