
 Neurovascular Access Catheters Market | 2026-2036
Neurovascular Access Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Neurovascular Access Catheters Market Foresight
The capital-intensity divergence between large integrated manufacturers and focused catheter specialists is bifurcating competitive dynamics. Stryker Corporation leverages its Neurovascular division's full-stack manufacturing to control costs across guide catheter and aspiration catheter lines. Medtronic Plc anchors its position through deep R&D investment in thrombectomy delivery systems. Penumbra, Inc competes by specializing in trackable microcatheters for distal access procedures.
Neurovascular access catheters are thin-walled, torqueable tubes engineered from braided nylon or polyurethane composites with hydrophilic coatings, designed to navigate tortuous cerebral vasculature and deliver interventional devices to target lesions. Guide catheters command the largest revenue share due to their universal deployment across thrombectomy and stenting procedures, while microcatheters represent the fastest-growing segment as physicians pursue more distal access for complex aneurysm embolization. The material dimension shows polyurethane dominating catheter shaft construction for its kink resistance, though polyethylene variants gain traction in cost-sensitive hospital procurement frameworks.
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for catheter manufacturers. The EPA and OSHA frameworks additionally govern solvent-based coating processes and cleanroom manufacturing standards in US production facilities. Stakeholders must monitor evolving reimbursement codes for mechanical thrombectomy and distal access procedures across Medicare, national health services, and private payers to anticipate volume shifts between product categories.
Market Dynamics
Academic medical centers in the United States, Germany, and Japan are consolidating stroke care into comprehensive treatment networks, concentrating catheter procurement decisions into fewer hospital systems with standardized device protocols.
Growth Catalysts
- EU MDR conformity assessments:Accelerated technical documentation pathways are compressing product clearance timelines for catheter manufacturers seeking European market access.
- Distal access procedures:Physician pursuit of complex aneurysm embolization in tortuous cerebral vasculature is expanding addressable procedure volumes.
- Japan:METI-supported scaling of comprehensive stroke center networks is concentrating demand for thrombectomy delivery systems.
Market Restraints
- Nylon and polyurethane composites:Volatility in medical-grade polymer feedstock costs compresses margin buffers for catheter shaft production.
- Cleanroom manufacturing concentration:EPA and OSHA solvent-based coating standards limit US production facility expansion options.
- Technical limitation:Kink resistance requirements in polyethylene variants constrain cost-down substitution for polyurethane in premium segments.
Strategic Opportunities
- India:CDSCO regulatory harmonization with international standards is opening procedural access for catheter-based thrombectomy in underserved stroke corridors.
- Robotic-assisted delivery:Convergence of trackable microcatheter technology with surgical navigation systems creates new interventional workflow categories.
- Direct hospital system contracting:Bypassing traditional distributor networks captures margin from consolidated academic medical center procurement.
Industry Challenges
- Specialized interventional neuroradiologists:Training pipeline bottlenecks limit procedure volume scaling even where catheter supply exists.
- FDA premarket notification timelines:510(k) pathway documentation requirements extend product launch schedules for novel catheter geometries.
- Legacy aspiration catheter integration:Compatibility testing with third-party thrombectomy devices consumes R&D resources without differentiation payoff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurovascular Access Catheters Market |
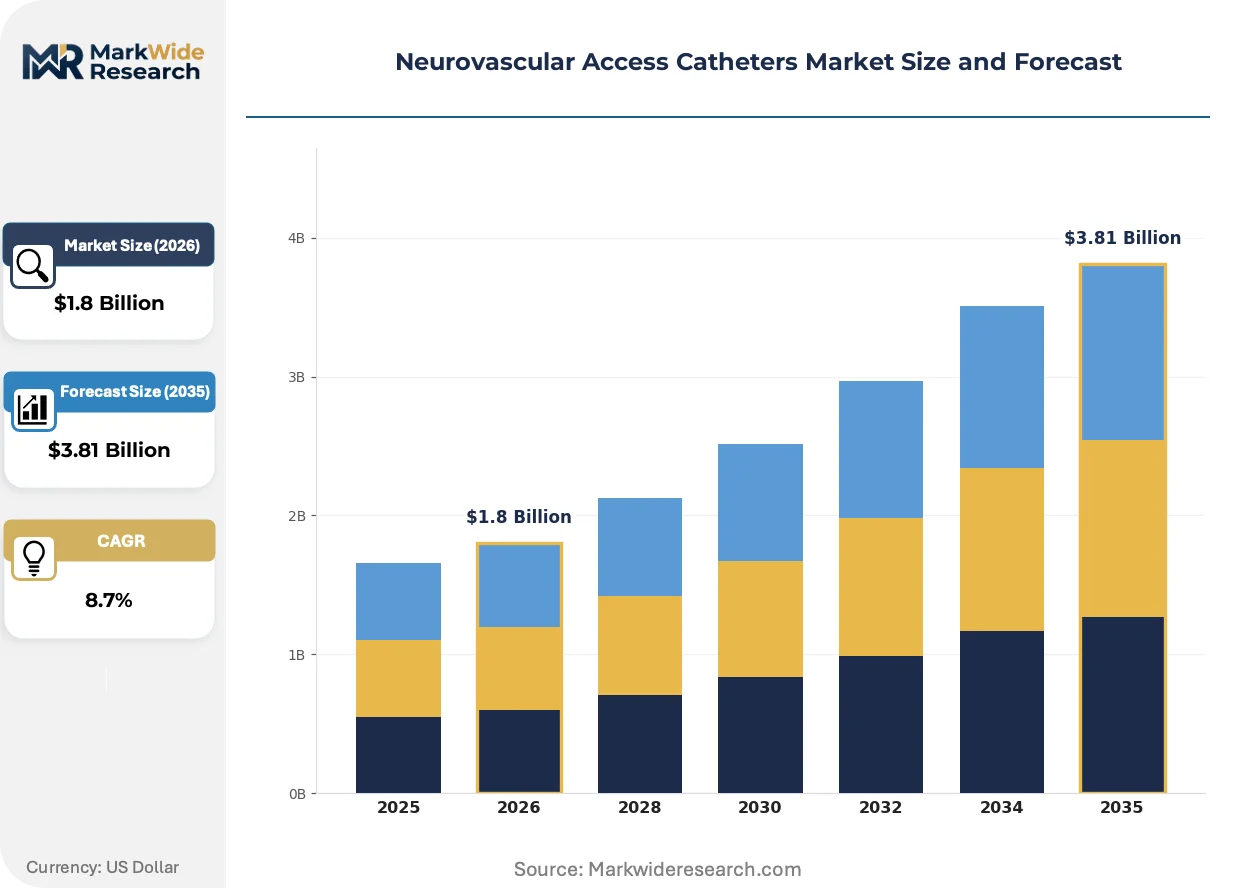
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Guide Catheters, Sheath-Needles, Microcatheters End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Research Institutions Application: Thrombectomy, Stenting, Angioplasty, Embolization Material: Polyurethane, Nylon, Silicone, Polyethylene |
| Companies Covered | Stryker Corporation, Medtronic Plc, Johnson & Johnson, Integer Holdings Corporation, Penumbra, Inc, Terumo Corporation, Biomerics, Imperative Care Inc, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurovascular Access Catheters Market Shifts & Advancements
Catheter engineering is pivoting from universal-platform designs toward lesion-specific architectures, with hydrophilic coating chemistry and braid reinforcement patterns becoming primary competitive variables.
Polyurethane composites with variable-durometer shaft construction are bifurcating the guide catheter segment. Academic stroke centers in the United States are adopting these platforms for universal thrombectomy and stenting deployment. The technology is bifurcating procurement decisions between integrated manufacturers with captive polymer compounding and specialists dependent on external material supply.
EU MDR technical documentation requirements are reshaping European market access economics. Manufacturers must maintain clinical evidence portfolios for legacy catheter lines alongside new submissions. Distal access microcatheters face the steepest compliance cost escalation due to their shorter commercial lifecycles and indication expansions.
Hospital procurement committees are consolidating vendor relationships around full-stack thrombectomy system suppliers. Independent catheter specialists face exclusion from preferred vendor lists unless they bundle with aspiration or stent-retriever platforms. Germany exhibits the most advanced committee-driven consolidation, with university hospitals standardizing on two-vendor catheter portfolios.
Neurovascular Access Catheters Market Segmentation
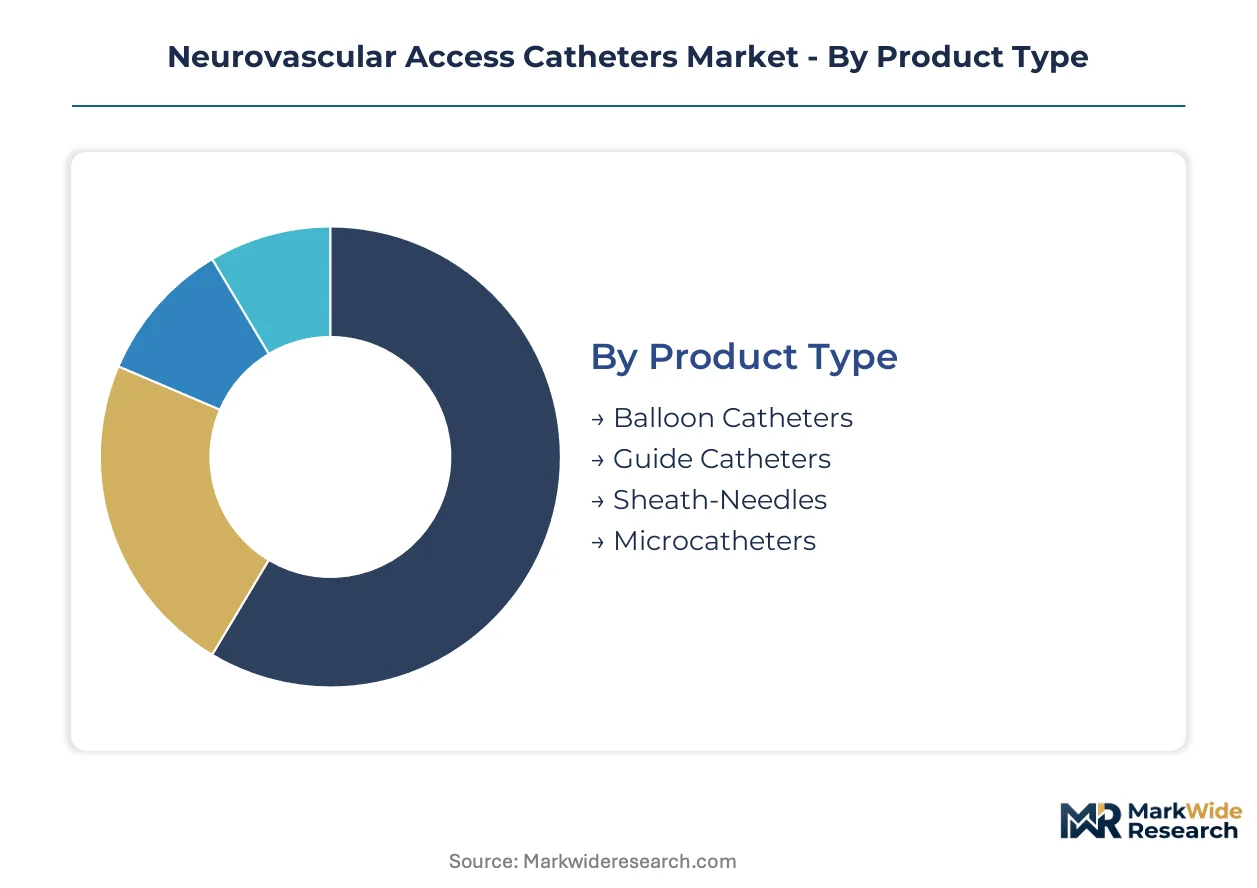
Segmentation in neurovascular access catheters reveals how regulatory pathways, reimbursement codes, and procedure economics concentrate demand across distinct product architectures and clinical settings. Each dimension carries specific compliance burdens and margin structures that reshape competitive positioning.
Product Type:
FDA 510(k) clearance pathways and EU MDR technical documentation requirements create divergent market access timelines across catheter architectures, with larger-bore devices facing steeper clinical evidence thresholds.
- Guide Catheters:Braided nylon or polyurethane composite shafts with hydrophilic coatings enable universal deployment across thrombectomy and stenting workflows. Academic medical centers in the United States concentrate procurement for these platforms through standardized comprehensive stroke center protocols.
- Microcatheters:Trackable distal access designs with variable-durometer construction navigate tortuous cerebral vasculature for complex aneurysm embolization. Physician pursuit of more distal lesion reach in Germany and Japan expands addressable procedure volumes fastest.
- Balloon Catheters:Inflation-lumen integrated designs for angioplasty and flow control occupy niche interventional neuroradiology applications.
- Sheath-Needles:Vascular entry systems providing initial arterial access for subsequent catheter exchanges.
Established volume favors guide catheters; emerging adoption favors microcatheters.
End User:
Procurement authority concentrates differently across facility types, with hospital system committees wielding vendor consolidation power that ambulatory and research settings cannot replicate.
- Hospitals:Comprehensive stroke centers and academic medical centers command catheter procurement through standardized device protocols and preferred vendor lists. Consolidated purchasing in the United States, Germany, and Japan compresses supplier margins while locking in volume commitments.
- Ambulatory Surgical Centers:Limited neurovascular intervention footprint due to emergency stroke care requirements and imaging infrastructure needs.
- Diagnostic Laboratories:Angiography suite operators requiring access catheters for diagnostic cerebral angiography rather than therapeutic intervention.
- Research Institutions:Preclinical and clinical trial sites driving early adoption of novel catheter geometries and coating chemistries.
Commercial concentration sits with hospitals; technology validation originates in research institutions.
Application:
Reimbursement code specificity and procedure volume economics segment the addressable market by clinical indication, with mechanical thrombectomy commanding the most favorable payment structures.
- Thrombectomy:Mechanical clot retrieval for acute ischemic stroke represents the highest-volume neurovascular intervention. Medicare and national health service reimbursement codes in the United States, Germany, and Japan concentrate catheter demand through comprehensive stroke center networks.
- Embolization:Aneurysm and arteriovenous malformation treatment requiring distal microcatheter access. Complex lesion anatomy in tortuous vasculature drives fastest technology turnover.
- Stenting:Intracranial atherosclerotic disease management using self-expanding or balloon-expandable platforms.
- Angioplasty:Balloon dilation for intracranial stenosis with limited procedure volume relative to thrombectomy.
Reimbursement scale favors thrombectomy; technical complexity favors embolization.
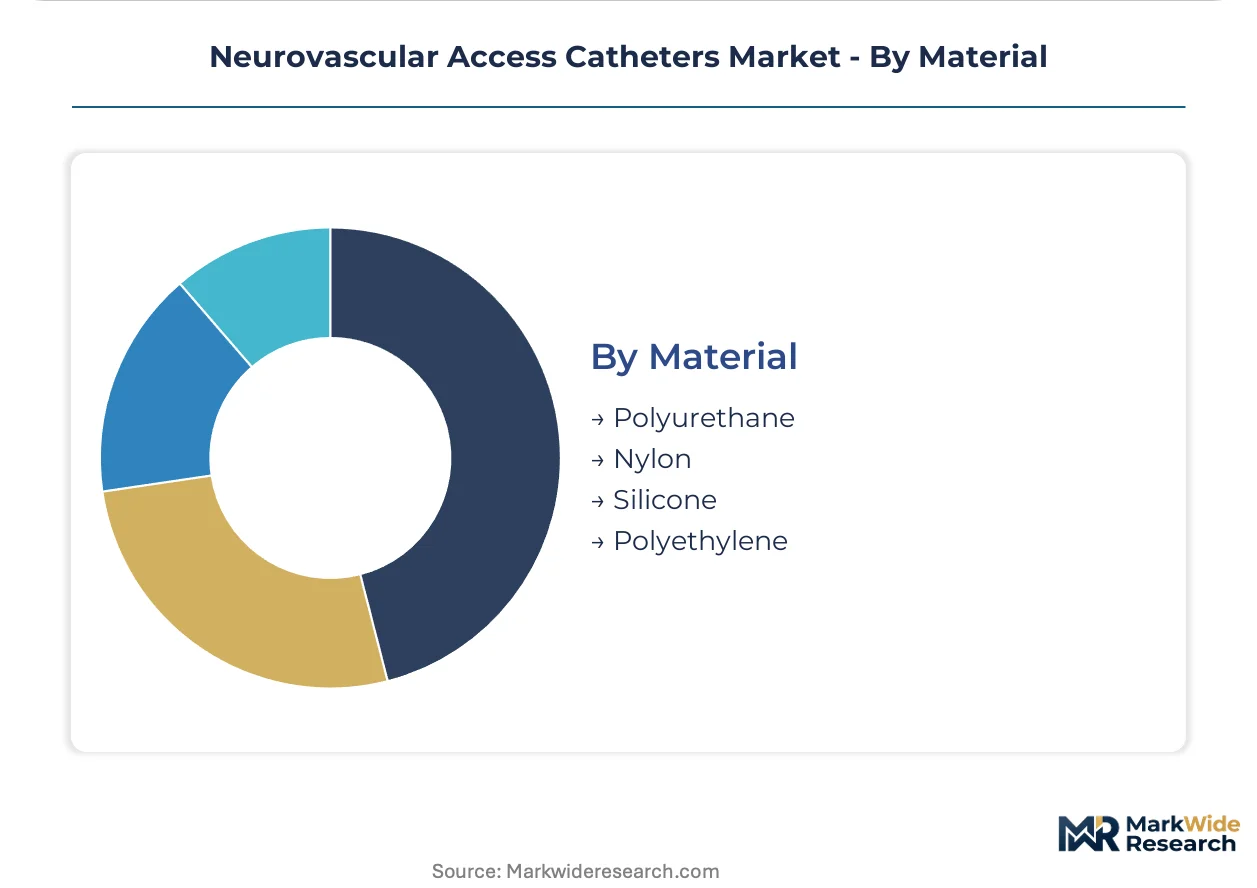
Material:
Medical-grade polymer feedstock costs and EPA solvent-handling standards constrain material substitution strategies across catheter shaft production.
- Polyurethane:Dominates premium guide catheter construction through kink resistance and variable-durometer shaft engineering. Captive polymer compounding by integrated manufacturers controls cost structures.
- Nylon:Braided composite layers providing torque response and pushability in microcatheter designs.
- Polyethylene:Cost-sensitive variants gaining traction in hospital procurement frameworks constrained by budget pressure.
- Silicone:Specialized coating and balloon applications with limited structural shaft use.
Performance requirements favor polyurethane; procurement pressure favors polyethylene.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany exercise the least price elasticity, while polyethylene adoption in India signals acute budget sensitivity. The United States and Japan occupy intermediate positions where reimbursement scale offsets material cost premiums.
United States
Comprehensive stroke center networks in academic medical centers concentrate catheter procurement through standardized device protocols. FDA 510(k) premarket notification pathways govern clearance timelines for novel catheter geometries. The Greater Boston and Pacific Northwest clusters host preclinical validation sites driving early adoption of hydrophilic coating chemistries.
Germany
University hospital procurement committees standardize on two-vendor catheter portfolios with minimal price negotiation leverage for suppliers. EU MDR technical documentation requirements reshape market access economics for legacy and new catheter lines alike. The Baden-Württemberg industrial corridor anchors precision polymer compounding for medical-grade polyurethane shaft production.
Japan
METI-supported scaling of comprehensive stroke center networks concentrates demand for thrombectomy delivery systems in designated metropolitan zones. PMDA consultation pathways accelerate review timelines for breakthrough-designated catheter technologies. The Kanto region around Tokyo hosts the highest density of interventional neuroradiology training programs.
India
CDSCO regulatory harmonization with international standards opens procedural access for catheter-based thrombectomy in underserved stroke corridors across Maharashtra and Karnataka. Central government health insurance expansion creates reimbursement infrastructure for mechanical thrombectomy in tier-1 cities. Hospital procurement in Delhi-NCR and Mumbai demonstrates acute polyethylene preference under budget-constrained frameworks.
United Kingdom
NHS England specialized commissioning frameworks concentrate neurovascular intervention in designated neuroscience centers across London and the Midlands. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific submissions. The Oxford-Cambridge-London golden triangle hosts clinical trial infrastructure for distal access microcatheter validation.
Neurovascular Access Catheters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in neurovascular access catheters. Stryker Corporation and Medtronic Plc leverage captive polymer compounding and full-stack manufacturing to control cost structures across guide catheter lines. Penumbra, Inc and Terumo Corporation occupy the specialist tier with focused distal access and microcatheter portfolios. The dominant competitive moves are backward integration into medical-grade polyurethane supply and direct hospital system contracting to bypass distributor networks.
Among the integrated tier, Stryker Corporation and Medtronic Plc exemplify full-stack manufacturers with in-house control over braided shaft production and hydrophilic coating processes. Penumbra, Inc represents the specialist archetype, occupying a position defined by trackable microcatheter engineering for tortuous vasculature navigation. These three companies anchor the competitive structure, with their respective positions reflecting divergent capital-intensity strategies in catheter shaft manufacturing.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic Plc |
| Johnson & Johnson |
| Integer Holdings Corporation |
| Penumbra, Inc |
| Terumo Corporation |
| Biomerics |
| Imperative Care Inc |
| Integra LifeSciences Corporation |
| Others |
Supply & Pricing Matrix
FDA 510(k) premarket notification pathways and EU MDR technical documentation requirements simultaneously gate supplier qualification and stratify catheter pricing across premium polyurethane and cost-sensitive polyethylene tiers. Academic medical centers in the United States and university hospital committees in Germany leverage consolidated procurement volumes to compress margins on standard guide catheters while paying premiums for distal access microcatheters with breakthrough-designated trackability features.
Pricing Analysis
After-sales service contracts and extended warranty bundles for hydrophilic coating replenishment drive lifetime value beyond initial catheter unit sales. Three-tier pricing structure across premium, standard, and economy levels separates integrated manufacturers with captive polymer compounding from specialists dependent on external material supply. Price differentiation hinges on FDA breakthrough designation status and ISO 13485 certification tier. Cost compression in polyethylene variants is intensifying because hospital procurement committees in India and budget-constrained systems prioritize kink-resistant alternatives. Ambulatory surgical centers exhibit acute price sensitivity; comprehensive stroke centers in Japan show lowest elasticity due to METI-supported reimbursement scale.
Supply Chain Analysis
Medical-grade polyurethane resin concentration in the Baden-Württemberg industrial corridor and precision braiding equipment fabrication in Japan create dual chokepoints for catheter shaft production. Raw material dependencies center on medical-grade polyurethane pellets, braided nylon composite layers, and hydrophilic coating solvents sourced from Germany, Japan, and the United States. Single-source vulnerability in hydrophilic coating chemistry exposes manufacturers to EPA solvent-handling restriction delays. Distribution runs through specialized medical device distributors serving academic medical center networks, with direct hospital system contracting gaining share in consolidated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Catheter servicing contracts and coating replenishment subscriptions expand faster than hardware unit sales as hospitals lock in multi-year thrombectomy platform agreements. This service-attach dynamic repositions margin capture toward recurring revenue streams.
For Market Incumbents: Fortify backward integration into medical-grade polyurethane compounding to defend against feedstock cost volatility and specialist competitors. Lock in preferred vendor status with comprehensive stroke center networks through bundled thrombectomy system contracts. Deepen FDA breakthrough designation portfolios to sustain premium pricing against polyethylene substitution pressure. For New Entrants and Emerging Players: FDA 510(k) premarket notification fast-tracks for novel microcatheter geometries open procedural access in distal embolization workflows. Target underserved stroke corridors in Maharashtra and Karnataka where CDSCO regulatory harmonization is expanding reimbursement infrastructure. Lead with robotic-assisted delivery compatibility to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: EU MDR conformity assessment deadlines reshape the acquisition landscape by elevating compliance cost burdens for legacy catheter portfolios. Five-to-ten-year viability favors targets with captive polymer supply and established technical documentation libraries. Watch for PMDA breakthrough designation announcements as inflection indicators for Japanese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated 510(k) pathways compress launch timelines for distal access innovations. |
| EU MDR Technical Documentation | Clinical evidence portfolios for legacy lines reshape European market access economics. |
| Hospital System Partnership | Direct contracting with academic medical centers captures margin from distributor bypass. |
| Backward Integration | In-house polyurethane compounding controls shaft production cost structures. |
| Reimbursement Strategy | Medicare and national health service code alignment drives thrombectomy volume concentration. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with interventional neuroradiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement codes, and hospital procurement records. Bottom-up procedure volume modeling triangulated with top-down manufacturer revenue estimates across the forecast framework.
Across the analysis window, segmentation dimensions included catheter architecture, end-user facility type, clinical application, and material composition alongside regional regulatory cluster differentiation. CAGRs were derived from procedure volume trajectories and unit pricing dynamics. Forecast inputs incorporated METI stroke center scaling targets and CDSCO harmonization timelines.
Underlying assumptions cover reimbursement code stability and polymer feedstock supply continuity, with deviation risk concentrated in EU MDR compliance cost escalation and interventional neuroradiologist training pipeline constraints. Practitioners should keep alternative scenarios live as regulatory pathway timelines and hospital procurement consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hysterectomy Devices Market
Medical Devices
Tissue Expanders Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Organ Care Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Clinical Rollators Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Europe Spinal Surgery Devices Market