
 Asia-Pacific Breast Biopsy Market | 2026-2036
Asia-Pacific Breast Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Breast Biopsy Market Analytics
CE marking under the EU MDR is redrawing competitive access for Asia-Pacific manufacturers exporting to European-affiliated procurement networks in the region. Hologic Inc. leverages its integrated mammography-biopsy platform to dominate premium hospital installations across Australia and South Korea. BD sustains manufacturing scale across multiple needle formats, while Fujifilm Corporation specializes in ultrasound-guided systems that anchor its position in Japanese diagnostic imaging centers.
Breast biopsy encompasses tissue sampling procedures using hollow needles, vacuum-assisted probes, or image-guided instruments to extract cellular material for histopathological examination; specimens typically measure 1-2 centimeters and require formalin fixation for laboratory analysis. Vacuum-assisted biopsy systems command margin pools due to larger tissue yields per pass, while ultrasound guidance leads procedure volume across ambulatory surgical centers in the region. MRI guidance competes for complex lesion localization where X-ray mammography delivers insufficient contrast resolution.
Japan's PMDA, Australia's TGA, and India's CDSCO enforce divergent clinical evidence requirements that fragment product registration timelines and shape regional launch sequencing for device manufacturers. The EU AI Act's extraterritorial reach into algorithm-assisted imaging classification is forcing proactive compliance investments among Asia-Pacific software-enabled biopsy platforms. Stakeholders must monitor harmonization negotiations between ASEAN medical device directives and national regulators to anticipate streamlined market access pathways.
Market Dynamics
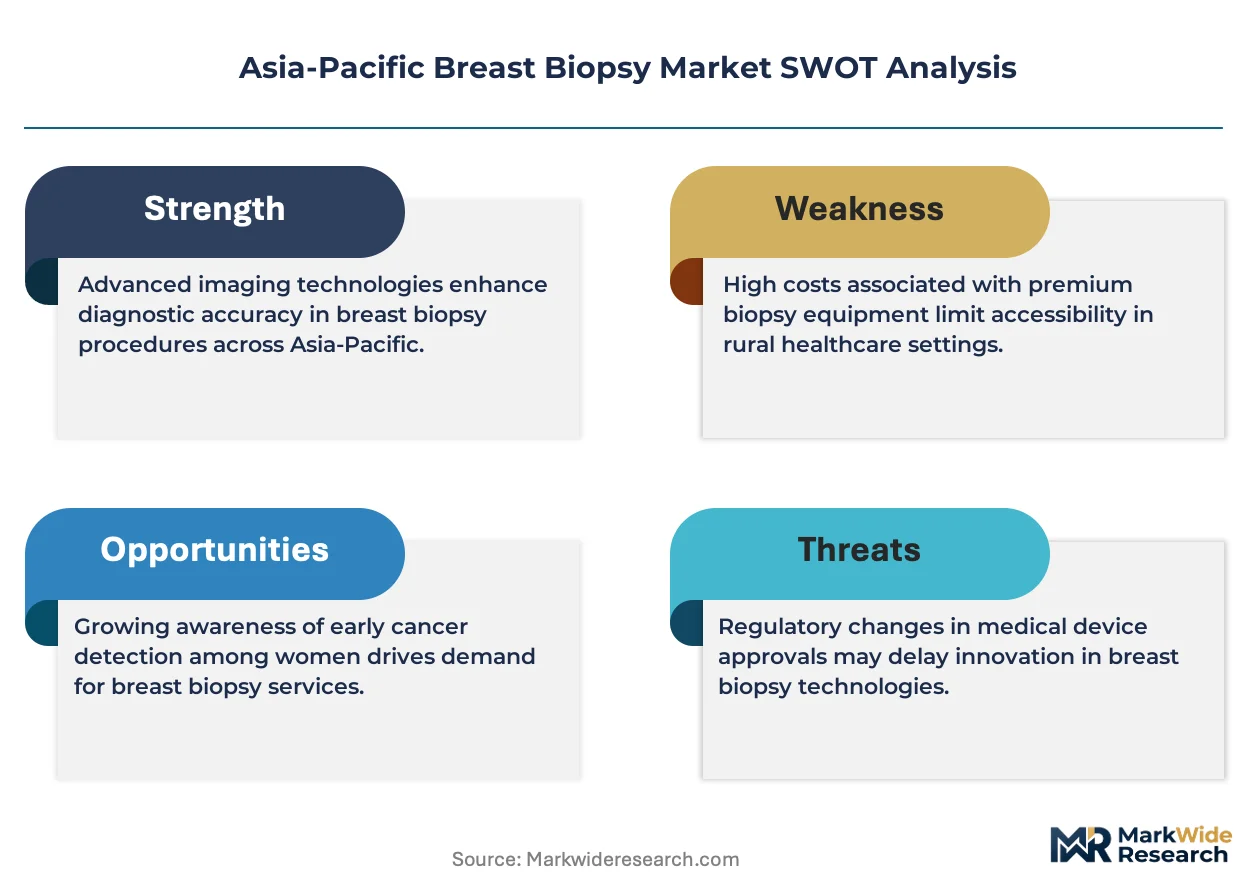
Vacuum-assisted biopsy systems are compressing open surgical excision volumes across tertiary hospitals in Australia, Japan, and South Korea as minimally invasive tissue yields approach diagnostic parity with surgical specimens.
Growth Catalysts
- Government screening mandates:India's CDSCO-aligned national breast cancer screening program is multiplying diagnostic imaging center networks in Maharashtra and Tamil Nadu.
- Ultrasound guidance penetration:Real-time imaging capabilities are displacing stereotactic X-ray systems in ambulatory surgical centers across Southeast Asia.
- PMDA pathway streamlining:Japan's regulator has compressed approval timelines for minimally invasive biopsy devices, accelerating product launches from domestic and foreign manufacturers.
Market Restraints
- Capital equipment intensity:MRI-compatible biopsy platforms require substantial upfront investment, limiting deployment to metropolitan tertiary centers in India and Indonesia.
- Specialist workforce scarcity:Interventional radiologists trained in image-guided core needle techniques concentrate in Tokyo, Seoul, and Sydney, leaving secondary cities underserved.
- Reimbursement fragmentation:Australia's TGA device registration does not guarantee uniform private insurer coverage, creating payment uncertainty for vacuum-assisted procedures.
Strategic Opportunities
- Vietnam and Philippines expansion:Diagnostic imaging infrastructure buildout in Ho Chi Minh City and Manila creates first-mover positioning for ultrasound-guided system vendors.
- AI-assisted lesion classification:Algorithm-enabled imaging platforms are converging with biopsy navigation systems to reduce sampling error rates in Japanese screening programs.
- Mobile screening units:Government procurement of truck-mounted mammography-biopsy combinations is opening channel innovation in rural India.
Industry Challenges
- CDSCO evidence requirements:India's regulator demands India-specific clinical data for novel biopsy devices, extending registration timelines by 18-24 months.
- Legacy PACS integration:Hospital information system interoperability gaps in Southeast Asia complicate digital pathology workflow adoption.
- Technician certification bottlenecks:Vacuum-assisted biopsy operation requires specialized training that outpaces institutional education capacity in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Breast Biopsy Market |
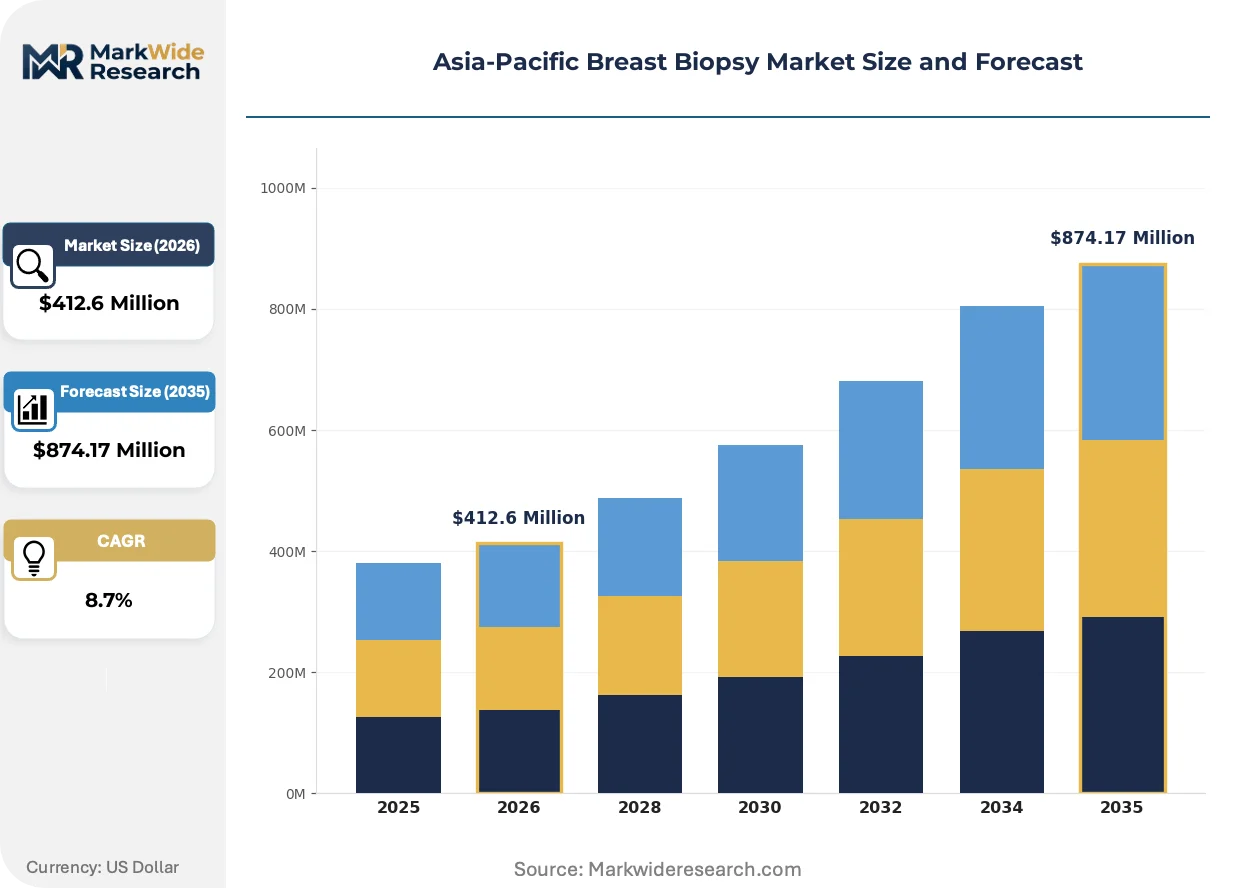
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Needle Biopsy, Vacuum-Assisted Biopsy, Fine Needle Aspiration, Stereotactic Biopsy Technology: Ultrasound Guidance, MRI Guidance, Stereotactic Guidance, X-ray Guidance End User: Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Research Laboratories Delivery Mode: Invasive, Non-Invasive, Outpatient, Integrated |
| Companies Covered | Hologic Inc., BD, Danaher Corporation, Argon Medical Devices Inc., Devicor Medical Products Inc., Merit Medical Systems Inc., Fujifilm Corporation, Sysmex Corp, Qiagen NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Breast Biopsy Market Evolving Landscape
Digital pathology connectivity and disposable single-use biopsy needle formats are restructuring capital-labor tradeoffs across Asia-Pacific healthcare systems. Three developments warrant particular attention.
Disposable core needle systems with integrated tissue acquisition chambers are displacing reusable instrument sterilization workflows in high-throughput Japanese diagnostic centers. Hospital infection control committees in Osaka and Fukuoka are mandating single-use formats to eliminate cross-contamination risk. This shift is compressing per-procedure labor costs while elevating consumables spending in procurement budgets.
Australia's TGA has aligned medical device cybersecurity requirements with the EU MDR's software validation standards, forcing firmware updates across installed imaging-guided biopsy platforms. Manufacturers must now submit penetration testing documentation for network-connected devices. The regulation most affects ultrasound-guided systems with cloud-based image storage, prompting vendors to establish local technical support presence in Sydney and Melbourne.
Consolidated purchasing by Australian and South Korean hospital networks is compressing vendor margins while demanding extended service contracts bundled with equipment sales. Procurement teams in Seoul's Asan Medical Center and Sydney's Royal Prince Alfred Hospital are unbundling maintenance from capital acquisition, selecting third-party service providers for post-warranty support. This behavioral shift is most visible in premium vacuum-assisted biopsy platform tenders, where total cost of ownership now dominates capital expenditure evaluation.
Asia-Pacific Breast Biopsy Market Segmentation
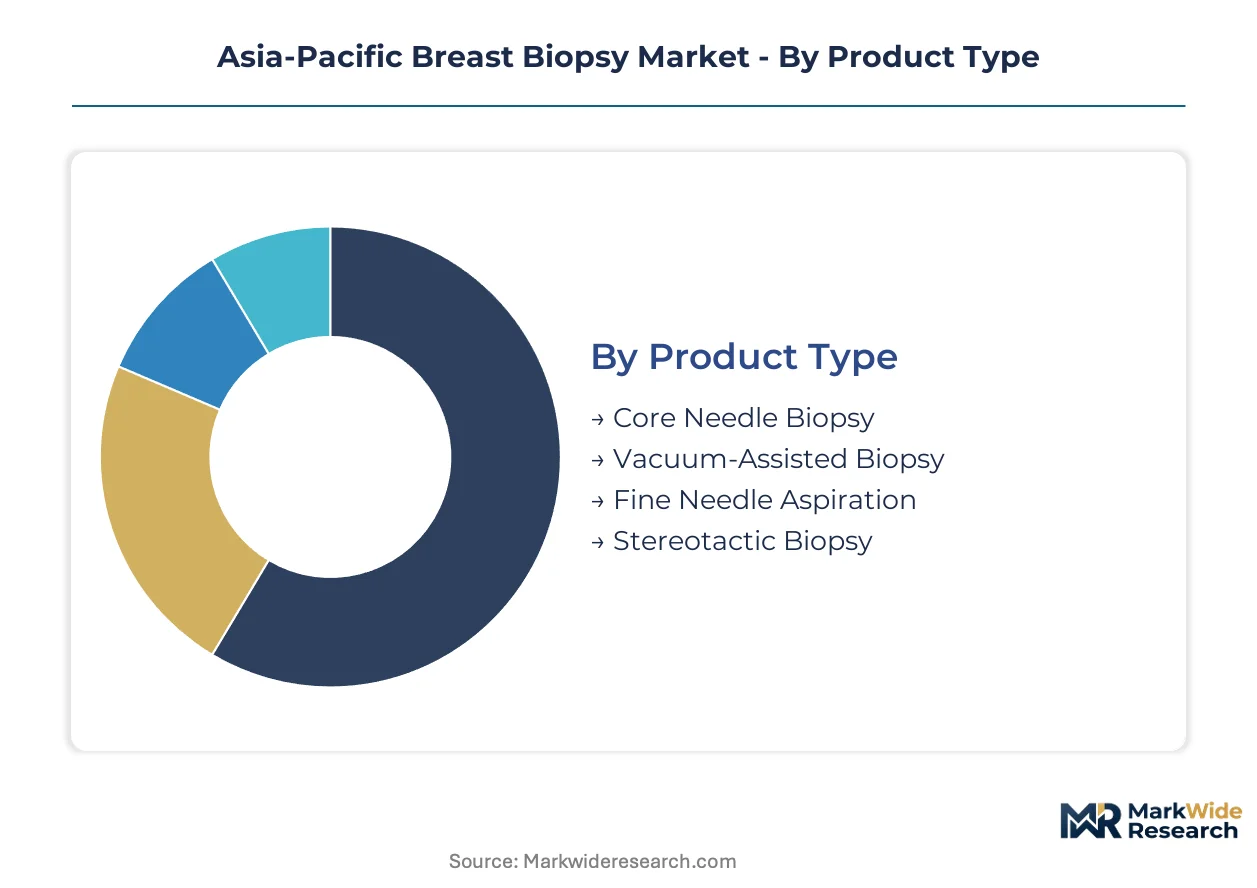
Segmentation in the Asia-Pacific breast biopsy market reveals how technology substitution pressures and capital intensity reshape procurement priorities across healthcare systems. Understanding these divisions clarifies where vacuum-assisted systems displace legacy formats and which guidance modalities concentrate in specific clinical settings.
Product Type:
Vacuum-assisted biopsy systems face the strongest substitution pressure from disposable core needle formats in cost-sensitive Indian and Indonesian hospital networks, while fine needle aspiration retains niche utility in resource-constrained rural screening programs.
- Core Needle Biopsy:Hollow needles extract tissue samples through single-pass insertion, typically yielding 1-2 centimeter specimens requiring formalin fixation. Demand concentrates in Maharashtra and Tamil Nadu diagnostic imaging centers where CDSCO procurement guidelines prioritize capital efficiency over per-procedure tissue volume.
- Vacuum-assisted Biopsy:Continuous suction probes acquire larger tissue volumes through single insertion points, approaching surgical specimen diagnostic parity. Premium hospital installations across Australia and South Korea favor this format for lesion characterization in government-funded screening programs.
- Fine Needle Aspiration:21-25 gauge needles extract cellular material for cytological examination without intact tissue architecture. Mobile screening units in rural India deploy this format where pathology infrastructure cannot support histological processing.
- Stereotactic Biopsy:X-ray guided coordinate targeting systems for non-palpable lesions. Metropolitan tertiary centers in Tokyo and Seoul maintain installed bases despite ultrasound displacement trends.
Core needle biopsy anchors the volume base while vacuum-assisted biopsy gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium MRI-compatible platforms from standard ultrasound systems, with reimbursement bandwidth determining adoption ceilings across public and private hospital networks.
- Ultrasound Guidance:Real-time imaging enables dynamic needle visualization without ionizing radiation exposure. Ambulatory surgical centers across Southeast Asia favor this modality for same-day discharge protocols in Ho Chi Minh City and Manila.
- MRI Guidance:Magnetic resonance targeting resolves lesions invisible to mammography in dense breast tissue. Australia's TGA-registered platforms concentrate in Sydney and Melbourne metropolitan networks where private insurance covers premium procedures.
- Stereotactic Guidance:Computerized X-ray coordinate systems for calcification targeting. Aging installed bases in Japanese diagnostic imaging centers face replacement decisions against ultrasound alternatives.
- X-ray Guidance:Fluoroscopic or mammographic visualization for interventional procedures. Secondary city hospitals in Indonesia retain this format where ultrasound technician certification remains limited.
Ultrasound guidance dominates procedure volume while MRI guidance expands most quickly in affluent metropolitan markets.
End User:
Customer type fragmentation reflects divergent capital availability, with government procurement patterns separating hospital network investments from independent diagnostic center equipment decisions.
- Hospitals:Integrated care settings with in-house pathology laboratories and surgical oncology backup. Tertiary centers across Australia, Japan, and South Korea deploy full modality suites for comprehensive lesion management.
- Diagnostic Imaging Centers:Specialized facilities with high-throughput screening mandates. CDSCO-aligned networks in Maharashtra and Tamil Nadu multiply under India's national breast cancer screening program expansion.
- Ambulatory Surgical Centers:Same-day procedure venues emphasizing throughput and capital efficiency. Southeast Asian markets in Vietnam and Philippines represent emerging channel opportunities.
- Research Laboratories:Academic medical centers conducting tissue banking and biomarker studies. PMDA-streamlined approval pathways accelerate device evaluation in Japanese university hospitals.
Diagnostic imaging centers anchor the volume base while ambulatory surgical centers climb the fastest as care decentralization accelerates.
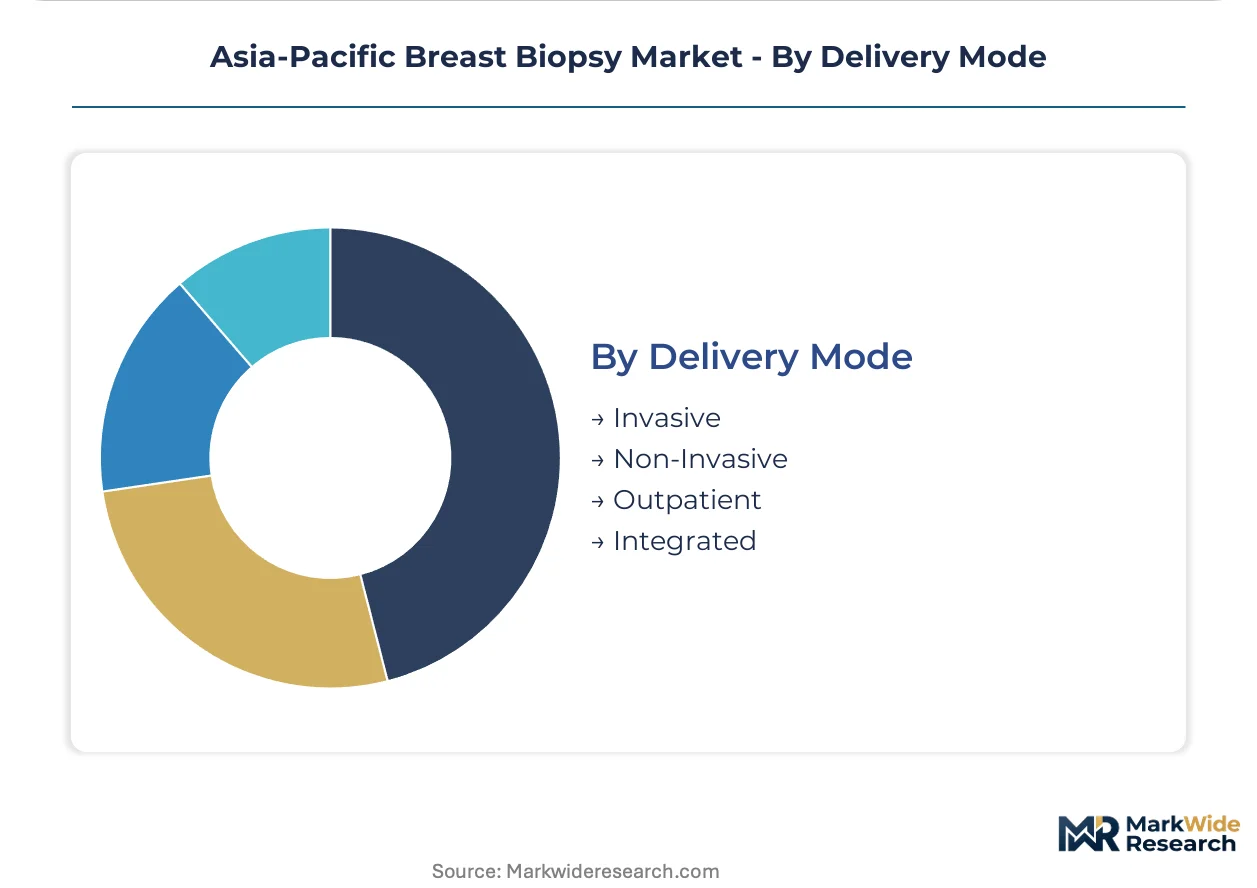
Delivery Mode:
Maturity gradients separate established invasive formats from emerging non-invasive alternatives, with regulatory evidence requirements determining commercialization timelines.
- Invasive:Tissue-disrupting procedures including needle biopsy and surgical excision. Current standard of care across all Asia-Pacific reimbursement systems with established clinical evidence bases.
- Non-Invasive:Blood-based liquid biopsy and advanced imaging surrogates. Early-stage development with limited CDSCO and PMDA approval pathways for diagnostic claims.
- Outpatient:Same-day discharge protocols without overnight admission. Australian and South Korean hospital networks optimize scheduling around this delivery format.
- Integrated:Combined mammography-biopsy platforms with single-session diagnosis-to-tissue acquisition. Hologic's installed base across Australian premium hospital installations exemplifies this approach.
Invasive delivery anchors the volume base while integrated systems gain share at the steepest rate in consolidated purchasing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government screening mandates and regulator pathway streamlining are redrawing procurement geography across the Asia-Pacific region. National health programs in India and Japan are accelerating diagnostic infrastructure deployment, while Australia's consolidated hospital networks reshape vendor access patterns.
India
CDSCO-aligned national breast cancer screening programs are multiplying diagnostic imaging center networks in Maharashtra and Tamil Nadu. The regulator demands India-specific clinical data for novel biopsy devices, extending registration timelines. Mobile screening units with truck-mounted mammography-biopsy combinations are penetrating rural districts where pathology infrastructure remains limited.
Japan
PMDA has compressed approval timelines for minimally invasive biopsy devices, accelerating product launches from domestic and foreign manufacturers. University hospitals in Tokyo and Osaka leverage streamlined pathways for device evaluation in government-funded screening programs. Disposable single-use biopsy needle formats are displacing reusable instrument sterilization workflows in high-throughput diagnostic centers.
Australia
TGA-aligned medical device cybersecurity requirements are forcing firmware updates across installed imaging-guided biopsy platforms. Consolidated purchasing by hospital networks in Sydney and Melbourne is compressing vendor margins while demanding extended service contracts. Private insurance coverage gaps create payment uncertainty for vacuum-assisted procedures despite device registration.
South Korea
MFDS-regulated premium hospital installations favor vacuum-assisted biopsy systems for lesion characterization in national screening programs. Procurement teams at Seoul's Asan Medical Center are unbundling maintenance from capital acquisition. Third-party service providers are capturing post-warranty support contracts previously held by equipment manufacturers.
Vietnam
Diagnostic imaging infrastructure buildout in Ho Chi Minh City creates first-mover positioning for ultrasound-guided system vendors. Government procurement of screening equipment is expanding beyond metropolitan hospitals into provincial facilities. Ambulatory surgical centers favor same-day discharge protocols enabled by real-time imaging capabilities.
Asia-Pacific Breast Biopsy Market Competitive Landscape
Player mix skews toward integrated diagnostic platform vendors and specialized needle manufacturers. Market structure concentrates around three to four dominant equipment suppliers with established service networks, while consumables segments fragment across regional fabricators. Two strategic archetypes prevail: integrated mammography-biopsy platform vendors leveraging hardware-software bundling, and specialized needle format manufacturers competing on manufacturing scale. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into disposable single-use formats.
Within the integrated platform tier, Hologic Inc. and Fujifilm Corporation exemplify equipment-software bundling strategies that anchor premium hospital installations. BD occupies a position among scale-driven needle format specialists with manufacturing breadth across multiple product configurations. These three entities represent the competitive anchors around which regional procurement negotiations and service contract unbundling dynamics currently revolve.
| Leading Market Players |
|---|
| Hologic Inc. |
| BD |
| Danaher Corporation |
| Argon Medical Devices Inc. |
| Devicor Medical Products Inc. |
| Merit Medical Systems Inc. |
| Fujifilm Corporation |
| Sysmex Corp |
| Qiagen NV |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for vacuum-assisted biopsy systems signal how concentrated manufacturing in Japan and South Korea amplifies pricing power for integrated platform vendors serving Australian hospital networks. Procurement teams in Sydney and Melbourne face limited alternative sourcing when lead times stretch, compressing their negotiating leverage against premium-tier suppliers.
Pricing Analysis
Certification level (PMDA/TGA/CDSCO-grade) creates the primary spread between premium vacuum-assisted platforms and economy core needle formats across Asia-Pacific procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects divergent clinical evidence requirements, with India's CDSCO-mandated India-specific trials adding 18-24 month cost premiums to novel device registrations. Cost compression in standard-tier ultrasound-guided systems is intensifying because consolidated hospital networks in Seoul and Sydney are unbundling service contracts from capital sales. Diagnostic imaging centers in Maharashtra and Tamil Nadu exhibit highest price sensitivity, while Tokyo's university hospitals demonstrate lowest sensitivity due to government-funded screening program budgets.
Supply Chain Analysis
Just-in-time inventory strategies dominate for disposable needle formats in high-throughput Japanese diagnostic centers, whereas strategic stockpiling of MRI-compatible biopsy platforms occurs in Australian metropolitan networks facing TGA cybersecurity firmware update delays. Manufacturing concentrates in Japan, South Korea, and the United States for precision-engineered vacuum-assisted probes and guidance systems. Supply chains draw from medical-grade stainless steel feedstock, specialized polymer housings, and high-resolution imaging sensor arrays. Single-source vulnerability persists for PMDA-approved minimally invasive device components where domestic Japanese manufacturers hold regulatory exclusivity. Distribution runs through authorized dealer networks with mandatory technician certification programs, particularly in Vietnam and Philippines expansion markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across Asia-Pacific breast biopsy markets as Australian hospital networks consolidate procurement functions and Indian state governments centralize CDSCO-aligned screening equipment tenders. This consolidation fragments vendor access channels and compresses margin pools for equipment manufacturers.
For Market Incumbents: Fortify service network density in Sydney, Melbourne, and Seoul to defend against third-party maintenance providers capturing post-warranty vacuum-assisted biopsy support contracts. Deepen backward integration into disposable needle manufacturing to offset procurement teams unbundling consumables from platform sales, while accelerating PMDA-streamlined approval pathways for next-generation ultrasound-guided systems before emerging entrants establish regulatory dossiers. For New Entrants and Emerging Players: CDSCO fast-track certification for core needle biopsy formats offers the most penetrable entry point into Maharashtra and Tamil Nadu diagnostic imaging center networks multiplying under India's national screening program. Target ambulatory surgical centers in Ho Chi Minh City and Manila where ultrasound technician certification gaps create first-mover positioning for simplified guidance platforms. Partner with established Japanese distributors to leverage PMDA regulatory consulting capabilities and accelerate product launch sequencing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable single-use biopsy needle segments as sterilization workflow elimination reduces per-procedure infrastructure requirements. Five-to-ten year viability favors specialized needle format manufacturers with manufacturing scale across multiple gauge configurations and established GPO contracts in Australian hospital networks. Monitor ASEAN medical device directive harmonization negotiations as the inflection signal for streamlined market access and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Fast-Track Approval | Accelerates product launches for minimally invasive biopsy devices in Japanese university hospitals. |
| CDSCO Registration Investment | Unlocks government-funded procurement channels in Maharashtra and Tamil Nadu screening networks. |
| Hospital System Partnership | Secures preferred vendor status amid consolidated purchasing by Sydney and Melbourne networks. |
| Software Companion Development | Addresses EU AI Act extraterritorial compliance for algorithm-assisted imaging classification platforms. |
| Reimbursement Strategy | Closes private insurance coverage gaps for vacuum-assisted procedures in Australian tertiary centers. |
Research Methodology
Desk research of PMDA approval databases, CDSCO registration filings, and hospital procurement records preceded structured interviews with interventional radiologists, biomedical engineers, GPO contracts managers, and diagnostic imaging center operations directors. Secondary validation drew from TGA medical device cybersecurity advisories, ASEAN medical device directive harmonization documentation, and Medicare Australia reimbursement schedules. Bottom-up procedure volume estimates across India, Japan, Australia, South Korea, and Vietnam were triangulated against top-down market sizing from equipment shipment data.
Variance decomposition across product type, guidance technology, end-user facility class, and national regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating government screening mandate expansion timelines, PMDA pathway streamlining impacts, and ultrasound technician certification capacity constraints. Forecast inputs included CDSCO-aligned diagnostic imaging center network buildout rates in Maharashtra and Tamil Nadu, and mobile screening unit procurement trajectories in rural Indian districts.
Underlying assumptions cover sustained government funding for national breast cancer screening programs, with deviation risk concentrated in reimbursement fragmentation for vacuum-assisted procedures and CDSCO evidence requirement extensions for novel devices. Practitioners should keep alternative scenarios live as ASEAN harmonization negotiations and EU AI Act enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Infertility Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Deaver Retractor Market
Medical Devices
Neurostimulation Market