
 APAC Ablation Devices Market | 2026-2036
APAC Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Ablation Devices Market Outlook
Radiofrequency electrode materials are consolidating around gold-plated and platinum-iridium alloys, displacing older nickel-titanium compositions in premium catheter designs. Abbott Laboratories leverages its structural heart portfolio to anchor electrophysiology catheter supply across Japanese university hospitals. Medtronic PLC sustains manufacturing scale in microwave ablation systems for hepatic oncology through its Greater China distribution infrastructure. Boston Scientific Corporation specializes in cryoballoon platforms for atrial fibrillation, competing directly with catheter-based radiofrequency alternatives in Australian cardiac centers.
APAC ablation devices are instruments that deliver thermal, electrical, or mechanical energy to destroy pathological tissue through percutaneous or laparoscopic access, typically operating at frequencies between 460 and 500 kHz for radiofrequency systems with tip temperatures reaching 60 to 100 degrees Celsius. These devices serve primarily to treat cardiac arrhythmias, solid tumors, and chronic pain while minimizing collateral tissue damage. Radiofrequency ablation occupies the largest revenue pool across the region due to established reimbursement in cardiology, while cryoablation segments are capturing faster procedural growth in pulmonary vein isolation. Robotic technology integration is reshaping capital equipment purchasing patterns as hospitals evaluate imaging-guided surgical platforms against conventional electrophysiology lab configurations.
Japan's PMDA and Australia's TGA enforce divergent electromagnetic compatibility standards for active implantable accessories, compelling manufacturers to maintain separate device registrations and testing protocols. China's NMPA requires domestic clinical trial data for novel energy modalities, extending market entry timelines for microwave and irreversible electroporation systems. India's CDSCO has tightened import licensing for reusable ablation generators, redirecting procurement toward disposable catheter bundles. Stakeholders must monitor regulatory divergence between Northeast Asian and Southeast Asian approval frameworks when allocating regional product development resources.
Market Dynamics
Robotic integration into hybrid operating rooms is compressing capital equipment replacement cycles across tertiary cardiac centers, forcing electrophysiology device manufacturers to bundle imaging guidance with ablation platforms rather than sell standalone catheters.
Growth Catalysts
- Japan's PMDA Streamlined Pathways:Accelerated approval timelines for minimally invasive electrophysiology devices are expanding patient access to atrial fibrillation treatments in university hospital networks.
- Hybrid OR Installations:Tier-one Chinese cities are multiplying integrated surgical suites, creating bundled demand for imaging-compatible ablation systems in cardiovascular service lines.
- Gold-Plated Electrode Migration:Radiofrequency catheter materials are consolidating around platinum-iridium alloys, improving thermal precision and reducing procedure variability in pulmonary vein isolation.
Market Restraints
- Domestic Clinical Trial Mandates:China's NMPA requires local efficacy data for microwave and irreversible electroporation systems, extending market entry timelines by 18-24 months for novel energy modalities.
- Reusable Generator Licensing:India's CDSCO tightened import permits for refurbished ablation power units, redirecting hospital procurement toward higher-cost disposable catheter bundles.
- Electromagnetic Compatibility Divergence:Japan's PMDA and Australia's TGA enforce non-harmonized testing protocols for active implantable accessories, compelling manufacturers to maintain separate device registrations.
Strategic Opportunities
- Southeast Asia Expansion:Underpenetrated markets in Vietnam and Indonesia present first-mover advantages for cryoballoon platforms as cardiac service lines mature in Ho Chi Minh City and Jakarta.
- Pain Management Diversification:Chronic pain applications for radiofrequency ablation remain underdeveloped relative to cardiology, offering procedural volume growth in Australian ambulatory surgical centers.
- Robotic-Assisted Integration:Convergence of electrophysiology mapping with magnetic navigation systems is creating premium pricing tiers for catheter ablation in Japanese and South Korean quaternary hospitals.
Industry Challenges
- Electrophysiology Talent Scarcity:Complex three-dimensional mapping procedures require specialized operator training that outpaces fellowship program expansion across the region's medical schools.
- Legacy System Interoperability:New ablation platforms must integrate with installed imaging and electronic medical record infrastructure, complicating hospital technology refresh decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Ablation Devices Market |
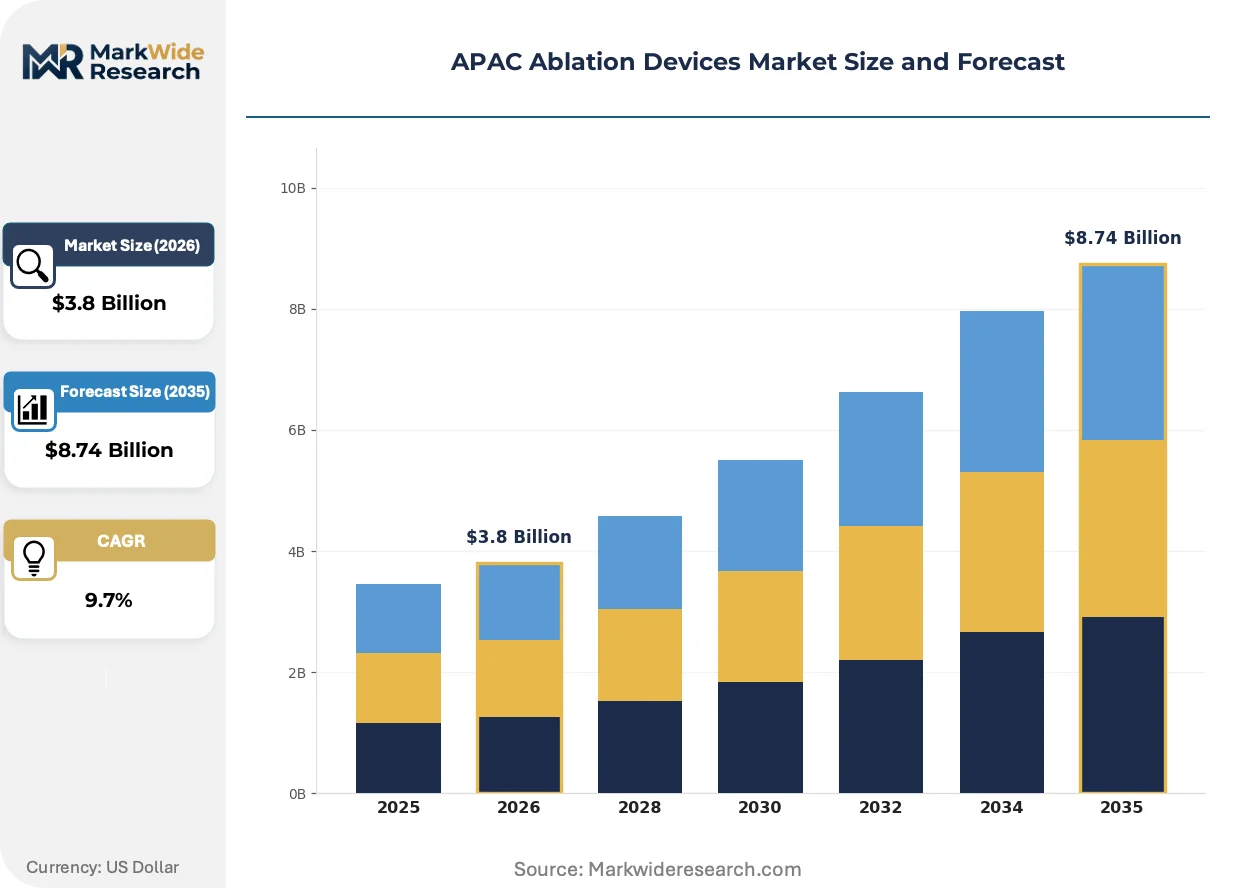
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency Ablation, Laser Ablation, Cryoablation, Microwave Ablation End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Technology: Electrophysiology, Surgical, Imaging, Robotic Application: Oncology, Cardiovascular, Gastroenterology, Pain Management |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic PLC, Johnson & Johnson, Olympus Corporation, Conmed Corporation, AtriCure Inc, AngioDynamics, Smith & Nephew PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Ablation Devices Market Strategic Shifts
Energy modality diversification and procedural automation are converging to redefine competitive positioning in cardiac and oncology ablation, with manufacturers racing to secure regulatory clearances for next-generation platforms ahead of hospital capital budget cycles.
Pulsed field ablation is electrifying atrial fibrillation treatment paradigms by delivering irreversible electroporation without thermal collateral damage. Japanese quaternary centers are piloting these systems for pulmonary vein isolation, compressing the addressable market for conventional radiofrequency catheter sales in premium cardiac segments.
Australia's TGA adopted str electromagnetic compatibility standards for active implantable accessories in alignment with evolving IEC frameworks, forcing manufacturers to retest legacy product lines. Cardiac ablation catheter suppliers with existing Australian registrations face compressed margins from compliance recertification costs while new entrants confront extended approval timelines.
Hospital buying committees are consolidating vendor relationships around full-platform contracts that bundle generators, catheters, and service agreements. Australian and South Korean cardiac centers increasingly favor single-source procurement for electrophysiology labs, displacing the previous multi-vendor equipment mix and concentrating purchasing power with integrated system suppliers.
APAC Ablation Devices Market Segmentation
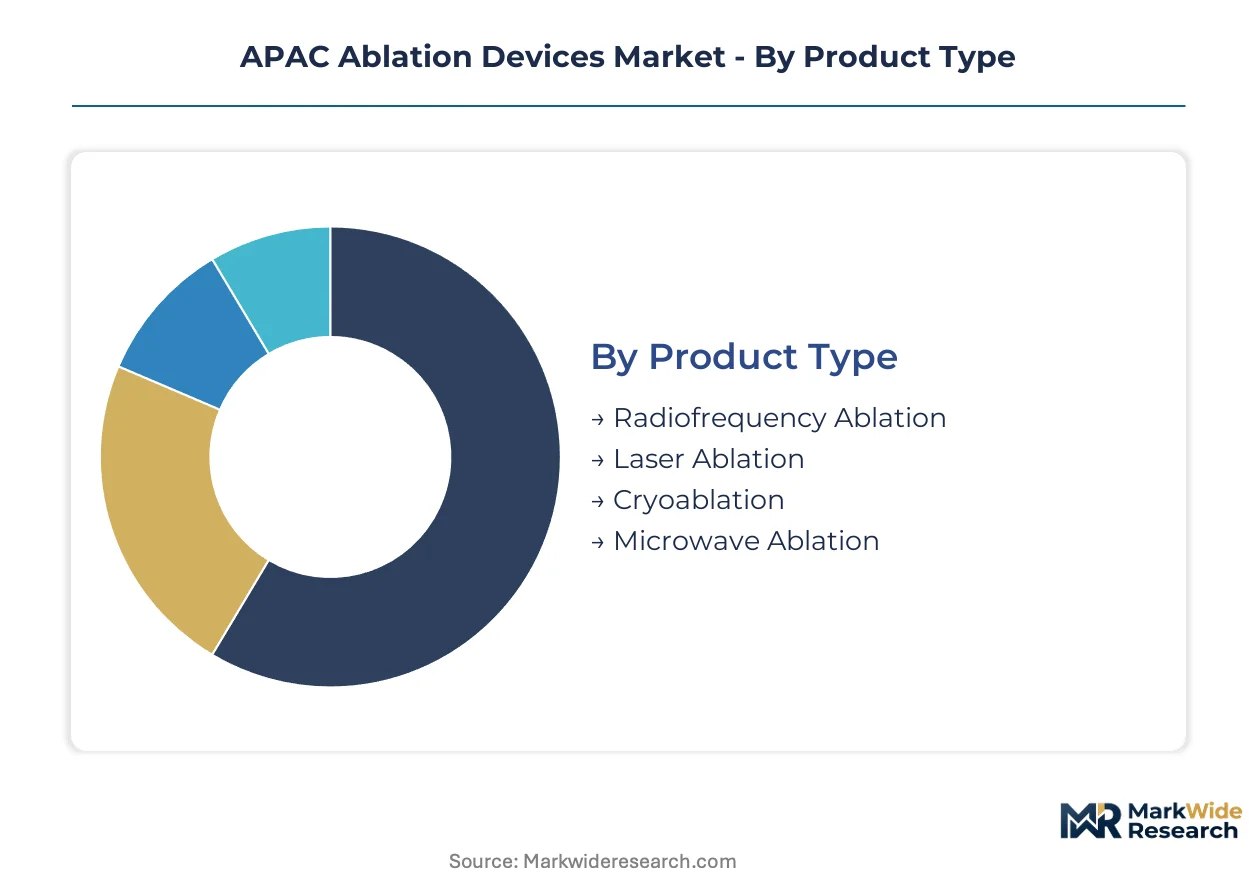
Segmentation in APAC ablation devices reveals divergent technology maturities and purchasing power concentrations across healthcare infrastructure tiers. Each dimension exposes distinct entry barriers and margin architectures for manufacturers navigating regulatory heterogeneity.
Product Type:
Radiofrequency systems dominate standalone electrophysiology lab configurations, while cryoablation and microwave platforms increasingly embed within hybrid surgical suites requiring imaging integration.
- Radiofrequency Ablation:Gold-plated and platinum-iridium electrode configurations deliver thermal energy at 460-500 kHz with tip temperatures reaching 60-100 degrees Celsius. Japanese university hospitals anchor demand for premium catheter designs with reduced procedure variability in pulmonary vein isolation.
- Cryoablation:Cryoballoon platforms deliver nitrous oxide-mediated tissue freezing for atrial fibrillation treatment without thermal collateral damage. Australian cardiac centers are expanding procedural volumes for pulmonary vein isolation, displacing catheter-based radiofrequency alternatives in select patient cohorts.
- Laser Ablation:Solid-state and diode laser systems target ophthalmic and dermatological applications with precise wavelength control.
- Microwave Ablation:Electromagnetic field generators at 915 MHz and 2.45 GHz target hepatic oncology with larger ablation zones.
Volume placements concentrate in Radiofrequency Ablation; the faster expansion belongs to Cryoablation.
End User:
Capital equipment purchasing authority fragments across facility types with divergent reimbursement structures and procedure complexity thresholds.
- Hospitals:Tertiary and quaternary cardiac centers in China's tier-one cities are multiplying hybrid operating room installations, creating bundled demand for imaging-compatible ablation systems. Japan's PMDA streamlined approval pathways specifically target university hospital networks for minimally invasive electrophysiology device uptake.
- Ambulatory Surgical Centers:Australian day-surgery facilities are expanding radiofrequency ablation for chronic pain management with streamlined patient throughput. These centers prioritize disposable catheter bundles over reusable generator investments due to lower capital allocation thresholds.
- Clinics:Outpatient settings concentrate dermatological and minor pain management procedures.
- Research Institutions:Academic medical centers pilot pulsed field ablation and irreversible electroporation platforms.
Revenue concentration sits with Hospitals; Ambulatory Surgical Centers are climbing the fastest.
Technology:
System architectures range from standalone energy delivery to fully integrated surgical platforms with magnetic navigation capabilities.
- Electrophysiology:Three-dimensional mapping systems with contact force sensing dominate atrial fibrillation treatment workflows. South Korean quaternary hospitals are adopting robotic-assisted electrophysiology mapping for premium catheter ablation pricing tiers.
- Robotic:Magnetic navigation and remote catheter manipulation systems compress capital equipment replacement cycles across Japanese and South Korean cardiac centers. These platforms force manufacturers to bundle imaging guidance with ablation catheters rather than sell standalone devices.
- Surgical:Laparoscopic and percutaneous delivery systems target solid tumor applications.
- Imaging:Intraoperative ultrasound and CT guidance systems enable real-time ablation monitoring.
Installed base dominance belongs to Electrophysiology; steepest expansion trajectory attaches to Robotic integration.
Application:
Clinical indications span cardiac rhythm management, oncological intervention, and neurological pain modulation with distinct regulatory pathways per therapeutic area.
- Cardiovascular:Atrial fibrillation ablation consumes the largest procedural volume across Japanese and Australian electrophysiology labs. Pulsed field ablation pilots in Japanese quaternary centers are compressing addressable market scope for conventional thermal modalities in premium segments.
- Oncology:Hepatic, renal, and lung tumor ablation leverages microwave and radiofrequency systems through Medtronic's Greater China distribution infrastructure. China's NMPA requires domestic clinical trial data for microwave systems, extending market entry timelines.
- Pain Management:Radiofrequency ablation for chronic back and joint pain remains underdeveloped relative to cardiology, offering procedural volume growth in Australian ambulatory settings.
- Gastroenterology:Endoscopic radiofrequency and cryoablation target Barrett's esophagus and pancreatic lesions.
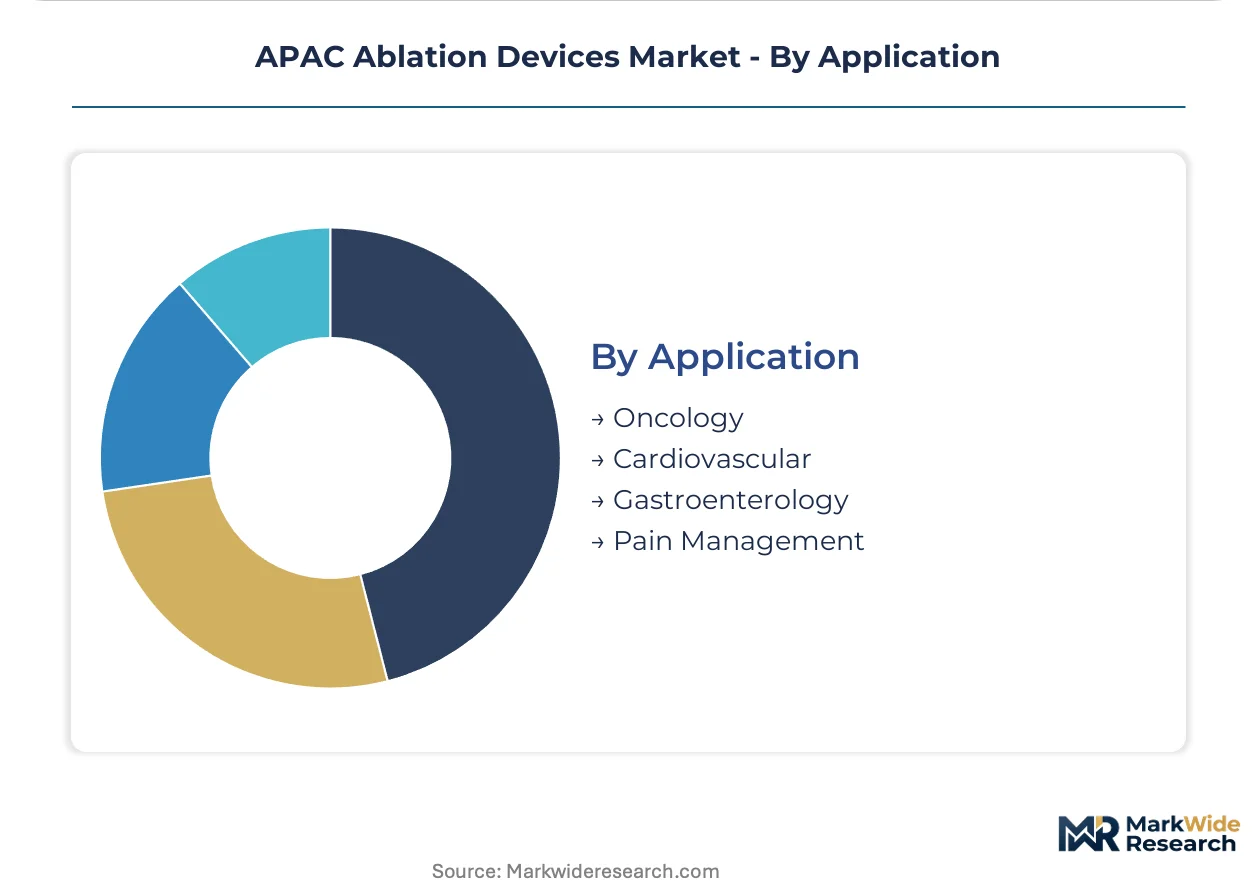
Procedure volume concentrates in Cardiovascular; Pain Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities concentrate hybrid operating room demand while Japan's university hospital networks anchor premium electrophysiology catheter consumption. Regulatory divergence across Northeast and Southeast Asia fragments approval timelines and testing protocols.
China
Shanghai and Beijing cardiac centers are multiplying hybrid surgical suite installations, creating bundled procurement for imaging-compatible ablation systems. NMPA requires domestic clinical trial data for microwave and irreversible electroporation platforms, extending market entry timelines by 18-24 months. Medtronic sustains manufacturing scale for hepatic oncology applications through its Greater China distribution infrastructure.
Japan
Quaternary hospitals in Tokyo and Osaka pilot pulsed field ablation systems for pulmonary vein isolation, compressing conventional radiofrequency catheter addressable markets. PMDA streamlined approval pathways specifically target university hospital networks for minimally invasive electrophysiology device uptake. Abbott Laboratories leverages its structural heart portfolio to anchor catheter supply across these institutions.
Australia
Ambulatory surgical centers in Sydney and Melbourne expand radiofrequency ablation for chronic pain management with streamlined patient throughput. TGA adopted stricter electromagnetic compatibility standards for active implantable accessories, forcing manufacturers to retest legacy product lines. Boston Scientific competes with cryoballoon platforms against catheter-based radiofrequency alternatives in cardiac centers.
South Korea
Seoul's quaternary hospitals are adopting robotic-assisted electrophysiology mapping for premium catheter ablation pricing tiers. MFDS enforces device registration requirements that align with evolving IEC frameworks for active implantable accessories. Magnetic navigation systems are compressing capital equipment replacement cycles across the country's cardiac centers.
India
Metro hospital networks in Mumbai and Delhi redirect procurement toward disposable catheter bundles following CDSCO's tightened import licensing for reusable ablation generators. Chronic pain applications remain underdeveloped relative to cardiology, offering procedural volume growth potential. Domestic manufacturing incentives are reshaping supply chain configurations for entry-level radiofrequency systems.
APAC Ablation Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated system suppliers capturing bundled procurement contracts while component-focused players serve replacement catheter demand. The vendor base concentrates around four to six multinational corporations with established electrophysiology portfolios, supplemented by regional distributors handling regulatory navigation and service localization. Two strategic archetypes dominate: full-platform providers bundling generators, catheters, and imaging guidance; and modality specialists concentrating on single energy technologies. Competitive moves center on hospital buying committee consolidation around single-source contracts and regulatory pre-clearance racing for next-generation energy modalities.
Among the established multinational tier, Abbott Laboratories, Boston Scientific Corporation, and Medtronic PLC represent the dominant full-platform archetype across Japanese and Australian cardiac centers. These entities occupy positions where hospital vendor consolidation favors integrated system suppliers over multi-vendor equipment mixes. Their geographic footprints span the region's tier-one hospital networks, with regulatory registrations anchoring competitive positioning in PMDA and TGA jurisdictions.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic PLC |
| Johnson & Johnson |
| Olympus Corporation |
| Conmed Corporation |
| AtriCure Inc |
| AngioDynamics |
| Smith & Nephew PLC |
| Others |
Value Chain & Pricing Dynamics
University hospital procurement committees in Japan and Australia's cardiac centers concentrate purchasing authority, anchoring contract-based bundled pricing for imaging-compatible ablation platforms rather than transactional catheter sales.
Pricing Analysis
High-volume disposable catheter bundles trade at compressed margins while integrated robotic-electrophysiology platforms command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates platinum-iridium electrode configurations from nickel-titanium legacy designs. Pricing pressure stems from India's CDSCO restrictions on reusable generator imports, redirecting procurement toward higher-cost disposable bundles. Ambulatory surgical centers in Australia exhibit greatest price sensitivity, while Japanese quaternary hospitals prioritize thermal precision over unit cost.
Supply Chain Analysis
Reverse-logistics flows for refurbished ablation generators face regulatory friction under India's tightened CDSCO import licensing, compressing secondary market circulation. Manufacturing concentrates in China, Japan, and the United States, with platinum-iridium electrode materials drawing from specialized metallurgical suppliers. Single-source vulnerability attaches to cryoballoon nitrous oxide delivery systems. Distribution runs through Medtronic's Greater China infrastructure and Abbott's Japanese university hospital networks, with GPO contracts dominating Australian and South Korean procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital buying committee consolidation around single-source platform contracts is accelerating competitive exits among standalone catheter suppliers without integrated imaging capabilities.
For Market Incumbents: Cement platform bundling advantages by embedding magnetic navigation compatibility into next-generation catheter designs, defending against pulsed field ablation substitution in Japanese quaternary centers. Deepen backward integration into platinum-iridium electrode supply to secure thermal precision differentiation as gold-plated configurations commoditize. For New Entrants and Emerging Players: Enter via chronic pain applications in Australian ambulatory surgical centers, where radiofrequency ablation penetration lags cardiology and capital thresholds favor disposable bundles over generator investments. Target Vietnam and Indonesian cardiac service lines with cryoballoon platforms as hybrid operating room infrastructure matures in Ho Chi Minh City and Jakarta. For Investors and Strategic Acquirers: Distressed-cycle entries favor modality specialists with NMPA clinical trial data already filed in China, where domestic efficacy requirements extend market entry timelines for microwave and irreversible electroporation platforms. Watch PMDA approval velocity for pulsed field systems as inflection indicator for conventional radiofrequency catheter obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Streamlined Approval Pathway | Accelerated Japanese university hospital access compresses competitive response windows for electrophysiology entrants. |
| Hybrid OR Installation Partnership | Chinese tier-one city bundled procurement locks in imaging-compatible ablation platform commitments ahead of capital cycles. |
| Platinum-Iridium Electrode Backward Integration | In-house metallurgical supply secures thermal precision differentiation as electrode material standards consolidate regionally. |
| Cryoballoon Southeast Asia Expansion | First-mover positioning in Vietnam and Indonesia cardiac centers captures procedural volume before radiofrequency entrenchment. |
| Magnetic Navigation Software Development | Robotic-assisted integration in South Korean quaternary hospitals creates premium pricing tiers for catheter ablation workflows. |
Study Parameters
Regulatory filings from PMDA, NMPA, and TGA, hospital procurement databases, and electrophysiology device registration records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with cardiac electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated procedural volume assumptions and pricing dynamics across Japanese, Australian, and Chinese tier-one cardiac centers. Bottom-up catheter shipment analysis and top-down healthcare expenditure allocation triangulated segment-level demand estimates.
Bottom-up modeling anchored installed base counts for radiofrequency, cryoablation, and microwave systems against replacement cycle assumptions, while top-down healthcare infrastructure investment flows cross-checked capital equipment penetration rates. Segmentation dimensions spanned energy modality, end-user facility tier, application area, and technology integration level across the analysis window. CAGRs derived from procedural volume growth trajectories and average selling price evolution, with specific inputs from hybrid operating room installation pipelines and regulatory approval timelines for novel energy platforms.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA domestic clinical trial mandate enforcement intensity and pulsed field ablation adoption velocity in Japanese quaternary centers. Practitioners should monitor PMDA approval timelines for irreversible electroporation systems and CDSCO import licensing modifications for reusable generator flows as early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Italy Spinal Surgery Devices Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Air Compressor Nebulizer Market
Medical Devices
Infant Incubator Market