
 Pneumonia Testing Market | 2026-2036
Pneumonia Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumonia Testing Market Intelligence
Recurring assay menu subscriptions is restructuring how pneumonia testing platforms generate lifetime revenue, shifting capital equipment sales toward per-test consumable models. Becton Dickinson and Company leverages its installed base of molecular systems to lock in long-term reagent commitments. Abbott Laboratories anchors its competitive position through integrated rapid diagnostic platforms that reduce lab turnaround times. Thermo Fisher Scientific competes by extending its cloud-connected analytics services that tie hardware performance to continuous software enhancements.
Pneumonia testing encompasses laboratory and point-of-care diagnostic methods that detect bacterial, viral, or fungal pathogens in lower respiratory tract infections, typically achieving sensitivity thresholds of 85-95% for nucleic acid amplification techniques and delivering results within 15-120 minutes depending on platform complexity. Molecular tests command premium positioning due to multiplex pathogen identification capabilities, while rapid diagnostic tests occupy high-volume screening segments where speed outweighs comprehensive panel breadth. Serology tests face margin compression as healthcare systems prioritize acute-phase pathogen detection over retrospective antibody assessment.
FDA premarket notification pathways for respiratory multiplex panels shape product development timelines and clinical validation requirements in the United States, while the EMA's IVDR transition in Europe is forcing manufacturers to resubmit technical documentation under stricter performance scrutiny. WHO prequalification standards for diagnostics in low-resource settings create parallel compliance tracks that influence manufacturing scale decisions. Stakeholders must monitor how decentralized testing authorization policies in hospital emergency departments versus centralized laboratory networks reshape channel economics and service bundling strategies.
Market Dynamics
Multiplex respiratory panel commercialization is compressing diagnostic timelines and forcing platform consolidation as hospital laboratories prioritize single-instrument workflows over fragmented point solutions.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification for respiratory multiplex assays reduces clinical validation timelines, enabling faster platform deployment in acute care settings.
- Point-of-Care Network Expansion:Hospital emergency departments in the United States, Germany, and Japan are installing rapid molecular systems to reduce antibiotic stewardship delays.
- Cloud-Connected Analytics Integration:Real-time instrument performance monitoring and remote software updates are extending hardware lifecycles and locking in reagent subscription revenue.
Market Restraints
- Reagent Cost Concentration:Proprietary consumable pricing from dominant platform manufacturers creates margin pressure for mid-sized hospital networks negotiating volume contracts.
- IVDR Technical Documentation Resubmission:European manufacturers face 12-18 month compliance gaps as legacy assays transition under EMA's stricter performance scrutiny requirements.
- Lateral Flow Sensitivity Limitations:Rapid antigen detection thresholds of 60-75% for atypical pathogens restrict screening utility in immunocompromised patient populations.
Strategic Opportunities
- Decentralized Testing Authorization:Pharmacy clinic networks in the United States are gaining CLIA-waived status for respiratory panels, opening retail diagnostic channels previously reserved for centralized laboratories.
- AI-Assisted Pathogen Identification:Machine learning algorithms trained on regional resistance patterns are converging with PCR amplification to reduce time-to-targeted-therapy decisions.
- WHO Prequalification Track:Manufacturers achieving low-resource setting certification can access pooled procurement mechanisms for emerging market health system tenders.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories struggle to hire computational biologists capable of interpreting multiplex panel outputs and integrating results with electronic health record systems.
- Legacy LIS Integration Complexity:Hospital information technology departments face 6-9 month implementation timelines when connecting new molecular platforms to existing laboratory information infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumonia Testing Market |
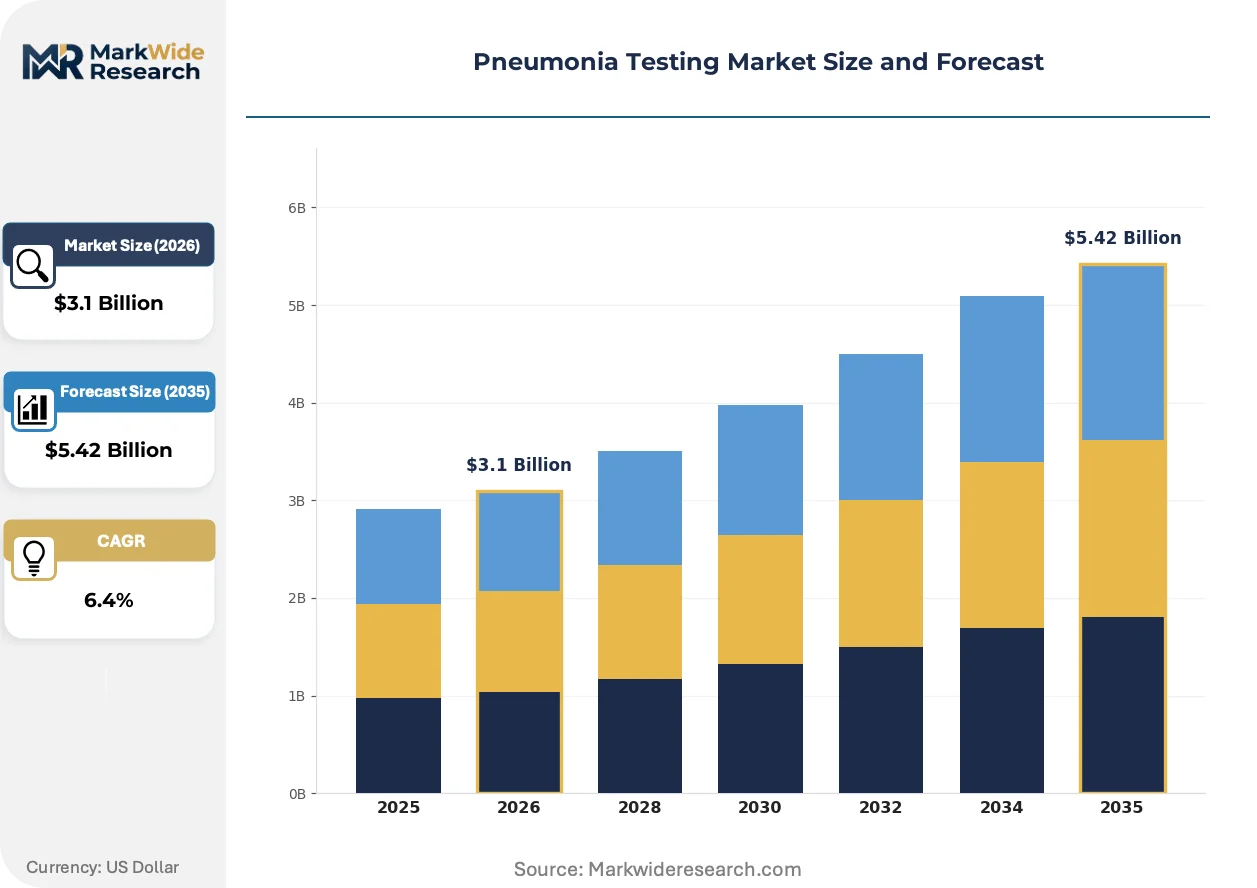
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molecular Tests, Antigen Tests, Serology Tests, Culture Tests Sample Type: Blood, Sputum, Nasopharyngeal Swabs, Bronchoalveolar Lavage Testing Methodology: Polymerase Chain Reaction, Enzyme-linked Immunosorbent Assay, Immunofluorescence, Rapid Diagnostic Tests End User: Hospitals, Diagnostic Laboratories, Ambulatory Care Centers, Research Institutes |
| Companies Covered | Becton Dickinson and Company, Hologic Inc, Abbott Laboratories, Meridian Bioscience, QuidelOrtho, Thermo Fisher Scientific, Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, bioMérieux SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumonia Testing Market Strategic Shifts & Innovations
Sample-to-answer automation is collapsing the distinction between laboratory and near-patient testing, while regulatory convergence across major jurisdictions is standardizing performance validation requirements.
Next-generation sequencing-based respiratory panels are unifying bacterial, viral, and fungal detection within single workflows. Academic medical centers in the United States are adopting these platforms for immunocompromised patient monitoring. This unification is compressing the addressable market for standalone antigen and culture-based methods by consolidating testing onto fewer instruments.
EMA's In Vitro Diagnostic Regulation transition is forcing manufacturers to resubmit technical documentation under expanded clinical evidence requirements. European notified bodies have reduced review capacity, creating bottlenecks for new product introductions. Multiplex respiratory panel developers are responding by prioritizing FDA clearance first, then leveraging that data package for European submissions.
Antibiotic stewardship programs are mandating rapid pathogen identification before empiric therapy initiation. Hospital pharmacy and infectious disease departments are replacing retrospective audit-based interventions with real-time molecular guidance. This behavioral shift is most visible in United States academic medical centers where Medicare reimbursement penalties for hospital-acquired pneumonia drive compliance investment.
Pneumonia Testing Market Segmentation
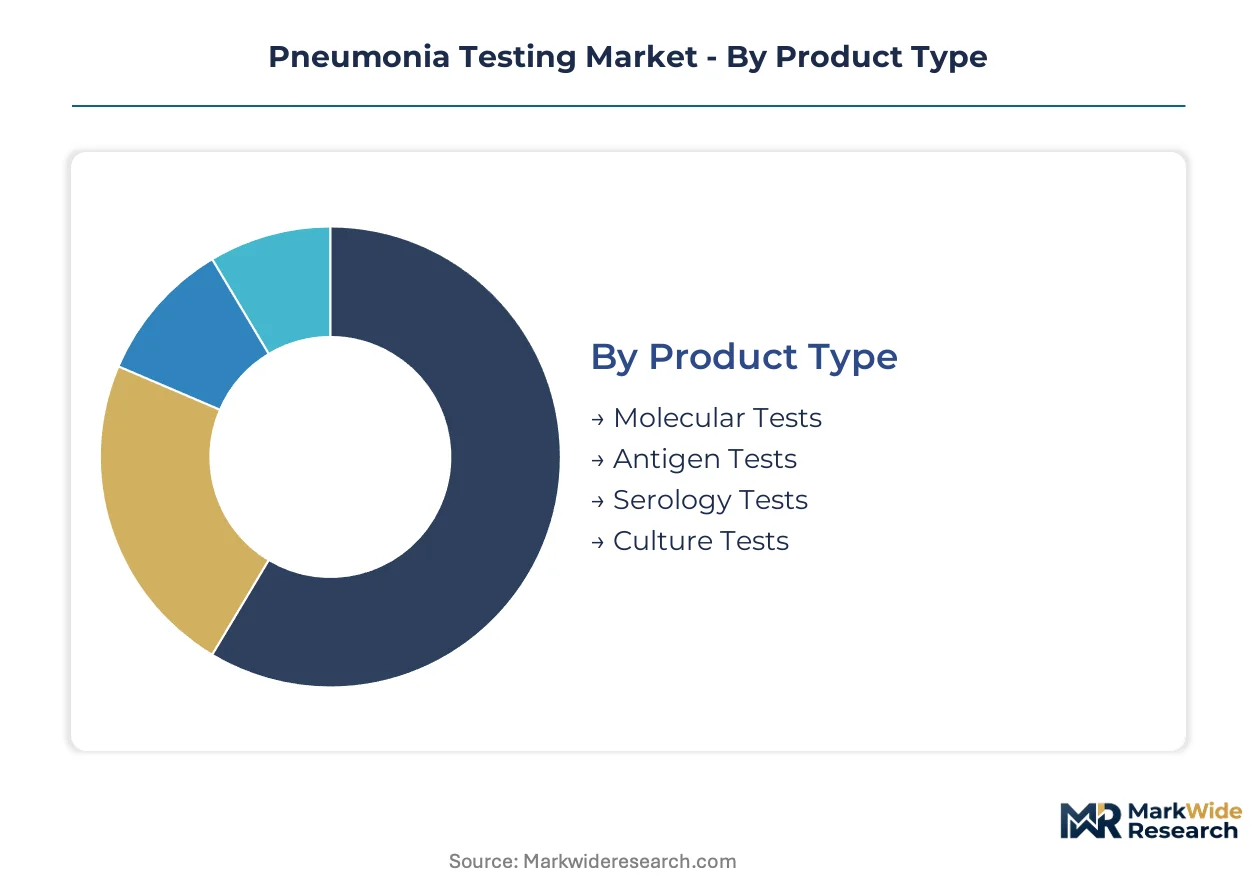
Pneumonia testing platforms fragment across four distinct dimensions that reshape procurement economics and channel strategy. Product type determines capital intensity and consumable lock-in, while sample collection protocols dictate workflow integration complexity. Testing methodology governs sensitivity thresholds and turnaround trade-offs, and end-user concentration shapes service bundling requirements.
Product Type:
Buyers in this category differentiate by whether they prioritize multiplex pathogen breadth or rapid screening speed at the point of care.
- Molecular Tests:Nucleic acid amplification platforms detect bacterial, viral, and fungal pathogens with 85-95% sensitivity. Hospital laboratories in the United States deploy these for antibiotic stewardship programs where comprehensive panels justify 45-120 minute turnaround times and premium reagent subscriptions.
- Antigen Tests:Lateral flow immunoassays deliver qualitative results within 15-30 minutes using visual line interpretation. Emergency departments in Germany favor these for triage decisions where speed outweighs the 60-75% sensitivity limitation for atypical pathogens.
- Serology Tests:Antibody detection assays face margin compression as retrospective immune response assessment loses priority to acute-phase pathogen identification.
- Culture Tests:Traditional bacterial isolation methods remain essential for antimicrobial susceptibility profiling despite 24-72 hour incubation requirements.
Volume sits with Antigen Tests; growth tilts toward Molecular Tests.
Sample Type:
Collection site invasiveness and patient compliance rates segment procurement patterns across acute versus chronic care settings.
- Blood:Serum and plasma samples enable serological retrospective analysis and biomarker quantification. Research institutes in Japan utilize blood-based panels for longitudinal immunocompromised patient monitoring where repeated sampling protocols are established.
- Sputum:Expectorated lower respiratory specimens concentrate bacterial load for culture-based antibiotic susceptibility testing. Diagnostic laboratories process these for hospital-acquired pneumonia investigations where quantitative colony counts guide therapy.
- Nasopharyngeal Swabs:Non-invasive upper respiratory collection dominates outpatient screening volumes in ambulatory care networks.
- Bronchoalveolar Lavage:Invasive sampling from distal airways serves immunocompromised populations where standard specimens yield false negatives.
Nasopharyngeal Swabs capture the highest throughput; Bronchoalveolar Lavage commands the steepest expansion trajectory in transplant centers.
Testing Methodology:
Technical sophistication and regulatory clearance pathways determine platform replacement cycles and capital allocation priorities.
- Polymerase Chain Reaction:Thermal cycling amplification achieves single-copy sensitivity for pathogen DNA and RNA detection. FDA 510(k) clearance pathways for respiratory multiplex panels accelerate deployment timelines in United States acute care settings.
- Enzyme-linked Immunosorbent Assay:Colorimetric antibody-antigen binding quantification supports high-throughput serological screening. Reference laboratories maintain these for batch processing efficiency where turnaround exceeds 4 hours.
- Immunofluorescence:Microscopic visualization of tagged antibodies enables direct pathogen observation in clinical specimens.
- Rapid Diagnostic Tests:Single-use lateral flow cassettes require no instrumentation and qualify for CLIA-waived status in pharmacy clinic networks.
Polymerase Chain Reaction anchors laboratory investment; Rapid Diagnostic Tests are expanding most quickly in decentralized settings.
End User:
Capital availability and reimbursement structures segment buyers across integrated health systems versus independent service providers.
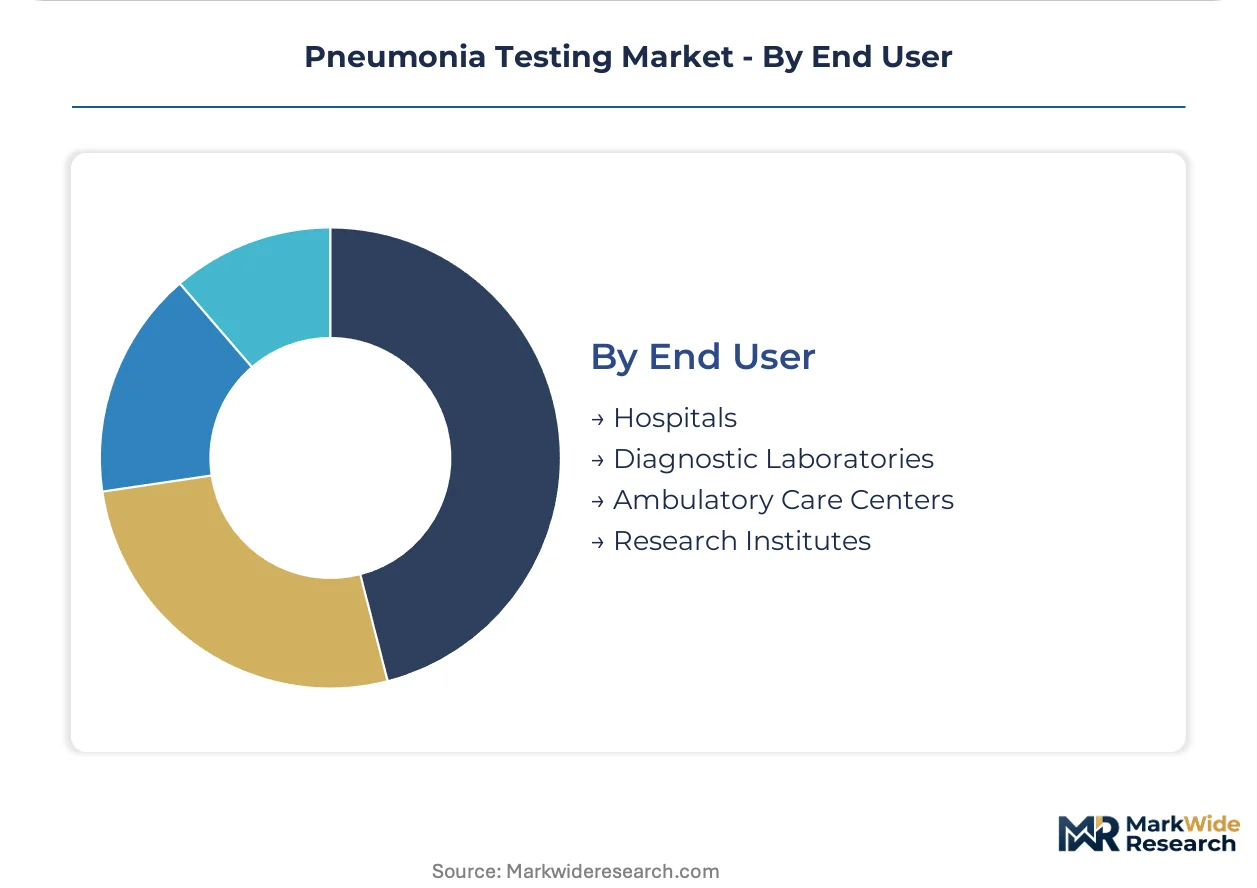
- Hospitals:Integrated delivery networks consolidate testing onto automated sample-to-answer platforms. Antibiotic stewardship mandates in United States academic medical centers drive real-time molecular guidance before empiric therapy initiation.
- Diagnostic Laboratories:Independent reference labs compete on panel breadth and turnaround time for outpatient pneumonia workups.
- Ambulatory Care Centers:Urgent care and primary care clinics prioritize CLIA-waived rapid tests that require minimal training.
- Research Institutes:Academic medical centers adopt next-generation sequencing panels for immunocompromised patient monitoring protocols.
Hospitals command the largest installed base; Ambulatory Care Centers are gaining share fastest as retail diagnostic channels expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for molecular diagnostic platforms clusters in the United States, Germany, and Japan, while demand expansion outpaces supply in emerging health systems across Southeast Asia and the Middle East. Consumption intensity concentrates where antibiotic stewardship programs mandate rapid pathogen identification before therapy initiation.
United States
Hospital emergency departments in Boston, New York, and California deploy point-of-care molecular systems to reduce antibiotic stewardship delays. FDA 510(k) clearance pathways accelerate product introductions for multiplex respiratory panels. The Research Triangle Park corridor in North Carolina anchors instrument manufacturing and clinical validation facilities for next-generation sequencing platforms.
Germany
Diagnostic laboratories in Munich and Hamburg prioritize rapid antigen tests for emergency department triage decisions. EMA's IVDR transition forces manufacturers to resubmit technical documentation under expanded clinical evidence requirements. The Baden-Württemberg region concentrates reagent production and automated sample-to-answer platform assembly.
Japan
Academic medical centers in Tokyo and Osaka adopt next-generation sequencing panels for immunocompromised patient monitoring. METI standards guide cloud-connected analytics integration for remote instrument performance monitoring. The Kansai region hosts manufacturing facilities for PCR amplification systems serving domestic and export markets.
China
Hospital networks in Beijing and Shanghai expand molecular diagnostic adoption for lower respiratory tract infections. NMPA regulatory pathways shape product development timelines and clinical validation requirements for domestic manufacturers. The Yangtze River Delta concentrates contract manufacturing for lateral flow immunoassay components.
India
Reference laboratories in Maharashtra and Karnataka batch-process serological screening for retrospective immune response assessment. CDSCO regulations govern import and local production of nucleic acid amplification platforms. The Delhi-NCR corridor attracts distribution partnerships for multiplex panel manufacturers targeting South Asian health system tenders.
Pneumonia Testing Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the pneumonia testing landscape. Consolidation characterizes the molecular platform segment where installed base scale determines reagent subscription economics. Three archetypes dominate: integrated life science conglomerates with diagnostic divisions, pure-play molecular diagnostics specialists, and rapid test manufacturers with pharmacy channel access. Capacity expansion and strategic partnerships represent the dominant competitive vectors as manufacturers seek CLIA-waived status for retail diagnostic channels.
Among United States-based conglomerates, Becton Dickinson and Company and Abbott Laboratories exemplify the integrated platform archetype, leveraging broad life science portfolios to lock in hospital laboratory commitments through consumable subscription models. Thermo Fisher Scientific occupies a position representing the cloud-connected analytics tier, extending hardware performance through software-enhanced service bundling. These three anchors illustrate how scale-driven players structure competitive positioning around installed base penetration rather than discrete equipment sales.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Hologic Inc |
| Abbott Laboratories |
| Meridian Bioscience |
| QuidelOrtho |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| bioMérieux SA |
| Others |
Cost & Logistics Intelligence
Sample-to-answer automation in molecular diagnostics is collapsing production cost curves while concentrating manufacturing scale among platform-integrated conglomerates, simultaneously compressing per-test economics and locking procurement into proprietary reagent ecosystems.
Pricing Analysis
Margin tightening in rapid antigen tiers reflects lateral flow commoditization as Chinese contract manufacturers expand capacity. Three-tier pricing structure across premium molecular systems, mid-range PCR platforms, and economy antigen cassettes segments buyer archetypes by turnaround requirement and panel complexity. Pricing pressure stems from hospital group purchasing organizations consolidating volume negotiations across integrated delivery networks. Emergency departments demonstrate lowest price sensitivity where stewardship mandates override procurement cost concerns.
Supply Chain Analysis
Regional distribution centers in Memphis and Rotterdam anchor hub-and-spoke cold chain logistics for temperature-sensitive reagents. Manufacturing concentrates in the United States, Germany, and Japan for instrument assembly, with China and South Korea supplying PCR thermal cycling components and lateral flow membranes. Supply chains rest on semiconductor-grade plastics and rare-earth magnets for precision fluidics. Single-source vulnerability concentrates in lyophilized enzyme suppliers following facility consolidation. Distribution runs through authorized distributor networks with direct-to-hospital service contracts for high-throughput laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capacity for multiplex respiratory panels remains constrained by notified body review bottlenecks under EMA's IVDR transition, propping pricing power for cleared platforms while deferring competitive entry.
For Market Incumbents: Extend installed base lock-in through cloud-connected reagent subscription models that tie hardware performance to continuous software enhancements. Consolidate position by acquiring CLIA-waived rapid test manufacturers to capture pharmacy channel expansion. Vertical integration into lyophilized enzyme production mitigates single-source supply risk threatening panel continuity.
For New Entrants and Emerging Players: Launch via pharmacy clinic networks gaining CLIA-waived status for respiratory panels, bypassing hospital laboratory procurement gatekeepers. Target ambulatory care centers in the United States where retail diagnostic channels expand fastest with minimal regulatory friction. Differentiate through AI-assisted pathogen identification algorithms trained on regional resistance patterns.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated diagnostics conglomerates seeking consumable subscription revenue streams. Five-to-ten year viability hinges on FDA 510(k) clearance velocity and European IVDR technical documentation resubmission success. Monitor WHO prequalification achievement as inflection signal for emerging market health system tender access.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification reduces clinical validation timelines for multiplex respiratory panels in acute care settings. |
| CE Marking Pathway Under IVDR | Expanded clinical evidence requirements under EMA scrutiny create compliance moats for resubmitted legacy assays. |
| Hospital System Partnership | Antibiotic stewardship mandates in United States academic medical centers drive real-time molecular guidance procurement. |
| Software Companion Development | Cloud-connected analytics integration extends hardware lifecycles and locks in reagent subscription revenue streams. |
| Reimbursement Strategy | Medicare penalties for hospital-acquired pneumonia compel compliance investment in rapid pathogen identification platforms. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, EMA IVDR technical documentation resubmission rates, and hospital laboratory procurement contract values anchored the trend analysis, supplemented by interviews with molecular diagnostics platform engineers, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA premarket notification databases, EMA notified body capacity reports, CMS Medicare reimbursement schedules, and hospital procurement databases. Bottom-up instrumentation shipment tracking and top-down healthcare expenditure triangulation converged on segment-level estimates.
Segment-weighting across product type, testing methodology, end-user concentration, and regional regulatory cluster shaped the analytical framework across the analysis window. CAGRs were derived from instrument installation base expansion trajectories coupled with per-test consumable throughput assumptions. Forecast inputs incorporated antibiotic stewardship program mandate adoption curves and cloud-connected platform upgrade cycles.
Regulatory clearance delays, notified body capacity constraints, and reimbursement policy shifts are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Biomarker Testing Services Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Global GMP Testing Service Market
Testing Services
Vestibular Testing System Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
US Viral Clearance Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
Mycological Testing Market
Testing Services
Point of Care Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market