
 Hearing Aids Market | 2026-2036
Hearing Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Aids Market Analysis
Audiologist workforce shortages across developed markets is reorganizing how manufacturers reach end users, with direct-to-consumer channels gaining structural importance. Sonova leverages its integrated retail-audiology network to sustain channel control in key European markets. WS Audiology anchors its position through R&D intensity in rechargeable and AI-enabled platforms. Demant A/S differentiates via vertical manufacturing scale across transducers and signal processing chips.
Hearing aids are electroacoustic wearable devices that amplify sound for individuals with sensorineural or conductive hearing loss, typically incorporating digital signal processors with 16-24 bit resolution and multi-channel compression algorithms to restore audibility across frequency ranges. Their primary commercial purpose is to improve speech intelligibility and quality of life for hearing-impaired users in daily communication environments. Digital technology dominates unit economics due to programmable frequency shaping and noise reduction capabilities, while AI-enabled systems represent the fastest-growing margin pool through adaptive scene classification and personalized fitting automation. Behind-the-ear configurations maintain volume leadership for severe-to-profound loss cases, though receiver-in-canal designs are capturing share among cosmetically motivated adult users.
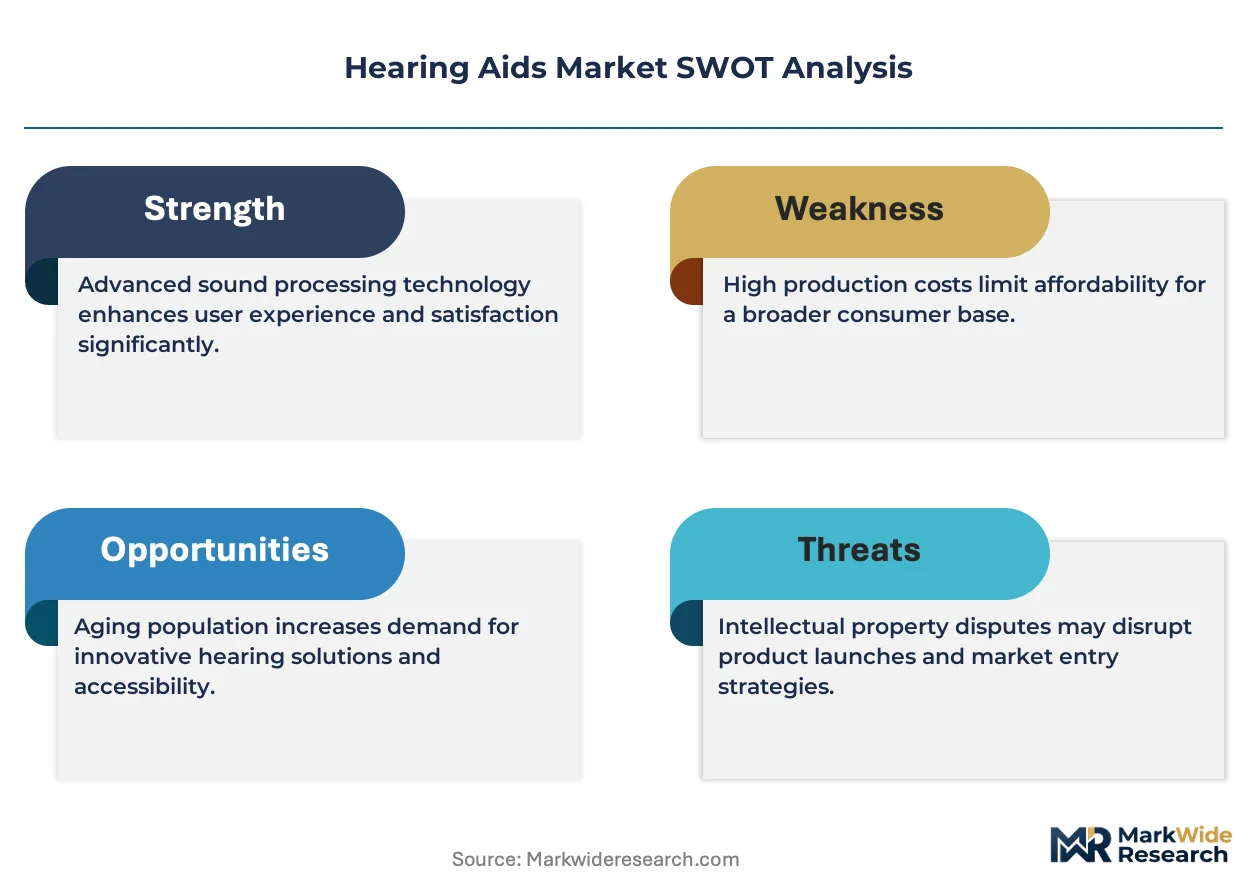
The FDA's OTC hearing aid regulations in the United States, coupled with EU MDR requirements for medical device traceability and the EU AI Act's risk classification for autonomous diagnostic functions, are elevating compliance costs while opening access pathways for new market entrants. Japan's MHLW reimbursement revisions and Australia's TGA parallel assessment pathways further fragment the regulatory landscape that manufacturers must navigate. Stakeholders should monitor how reimbursement policy divergence between self-fitting OTC channels and traditional audiology-directed models reshapes competitive positioning and customer lifetime value structures.
Market Dynamics
The FDA's over-the-counter hearing aid category is dismantling the audiology gatekeeper model in the United States, forcing manufacturers to rebuild go-to-market architectures around direct consumer access while defending professional-channel revenue in Europe and Japan.
Growth Catalysts
- Aging demographics:Germany, Japan, and Italy are expanding their senior populations at rates that outpace audiology workforce growth, creating structural demand for automated fitting solutions and self-service device categories.
- Rechargeable lithium-ion platforms:Elimination of zinc-air battery dependency reduces lifetime cost-of-ownership and aligns with EU battery sustainability directives, accelerating replacement cycles among existing users.
- AI Act medical device classification:The European Union's risk-tiering framework for autonomous diagnostic functions is creating regulatory clarity that enables faster product registration for algorithm-enabled hearing aids in member states.
Market Restraints
- Semiconductor foundry concentration:Taiwan-based fabrication capacity for low-power DSP chips creates geographic supply vulnerability, with hearing aid-specific wafer allocations competing against smartphone and automotive demand.
- EU MDR traceability requirements:The expanded Unique Device Identification mandate imposes serialization infrastructure costs that disproportionately burden smaller manufacturers, accelerating market consolidation.
- Cochlear implant candidacy expansion:Improved surgical techniques and expanded insurance coverage for implantable devices capture severe-to-profound loss cases that previously represented premium hearing aid revenue.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing create tariff-advantaged export platforms targeting Southeast Asian and Middle Eastern markets with price-sensitive demand.
- Tinnitus masking integration:Convergence of hearing amplification with sound therapy algorithms opens reimbursement pathways through audiology practices managing comorbid hearing loss and tinnitus presentations.
- Remote programming channels:Teleaudiology platforms enable manufacturers to capture rural and homebound users without physical retail presence, particularly in Australia's dispersed population centers and Canada's northern territories.
Industry Challenges
- Audiologist workforce attrition:Retirement waves in the United States and United Kingdom outpace university program output, compressing professional fitting capacity precisely as device complexity increases.
- Firmware validation timelines:Over-the-air update capabilities for AI-enabled devices trigger re-certification requirements under FDA and EU MDR frameworks, extending release cycles and fragmenting software versioning across markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Aids Market |
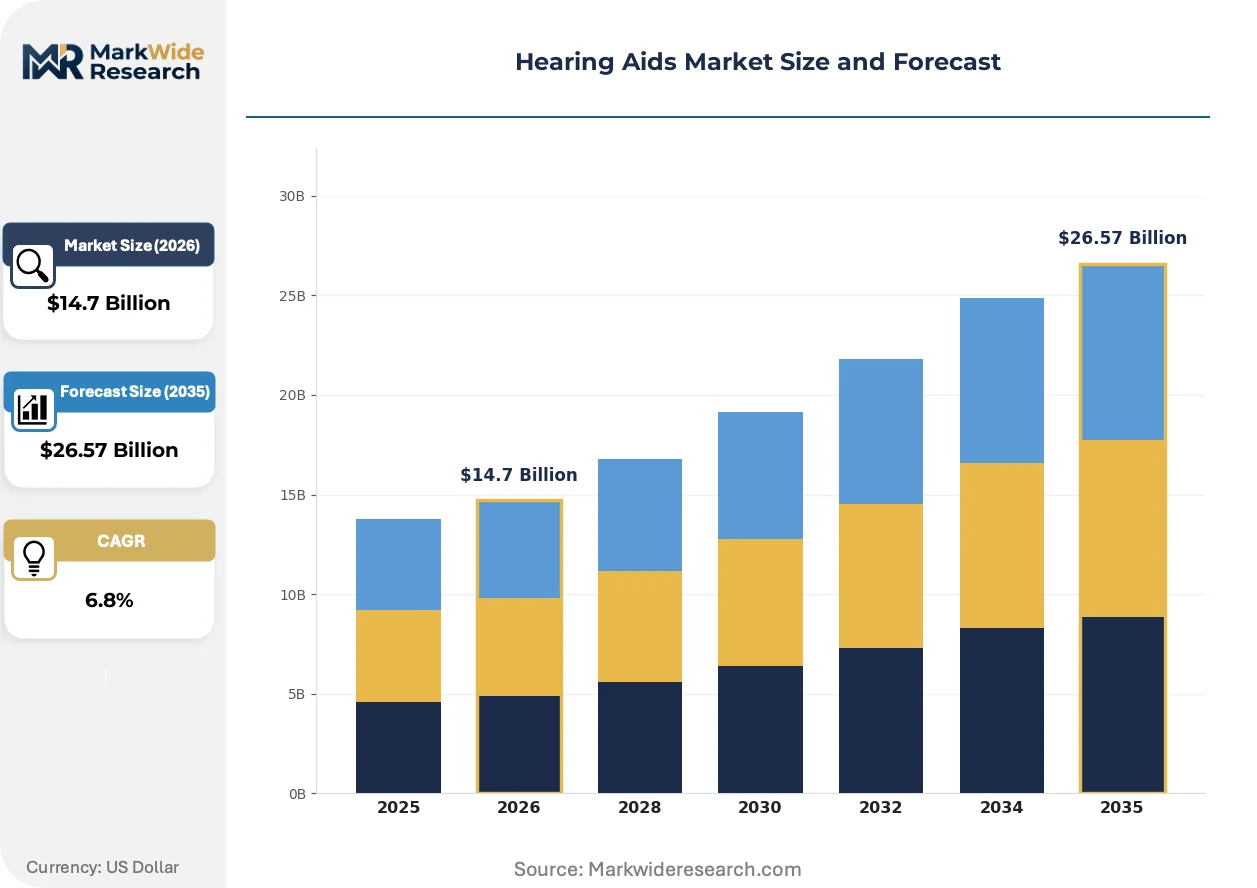
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BTE, ITE, RIC, CIC Technology: Digital, Analog, AI-enabled, Wireless End User: Seniors, Adults, Children, Medical Professionals Distribution Channel: Online, Retail Stores, Audiology Clinics, Hospitals |
| Companies Covered | Sonova, WS Audiology, Demant A/S, GN Store Nord A/S, Starkey Laboratories, Cochlear Ltd., Rion Co., Ltd., Eargo Inc., MED-EL Medical Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Aids Market Emerging Trajectories
Signal processing architectures are migrating toward edge-based neural inference, enabling real-time acoustic scene classification without cloud latency while complicating regulatory validation pathways across jurisdictions.
Deep neural network noise reduction is supplanting traditional multi-band compression algorithms in premium device tiers. Adult users with mild-to-moderate loss in Germany and the Netherlands are selecting these platforms at accelerating rates. The technology is compressing differentiation timelines between flagship and mid-tier product lines, forcing faster refresh cycles.
The EU AI Act's risk classification framework for autonomous diagnostic functions is mandating human-in-the-loop oversight for certain algorithmic fitting recommendations. Manufacturers serving the European market are restructuring software architectures to maintain audiology professional involvement. France and Spain are seeing the most pronounced compliance-driven product segmentation as national regulators interpret the mandate variably.
Subscription-based device access is displacing outright purchase models in direct-to-consumer channels. Younger adult users in the United States are selecting monthly plans that bundle hardware, software updates, and remote support. The model is most visible in metropolitan markets where smartphone-centric service delivery aligns with existing digital consumption patterns.
Hearing Aids Market Segmentation
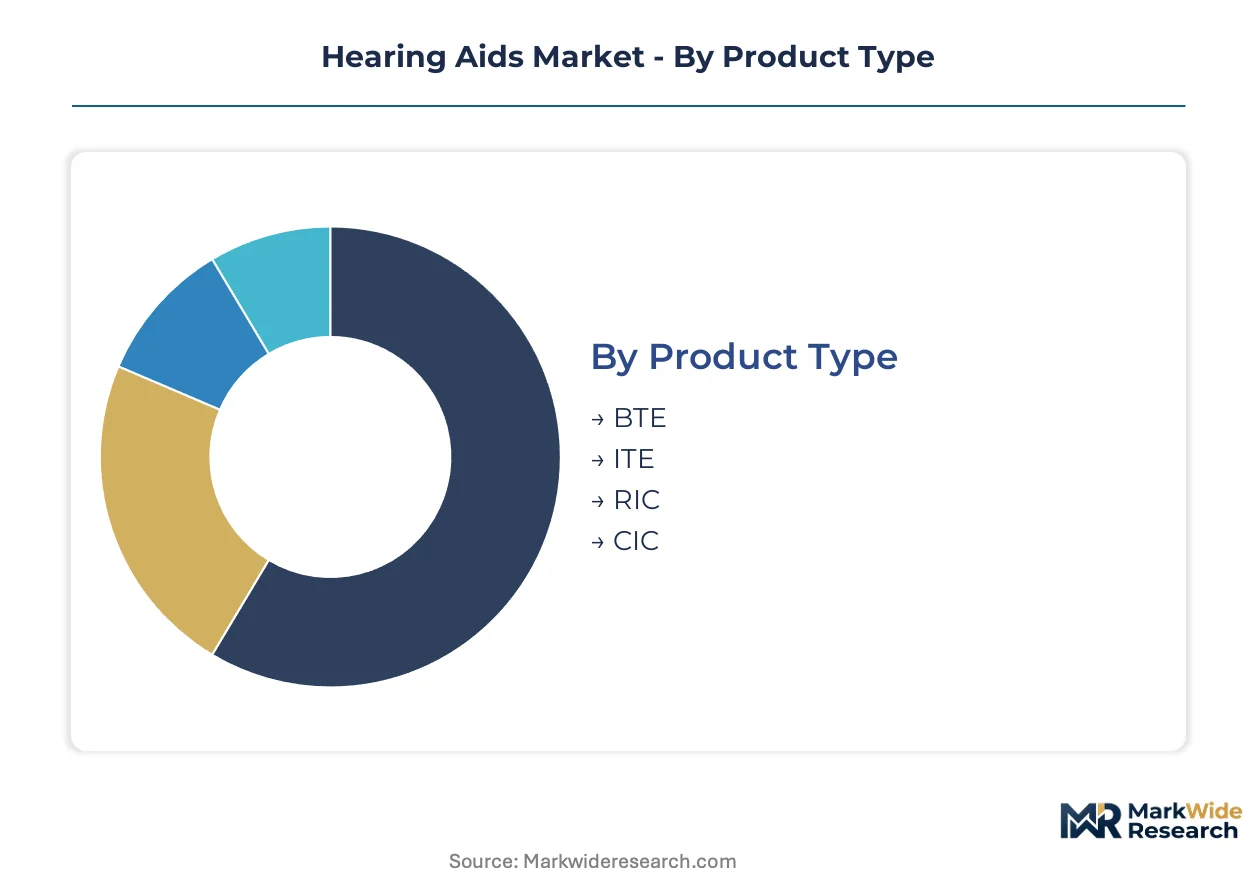
Hearing aids stratify across multiple technical and commercial dimensions that determine reimbursement pathways, fitting complexity, and channel economics. Manufacturers configure product portfolios around these divides to capture distinct margin pools and patient access routes.
Product Type:
Behind-the-ear units dominate export volumes to reimbursement-heavy European markets, while discreet in-canal designs concentrate in self-pay Asian and North American channels where cosmetic preferences override cost considerations.
- BTE:These devices house all electronics in a casing resting behind the ear, connected via tubing to an ear mold. Severe-to-profound loss cases in Germany and Japan drive demand through statutory reimbursement frameworks that prioritize functional outcomes over aesthetics. The architecture accommodates larger batteries and more powerful amplification circuits.
- RIC:Receiver-in-canal systems place the speaker directly in the ear canal while the processor sits behind the ear, enabling a smaller profile without sacrificing power. Adult users in the United States and Netherlands select this configuration at accelerating rates as FDA OTC regulations reduce fitting friction for mild-to-moderate loss presentations.
- ITE:In-the-ear models fill the concha and canal bowl with a custom-molded shell. Demand concentrates among seniors with dexterity limitations who struggle with smaller battery compartments.
- CIC:Completely-in-canal devices sit nearly invisible within the ear canal, appealing to working-age professionals in metropolitan markets who prioritize discretion over feature depth.
BTE commands the established base. The steepest expansion runs through RIC.
Technology:
Cost tiers separate legacy analog platforms from digital signal processing and emerging AI-enabled architectures, with pricing spreads of 10-15x between entry-level and premium tiers reflecting semiconductor content and algorithmic sophistication.
- Digital:Programmable 16-24 bit DSP architectures with multi-channel compression dominate commercial volumes across all major markets. Germany's statutory reimbursement funds these platforms as standard-of-care for sensorineural loss, while India's private audiology channel absorbs mid-tier digital units for price-sensitive urban consumers.
- AI-enabled:Edge-based neural inference engines perform real-time acoustic scene classification and adaptive noise reduction without cloud latency. The EU AI Act's risk classification framework is mandating human-in-the-loop oversight for autonomous fitting recommendations in France and Spain, complicating deployment timelines.
- Analog:Basic amplification circuits without frequency shaping persist in emerging market entry segments and humanitarian distribution programs where battery longevity and repair simplicity outweigh acoustic precision.
- Wireless:Bluetooth Low Energy connectivity for smartphone streaming and remote programming is becoming table stakes in premium tiers, with iOS and Android compatibility now standard in North American and European launches.
Digital platforms anchor current revenue. AI-enabled systems are climbing the fastest as manufacturers differentiate through adaptive algorithms.
End User:
Volume concentration and margin structure diverge sharply between geriatric reimbursement-funded segments and younger self-pay populations with different service delivery expectations.
- Seniors:Adults over 65 with age-related presbycusis represent the core demand base across developed economies. Japan's expanding super-aged population and Germany's statutory reimbursement frameworks sustain device penetration rates above 35% in this cohort, though audiologist workforce shortages are compressing fitting capacity.
- Adults:Working-age users aged 18-64 with noise-induced or early-onset loss present the fastest-growing addressable market as FDA OTC regulations in the United States enable direct purchase without professional gatekeeping. Subscription-based access models are gaining traction in metropolitan markets.
- Children:Pediatric fittings for congenital or early-acquired loss require specialized verification protocols and educational support services. Demand concentrates in hospital-based audiology departments with multidisciplinary care teams.
- Medical Professionals:Audiologists and ENT specialists themselves constitute a procurement segment for demonstration units, fitting software licenses, and calibration equipment that supports clinical service delivery.
Seniors command the established base. The steepest expansion runs through Adults.
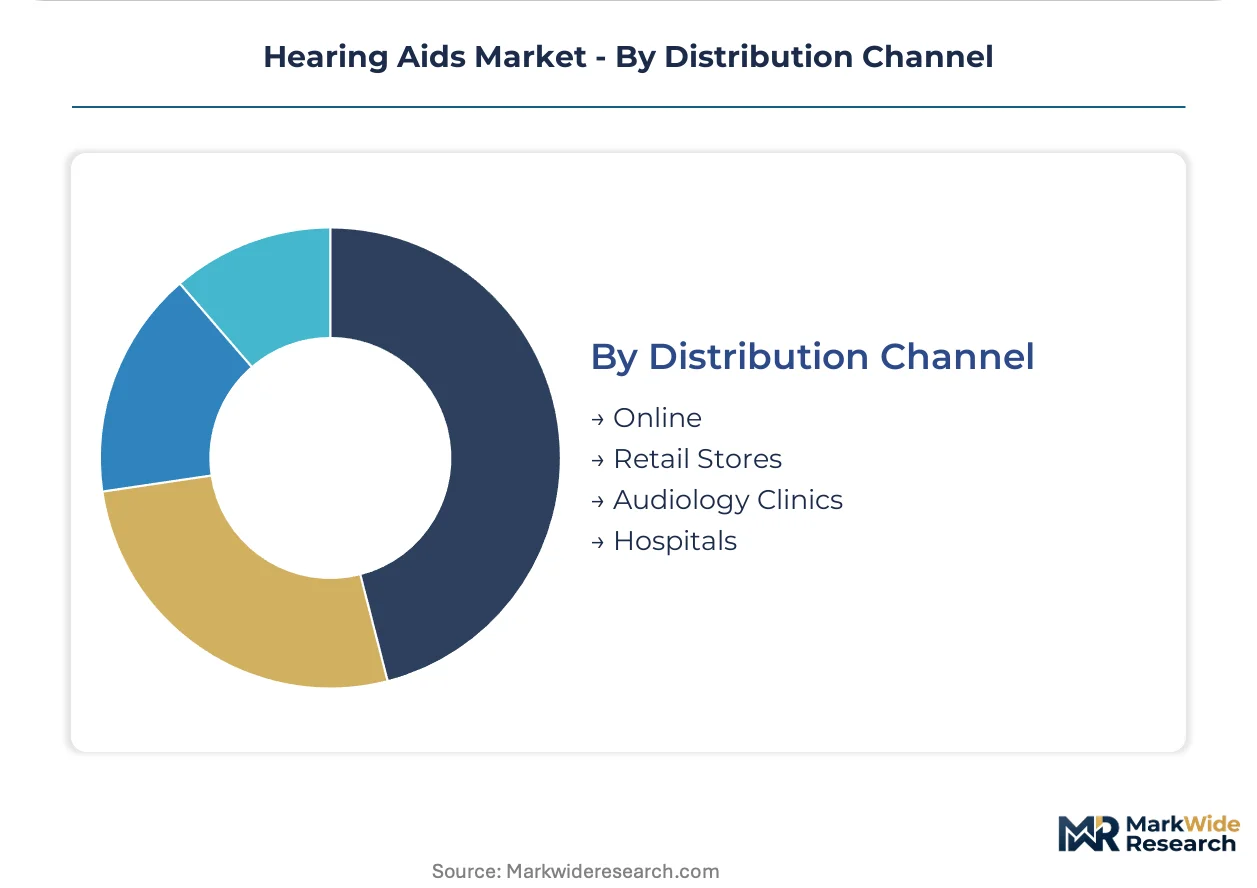
Distribution Channel:
Channel configuration determines customer acquisition costs, fitting service bundling, and regulatory compliance burdens across jurisdictions with divergent reimbursement architectures.
- Audiology Clinics:Professional-directed fitting with real-ear verification and ongoing rehabilitation services dominates reimbursement-funded markets in Germany, Japan, and the United Kingdom. These channels capture premium pricing through service bundling but face capacity constraints from workforce attrition.
- Online:Direct-to-consumer platforms are displacing traditional retail in the United States following FDA OTC implementation, with smartphone-based hearing tests and remote programming enabling self-fitting. Australia's dispersed population centers and Canada's northern territories show similar channel shift potential.
- Retail Stores:Big-box electronics and pharmacy chains are entering the hearing aid category in deregulated markets, leveraging foot traffic and existing healthcare product familiarity to capture price-sensitive demand.
- Hospitals:Acute care and outpatient ENT departments handle complex cases requiring surgical evaluation or cochlear implant candidacy assessment, particularly for pediatric and sudden-onset loss presentations.
Audiology Clinics command the established base. The steepest expansion runs through Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan treat hearing aids as statutory benefits with professional fitting requirements, while the United States and Australia are shifting toward self-directed purchase models that bypass traditional audiology gatekeeping.
United States
FDA's OTC hearing aid regulations enacted in 2022 have dismantled the professional-fitting monopoly for mild-to-moderate loss cases. Smartphone-based hearing tests and direct-to-consumer platforms now capture metropolitan markets where younger users prefer subscription access over clinical visits. Boston and San Francisco clusters host teleaudiology startups targeting this channel shift.
Germany
Statutory health insurance funds approximately 80% of device costs for certified hearing aids, sustaining Europe's highest penetration rate among seniors. The EU MDR's Unique Device Identification mandate has forced manufacturers to restructure serialization systems for traceability compliance. Berlin and Munich audiology networks remain the primary distribution channel despite online emergence.
Japan
MHLW reimbursement revisions have expanded coverage for advanced digital platforms while tightening qualification criteria for device upgrades. Super-aged prefectures like Aichi and Hiroshima face acute audiologist shortages, accelerating interest in automated fitting algorithms. Osaka's medical device cluster concentrates domestic manufacturing for regional export.
Australia
TGA parallel assessment pathways enable faster registration for devices already approved in comparable jurisdictions. The country's dispersed population centers in Queensland and Western Australia drive teleaudiology adoption for rural and remote access. Sydney and Melbourne audiology practices are experimenting with hybrid remote-in-person service models.
India
PLI scheme incentives for medical device manufacturing are attracting assembly operations targeting price-sensitive Southeast Asian and Middle Eastern export markets. Private audiology chains in Mumbai and Bangalore absorb mid-tier digital units for urban consumers outside statutory coverage. Domestic production remains concentrated in Tamil Nadu's electronics manufacturing corridor.
Hearing Aids Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling retail-audiology networks and semiconductor supply chains while smaller players compete on algorithmic differentiation or niche form factors. Market structure reflects this bifurcation: consolidated at the top where scale economies in R&D and distribution matter, fragmented below where regional brands and startup entrants find footholds. Two strategic archetypes dominate—vertically integrated full-stack manufacturers with captive retail channels, and technology-focused specialists betting on AI-enabled self-fitting platforms. Competitive moves center on M&A to secure audiology clinic networks and strategic partnerships with semiconductor foundries for low-power DSP supply.
Within the integrated leader tier, Sonova and WS Audiology occupy positions that exemplify divergent responses to channel disruption—Sonova leveraging its retail-audiology network to maintain professional-channel control in European markets, WS Audiology anchoring its position through R&D concentration in rechargeable and algorithmic platforms. Demant A/S represents the manufacturing-scale archetype with upstream integration into transducers and signal processing components. These three European-structured entities collectively illustrate how geographic origin and corporate form shape strategic posture amid regulatory divergence between OTC-access and professional-fitting markets.
| Leading Market Players |
|---|
| Sonova |
| WS Audiology |
| Demant A/S |
| GN Store Nord A/S |
| Starkey Laboratories |
| Cochlear Ltd. |
| Rion Co., Ltd. |
| Eargo Inc. |
| MED-EL Medical Electronics |
| Others |
Supply Flow & Price Mechanics
Wafer-scale DSP fabrication economics in Taiwan concentrate component supply among hearing aid manufacturers, compressing price floors for mid-tier digital platforms while premium AI-enabled tiers sustain margin buffers through algorithmic differentiation and audiology service bundling.
Pricing Analysis
Long-term offtake contracts for lithium-ion battery cells and MEMS microphone arrays dominate procurement, though spot-market spot purchasing for packaging materials introduces cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled platforms with remote programming from basic digital units and analog entry devices. Pricing pressure stems from FDA OTC channel expansion in the United States, where direct-to-consumer platforms bypass audiology markup. Self-pay adults in metropolitan markets exhibit lowest price sensitivity, while statutory reimbursement-funded seniors in Germany and Japan prioritize functional outcomes over cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports shape European distribution economics, with container availability fluctuations affecting inventory positioning for German audiology networks. Taiwan, China, and Vietnam concentrate semiconductor wafer fabrication and final assembly operations. Raw material dependencies include rare-earth magnets for receivers, medical-grade silicones for ear molds, and cobalt for rechargeable cells. Single-source vulnerability runs through TSMC's low-power DSP allocation priorities competing against smartphone demand. Distribution runs through captive retail-audiology networks in Europe and direct-to-consumer platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hearing aid manufacturing exhibits durable defensive moats through regulatory entrenchment, where FDA and EU MDR certification timelines create multi-year barriers against commoditization and sustain incumbent pricing power.
For Market Incumbents: Shield professional-channel revenue in Germany and Japan by deepening audiology clinic partnerships and exclusive fitting software ecosystems against OTC self-fitting erosion. Prioritize R&D concentration in rechargeable platforms and edge-based AI inference to differentiate premium tiers from emerging direct-to-consumer entrants. Secure multi-year foundry allocation agreements for low-power DSP supply to insulate against semiconductor capacity competition.
For New Entrants and Emerging Players: Differentiate on teleaudiology-enabled remote programming for rural and homebound populations in Australia's dispersed territories and Canada's northern regions. Target working-age adults with mild-to-moderate loss in United States metropolitan markets through subscription-based access models bundled with smartphone-centric service delivery. Pursue regulatory arbitrage via TGA parallel assessment pathways for faster Australian market entry.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive retail networks and upstream component control over pure-play algorithm developers. Long-term viability hinges on navigating divergence between OTC-access and professional-fitting regulatory regimes across jurisdictions. Acquisition targets should demonstrate audiology clinic network density or proprietary DSP architecture. Watch FDA enforcement discretion on OTC self-fitting claims as inflection indicator for channel economics.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance enables statutory reimbursement access across German and Dutch health insurance frameworks. |
| Audiology Clinic Acquisition | Captive retail networks defend professional-channel positioning against OTC channel shift in European markets. |
| Rechargeable Platform Launch | Lithium-ion elimination of zinc-air dependency aligns with EU battery sustainability directives and accelerates replacement cycles. |
| Teleaudiology Partnership | Remote programming capabilities capture rural access demand in Australia's dispersed population centers. |
| Foundry Allocation Agreement | Secured wafer supply insulates against TSMC capacity competition from smartphone and automotive demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and statutory reimbursement databases across Germany, Japan, and the United States. Primary interviews engaged audiology clinic directors, biomedical engineers at hearing aid manufacturers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from CMS Medicare claims data, Japan's MHLW reimbursement bulletins, and customs trade records for DSP component flows. Bottom-up unit shipment estimates triangulated against top-down market sizing from reimbursement expenditure reports.
Segmentation dimensions modeled include product architecture, signal processing technology tier, end-user age cohort, and distribution channel configuration across the projection horizon. CAGRs derive from regression analysis of historical penetration rates against demographic projections and reimbursement policy trajectories. Forecast inputs incorporate audiology workforce attrition rates, FDA OTC channel adoption curves, and semiconductor foundry capacity allocation trends.
Forecasts assume regulatory continuity in FDA enforcement posture and EU MDR implementation timelines; material policy shifts would require re-modeling. Cochlear implant candidacy expansion, foundry supply disruption, or reimbursement rate compression in statutory markets present specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Creatinine Meter Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Bariatric Beds Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Global Spirometers Market