
 Cervical Total Disc Replacement Device Market | 2026-2036
Cervical Total Disc Replacement Device Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Total Disc Replacement Device Market Analysis
The cervical total disc replacement device market is consolidating around a widening gap between premium motion-preservation systems and commoditized fusion alternatives. Stryker Corporation leverages its integrated trauma and spine platform to sustain hospital contracting leverage across major US health systems. Zimmer Biomet Holdings anchors its position through specialized cervical disc portfolios that compete on bearing-surface longevity. Globus Medical differentiates via vertically controlled manufacturing of titanium and PEEK constructs.
Cervical total disc replacement devices are implantable prostheses, typically 14-18 mm in diameter, designed to restore disc height and segmental motion after discectomy using cobalt-chromium, titanium, or polymer cores. Their primary purpose is preserving cervical kinematics while avoiding adjacent-segment degeneration associated with anterior cervical discectomy and fusion. Bioceramic-bearing artificial discs command concentrated margin pools due to wear-resistance advantages in younger, active patient cohorts. Motion preservation technology leads growth trajectories as adjustable-height systems mature into standard-of-care positioning across ambulatory surgery centers. Direct sales channels dominate high-value hospital accounts while third-party distributors penetrate orthopedic practices in secondary markets.
FDA premarket approval requirements and the EU MDR conformity assessment process govern device safety, biocompatibility testing, and post-market surveillance obligations. Japan's PMDA enforces JIS-aligned clinical evaluation standards that extend approval timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement decisions by CMS and Germany's Federal Joint Committee as these determine whether motion-preservation procedures displace fusion volumes in covered indications.
Market Dynamics
Hospital procurement committees are consolidating vendor lists around motion-preservation platforms that demonstrate measurable adjacent-segment sparing, forcing manufacturers to prove kinematic durability through extended follow-up registries rather than short-term clinical endpoints.
Growth Catalysts
- FDA PMA Pathway Clarity:Streamlined premarket approval timelines for cervical disc devices with established predicate comparisons accelerate US commercialization for second-generation bearing surfaces.
- Bioceramic Core Adoption:Oxinium and silicon nitride bearing materials reduce wear debris generation in active patient populations under 55, expanding addressable surgical indications beyond traditional fusion candidates.
- Germany's Federal Joint Committee Reimbursement Expansion:Motion-preservation procedures now receive equivalent DRG weighting to fusion in multi-level cervical pathologies, removing historical financial disincentives for disc replacement.
Market Restraints
- Cobalt-Chromium Supply Concentration:Forged alloy blanks for bearing surfaces originate from a limited supplier base in the US Midwest, exposing device manufacturers to input cost volatility and allocation risk.
- EU MDR Technical Documentation Burden:Enhanced clinical evidence requirements for Class III implantable devices extend conformity assessment timelines by 18-24 months, compressing effective patent life for premium platforms.
- Anterior Cervical Discectomy and Fusion Substitution:Mature fusion techniques with established 20-year outcome data and lower implant costs retain preference among surgeons in resource-constrained hospital systems.
Strategic Opportunities
- Japan PMDA Conditional Early Approval:Foreign manufacturers leveraging existing FDA PMA data can secure limited-market authorization with post-market surveillance obligations, opening access to the world's fastest-aging cervical spine patient population.
- Ambulatory Surgery Center Channel Development:Same-day cervical disc replacement protocols are migrating to outpatient settings in Texas, Florida, and Arizona, creating demand for simplified instrumentation sets and compressed procedure times.
- Patient-Specific Implant Convergence:Integration of preoperative CT-based planning software with adjustable-height disc designs enables intraoperative customization without explant-and-replace workflows.
Industry Challenges
- Spine Surgeon Training Pipeline Constraints:Fellowship programs produce fewer surgeons trained in motion-preservation techniques than required to meet procedural volume targets in expanding metropolitan markets.
- Long-Term Registry Maintenance Burden:Post-market surveillance obligations under FDA PMA and EU MDR require sustained data collection infrastructure across 10-15 year follow-up periods, consuming operational resources.
- Legacy Hospital Information System Integration:Implant tracking and adverse event reporting workflows must interface with electronic health record platforms from Epic and Cerner, creating middleware development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Total Disc Replacement Device Market |
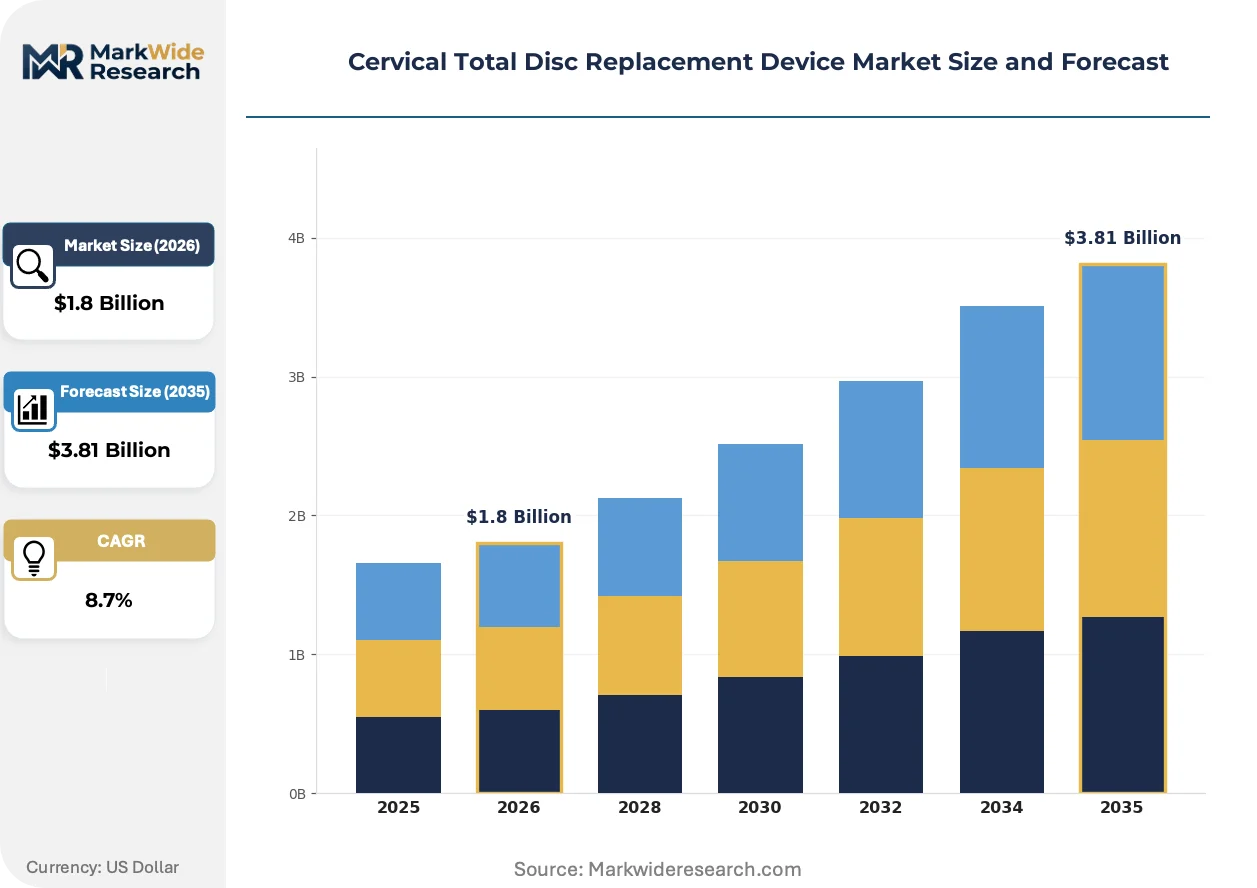
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Titanium, PEEK, Bioceramics End User: Hospitals, Ambulatory Surgery Centers, Rehabilitation Clinics, Orthopedic Practices Technology: Artificial Discs, Adjustable Heights, Motion Preservation, Hybrid Constructs Distribution Channel: Direct Sales, Online Retail, Wholesalers, Third-Party Distributors |
| Companies Covered | Medtronic plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., Globus Medical, Inc., NuVasive, Inc., Orthofix Medical Inc., Centinel Spine, Inc., ZimVie, Inc., DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Total Disc Replacement Device Market Emerging Trajectories
Device architecture is converging around modularity that permits intraoperative height and lordosis adjustment, while bearing surface chemistry advances target oxidative wear reduction in younger, more active surgical candidates.
Polyethylene-core artificial discs with vitamin E stabilization are unifying the mid-market segment by combining cobalt-chromium wear resistance with polymer shock absorption. Community hospital spine programs in the US Southeast are adopting these hybrid platforms at twice the rate of conventional metal-on-metal designs. This unification is compressing the premium-standard price gap while elevating baseline performance expectations for entry-level disc replacement.
EU MDR Article 117 requirements for notified body involvement in quality system audits are extending device recertification cycles for legacy cervical disc products. Manufacturers must submit updated clinical evaluation reports against current state-of-the-art benchmarks rather than historical predicate comparisons. Products with pre-2017 CE marks face the steepest compliance burden, particularly those lacking prospective registry data from European sites.
Surgeon ownership of ambulatory surgery centers is altering equipment procurement authority, concentrating purchasing decisions among physician-investors rather than hospital materials management committees. This channel shift favors vendors offering direct-to-practice instrument loaner programs and compressed case-cart configurations. The transformation is most pronounced in Florida and Texas, where certificate-of-need restrictions on ASC development have relaxed, enabling rapid site expansion for cervical spine procedures.
Cervical Total Disc Replacement Device Market Segmentation
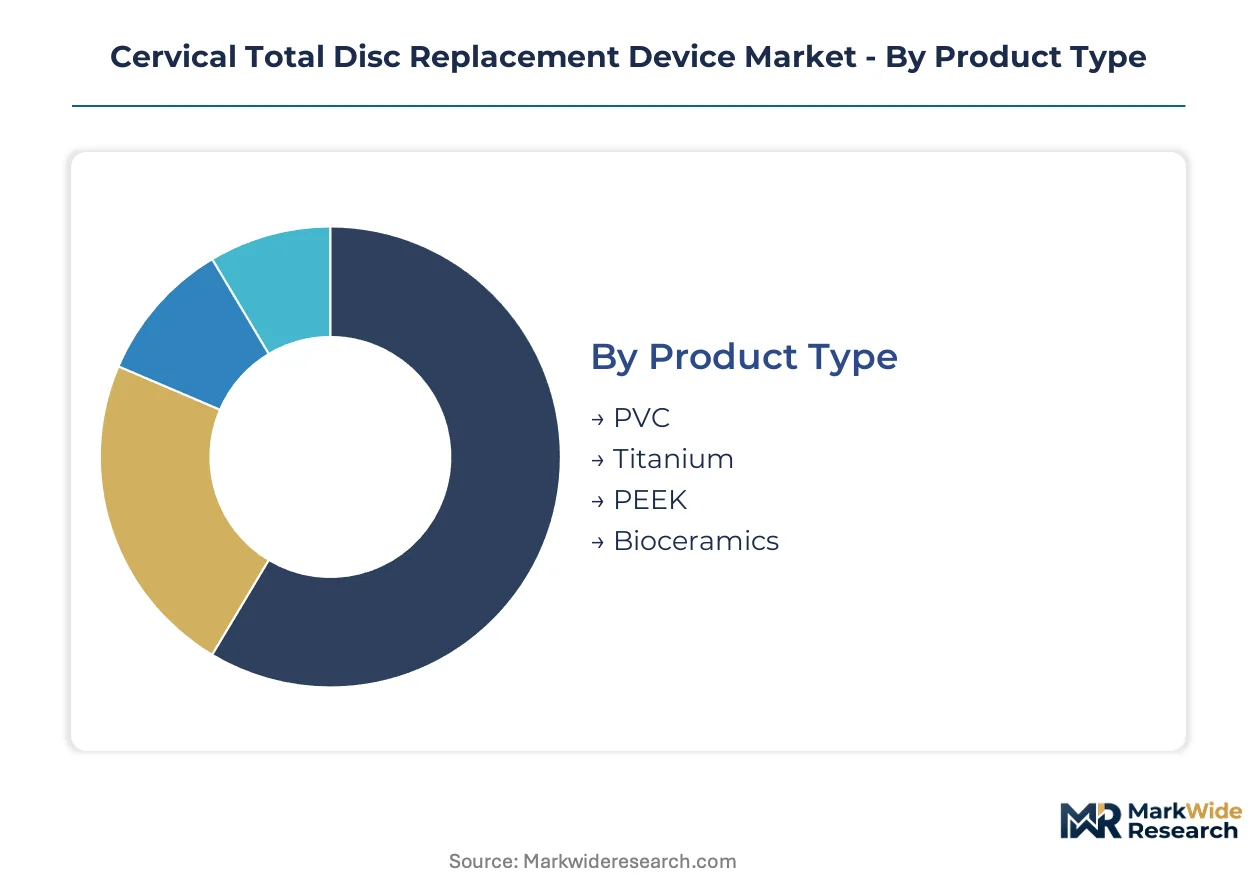
Surgeon preference for bearing surface longevity and hospital procurement consolidation around motion-preservation platforms create divergent demand patterns across product categories. Each segmentation dimension reveals distinct margin structures and channel access requirements that shape vendor competitive positioning.
Product Type:
Material selection decisions hinge on patient age, activity level, and hospital formulary restrictions that limit alloy options in specific health systems.
- Titanium:Machined titanium endplates with porous surface coatings promote osseointegration in single-level procedures. Demand concentrates in German university hospitals where Federal Joint Committee reimbursement parity removed cost barriers to motion-preservation adoption.
- Bioceramics:Oxinium oxidized zirconium and silicon nitride bearing surfaces deliver wear resistance for patients under 55 with higher functional demands. US metropolitan spine centers of excellence drive procurement volume as surgeons prioritize adjacent-segment sparing in younger cohorts.
- PEEK:Polyetheretherketone cores with radiolucent properties facilitate postoperative imaging assessment in multi-level constructs.
- PVC:Polyvinyl chloride components serve cost-constrained health systems in secondary markets with established fusion conversion protocols.
Volume sits with titanium platforms; growth tilts toward bioceramic bearing surfaces.
End User:
Site-of-care migration and physician ownership structures are redistributing purchasing authority away from traditional hospital supply chains.
- Hospitals:Academic medical centers and community hospital spine programs with established fellowship training pipelines generate the highest procedural volumes for complex multi-level cases. US health systems with integrated electronic health records from Epic and Cerner prioritize implant tracking compatibility in vendor selection criteria.
- Ambulatory Surgery Centers:Same-day discharge protocols in Texas, Florida, and Arizona require compressed instrumentation sets and streamlined case carts. Surgeon-investor ownership concentrates procurement decisions among physician stakeholders rather than materials management committees.
- Orthopedic Practices:Private practice spine surgeons in secondary US markets rely on third-party distributor relationships for instrument loaner programs and inventory management.
- Rehabilitation Clinics:Postoperative monitoring facilities coordinate with implanting surgeons for motion-preservation outcome tracking and physical therapy protocol alignment.
Procedure volume clusters in hospital-based programs; site expansion accelerates fastest in ambulatory surgery centers.
Technology:
Modularity and intraoperative adjustability are converging design requirements that compress development timelines for next-generation platforms.
- Motion Preservation:Ball-and-socket or saddle-bearing designs restore segmental kinematics while limiting adjacent-segment stress. Japanese PMDA conditional approval pathways reward manufacturers with existing FDA PMA data, opening access to the world's fastest-aging cervical spine patient population.
- Adjustable Heights:Intraoperative lordosis and disc height modification without explant-and-replace workflows reduce revision rates in anatomically variable patient anatomies. Preoperative CT-based planning software integration enables patient-specific customization in US centers of excellence.
- Artificial Discs:Fixed-height cobalt-chromium and polyethylene constructs serve established indications with mature clinical evidence portfolios.
- Hybrid Constructs:Combined fusion and motion-preservation systems address multi-level pathologies with adjacent-segment disease.
Artificial discs retain installed base dominance; adjustable-height systems gain share fastest among new product launches.
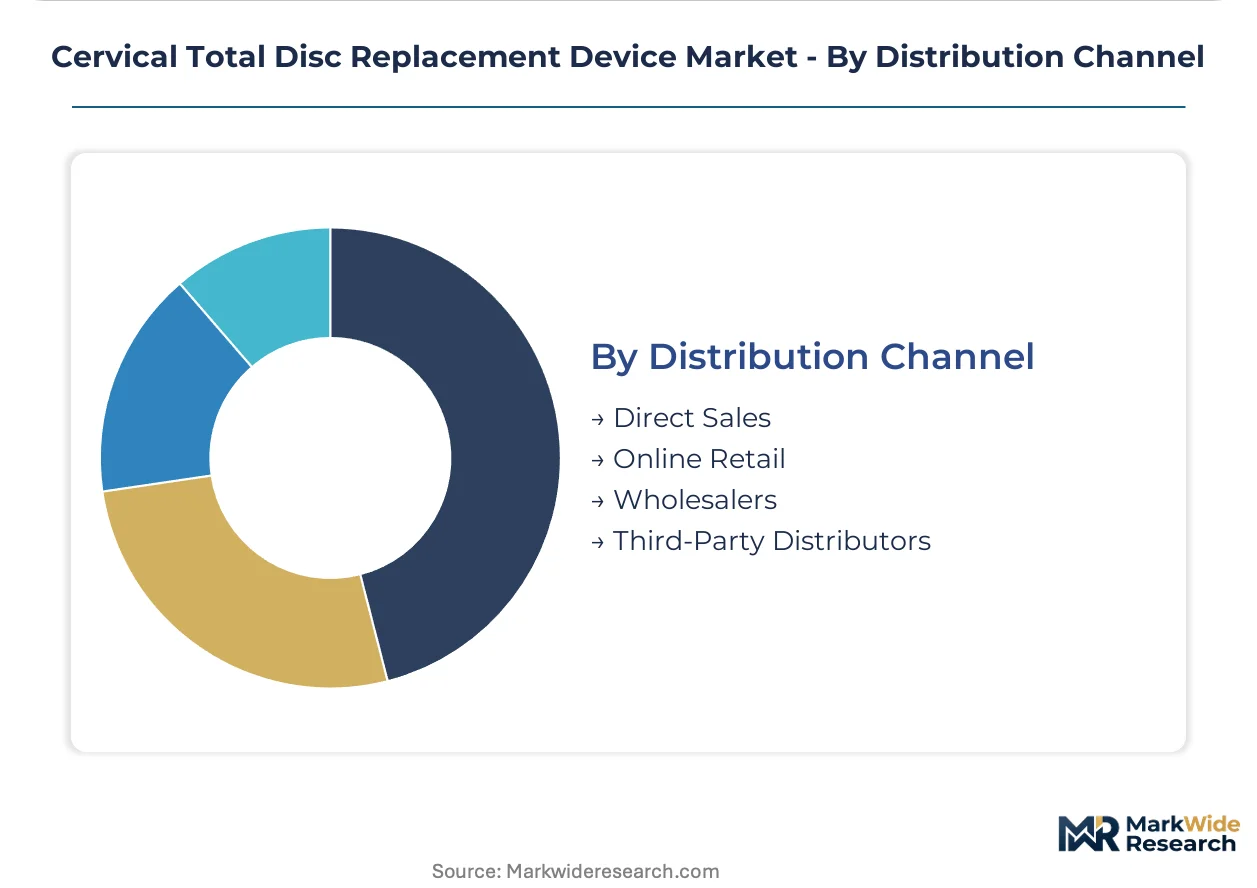
Distribution Channel:
Account control strategies vary by customer scale and geographic concentration of surgical volume.
- Direct Sales:Manufacturer-employed specialists manage high-value hospital accounts with dedicated instrument support and surgeon training programs. Stryker Corporation and Zimmer Biomet Holdings deploy direct teams across major US health systems with spine surgery centers of excellence.
- Third-Party Distributors:Independent orthopedic distributors penetrate secondary markets and community hospital spine programs with localized inventory and relationship-based selling. The US Southeast and Midwest rely heavily on this channel for cervical disc replacement device access.
- Wholesalers:Group purchasing organization contracts aggregate demand across hospital networks for standardized implant pricing.
- Online Retail:Limited applicability for implantable devices due to FDA and EU MDR traceability requirements; restricted to ancillary instrumentation and disposable components.
Revenue concentrates in direct sales channels; third-party distributor penetration expands most quickly in underserved metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan hospital networks in the United States anchor procedural volume for cervical total disc replacement, with Texas Medical Center in Houston and Mayo Clinic in Rochester generating concentrated demand for motion-preservation platforms.
United States
Academic medical centers in Boston and Baltimore drive adoption of adjustable-height systems through established spine surgery fellowship pipelines. FDA premarket approval pathways for second-generation bearing surfaces streamline commercialization timelines for manufacturers with predicate device comparisons. Hospital procurement consolidation in the Southeast favors vendors offering integrated electronic health record compatibility with Epic and Cerner platforms.
Germany
Federal Joint Committee reimbursement parity for motion-preservation procedures removed historical financial disincentives, expanding disc replacement volumes in Berlin and Munich university hospitals. EU Medical Device Regulation conformity assessment requirements extend technical documentation timelines for Class III implantable devices. The Baden-Württemberg medical technology corridor hosts specialized machining suppliers for titanium endplate components.
Japan
PMDA conditional early approval pathways reward manufacturers with existing FDA PMA data, accelerating market access for foreign device makers in Tokyo and Osaka metropolitan areas. JIS-aligned clinical evaluation standards enforce rigorous biocompatibility testing protocols. Japan's fastest-aging cervical spine patient population concentrates surgical demand in Kanto region academic centers.
United Kingdom
NICE technology appraisal processes determine NHS commissioning eligibility for motion-preservation devices, creating regulatory uncertainty for premium bearing surface platforms. London teaching hospitals maintain referral networks for complex multi-level cervical pathologies. The Oxford-Cambridge arc generates clinical evidence through prospective registry participation in EU MDR post-market surveillance frameworks.
Australia
TGA conformity assessment requirements for Class III active implantable medical devices align with EU MDR technical documentation standards, simplifying parallel market entry for US and European manufacturers. Sydney and Melbourne spine centers drive adoption of same-day discharge protocols. Private hospital networks in Queensland expand ambulatory surgery capacity for cervical disc replacement procedures.
Cervical Total Disc Replacement Device Market Vendor Landscape
Premium-margin players sit above commodity-margin players across bearing surface chemistry and kinematic durability dimensions. The vendor base stratifies into three tiers: diversified orthopedic conglomerates with integrated trauma-spine platforms, specialized spine device manufacturers with focused cervical portfolios, and emerging entrants targeting ambulatory surgery center channels. Consolidated procurement authority at US health systems and German hospital networks favors scale-driven vendors with dedicated instrument support infrastructure. Competitive positioning depends on extended follow-up registry maintenance and surgeon training program density.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings occupy positions defined by hospital contracting leverage across major metropolitan health systems. Medtronic plc anchors the premium-tier vector through its integrated spine-robotics platform. These three entities exemplify the strategic archetype of vendors leveraging breadth across trauma, spine, and neurosurgical categories to defend account control in high-volume cervical disc replacement centers.
| Leading Market Players |
|---|
| Medtronic plc |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Globus Medical, Inc. |
| NuVasive, Inc. |
| Orthofix Medical Inc. |
| Centinel Spine, Inc. |
| ZimVie, Inc. |
| DePuy Synthes |
| Others |
Supply Flow & Price Mechanics
Forged cobalt-chromium alloy blanks from the US Midwest flow through three distinct pricing tiers determined by bearing surface chemistry and kinematic durability certification. Hospital procurement committees in metropolitan health systems translate raw material scarcity into vendor consolidation pressure that favors manufacturers with captive supply arrangements.
Pricing Analysis
Value-based pricing anchored to adjacent-segment sparing outcomes dominates procurement negotiations in US spine centers of excellence. Three-tier pricing structure across premium bioceramic, standard titanium, and economy PEEK levels separates motion-preservation platforms by bearing longevity and patient age stratification. Pricing pressure stems from Germany's Federal Joint Committee reimbursement parity removing historical fusion premiums. Ambulatory surgery centers exhibit highest price sensitivity due to compressed procedure economics, while academic medical centers prioritize kinematic performance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg, Germany and the US Midwest machining corridor limit precision titanium endplate production capacity. Supply concentrates in Switzerland for PEEK polymer cores, the United States for cobalt-chromium forging, and Japan for silicon nitride ceramic blanks. Raw material dependencies include oxidized zirconium feedstock, medical-grade titanium sponge, and vitamin E-stabilized polyethylene. Single-source vulnerability in forged alloy blank supply creates allocation risk during demand surges. Distribution runs through direct sales teams for hospital accounts and third-party orthopedic distributors for secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MDR technical documentation requirements and FDA PMA pathway investments create barrier-to-entry moats favoring manufacturers with established regulatory infrastructure.
For Market Incumbents: Lock in hospital system partnerships through integrated electronic health record compatibility with Epic and Cerner platforms. Extend registry maintenance infrastructure to satisfy FDA and EU MDR post-market surveillance obligations. Counter emerging entrant pressure by securing exclusive instrument loaner programs at ambulatory surgery centers in Texas and Florida.
For New Entrants and Emerging Players: Launch via third-party distributor relationships targeting orthopedic practices in the US Southeast and Midwest secondary markets. Exploit white-space in adjustable-height system segments where preoperative CT-planning software integration remains underdeveloped. Penetrate Japan's aging cervical spine patient population through PMDA conditional early approval leveraging existing FDA PMA data.
For Investors and Strategic Acquirers: Japan PMDA conditional approvals for foreign manufacturers with FDA predicate data is the leading indicator that regulatory pathway efficiency is improving. Long-term viability centers on manufacturers with vertically controlled titanium and PEEK manufacturing and sustained registry data collection infrastructure. Target acquisition archetypes include specialized cervical disc portfolios with bioceramic-bearing platforms and established surgeon training program density.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Streamlined PMA timelines for second-generation bearing surfaces accelerate US commercialization for predicate-comparison devices. |
| EU MDR Conformity Assessment | Enhanced clinical evidence requirements for Class III implants extend certification cycles and compress effective patent life. |
| Hospital System Partnership | Integrated EHR compatibility with Epic and Cerner platforms anchors vendor selection criteria in major US health systems. |
| Reimbursement Strategy | Federal Joint Committee parity decisions in Germany and CMS coverage determinations in the US shape procedure volume displacement. |
| Surgeon Training Program | Fellowship pipeline density in motion-preservation techniques determines addressable surgical capacity in expanding metropolitan markets. |
Methodological Framework
FDA PMA filings, EU MDR technical documentation databases, and hospital procurement contract records formed the secondary backbone of this analysis. Primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated demand patterns and pricing dynamics. Bottom-up and top-down triangulation reconciled device shipment data with procedural volume estimates across metropolitan hospital networks.
Bottom-up modeling anchored forecasts to surgeon-trained capacity and site-of-care migration patterns, while top-down validation cross-checked against health system capital expenditure disclosures. Segmentation dimensions included bearing surface chemistry, end-user facility type, technology modularity, and distribution channel structure across the projection horizon. CAGRs derived from procedure volume elasticity to reimbursement decisions and bearing material innovation cycles.
Regulatory approval delays, reimbursement policy reversals, and raw material supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about surgeon training pipeline expansion and ambulatory surgery center certificate-of-need relaxation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Nasal Packing Devices Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Subperiosteal Implants Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Digital Phoropter Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Global Dermatome Device Market