
 Electric Acupuncture Devices Market | 2026-2036
Electric Acupuncture Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Acupuncture Devices Market Foresight
Licensed acupuncturist workforce shortages across North America and Western Europe is unwinding clinic expansion plans and forcing equipment providers to target home-user segments. Omron Corporation leverages its consumer health electronics heritage to dominate portable device distribution through pharmacy channels. Schwa-medico GmbH anchors its position in European clinical settings through CE-marked stationary systems with integrated diagnostic modules. Asia-med GmbH specializes in combined systems that merge electro-acupuncture with thermal therapy for German rehabilitation centers.
Electric acupuncture devices deliver controlled electrical impulses through needle electrodes at frequencies typically ranging from 2 to 100 Hz to modulate neural signaling and promote therapeutic outcomes. These systems serve clinical and home settings for pain management, musculoskeletal rehabilitation, and adjunctive neurological therapy. Portable devices and handheld units capture expanding margin pools as home-user adoption rises, while stationary equipment retains dominance in hospital and clinic infrastructure budgets. Electro-acupuncture technology leads clinical installations for its direct needle-integration precision, whereas transcutaneous electrical nerve stimulation segments compete in the consumer-accessible home therapy space.
FDA 510(k) clearance requirements shape product development timelines and predicate device selection for US market entrants, while CE marking under the EU MDR governs European commercialization pathways. China's NMPA medical device registration and Japan's PMDA approval processes create distinct compliance thresholds that filter manufacturer participation in East Asian markets. Stakeholders must monitor evolving reimbursement classifications for electro-acupuncture across national health systems to align product positioning with payer coverage expansion.
Market Dynamics
Licensed practitioner shortages across North America and Western Europe are fragmenting demand toward home-use segments, forcing manufacturers to bifurcate product portfolios between clinical-grade stationary systems and consumer-accessible portable units.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's abbreviated clearance pathway for predicate electro-acupuncture devices compresses US market entry timelines from 18 months to under 9 months for manufacturers with established predicate claims.
- German Reimbursement Evolution:Chronic pain management clinics in Germany are expanding device procurement as statutory health insurance frameworks expand coverage for electro-acupuncture under integrated care contracts.
- Needle-Integrated Precision:Electro-acupuncture technology delivers superior neural modulation accuracy compared to surface TENS units, anchoring clinical preference in hospital rehabilitation departments.
Market Restraints
- Copper and Rare Earth Volatility:Electrode manufacturing depends on copper pricing and neodymium magnet supply chains concentrated in Chinese processing facilities, creating input cost instability.
- Practitioner Licensing Bottlenecks:North American acupuncturist workforce growth stagnates below 2% annually, capping installed base expansion for clinical-grade equipment.
- Transcutaneous Substitution:Wireless TENS patches and consumer neuromodulation wearables capture price-sensitive home users seeking needle-free alternatives.
Strategic Opportunities
- South Korean Wellness Networks:Premium wellness centers in Seoul and Busan are creating dedicated electro-acupuncture suites, opening channel partnerships for combined thermal-electrical systems.
- Telehealth Integration:Remote patient monitoring platforms are embedding electro-acupuncture protocol adherence tracking, enabling subscription-based device-as-a-service models.
- Japan's PMDA Fast-Track:Breakthrough device designation for neuropathic pain applications accelerates approval timelines for novel waveform algorithms.
Industry Challenges
- Firmware Validation Complexity:IEC 62304 medical device software lifecycle requirements extend development cycles for app-connected portable units by 8-14 months.
- Legacy EMR Integration:Hospital procurement committees demand HL7 FHIR compatibility, forcing middleware development costs on mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Acupuncture Devices Market |
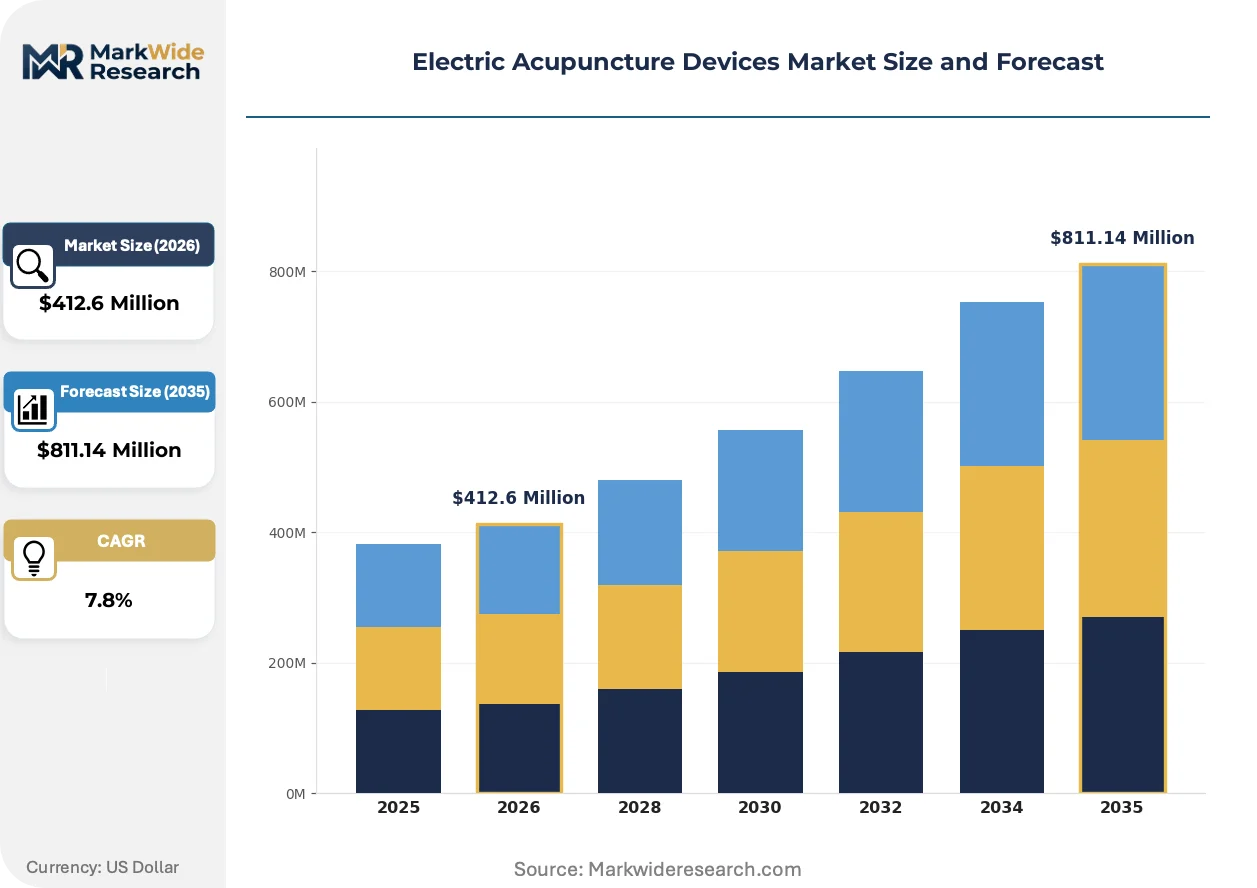
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $811.14 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Handheld Units, Stationary Equipment, Combined Systems End User: Clinics, Home Users, Hospitals, Wellness Centers Technology: Electro-Acupuncture, Transcutaneous Electrical Nerve Stimulation, Pulsed Electromagnetic Field, Microcurrent Therapy Distribution Channel: Online Retail, Direct Sales, Medical Supply Stores, Dealers |
| Companies Covered | Suzhou Hualun Medical Appliance Co. Ltd., Wuxi Biomedical Technology Co. Ltd., Schwa-medico GmbH, Zepter International, Omron Corporation, MKW Lasersystem GmbH, Ito Co. Ltd., Asia-med GmbH, Wuxi Jiajian Medical Instruments Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Acupuncture Devices Market Shifts & Advancements
Digital waveform modulation and embedded biosensors are transforming electro-acupuncture from analog fixed-frequency delivery into adaptive, closed-loop therapeutic systems.
Artificial intelligence-driven pattern recognition is supplanting manual frequency selection protocols in next-generation devices. Rehabilitation departments at tier-one hospitals in China are piloting these systems for stroke recovery protocols. The technology is compressing treatment session duration from 30 minutes to 12-15 minutes while maintaining efficacy endpoints.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for all electro-acupuncture device classifications above Class IIa. Manufacturers face expanded post-market surveillance obligations including annual safety update reports. German notified bodies are prioritizing combined electro-thermal systems for conformity assessment, creating approval queue advantages for multi-modal platforms.
Home users now initiate purchase journeys through pharmacy retail channels rather than practitioner referrals. Omron Corporation's pharmacy network partnerships in Japan demonstrate this channel migration, with over-the-counter portable units displacing clinic-based trial rentals. South Korean consumers exhibit the strongest direct-to-consumer purchasing velocity, driven by wellness center social media marketing integration.
Electric Acupuncture Devices Market Segmentation
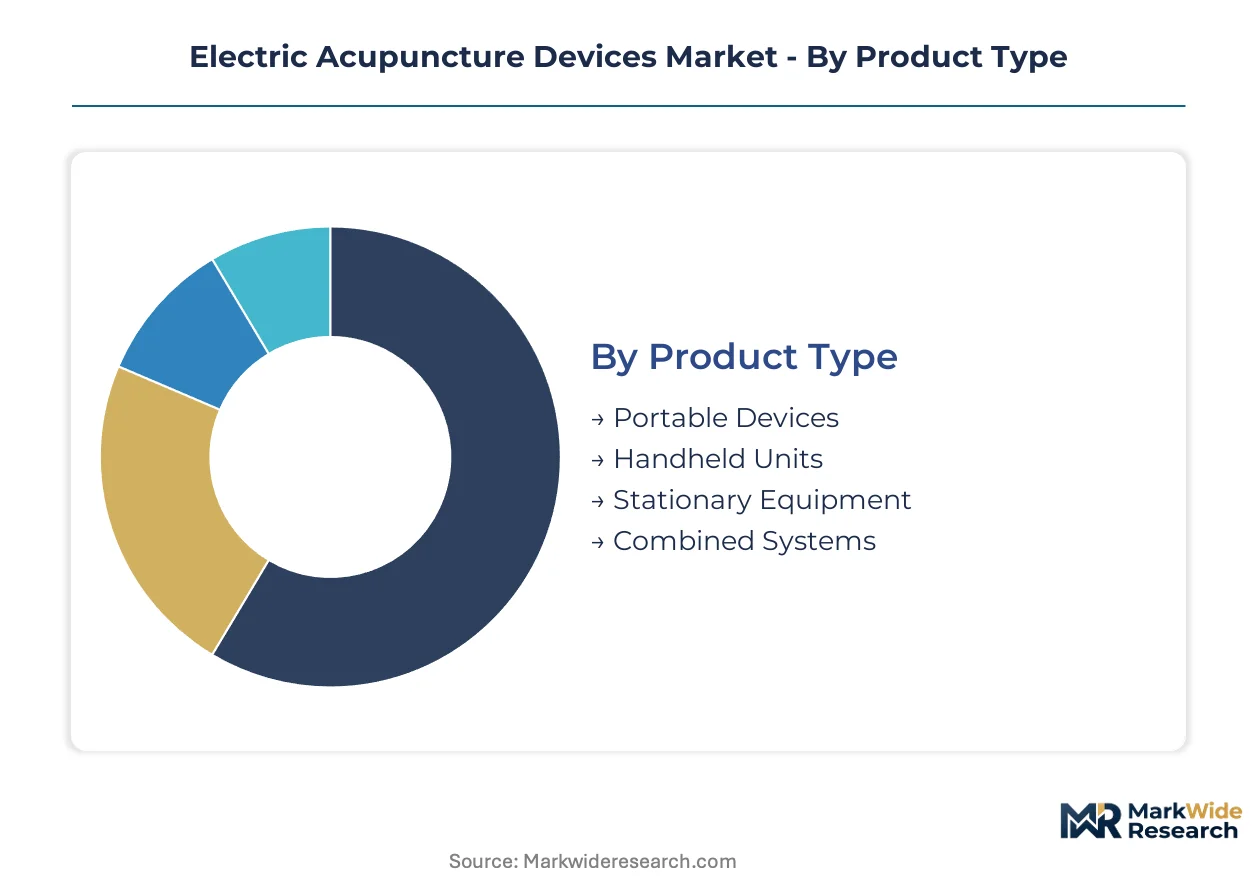
Electric acupuncture devices fragment across multiple axes that determine pricing power, regulatory burden, and channel strategy. Product form factor and end-user setting create the deepest strategic cleavages, while technology type and distribution pathway shape margin capture and geographic reach.
Product Type:
Stationary equipment dominates domestic procurement in Germany and Japan where hospital rehabilitation departments anchor installed base expansion. Portable devices and handheld units drive export-led growth into North American pharmacy channels and South Korean direct-to-consumer markets.
- Portable Devices:Battery-powered units with 2-100 Hz frequency modulation and integrated safety cutoffs. Demand concentrates in Japanese pharmacy retail where Omron's distribution partnerships displace clinic-based trial rentals; home-user adoption accelerates as licensed practitioner shortages force self-administration.
- Handheld Units:Compact single-channel devices optimized for travel and intermittent use. South Korean wellness center networks in Seoul and Busan create premium positioning through social media marketing integration; consumers exhibit the strongest direct-to-consumer purchasing velocity.
- Stationary Equipment:Multi-channel clinical systems with HL7 FHIR EMR compatibility for hospital procurement committees.
- Combined Systems:Platforms integrating electro-acupuncture with thermal therapy modules for German rehabilitation centers.
Stationary equipment holds the largest share; momentum sits with portable devices.
End User:
Cost tier stratification separates premium clinical installations from economy home-use penetration. Hospitals and clinics absorb firmware validation complexity and middleware development costs; home users prioritize price accessibility and over-the-counter availability.
- Clinics:Licensed acupuncture practices requiring FDA 510(k) cleared or CE-marked systems. German chronic pain management clinics expand procurement as statutory health insurance frameworks evolve; workforce shortages across North America cap installed base growth below 2% annually.
- Home Users:Self-administering consumers purchasing through pharmacy channels or online retail. China's tier-one hospital rehabilitation departments pilot patient discharge programs with rental-to-own portable units; telehealth integration enables subscription-based device-as-a-service models.
- Hospitals:Tier-one rehabilitation departments demanding IEC 62304 compliant software lifecycle documentation.
- Wellness Centers:Premium facilities in South Korea creating dedicated electro-acupuncture suites with combined thermal-electrical systems.
Clinics retain the dominant revenue pool; home users are expanding most quickly.
Technology:
Application specificity determines clinical preference versus consumer substitution risk. Needle-integrated modalities command hospital preference for neural modulation accuracy; surface delivery methods compete on price and convenience in home settings.
- Electro-Acupuncture:Direct needle electrode delivery with superior precision for modulating neural signaling. Tier-one hospitals in China pilot AI-driven pattern recognition systems for stroke recovery protocols; treatment session duration compresses from 30 minutes to 12-15 minutes while maintaining efficacy.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode delivery avoiding needle penetration. Wireless patches capture price-sensitive home users seeking needle-free alternatives; consumer neuromodulation wearables fragment the economy segment.
- Pulsed Electromagnetic Field:Non-contact field induction for adjunctive neurological therapy applications.
- Microcurrent Therapy:Sub-sensory current delivery for aesthetic and wellness applications in premium spa settings.
Electro-acupuncture anchors clinical infrastructure budgets; transcutaneous delivery is gaining share fastest in consumer channels.
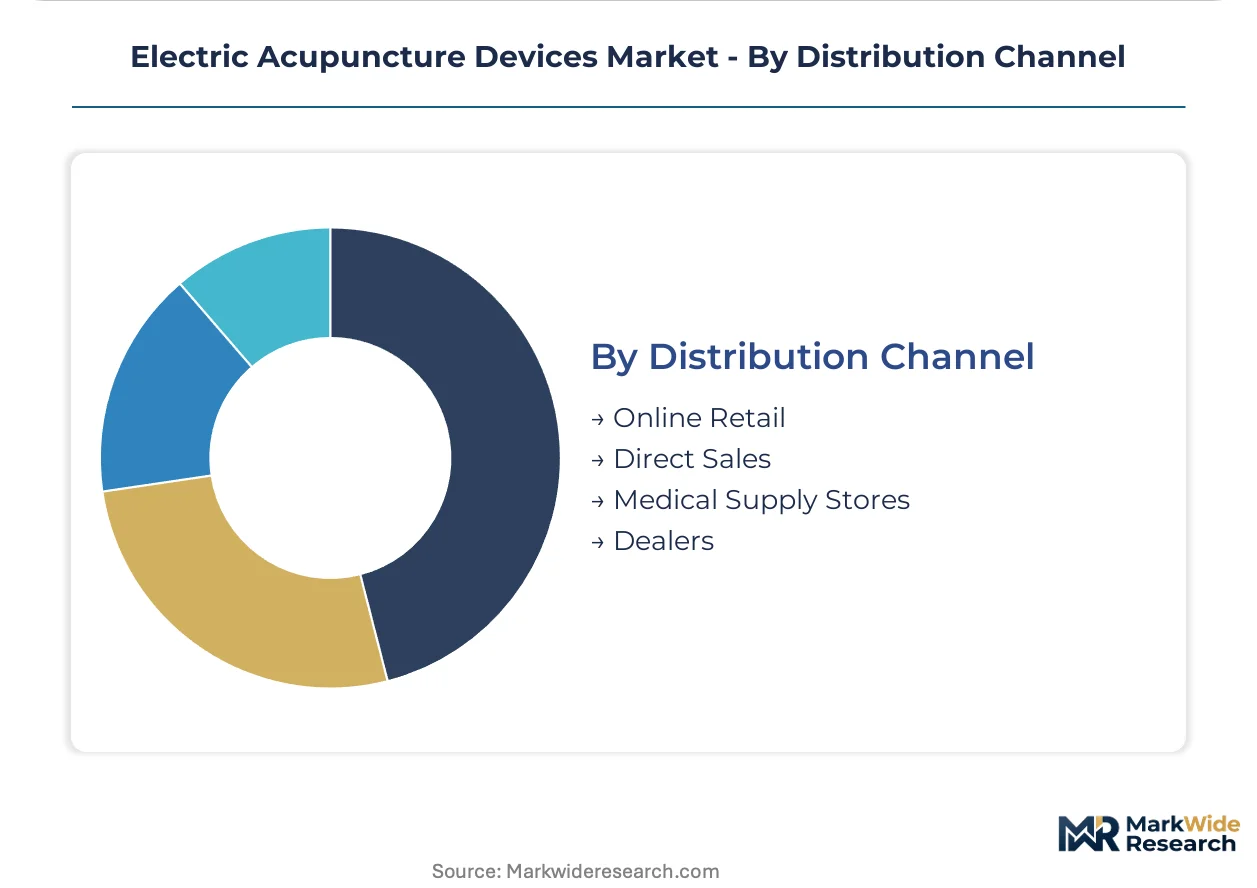
Distribution Channel:
Volume concentration varies sharply by geography and customer type. Direct sales retain dominance for hospital procurement committees; online retail accelerates in markets with pharmacy deregulation and wellness center social media integration.
- Online Retail:E-commerce platforms and direct-to-consumer brand sites. South Korean consumers initiate purchase journeys through integrated wellness center marketing; over-the-counter portable units displace traditional clinic referral pathways.
- Direct Sales:Manufacturer field forces targeting hospital procurement committees. EU MDR Article 10 technical documentation requirements favor established vendors with clinical evidence portfolios; German notified bodies prioritize combined electro-thermal systems for conformity assessment.
- Medical Supply Stores:Regional distributors serving independent clinics and small rehabilitation practices.
- Dealers:Third-party representatives covering geographic territories with limited manufacturer presence.
Direct sales capture the highest-value contracts; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant regulatory geography, while China's NMPA registration and Japan's PMDA approval processes create distinct East Asian compliance thresholds that filter manufacturer participation.
United States
Chronic pain management clinics and hospital rehabilitation departments drive demand for clinical-grade stationary systems. FDA 510(k) clearance compresses market entry timelines from 18 months to under 9 months for manufacturers with established predicate claims. The Northeast Corridor and California medical device clusters concentrate procurement committees demanding HL7 FHIR EMR compatibility.
Germany
Statutory health insurance frameworks are expanding coverage for electro-acupuncture under integrated care contracts, triggering device procurement growth in chronic pain clinics. CE marking under EU MDR Article 10 mandates clinical evidence for Class IIa and above classifications. Bavarian and North Rhine-Westphalia rehabilitation centers prioritize combined electro-thermal systems in procurement queues.
China
Tier-one hospital rehabilitation departments in Beijing, Shanghai, and Guangzhou pilot AI-driven pattern recognition systems for stroke recovery protocols. NMPA medical device registration creates compliance thresholds distinct from Western pathways. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic manufacturing and hospital procurement authority.
Japan
Pharmacy retail channels displace clinic-based trial rentals for portable device distribution. PMDA breakthrough device designation for neuropathic pain applications accelerates approval timelines for novel waveform algorithms. Tokyo and Osaka wellness networks drive premium positioning for combined thermal-electrical systems.
South Korea
Premium wellness centers in Seoul and Busan create dedicated electro-acupuncture suites, opening channel partnerships for multi-modal platforms. MFDS approval processes align with international standards while maintaining local testing requirements. The Seoul Capital Area exhibits the strongest direct-to-consumer purchasing velocity through social media marketing integration.
Electric Acupuncture Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure bifurcating between clinical-grade stationary system providers and consumer-accessible portable device manufacturers. The competitive terrain fragments across three strategic archetypes: diversified health electronics conglomerates, specialized medical device fabricators, and regional engineering-focused suppliers. Dominant competitive moves include geographic expansion through pharmacy channel partnerships and portfolio diversification into combined thermal-electrical modalities.
Within the diversified health electronics tier, Omron Corporation exemplifies scale-driven distribution leverage through consumer health electronics heritage. Among German-based medical device specialists, Schwa-medico GmbH and Asia-med GmbH occupy positions anchoring European clinical settings through CE-marked systems. Chinese engineering-focused suppliers including Suzhou Hualun Medical Appliance Co. Ltd. and Wuxi Biomedical Technology Co. Ltd. represent the manufacturing density of the Yangtze River Delta cluster.
| Leading Market Players |
|---|
| Suzhou Hualun Medical Appliance Co. Ltd. |
| Wuxi Biomedical Technology Co. Ltd. |
| Schwa-medico GmbH |
| Zepter International |
| Omron Corporation |
| MKW Lasersystem GmbH |
| Ito Co. Ltd. |
| Asia-med GmbH |
| Wuxi Jiajian Medical Instruments Co. Ltd. |
| Others |
Supply & Pricing Matrix
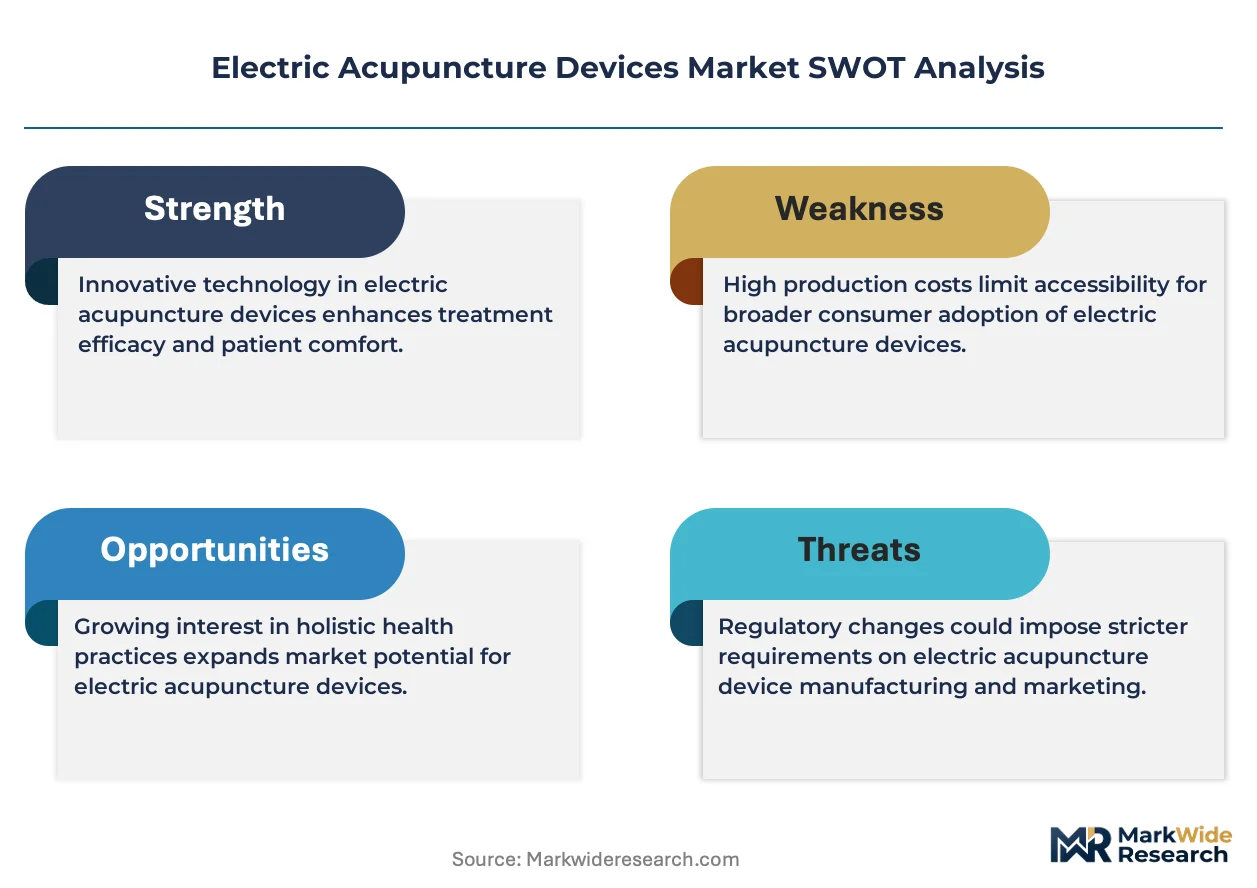
Wireless TENS patch substitution for needle-integrated systems simultaneously redistributes manufacturing toward Chinese consumer electronics clusters and compresses premium pricing power for clinical-grade electro-acupuncture equipment. This displacement dynamic fragments margin pools across the value chain as pharmacy retail channels capture downstream value previously retained by practitioner networks.
Pricing Analysis
Price spreads between German clinical installations and South Korean direct-to-consumer channels exceed threefold for functionally equivalent portable units. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) cleared systems with HL7 FHIR compatibility from CE-marked pharmacy retail units and unregistered economy imports. Pricing pressure stems from copper electrode cost volatility and neodymium magnet supply uncertainty. Home users exhibit acute price sensitivity; hospital procurement committees prioritize certification grade over unit economics.
Supply Chain Analysis
China and South Korea anchor electrode manufacturing and final device assembly respectively. Raw material flows draw from Chilean copper concentrate and Chinese rare earth processing facilities. Single-source vulnerability concentrates in neodymium magnet supply chains tethered to domestic Chinese processors. Distribution runs through German notified body certification queues for clinical systems and Japanese pharmacy retail networks for consumer units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proficiency in IEC 62304 medical device software lifecycle documentation represents the critical capability gap separating viable competitors from market participants facing 8-14 month development delays. This technical scarcity concentrates competitive advantage among established vendors with validated firmware architectures.
For Market Incumbents: Secure firmware validation capabilities through acquisition of specialized medical software consultancies to compress development cycles for app-connected portable units. Anchor hospital procurement relationships by accelerating HL7 FHIR middleware deployment ahead of competitor certification completion. Vertical integration into copper electrode manufacturing mitigates input cost volatility threatening margin stability.
For New Entrants and Emerging Players: Lead with telehealth-integrated device-as-a-service models targeting North American home-user segments where licensed practitioner shortages force self-administration adoption. South Korean wellness center networks present the most penetrable premium channel for combined thermal-electrical systems. Pursue pharmacy retail partnerships in Japan to bypass traditional clinic referral pathways.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German medical device specialists possessing CE-marked stationary system portfolios and established notified body relationships. Five-to-ten year viability hinges on reimbursement expansion trajectories across statutory health insurance frameworks. Monitor FDA breakthrough device designation velocity for novel waveform algorithms as inflection indicator for platform technology valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | German notified body prioritization of combined electro-thermal systems compresses approval queues for multi-modal platforms. |
| Software Companion Development | IEC 62304 compliant firmware architectures enable subscription-based protocol adherence tracking for telehealth integration. |
| Hospital System Partnership | HL7 FHIR EMR compatibility secures procurement committee approval for tier-one rehabilitation department installations. |
| Reimbursement Strategy | Statutory health insurance framework alignment in Germany unlocks integrated care contract coverage expansion. |
| Geographic Channel Expansion | Japanese pharmacy retail network partnerships displace clinic-based trial rentals for portable device distribution. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and licensed acupuncturists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, NMPA registration databases, EU MDR notified body assessment reports, and hospital procurement contract repositories. Bottom-up demand modeling and top-down regulatory filtering triangulated market sizing across the analysis window.
Sensitivity analysis tested forecast robustness against copper price volatility scenarios and practitioner workforce growth assumptions. Segmentation dimensions modeled include product form factor, end-user setting, technology type, and distribution channel complexity. CAGRs derived from installed base expansion rates and replacement cycle compression in AI-enabled systems. Forecast inputs incorporated reimbursement policy trajectory assumptions and telehealth platform integration velocity.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways, EU MDR Article 10 technical documentation requirements, and Japan PMDA breakthrough device designation frameworks; material policy shifts would require re-modeling. Specific risks include copper supply disruption, firmware validation timeline extensions, and transcutaneous substitution acceleration. Recalibration cycles align with material shifts in statutory reimbursement classifications and AI pattern recognition clinical trial readouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cosmetic Implants Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Ocular Implants Market
Medical Devices
Oxygenator Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Global Otoscopes Market